
 Computer Backup Software Market | 2026-2036
Computer Backup Software Market Size, Share, and Industry Trends Forecast 2026-2036
Computer Backup Software Market Insights
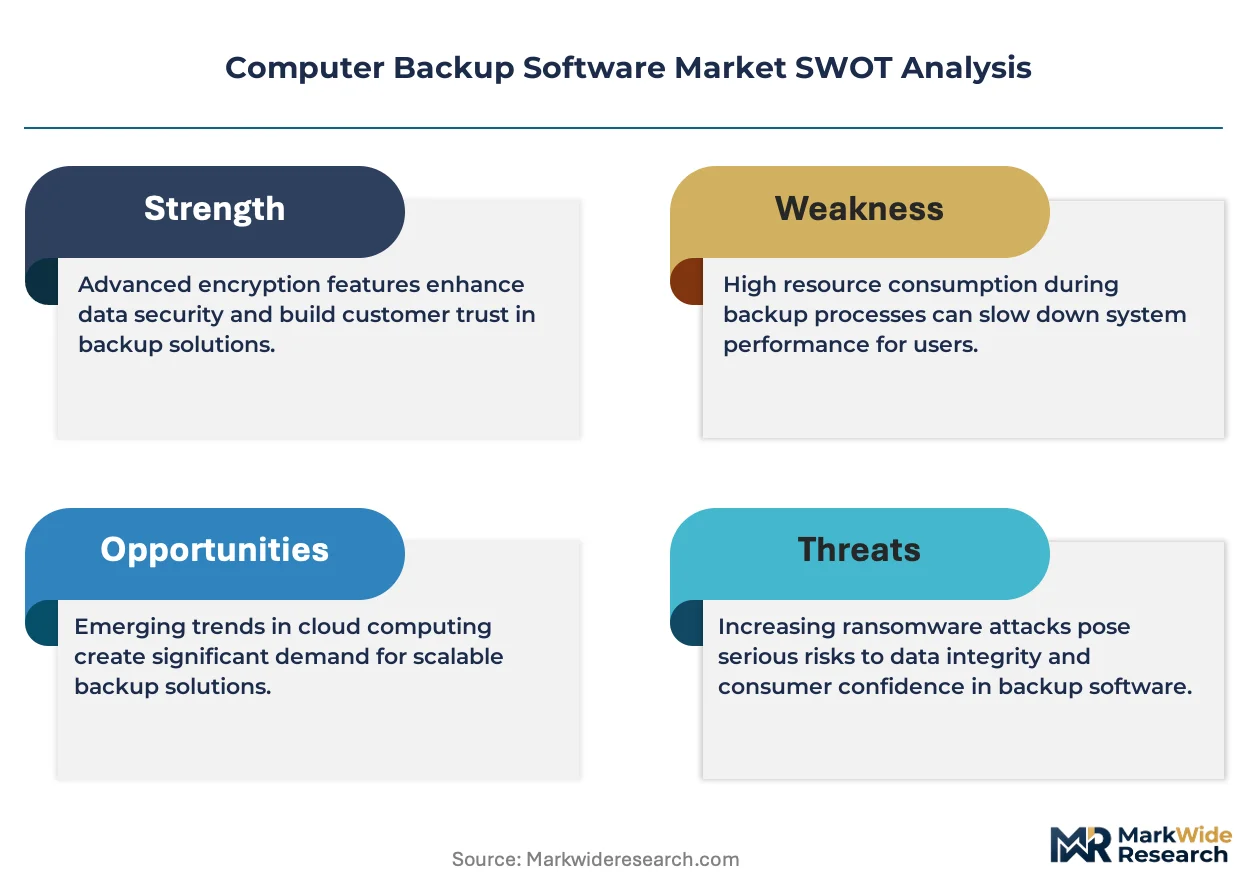
Multi-source deployment strategies are pivoting toward hybrid architectures as enterprises balance latency requirements with ransomware resilience. Veeam leverages deep integration with VMware and Microsoft ecosystems to sustain channel dominance in virtualized environments. Acronis anchors its position through integrated cyber protection layers that span backup, disaster recovery, and endpoint security. Backblaze competes aggressively on storage economics, undercutting incumbents with straightforward per-gigabyte pricing for cloud backup tiers.
Computer backup software comprises applications engineered to create redundant copies of digital assets across heterogeneous storage media, typically supporting block-level deduplication, AES-256 encryption, and granular recovery point objectives measured in minutes. Its primary commercial purpose centers on ensuring business continuity, regulatory compliance, and operational resilience against data corruption, hardware failure, or malicious encryption events. Cloud-based deployment leads structural expansion as organizations abandon capital-intensive on-premise tape libraries for subscription consumption models. Enterprise end users command the deepest margin pools given their requirements for immutable backups, air-gapped vaulting, and sub-hour recovery time objectives. File backup solutions remain the volume foundation, though system recovery functionality captures premium pricing through bare-metal restore capabilities and cross-platform portability.
FDA 21 CFR Part 11 shapes validation requirements for backup systems serving pharmaceutical manufacturing environments, while HIPAA Security Rule mandates encrypted, recoverable copies of electronic protected health information with documented testing protocols. NIST Cybersecurity Framework and ISO 27001 further harden procurement criteria, particularly for federal contractors and financial services entities subject to SEC cybersecurity disclosure rules. Stakeholders must monitor how zero-trust architecture mandates reshape backup authentication pathways and vault access controls.
Market Dynamics
Cloud-native architectures are displacing legacy tape systems across enterprise IT stacks, forcing backup vendors to reengineer platforms for containerized workloads and immutable object storage while federal contractors absorb DFARS cybersecurity mandates.
Growth Catalysts
- HIPAA Security Rule:Healthcare organizations in the United States face mandatory encrypted, recoverable copies of electronic protected health information with documented testing protocols, expanding backup investments.
- Ransomware resilience requirements:Enterprises across financial services and critical infrastructure sectors demand air-gapped vaulting and sub-hour recovery time objectives.
- Containerized workload proliferation:Kubernetes-native backup capabilities now serve as procurement gatekeepers for DevOps-led infrastructure decisions.
Market Restraints
- Cloud egress cost volatility:Unpredictable data retrieval fees from hyperscale providers compress margins for multi-tenant backup services.
- Legacy system integration friction:Mainframe and AS/400 environments resist API-based backup orchestration, fragmenting vendor R&D allocation.
- Tape library sunk costs:Capital-intensive on-premise investments in regulated industries delay full cloud migration timelines.
Strategic Opportunities
- Edge computing backup:Distributed manufacturing and retail IoT deployments in Germany and Japan lack mature data protection solutions.
- AI-driven anomaly detection:Convergence of backup platforms with behavioral analytics creates preemptive ransomware identification capabilities.
- SEC cybersecurity disclosure rules:Mandated incident reporting accelerates board-level backup modernization budgets in publicly traded entities.
Industry Challenges
- Immutable storage certification delays:FDA 21 CFR Part 11 validation for pharmaceutical manufacturing environments extends sales cycles.
- Multi-cloud orchestration complexity:Enterprises struggle to maintain consistent recovery point objectives across AWS, Azure, and Google Cloud simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computer Backup Software Market |
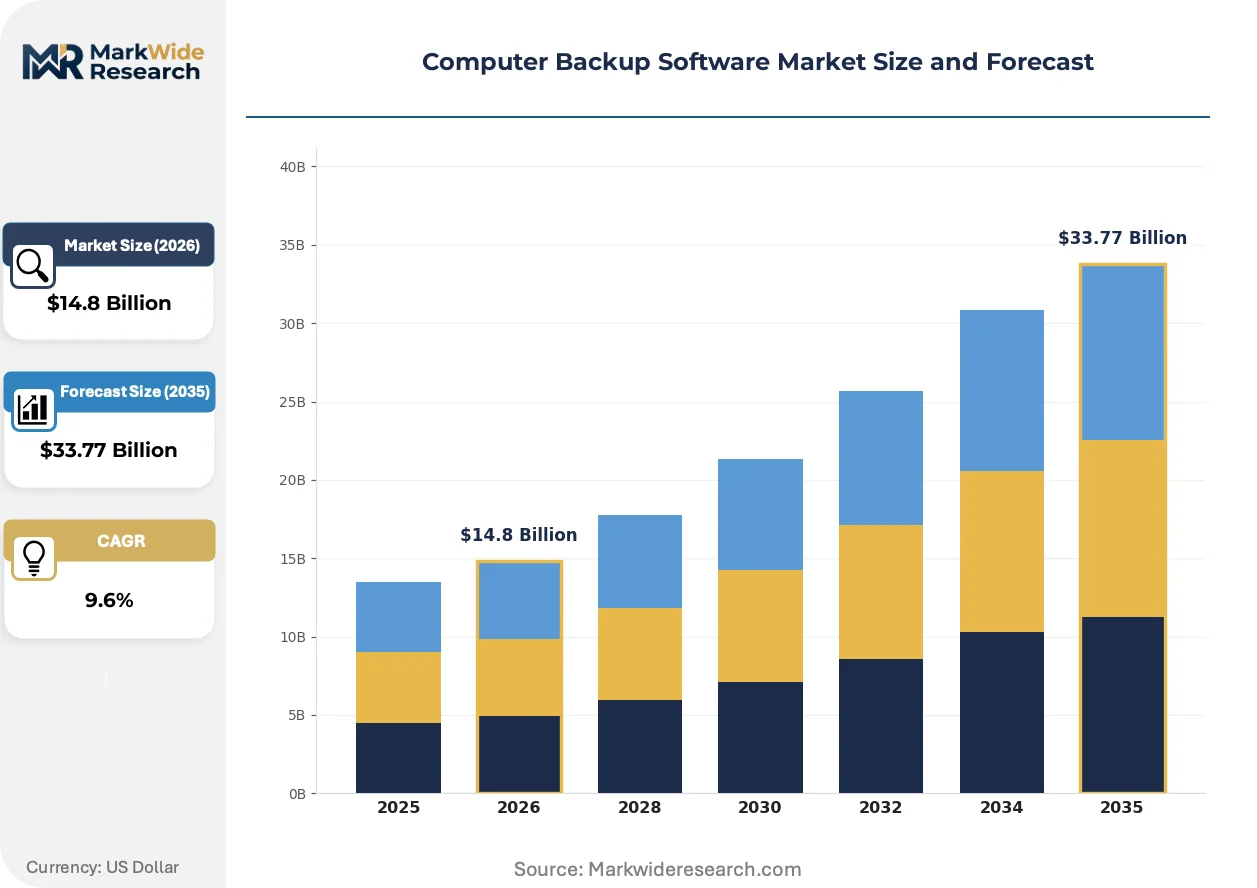
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $33.77 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Local Storage End User: Individuals, Small Businesses, Enterprises, Educational Institutions Solution: File Backup, Image Backup, System Recovery, Data Archiving Functionality: Incremental Backup, Continuous Data Protection, Scheduling, Encryption |
| Companies Covered | Acronis, Internxt, NinjaOne, Druva, BackBox, MSP360, Backblaze, Veeam, iDrive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computer Backup Software Market Trends and Innovations
Backup platforms are absorbing adjacent security functions while deployment models fragment across edge, core, and cloud tiers. Vendors now compete on automation depth rather than storage capacity alone.
Policy-driven backup orchestration is automating compliance posture management across heterogeneous infrastructure stacks. Financial services institutions in the United States deploy these engines to satisfy SEC cybersecurity disclosure rules without manual audit preparation. The technology is automating the translation of regulatory text into executable recovery workflows, compressing compliance timelines from quarters to weeks.
EU Cyber Resilience Act mandates for connected device manufacturers now extend to backup and recovery capabilities in IoT supply chains. European medical device producers must demonstrate recoverable firmware states under MDR technical documentation requirements. German automotive suppliers face the steepest adaptation curves as they reconcile KBA type-approval processes with software-defined vehicle architectures.
Consumption-based licensing models now dominate procurement discussions for mid-market enterprises previously locked into perpetual software agreements. Managed service providers in the United Kingdom bundle backup with security operations center services, displacing direct vendor relationships. Healthcare systems in Australia exhibit the fastest behavioral shift, consolidating backup spend under national procurement frameworks administered by TGA-registered technology aggregators.
Computer Backup Software Market Segmentation
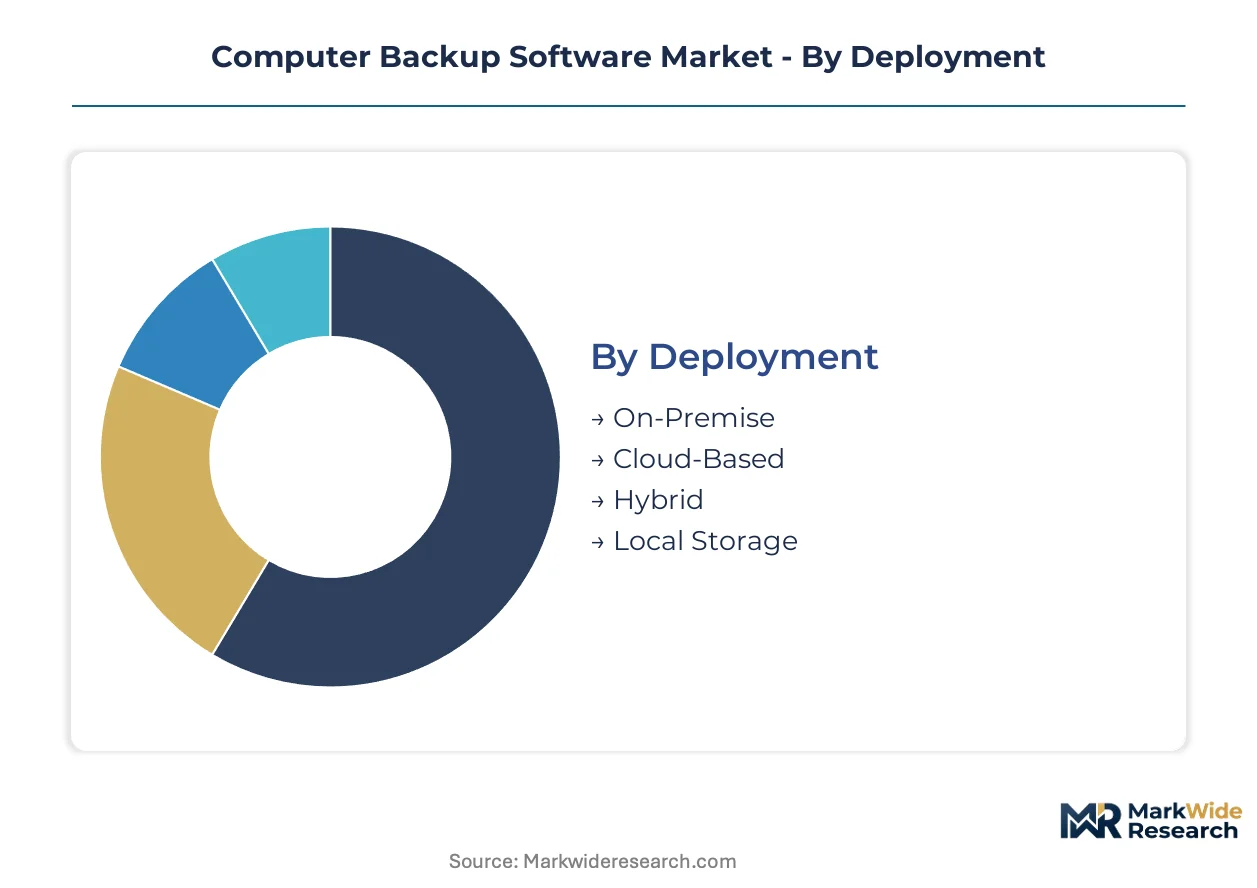
Computer backup software vendors engineer distinct product configurations to match heterogeneous infrastructure footprints and compliance postures. Segmentation reveals where margin pools concentrate and which deployment models capture modernization budgets.
Deployment:
Supply concentration tilts toward subscription models as vendors abandon perpetual license revenue recognition for recurring streams.
- Cloud-Based:Multi-tenant architectures with immutable object storage backends serve enterprises abandoning capital-intensive tape libraries. Healthcare systems in the United States absorb these solutions fastest as HIPAA mandates encrypted, recoverable copies with documented testing protocols.
- Hybrid:Orchestration layers span on-premise appliances and hyperscale vaults, balancing latency requirements against ransomware resilience. Financial services institutions deploy these configurations to satisfy SEC cybersecurity disclosure rules without sacrificing local recovery speed.
- On-Premise:Dedicated hardware appliances retain dominance in regulated manufacturing environments where FDA 21 CFR Part 11 validation extends sales cycles.
- Local Storage:Direct-attached disk and NAS-targeted solutions persist among creative professionals and small-scale video production workflows.
Today's leader: Cloud-Based. Tomorrow's challenger: Hybrid.
End User:
Cost tier stratification separates consumption models, with per-seat pricing dominating low-end segments and capacity-based enterprise agreements commanding premium tiers.
- Enterprises:Immutable backups, air-gapped vaulting, and sub-hour recovery time objectives define procurement criteria. Federal contractors in the United States face DFARS cybersecurity mandates that accelerate modernization timelines.
- Small Businesses:Managed service providers bundle backup with security operations center services, displacing direct vendor relationships in the United Kingdom and Australia.
- Educational Institutions:Budget-constrained K-12 districts and research universities prioritize straightforward per-gigabyte pricing over advanced automation features.
- Individuals:Consumer-grade subscriptions emphasize mobile device protection and photo-centric recovery workflows.
Volume concentrates with Enterprises. Margin expansion tracks fastest with Small Businesses.
Solution:
Application-driven purchasing separates file-centric protection from bare-metal recovery capabilities.
- System Recovery:Bare-metal restore capabilities and cross-platform portability capture premium pricing. German automotive suppliers reconcile KBA type-approval processes with software-defined vehicle architectures using these solutions.
- File Backup:Granular object-level protection remains the volume foundation across all end-user tiers.
- Image Backup:Block-level disk snapshots serve virtualized environments with aggressive recovery point objectives.
- Data Archiving:Long-term retention with legal hold capabilities addresses SEC record-keeping requirements and EU MDR technical documentation mandates.
Revenue concentrates with System Recovery. Expansion velocity favors Data Archiving.
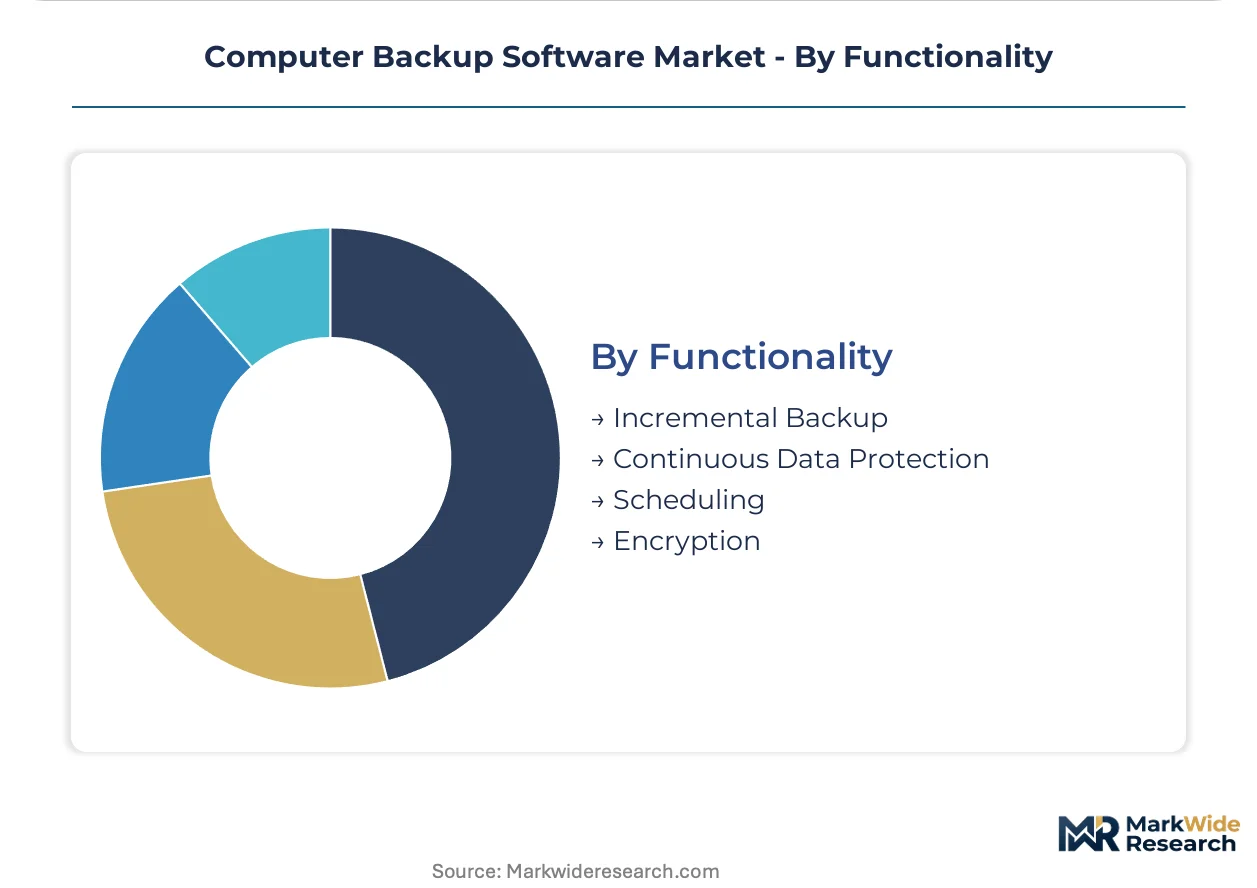
Functionality:
Customer type dictates automation depth, with DevOps-led infrastructure decisions prioritizing API-native orchestration.
- Continuous Data Protection:Journal-based replication with near-zero recovery point objectives serves Kubernetes-native workloads. Containerized workload proliferation now functions as a procurement gatekeeper for platform selection.
- Encryption:AES-256 at rest and in transit satisfies HIPAA Security Rule mandates and NIST Cybersecurity Framework procurement criteria.
- Incremental Backup:Block-level deduplication reduces storage consumption for high-change-rate datasets.
- Scheduling:Policy-driven automation compresses compliance timelines from quarters to weeks for financial services institutions.
Technical differentiation centers on Continuous Data Protection. Standardization pressure converges on Encryption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's concentration of cloud infrastructure providers anchors North American demand for enterprise backup solutions, while regulatory divergence across major economies is fragmenting vendor compliance roadmaps.
United States
Federal contractors absorb DFARS cybersecurity mandates that accelerate modernization timelines away from legacy tape systems. HIPAA Security Rule enforcement drives healthcare systems toward encrypted, recoverable copies with documented testing protocols. Boston's pharmaceutical corridor demands FDA 21 CFR Part 11 validation for manufacturing environment backups, extending enterprise sales cycles.
Germany
Automotive suppliers reconcile KBA type-approval processes with software-defined vehicle architectures requiring bare-metal restore capabilities. EU Cyber Resilience Act mandates for connected device manufacturers now extend to backup capabilities in IoT supply chains. Munich's industrial automation cluster exhibits steep adaptation curves as manufacturers integrate edge computing backup for distributed production lines.
United Kingdom
Managed service providers bundle backup with security operations center services, displacing direct vendor relationships across mid-market enterprises. Financial services institutions deploy hybrid configurations to satisfy regulatory expectations without sacrificing local recovery speed. London's fintech density concentrates demand for sub-hour recovery time objectives and immutable vaulting architectures.
Japan
Manufacturing IoT deployments in Osaka and Nagoya industrial corridors lack mature data protection solutions for edge computing environments. METI guidance on critical infrastructure resilience shapes procurement criteria for ransomware protection. Tokyo's financial district drives premium pricing for continuous data protection and cross-platform portability features.
Australia
Healthcare systems consolidate backup spend under national procurement frameworks administered by TGA-registered technology aggregators. Budget-constrained educational institutions prioritize straightforward per-gigabyte pricing over advanced automation. Sydney's research universities anchor demand for long-term data archiving with legal hold capabilities addressing record-keeping requirements.
Computer Backup Software Market Competitive Landscape
Global majors compete with regional champions across cloud-native deployment capabilities, creating a tiered structure where VMware ecosystem integration and cyber protection layering define strategic positioning. The vendor base separates into three archetypes: infrastructure-integrated platforms, security-converged suites, and storage-economics disruptors. Dominant competitive moves include strategic partnerships with hyperscale cloud providers and portfolio diversification into adjacent security functions.
Within the infrastructure-integrated tier, Veeam and Acronis exemplify contrasting approaches to ecosystem dominance. Veeam leverages deep VMware and Microsoft integration to sustain channel relationships in virtualized environments. Acronis anchors its position through converged cyber protection spanning backup, disaster recovery, and endpoint security. Backblaze occupies a distinct position at the storage-economics end, competing through transparent per-gigabyte pricing that undercuts incumbent cloud backup tiers.
| Leading Market Players |
|---|
| Acronis |
| Internxt |
| NinjaOne |
| Druva |
| BackBox |
| MSP360 |
| Backblaze |
| Veeam |
| iDrive |
| Others |
Pricing and Supply Chain Analysis
DevOps engineering talent concentration in Bangalore and Warsaw creates labor-cost differentials that widen pricing-tier spreads between premium cyber-protection suites and economy-tier file backup offerings. Cloud infrastructure engineers in these markets command one-third the compensation of their Silicon Valley counterparts, enabling vendors to maintain margin integrity on mid-market subscriptions while funding R&D for enterprise immutable vaulting features.
Pricing Analysis
Input-cost pass-through from hyperscale storage fees shapes subscription tiering across the market. Three-tier pricing structure across premium, standard, and economy levels separates immutable air-gapped vaulting from basic encrypted file sync. Certification grade—specifically ISO 27001 and SOC 2 Type II attestation—commands 40-60% premiums over uncertified alternatives. Pricing pressure stems from cloud egress cost volatility as AWS and Azure adjust retrieval fees quarterly. Small businesses exhibit highest price sensitivity, gravitating toward per-gigabyte transparent pricing, while federal contractors absorb premium tiers to satisfy DFARS cybersecurity mandates without procurement friction.
Supply Chain Analysis
Immutable object storage supply rests on hyperscale infrastructure providers concentrated in the United States, Ireland, and Singapore. Vendors draw from AWS S3 Glacier, Azure Blob Archive, and Google Cloud Storage Nearline for backend vaulting, while encryption key management hardware sources from Thales and Entrust datacenters in France and Canada. Single-source vulnerability concentrates in API dependency on three cloud providers for multi-tenant architectures. Distribution runs through managed service providers in the United Kingdom and technology aggregators in Australia, displacing direct vendor relationships across mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between United States federal compliance premiums and European operational cost efficiencies, with HIPAA-mandated healthcare investments in Boston and San Francisco subsidizing margin compression from GDPR-driven engineering overhead in Frankfurt and Dublin.
For Market Incumbents: Hedge against cloud-native disruptors by deepening VMware ecosystem integration and acquiring Kubernetes-native backup specialists before containerized workload proliferation locks in procurement decisions. Channel control through managed service provider exclusivity agreements in the United Kingdom and Australia defends against Backblaze-style storage-economics entrants. Certification investment in FDA 21 CFR Part 11 validation capabilities extends pharmaceutical manufacturing moats. For New Entrants and Emerging Players: Launch via consumption-based licensing models targeting budget-constrained educational institutions in Australia and Japan, where straightforward per-gigabyte pricing displaces feature-heavy incumbents. Edge computing backup for German automotive suppliers and Japanese manufacturing IoT corridors represents the most penetrable white space, with KBA type-approval friction deterring established vendors. Partner with TGA-registered technology aggregators for healthcare system access. For Investors and Strategic Acquirers: Private equity firms with cybersecurity portfolio holdings are the most active acquirer in this space, seeking backup platforms with integrated endpoint security layers. Long-term viability centers on convergence with zero-trust architecture mandates and AI-driven anomaly detection capabilities. Watch SEC cybersecurity disclosure rule enforcement intensity as the inflection indicator for board-level backup modernization budgets in publicly traded entities.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep VMware and Microsoft ecosystem embedding sustains channel dominance in virtualized environments. |
| Strategic Partnership | Hyperscaler co-sell agreements with AWS and Azure accelerate enterprise immutable vaulting adoption. |
| Acquisition of Specialist Firm | Kubernetes-native backup capabilities serve as procurement gatekeepers for DevOps-led infrastructure decisions. |
| Product Launch | AI-driven anomaly detection layers preemptive ransomware identification onto backup orchestration. |
| Geographic Expansion | Edge computing backup penetration in German automotive and Japanese manufacturing IoT corridors captures underserved demand. |
Research Methodology
Direct dialogue with backup software product managers, enterprise IT procurement officers, managed service provider executives, and healthcare technology directors grounded qualitative insights. Secondary validation drew from SEC cybersecurity disclosure filings, HIPAA enforcement action records, hyperscaler capex and pricing disclosures, and EU Cyber Resilience Act technical documentation requirements. Bottom-up deployment model adoption curves and top-down enterprise IT spending patterns were triangulated to anchor market sizing.
Segmentation outputs across deployment architecture, end-user organization scale, solution type, and functionality tier were generated through the projection horizon. CAGRs were derived from elasticity modeling against cloud infrastructure spend growth and regulatory compliance investment cycles. Kubernetes-native workload proliferation rates and DFARS cybersecurity mandate adoption timelines served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt hyperscaler pricing adjustments or accelerated zero-trust architecture mandate enforcement. A small set of named triggers—cloud egress fee volatility, FDA 21 CFR Part 11 validation timeline shifts, and SEC cybersecurity disclosure rule expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Web Scraping Software Market
Software & Services
Optical Design Software Market
Software & Services
Cloud Backup and Recovery Software Market
Software & Services
Client Virtualization Software Market
Software & Services
Service Resource Planning (SRP) Saas Solutions Market
Software & Services
Fitness App Market
Software & Services
Global Embedded Hypervisor Software Market
Software & Services
Social Software As a Collaborative ERP Tool Market
Software & Services
Referral Marketing Software Market
Software & Services
Global Managed File Transfer Software Market
Software & Services
US Content Services Platform Market
Software & Services
AI Sales Assistant Software Market
Software & Services
Automation Test Software Market
Software & Services
Balance Sheet Management Software Market
Software & Services
Global Data Extraction Software Market
Software & Services
Global Online Form Builder Software Market