
 Multi-Cloud Networking in Fintech Market | 2026-2036
Multi-Cloud Networking in Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Cloud Networking in Fintech Market Analysis
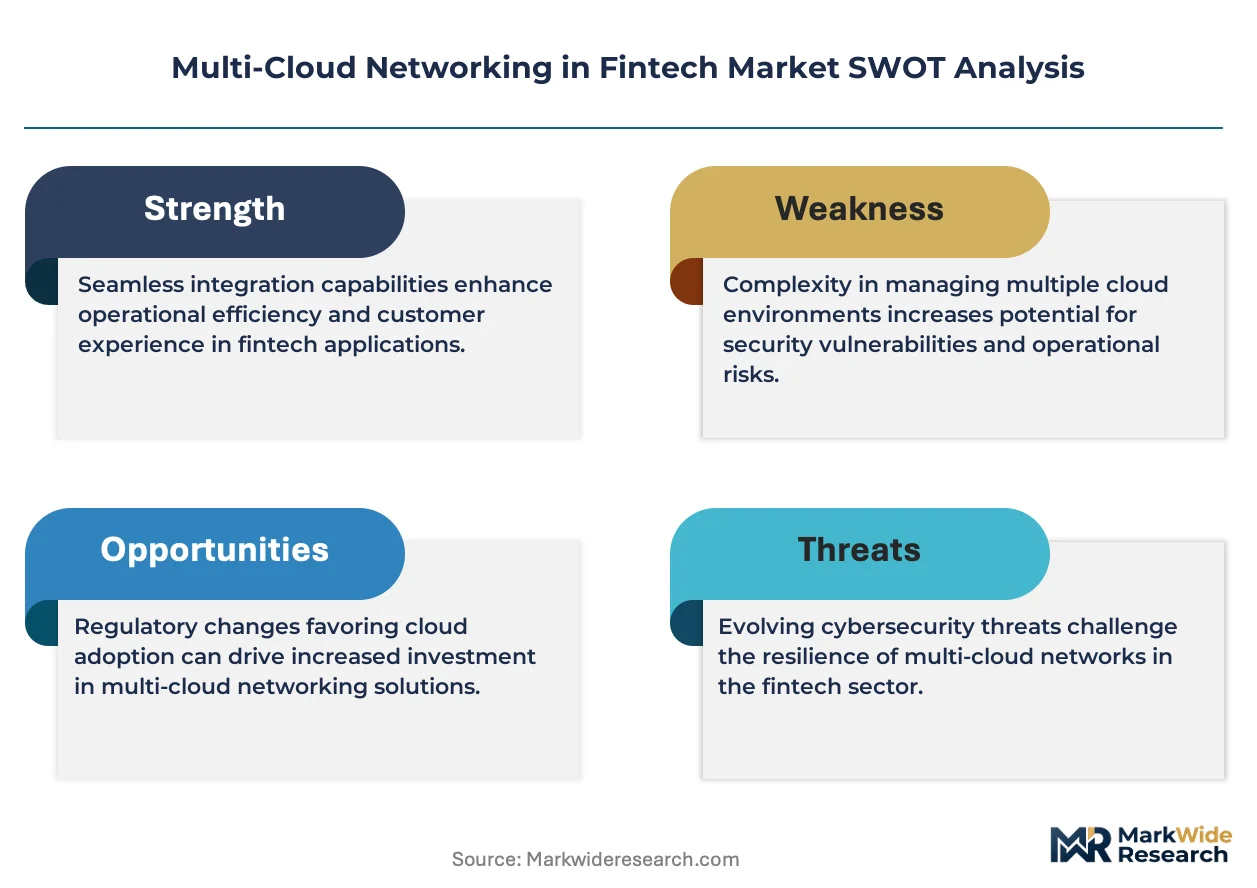
A shortage of Site Reliability Engineers with multi-cloud orchestration expertise is unwinding deployment timelines for tier-one financial institutions. F5 leverages its application delivery controller heritage to anchor high-availability traffic management across dispersed cloud estates. Juniper Networks competes through Contrail-based SD-WAN integration that sustains low-latency connectivity between on-premise cores and public cloud nodes. Aviatrix specializes in cloud-native network security that differentiates its controller architecture from legacy hardware-centric approaches.
Multi-cloud networking in fintech denotes the interconnection of workloads across two or more independent cloud environments using software-defined overlays, API gateways, and encrypted transit fabrics to maintain sub-50 millisecond latency thresholds for real-time payment validation. Its primary commercial purpose is to eliminate single-provider dependency while preserving transactional integrity during provider outages or regional failures. The deployment model dimension shows hybrid cloud configurations capturing the dominant margin pool as banks retain core ledger systems on private infrastructure while bursting customer-facing applications to public tiers. Within service type, managed services are expanding fastest because retail banks and insurtech carriers lack internal cloud networking competencies. The technology segment reveals SDN and NFV converging as foundational layers, with API management emerging as the critical control plane for open banking interoperability.
The Federal Reserve's Operational Resilience Framework, the EU Digital Operational Resilience Act, and PCI DSS 4.0 collectively mandate multi-region failover capabilities and encrypted data-in-transit standards that reshape procurement specifications for cloud networking vendors. HIPAA-aligned health-fintech hybrids and SEC custody rule amendments for digital assets further fragment compliance requirements across client type segments. Stakeholders must evaluate whether their current overlay architectures can absorb forthcoming quantum-resistant encryption mandates without forklift upgrades to existing control planes.
Market Dynamics
Payment processors are consolidating workloads across AWS, Azure, and Google Cloud to satisfy the Federal Reserve's Operational Resilience Framework mandates for sub-minute failover. This architectural imperative is compressing vendor selection cycles and elevating sovereign data routing to a board-level priority.
Growth Catalysts
- EU Digital Operational Resilience Act:Mandated multi-region redundancy is compelling continental banks to procure encrypted transit fabrics that span at least two cloud providers.
- Real-time payment networks:FedNow and SEPA Instant are driving sub-50 millisecond latency requirements that single-cloud architectures cannot guarantee during regional outages.
- Health-fintech convergence:HIPAA-aligned hybrid deployments are expanding addressable market for managed multi-cloud networking services among insurance carriers.
Market Restraints
- Specialized labor scarcity:Site Reliability Engineers with multi-cloud orchestration expertise command compensation premiums that extend deployment timelines by 8-14 months.
- Legacy core dependency:Mainframe-based ledger systems resist API gateway integration, forcing costly middleware layers that degrade performance budgets.
- Quantum-resistant encryption uncertainty:NIST post-quantum standards remain in draft, freezing long-term procurement decisions for control plane infrastructure.
Strategic Opportunities
- Embedded finance in Southeast Asia:Singapore and Indonesia's digital banking licenses are creating greenfield demand for cloud-native networking without legacy baggage.
- SD-WAN and SASE convergence:Unified edge-to-cloud security fabrics are opening attach-rate expansion for networking vendors serving distributed trading floors.
- SEC custody rule amendments:Digital asset infrastructure requirements are fragmenting compliance specifications and creating specialist vendor niches.
Industry Challenges
- Control plane complexity:Maintaining consistent policy enforcement across Contrail, NSX, and native cloud networking stacks demands architectural discipline most institutions lack.
- PCI DSS 4.0 transition:New encrypted data-in-transit mandates require certificate lifecycle automation that conflicts with existing change management protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Cloud Networking in Fintech Market |
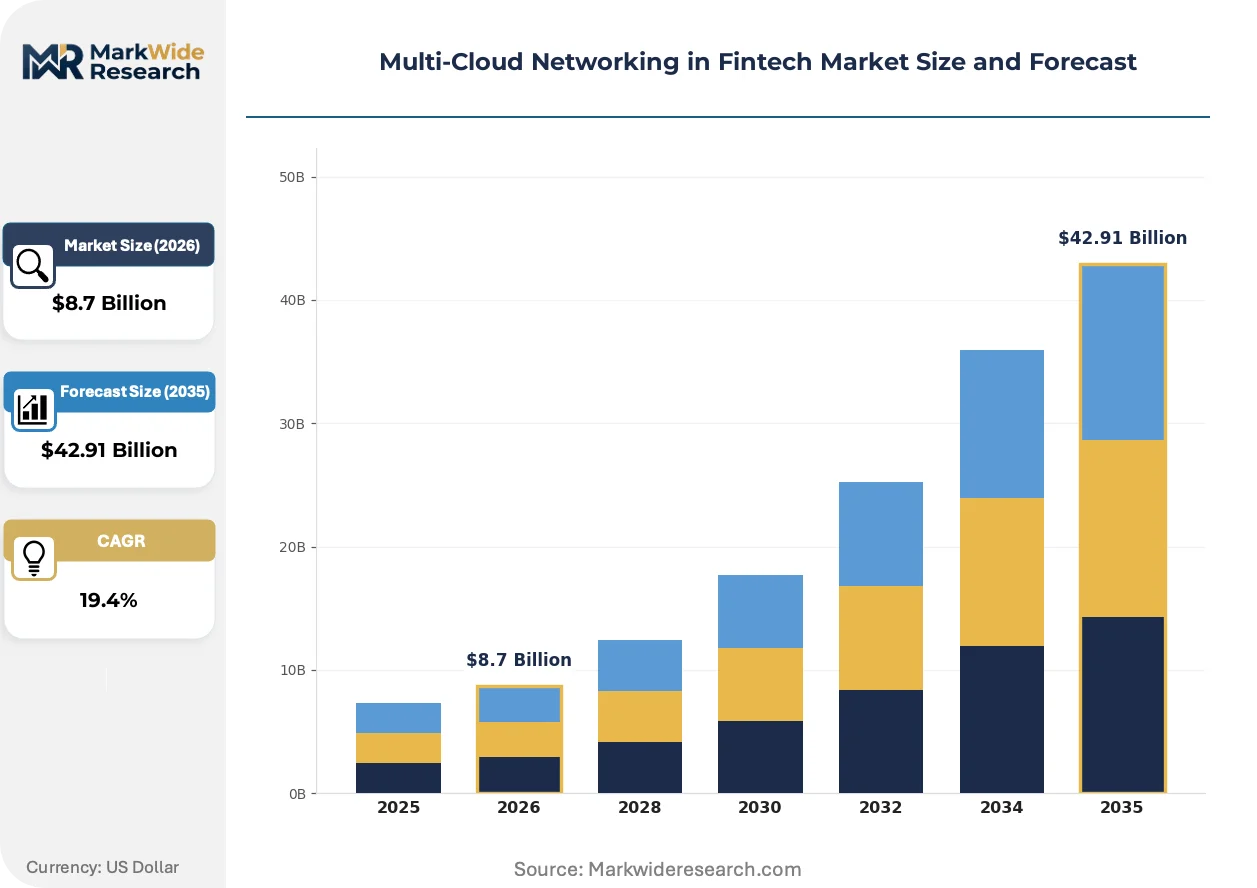
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Managed Services, Cloud Connectivity, Security Services, Data Backup Client Type: Retail Banks, Investment Firms, Payment Processors, Insurtech Technology: SDN, NFV, API Management, Network Function Virtualization |
| Companies Covered | F5, Nutanix, Aviatrix, Juniper Networks, Cloudflare, VMware, Cisco Systems, Citrix Systems, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Cloud Networking in Fintech Market Emerging Trajectories
Software-defined overlays are absorbing functions once performed by hardware appliances, compressing procurement categories and reshaping vendor competitive boundaries. This shift is elevating API management from operational convenience to strategic control plane.
Service mesh architectures are decomposing monolithic application delivery controllers into sidecar proxies that handle east-west traffic encryption within Kubernetes clusters. Tier-one banks are piloting Istio and Linkerd at production scale to replace hardware load balancers for containerized payment microservices. This decomposition is collapsing the distinction between network operations and platform engineering functions.
The EU AI Act's risk classification framework is forcing fintechs to implement data residency controls that restrict model training workloads to specific cloud regions. Financial institutions are deploying sovereign cloud nodes in Frankfurt and Paris to satisfy GDPR Article 44 transfer limitations. Retail banking divisions face the steepest compliance burden as customer-facing algorithms trigger high-risk designations.
Centralized procurement of networking infrastructure is fragmenting as individual lines of business acquire cloud services directly. Treasury and capital markets units are bypassing enterprise IT to procure dedicated low-latency connectivity from specialized providers. This pattern is most pronounced among hedge funds and proprietary trading desks in the United States, where speed-to-market overrides standardization mandates.
Multi-Cloud Networking in Fintech Market Segmentation
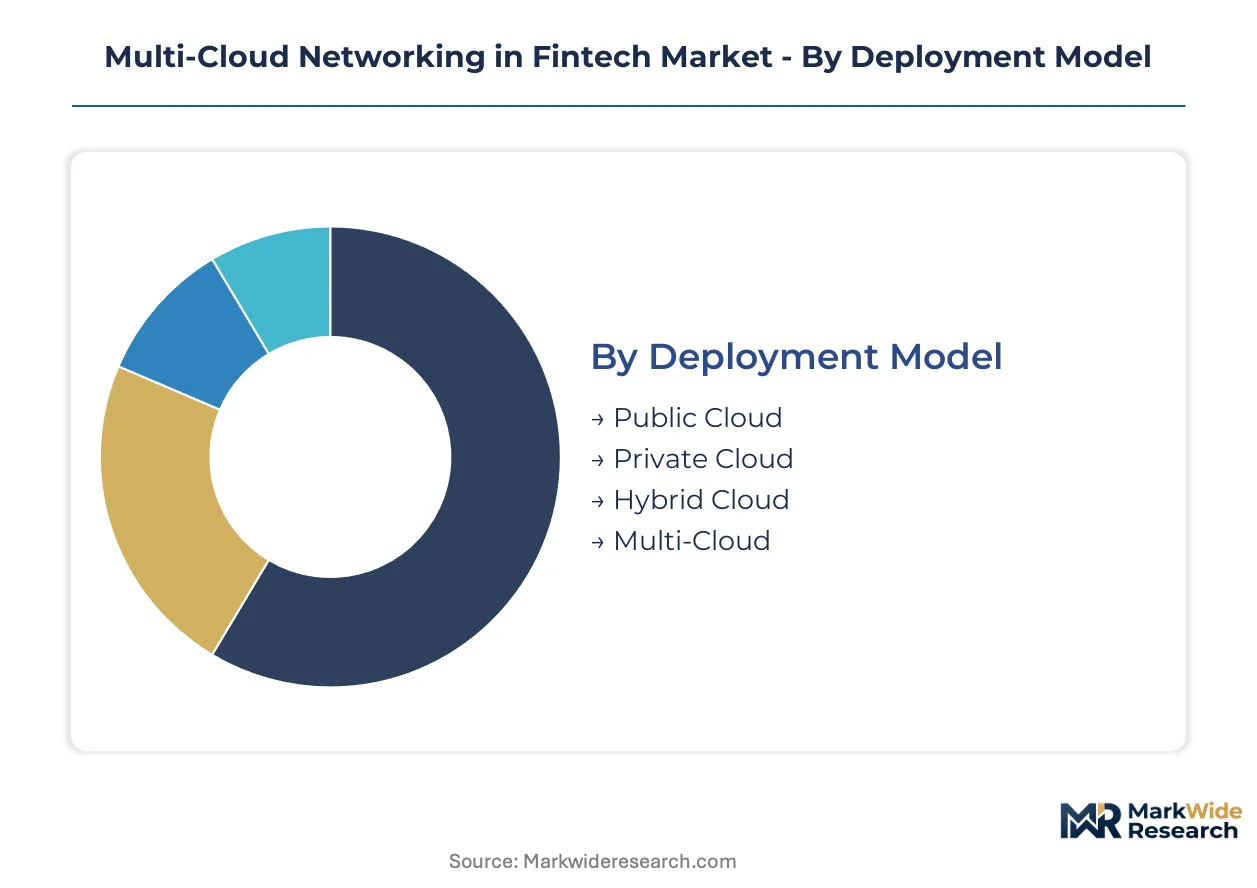
Segmentation in multi-cloud networking for fintech reveals how procurement authority fragments across infrastructure layers and buyer types. Deployment models determine capital allocation between owned and consumed capacity. Service types expose competency gaps that vendors monetize through managed offerings.
Deployment Model:
Channel mix varies sharply by deployment model: hybrid configurations flow through systems integrators with mainframe expertise, while public cloud deployments route through hyperscaler marketplaces and direct vendor relationships.
- Hybrid Cloud:Combines private infrastructure for core ledger systems with public cloud bursting for customer-facing applications. Retail banks in the United States concentrate demand here as they modernize without abandoning mainframe investments.
- Multi-Cloud:Distributes workloads across AWS, Azure, and Google Cloud to satisfy operational resilience mandates. Payment processors are expanding this segment fastest to achieve sub-minute failover capabilities under Federal Reserve requirements.
- Public Cloud:Relies on single-provider infrastructure with software-defined overlays for traffic management. Insurtech carriers lacking legacy baggage favor this route for speed-to-market.
- Private Cloud:Maintains sovereign infrastructure for data residency compliance. European institutions deploy this model to satisfy GDPR Article 44 transfer limitations.
Hybrid Cloud dominates installed base. Multi-Cloud is where expansion concentrates.
Service Type:
Cost tier stratification separates premium managed services from commoditized connectivity offerings, with security services commanding mid-tier pricing based on compliance certification requirements.
- Managed Services:Outsourced network operations including policy orchestration, performance monitoring, and incident response. Retail banks and insurtech carriers lacking internal cloud networking competencies are driving demand concentration here.
- Security Services:Encrypted transit fabrics, zero-trust segmentation, and certificate lifecycle automation. Investment firms facing SEC custody rule amendments for digital assets prioritize this segment for compliance.
- Cloud Connectivity:Dedicated interconnects and SD-WAN integration between cloud regions. Payment processors procure this service type directly to guarantee sub-50 millisecond latency for real-time validation.
- Data Backup:Multi-region replication and disaster recovery orchestration. HIPAA-aligned health-fintech hybrids expand addressable market for this offering among insurance carriers.
Managed Services captures the dominant margin pool. Cloud Connectivity is climbing the fastest as latency requirements tighten.
Client Type:
Application intensity varies by client sophistication: payment processors demand real-time performance optimization while retail banks prioritize regulatory audit trails and change management integration.
- Payment Processors:Transaction volume aggregators requiring sub-50 millisecond latency and multi-region redundancy. FedNow and SEPA Instant mandates are expanding procurement urgency for this segment.
- Retail Banks:Full-service institutions with legacy core dependencies and branch network footprints. The EU Digital Operational Resilience Act is compelling continental banks in this category to procure encrypted transit fabrics.
- Investment Firms:Hedge funds and proprietary trading desks prioritizing speed-to-market over standardization. Treasury and capital markets units within these firms increasingly bypass enterprise IT for specialized connectivity.
- Insurtech:Technology-native carriers and health-fintech hybrids. HIPAA alignment requirements and digital banking license opportunities in Singapore and Indonesia are creating greenfield demand without legacy baggage.
Retail Banks dominate installed base. Payment Processors represent the steepest expansion trajectory.
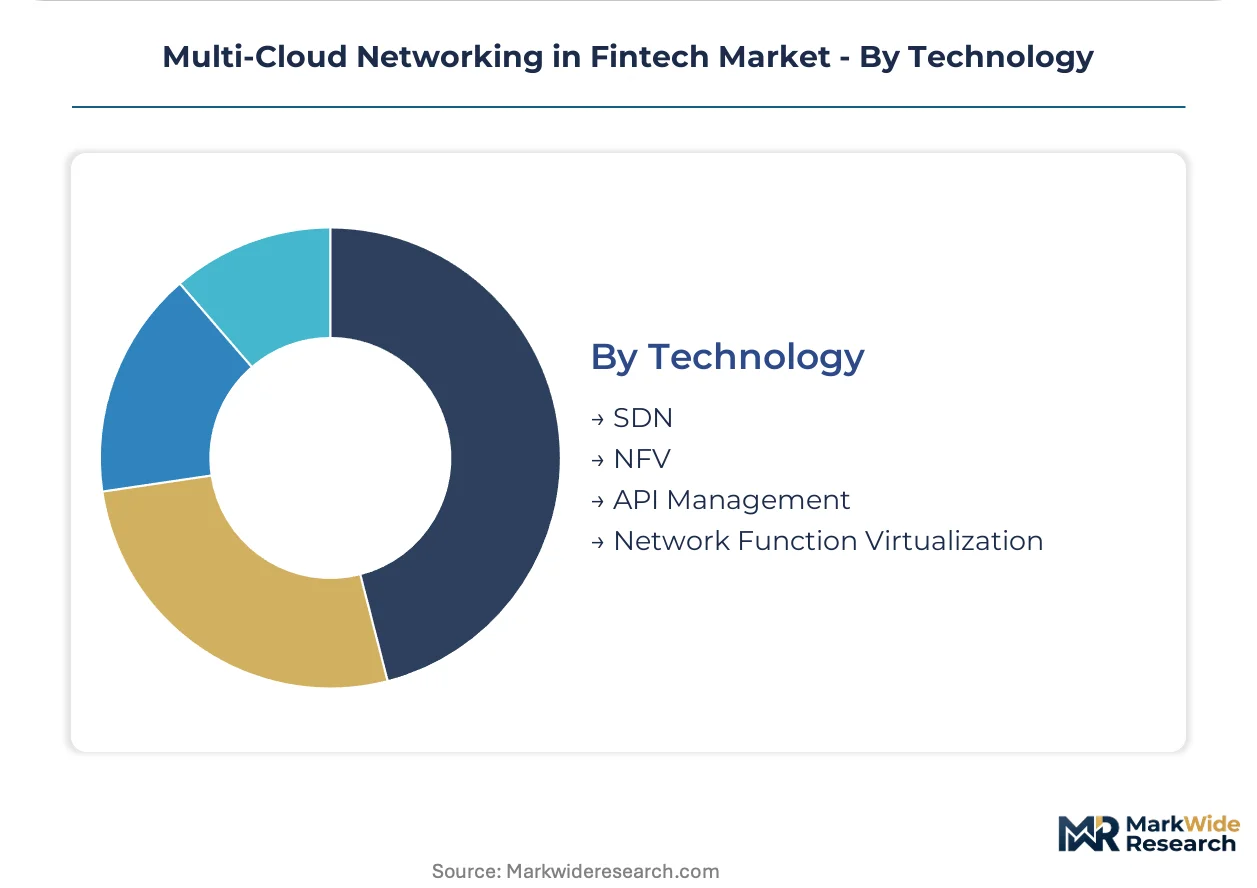
Technology:
Supply concentration in control plane software elevates API management and SDN platforms above hardware-centric alternatives, with NFV gaining share as virtualization matures in production environments.
- SDN:Software-defined overlays replacing hardware appliances for traffic management and policy enforcement. Tier-one banks are piloting service mesh architectures at production scale for containerized payment microservices.
- API Management:Gateway and lifecycle tooling for open banking interoperability. This segment is gaining strategic priority as the control plane layer connecting legacy cores to cloud-native applications.
- NFV:Network function virtualization decoupling security and routing from proprietary hardware. Contrail-based and NSX-based implementations compete for enterprise adoption.
- Network Function Virtualization:Specialized virtualized appliances for load balancing and firewall functions. This segment overlaps functionally with NFV but emphasizes discrete appliance replacement over platform consolidation.
SDN dominates installed base. API Management is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Federal Reserve's Operational Resilience Framework anchors procurement urgency in the United States, where payment processors and retail banks are consolidating multi-cloud architectures to satisfy sub-minute failover mandates. Regulatory pressure on operational continuity intersects with cloud-native infrastructure buildouts across major financial centers.
United States
New York-based payment processors and Chicago futures exchanges are driving demand for sub-50 millisecond latency fabrics. The SEC's custody rule amendments for digital assets are fragmenting compliance specifications among investment firms. Treasury units in Manhattan and Greenwich increasingly bypass enterprise IT to procure specialized connectivity directly.
United Kingdom
London's clearing banks and fintech clusters in Shoreditch are expanding hybrid cloud deployments to maintain core ledger sovereignty. The Financial Conduct Authority's operational resilience requirements align with EU DORA timelines for multi-region redundancy. Canary Wharf trading floors prioritize low-latency edge-to-cloud fabrics for real-time settlement systems.
Germany
Frankfurt's banking concentration and Munich's insurtech hubs are deploying sovereign cloud nodes to satisfy GDPR Article 44 transfer limitations. BaFin's supervisory expectations for IT risk management reinforce encrypted transit procurement. The Rhine-Main metropolitan region hosts the densest concentration of API gateway implementations for open banking interoperability.
Singapore
Digital banking license recipients and embedded finance platforms are building greenfield multi-cloud networks without legacy core dependencies. The Monetary Authority of Singapore's technology risk management guidelines mandate resilience testing across cloud providers. Marina Bay financial district and One-North technology corridor concentrate demand for managed security services.
India
Mumbai's payment system operators and Bangalore's fintech unicorns are scaling multi-cloud connectivity to support UPI transaction volumes. RBI's guidelines on information technology governance require data localization and disaster recovery orchestration. The Delhi-NCR corridor is emerging as a secondary hub for cloud-native networking talent and managed service delivery.
Multi-Cloud Networking in Fintech Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the multi-cloud networking landscape. The vendor base stratifies into three tiers: established networking hardware incumbents with application delivery controller heritage, cloud-native specialists with controller-based architectures, and hyperscaler-aligned platform providers. Consolidation pressure is intensifying as procurement cycles compress under regulatory deadlines. Strategic moves center on SD-WAN and SASE convergence for unified edge-to-cloud fabrics, alongside API management platform acquisitions to anchor open banking control planes.
Within the established infrastructure tier, F5 leverages its application delivery controller heritage to anchor high-availability traffic management across dispersed cloud estates. Juniper Networks competes through Contrail-based SD-WAN integration that sustains low-latency connectivity between on-premise cores and public cloud nodes. Aviatrix occupies a position among cloud-native specialists, differentiating through security-focused controller architectures that depart from legacy hardware-centric approaches.
| Leading Market Players |
|---|
| F5 |
| Nutanix |
| Aviatrix |
| Juniper Networks |
| Cloudflare |
| VMware |
| Cisco Systems |
| Citrix Systems |
| Oracle Corporation |
| Others |
Supply Flow & Price Mechanics
Hyperscaler capacity utilization in Virginia, Frankfurt, and Singapore directly shapes margin structures for multi-cloud networking vendors, concentrating supply leverage among providers with sovereign cloud nodes while compressing price floors for commodity connectivity services.
Pricing Analysis
North American deployment costs run 15-25 percent above Southeast Asian benchmarks due to FedNow latency requirements and SEC custody rule compliance overhead. Three-tier pricing structure across premium managed services, mid-tier security offerings, and economy connectivity bundles dominates procurement. Cost compression in cloud connectivity tiers is intensifying because payment processors are consolidating vendor relationships to satisfy Federal Reserve operational resilience mandates. Retail banks exhibit highest price sensitivity due to legacy core maintenance burdens, while hedge funds and proprietary trading desks absorb premium pricing for sub-50 millisecond latency guarantees.
Supply Chain Analysis
Submarine cable landing stations in Marseille, Mumbai, and Singapore constitute critical chokepoints for encrypted transit fabric delivery to financial centers. Component sourcing draws from Taiwan for advanced switching silicon, Israel for encryption acceleration hardware, and Ireland for EU-sovereign data residency infrastructure. Single-source vulnerability concentrates in NIST post-quantum cryptography chip supply pending final standard ratification. Distribution runs through hyperscaler marketplaces for public cloud deployments and systems integrators with mainframe expertise for hybrid configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-cloud networking in fintech sits within an early-cycle expansion phase as regulatory mandates for operational resilience force architectural refresh across institutions that previously deferred cloud-native investment.
For Market Incumbents: Fortify controller architecture differentiation against service mesh disintermediation by deepening API management platform integration for open banking interoperability. Expand Contrail-based and NSX-certified engineering capacity in Frankfurt and Singapore to capture EU Digital Operational Resilience Act and MAS technology risk management compliance cycles ahead of mid-tier competitors. For New Entrants and Emerging Players: Lead with sovereign cloud node deployment in Jakarta and Bangalore to serve digital banking license recipients without legacy core baggage. Target health-fintech hybrid segments requiring HIPAA-aligned encrypted transit fabrics, where incumbent hardware vendors carry pricing premiums that cloud-native architectures can undercut through NFV-based delivery models. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed security service providers with FedRAMP and PCI DSS 4.0 certification pipelines already in process. Acquisition focus should center on cloud-native controller vendors with production-scale Istio or Linkerd deployments at tier-one banks, monitoring NIST post-quantum standard finalization as the signal for control plane infrastructure refresh inflection.| Strategic Initiative | Industry Significance |
|---|---|
| API Management Platform Acquisition | Secures control plane positioning for open banking interoperability mandates under EU DORA. |
| Sovereign Cloud Node Deployment | Satisfies GDPR Article 44 transfer limitations for Frankfurt and Paris banking concentrations. |
| Service Mesh Production Certification | Validates replacement of hardware load balancers for containerized payment microservices at scale. |
| SD-WAN and SASE Convergence | Captures attach-rate expansion for distributed trading floors requiring unified edge-to-cloud fabrics. |
| Post-Quantum Cryptography Readiness | Positions for NIST standard finalization without forklift upgrades to existing encryption layers. |
Methodological Framework
Cross-validation between primary interviews with cloud architects, Site Reliability Engineers, and compliance officers at payment processors and retail banks anchors the qualitative findings against secondary validation from SEC 10-K filings, RBI technology governance circulars, and hyperscaler capex disclosures. Bottom-up triangulation against top-down regulatory mandate sizing ensures segmentation integrity across deployment models, service types, and client archetypes.
Sensitivity analysis around latency threshold compliance costs and SRE compensation premium trajectories informs the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment model complexity, service tier bundling, client regulatory burden intensity, and regional sovereign data routing requirements. CAGRs derive from adoption curve benchmarking against prior infrastructure refresh cycles, with FedNow transaction volume growth and EU DORA enforcement timelines serving as industry-specific demand inputs.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement intensity or accelerated NIST standard finalization would require recalibration. Practitioners should keep alternative scenarios live as quantum-resistant encryption procurement freeze-thaw dynamics and Southeast Asian digital banking license issuance patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Information and Communication Technology
Intelligent Enterprise Data Capture Software Market
Information and Communication Technology
Commercial Service Robotics Market
Information and Communication Technology
Global Mindfulness Meditation Apps Market
Information and Communication Technology
Hong Kong Data Center Server Market
Information and Communication Technology
Asia-Pacific Encryption Software Market
Information and Communication Technology
Homomorphic Encryption Market
Information and Communication Technology
Cognitive Services Platform Market
Information and Communication Technology
Semantic Knowledge Graphing Market
Information and Communication Technology
Construction Simulation Software Market
Information and Communication Technology
File Sharing Market
Information and Communication Technology
Global SD WAN Market
Information and Communication Technology
Digital Certificates Market
Information and Communication Technology
India Communication Platform As a Service (Cpaas) Market
Information and Communication Technology
Asia Pacific B2C Legal Services Market
Information and Communication Technology
Canada Data Center Storage Market
Information and Communication Technology
Singapore Cloud Robotics Market