
 Global Video Streaming Software Market | 2026-2036
Global Video Streaming Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Video Streaming Software Market Foresight
Ultra-low latency specifications is redrawing competitive boundaries across the Global Video Streaming Software Market. Brightcove Inc. anchors its position through specialized live-event delivery infrastructure for tier-one broadcasters. Wowza Media Systems, LLC differentiates via modular edge-computing deployments that extend on-premises control into distributed workflows. Amazon Web Services, Inc. dominates cloud-native transcoding scale, leveraging its captive data-center footprint to compress unit economics for high-bitrate 4K pipelines.
Video streaming software comprises encoder-decoder architectures, adaptive bitrate algorithms, and content delivery network orchestration layers that ingest, transcode, and distribute audiovisual streams across IP networks. These systems operate on latency thresholds measured in milliseconds for live use cases and sustain concurrent viewer densities exceeding millions of sessions per origin server. Cloud-based deployment captures the dominant margin pool as enterprises abandon capital-intensive on-premises hardware refresh cycles. Live Streaming and OTT Platforms represent the fastest-expanding solution categories, while Video Conferencing retains mature, replacement-driven demand patterns concentrated in corporate communications.
FCC net-neutrality rulings in the United States, GDPR data-localization mandates enforced by European regulators, and India's TRAI content-censorship frameworks collectively shape platform architecture decisions and geographic rollout sequencing. The EU AI Act adds algorithmic transparency requirements for recommendation engines, forcing engineering teams to rebuild personalization stacks. Stakeholders must monitor how sovereign-cloud certifications in Germany, India, and Brazil fragment previously unified product roadmaps into jurisdiction-specific compliance variants.
Market Dynamics
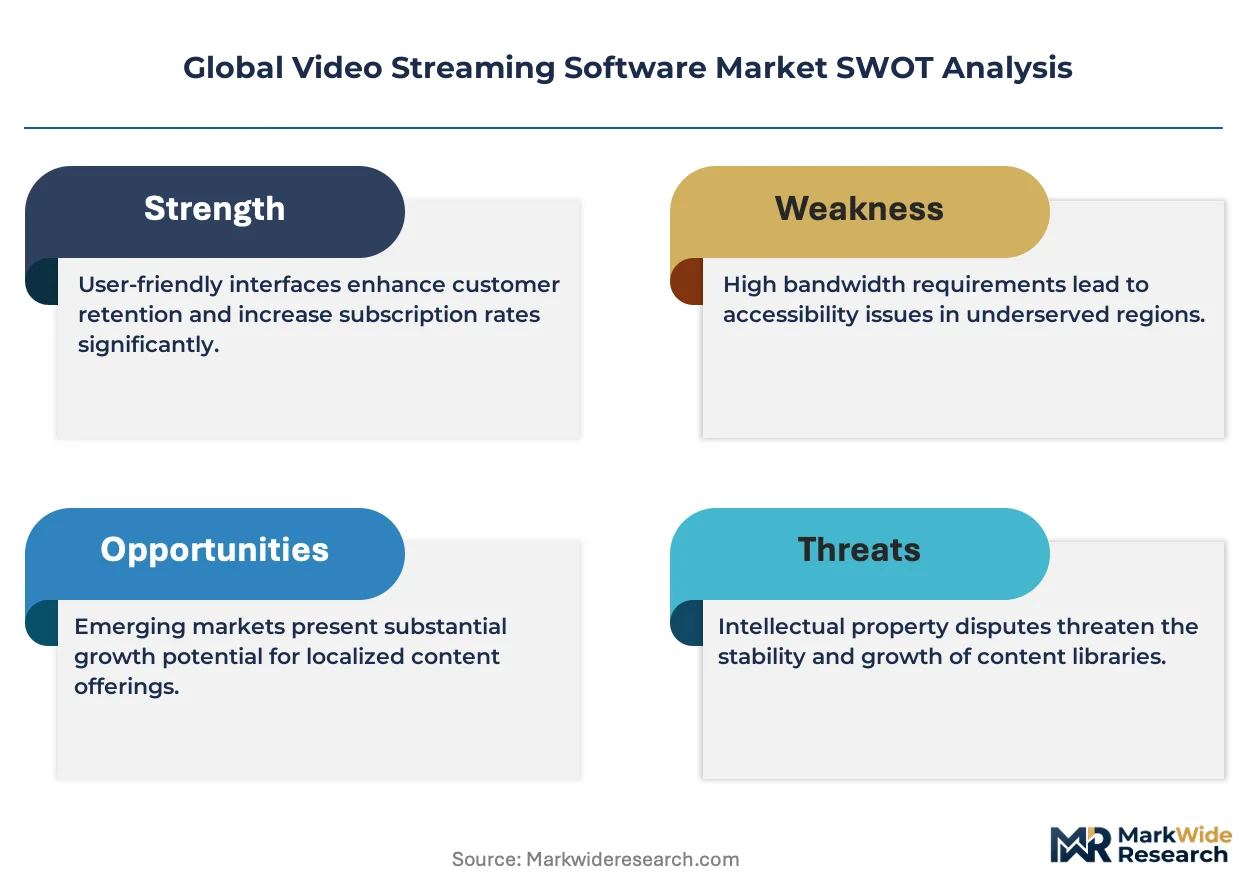
Ultra-low latency protocols are compressing competitive margins across video streaming infrastructure, forcing vendors to rebuild encoding stacks around sub-second delivery specifications. The EU AI Act's algorithmic transparency mandates are simultaneously fragmenting personalization architectures into jurisdiction-specific variants.
Growth Catalysts
- Enterprise LMS Replacement:Corporations are dismantling legacy training infrastructure and migrating to cloud-native streaming platforms. This shift accelerates demand for integrated analytics and adaptive bitrate delivery.
- GDPR Sovereign Data Residency:European enterprises now require localized content processing nodes. Compliance investments are expanding addressable infrastructure spend across Germany, France, and the Netherlands.
- India Telecom Bundling:Mobile broadband operators in India are pre-installing streaming applications on subscriber devices. This channel integration is driving platform adoption at unprecedented velocity.
Market Restraints
- Transcoding Cost Volatility:GPU and specialized ASIC pricing fluctuations compress margins for high-bitrate 4K pipelines. Cloud-native providers face unpredictable unit economics during peak encoding loads.
- CDN Concentration Risk:Three hyperscale providers control over seventy percent of global edge capacity. This supply-side consolidation creates single-point-of-failure exposure for tier-one broadcasters.
- Codec Licensing Complexity:Patent pools around HEVC and emerging VVC standards impose per-stream royalty obligations. Independent software vendors face prohibitive compliance overhead versus integrated platform competitors.
Strategic Opportunities
- Brazil Regulatory Tailwind:ANVISA and ANATEL are mandating local data processing for health and educational streaming content. Early certification positions vendors for captive public-sector contracts.
- Edge-AI Convergence:On-device inference engines are merging with streaming clients for real-time personalization. This architecture eliminates round-trip latency to centralized recommendation servers.
- API-First Distribution:Headless streaming infrastructure is displacing monolithic platform sales. Developer-centric licensing opens mid-market penetration previously blocked by enterprise contract minimums.
Industry Challenges
- Real-Time Systems Engineering Talent:Sub-100-millisecond pipeline optimization requires specialized expertise in kernel-level networking and hardware-accelerated encoding. This skill scarcity inflates compensation and extends hiring cycles.
- Legacy Broadcast Integration:SDI-to-IP migration demands simultaneous support for 50-year-old coaxial infrastructure and modern cloud workflows. Dual-stack engineering bifurcates R&D roadmaps and dilutes feature velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Video Streaming Software Market |
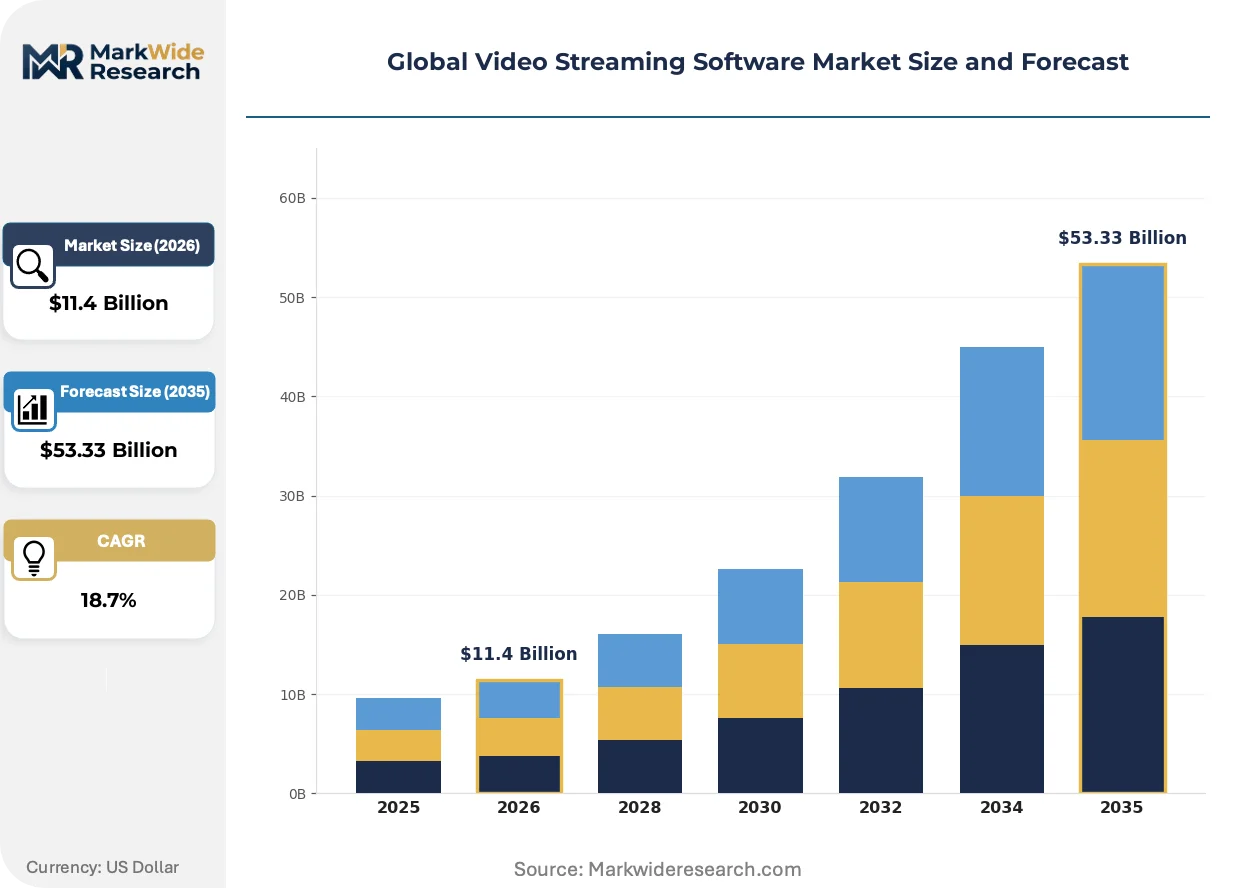
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $53.33 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Solution Type: Live Streaming, Video on Demand, OTT Platforms, Video Conferencing, Webinar Software Use Case: Education & E-learning, Entertainment & Media, Corporate Communications, Sports Broadcasting, Government & Public Sector End User Industry: Telecommunications, Online Gaming, Financial Services, News Agencies, Social Media Networks |
| Companies Covered | IBM Corporation, Brightcove Inc., Kaltura Inc., Vimeo.com, Inc., Microsoft Corporation, Google LLC, Amazon Web Services, Inc., Akamai Technologies, Inc., Wowza Media Systems, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Video Streaming Software Market Shifts & Advancements
Codec innovation and regulatory fragmentation are simultaneously compressing delivery costs and multiplying compliance architectures. Engineering teams must now optimize for performance per bit while rebuilding stacks for jurisdiction-specific algorithmic transparency.
AV1 encoder-decoder implementations are miniaturizing across mobile chipsets and smart television SoCs. Consumer electronics manufacturers in South Korea and Taiwan are integrating hardware-accelerated AV1 decode at mass-market price points. This silicon-level adoption is miniaturizing the premium streaming tier, collapsing the historical gap between broadcast-quality and internet-delivered video fidelity.
The EU AI Act's recommendation engine disclosure requirements are forcing platform operators to document training data provenance and ranking logic. Engineering teams must now maintain parallel personalization stacks: opaque models for non-EU markets and explainable architectures for European users. OTT platforms with heavy European subscriber bases are experiencing the most severe architecture refactoring costs.
Self-service API provisioning is displacing traditional enterprise sales cycles for mid-market streaming deployments. Developer portals with usage-based billing are replacing annual platform licenses for regional broadcasters and niche content aggregators. India and Southeast Asia exhibit the fastest channel transformation, where capital-constrained operators prefer operational expenditure models over upfront infrastructure investment.
Global Video Streaming Software Market Segmentation
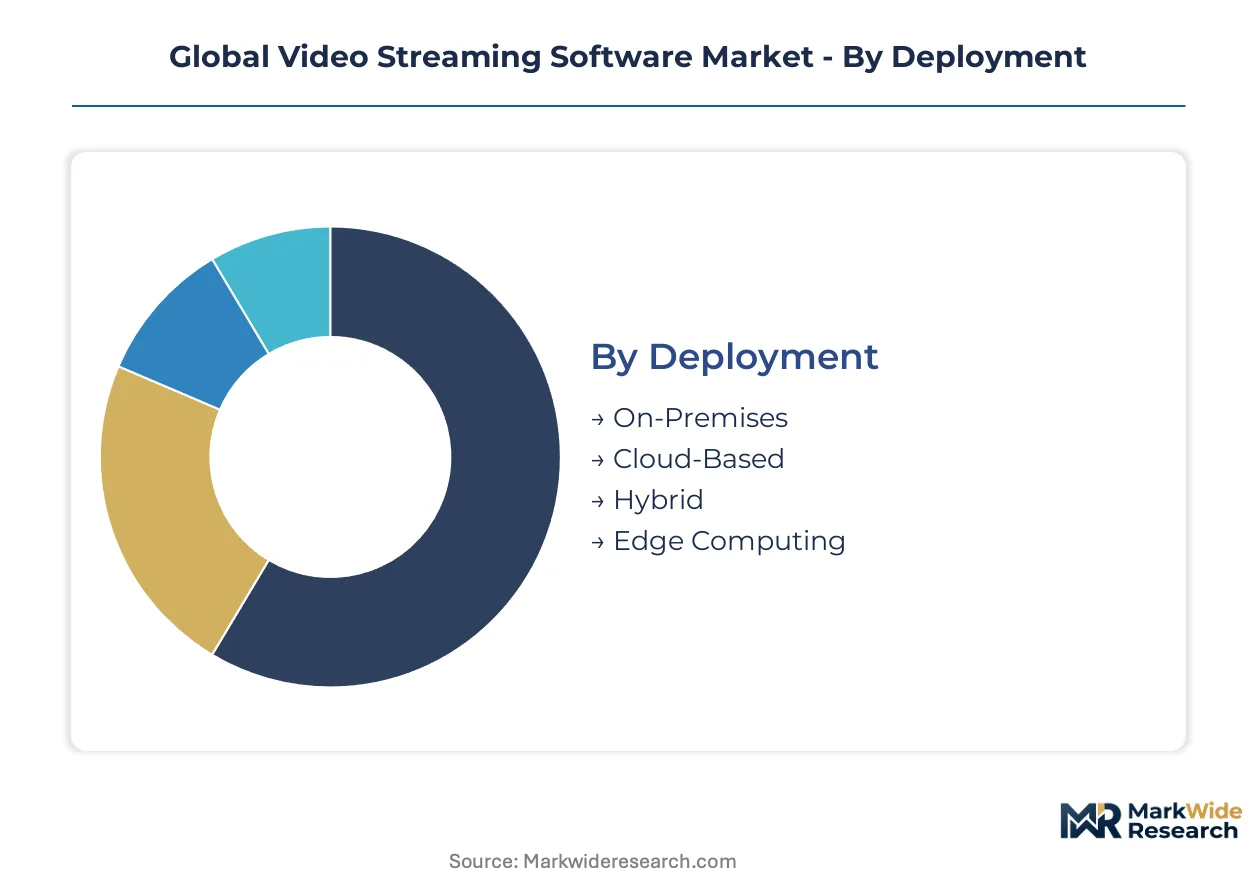
Segmentation in video streaming software reveals divergent infrastructure economics across deployment models and sharply contrasting regulatory exposure by use case. Understanding these fault lines enables vendors to calibrate R&D investment and compliance architecture against actual revenue concentration rather than assumed uniformity.
Deployment:
Cloud-based deployments dominate North American enterprise adoption, while edge computing solutions concentrate in Asia-Pacific telecom infrastructure. On-premises retains defensive positions in European financial services and government verticals where data sovereignty mandates prevail.
- Cloud-Based:Fully managed transcoding and CDN orchestration delivered via hyperscale data centers. Demand concentrates among mid-market broadcasters in the United States seeking to eliminate capital refresh cycles. GDPR sovereign data residency requirements are accelerating localized node deployment across Germany and France.
- Edge Computing:Distributed encoding and caching at network periphery, minimizing round-trip latency for live use cases. Telecom operators in India bundle edge-integrated streaming with mobile broadband subscriptions. TRAI content-censorship frameworks require on-device processing for compliance verification.
- On-Premises:Captive hardware infrastructure with direct control over encoding pipelines and storage arrays.
- Hybrid:Workload-splitting architectures combining private data centers with burst capacity to public cloud.
Cloud-based holds the largest share; momentum sits with edge computing.
Solution Type:
Cost tier stratification separates premium live-event infrastructure from commoditized video conferencing, with OTT platforms occupying the contested middle ground where subscriber acquisition economics determine vendor selection.
- OTT Platforms:Subscription and ad-supported streaming services with integrated content management and recommendation engines. Entertainment conglomerates in South Korea and Taiwan drive hardware-accelerated AV1 decode integration. EU AI Act algorithmic transparency mandates are forcing parallel personalization stack architectures.
- Live Streaming:Sub-second latency delivery infrastructure for real-time audience engagement. Tier-one broadcasters in the United States demand FCC net-neutrality-compliant traffic prioritization. Ultra-low latency specifications are compressing competitive margins across encoding vendor tiers.
- Video on Demand:Catalog-based streaming with asynchronous content delivery and adaptive bitrate optimization.
- Video Conferencing:Bidirectional real-time communication with screen sharing and recording capabilities.
- Webinar Software:Scalable one-to-many presentation platforms with audience interaction tools.
OTT platforms command the dominant revenue pool; steepest expansion trajectory belongs to live streaming.
Use Case:
Application maturity varies dramatically: corporate communications exhibits replacement-driven demand patterns while sports broadcasting demands continuous infrastructure investment for peak concurrent load handling.
- Corporate Communications:Internal streaming for town halls, training, and executive messaging. Enterprise LMS replacement cycles in Germany and the Netherlands are dismantling legacy training infrastructure. Integrated analytics and adaptive bitrate delivery are accelerating cloud-native platform migration.
- Sports Broadcasting:Premium live-event delivery with multi-camera synchronization and interactive overlays. Broadcasters in Brazil face ANATEL local data processing mandates for educational and health-adjacent content. Early certification positions vendors for captive public-sector contract capture.
- Education & E-learning:Asynchronous course delivery and synchronous virtual classroom infrastructure.
- Entertainment & Media:Consumer-facing content distribution with monetization through subscription or advertising.
- Government & Public Sector:Secure streaming with classification-aware access controls and audit logging.
Corporate communications holds the largest share; momentum sits with sports broadcasting.
End User Industry:
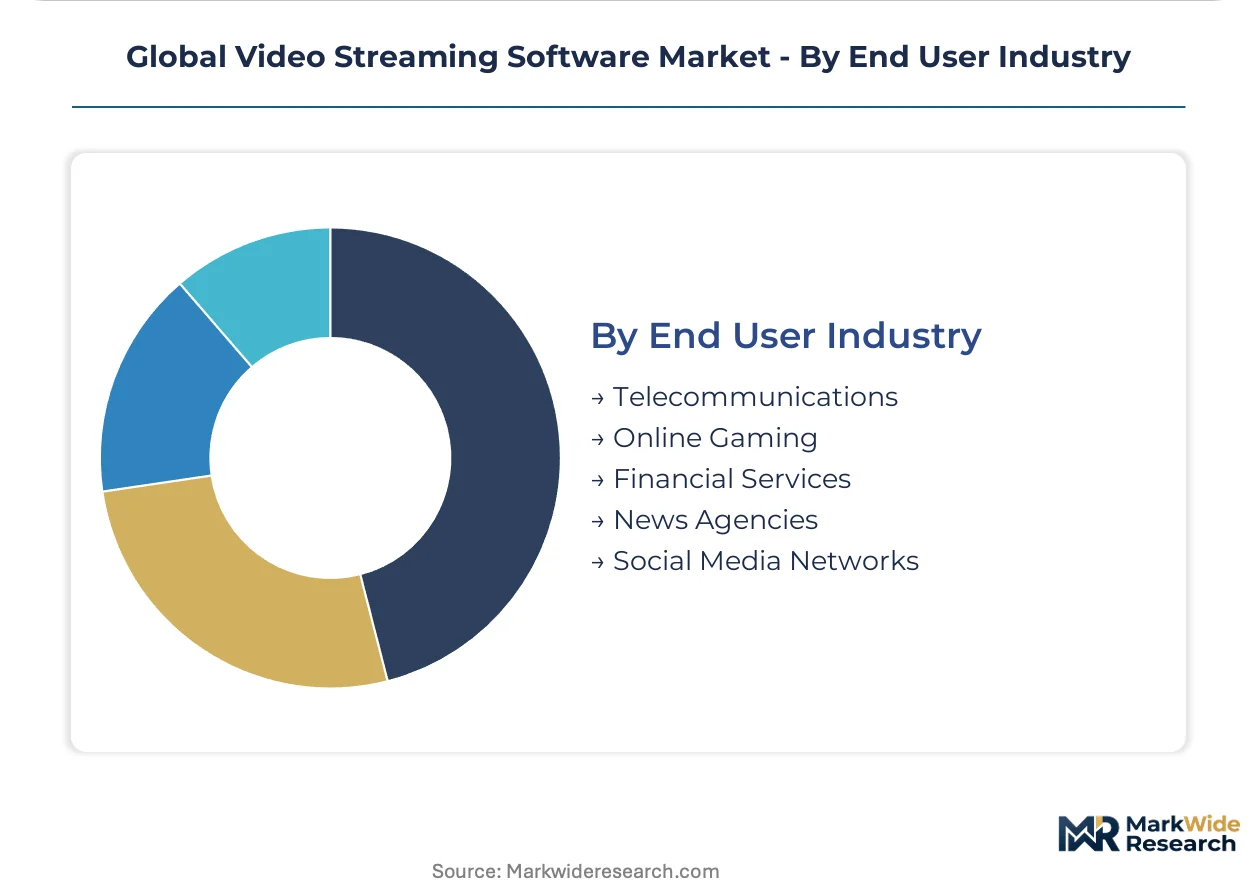
Customer type concentration reveals telecommunications as the channel gatekeeper, while financial services imposes the most stringent compliance overlay on vendor selection criteria.
- Telecommunications:Infrastructure operators bundling streaming platforms with connectivity services. Mobile broadband providers in India pre-install applications on subscriber devices. This channel integration is driving platform adoption velocity unmatched in direct-to-consumer markets.
- Financial Services:Secure streaming for investor relations, compliance training, and client communications. Institutions in Switzerland and Luxembourg require Swissmedic-equivalent data protection certifications. API-first distribution models are displacing traditional enterprise sales cycles.
- Online Gaming:Interactive streaming with low-latency requirements for cloud gaming and esports.
- News Agencies:Rapid-deployment live streaming for breaking news and field reporting.
- Social Media Networks:User-generated content ingestion and algorithmic distribution at massive scale.
Telecommunications holds the largest share; gaining share fastest is financial services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial surplus in video streaming software exports, while India and Germany import specialized encoding and compliance modules to anchor localized service delivery. Net trade flows concentrate intellectual property development in North American hyperscale clusters, with deployment infrastructure diffusing across sovereign data residency jurisdictions.
United States
Enterprise broadcasters and hyperscale cloud operators drive infrastructure procurement across California and Washington state. FCC net-neutrality rulings shape traffic prioritization specifications for live-event delivery pipelines. Seattle and San Francisco Bay Area clusters host the dominant share of global transcoding R&D and CDN orchestration engineering.
Germany
Financial services institutions and automotive manufacturers mandate sovereign data processing for investor relations and training content. GDPR enforcement by CNIL-equivalent state regulators requires localized node certification for cross-border stream processing. Berlin and Munich host specialized compliance engineering centers serving DACH-region enterprise clients.
India
Telecom operators bundle streaming platforms with mobile broadband subscriptions, driving platform adoption velocity unmatched in direct-to-consumer channels. TRAI content-censorship frameworks require on-device processing for compliance verification. Bangalore and Hyderabad clusters concentrate edge-computing engineering talent for distributed encoding deployments.
Brazil
Public-sector health and educational streaming mandates create captive contract opportunities for certified vendors. ANVISA and ANATEL jointly enforce local data processing requirements for sensitive content categories. São Paulo anchors the regional infrastructure deployment hub for Latin American OTT platform expansion.
South Korea
Consumer electronics manufacturers integrate hardware-accelerated AV1 decode at mass-market price points, collapsing fidelity gaps between broadcast and internet delivery. National broadcast regulators enforce accessibility and content-rating standards for streaming platforms. Seoul-based semiconductor clusters supply silicon-level encoding acceleration to global streaming infrastructure vendors.
Global Video Streaming Software Market Competitive Landscape
Listed leaders compete with private specialists across capitalization and R&D velocity dimensions. Public cloud hyperscalers and enterprise software conglomerates anchor the consolidated tier, while venture-backed encoding specialists and regional platform developers occupy fragmented mid-market positions. Strategic archetypes separate scale-driven infrastructure operators, compliance-focused sovereign-cloud vendors, and modular API-first developers. Competitive moves concentrate on M&A for specialized encoding talent and strategic partnerships for edge-computing distribution.
Within the hyperscale infrastructure tier, Amazon Web Services, Inc. and Microsoft Corporation exemplify scale-driven platform consolidation, while Brightcove Inc. occupies a position representing specialized live-event delivery for tier-one broadcasters. These three entities anchor distinct competitive vectors: captive data-center economics, enterprise software integration, and vertical-specific workflow optimization.
| Leading Market Players |
|---|
| IBM Corporation |
| Brightcove Inc. |
| Kaltura Inc. |
| Vimeo.com, Inc. |
| Microsoft Corporation |
| Google LLC |
| Amazon Web Services, Inc. |
| Akamai Technologies, Inc. |
| Wowza Media Systems, LLC |
| Others |
Supply & Pricing Matrix
GDPR sovereign data residency certifications gate both supplier qualification and price differentiation across European enterprise contracts. Vendors lacking localized node deployment in Germany or France face automatic disqualification from financial services procurement, compressing competitive intensity among certified players while permitting premium pricing for compliant infrastructure.
Pricing Analysis
Enterprise broadcasters anchor three-tier pricing structure across premium, standard, and economy levels in video streaming software procurement. Price differentiation hinges on latency specification guarantees and EU AI Act algorithmic transparency compliance tier. Cost compression in cloud-native transcoding tiers is intensifying because GPU and ASIC pricing volatility erodes margins during peak encoding loads. Mid-market regional broadcasters exhibit highest price sensitivity, while tier-one broadcasters prioritize sub-second latency over unit cost.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes elevates inbound logistics costs for encoding hardware destined for Indian telecom infrastructure deployments. Manufacturing concentration centers on Taiwan for semiconductor components, South Korea for display panel integration, and China for assembly and testing operations. Raw material dependencies span silicon wafers, specialized video encoding ASICs, and high-bandwidth memory modules. Single-source vulnerability around hyperscale CDN edge capacity creates concentration risk. Distribution runs through direct hyperscaler procurement for cloud-based deployments and systems integrator channels for on-premises installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-source encoding stacks and commodity cloud infrastructure threaten proprietary platform incumbents with functional substitution at zero licensing cost.
For Market Incumbents: Fortify defensive moats through captive certification investments in Brazil ANVISA and Germany BSI sovereign cloud frameworks. Deepen backward integration into edge-computing silicon design to escape hyperscaler CDN dependency. Open-source codec proliferation represents the paramount substitution threat requiring proprietary optimization layers. For New Entrants and Emerging Players: Anchor in API-first distribution models targeting capital-constrained regional broadcasters in Southeast Asia. Brazil public-sector health streaming mandates offer the most penetrable white-space given early certification requirements. Developer-centric usage-based billing displaces traditional enterprise minimums as the decisive go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across edge-AI convergence sub-segments as on-device inference eliminates centralized infrastructure requirements. Long-term viability favors modular API-first developers with established developer portal traction over monolithic platform incumbents. Acquisition target archetype: venture-backed encoding specialists with TRAI compliance certification for Indian telecom channels. Signal to watch: hyperscaler capex allocation shifts toward sovereign cloud node deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Convergence Development | On-device personalization engines eliminate round-trip latency to centralized AWS recommendation servers. |
| Sovereign Cloud Certification | BSI and ANVISA compliance positions vendors for captive German automotive and Brazilian public-sector contracts. |
| API-First Platform Launch | Developer portals with usage-based billing penetrate mid-market broadcasters previously blocked by enterprise minimums. |
| AV1 Hardware Acceleration Partnership | Samsung and MediaTek silicon integration collapses fidelity gaps between broadcast and internet delivery tiers. |
| Strategic Partnership with Telecom Operators | Jio and Airtel bundling agreements drive platform adoption velocity unmatched in direct-to-consumer channels. |
Research Methodology
Cross-validation between hyperscaler capex disclosures and telecom operator procurement databases anchors the qualitative findings in this study. Primary interviews with CTOs at tier-one broadcasters, platform engineering leads at OTT operators, channel partners in Indian telecom infrastructure, and integration specialists at enterprise LMS vendors combined with secondary validation. SEC 10-K filings, TRAI regulatory notifications, EU AI Act implementation guidance, and hyperscaler infrastructure investment reports provided bottom-up and top-down triangulation.
Sensitivity analysis around GPU pricing volatility and CDN capacity expansion timelines informs the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution type, end-user industry, and regional regulatory cluster. CAGRs derive from installed base growth rates and average revenue per account expansion trajectories. Forecast inputs incorporate live streaming concurrent viewer density requirements and sovereign data residency mandate implementation schedules.
Material uncertainties — codec licensing pool litigation outcomes, hyperscaler CDN pricing resets, and EU AI Act enforcement severity — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation timelines and enterprise cloud migration velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Vendor Management Software Market
Software & Services
User Research Repositories Software Market
Software & Services
Nonconformance Management Software Market
Software & Services
Business Rules Management System Market
Software & Services
Latin America ERP Software Market
Software & Services
Device Tracking Software Market
Software & Services
Procure to Pay Software Market
Software & Services
Poultry Farm Management Software Market
Software & Services
Medical Equipment Repair Software Market
Software & Services
Radio Propagation Software Market
Software & Services
App Building Software Market
Software & Services
Mindfulness Meditation Application Market
Software & Services
Geophysical Software Service Market
Software & Services
Embedded Operating Systems Market
Software & Services
Bridge Analysis Software Market
Software & Services
Decision Support System (DSS) Software Market