
 App Creation Software Market | 2026-2036
App Creation Software Market Size, Share, and Industry Trends Forecast 2026-2036
App Creation Software Market Analysis
Low-code and no-code abstraction is tilting enterprise software development toward citizen developers and line-of-business teams. OutSystems leverages deep vertical integration across full-stack deployment to sustain premium positioning in regulated industries. Mendix anchors European manufacturing and industrial IoT use cases through Siemens channel control. Bubble Group Inc specializes in frontend design flexibility, competing for startup and freelancer segments where speed-to-launch dominates purchasing criteria.
App creation software encompasses platforms, tools, and environments that enable users to design, build, test, and deploy software applications through visual interfaces, pre-built components, and declarative logic rather than traditional hand-coding, typically supporting web and mobile output with integrated database and API connectivity. These systems serve commercial purposes by collapsing development cycles from months to days while reducing dependency on scarce professional developer talent. Cloud-based deployment leads volume adoption due to elastic scaling and reduced infrastructure overhead, though on-premises installations retain strongholds in banking and defense sectors where data sovereignty governs procurement. Low-code functionality captures the broadest enterprise wallet share by balancing accessibility with customization depth, while no-code segments expand fastest among small businesses and marketing departments seeking zero technical onboarding.
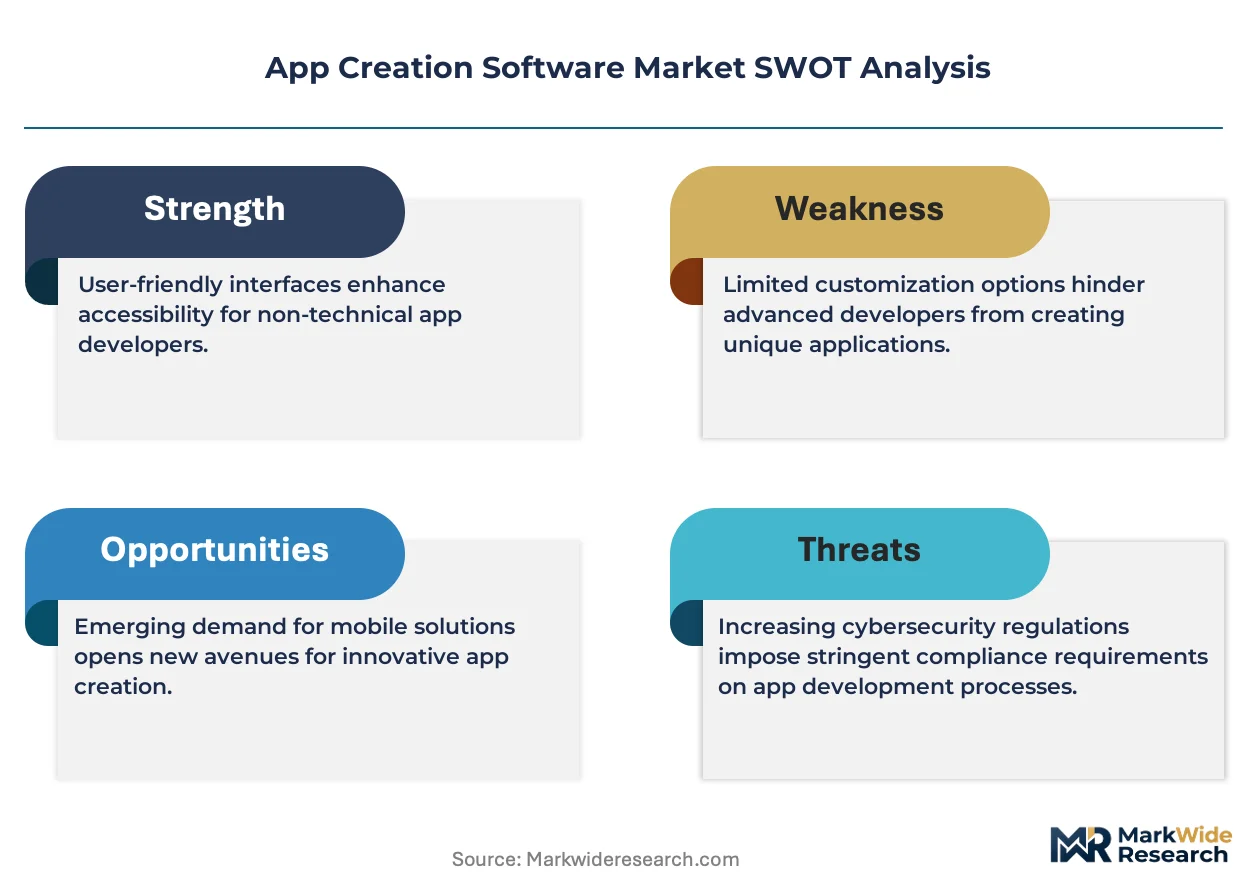
FDA scrutiny of software-as-medical-device classifications shapes how healthcare-facing platforms architect validation trails and audit logging. The EU AI Act imposes conformity assessments on app modules deploying automated credit decisions or biometric identification, directly affecting product roadmaps for finance and retail verticals. GDPR data portability requirements force template-based and SaaS providers to engineer granular export and deletion workflows. Stakeholders must weigh regulatory trajectory against platform lock-in risks when selecting architecture partners for multi-year digital transformation programs.
Market Dynamics
Enterprise IT departments face acute developer shortages while HIPAA and the EU AI Act impose escalating compliance burdens on software outputs, forcing procurement teams toward platforms that embed audit trails and validation documentation natively.
Growth Catalysts
- HIPAA-mandated audit logging:Healthcare providers in the United States require patient-facing apps with built-in compliance documentation, accelerating demand for platforms that automate validation workflows.
- Industrial IoT deployment:German and Dutch manufacturing conglomerates deploy shop-floor applications without embedded software teams, expanding the addressable base for visual development environments.
- Cloud-native architecture:Elastic scaling and API-first design patterns reduce infrastructure overhead for mid-market buyers previously blocked by capital constraints.
Market Restraints
- EU AI Act conformity assessments:Automated decision-making modules in finance and retail verticals face mandatory third-party audits, extending sales cycles and elevating implementation costs.
- Specialized integration talent scarcity:Legacy system connectivity requires scarce API architecture expertise, creating bottlenecks for enterprise deployments.
- Platform lock-in risk:Proprietary runtime environments and data schemas complicate migration, deterring risk-averse procurement committees from multi-year commitments.
Strategic Opportunities
- GDPR data portability mandates:Template-based providers can differentiate by engineering granular export and deletion workflows that exceed baseline compliance.
- Biometric identification modules:Convergence of computer vision APIs and no-code frontends opens retail and security applications previously requiring dedicated engineering teams.
- Indian SME digitization:The country's central bank push for financial inclusion creates demand for customer-facing apps among non-technology small businesses.
Industry Challenges
- Citizen developer governance:Line-of-business teams lack secure coding practices, exposing organizations to data leakage and compliance violations.
- Multi-environment deployment complexity:Synchronizing versions across on-premises banking infrastructure and cloud instances requires DevOps capabilities most buyers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | App Creation Software Market |
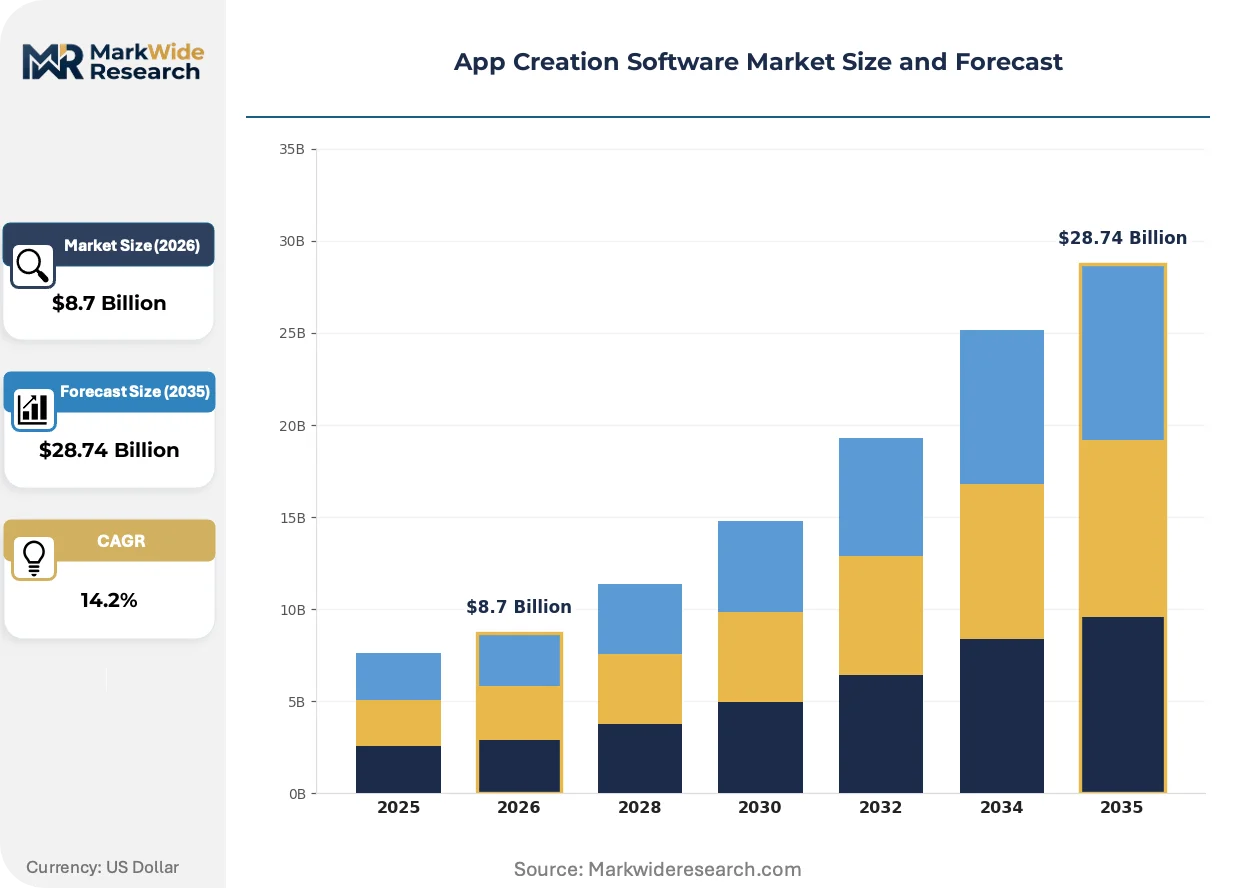
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS User Type: Small Businesses, Enterprises, Freelancers, Startups Functionality: Low-Code, No-Code, Pro-Code, Template-Based Industry Vertical: Education, Healthcare, Retail, Finance |
| Companies Covered | Appian Corporation, OutSystems, Mendix, Zoho Corporation Pvt. Ltd., Pegasystems Inc., Quick Base Inc., Caspio Inc., Appy Pie LLC, Bubble Group Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
App Creation Software Market Emerging Trajectories
Visual abstraction layers are collapsing traditional software development hierarchies, enabling non-technical staff to own application lifecycles while embedding compliance and security controls at the infrastructure level.
Generative AI code assistants are digitizing specification-to-deployment pipelines by translating natural language prompts into functional application components. Marketing departments and freelance operators adopt these tools fastest, compressing prototype timelines from weeks to hours. The structural consequence is a redistribution of development authority from centralized IT to distributed business units.
The EU AI Act imposes conformity assessments on automated credit decisioning and biometric identification modules, forcing platform vendors to architect explainability features and audit logging natively. Finance and retail verticals face the steepest compliance gradients. Vendors respond by pre-certifying template libraries and embedding documentation generators that streamline third-party validation.
Enterprise buyers now unbundle implementation services from platform licensing, preferring fixed-scope professional engagements over traditional subscription-plus-support models. Systems integrators and boutique consultancies capture this margin. The United States exhibits this pattern most acutely, where IT procurement teams prioritize cost predictability in multi-year digital transformation programs.
App Creation Software Market Segmentation
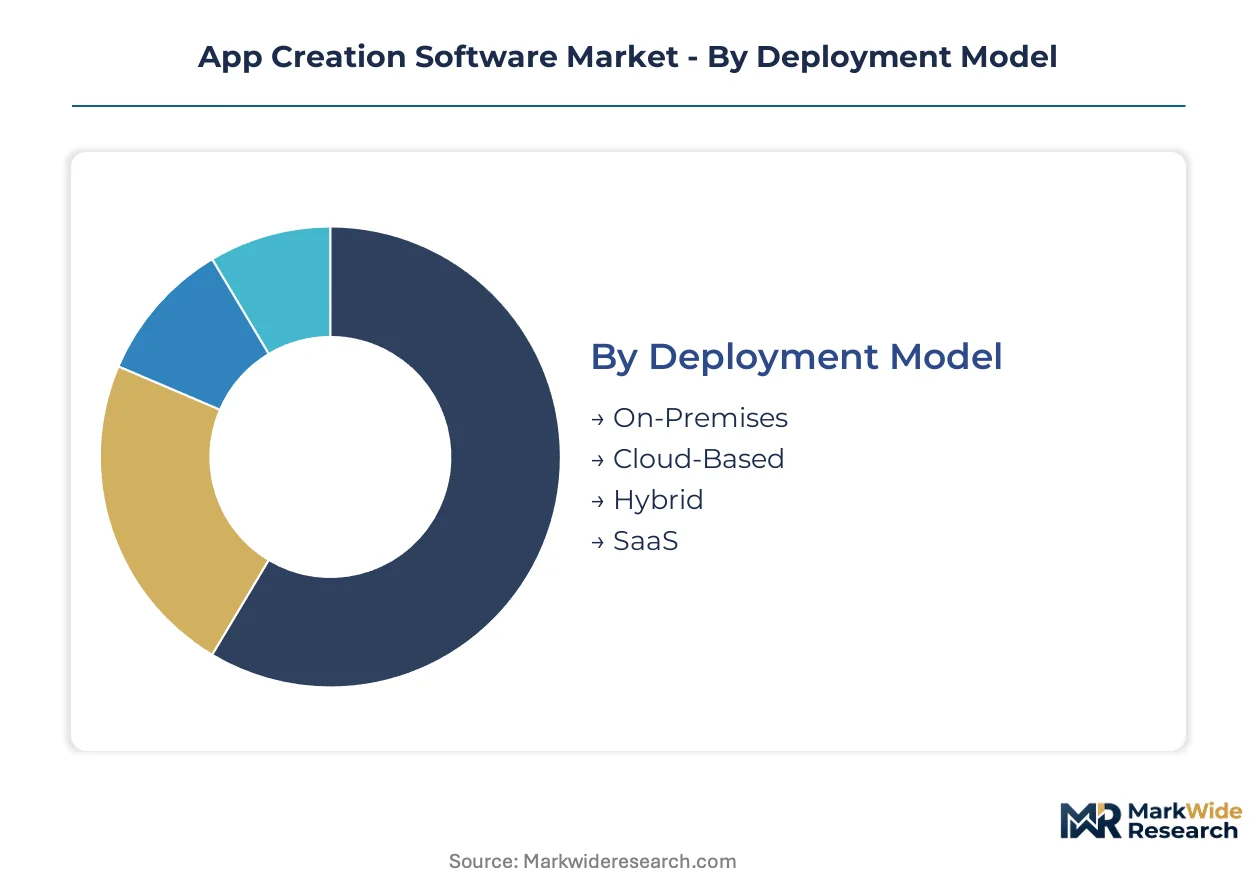
Segmentation in app creation software reveals how procurement priorities diverge between regulated enterprises seeking compliance infrastructure and agile teams prioritizing launch velocity. Platform vendors architect feature sets around these tension points, embedding audit trails for healthcare and finance while stripping friction for startup and freelance segments.
Deployment Model:
Deployment architecture spans a cost-to-control spectrum, with data sovereignty requirements and capital constraints dictating selection across use cases.
- Cloud-Based:Elastic compute and storage resources scale with user demand without upfront infrastructure investment. Healthcare providers in the United States deploy patient-facing apps through HIPAA-compliant cloud instances to avoid capital expenditure on physical servers.
- SaaS:Subscription pricing bundles runtime, maintenance, and security updates into predictable operational expenditure. Marketing departments and small businesses favor this model for zero-touch infrastructure management and rapid onboarding.
- On-Premises:Self-hosted installations retain full data custody within organizational firewalls, satisfying defense and banking sector procurement requirements.
- Hybrid:Split architectures isolate sensitive workloads on-premises while bursting compute-intensive operations to public cloud resources.
The dominant share belongs to Cloud-Based, while SaaS is closing the gap fastest.
User Type:
Customer archetypes range from resource-constrained individual operators to procurement committees managing multi-year digital transformation budgets.
- Enterprises:IT departments purchase platform licenses across thousands of seats, mandating SSO integration, role-based access controls, and audit logging. Siemens channel partners drive Mendix adoption among German manufacturing conglomerates seeking shop-floor digitization without embedded software teams.
- Startups:Pre-revenue ventures prioritize speed-to-launch over customization depth, accepting template constraints to compress fundraising timelines. Bubble Group Inc captures this segment through frontend design flexibility and rapid prototyping capabilities.
- Small Businesses:Owner-operators seek customer-facing apps for appointment scheduling, inventory management, and payment processing without technical staff.
- Freelancers:Independent developers and designers resell white-label applications to local clients, valuing exportable code and custom domain support.
Enterprise procurement commands the largest revenue pool, though startup adoption is expanding most quickly.
Functionality:
Abstraction depth determines who controls the application lifecycle, from declarative visual builders to professional IDE environments.
- Low-Code:Visual interfaces with optional code extension balance accessibility and customization, capturing the broadest enterprise wallet share. OutSystems sustains premium positioning through full-stack deployment capabilities and deep vertical integration in regulated industries.
- No-Code:Purely declarative environments eliminate syntax requirements entirely, expanding fastest among small businesses and marketing departments seeking zero technical onboarding.
- Template-Based:Pre-configured industry applications accelerate deployment for common use cases like patient portals and e-commerce storefronts.
- Pro-Code:Traditional integrated development environments retain dominance where algorithmic complexity or hardware integration demands hand-optimized implementation.
Low-Code functionality holds the dominant position, while No-Code is gaining share fastest.
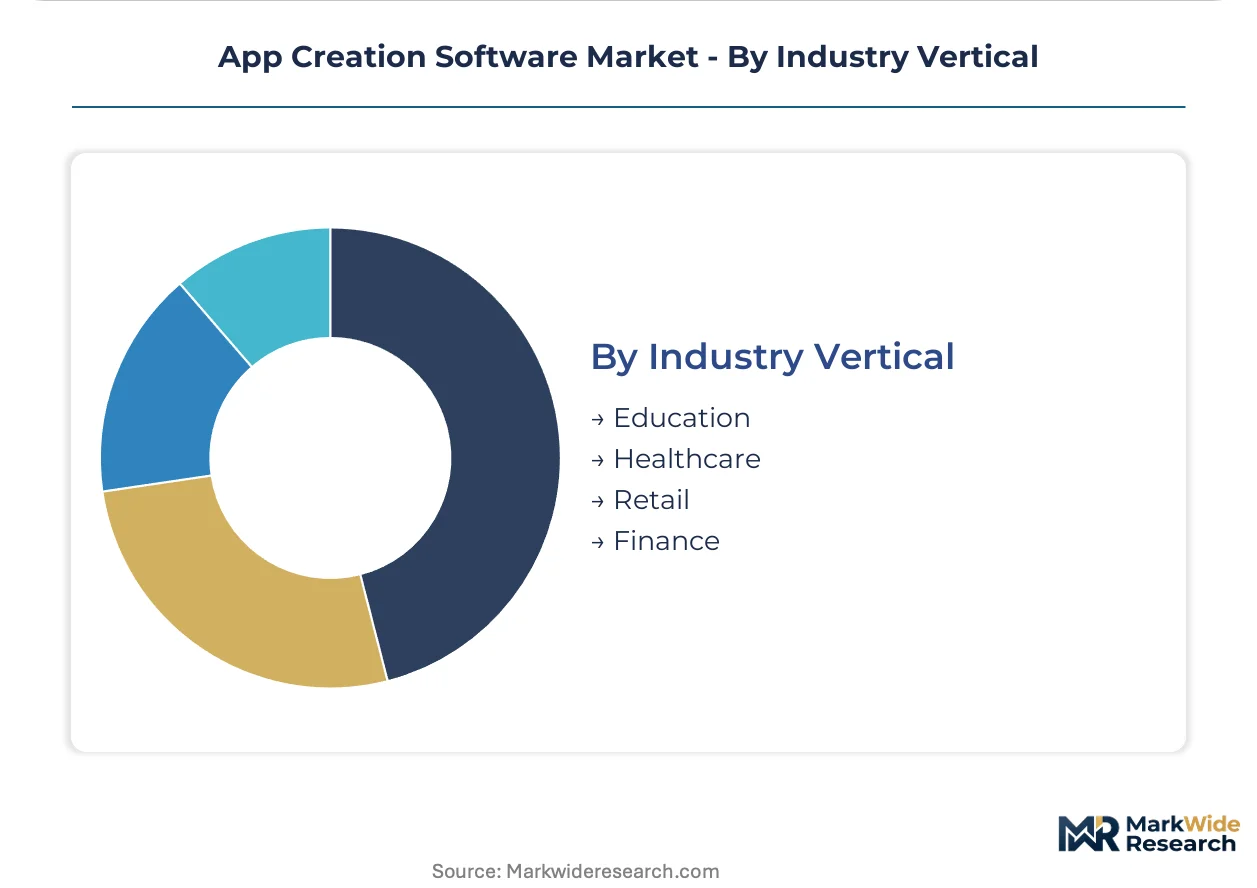
Industry Vertical:
Regulatory intensity and customer interaction models reshape platform requirements across end-use sectors.
- Healthcare:HIPAA-mandated audit logging and FDA software-as-medical-device classifications force platforms to automate validation workflows and documentation generation. United States providers now deploy patient-facing apps without dedicated engineering teams.
- Finance:The EU AI Act imposes conformity assessments on automated credit decisioning modules, requiring explainability features and third-party audit trails. Retail banking applications face the steepest compliance gradients.
- Retail:Convergence of computer vision APIs and no-code frontends opens biometric identification and personalized recommendation applications previously requiring dedicated engineering teams.
- Education:Learning management integrations and accessibility compliance (WCAG) drive procurement for student-facing administrative and instructional tools.
Healthcare commands the dominant vertical share, while Finance is climbing the fastest amid regulatory complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based platforms export subscription services to enterprise buyers across Germany, Japan, and India, with cloud delivery collapsing cross-border procurement friction. Regulatory divergence between HIPAA-mandated healthcare compliance and EU AI Act conformity assessments shapes regional product roadmaps. Capital concentration in Silicon Valley and Boston sustains R&D intensity unmatched by other geographies.
United States
Enterprise IT budgets and startup density generate the deepest customer base for visual development platforms. HIPAA mandates audit logging for patient-facing applications, forcing healthcare providers toward compliant cloud instances. Silicon Valley clusters anchor innovation in generative AI code assistants, with Boston's healthcare technology corridor driving FDA-aligned validation workflows.
Germany
Industrial IoT deployment across manufacturing conglomerates expands demand for shop-floor applications without embedded software teams. The EU AI Act imposes conformity assessments on automated decision-making modules, extending sales cycles for finance verticals. Siemens channel partners concentrate in Bavaria and Baden-Württemberg, driving Mendix adoption among automotive suppliers.
United Kingdom
Financial services digitization and freelance developer density sustain demand for rapid prototyping tools. GDPR data portability requirements force granular export and deletion workflows into platform architectures. London's fintech corridor concentrates procurement of low-code environments for credit decisioning applications subject to emerging AI accountability frameworks.
India
The Reserve Bank of India's financial inclusion push creates demand for customer-facing apps among non-technology small businesses. Central bank digital currency pilots and UPI infrastructure expansion accelerate SME digitization. Bengaluru and Hyderabad clusters host development centers serving export markets, with domestic procurement rising among Mumbai-Gujarat manufacturing networks.
Japan
Manufacturing conglomerates deploy shop-floor digitization tools to offset demographic constraints on professional developer hiring. METI industrial policy encourages SME technology adoption through subsidized platform access. Tokyo-Osaka corridor concentrates enterprise procurement, with Nagoya's automotive cluster driving specialized IoT application demand.
App Creation Software Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where vertical integration depth separates premium positioning from volume segments. The vendor base clusters around three strategic archetypes: full-stack deployment platforms with deep compliance integration, frontend-specialist tools targeting speed-to-launch buyers, and template-based providers serving zero-technical-onboarding segments. Dominant competitive moves include strategic partnerships with systems integrators and geographic expansion through localized compliance certification.
Within the full-stack tier, OutSystems and Mendix occupy positions defined by deployment architecture and channel control patterns. OutSystems exemplifies premium positioning through vertical integration across regulated industries, while Mendix anchors European manufacturing adoption through Siemens distribution infrastructure. Bubble Group Inc represents the frontend-specialist archetype, with speed-to-launch capabilities capturing startup and freelance segments where template flexibility dominates purchasing criteria.
| Leading Market Players |
|---|
| Appian Corporation |
| OutSystems |
| Mendix |
| Zoho Corporation Pvt. Ltd. |
| Pegasystems Inc. |
| Quick Base Inc. |
| Caspio Inc. |
| Appy Pie LLC |
| Bubble Group Inc |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific fiber-optic cable capacity costs are compressing cloud infrastructure delivery to enterprise buyers, concentrating pricing power among hyperscale platform operators while forcing regional SaaS providers into sharper subscription-tier differentiation. This corridor's cost dynamics amplify the technology-generation pricing gap that separates incumbent full-stack vendors from template-based challengers.
Pricing Analysis
Technology-generation pricing gaps separate current-gen AI-augmented platforms from prior-generation visual builders and emerging next-gen autonomous development environments. Three-tier pricing structure across premium, standard, and economy levels dominates, with HIPAA compliance certification and SSO integration capabilities driving tier placement. Pricing pressure stems from freemium no-code alternatives eroding entry-level subscriptions. Startups exhibit highest price sensitivity, while regulated healthcare enterprises accept premium positioning for embedded audit trails.
Supply Chain Analysis
Extended payment terms from cloud infrastructure providers now stretch to ninety days for established platform vendors, compressing working capital cycles for mid-tier competitors. Component sourcing draws from United States hyperscale data centers, Irish GDPR-compliant hosting facilities, and Singaporean edge computing nodes. Supply chain risk centers on single-source API dependency for computer vision and natural language processing modules. Distribution runs through direct self-service onboarding for small businesses and systems integrator channels for enterprise deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
App creation software sits in early-cycle expansion as HIPAA-mandated healthcare digitization and EU AI Act compliance requirements force institutional buyers toward validated platforms faster than organic replacement cycles would predict.
For Market Incumbents: Insulate installed base through backward integration into compliance documentation generators and captive supply of pre-certified vertical templates. OutSystems and Mendix defend against Bubble Group Inc's speed-to-launch encroachment by embedding FDA validation workflows and EU AI Act conformity assessments natively. Channel control through Siemens partnerships and systems integrator certification programs remains the priority lever for European manufacturing retention. For New Entrants and Emerging Players: Pursue white-space in Indian SME financial inclusion apps and Japanese manufacturing IoT segments where localized compliance engineering lags demand. The most penetrable geography is India, where RBI financial inclusion mandates outpace domestic platform capability. A vertical-specific go-to-market angle—pre-built patient portal templates for United States rural health clinics—bypasses incumbent enterprise sales cycles. For Investors and Strategic Acquirers: Full-stack platforms with embedded healthcare compliance infrastructure represent the most defensible acquisition archetype as regulatory complexity compounds. Long-term viability across the next decade hinges on AI explainability feature depth and multi-cloud deployment flexibility. The signal to watch is FDA software-as-medical-device classification expansion beyond diagnostic imaging into clinical decision support modules.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding computer vision APIs from Google Cloud and AWS into no-code frontends opens retail biometric applications without engineering teams. |
| Strategic Partnership | Siemens channel partners in Bavaria drive Mendix adoption among automotive suppliers seeking shop-floor digitization. |
| Acquisition of Specialist Firm | Buying HIPAA-compliant hosting providers secures data sovereignty credentials for United States healthcare procurement committees. |
| Geographic Expansion | Localized EU AI Act conformity certification in Germany and France unlocks finance vertical sales previously blocked by audit requirements. |
| Product Launch | Generative AI code assistants compress prototype timelines from weeks to hours for marketing department citizen developers. |
Methodological Framework
Operator-level perspectives from CTOs, IT procurement officers, platform engineers, and healthcare compliance leads anchored the qualitative base for this analysis. Primary interview insights combined with secondary validation from SEC filings, hyperscaler capex disclosures, App Annie mobile platform data, and FDA software-as-medical-device registration databases. Bottom-up deployment model sizing and top-down enterprise IT budget analysis provided triangulation across the projection horizon.
Scenario-bracketing framed the analytical approach, with conservative and expansion cases bounding the outlook across the modeling period. Segmentation dimensions modeled include deployment architecture, organization size, vertical regulatory intensity, integration complexity, and regional adoption pattern. CAGRs derived from historical platform seat growth rates, cloud infrastructure expansion curves, and vertical-specific compliance spending trajectories. AI code assistant penetration and EU AI Act implementation timelines served as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in enterprise IT budget growth, cloud infrastructure pricing, or regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about HIPAA audit logging automation adoption and EU AI Act conformity assessment rollout pacing. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Online Project Management Software Market
Software & Services
Entity Management Software Market
Software & Services
Sports Facility Scheduling and Management Software Market
Software & Services
Construction Simulation Software Market
Software & Services
Global Application Management Services Market
Software & Services
AI Powered Software Testing Tool Market
Software & Services
Sales Force Automation Software Market
Software & Services
Global Janitorial Software Market
Software & Services
Global Automotive Software Market
Software & Services
Chromatography Data System (CDS) Software Market
Software & Services
Asia-Pacific ERP Software Market
Software & Services
Mobile Tracking Software Market
Software & Services
Preschool Education Software Market
Software & Services
Predictive Dialer Software Market
Software & Services
EDA Tools Market
Software & Services
Small Business Manufacturing Software Market