
 Global Decision Support Software Market | 2026-2036
Global Decision Support Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Decision Support Software Market Foresight
The capital-intensity divergence between hyperscale cloud platforms and specialized analytics vendors is redrawing competitive boundaries in decision support software. Microsoft Corporation leverages its Azure infrastructure to anchor enterprise deployments across hybrid environments. SAP SE competes through deep ERP integration that sustains manufacturing customer loyalty. SAS Institute Inc. differentiates via proprietary statistical engines that dominate risk-scoring workflows in regulated industries.
Decision support software encompasses algorithmic platforms that ingest structured and unstructured data, apply statistical or machine-learning models, and generate actionable recommendations for operational or strategic choices. These systems typically process batch and real-time data streams with latency thresholds under 500 milliseconds for time-sensitive applications such as fraud detection or dynamic pricing. Cloud-based deployment leads solution delivery, while predictive modeling captures expanding margin pools as financial services firms replace legacy spreadsheet workflows. On-premise installations retain share in defense and intelligence sectors where air-gapped security architectures remain mandatory.
The EU AI Act, HIPAA, and FDA 21 CFR Part 11 collectively shape product certification requirements and data residency obligations for vendors serving European and North American customers. Compliance costs are forcing smaller providers toward white-label partnerships or vertical specialization rather than multi-sector platform builds. Stakeholders must monitor how emerging algorithmic accountability frameworks in Brazil and South Korea alter market access conditions for cloud-native entrants.
Market Dynamics
Cloud infrastructure consolidation is compressing vendor margins while compliance mandates under the EU AI Act and HIPAA force architectural redesigns across enterprise deployments.
Growth Catalysts
- EU AI Act cloud mandates:European enterprises must deploy auditable decision systems, accelerating procurement of compliant platforms with built-in explainability modules.
- Healthcare predictive modeling:Hospital systems in Germany and the United States are replacing spreadsheet-based resource allocation with real-time clinical optimization engines.
- Edge computing latency requirements:Sub-500 millisecond processing thresholds for fraud detection and dynamic pricing are driving investment in distributed inference architectures.
Market Restraints
- GPU supply concentration:Training infrastructure dependence on Taiwan-based semiconductor fabrication creates procurement bottlenecks for model development cycles.
- Data residency compliance costs:Brazil's emerging algorithmic accountability frameworks and South Korea's AI governance rules fragment cloud deployment strategies.
- Air-gapped security requirements:Defense and intelligence sectors in the United States mandate on-premise installations that forego SaaS economics.
Strategic Opportunities
- Industrial ERP integration in Germany:Manufacturing clusters around Stuttgart and Munich seek supply chain optimization modules that interface with legacy SAP infrastructure.
- FDA 21 CFR Part 11 digital validation:Pharmaceutical quality management systems present untapped demand for compliant decision support in batch release workflows.
- Federated learning architectures:Privacy-preserving model training across hospital networks without centralizing patient data unlocks multi-site clinical trials.
Industry Challenges
- MLOps talent scarcity:Production deployment of machine learning pipelines requires specialists combining software engineering and statistical validation expertise that remains scarce.
- Legacy system integration friction:Mainframe data formats in financial services and healthcare resist standard API connectivity, inflating implementation timelines.
- Algorithmic audit documentation:Regulators in the European Union and United States demand traceability matrices that most vendors lack automated tooling to generate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Decision Support Software Market |
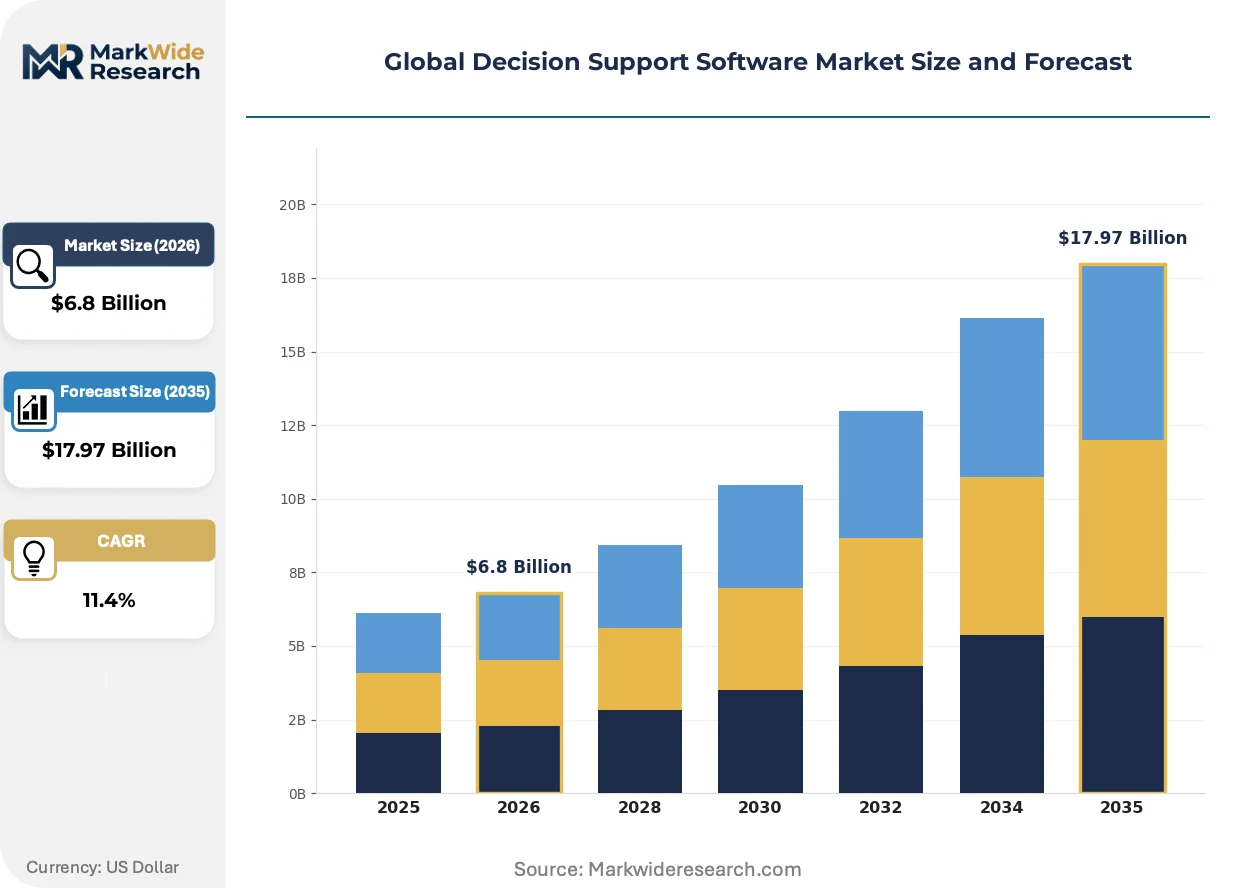
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Virtualized Solution Offering: Data-Driven Analytics, Predictive Modeling, Risk Management, Performance Monitoring, Resource Optimization Application: Financial Planning, Supply Chain Management, Customer Insights, Fraud Detection, Market Analysis End User Industry: Healthcare Providers, Manufacturing Firms, Telecommunications, Energy Companies, Educational Institutions |
| Companies Covered | IBM Corporation, Microsoft Corporation, Oracle Corporation, SAP SE, SAS Institute Inc., QlikTech International AB, Tableau Software, Domo Inc., MicroStrategy Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Decision Support Software Market Shifts & Advancements
Decision support architectures are converging around real-time inference at the edge, regulatory automation, and procurement models that decouple software licensing from infrastructure commitments.
Embedded analytics is miniaturizing statistical engines into operational databases, eliminating ETL latency for transactional decisioning. Retailers and logistics operators are deploying these compact models directly within warehouse management systems and point-of-sale terminals. The technology is miniaturizing what once required dedicated BI servers into millisecond-response query layers.
REACH chemical safety data requirements and the EU AI Act's risk classification system are forcing vendors to pre-certify training data provenance and model drift monitoring. Industrial software suppliers must now maintain technical documentation repositories that satisfy both environmental compliance and algorithmic accountability audits. German automotive and chemical manufacturers are consolidating vendor lists to those with dual certification capabilities.
Consumption-based licensing is displacing perpetual seat agreements as hyperscale cloud marketplaces become the dominant distribution channel. Enterprise buyers in financial services are negotiating commit-based contracts that scale with transaction volume rather than user count. This shift is most pronounced in the United States, where AWS and Azure marketplaces now capture the majority of new procurement decisions for analytics workloads.
Global Decision Support Software Market Segmentation
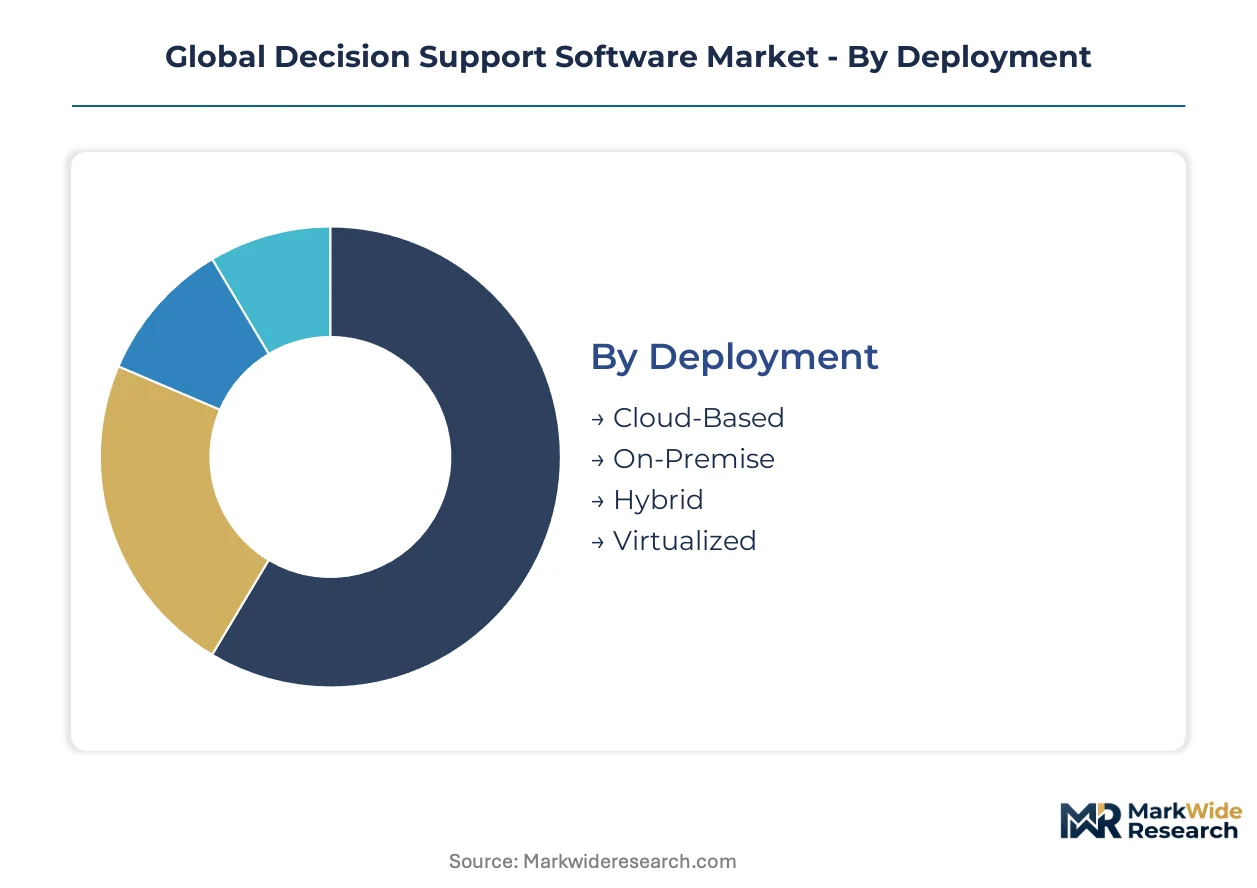
Decision support software segments diverge sharply by infrastructure requirements and regulatory exposure. Cloud deployment dominates procurement in financial services, while on-premise installations persist where HIPAA and EU AI Act data residency rules impose strict geographic boundaries on data storage.
Deployment:
Cloud-Based solutions serve export-led demand from multinational enterprises seeking centralized governance, while On-Premise and Hybrid deployments concentrate domestically within regulated sectors.
- Cloud-Based:Multi-tenant architectures with sub-500 millisecond latency SLAs process real-time fraud detection and dynamic pricing workloads. German automotive manufacturers and US healthcare systems are consolidating procurement around Microsoft Azure and AWS to satisfy EU AI Act auditability mandates without building captive data centers.
- On-Premise:Air-gapped installations run entirely within customer-controlled facilities, mandatory for US defense contractors and intelligence agencies. These deployments forego SaaS economics but satisfy HIPAA and FDA 21 CFR Part 11 validation requirements for pharmaceutical quality systems.
- Hybrid:Split architectures keep sensitive training data on-premise while pushing inference workloads to edge nodes, bridging compliance and scalability for hospital networks across Germany and the United States.
- Virtualized:Containerized deployments abstract hardware dependencies, enabling rapid migration between cloud regions to meet Brazil's emerging algorithmic accountability frameworks and South Korea's AI governance rules.
Cloud-Based holds the largest share; momentum sits with Hybrid as compliance fragmentation accelerates.
Solution Offering:
Margin concentration varies by analytical depth, with predictive modeling commanding premium pricing while performance monitoring commoditizes toward bundled ERP features.
- Data-Driven Analytics:Descriptive dashboards and ad-hoc query engines process historical operational data. These tools face margin compression as embedded analytics miniaturize statistical engines directly into SAP and Oracle databases.
- Predictive Modeling:Machine learning pipelines generate forward-looking forecasts for clinical resource allocation and supply chain demand planning. German hospital systems in Stuttgart and Munich are replacing spreadsheet workflows with real-time optimization engines that integrate with existing ERP infrastructure.
- Risk Management:Regulatory capital calculations and credit scoring models dominate banking procurement in the United States and United Kingdom. Vendors must maintain automated traceability matrices to satisfy EU AI Act explainability requirements.
- Performance Monitoring:Real-time KPI tracking and anomaly detection for manufacturing equipment. These solutions are increasingly bundled as modules within industrial IoT platforms rather than standalone purchases.
- Resource Optimization:Workforce scheduling and inventory positioning algorithms. Demand concentrates in US healthcare and German manufacturing where labor cost pressures drive automation of operational decisions.
Predictive Modeling commands the steepest expansion trajectory as financial services abandon legacy spreadsheets.
Application:
Application segments map directly to functional owner budgets, with Supply Chain Management residing in operations and Fraud Detection reporting through risk and compliance.
- Financial Planning:Scenario modeling and rolling forecast platforms. These tools face displacement from predictive modeling solutions that incorporate external macroeconomic indicators beyond internal ledger data.
- Supply Chain Management:Multi-echelon inventory optimization and logistics routing. German manufacturers around Munich seek modules that interface natively with SAP ECC and S/4HANA installations.
- Customer Insights:Segmentation and churn prediction for telecommunications and retail. GDPR and emerging Brazilian algorithmic accountability rules restrict cross-border data flows for model training.
- Fraud Detection:Real-time transaction scoring with sub-500 millisecond response requirements. US banks and payment processors are the primary demand source, with edge computing investments reducing cloud round-trip latency.
- Market Analysis:Competitive intelligence and pricing optimization for consumer goods and energy trading. These applications require continuous external data ingestion that complicates data residency compliance.
Supply Chain Management anchors current revenue; Fraud Detection is gaining share fastest on latency-critical infrastructure investment.
End User Industry:
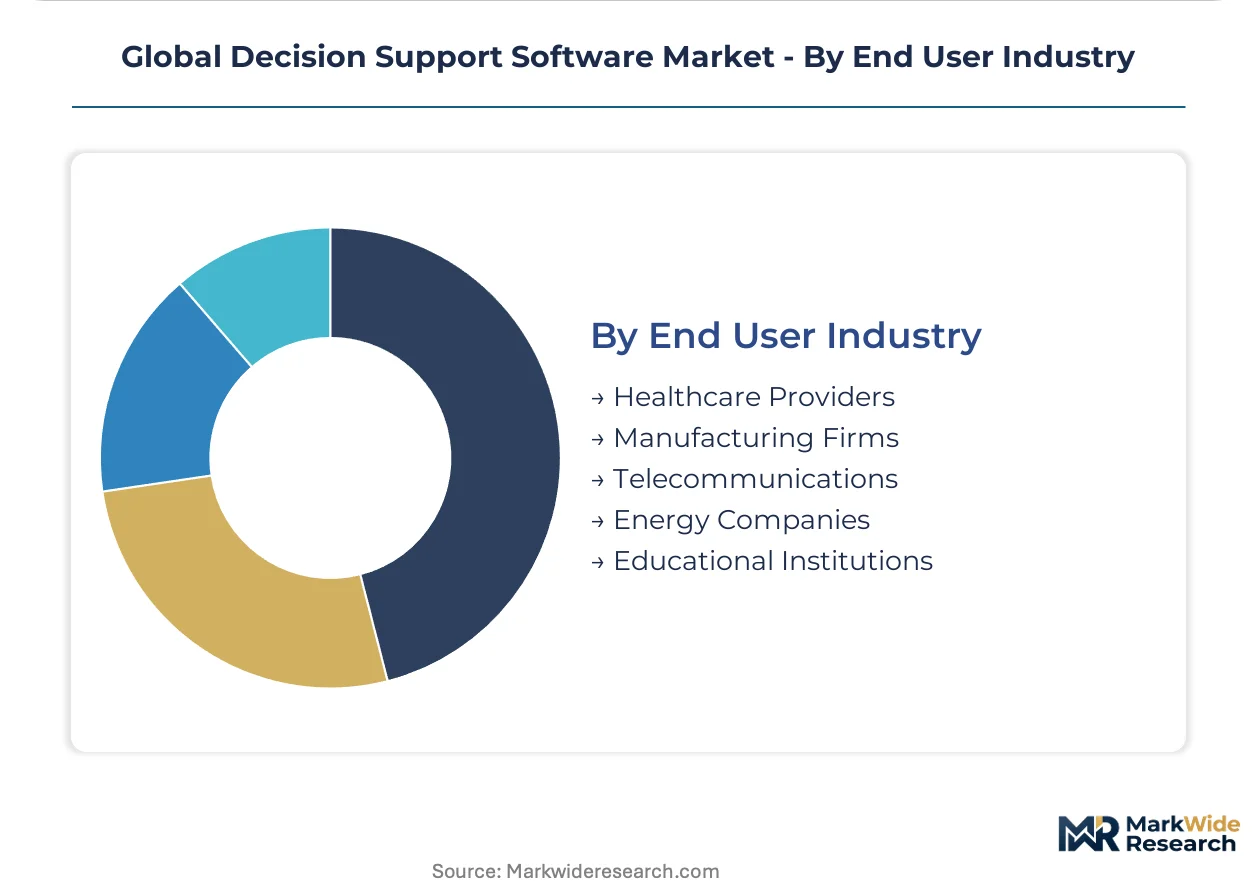
Industry verticals exhibit divergent procurement authority structures, with Healthcare Providers centralizing IT governance while Manufacturing Firms distribute purchasing to plant-level operations.
- Healthcare Providers:Hospital systems and integrated delivery networks deploy clinical decision support for resource allocation and quality measurement. HIPAA and FDA 21 CFR Part 11 impose validation documentation burdens that favor established vendors with pre-certified platforms.
- Manufacturing Firms:Discrete and process manufacturers integrate supply chain optimization with MES and ERP systems. German automotive and chemical clusters are consolidating vendor lists to suppliers with dual REACH and EU AI Act certification capabilities.
- Telecommunications:Network operators use customer insights and fraud detection across subscriber bases. These firms negotiate consumption-based licensing scaled to transaction volume rather than user seats.
- Energy Companies:Trading floors and grid operators deploy market analysis and risk management for commodity positions. FERC reporting requirements in the United States shape data retention and audit trail specifications.
- Educational Institutions:Universities and research hospitals apply resource optimization to facilities and course scheduling. Procurement cycles lag commercial sectors by 18-24 months due to budget approval processes.
Healthcare Providers represent the largest installed base; Manufacturing Firms show the steepest adoption curve on ERP integration requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where HIPAA compliance premiums command double-digit uplifts, while German buyers extract volume discounts through consolidated procurement consortia. Healthcare systems in Stuttgart and Munich negotiate enterprise-wide SAP integration contracts that compress vendor margins. Cloud deployment mandates under the EU AI Act reshape procurement timelines across European hospital networks.
United States
Hospital systems in Boston and the Research Triangle deploy predictive modeling for clinical resource allocation, replacing spreadsheet workflows with real-time optimization engines. FDA 21 CFR Part 11 and HIPAA impose validation documentation burdens that favor established vendors with pre-certified platforms. The Cleveland Clinic and Mayo Clinic anchor demand for hybrid architectures that keep sensitive training data on-premise while pushing inference to edge nodes.
Germany
Automotive manufacturers around Stuttgart and chemical producers in Ludwigshafen integrate supply chain optimization modules with legacy SAP ECC and S/4HANA infrastructure. REACH chemical safety data requirements and the EU AI Act's risk classification system force vendors to maintain dual certification capabilities. The country's national pharmaceutical regulator, BfArM, coordinates with EMA on algorithmic accountability standards for clinical decision support.
United Kingdom
Financial services firms in the City of London replace legacy spreadsheet workflows with predictive modeling for regulatory capital calculations. GDPR and emerging FCA guidance on algorithmic trading reshape data residency requirements for model training. The NHS in Manchester and Birmingham consolidates procurement around cloud-native platforms with built-in explainability modules.
Japan
Manufacturers in the Chubu region around Nagoya deploy edge computing architectures for sub-500 millisecond fraud detection and dynamic pricing. METI's AI governance guidelines and PMDA's software-as-medical-device framework create compliance-driven procurement cycles. Tokyo-based trading floors anchor demand for market analysis platforms that process continuous external data ingestion.
Brazil
Telecommunications operators in São Paulo negotiate consumption-based licensing scaled to transaction volume rather than user seats. ANVISA and emerging algorithmic accountability frameworks fragment cloud deployment strategies for pharmaceutical quality systems. The country's central bank, Banco Central do Brasil, mandates traceability matrices for credit-scoring models that most vendors lack automated tooling to generate.
Global Decision Support Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with hyperscale cloud platforms anchoring enterprise deployments through infrastructure integration while specialized analytics vendors dominate risk-scoring workflows in regulated industries. The market structures around three tiers: consolidated hyperscalers with captive distribution channels, mid-tier ERP-integrated specialists with manufacturing customer loyalty, and boutique statistical engine providers serving compliance-intensive verticals. Dominant competitive moves include white-label partnerships for smaller providers seeking multi-sector reach and vertical specialization to escape compliance cost pressures.
Within the hyperscaler tier, Microsoft Corporation and IBM Corporation occupy positions that leverage captive cloud infrastructure to anchor hybrid enterprise deployments. Oracle Corporation and SAP SE exemplify the ERP-integrated archetype, sustaining manufacturing customer loyalty through deep system interoperability. SAS Institute Inc. sits within the specialized analytics tier, anchoring risk-scoring workflows in banking and healthcare where regulatory validation requirements create defensive moats. These three archetypes—hyperscale infrastructure, ERP integration, and statistical specialization—collectively define competitive positioning as compliance mandates force architectural redesigns across enterprise deployments.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| SAS Institute Inc. |
| QlikTech International AB |
| Tableau Software |
| Domo Inc. |
| MicroStrategy Incorporated |
| Others |
Supply & Pricing Matrix
Capacity reservation contracts with hyperscale cloud providers lock in both GPU training infrastructure access and predictable per-inference pricing for enterprise buyers navigating EU AI Act compliance timelines. These multi-year commitments bind software vendors to Azure and AWS infrastructure while insulating hospital systems and manufacturers from spot-market volatility in semiconductor supply.
Pricing Analysis
The customization-premium spread separates standard SaaS tiers from configured-to-order deployments integrating with legacy SAP ECC systems. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth—FDA 21 CFR Part 11 validation commands substantial uplifts in US healthcare procurement. Cost compression in standard tiers is intensifying because embedded analytics miniaturization eliminates dedicated BI server requirements. Mid-market manufacturing firms in Germany exhibit highest price sensitivity, while US defense contractors absorbing air-gapped installations show least elasticity.
Supply Chain Analysis
Inventory lead times for NVIDIA H100 and AMD MI300X accelerators now stretch 40-52 weeks, forcing vendors into long-range capacity planning. Taiwan, South Korea, and the United States anchor GPU fabrication and advanced packaging capacity. Training infrastructure draws from TSMC's N4 process nodes, high-bandwidth memory stacks from SK Hynix, and substrate interposers from Japanese suppliers. Single-source vulnerability at TSMC's Hsinchu facilities concentrates risk. Distribution runs through hyperscale cloud marketplaces rather than traditional software licensing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Decision Support Software Market represents high-growth disruption as EU AI Act cloud mandates force architectural redesigns across every enterprise deployment, compressing procurement cycles from 18 months to 90 days for compliant platforms.
For Market Incumbents: Shield installed base through backward integration into edge inference hardware, locking in latency performance for fraud detection workloads. Fortify certification moats by pre-positioning FDA 21 CFR Part 11 and EU AI Act dual-validation documentation before competitor platforms complete audit trails. The threat of consumption-based licensing from AWS and Azure marketplaces demands channel control investment.
For New Entrants and Emerging Players: Lead with federated learning architectures targeting German hospital networks constrained by patient data residency rules. White-label partnerships with established ERP integrators offer fastest path past procurement committees at Stuttgart automotive clusters. The penetrable white-space sits in pharmaceutical quality management systems awaiting compliant batch release automation.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized analytics vendors with pre-certified statistical engines serving banking risk-scoring workflows. Long-term viability over the coming decade hinges on automated traceability matrix generation capabilities that satisfy emerging algorithmic accountability frameworks. Watch for BfArM-EMA coordination on clinical decision support standards as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native SAP S/4HANA connectivity captures German manufacturing procurement consolidation. |
| Regulatory Pre-Certification | FDA 21 CFR Part 11 validation unlocks pharmaceutical quality management system deployments. |
| Edge Computing Partnership | Sub-500 millisecond inference co-location satisfies fraud detection latency requirements. |
| Acquisition of Specialist Firm | MLOps talent scarcity makes statistical validation boutiques attractive targets. |
| Geographic Expansion | Brazilian ANVISA alignment opens algorithmic accountability-compliant pharmaceutical opportunities. |
Research Methodology
Cross-validation between primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners and secondary validation through SEC filings, hyperscaler capex disclosures, and EU regulatory repositories anchors the qualitative findings. Bottom-up sizing of deployment models and solution offerings triangulates against top-down macroeconomic indicators across the analysis window.
Sensitivity analysis around GPU supply concentration and compliance timeline acceleration stress-tests the analytical framework. Segmentation dimensions span deployment architecture, organization size, vertical integration complexity, and regional adoption pattern. CAGRs derive from weighted regression across historical procurement cycles and projected EU AI Act implementation phases. Federated learning penetration rates and embedded analytics displacement curves inform sector-specific trajectory assumptions.
The analysis sits within stated boundaries; outcomes outside sustained hyperscale infrastructure investment or abrupt regulatory relaxation would require recalibration. Forecasts reflect documented assumptions around compliance cost pass-through and cloud marketplace capture rates. GPU supply chain disruption or algorithmic accountability framework fragmentation in Brazil and South Korea could materially revise projections. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Embedded Software Market
Software & Services
Global Retail Inventory Management Software Market
Software & Services
Global Time Series Analysis Software Market
Software & Services
PCB Design Software Market
Software & Services
Global Home Inspection Software Market
Software & Services
Workstation Software Market
Software & Services
Global Disk Imaging Software Market
Software & Services
Marketing Automation Software Market
Software & Services
Global Student Information System Market
Software & Services
Mindfulness Meditation Application Market
Software & Services
Global Online Form Builder Software Market
Software & Services
Global Content Management Software Market
Software & Services
Network Bandwidth Management Software Market
Software & Services
Global HVAC Software Market
Software & Services
Global Virtual Desktop Market
Software & Services
Global Disclosure Management Software Market