
 GCC Human Capital Management Software Market | 2026-2036
GCC Human Capital Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Human Capital Management Software Market Insights
Subscription-based workforce analytics is pivoting how GCC enterprises consume human capital management capabilities, shifting from perpetual licenses to recurring revenue models tied to employee headcount. SAP SE leverages deep localization for Gulf payroll and compliance requirements across Saudi Arabia and the UAE. Oracle Corporation anchors its position through integrated talent-to-finance cloud suites that reduce IT fragmentation for large regional employers. ADP LLC differentiates via managed payroll services that absorb regulatory complexity for mid-market firms without dedicated HR technology staff.
Human capital management software comprises integrated applications for workforce administration, talent acquisition, performance tracking, compensation planning, and labor compliance, typically delivered through cloud-native architectures with API connectivity to enterprise resource planning systems. Its primary commercial purpose is to automate HR workflows, enforce regulatory adherence, and generate predictive workforce intelligence for operational planning. Cloud-based deployment leads adoption as GCC organizations retire legacy on-premise systems, while workforce analytics represents the fastest-expanding solution segment as boards demand data-driven retention and productivity metrics. Talent management captures concentrated margin pools due to high switching costs and recurring configuration needs tied to localization requirements.
Saudi Arabia's Ministry of Human Resources and Social Development enforces Nitaqat quotas that mandate workforce nationalization percentages, directly shaping HCM software feature roadmaps for compliance reporting. The UAE's Nafis program and Emiratisation targets create parallel regulatory demand for citizen-hiring tracking and training-budget allocation modules. Saudi Data and Artificial Intelligence Authority guidelines on employee data residency add infrastructure requirements that favor regional cloud providers or in-country data centers. Stakeholders must monitor how evolving localization mandates across Gulf jurisdictions reshape vendor certification requirements and implementation timelines.
Market Dynamics
Workforce nationalization mandates across Gulf Cooperation Council jurisdictions are compressing HCM software replacement cycles as enterprises scramble to deploy compliance-ready platforms before regulatory deadlines. Saudi Arabia's Nitaqat system and the UAE's Nafis program impose granular reporting requirements that legacy systems cannot satisfy.
Growth Catalysts
- Saudi Vision 2030 localization targets:Private-sector workforce nationalization quotas mandate real-time citizen-hiring dashboards and automated quota calculations.
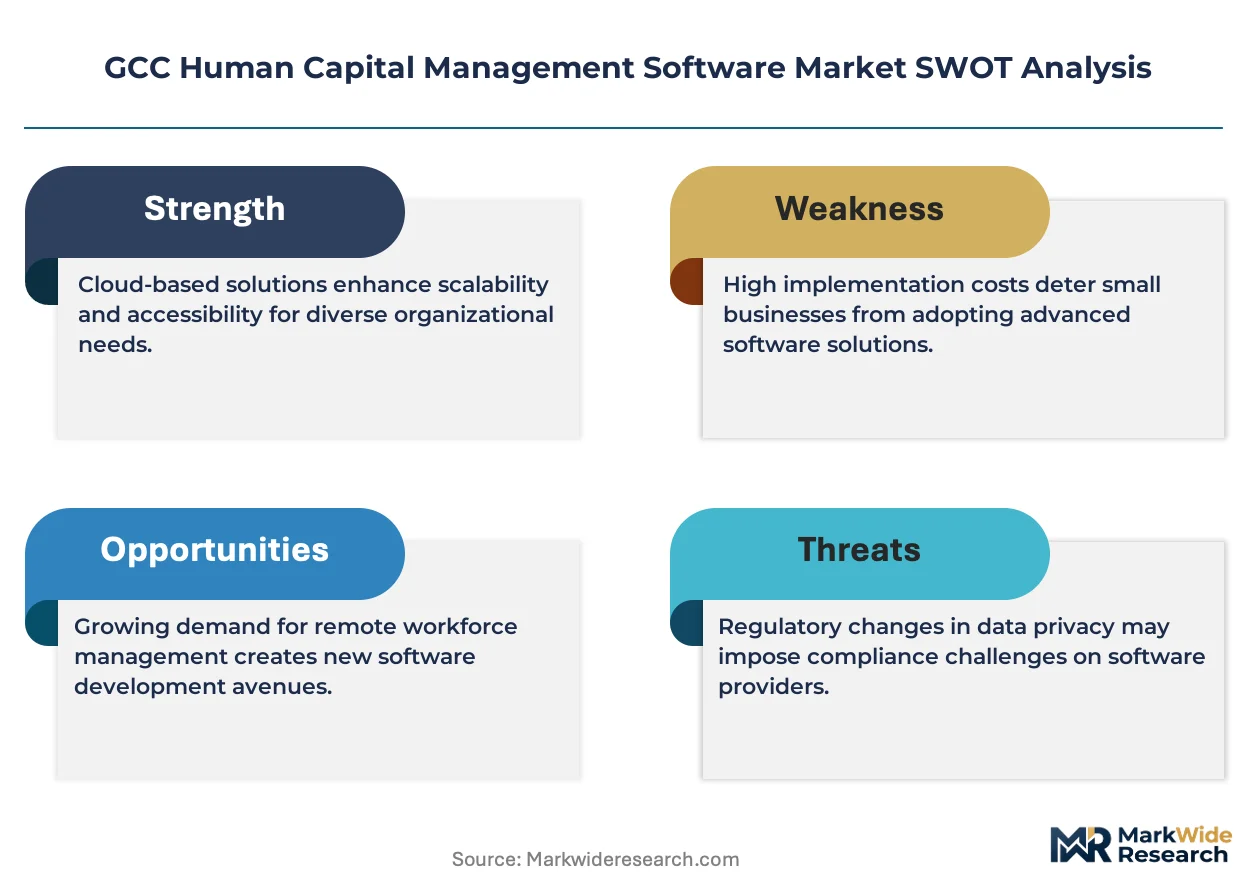
- Cloud migration imperatives:Gulf enterprises are retiring on-premise HR systems to access elastic scalability and reduce data center capital expenditure.
- SDAIA data residency guidelines:Saudi Data and Artificial Intelligence Authority requirements for employee data sovereignty are accelerating regional cloud infrastructure deployment.
Market Restraints
- Implementation cost concentration:Mid-market firms face prohibitive upfront configuration expenses for localized payroll and compliance modules.
- Talent scarcity in Gulf implementation partners:Certified system integrators with Arabic-language and Sharia-compliant payroll expertise remain concentrated in Riyadh and Dubai.
- Legacy system technical debt:Decades-old on-premise installations in oil and gas majors resist API-based integration with modern talent analytics platforms.
Strategic Opportunities
- Qatar and Kuwait underpenetration:Smaller GCC markets lack mature HCM vendor ecosystems, creating first-mover advantages for cloud-native entrants.
- AI-driven predictive retention:Machine learning models forecasting flight risk among nationalized employees address board-level workforce planning priorities.
- Mobile-first workforce engagement:Smartphone-dominant employee populations in construction and logistics sectors demand app-based self-service portals.
Industry Challenges
- Localization engineering complexity:Each Gulf jurisdiction maintains distinct labor law interpretations requiring separate payroll calculation engines.
- Integration friction with ERP estates:SAP and Oracle financial systems in regional enterprises demand custom middleware for HCM data synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Human Capital Management Software Market |
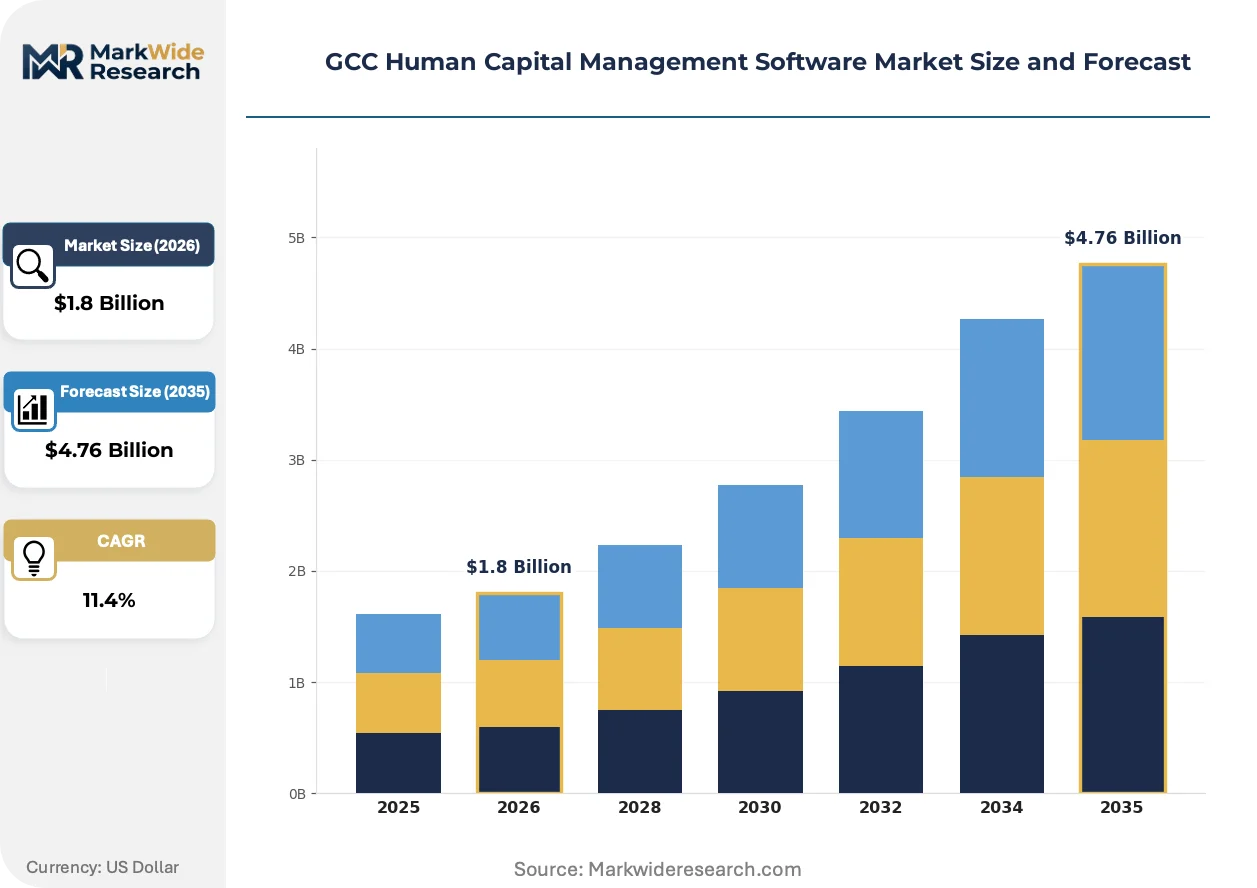
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Multi-Tenant End User: Corporate Sector, Educational Institutions, Government Agencies, SMEs Solution: Talent Management, Payroll Management, Workforce Analytics, Employee Benefits Industry Vertical: Healthcare, Retail, Manufacturing, Technology |
| Companies Covered | SAP SE, Oracle Corporation, ADP LLC, Infor Group, Akrivia HCM, PeopleStrong, DarwinBox, ZingHR, gulfHR, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Human Capital Management Software Market Trends and Innovations
Generative AI is embedding into core HR workflows across GCC enterprises, shifting vendor competition from feature breadth to predictive accuracy. This transformation is compressing sales cycles for platforms demonstrating measurable workforce retention improvements.
Embedded natural language processing is electrifying how Saudi and Emirati HR teams interact with workforce data. Large language models enable conversational queries against employee databases without SQL expertise. Regional banks and telecom operators are deploying these interfaces for manager self-service analytics. The technology is electrifying competitive positioning for vendors offering Arabic-language model fine-tuning.
The UAE's Nafis program and parallel Emiratisation enforcement mechanisms are mandating granular citizen-hiring tracking that exceeds standard HCM functionality. Employers must now report training budget allocations and career progression milestones to government portals. This regulatory density favors vendors with pre-built compliance connectors to Ministry of Human Resources and Emiratisation systems. Oil and gas conglomerates with distributed workforces across multiple emirates face the steepest adaptation requirements.
Subscription consumption models are displacing perpetual license structures across mid-market GCC employers. Chief financial officers prefer operational expenditure treatment for software costs amid workforce volatility. Regional system integrators are responding with managed service wrappers that bundle implementation, training, and ongoing configuration. Saudi construction and logistics firms with seasonal hiring patterns demonstrate the strongest preference for headcount-scalable pricing.
GCC Human Capital Management Software Market Segmentation
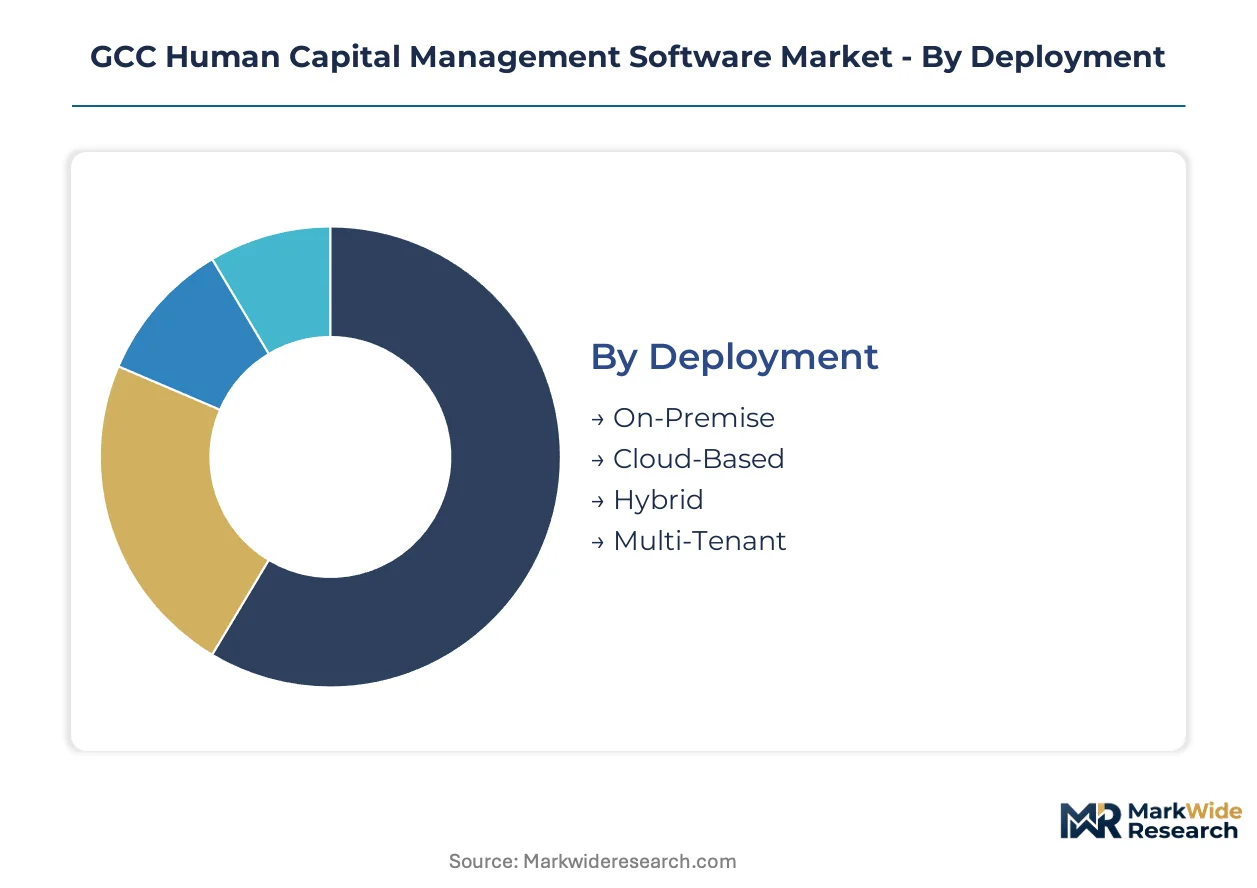
Segmentation in the GCC human capital management software market reveals how deployment choices, end-user priorities, and solution architectures map onto regulatory requirements and workforce nationalization mandates. Understanding these divisions helps vendors align product roadmaps with the capital constraints and compliance pressures shaping procurement decisions across Saudi Arabia and the UAE.
Deployment:
Capital intensity varies sharply across deployment modes, with on-premise installations demanding the heaviest upfront infrastructure investment while cloud alternatives shift costs to recurring operational expenditure.
- On-Premise:Requires dedicated server hardware, data center facilities, and in-house IT maintenance teams. Saudi oil and gas conglomerates with legacy ERP estates favor this mode to retain direct control over employee data residency under SDAIA guidelines. High capital barriers limit adoption to large enterprises with existing infrastructure footprints.
- Cloud-Based:Delivers elastic scalability through regional cloud providers with in-country data centers. UAE government agencies accelerating digital transformation drives concentrated demand here, particularly where Emiratisation compliance dashboards require rapid provisioning.
- Hybrid:Combines on-premise core payroll engines with cloud analytics layers. Mid-market Saudi construction firms use this architecture to satisfy Nitaqat reporting while containing infrastructure spend.
- Multi-Tenant:Shares infrastructure across multiple client organizations, minimizing per-tenant costs. Regional system integrators deploy this model for SME aggregators in Qatar and Kuwait where standalone deployments prove uneconomical.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Multi-Tenant configurations as vendor ecosystems mature in underpenetrated GCC markets.
End User:
Procurement authority and budget scale diverge dramatically across end-user types, with government agencies wielding sovereign purchasing power while SMEs face acute cost sensitivity.
- Corporate Sector:Saudi Arabia's private employers under Vision 2030 localization targets represent the dominant revenue pool. These organizations require integrated talent-to-finance suites with real-time Nitaqat quota calculations and automated citizen-hiring workflows.
- Government Agencies:Federal and emirate-level entities in the UAE mandate pre-built compliance connectors to Ministry of Human Resources and Emiratisation systems. Procurement cycles here favor vendors with Arabic-language support and established security certifications.
- Educational Institutions:Universities and vocational training centers track graduate placement outcomes against Nafis program metrics. Demand concentrates in workforce analytics modules linking student records to employment verification.
- SMEs:Small and mid-sized enterprises prioritize headcount-scalable pricing and managed service wrappers. Saudi logistics firms with seasonal hiring patterns demonstrate strongest preference for subscription consumption models.
Revenue concentration sits with the Corporate Sector. Government Agencies are gaining share fastest as federal digital transformation budgets expand.
Solution:
Functional specialization determines integration complexity and recurring configuration revenue, with talent management commanding premium pricing due to high switching costs.
- Talent Management:Encompasses acquisition, performance tracking, and succession planning with granular localization for Gulf labor law interpretations. Saudi corporate employers invest here to automate retention strategies for nationalized employees.
- Workforce Analytics:Predictive models forecasting flight risk and productivity metrics. UAE banks and telecom operators deploy Arabic-language natural language processing interfaces for manager self-service analytics.
- Payroll Management:Sharia-compliant calculation engines with jurisdiction-specific social insurance deductions. Oil and gas majors require custom middleware to synchronize with legacy SAP financial systems.
- Employee Benefits:End-to-end administration of health insurance, pension contributions, and training budget allocations. Nafis program compliance mandates granular tracking of citizen employee benefit utilization.
Margin pools concentrate in Talent Management. Workforce Analytics is climbing the fastest as board-level demand for predictive intelligence intensifies.
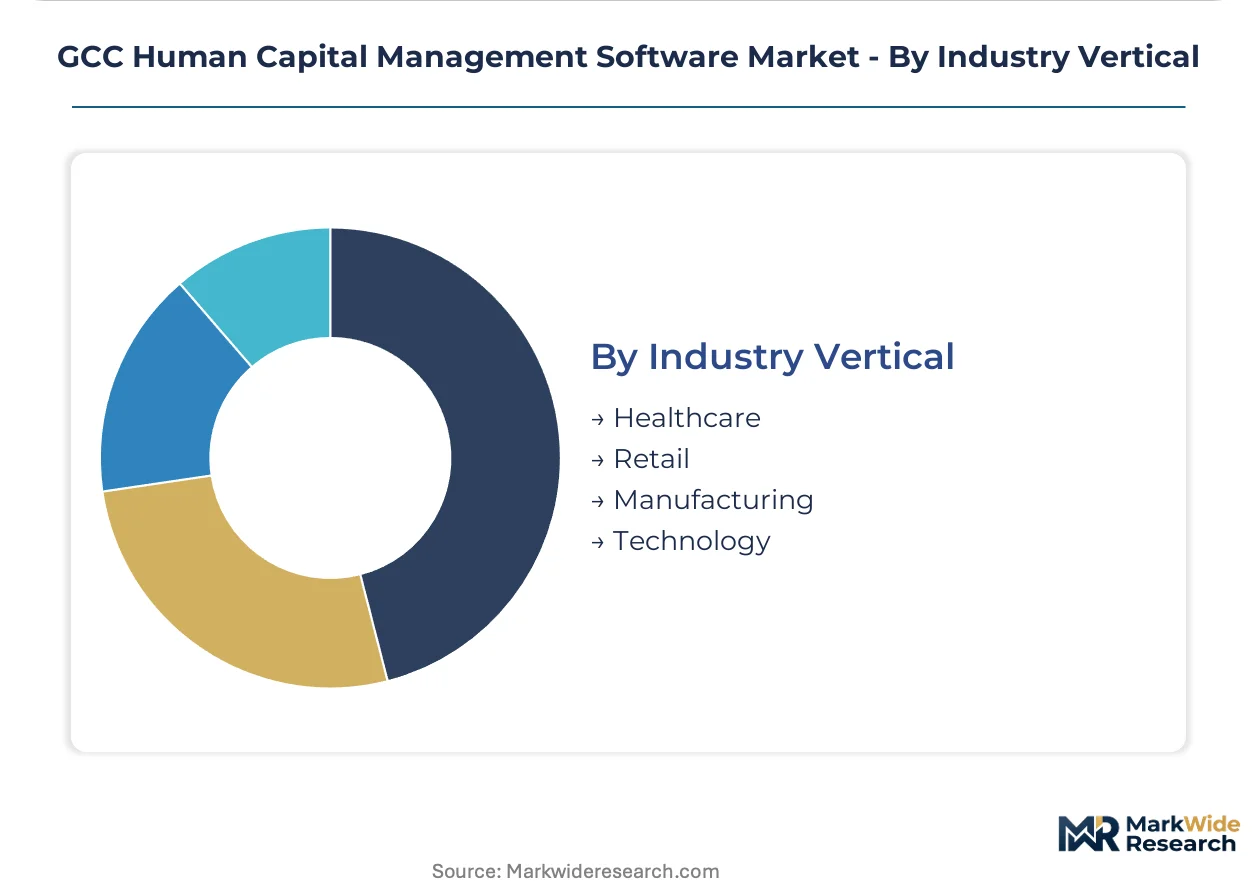
Industry Vertical:
Sector-specific workforce structures and regulatory exposure create divergent solution requirements across vertical markets.
- Healthcare:Saudi hospital networks require credentialing modules for expatriate medical staff alongside Nitaqat compliance for administrative roles. Shift scheduling complexity drives demand for mobile-first workforce engagement tools.
- Retail:High-velocity hiring and turnover in UAE mall operations favors automated onboarding and digital document management. Seasonal workforce scaling demands elastic cloud provisioning.
- Manufacturing:Saudi industrial cities integrate HCM platforms with shop-floor productivity systems. Safety certification tracking and skills-based scheduling represent priority functionality.
- Technology:Dubai Internet City and Riyadh tech clusters prioritize AI-driven talent acquisition and global remote workforce management. These employers lead adoption of generative AI embedded in core HR workflows.
Deployment volume centers on Healthcare. Technology verticals are expanding most quickly as GCC digital economy initiatives accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between Gulf jurisdictions is accelerating HCM software procurement as enterprises migrate operations to markets offering clearer compliance pathways and faster cloud infrastructure deployment. Cost-of-compliance gaps between Saudi Arabia and smaller GCC states are reshaping vendor resource allocation.
Saudi Arabia
Riyadh-based corporate headquarters dominate regional HCM software spend as Vision 2030 localization mandates force system replacements. The Ministry of Human Resources and Social Development enforces Nitaqat quotas requiring real-time citizen-hiring dashboards. Eastern Province oil and gas conglomerates maintain hybrid deployments to satisfy SDAIA data residency guidelines while containing infrastructure costs.
United Arab Emirates
Dubai's government agencies drive concentrated demand for cloud-native workforce analytics with pre-built Ministry of Human Resources and Emiratisation connectors. The Nafis program mandates granular training-budget tracking that exceeds standard platform functionality. Abu Dhabi sovereign wealth entities are deploying AI-driven retention models for nationalized employee populations.
Qatar
Doha's financial services sector is emerging as a testbed for multi-tenant HCM architectures serving mid-market employers. The country's national workforce development strategy creates compliance requirements analogous to Saudi and UAE frameworks. Lusail City smart district projects integrate workforce management platforms with municipal digital infrastructure.
Kuwait
Kuwait City banking groups represent the primary addressable market as regulatory pressure for workforce nationalization intensifies. The Civil Service Commission's digitization agenda is creating procurement opportunities for Arabic-language compliance modules. Ahmadi industrial zone manufacturing operations are piloting mobile-first workforce engagement tools for expatriate-dominated workforces.
GCC Human Capital Management Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with enterprise-grade suite vendors commanding premium pricing while regional system integrators capture implementation and managed service revenue. Market structure concentrates around three tiers: multinational cloud platforms with Gulf localization teams, India-headquartered SaaS specialists with Arabic-language capabilities, and regional consultancies bundling configuration with ongoing compliance support. Dominant competitive moves include strategic partnerships between global vendors and local system integrators to accelerate certification timelines, plus portfolio diversification into adjacent workforce analytics modules.
Within the multinational enterprise tier, SAP SE and Oracle Corporation occupy positions anchored by deep ERP integration heritage across Saudi and UAE corporate accounts. Among India-originated SaaS specialists, DarwinBox and ZingHR exemplify the cloud-native archetype targeting mid-market employers with rapid-deployment subscription models. Gulf-focused regional players including gulfHR sit within the compliance-specialist niche, leveraging proximity to regulatory bodies for faster feature certification against evolving Nitaqat and Emiratisation requirements.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| ADP LLC |
| Infor Group |
| Akrivia HCM |
| PeopleStrong |
| DarwinBox |
| ZingHR |
| gulfHR |
| Others |
Pricing and Supply Chain Analysis
Localization engineering labor costs cascade through three distinct pricing tiers as Gulf system integrators translate multinational SaaS platforms into Nitaqat-compliant and Emiratisation-ready configurations. Saudi and UAE enterprises absorb these configuration premiums at the point of procurement, with mid-market buyers facing steeper per-employee costs due to diseconomies of scale in Arabic-language payroll module customization.
Pricing Analysis
System integrator margins dominate downstream pricing as regional partners bundle implementation, training, and ongoing compliance configuration. Subscription models stratify across premium enterprise suites with real-time government portal connectors, standard mid-market offerings with quarterly compliance updates, and economy tiers for SME aggregators on multi-tenant infrastructure. Pricing pressure stems from certified Arabic-language implementation partner scarcity in Riyadh and Dubai, which inflates deployment costs. Government agencies exhibit lowest price sensitivity due to sovereign budget certainty, while Saudi construction firms with seasonal headcount volatility demonstrate highest sensitivity to per-employee pricing structures.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscaler data center investments in Saudi Arabia, the UAE, and Bahrain to satisfy SDAIA and local data residency mandates. Core software intellectual property draws from development centers in India, Ireland, and the United States, while localization engineering talent concentrates in Riyadh and Dubai. Single-source vulnerability sits with the thin pipeline of Gulf-certified system integrators possessing both Arabic fluency and Sharia-compliant payroll expertise. Distribution runs through direct enterprise sales teams for multinational vendors and regional system integrator networks for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC human capital management software market compounds steadily as workforce nationalization mandates across Saudi Arabia and the UAE force recurring platform refreshes. Regulatory compliance creates predictable replacement cycles that insulate revenue streams from macroeconomic volatility.
For Market Incumbents: Extend localization certification pipelines to compress implementation timelines for Nitaqat and Emiratisation compliance modules. Acquire or deeply partner with Riyadh-based system integrators to secure scarce Arabic-language payroll engineering capacity. Cloud-native challengers from India threaten mid-market share with rapid-deployment subscription models; counter by embedding predictive retention analytics that demonstrate measurable workforce ROI to Saudi corporate boards. For New Entrants and Emerging Players: Nafis program enforcement in the UAE opens a window for compliance-first platforms with pre-built Ministry of Human Resources and Emiratisation connectors. Qatar and Kuwait lack mature vendor ecosystems and present first-mover opportunities for multi-tenant architectures serving SME aggregators. Target mobile-first workforce engagement tools for construction and logistics sectors where smartphone-dominant employee populations remain underserved by incumbent desktop-centric interfaces. For Investors and Strategic Acquirers: Consolidation pressure builds where localization engineering talent scarcity meets fragmented regional system integrator landscapes. The market supports a 5-10 year compounder thesis anchored by irreversible workforce nationalization policy trajectories. Priority acquisition targets include Gulf-based compliance specialists with established SDAIA certification pathways and existing government agency reference accounts. Watch for Nitaqat quota threshold adjustments as the signal indicating accelerated replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Strategic Partnership | Global vendors partnering with Riyadh system integrators accelerate Nitaqat certification timelines. |
| Product Launch | Arabic-language natural language processing interfaces differentiate workforce analytics offerings for UAE banks. |
| Geographic Expansion | Multi-tenant cloud deployment in Qatar and Kuwait captures underpenetrated mid-market employer segments. |
| Platform Integration | Pre-built connectors to Ministry of Human Resources and Emiratisation systems lock in government agency contracts. |
| Acquisition of Specialist Firm | Buying Gulf-certified payroll engineering teams secures scarce localization talent against competitor poaching. |
Research Methodology
Coverage spans Saudi Arabia, the UAE, Qatar, and Kuwait, with primary inputs from each jurisdiction's corporate HR directors, government digital transformation officers, system integrator implementation leads, and compliance consultants at Big Four advisory practices. Secondary validation draws from SDAIA data residency guidelines, Ministry of Human Resources and Social Development Nitaqat enforcement circulars, UAE Ministry of Human Resources and Emiratisation portal specifications, and hyperscaler regional infrastructure investment disclosures. Bottom-up sizing of vendor-reported subscription revenue triangulates against top-down estimates derived from employer headcount and software penetration assumptions.
Rate-of-change decomposition separates volume growth from pricing evolution across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user organization type, solution functional area, and industry vertical. CAGRs derive from regression analysis against historical replacement cycle data and regulatory deadline schedules. Forecast inputs incorporate Vision 2030 localization target trajectories, Nafis program budget allocations, and cloud infrastructure capacity expansion timelines.
Revisions become necessary when regulatory quota thresholds shift, data residency requirements expand to additional GCC jurisdictions, or hyperscaler regional data center investments stall. Forecasts reflect documented assumptions about employer technology refresh propensity and system integrator capacity expansion. A small set of named triggers warrants ongoing watch: Nitaqat band reclassification events, Emiratisation enforcement intensity changes, and SDAIA cross-border data flow rule amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Virtual Client Computing Software Market
Software & Services
Vending Software Market
Software & Services
Optical Design Software Market
Software & Services
Global Polling Software Market
Software & Services
Cloud Communication Platform Software Market
Software & Services
Spend Analysis Software Market
Software & Services
Mind Mapping Software Market
Software & Services
Asia-Pacific Text to Speech (TTS) Software Market
Software & Services
Embedded Operating Systems Market
Software & Services
Europe Pharmacy POS Software Market
Software & Services
Global Molecular Modeling Software for Chemistry Market
Software & Services
Channel Management Software Market
Software & Services
Configuration Management (CM) Tools Market
Software & Services
Model Based Testing Tools Market
Software & Services
Website Translation Software Market
Software & Services
Period-Tracking Software Market