
 Sourcing Software Market | 2026-2036
Sourcing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Sourcing Software Market Outlook
The capability gap between cloud-native architectures and legacy on-premises stacks is reorganizing competitive dynamics across the sourcing software landscape. SAP Ariba leverages its embedded ERP connectivity to dominate enterprise accounts with complex procurement workflows. Oracle Corporation sustains R&D intensity in autonomous sourcing features, while Coupa Software Inc. specializes in spend analytics modules that anchor mid-market expansion.
Sourcing software encompasses applications that automate supplier discovery, bid management, contract negotiation, and procurement execution through configurable workflow engines and API-based integration layers. These systems process requisition-to-pay cycles, enforce compliance rules, and generate audit trails for enterprise procurement operations. Cloud-based deployment leads adoption as retailers and manufacturers prioritize scalable infrastructure over capital-intensive on-premises installations. Supplier management and spend analysis solutions capture expanding margin pools as enterprises seek granular visibility into tier-two and tier-three vendor networks.
The EU AI Act and GDPR shape algorithmic transparency requirements for automated supplier scoring systems in Europe, while ISO 27001 and SOC 2 Type II certifications function as baseline market-access credentials across North American and Asia-Pacific procurement evaluations. FDA supply-chain traceability mandates for pharmaceutical manufacturers indirectly elevate sourcing software standards for batch-lot tracking and vendor qualification protocols. Procurement leaders must weigh data residency constraints against platform interoperability when selecting multi-region deployment architectures.
Market Dynamics
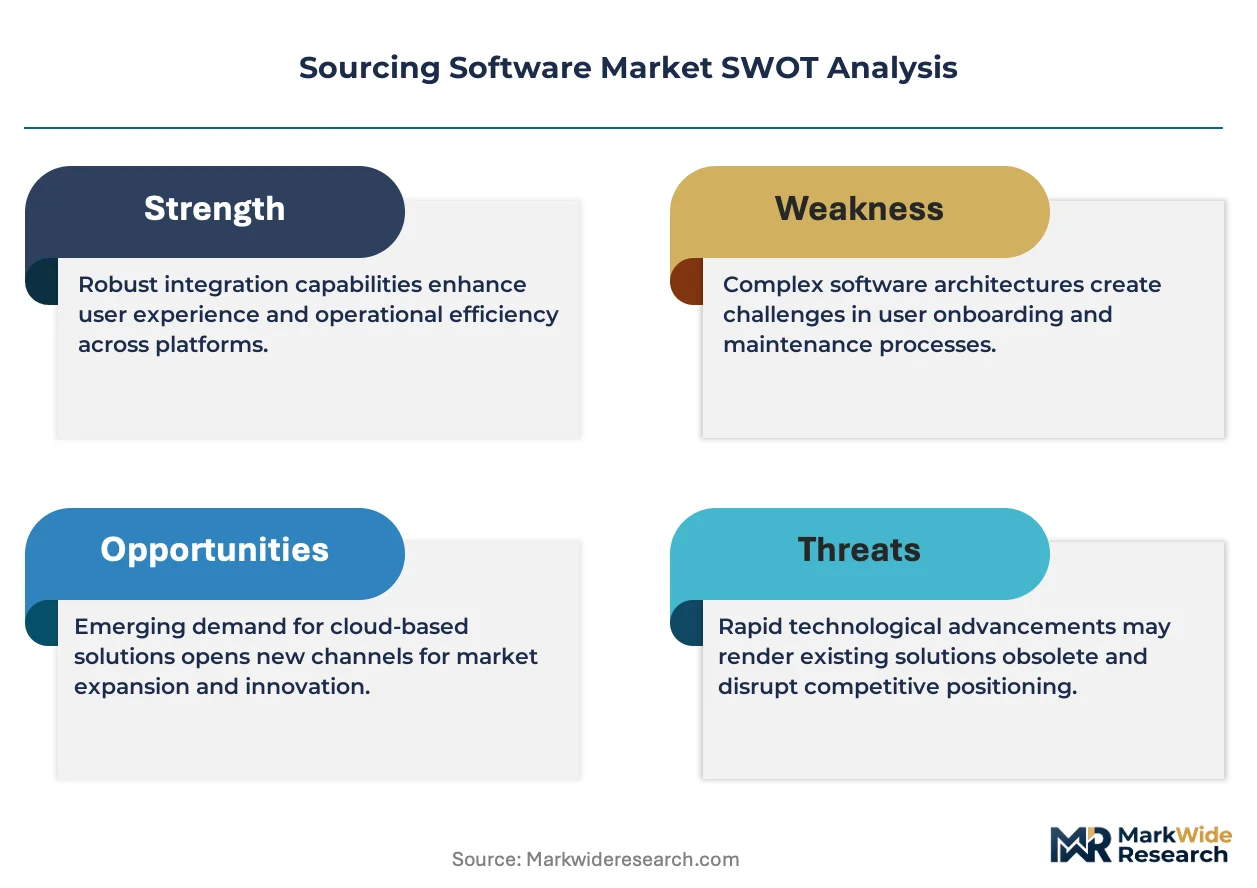
Cloud-native procurement platforms are compressing implementation timelines and displacing legacy ERP-integrated suites, forcing established vendors to rearchitect their delivery models around API-first connectivity and microservices deployment.
Growth Catalysts
- GDPR algorithmic transparency mandates:European procurement teams now require auditable supplier scoring logic, creating demand for explainable AI modules within sourcing suites.
- Automotive tier-n visibility requirements:OEMs in Germany and the United States are mandating real-time supplier risk monitoring, accelerating adoption of multi-tier mapping tools.
- India's PLI scheme for manufacturing:Domestic production incentives are driving Indian enterprises to modernize supplier onboarding infrastructure to qualify for subsidy compliance.
Market Restraints
- Data residency fragmentation:Divergent sovereignty rules across Germany, India, and the United States force vendors to maintain region-locked instances, inflating operational overhead.
- Legacy system entrenchment:SAP ERP dominance in Fortune 500 accounts creates switching costs that delay cloud migration timelines by 18-36 months.
- Specialized talent scarcity:Shortage of procurement technologists fluent in both supplier negotiation and API integration limits enterprise implementation velocity.
Strategic Opportunities
- Small and mid-sized manufacturing in India:Underpenetrated domestic suppliers lack digitized procurement workflows, presenting greenfield SaaS adoption potential.
- EU CSRD supply-chain disclosure:Mandatory Scope 3 emissions reporting is creating demand for carbon-accounting modules embedded within sourcing platforms.
- Convergence of sourcing and treasury:Integration between procurement execution and working capital financing represents unclaimed margin pools for platform vendors.
Industry Challenges
- Multi-cloud orchestration complexity:Enterprises operating across AWS, Azure, and GCP instances face integration failures when synchronizing supplier master data.
- ISO 27001 certification backlogs:Three-to-six-month audit queues delay vendor qualification for regulated industries including pharmaceuticals and defense.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sourcing Software Market |
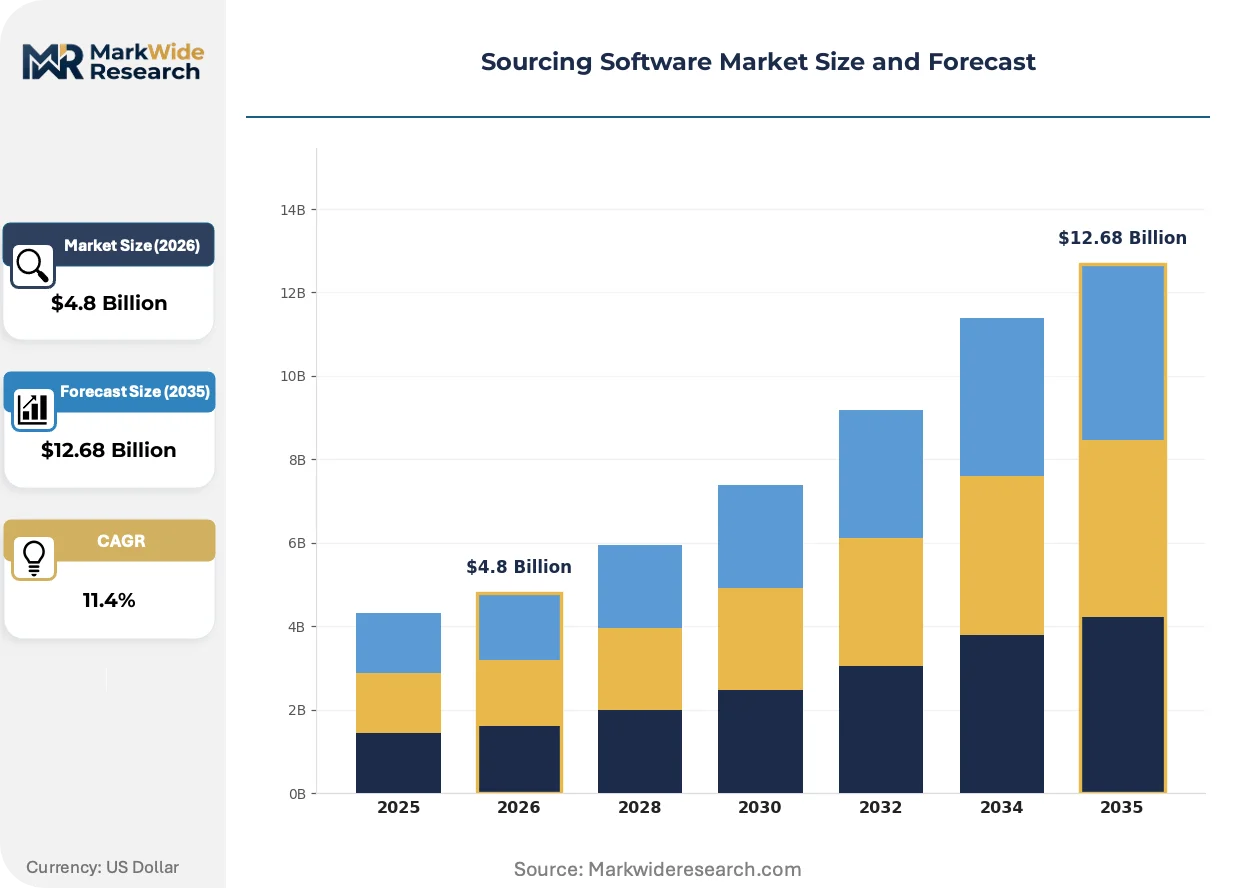
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: Retailers, Manufacturers, Distributors, Wholesalers Solution: Procurement Management, Supplier Management, Spend Analysis, Contract Management Service Type: Consulting, Implementation, Support, Training |
| Companies Covered | Oracle Corporation, Coupa Software Inc., GEP Corporation, SAP Ariba, Ivalua Inc., Jaggaer Inc., Zycus Inc., Workday Inc., Aavenir, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sourcing Software Market Strategic Shifts
Agentic AI architectures are redefining how procurement teams interact with supplier data, compressing the gap between analytical insight and executable workflow automation.
Natural language procurement interfaces are miniaturizing the technical barrier to complex sourcing operations. Category managers without SQL training now query supplier performance through conversational prompts. Retailers in Germany and the United States are deploying these tools to accelerate RFP generation. The technology is miniaturizing the role of dedicated procurement analysts, shifting headcount toward supplier relationship strategy.
The EU AI Act's risk classification framework is forcing vendors to document automated decision logic for high-risk procurement applications. Suppliers scoring algorithms must now expose weighting factors and training data provenance. Pharmaceutical manufacturers sourcing active ingredients face the steepest compliance burdens. Vendors are responding by modularizing AI components to isolate audit-ready subsystems.
Self-service supplier onboarding portals are displacing traditional email-based qualification workflows. Mid-market manufacturers in India now expect real-time credential verification without procurement team intermediation. This channel compression is most visible among industrial distributors serving tier-two automotive suppliers. Platform vendors capturing this behavior shift are unbundling implementation services into subscription tiers.
Sourcing Software Market Segmentation
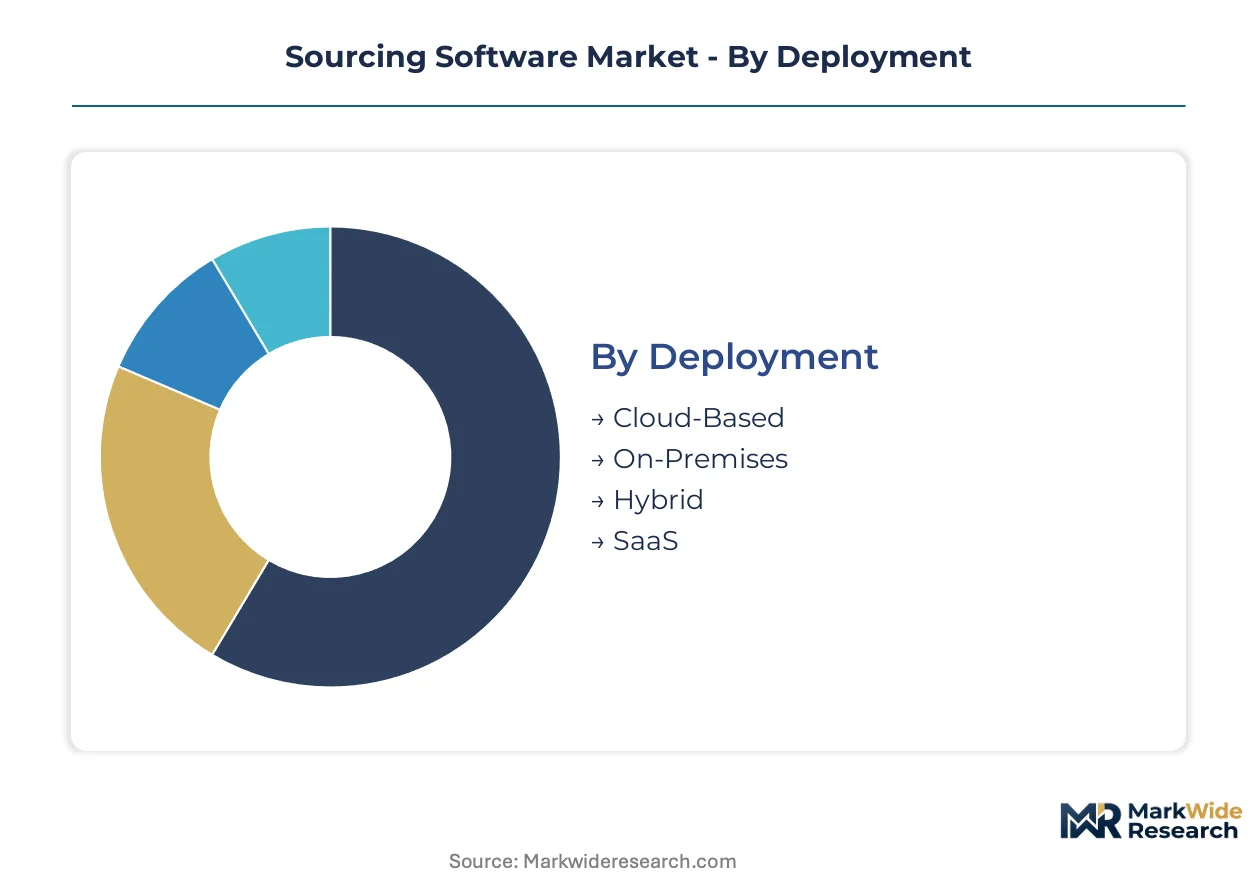
Sourcing software vendors architect product portfolios around deployment flexibility and buyer sophistication tiers. Segment boundaries shift as cloud-native platforms absorb functionality previously delivered through professional services engagements.
Deployment:
Substitution pressure runs strongest against capital-intensive installation models as subscription economics reframe procurement technology ownership.
- Cloud-Based:Multi-tenant architectures with elastic compute provisioning support seasonal procurement volume spikes. German automotive OEMs and US pharmaceutical manufacturers prioritize these platforms for supplier risk monitoring dashboards that scale across tier-n networks.
- SaaS:Pre-configured workflow templates with API-first integration layers compress implementation timelines. Indian manufacturing enterprises under PLI scheme compliance deadlines favor rapid-deployment SaaS modules for vendor qualification automation.
- Hybrid:Split architectures maintain sensitive supplier data on-premises while routing transactional workflows through cloud gateways. Organizations in regulated industries deploy these configurations to satisfy data residency constraints without sacrificing collaboration tools.
- On-Premises:Legacy ERP-integrated stacks with dedicated hardware infrastructure. Fortune 500 accounts with entrenched SAP deployments face switching costs that delay migration timelines.
Cloud-Based deployments anchor the volume base while SaaS gains share at the steepest rate.
End User:
Cost tier stratification separates enterprise-grade feature depth from mid-market configurability requirements.
- Manufacturers:Complex BOM-driven procurement with multi-tier supplier mapping and quality audit trails. German automotive tier suppliers and US medical device producers drive demand for batch-lot traceability modules.
- Retailers:High-velocity SKU management with seasonal demand forecasting integration. Fashion and grocery chains prioritize real-time inventory synchronization with private-label supplier networks.
- Distributors:Inventory-positioning optimization across fragmented supplier bases. Industrial distributors serving construction and MRO segments require quote-to-order automation for project-based procurement.
- Wholesalers:Volume aggregation tools with rebate management and consolidated billing. Foodservice and electrical wholesale verticals seek margin protection through spend analytics visibility.
Manufacturers anchor the volume base while Retailers expand most quickly as e-commerce fulfillment pressures intensify.
Solution:
Application maturity varies sharply, with adjacent modules threatening standalone point solutions.
- Spend Analysis:Multi-dimensional cost cube construction with commodity benchmarking and price variance alerts. Procurement teams in India and Germany deploy these tools to identify maverick spending across decentralized purchasing units.
- Supplier Management:Credential verification portals with automated risk scoring and performance scorecards. Pharmaceutical manufacturers sourcing active ingredients require FDA-aligned vendor qualification protocols.
- Procurement Management:Requisition-to-pay workflow orchestration with three-way matching and accrual automation. Mid-market manufacturers adopt these suites to replace email-based purchase order processes.
- Contract Management:Clause libraries with obligation tracking and renewal alert systems. Legal procurement teams prioritize AI-assisted redlining for high-volume vendor agreement processing.
Procurement Management anchors the volume base while Spend Analysis climbs the fastest as margin pressure demands granular cost visibility.
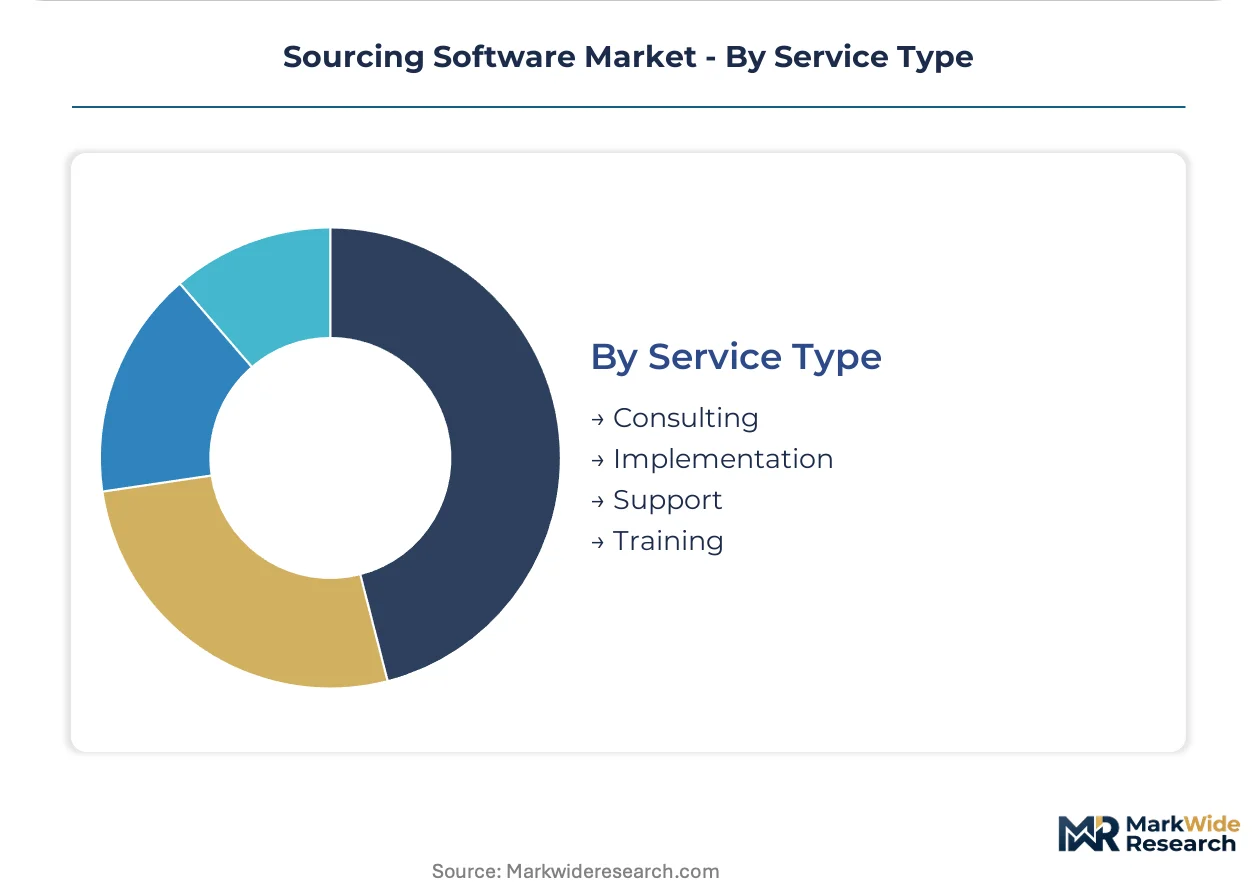
Service Type:
Customer type stratification separates self-sufficient SaaS adopters from transformation-dependent enterprise accounts.
- Implementation:System configuration, data migration, and integration architecture deployment. Complex ERP connectivity projects for SAP environments consume the longest professional services cycles.
- Consulting:Procurement operating model redesign and category strategy development. Organizations pursuing CSRD compliance engage consultants for Scope 3 emissions baseline establishment.
- Support:Technical issue resolution and platform optimization guidance. 24/7 coverage tiers differentiate service levels for mission-critical procurement operations.
- Training:End-user enablement and administrator certification programs. Natural language interface adoption reduces traditional training dependencies for casual system users.
Implementation services anchor the volume base while Consulting expands most rapidly as regulatory complexity deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where enterprise procurement budgets absorb premium SaaS tiers, while Indian manufacturers operate under tighter margin constraints that favor rapid-deployment subscription models.
United States
FDA supply-chain traceability mandates for pharmaceutical manufacturers elevate sourcing software standards for batch-lot tracking and vendor qualification protocols. Procurement teams at Fortune 500 manufacturers face 18-36 month cloud migration timelines due to entrenched SAP ERP deployments. The Boston-Cambridge biotech corridor drives demand for automated supplier risk monitoring dashboards that scale across tier-n networks.
Germany
Automotive OEMs mandate real-time supplier risk monitoring, accelerating adoption of multi-tier mapping tools for tier-two and tier-three visibility. The EU AI Act and GDPR impose algorithmic transparency requirements on automated supplier scoring systems, forcing vendors to document decision logic. Industrial procurement clusters in Bavaria and Baden-Württemberg prioritize explainable AI modules within sourcing suites.
India
Domestic production incentives under the PLI scheme drive enterprises to modernize supplier onboarding infrastructure for subsidy compliance. CDSCO pharmaceutical regulations and evolving data sovereignty rules reshape vendor selection criteria for regulated industries. Manufacturing hubs in Maharashtra and Gujarat present greenfield SaaS adoption potential among underpenetrated mid-sized suppliers.
United Kingdom
Post-Brexit customs complexity increases demand for supplier credential verification portals with automated compliance checking. The FCA and Information Commissioner's Office enforce data residency constraints that complicate multi-region deployment architectures. London-based financial services procurement teams prioritize integration between sourcing execution and working capital financing modules.
Japan
METI industrial digitization programs accelerate cloud-native procurement platform adoption among precision manufacturers. PMDA pharmaceutical regulations align with FDA standards, elevating vendor qualification protocols for active ingredient sourcing. The Nagoya automotive cluster and Osaka industrial belt drive demand for real-time inventory synchronization with private-label supplier networks.
Sourcing Software Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with ERP-embedded suites commanding enterprise accounts while API-first specialists capture mid-market expansion. The market structure consolidates around three strategic tiers: legacy ERP-integrated incumbents, cloud-native challengers, and vertical specialists. Dominant competitive moves include M&A activity targeting spend analytics capabilities and strategic partnerships embedding procurement modules within broader enterprise SaaS ecosystems.
Within the ERP-embedded tier, SAP Ariba and Oracle Corporation occupy positions defined by embedded connectivity to complex procurement workflows. Coupa Software Inc. exemplifies the cloud-native challenger archetype, anchoring mid-market expansion through specialized spend analytics modules. These three companies represent the primary competitive anchors across enterprise and mid-market segments.
| Leading Market Players |
|---|
| Oracle Corporation |
| Coupa Software Inc. |
| GEP Corporation |
| SAP Ariba |
| Ivalua Inc. |
| Jaggaer Inc. |
| Zycus Inc. |
| Workday Inc. |
| Aavenir |
| Others |
Value Chain & Pricing Dynamics
Cloud-native architectures displacing legacy on-premises stacks simultaneously compress implementation timelines and redistribute pricing power toward vendors with elastic infrastructure footprints. This substitution dynamic concentrates margin capture among API-first specialists while forcing ERP-embedded incumbents to rearchitect delivery economics around subscription tiers rather than perpetual licensing.
Pricing Analysis
The customization-premium spread separates configured-to-order enterprise deployments from pre-configured SaaS tiers, with German automotive OEMs and US pharmaceutical manufacturers absorbing premium pricing for multi-tier supplier mapping modules. Price differentiation centers on integration complexity and data residency certification levels, with ISO 27001 and SOC 2 Type II credentials commanding tier premiums. Pricing pressure stems from mid-market manufacturers in India demanding rapid-deployment subscription models under PLI scheme compliance deadlines. Small and mid-sized enterprises exhibit highest price sensitivity, while Fortune 500 accounts with entrenched SAP deployments tolerate premium professional services cycles.
Supply Chain Analysis
ISO 27001 certification audit queues spanning three-to-six months create a chokepoint that delays vendor qualification for pharmaceutical and defense procurement evaluations. Software development concentrates in the United States, Germany, and India, with cloud infrastructure provisioning drawing from AWS, Azure, and GCP hyperscaler networks. Raw material dependencies include elastic compute capacity, API gateway services, and specialized procurement technologist talent pools. Single-source vulnerability runs through concentrated certification auditor capacity. Distribution runs through direct enterprise sales teams and channel partners embedding sourcing modules within broader SaaS ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sourcing software fragmentation creates entry niches as regulatory complexity splinters buyer requirements across GDPR algorithmic transparency, FDA supply-chain traceability, and CDSCO pharmaceutical mandates.
For Market Incumbents: Secure embedded ERP connectivity advantages by deepening API-first architecture investments that compress cloud migration timelines for SAP-dominated Fortune 500 accounts. Fortify positions against cloud-native challengers through autonomous sourcing R&D intensity and explainable AI module development that satisfies EU AI Act documentation requirements.
For New Entrants and Emerging Players: Anchor in underpenetrated mid-sized manufacturing clusters in Maharashtra and Gujarat where PLI scheme compliance deadlines drive greenfield SaaS adoption without legacy system entrenchment. Target rapid-deployment supplier onboarding portals with real-time credential verification as the primary go-to-market wedge against email-based qualification workflows.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed spend analytics specialists possessing modular AI components that isolate audit-ready subsystems for pharmaceutical manufacturers. Long-term viability favors platforms converging sourcing execution with working capital financing modules. Watch CSRD Scope 3 emissions disclosure enforcement as the signal indicating accelerated carbon-accounting module demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first connectivity to SAP ERP environments captures entrenched enterprise accounts with complex procurement workflows. |
| Acquisition of Specialist Firm | Spend analytics capabilities deepen margin pool capture as enterprises seek tier-two and tier-three supplier visibility. |
| Geographic Expansion | India manufacturing hubs under PLI scheme deadlines present greenfield SaaS adoption among domestic supplier networks. |
| Strategic Partnership | Embedding procurement modules within hyperscaler marketplaces accelerates mid-market penetration through channel leverage. |
| Product Launch | Natural language procurement interfaces miniaturize technical barriers for category managers without SQL training. |
Study Parameters
The analysis maps cloud-based, SaaS, hybrid, and on-premises deployment segments, each validated through chief procurement officers, IT integration specialists, supplier risk managers, and cloud platform engineers. Primary interviews with these stakeholders combined with secondary validation from SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory filings. Bottom-up deployment model adoption rates triangulated against top-down enterprise software spending patterns.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical industry, integration complexity level, and regional regulatory cluster. CAGRs derived from elasticity-adjusted adoption curves and replacement cycle timing. Industry-specific forecast inputs incorporated PLI scheme compliance deadlines and CSRD disclosure phase-in schedules.
Decision-makers should treat outputs as directional under base assumptions of sustained cloud migration momentum and regulatory enforcement continuity; material deviation in GDPR or EU AI Act implementation timelines would warrant model refresh. Practitioners should keep alternative scenarios live as data sovereignty rule evolution and legacy ERP entrenchment patterns shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
United States Contract Lifecycle Management Software Market
Software & Services
Over-The-Air Software Update Market
Software & Services
Legal Software Market
Software & Services
General Ledger Accounting Software Market
Software & Services
Procurement Software Market
Software & Services
Service Dispatch Software Market
Software & Services
Virtual Fitting Software Market
Software & Services
Android Emulator Market
Software & Services
Global Landscape Software Market
Software & Services
Global Construction Punch List Software Market
Software & Services
Global ITSM Software Market
Software & Services
Middle East HR Payroll Software Market
Software & Services
Server Software Market
Software & Services
Australia HR Payroll Software Market
Software & Services
Ccaas Software Market
Software & Services
Global Polling Software Market