
 Enterprise Mobility Software Market | 2026-2036
Enterprise Mobility Software Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Mobility Software Market Analysis
India is fragmenting as a deployment hub as cloud infrastructure investments multiply across Bengaluru and Hyderabad data center corridors. VMware sustains enterprise-grade virtualization capabilities that anchor multi-platform device orchestration for Fortune 500 accounts. IBM dominates security-intensive segments through its Watson-powered threat intelligence integrations. Kandji specializes in Apple-centric MDM workflows, occupying a defensible niche among creative and professional services firms.
Enterprise mobility software encompasses platforms that provision, secure, and manage corporate data access across smartphones, tablets, and ruggedized field devices through centralized policy engines and containerization protocols. These systems enforce encryption standards, geofencing rules, and remote wipe capabilities to protect sensitive assets without compromising end-user productivity. Mobile Device Management solutions lead current revenue pools as organizations retrofit legacy fleets, while Mobile Security modules capture expanding margin pools as zero-trust architectures displace perimeter-based defenses. Cloud-Based deployment models are displacing on-premise installations fastest among mid-market buyers seeking OpEx flexibility.
FCC guidelines on wireless spectrum allocation shape device connectivity standards for cross-border workforce mobility in the United States. GDPR data residency requirements and the EU AI Act's automated decision-making disclosures constrain how European enterprises deploy AI-driven endpoint analytics. Stakeholders must weigh sovereign cloud mandates against interoperability costs when architecting multi-national mobility stacks.
Market Dynamics
Zero-trust security architectures are compressing deployment cycles for enterprise mobility platforms as perimeter-based defenses lose institutional credibility. Healthcare systems and industrial manufacturers now demand continuous device verification rather than one-time authentication gates.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises must retrofit automated endpoint management systems with algorithmic transparency features. This regulatory pressure accelerates replacement cycles for legacy mobility stacks.
- Industrial manufacturing mobility:German factory operators are deploying ruggedized device fleets with geofenced data access. Secure mobile operations on production floors now represent a procurement priority.
- Cloud-native containerization:Kubernetes-orchestrated mobility platforms enable policy portability across multi-cloud environments. Mid-market buyers favor OpEx flexibility over capital-intensive on-premise installations.
Market Restraints
- GDPR data residency costs:Sovereign cloud mandates force redundant infrastructure deployment across European member states. Interoperability expenses inflate total cost of ownership for multinational mobility architectures.
- Specialized talent scarcity:Zero-trust architecture implementation requires scarce cybersecurity expertise. Organizations face extended deployment timelines due to certified engineer shortages.
- Legacy system entrenchment:Decades-old on-premise identity management systems resist API-based integration. Rip-and-replace costs deter incremental modernization efforts.
Strategic Opportunities
- India cloud corridor expansion:Bengaluru and Hyderabad data center investments are fragmenting deployment infrastructure. Mobility vendors can establish localized service nodes without Mumbai-centric concentration.
- AI-driven endpoint analytics:Converging machine learning inference with mobile threat detection creates predictive security capabilities. Early movers capture premium positioning in automated incident response.
- Outcome-based security contracting:Enterprise buyers seek guaranteed breach-response SLAs rather than seat-based licensing. Pricing innovation aligns vendor incentives with customer risk reduction.
Industry Challenges
- Cross-platform policy harmonization:iOS, Android, and ruggedized Linux endpoints require divergent management protocols. Engineering teams struggle to maintain consistent encryption standards across heterogeneous fleets.
- Certification timeline compression:Common Criteria and FIPS 140-2 validation cycles lag behind product release schedules. Federal and healthcare procurement windows close before security attestations complete.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Mobility Software Market |
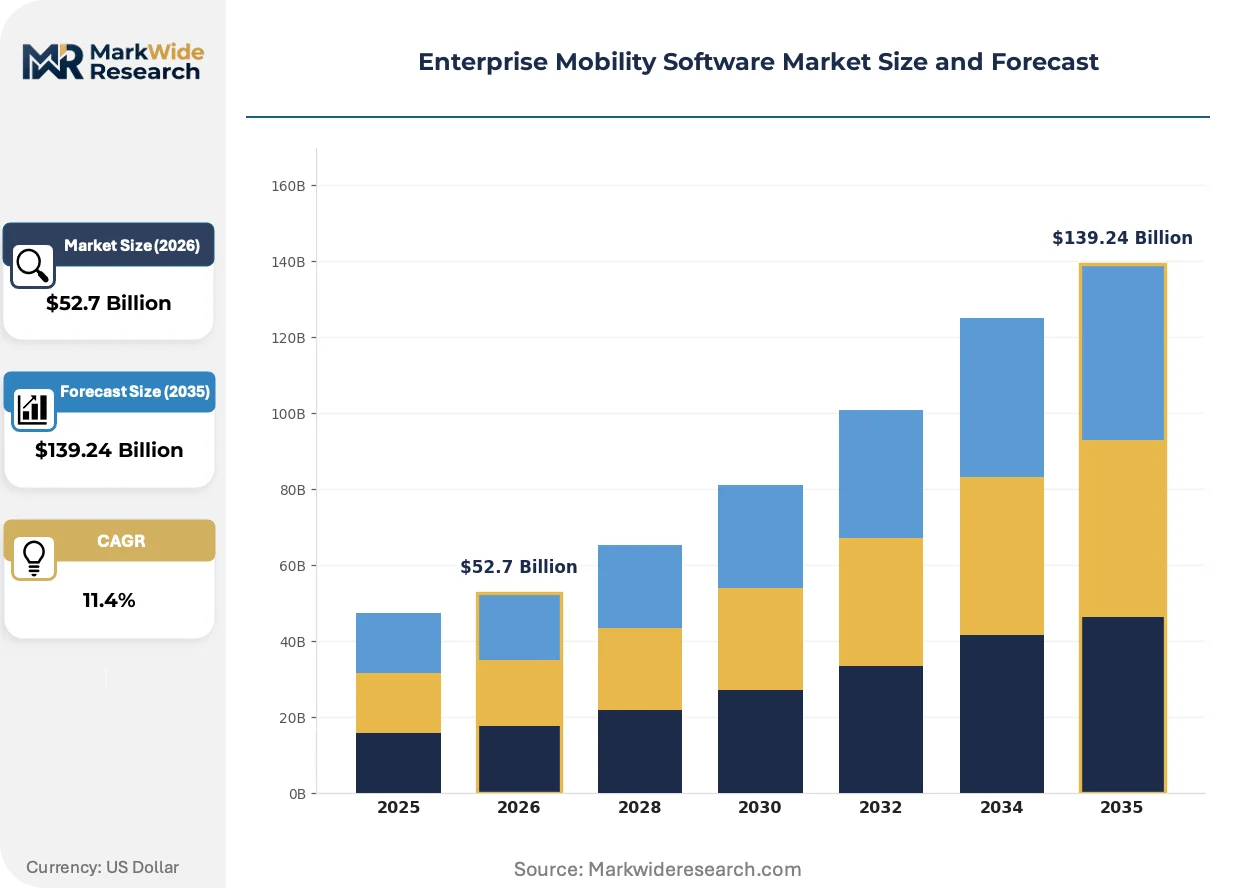
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $139.24 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User: Small Enterprises, Medium Enterprises, Large Corporations, Government Agencies Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services Solution: Mobile Device Management, Mobile Application Management, Mobile Security, Mobile Content Management Industry Vertical: Healthcare, Retail, Manufacturing, Finance |
| Companies Covered | Scalefusion, Kandji, VMware, FileWave, Addigy, SOTI, AirDroid Business, Meraki, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Mobility Software Market Emerging Trajectories
Edge computing integration is redefining where mobility policy enforcement occurs, shifting computation from centralized data centers toward distributed device clusters. This architectural pivot demands new orchestration capabilities.
Confidential computing enclaves are digitizing sensitive data processing on mobile endpoints. Financial services institutions pilot hardware-isolated execution environments for trading applications. The technology is digitizing compliance workflows by enabling attestation without exposing raw data to host operating systems.
The EU AI Act's automated decision-making disclosure requirements are forcing transparency into endpoint management algorithms. European enterprises must now document how AI-driven access policies evaluate user behavior. Mobility vendors serving Germany, France, and the Netherlands are retrofitting audit trails into existing orchestration engines.
Subscription-based consumption models are displacing perpetual licensing in mid-market procurement. IT departments prefer operational expenditure treatment for mobility infrastructure. North American healthcare systems and professional services firms now prioritize month-to-month flexibility over multi-year enterprise agreements.
Enterprise Mobility Software Market Segmentation
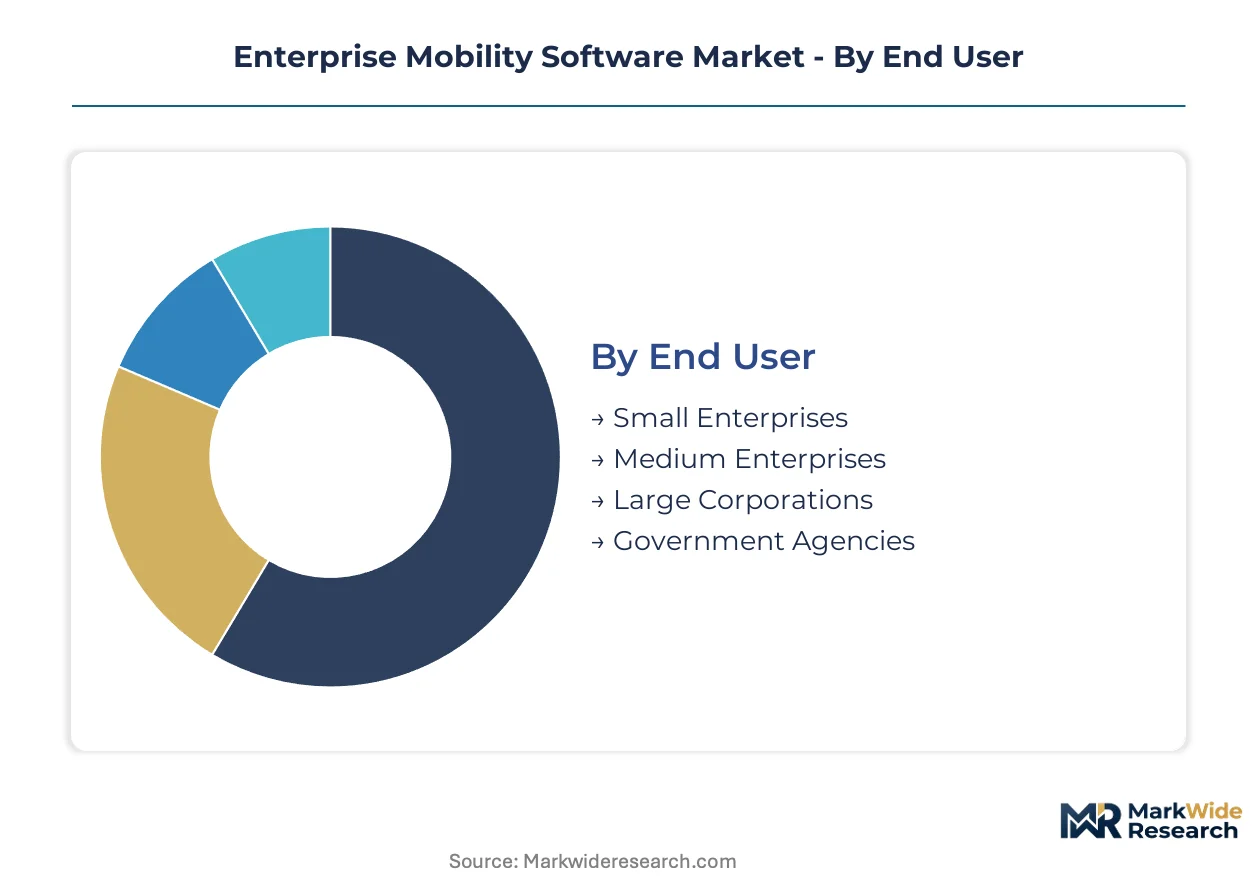
Enterprise mobility software procurement varies sharply by organizational scale, infrastructure posture, and regulatory exposure. Segmentation reveals where solution complexity concentrates and which deployment models capture margin expansion.
End User:
Workforce size dictates feature depth, with compliance requirements scaling non-linearly against employee count.
- Small Enterprises:Cloud-native MDM suites with minimal IT overhead dominate procurement. These buyers prioritize out-of-box deployment over customization, with HIPAA and PCI-DSS pre-certifications driving vendor selection in US healthcare and retail sub-sectors.
- Medium Enterprises:Hybrid identity architectures bridge legacy Active Directory with modern zero-trust frameworks. German industrial manufacturers in this tier demand geofenced data access for shop-floor tablets, accelerating investment in policy automation.
- Large Corporations:Multi-tenant orchestration platforms with API extensibility anchor procurement. Fortune 500 accounts require cross-platform containerization spanning iOS, Android, and ruggedized Linux endpoints.
- Government Agencies:FIPS 140-2 and Common Criteria certifications filter vendor eligibility. Federal procurement cycles in the United States favor established suppliers with pre-validated encryption modules.
The dominant share belongs to Large Corporations, while Medium Enterprises are closing the gap fastest.
Deployment:
Capital structure preferences are rebalancing infrastructure ownership models across buyer tiers.
- On-Premise:Air-gapped installations persist in defense and classified research environments. These deployments retain full data sovereignty but incur hardware refresh cycles that strain capital budgets.
- Cloud-Based:Kubernetes-orchestrated platforms enable policy portability across AWS, Azure, and GCP environments. Mid-market healthcare systems in North America favor OpEx treatment for mobility infrastructure over multi-year capital commitments.
- Hybrid:Sensitive identity data remains on-premise while device management shifts to cloud control planes. European manufacturers navigate GDPR residency requirements through this split architecture.
- Managed Services:Third-party SOC operations handle threat monitoring and incident response. Talent-scarce organizations outsource zero-trust implementation to certified MSSP partners.
Cloud-Based deployments command the largest revenue pool, though Managed Services is expanding most quickly among security-mature buyers.
Solution:
Functional modules compete for budget priority as security architectures evolve.
- Mobile Device Management:Fleet provisioning, configuration enforcement, and remote wipe capabilities form the foundational layer. Legacy retrofit projects in industrial manufacturing sustain current revenue concentration.
- Mobile Application Management:Containerized app delivery separates corporate data from personal device storage. Financial services institutions deploy MAM for trader mobility without full device enrollment.
- Mobile Security:Zero-trust access policies with continuous device verification capture expanding margin pools. EU AI Act compliance mandates are accelerating replacement of perimeter-based endpoint analytics.
- Mobile Content Management:Document synchronization with DRM enforcement protects intellectual property in creative and professional services workflows. Kandji and Apple-centric vendors specialize here.
Mobile Device Management retains the installed base majority, yet Mobile Security is gaining share fastest as zero-trust displaces legacy defenses.
Industry Vertical:
Sector-specific compliance regimes and workforce mobility patterns shape solution requirements.
- Healthcare:HIPAA encryption standards and FDA guidance on clinical decision support govern mobile deployments. Patient care coordination drives tablet and smartphone integration across hospital systems.
- Retail:PCI-DSS compliance for mobile point-of-sale and inventory management dominates procurement. Seasonal workforce scaling favors cloud-based policy deployment.
- Manufacturing:Ruggedized device fleets with geofenced shop-floor access represent priority investments. German factory operators lead European demand for secure mobile operations.
- Finance:SEC cybersecurity disclosure rules and confidential computing pilots for trading applications define leading-edge adoption. Hardware-isolated execution environments are digitizing compliance workflows.
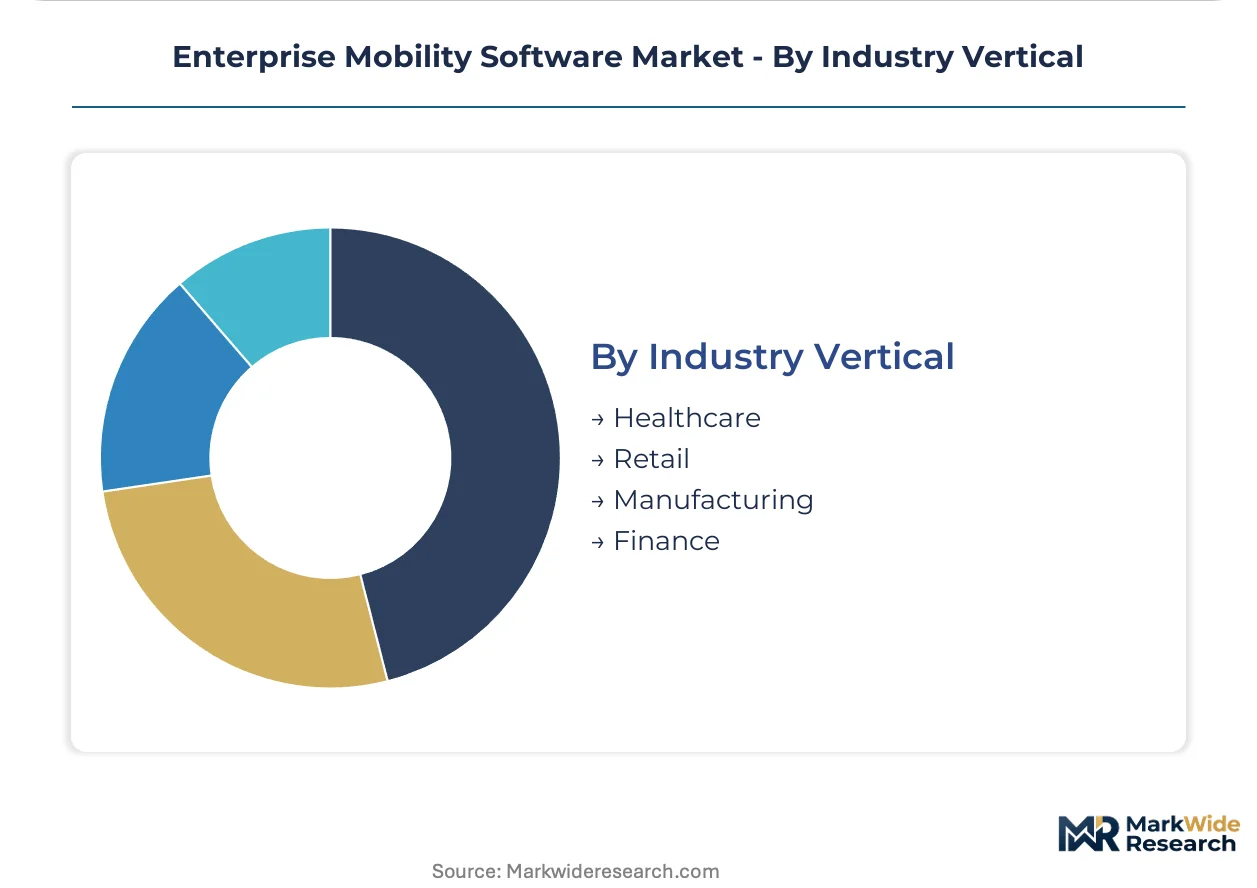
Healthcare anchors current spending, while Manufacturing is climbing the fastest on industrial IoT convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure investments concentrate mobility software deployment capacity across three distinct continental corridors. Regulatory fragmentation around data sovereignty and AI governance is forcing vendors to architect region-specific compliance stacks rather than unified global platforms.
United States
Federal healthcare systems and Fortune 500 manufacturers drive zero-trust mobility adoption. FCC spectrum allocation guidelines shape cross-border workforce connectivity standards. Silicon Valley and Seattle anchor cloud-native MDM development clusters where Kubernetes-orchestrated platforms emerge.
Germany
Industrial manufacturers in Bavaria and Baden-Württemberg deploy ruggedized device fleets with geofenced shop-floor access. EU AI Act automated decision-making disclosures constrain AI-driven endpoint analytics deployment. Frankfurt and Munich data centers concentrate sovereign cloud infrastructure for GDPR-compliant mobility stacks.
India
Cloud corridor expansion across Bengaluru and Hyderabad fragments deployment infrastructure away from Mumbai-centric concentration. TRAI data localization guidelines intersect with enterprise mobility procurement requirements. Hyderabad's data center investments enable localized service nodes for mid-market MDM buyers.
United Kingdom
Financial services institutions in London pilot confidential computing enclaves for trading mobility applications. GDPR residency requirements persist post-Brexit through UK Data Protection Act alignment. The Thames Valley corridor hosts managed security service providers handling zero-trust implementation for talent-scarce organizations.
Japan
Manufacturing conglomerates in Kansai and Chubu regions integrate ruggedized mobility into industrial IoT workflows. METI cybersecurity frameworks govern critical infrastructure endpoint protection standards. Tokyo's enterprise software vendors develop API-extensible orchestration platforms for multi-tenant multinational deployments.
Enterprise Mobility Software Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower functional scope. The vendor base clusters around three strategic archetypes: virtualization-heavy incumbents with multi-platform orchestration capabilities, security-centric players with threat intelligence integration, and Apple-focused boutiques serving creative verticals. Competitive moves concentrate on cloud-native containerization partnerships and outcome-based security contracting with guaranteed breach-response SLAs.
Within the platform integrator tier, VMware and IBM exemplify divergent strategic positioning—one anchoring enterprise-grade virtualization for Fortune 500 multi-platform fleets, the other dominating security-intensive segments through Watson-powered threat intelligence. Kandji occupies a defensible niche among Apple-centric MDM specialists, serving creative and professional services firms with streamlined macOS and iOS workflows. Scalefusion and SOTI represent mid-market challengers with cloud-native deployment flexibility, while Addigy and FileWave sit within the Apple-specialist tier alongside Kandji. Meraki and AirDroid Business anchor network-integrated and cross-platform Android mobility vectors respectively.
| Leading Market Players |
|---|
| Scalefusion |
| Kandji |
| VMware |
| FileWave |
| Addigy |
| SOTI |
| AirDroid Business |
| Meraki |
| IBM |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on hyperscaler cloud infrastructure determines both pricing tier spreads and supply chain shape in enterprise mobility software, as AWS, Azure, and GCP concentration forces vendors into margin-compressing platform commitments while creating procurement rigidity for end buyers.
Pricing Analysis
FCC spectrum allocation guidelines and GDPR data residency mandates dictate the pricing tier structure across the Enterprise Mobility Software Market, with compliance-certified deployments commanding premiums over standard cloud-native offerings. Three-tier pricing structure across premium, standard, and economy levels separates FIPS 140-2 validated federal-grade solutions from mid-market HIPAA-compliant suites and basic SMB MDM packages. Cost compression in the economy tier is intensifying because Indian cloud corridor expansion enables localized service delivery at reduced operational expenditure. Government agencies exhibit the least price sensitivity due to certification barriers, while small enterprises in North American healthcare demonstrate acute sensitivity to per-seat licensing costs.
Supply Chain Analysis
Upstream feedstock in enterprise mobility software centers on semiconductor fabrication for secure enclave processors, with Taiwan, South Korea, and the United States anchoring advanced node production for confidential computing chipsets. Kubernetes orchestration engines and zero-trust policy engines draw from open-source foundations and proprietary threat intelligence feeds respectively. Single-source vulnerability in EU sovereign cloud infrastructure creates procurement bottlenecks for German industrial manufacturers requiring GDPR-compliant data residency. Distribution runs through direct enterprise sales for Fortune 500 accounts and certified MSSP channels for talent-constrained mid-market buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across deployment models and regulatory jurisdictions creates niche formation opportunities, as EU AI Act compliance mandates splinter unified platforms into region-specific compliance stacks.
For Market Incumbents: Harden API extensibility around legacy Active Directory integrations to defend against cloud-native challengers eroding the hybrid identity architecture segment. Fortify certification pipelines for Common Criteria and FIPS 140-2 validation cycles, compressing timeline gaps that federal procurement windows exploit. Deepen vertical integration into confidential computing hardware partnerships to capture premium positioning in financial services pilots. For New Entrants and Emerging Players: Hyderabad and Bengaluru cloud corridor underpenetration offers white-space entry for localized MDM service nodes outside Mumbai-centric vendor concentration. Target German industrial manufacturers with ruggedized device geofencing solutions purpose-built for GDPR-compliant shop-floor deployments. Pursue outcome-based security contracting with guaranteed breach-response SLAs as the primary go-to-market angle to differentiate from seat-based incumbents. For Investors and Strategic Acquirers: EU AI Act implementation milestones reshape the acquisition landscape toward algorithmic transparency capabilities and automated decision-making audit trail technologies. Position portfolios for long-term viability by targeting Apple-centric MDM specialists with defensible creative vertical moats or zero-trust architecture boutiques with Watson-class threat intelligence integration. Monitor hyperscaler partnership exclusivity announcements as the critical inflection signal for platform consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Kubernetes-orchestrated policy portability across AWS, Azure, and GCP environments captures mid-market OpEx preference. |
| Acquisition of Specialist Firm | Apple-centric MDM boutiques in creative verticals offer defensible niche positioning against multi-platform incumbents. |
| Geographic Expansion | Hyderabad data center investments enable localized service nodes for Indian cloud corridor fragmentation. |
| Strategic Partnership | Confidential computing hardware alliances with semiconductor vendors unlock financial services trading mobility pilots. |
| Product Launch | AI-driven endpoint analytics with EU AI Act algorithmic transparency features accelerate European replacement cycles. |
Methodological Framework
Cross-validation between primary interviews with CISOs, IT procurement officers, platform engineers, and MSSP operations leads anchors the qualitative findings, while secondary validation draws from SEC filings, hyperscaler capex disclosures, GPO contracts, and hospital procurement databases. Bottom-up deployment model sizing and top-down vertical spending analysis complete the triangulation architecture.
Calibration against historical adoption curves and regulatory implementation timelines shapes the analytical framework across the analysis window. Segmentation dimensions include deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs derive from installed base migration rates and replacement cycle compression, with EU AI Act compliance deadlines and zero-trust architecture maturity curves serving as primary forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native challengers or sovereign cloud mandates would shift outcomes. Cross-checking against hyperscaler partnership announcements and federal certification timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Intellectual Property Software Market
Software & Services
Laboratory Management Software Market
Software & Services
Employee Referral Software Market
Software & Services
Global Accounts Receivable Software Market
Software & Services
Poultry Farm Management Software Market
Software & Services
Cloud-Based Dental Practice Management Software Market
Software & Services
Push Notifications Software Market
Software & Services
HACCP Software Market
Software & Services
Job Description Management Software Market
Software & Services
Adaptive Learning Software Market
Software & Services
Managed Information Services Market
Software & Services
Global Sales Enablement Platform Market
Software & Services
Jobsite Management Software Market
Software & Services
Global Application Platform Market
Software & Services
Pet Tracking Software Market
Software & Services
Software Release Management Tools Market