
 Commissioning Software Market | 2026-2036
Commissioning Software Market Size, Share, and Industry Trends Forecast 2026-2036
Commissioning Software Market Outlook
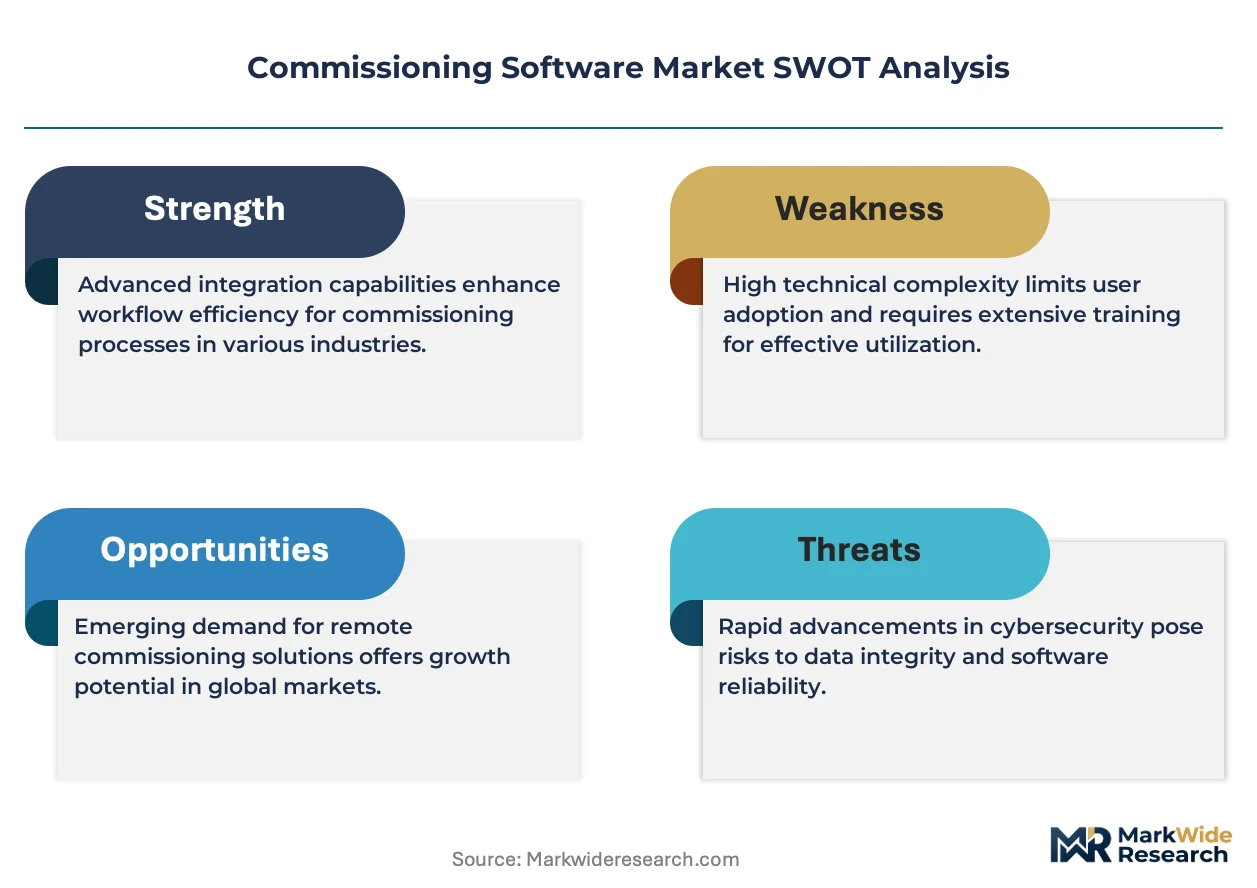
The gap between premium integrated suites and commodity point solutions is shifting from feature count to ecosystem depth. Siemens anchors its position through captive hardware-software integration across building automation portfolios. BlueRithm differentiates via specialized HVAC commissioning workflows that sustain pricing power in contractor segments. CxAlloy competes on cloud-native architecture that extends deployment velocity for distributed engineering services.
Commissioning software encompasses digital platforms that verify, document, and manage building system performance against design intent, typically integrating IoT sensor data, test script libraries, and compliance checklists into unified project dashboards. Its primary purpose is to reduce energy waste, system defects, and handover disputes across complex construction and retrofit projects. Web-based deployment leads in new sales due to lower IT overhead and faster onboarding for construction firms with transient project teams. Cloud-based infrastructure represents the fastest-expanding deployment category as engineering services consolidate fragmented toolchains into centralized platforms. On-premises solutions retain margin concentration among defense and critical infrastructure clients with air-gapped security requirements.
ISO 50001 energy management standards, the EU Green Deal's building renovation wave, and F-Gas Regulation compliance protocols collectively shape product roadmaps and certification requirements for vendors serving European markets. The US EPA ENERGY STAR program and ASHRAE Guideline 0-2019 further define functional benchmarks that determine procurement eligibility in North American public projects. Stakeholders must monitor how evolving carbon disclosure mandates in France, Germany, and California reshape the minimum viable feature set for competitive commissioning platforms.
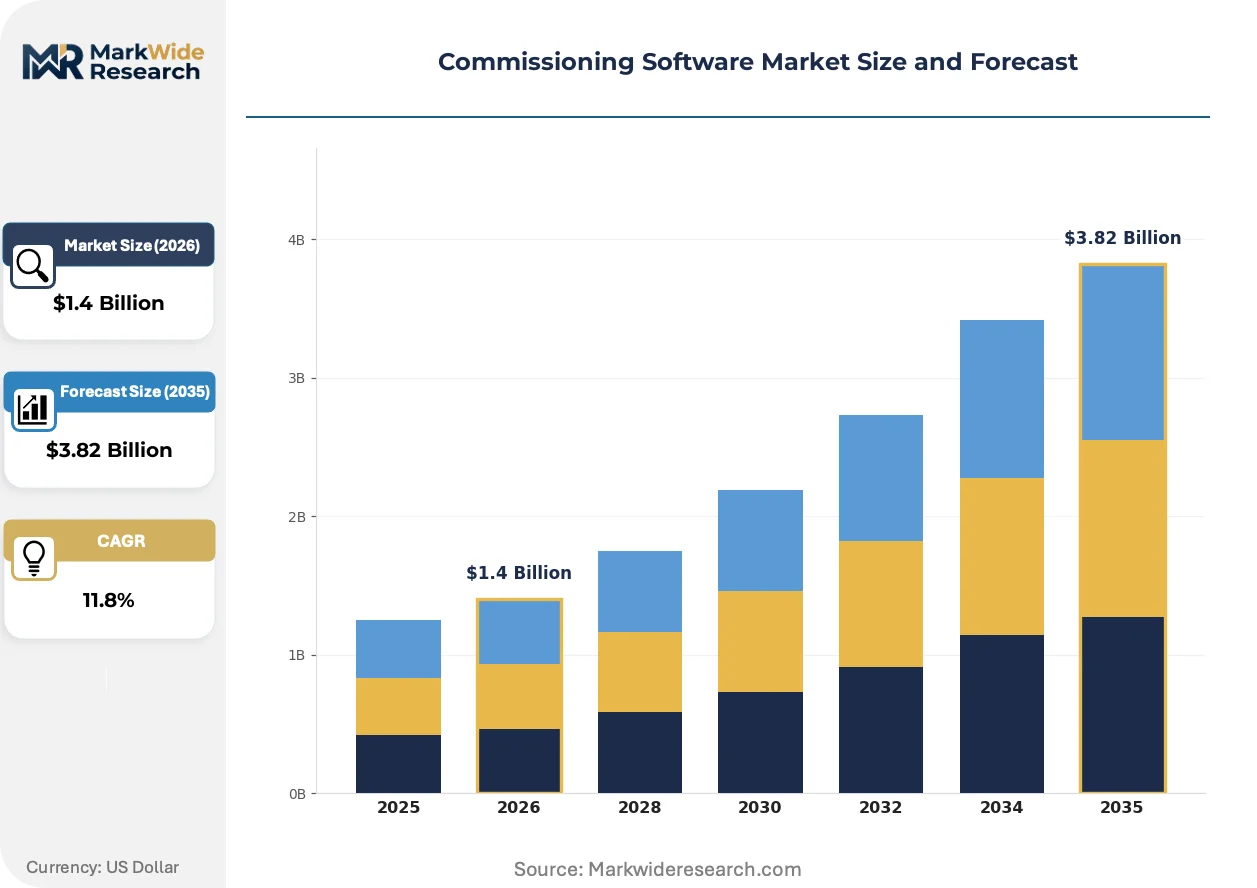
Market Dynamics
The Commissioning Software Market is experiencing structural compression as building energy codes tighten across developed economies, forcing facility owners to replace paper-based verification with digital audit trails that satisfy enforcement agencies.
Growth Catalysts
- EU Green Deal building renovation wave:The European Commission mandates systematic energy performance documentation for all large buildings undergoing renovation, creating immediate procurement requirements for commissioning platforms that automate compliance checklists.
- IoT sensor proliferation:Falling hardware costs enable continuous commissioning models where real-time building performance data feeds directly into software dashboards, reducing manual inspection labor for facilities teams.
- Germany's federal building energy codes:The 2024 amendments require digital handover documentation for HVAC systems in commercial buildings above specific thresholds, concentrating demand among German engineering services firms.
Market Restraints
- Legacy system integration costs:Many commercial buildings operate Building Management Systems from the 1990s that lack API connectivity, forcing expensive middleware development or partial automation that limits software value capture.
- Construction sector labor constraints:Skilled commissioning agents remain scarce in markets with aging workforces, creating bottlenecks where software deployment outpaces qualified users who can interpret automated diagnostics.
- Data sovereignty requirements:Critical infrastructure operators in defense and healthcare sectors mandate on-premises deployment, fragmenting vendor development resources across incompatible architecture requirements.
Strategic Opportunities
- France's tertiary building decarbonization mandate:The RE2020 regulatory framework requires progressive energy consumption reductions through 2050, positioning commissioning software as essential infrastructure for compliance tracking and penalty avoidance.
- Digital twin convergence:Integration between commissioning platforms and Building Information Modeling creates persistent virtual replicas that support operational optimization long after construction handover, extending contract value.
- Subscription pricing penetration:Smaller mechanical contractors previously priced out of perpetual license models now access cloud-native platforms through monthly fees, expanding addressable market into the long tail of regional service providers.
Industry Challenges
- Interoperability standard fragmentation:Competing data exchange protocols between BACnet, Modbus, and proprietary vendor formats force custom integration work for each deployment, eroding margin on mid-market projects.
- Cybersecurity certification timelines:Achieving IEC 62443 compliance for industrial control systems software requires 12-18 month validation cycles that delay product releases and freeze feature roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commissioning Software Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Web-Based, Mobile Apps, On-Premises, Hybrid Solutions End User: Construction Firms, Engineering Services, Facilities Management, HVAC Installers Deployment: Cloud-Based, On-Site Implementation, Managed Services, Third-Party Platforms Feature: Task Management, Reporting Tools, Collaboration Features, Integration Capabilities |
| Companies Covered | CxAlloy, CxPlanner, BlueRithm, flowdit, ProjecTools, Siemens, WinPCS, Facility Dynamics, GATE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commissioning Software Market Strategic Shifts
Commissioning software architecture is pivoting from project-centric tools to operational platforms that persist through building lifecycles. This shift redefines vendor relationships from one-time sales to recurring engagement models.
Digital twin technology is unifying previously siloed commissioning workflows. Siemens, Schneider Electric, and Autodesk now embed commissioning modules within broader building lifecycle platforms. Engineering services firms in Germany and the Netherlands are adopting these integrated suites fastest, compressing procurement cycles that previously required separate software evaluations for design, construction, and operations phases.
The F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is reshaping HVAC commissioning requirements across EU member states. Inspection protocols now mandate leak detection documentation and refrigerant charge verification that legacy paper systems cannot support. French and Italian contractors are upgrading software capabilities specifically to satisfy these environmental enforcement requirements.
Facility management procurement patterns are compressing software evaluation cycles. Large real estate investment trusts now mandate commissioning platform compatibility with their existing enterprise asset management systems before vendor consideration. This precondition is most visible in California and New York, where institutional owners operate portfolios spanning hundreds of buildings and prioritize centralized data aggregation over point solution functionality.
Commissioning Software Market Segmentation
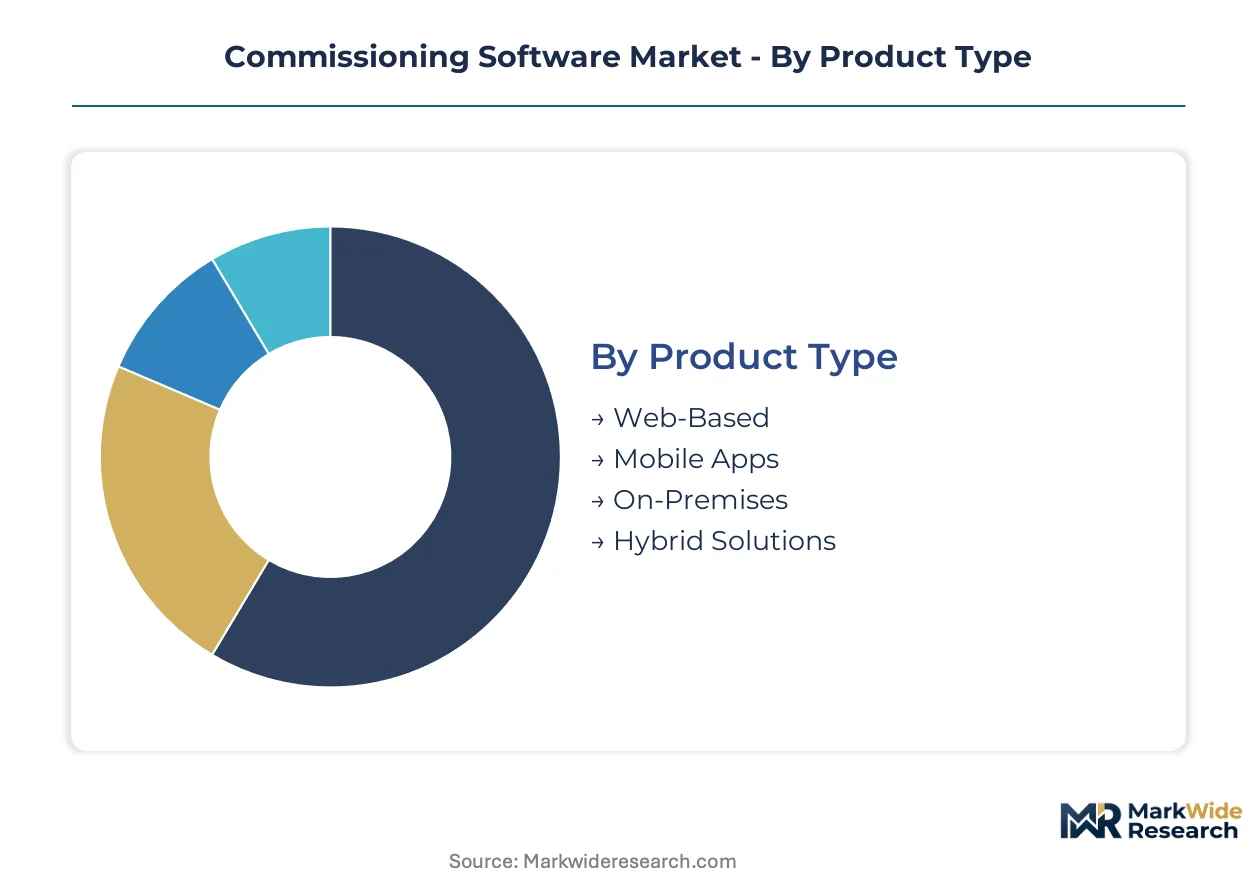
Commissioning software segmentation reveals how compliance requirements fragment procurement patterns across user types. Certification burdens vary sharply between regulated infrastructure and commercial construction, reshaping vendor go-to-market priorities.
Product Type:
ISO 50001 energy management certification and IEC 62443 cybersecurity standards impose divergent validation requirements across deployment modes. Air-gapped on-premises installations face the longest compliance timelines.
- Web-Based:Browser-accessible platforms with minimal IT infrastructure requirements. Construction firms in Germany favor these for transient project teams needing rapid onboarding without client-side installation. The EU Green Deal's documentation mandates accelerate replacement of paper workflows here.
- Mobile Apps:Native or progressive web applications optimized for field data capture. HVAC installers in France adopt these for refrigerant leak documentation required under F-Gas Regulation protocols. Offline synchronization capabilities determine competitive positioning among contractor segments.
- On-Premises:Self-hosted installations meeting defense and healthcare data sovereignty requirements. Critical infrastructure operators mandate these despite 18-month IEC 62443 certification cycles that freeze vendor roadmaps.
- Hybrid Solutions:Architectures combining cloud coordination with local edge processing. Engineering services firms in the Netherlands deploy these for projects with mixed security classifications.
Web-Based sits at the top of the volume ranking, with Mobile Apps climbing the fastest.
End User:
Procurement authority concentrates differently across these segments, with facilities management consolidating vendor relationships while construction remains fragmented.
- Construction Firms:General contractors and specialty trades managing project-phase commissioning. German federal building energy codes now mandate digital handover documentation, forcing mid-tier firms off paper systems. Subscription pricing models expand access for regional players previously priced out.
- Engineering Services:Commissioning authorities and MEP consultants performing third-party verification. These users drive demand for test script libraries and automated compliance checklists. Cloud-native platforms gain traction among distributed practices.
- Facilities Management:Building operators conducting continuous commissioning post-handover. California and New York institutional owners mandate enterprise asset management integration before vendor consideration. IoT sensor proliferation enables persistent performance monitoring contracts.
- HVAC Installers:Mechanical contractors executing system startup and balancing. French contractors specifically upgrade capabilities to satisfy RE2020 tertiary building decarbonization mandates. Leak detection documentation requirements reshape feature priorities.
Facilities Management commands the largest contract values, though HVAC Installers show the steepest expansion trajectory as regulatory deadlines approach.
Deployment:
Margin structures diverge sharply between self-managed implementations and vendor-controlled service arrangements.
- Cloud-Based:Multi-tenant SaaS platforms with centralized infrastructure. Fastest-expanding category as engineering services consolidate fragmented toolchains. ASHRAE Guideline 0-2019 functional benchmarks determine procurement eligibility in US public projects.
- On-Site Implementation:Dedicated instances with customer-controlled infrastructure. Retains concentration among defense clients with air-gapped security requirements. Higher upfront costs limit penetration outside regulated sectors.
- Managed Services:Vendor-operated platforms with outsourced administration. Appeals to construction firms lacking internal IT capacity. Recurring revenue models extend customer lifetime value for software providers.
- Third-Party Platforms:Integration layers connecting commissioning modules to broader building lifecycle systems. Siemens and Schneider Electric embed these within digital twin architectures. Procurement cycles compress when design, construction, and operations phases share unified data environments.
Cloud-Based leads deployment volumes, while Third-Party Platforms gain share fastest through convergence with Building Information Modeling workflows.
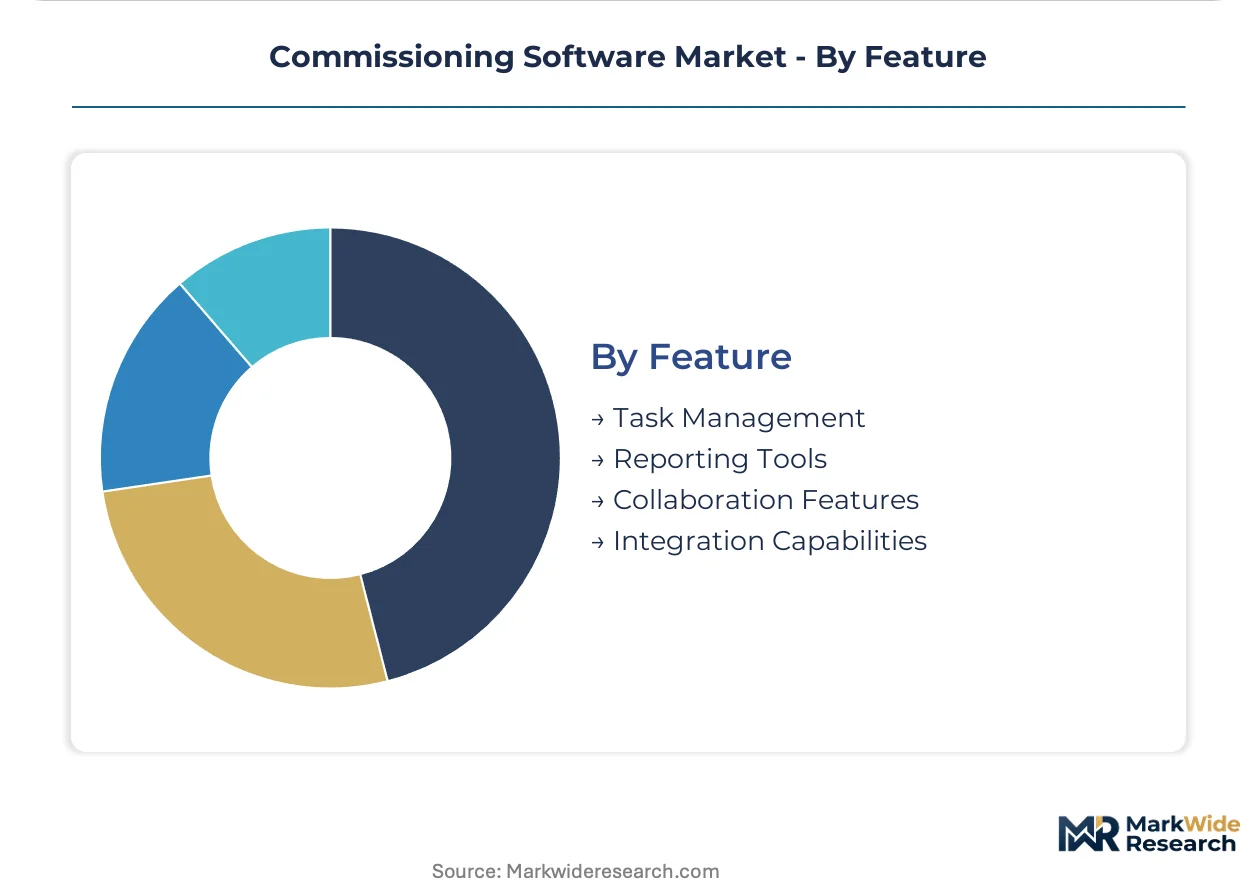
Feature:
Feature bundling strategies reflect whether buyers prioritize operational efficiency or regulatory audit trails.
- Task Management:Work assignment, scheduling, and completion tracking for commissioning agents. Scarcity of qualified commissioning professionals in aging workforces elevates automation value. Digital workflow routing reduces manual coordination overhead.
- Reporting Tools:Automated generation of compliance documentation and performance certificates. EPA ENERGY STAR program eligibility depends on standardized output formats. French enforcement agencies require specific refrigerant charge verification templates.
- Collaboration Features:Multi-stakeholder communication and document sharing across project phases. Reduces handover disputes through persistent audit trails. Real estate investment trusts prioritize centralized data aggregation capabilities.
- Integration Capabilities:API connectivity to Building Management Systems and enterprise asset management platforms. BACnet and Modbus protocol support remains inconsistent, forcing custom middleware development. Interoperability standard fragmentation erodes margins on mid-market deployments.
Reporting Tools dominates procurement specifications, with Integration Capabilities expanding most quickly as facility management platforms consolidate vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering services talent clusters in Germany, the Netherlands, and France anchor European commissioning software adoption, while California and New York institutional owners drive North American procurement consolidation.
Germany
Federal building energy code amendments mandate digital handover documentation for commercial HVAC systems, concentrating demand among Munich and Frankfurt engineering services firms. The 2024 amendments require systematic commissioning documentation above specific building thresholds. Berlin-based facilities management teams are replacing paper verification workflows with cloud-native platforms to satisfy enforcement agency audit trails.
France
RE2020 tertiary building decarbonization mandates require progressive energy consumption reductions through 2050, positioning commissioning software as penalty avoidance infrastructure. ANSM and CNIL oversight shapes data handling requirements for building performance platforms. Lyon and Marseille contractors specifically upgrade capabilities to satisfy refrigerant leak detection documentation under F-Gas Regulation protocols.
United States
EPA ENERGY STAR program eligibility and ASHRAE Guideline 0-2019 benchmarks determine procurement requirements for public projects. California Title 24 building standards mandate commissioning for non-residential buildings exceeding specific floor areas. New York City Local Law 87 drives retro-commissioning documentation requirements across Manhattan and Brooklyn commercial portfolios.
Netherlands
Engineering services firms in Amsterdam and Rotterdam adopt hybrid cloud-edge architectures for projects with mixed security classifications. The country's national building energy regulator enforces performance verification standards aligned with EU Green Deal renovation wave targets. Eindhoven's smart building cluster accelerates digital twin convergence between commissioning platforms and Building Information Modeling workflows.
United Kingdom
London institutional real estate investment trusts mandate enterprise asset management integration before commissioning vendor consideration. The country's national building standards regulator enforces post-Grenfell fire safety documentation requirements that digital platforms must satisfy. Manchester and Birmingham facilities management teams prioritize centralized data aggregation across distributed building portfolios.
Commissioning Software Market Competitive Environment
Top-tier vendors anchor integrated building lifecycle platforms, while specialized commissioning workflow providers occupy contractor-facing segments. The market structures around three tiers: captive hardware-software suites, cloud-native specialists, and legacy on-premises installations. Two strategic archetypes dominate: ecosystem integrators leveraging digital twin convergence, and compliance-focused specialists capturing regulatory deadline-driven upgrades. Competitive moves concentrate on strategic partnerships with Building Information Modeling vendors and portfolio diversification into continuous commissioning services.
Within the cloud-native specialist tier, CxAlloy and BlueRithm exemplify architectures designed for distributed engineering services velocity. Siemens occupies a position representing captive hardware-software integration across building automation portfolios. These three anchors illustrate how vendor positioning fragments between ecosystem depth and workflow specialization.
| Leading Market Players |
|---|
| CxAlloy |
| CxPlanner |
| BlueRithm |
| flowdit |
| ProjecTools |
| Siemens |
| WinPCS |
| Facility Dynamics |
| GATE |
| Others |
Value Chain & Pricing Dynamics
Cloud-native SaaS migration simultaneously compresses marginal delivery costs and concentrates vendor bargaining power among hyperscale infrastructure providers. This dual shift rewards engineering services firms with distributed practices while squeezing margins for on-premises specialists facing fragmented development overhead.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive positioning across deployment tiers. Three-tier pricing structure across premium, standard, and economy levels separates ecosystem-integrated suites from standalone commissioning modules. Price differentiation rests on certification depth—ISO 50001 energy management and IEC 62443 cybersecurity tiers command substantial premiums. Pricing pressure stems from subscription model proliferation among cloud-native entrants targeting mid-market construction firms. HVAC installers in France exhibit highest price sensitivity due to thin project margins, while facilities management teams at California institutional owners prioritize integration capabilities over unit cost.
Supply Chain Analysis
Domestic-content mandates in France and Germany reshape sourcing patterns for data residency-compliant infrastructure. Software development concentrates in Germany, the Netherlands, and the United States, with cloud infrastructure anchored in Irish and Swedish hyperscale regions. Raw material dependencies span semiconductor chips for edge devices, lithium-ion cells for mobile field hardware, and rare earth elements for IoT sensors. Single-source vulnerability runs through Taiwan-based foundries supplying industrial control components. Distribution runs through direct vendor sales for enterprise accounts and regional system integrators serving contractor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Commissioning Software Market functions as a stable compounder, with regulatory compliance mandates across EU member states and US states generating recurring procurement cycles that outpace discretionary IT spending volatility.
For Market Incumbents: Cement ecosystem lock-in through captive hardware-software integration across building automation portfolios. Deepen API connectivity to Siemens and Schneider Electric digital twin architectures to defend against cloud-native specialists. Prioritize IEC 62443 certification investment to maintain eligibility among defense and healthcare operators with air-gapped requirements.
For New Entrants and Emerging Players: Digital-channel self-service onboarding offers the most penetrable route into mid-tier mechanical contractors previously priced out of perpetual licenses. Target French HVAC installers facing RE2020 tertiary building decarbonization deadlines with refrigerant leak detection documentation modules. Pursue mobile-first field data capture as the primary go-to-market angle against legacy web-only incumbents.
For Investors and Strategic Acquirers: Valuations sit cheapest among on-premises specialists with concentrated defense exposure but limited cloud transition momentum. Five-to-ten-year viability favors vendors with recurring revenue exceeding sixty percent of total bookings. Watch F-Gas Regulation enforcement intensity across Italy and Spain as the signal for accelerated replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding commissioning modules within Autodesk Revit workflows compresses procurement cycles for Dutch engineering services. |
| Strategic Partnership | Alliances with Building Information Modeling vendors extend contract value through persistent digital twin engagement models. |
| Geographic Expansion | Entry into German federal building energy code compliance segments captures mandated digital handover documentation demand. |
| Product Launch | Offline-synchronized mobile applications satisfy F-Gas Regulation leak detection protocols for French contractor segments. |
| Acquisition of Specialist Firm | Consolidation of HVAC commissioning workflow expertise defends pricing power against integrated building lifecycle platforms. |
Study Parameters
Multiple input streams — commissioning authority interviews, facilities management procurement surveys, and regulatory filing analysis — were reconciled to construct market estimates. Primary fieldwork encompassed conversations with MEP consultants, HVAC contractor operations managers, building automation system integrators, and enterprise asset management procurement officers at California and New York institutional owners. Secondary validation drew from EU Green Deal implementation reports, EPA ENERGY STAR program documentation, ASHRAE guideline publications, and German federal building energy code amendments. Bottom-up project pipeline analysis and top-down construction spending allocation were triangulated against vendor-reported deployment metrics.
Data-stream reconciliation anchored the forecast framework across deployment modes, end-user segments, and regional regulatory clusters. Segmentation dimensions encompassed product architecture, user type procurement authority, infrastructure deployment model, and functional capability bundling. CAGRs were derived from fitted adoption curves calibrated to compliance deadline schedules and IoT sensor penetration trajectories. Cloud infrastructure cost curves and cybersecurity certification timeline assumptions shaped the projection envelope.
The model assumes a particular technology adoption path; alternative pathways for edge computing architectures would alter the outlook if latency requirements shift processing away from centralized clouds. Forecasts reflect assumptions regarding EU member state enforcement consistency and US state-level building code adoption timing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Ecommerce Software and Platform Market
Software & Services
Global Maintenance Management Software Market
Software & Services
Global UIUX Software Market
Software & Services
Waterway Transportation Software Solutions Market
Software & Services
Lawn Care Software Market
Software & Services
BFSI Software Market
Software & Services
Global Photogrammetry Software Market
Software & Services
Global Cloud-Based Call Center Software Market
Software & Services
Application Platform As a Service Market
Software & Services
Global Decision Support Software Market
Software & Services
Global Decision Making Software Market
Software & Services
Global Corporate Wellness Software Market
Software & Services
North America Digital Marketing Software Market
Software & Services
Fitness App Market
Software & Services
System Infrastructure Software Market
Software & Services
Global Document Control Software Market