
 Storyboarding Software Market | 2026-2036
Storyboarding Software Market Size, Share, and Industry Trends Forecast 2026-2036
Storyboarding Software Market Analytics
The EU Green Deal is recalibrating energy-use standards for data centers hosting cloud-based creative platforms, pushing studios toward lower-carbon SaaS providers. Toon Boom Storyboard Pro leverages decades of specialized animation expertise to anchor the professional 2D segment. FrameForge dominates photorealistic previsualization for live-action productions through proprietary optical simulation engines. Canva extends mass-market accessibility with template-driven storyboarding tools that compete on speed rather than feature depth.
Storyboarding software encompasses digital tools that enable visual sequencing of scenes through frame-by-frame composition, typically supporting timeline-based editing, layered asset manipulation, and real-time camera positioning for film, television, and interactive media production. Cloud-based deployment now leads installation volume among advertising agencies seeking distributed team collaboration, while on-premise installations retain preference at film studios managing unreleased intellectual property under strict security protocols. Independent creators represent the fastest-growing end-user category as subscription pricing democratizes access to professional-grade preview functionality and export options previously restricted to enterprise licenses.
The Federal Communications Commission oversees broadband infrastructure standards that directly affect cloud-based storyboarding latency for remote production teams, while the Copyright Office shapes digital asset management compliance requirements across US-based platforms. The EU's General Data Protection Regulation imposes cross-border data handling constraints on SaaS providers serving European film studios and educational institutions. Stakeholders must monitor evolving AI disclosure mandates from multiple jurisdictions as generative features embed deeper into previsualization workflows.
Market Dynamics
Cloud migration is compressing deployment timelines across production pipelines while the EU AI Act forces compliance redesign for generative previsualization tools embedded in enterprise suites.
Growth Catalysts
- Cloud infrastructure expansion:Advertising agencies in Germany and France are replacing on-premise installations with SaaS platforms to enable real-time collaboration across distributed creative teams.
- GDPR-compliant data architectures:European studios are demanding region-locked cloud instances, pushing vendors to build localized data residency capabilities that accelerate continental adoption.
- Independent creator democratization:Subscription pricing tiers below $50 monthly are unlocking professional-grade storyboarding for freelance animators and small production houses in Spain and Italy.
Market Restraints
- Cross-border data friction:GDPR Article 44 restrictions on international data transfers force US-based SaaS providers to maintain expensive EU infrastructure or risk market exclusion.
- Rendering compute costs:Photorealistic previsualization requires GPU-intensive processing that fluctuates with energy pricing, squeezing margins for mid-tier vendors.
- Legacy talent pools:Traditional hand-drawn storyboard artists in France and Belgium resist digital tool migration, creating workflow bottlenecks at heritage animation studios.
Strategic Opportunities
- AI disclosure mandates:The EU AI Act's transparency requirements for generative content create first-mover advantage for vendors building automated provenance tracking into export pipelines.
- Educational institutional procurement:Film schools in Poland and Czech Republic are upgrading curriculum infrastructure, opening volume licensing contracts for cloud-based collaborative platforms.
- Virtual production convergence:Real-time engine integration with LED volume stages is electrifying demand for live-action previsualization tools that bridge storyboarding and final pixel output.
Industry Challenges
- Generative IP ambiguity:Unclear copyright status of AI-assisted storyboard frames is delaying insurance coverage and contractual indemnification for European co-productions.
- Interoperability fragmentation:Proprietary file formats from dominant vendors block seamless handoffs between previsualization, editing, and asset management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Storyboarding Software Market |
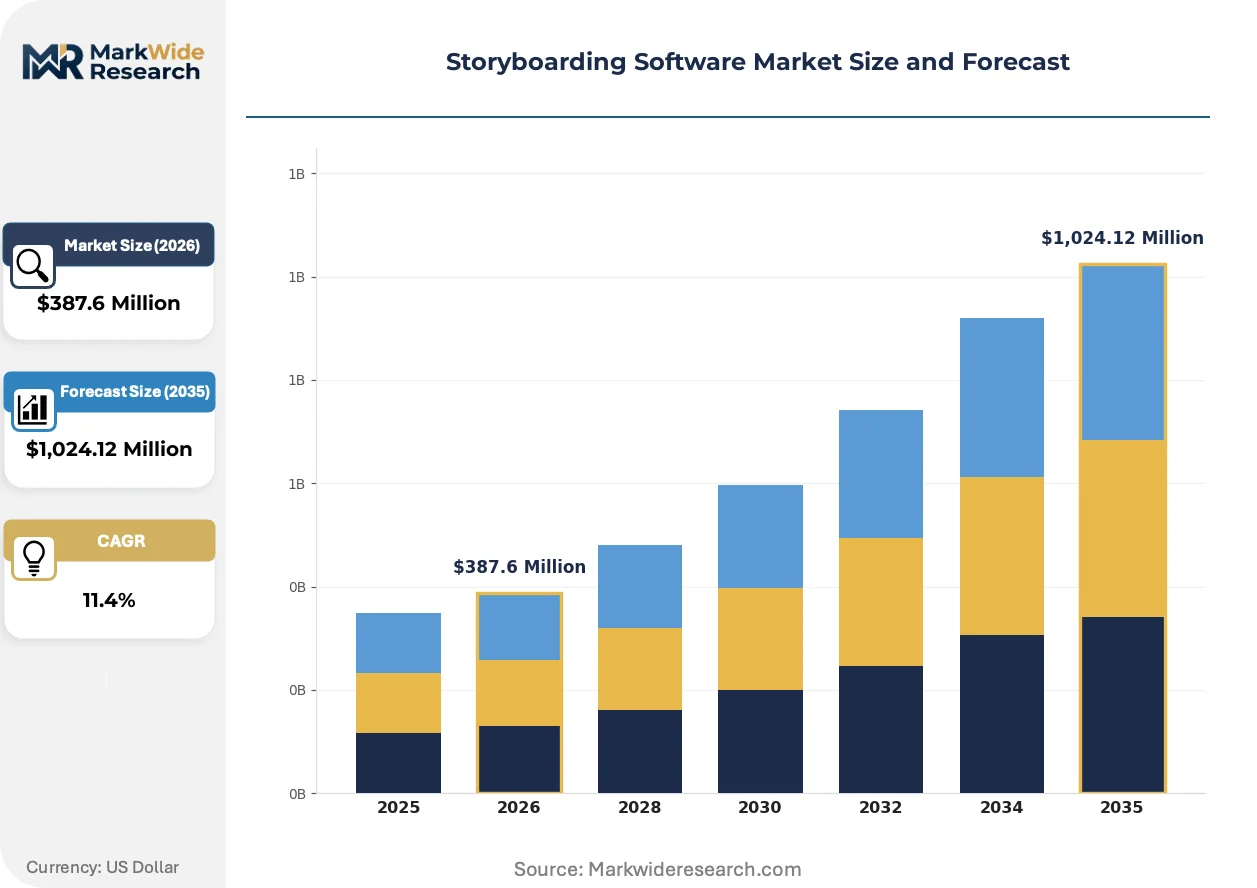
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Software Type: 2D Animation, 3D Animation, Visual Effects, Game Development Deployment Model: On-Premise, Cloud-Based, Hybrid, SaaS End User: Film Studios, Advertising Agencies, Independent Creators, Educational Institutions Feature Set: Collaboration Tools, Asset Management, Preview Functionality, Export Options |
| Companies Covered | FrameForge, Toon Boom Storyboard Pro, Drawstory, Celtx, Canva, LTX Studio, Studiovity, StudioBinder, Boords, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Storyboarding Software Market Evolving Landscape
Real-time rendering engines are collapsing the boundary between previsualization and final output, while regulatory pressure on algorithmic transparency is forcing architectural redesign of automated creative tools.
Neural frame interpolation is electrifying workflow compression for 2D animation pipelines. The technology generates in-between frames from key poses, cutting manual labor hours by half at mid-sized European studios. Independent creators in Portugal and Greece are adopting these tools fastest, enabling solo operators to deliver broadcast-ready sequences previously requiring five-person teams.
The EU AI Act's risk classification system for generative content tools is mandating audit trails and human oversight protocols across automated storyboarding features. Vendors must now embed logging mechanisms that track every algorithmic suggestion and revision. French and German studios are demanding these compliance capabilities as procurement prerequisites, filtering non-compliant platforms from enterprise shortlists.
Educational licensing is displacing traditional perpetual-seat sales in European markets. Film schools in Netherlands and Denmark are negotiating campus-wide subscriptions that bundle training modules with production tools. This shift concentrates vendor relationships at the curriculum level, locking in preference patterns before graduates enter professional ranks and influencing long-term procurement decisions at major studios.
Storyboarding Software Market Segmentation
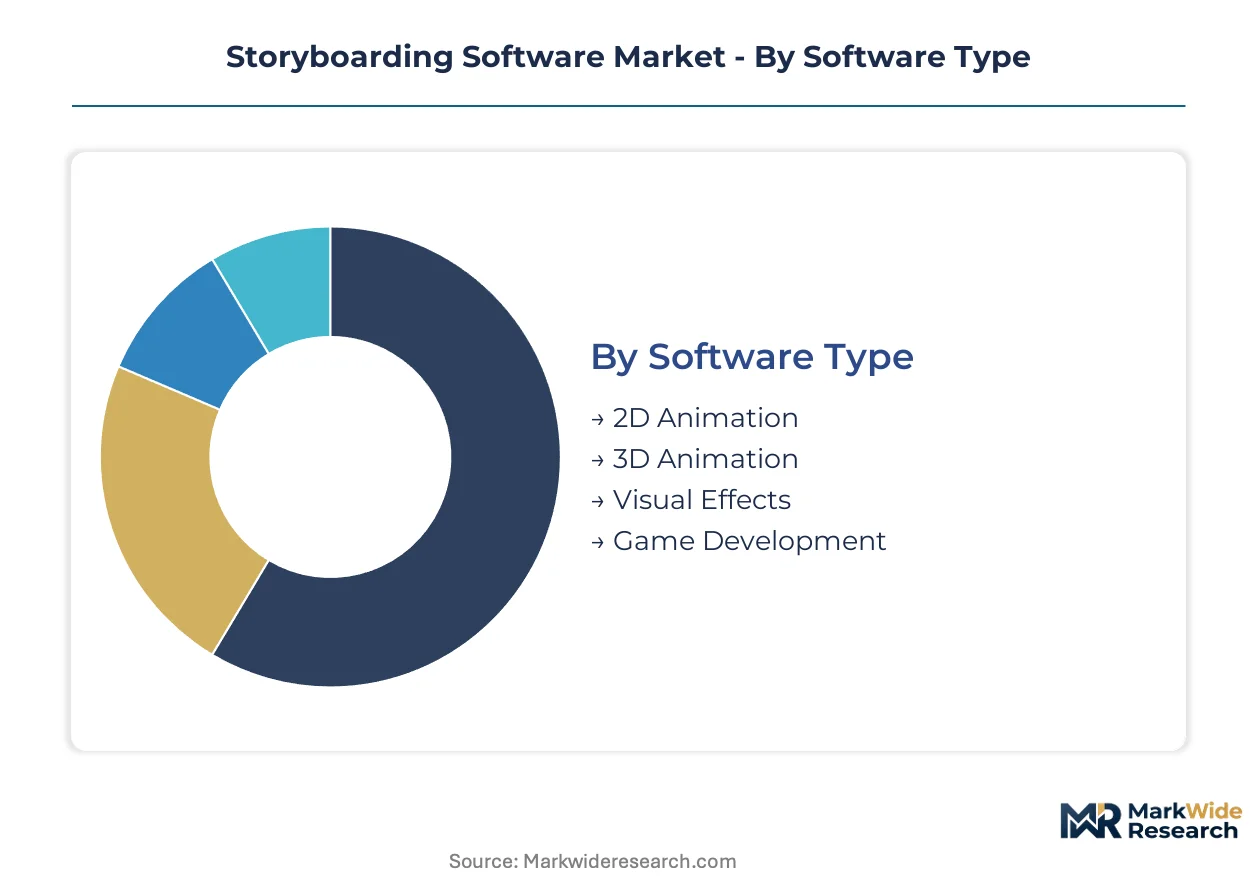
Storyboarding software segments diverge sharply by technical sophistication and buyer budget. Deployment preferences split between security-conscious studios and collaboration-hungry agencies, while feature depth separates enterprise procurement from creator economy subscriptions.
Software Type:
Volume concentrates in established 2D workflows. Premium pricing attaches to photorealistic 3D and integrated visual effects pipelines.
- 2D Animation:Frame-based composition with vector and raster asset support dominates traditional animation pipelines. California's independent creators and heritage European studios in France and Belgium anchor demand, though neural interpolation tools are compressing production timelines by half.
- 3D Animation:Spatial camera positioning and real-time lighting simulation serve previsualization for live-action productions. German advertising agencies and UK virtual production stages are driving adoption as LED volume integration becomes standard.
- Visual Effects:Compositing-heavy workflows bridging practical and digital elements.
- Game Development:Engine-integrated storyboarding with interactive branching narratives.
Mature deployment sits with 2D Animation. Newer deployment is concentrated in 3D Animation.
Deployment Model:
Cloud architectures are displacing on-premise dominance among distributed teams. Security protocols and IP sensitivity preserve hybrid configurations at major studios.
- Cloud-Based:Browser-accessible platforms with real-time synchronization enable geographically dispersed creative teams. Advertising agencies in Germany and France are replacing legacy installations fastest, though GDPR Article 44 compliance costs burden US-based providers.
- SaaS:Subscription-tiered access with automatic updates and API extensibility attracts independent creators in Spain and Italy. Sub-$50 monthly pricing unlocks professional-grade tools previously gated behind enterprise licensing.
- On-Premise:Air-gapped installations with local asset storage satisfy unreleased IP security requirements at major film studios.
- Hybrid:Split configurations keeping sensitive pre-production local while enabling cloud collaboration for non-critical phases.
On-Premise retains preference where IP sensitivity peaks. SaaS is gaining share fastest among price-sensitive entrants.
End User:
Enterprise procurement favors perpetual licenses with customization. Mass-market growth flows through subscription democratization.
- Film Studios:Multi-seat enterprise deployments with strict security auditing and custom pipeline integration. California's major studios and London post-production houses demand on-premise or region-locked cloud instances for unreleased content protection.
- Independent Creators:Solo operators and small production houses in Portugal and Greece leverage subscription tiers for broadcast-ready output. Neural frame interpolation enables single-artist delivery of sequences previously requiring five-person teams.
- Advertising Agencies:Rapid-turnaround campaigns with distributed creative teams.
- Educational Institutions:Campus-wide licensing with curriculum integration at film schools in Netherlands and Denmark.
Film Studios represent the highest contract value segment. Independent Creators are expanding most quickly as pricing barriers collapse.
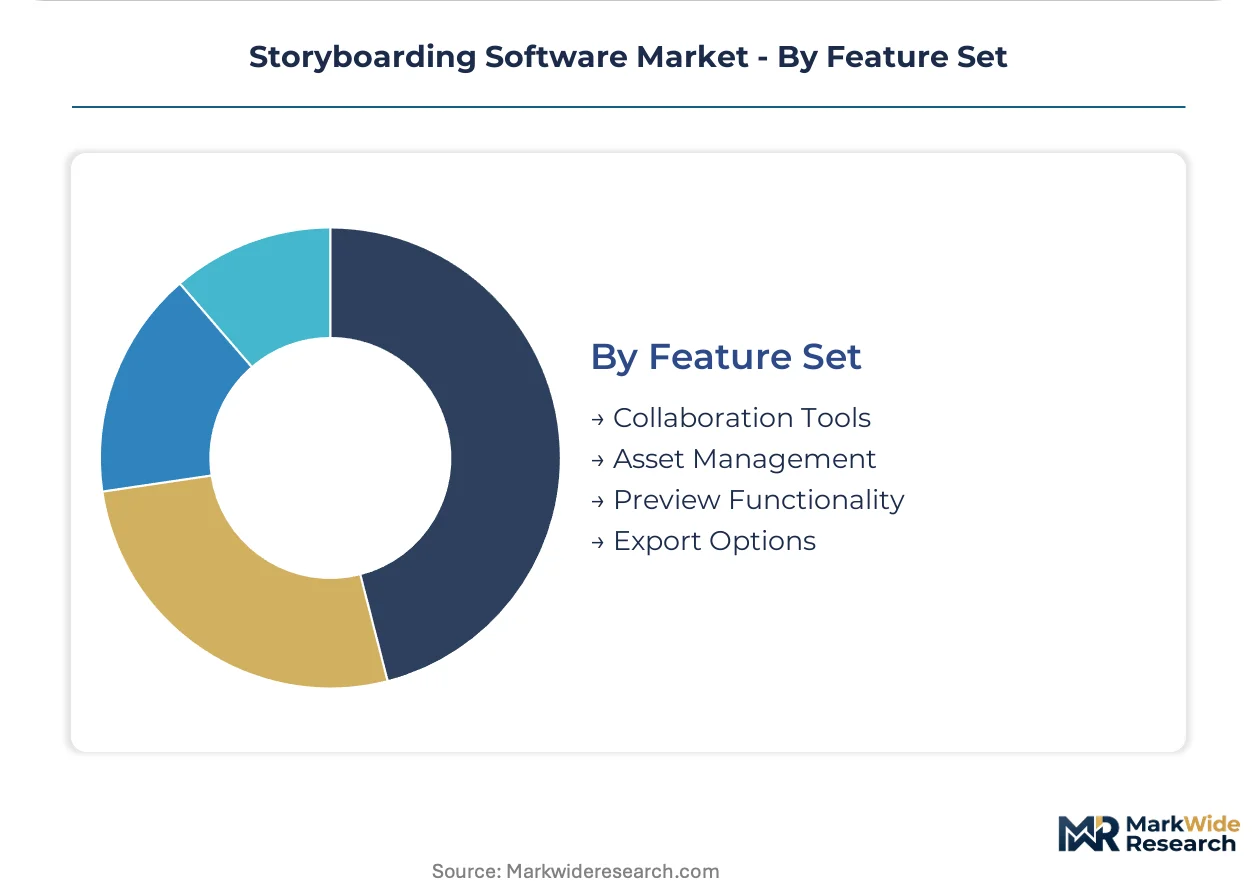
Feature Set:
Core functionality differentiates by collaboration intensity versus asset control priorities.
- Collaboration Tools:Real-time multi-user editing with version control and comment threading. Cloud-native agencies in France and Germany require these as baseline procurement criteria.
- Asset Management:Centralized libraries with metadata tagging and rights tracking. Studios managing extensive IP catalogs prioritize these capabilities for pipeline efficiency.
- Preview Functionality:Real-time playback with timing and audio synchronization.
- Export Options:Multi-format delivery with resolution and codec flexibility.
Asset Management dominates enterprise procurement specifications. Collaboration Tools are climbing fastest as remote production normalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's entertainment technology corridor anchors global storyboarding software demand, with Los Angeles and San Francisco hosting dense concentrations of independent creators, major studios, and vendor headquarters.
United States
Film studios in California and New York Metro drive enterprise procurement of on-premise and hybrid deployments for unreleased IP protection. The Federal Communications Commission oversees broadband infrastructure standards affecting cloud-based latency for remote production teams. Los Angeles hosts the densest concentration of major studios and previsualization vendors, with independent creators clustering in Silver Lake and Burbank.
Germany
Advertising agencies in Berlin and Hamburg are replacing legacy installations with SaaS platforms for distributed creative collaboration. GDPR Article 44 compliance requirements force US-based providers to maintain expensive EU infrastructure or risk market exclusion. Bavaria's media production hubs in Munich anchor photorealistic previsualization demand for live-action advertising.
France
Heritage animation studios in Paris and Annecy anchor 2D animation workflows, though traditional hand-drawn artists resist digital migration creating workflow bottlenecks. The EU AI Act's transparency requirements for generative content mandate audit trails and human oversight protocols. Île-de-France concentrates vendor relationships with film schools negotiating campus-wide curriculum subscriptions.
United Kingdom
Virtual production stages in London and Manchester electrify demand for 3D previsualization tools bridging storyboarding and LED volume output. The Information Commissioner's Office enforces GDPR cross-border data handling constraints on SaaS providers serving British studios. Soho post-production houses demand region-locked cloud instances for unreleased content security.
India
Animation service providers in Bengaluru and Mumbai adopt subscription tiers for broadcast-ready output, with neural frame interpolation enabling smaller teams. The Ministry of Electronics and Information Technology oversees data localization requirements affecting cloud platform architecture. Hyderabad's emerging media technology corridor attracts volume licensing from educational institutions upgrading curriculum infrastructure.
Storyboarding Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across feature depth and security certification dimensions, with specialized 2D animation suites commanding higher per-seat pricing than template-driven mass-market alternatives. The vendor base stratifies into three tiers: established previsualization specialists with decades of animation expertise, cloud-native collaborative platforms targeting advertising workflows, and mass-market template providers competing on accessibility. Dominant competitive moves include API extensibility investments for pipeline integration and educational institutional procurement targeting curriculum-level vendor lock-in.
Within the specialized previsualization tier, FrameForge and Toon Boom Storyboard Pro occupy positions representing photorealistic live-action and professional 2D animation archetypes respectively. Canva sits within the mass-market accessibility tier, exemplifying template-driven speed competition rather than feature depth. LTX Studio represents emerging cloud-native platforms targeting virtual production convergence with real-time engine integration.
| Leading Market Players |
|---|
| FrameForge |
| Toon Boom Storyboard Pro |
| Drawstory |
| Celtx |
| Canva |
| LTX Studio |
| Studiovity |
| StudioBinder |
| Boords |
| Others |
Value Network & Pricing Analysis
Advertising agencies in Germany and France command SaaS subscription tiers below $50 monthly, compressing pricing power for mid-tier vendors while enterprise studios in California and London sustain premium perpetual licensing for air-gapped security.
Pricing Analysis
Value-based pricing anchors on production throughput and team collaboration intensity. Three-tier pricing structure across premium, standard, and economy levels separates FrameForge's photorealistic simulation from Toon Boom's professional 2D suites and Canva's template-driven accessibility. Cost compression in the mid-tier intensifies because GPU-intensive rendering fluctuates with energy pricing. Independent creators in Portugal and Greece exhibit highest price sensitivity, while major film studios in California demonstrate lowest sensitivity due to IP security requirements.
Supply Chain Analysis
GDPR Article 44's data residency mandates are reshaping cloud infrastructure sourcing toward EU-based server deployments. Software development concentrates in the United States, Germany, and Canada, with rendering compute capacity drawing from Taiwan, South Korea, and Ireland. Single-source vulnerability sits with NVIDIA's GPU supply chain for photorealistic previsualization. Distribution runs through direct vendor sales for enterprise studios and self-service digital marketplaces for independent creators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around compliance-capable platforms, with the EU AI Act's transparency mandates forcing weaker vendors without audit-trail architecture toward exit or acquisition.
For Market Incumbents: Acquire specialized neural interpolation engines to compress production timelines for 2D animation clients. Integrate automated provenance logging into export pipelines before the EU AI Act's enforcement window closes, as French and German studios are already filtering non-compliant platforms from procurement shortlists. Deepen backward integration into real-time rendering engines to capture virtual production convergence demand from UK LED volume stages. For New Entrants and Emerging Players: Capture educational institutional procurement in Poland and Czech Republic before curriculum-level vendor lock-in solidifies. Film schools in Netherlands and Denmark are negotiating campus-wide subscriptions that bundle training with production tools, creating preference patterns before graduates enter professional ranks. Lead with GDPR-compliant cloud-native architecture as a go-to-market wedge against legacy US-based providers burdened by Article 44 infrastructure costs. For Investors and Strategic Acquirers: The window for entry favors specialized 2D animation suites with heritage European studio relationships over undifferentiated cloud-collaboration platforms. Long-term viability hinges on pipeline integration depth and regulatory compliance certification rather than feature breadth. Watch for inflection when major California studios begin mandating AI disclosure metadata as standard contractual terms for previsualization deliverables.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Real-time engine connectivity with LED volume stages electrifies demand from UK virtual production facilities. |
| Acquisition of Specialist Firm | Neural frame interpolation capabilities compress timelines for heritage studios in France and Belgium. |
| Strategic Partnership | Film school curriculum bundling in Netherlands and Denmark locks in graduate preference patterns. |
| Product Launch | GDPR-compliant cloud instances with region-locked data residency satisfy German advertising agency procurement. |
| Geographic Expansion | EU infrastructure deployment circumvents Article 44 transfer restrictions for US-based SaaS providers. |
Research Methodology
Independent corroboration across CTOs at advertising agencies, platform engineers at cloud-native vendors, procurement officers at California film studios, and curriculum directors at European film schools underwrites the qualitative findings. Secondary validation draws from SEC filings of publicly traded creative software vendors, hyperscaler capex disclosures for cloud infrastructure buildout, GDPR enforcement actions from European data protection authorities, and EU AI Act implementation guidance documents. Bottom-up segmentation modeling triangulates against top-down market sizing from installed base estimates and subscription pricing benchmarks.
Comparable-period anchoring to pre-pandemic collaboration patterns and post-2020 remote production normalization establishes the forecast baseline across the analysis window. Segmentation dimensions span deployment model, organization size, vertical application, integration complexity with downstream editing systems, and regional regulatory adoption pattern. CAGRs derive from elasticity modeling against creative workforce growth and cloud infrastructure expansion rates, with neural interpolation adoption curves and virtual production stage deployment counts as industry-specific inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement consistency, GPU supply chain disruptions, and generative IP litigation precedents. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Architecture, Engineering, and Construction (AEC) Software Market
Software & Services
Indonesia Big Data Analytics Software Market
Software & Services
Global Process Mining Software Market
Software & Services
Screen and Video Capture Software Market
Software & Services
Vending Software Market
Software & Services
Global Data Integration and Integrity Software Market
Software & Services
Agile Application Life-Cycle Management Market
Software & Services
Supplier Relationship Management Software Market
Software & Services
Server Software Market
Software & Services
Global Sales Enablement Platform Market
Software & Services
Performance Management Software Market
Software & Services
UK Point of Sale Software Market
Software & Services
Sales Performance Management (SPM) Software Market
Software & Services
Email Checker Tools Market
Software & Services
Mining Simulation Software Market
Software & Services
Middle East and Africa Automotive Software Market