
 Dual-Ovenable Trays and Containers Market | 2026-2036
Dual-Ovenable Trays and Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Dual-Ovenable Trays and Containers Market Analysis
Food service aggregators is collapsing the historic dominance of institutional catering buyers in dual-ovenable procurement. Sabert Corporation leverages its thermoforming scale to anchor North American quick-service supply chains. Huhtamaki Oyj competes through fiber-based ovenable platforms that navigate tightening EU disposable packaging rules.
Dual-ovenable trays and containers are rigid or semi-rigid packaging structures engineered from crystallized polyethylene terephthalate, polypropylene, or aluminum laminates to withstand temperatures between minus forty degrees Celsius and plus two hundred twenty degrees Celsius without deformation or chemical leaching. These units serve prepared meal manufacturers, retail delis, and delivery kitchens requiring seamless transition from freezer storage through conventional or microwave oven to consumer presentation. Polypropylene formulations dominate volume production due to lower specific gravity and superior impact resistance at frozen temperatures, though aluminum segments command premium positioning in European retail ready-meal aisles where metallic browning performance differentiates shelf appeal. Prepared Meals as an application category captures the deepest margin pools because contract manufacturers specify custom cavity geometries and lidding compatibility that lock in multi-year supply agreements.
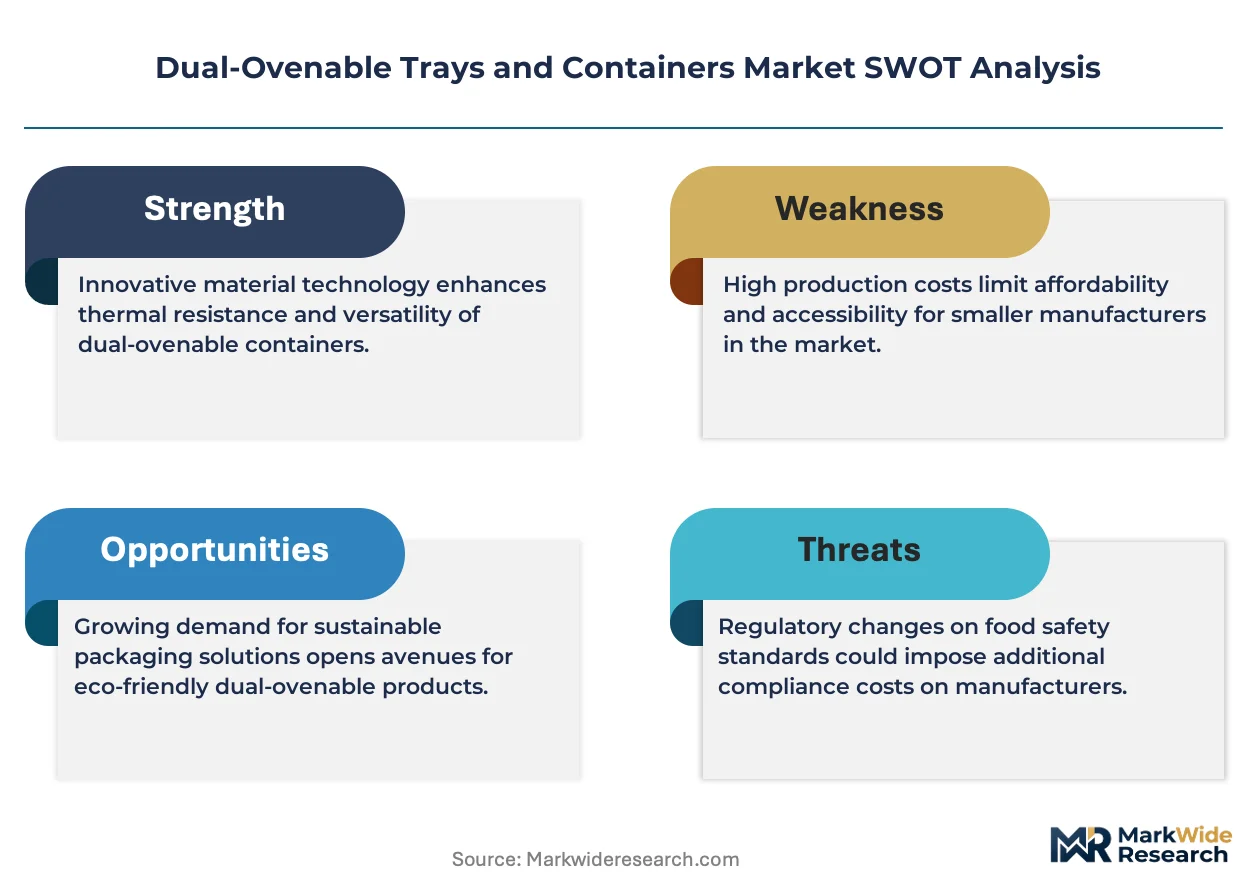
FDA maintains 21 CFR 177.1630 compliance pathways for olefin polymers in ovenable food contact, while EU REACH and F-Gas Regulation constrain fluorinated barrier chemistries that historically enabled high-temperature performance. EFSA migration limit reviews are forcing reformulation timelines across suppliers serving pan-European retail brands. Stakeholders must monitor whether California SB 54 implementation rules will extend beyond single-use plastics to classify certain CPET grades as problematic, reshaping material investment priorities.
Market Dynamics
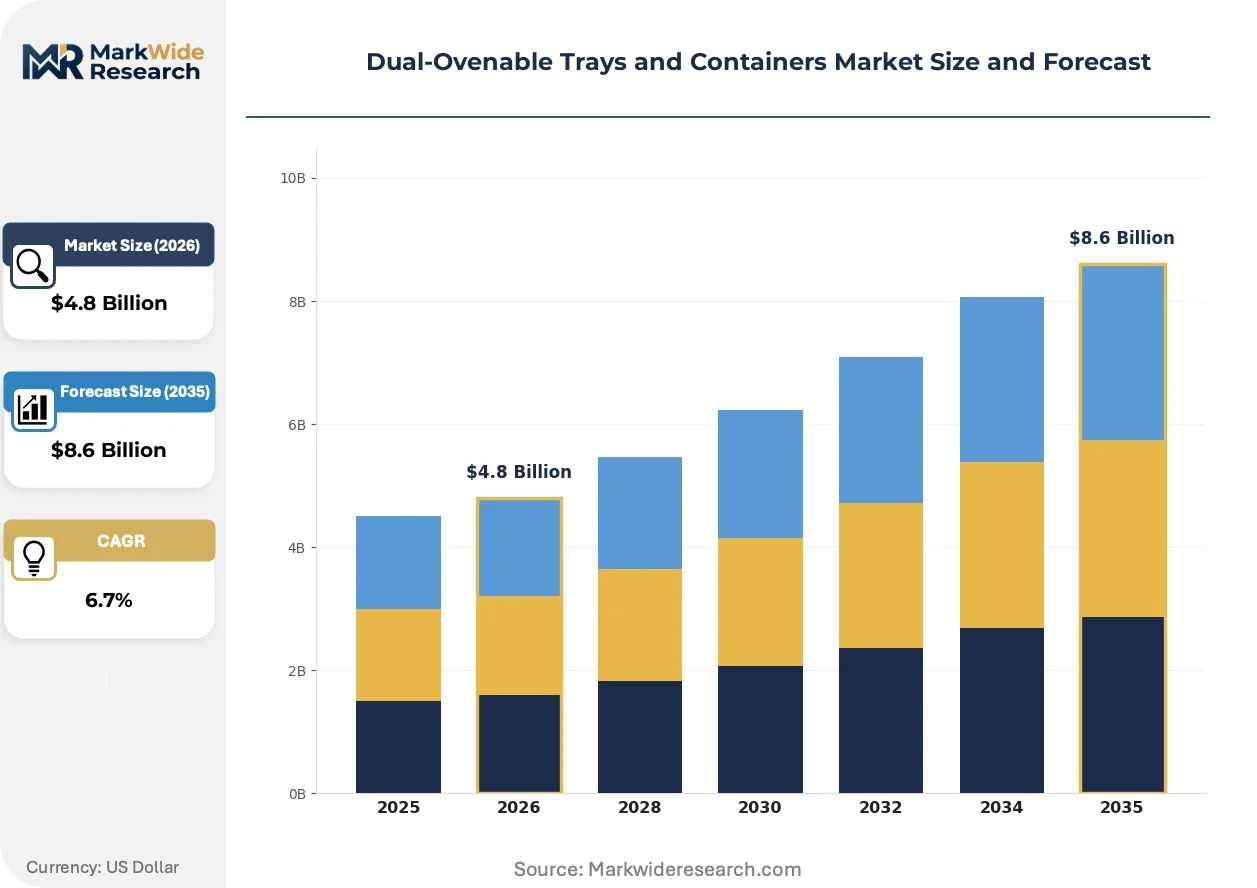
EU Single-Use Plastics Directive amendments are forcing crystallized polyethylene terephthalate reformulation across European supply chains, while quick-service restaurant procurement consolidation is compressing supplier margins in North America.
Growth Catalysts
- Centralized retail chain procurement:German supermarket operators mandate certified ovenable packaging for private-label ready meals, locking in multi-year supply commitments with thermoforming specialists.
- REACH compliance pathways:ECHA authorization processes for alternative barrier chemistries are creating first-mover advantages for suppliers with validated non-fluorinated high-temperature formulations.
- Ghost kitchen infrastructure expansion:Delivery-only food service operators in urban clusters require freezer-to-oven compatibility without repackaging, driving specification of polypropylene tray formats.
Market Restraints
- Petrochemical feedstock volatility:Propylene monomer price swings directly compress margins on polypropylene tray production, forcing hedging costs onto mid-scale thermoformers.
- Aluminum laminate supply concentration:European foil rolling capacity clusters in Germany and Austria, creating single-source risk for premium retail ready-meal applications requiring metallic browning performance.
- FDA 21 CFR 177.1630 testing timelines:Olefin polymer migration studies require eighteen-to-twenty-four month validation cycles, delaying new grade commercialization.
Strategic Opportunities
- Fiber-based ovenable platforms:Molded pulp barrier technologies that withstand two-hundred-degree Celsius temperatures offer compliance pathways under tightening EU disposable packaging rules.
- California SB 54 implementation:Extended producer responsibility frameworks may classify certain CPET grades as problematic, creating demand for certified recyclable alternatives ahead of rule finalization.
- Conventional oven compatibility gaps:Microwave-only tray formats dominate Asian retail ready-meal aisles, leaving white space for dual-ovenable specifications as Western consumption patterns diffuse.
Industry Challenges
- Thermoforming tool engineering capacity:Custom cavity geometry design for contract manufacturers requires specialized CAD-CAM talent pools concentrated in Northern Italy and Southern Germany.
- EFSA migration limit recertification:Updated specific migration limits for oligomers force reformulation of established CPET grades without grandfathering provisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dual-Ovenable Trays and Containers Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polypropylene, Polyethylene, Aluminum, Paperboard End User: Food Service, Retail, Hospitality, Catering Application: Prepared Meals, Frozen Foods, Bakery Products, Takeaway Distribution Channel: Direct Sales, Online Retail, Supermarkets, Convenience Stores |
| Companies Covered | Sealed Air Corporation, Sabert Corporation, Huhtamaki Oyj, Berry Global, Inc., Genpak, LLC, Sonoco Products Company, Pactiv LLC, DuPont Teijin Films, Amcor Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dual-Ovenable Trays and Containers Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry constraints are simultaneously enabling and compressing innovation pathways across ovenable packaging supply chains.
Non-fluorinated barrier coatings are supplanting historical perfluoroalkyl substance chemistries in high-temperature applications. Prepared meal manufacturers in France and the Netherlands are accelerating qualification of silicone-oxide and aluminum-oxide vapor-deposited alternatives. This transition is compressing the addressable market for legacy fluoropolymer suppliers while opening specification windows for coating equipment specialists.
EU F-Gas Regulation phase-down schedules are constraining hydrofluorocarbon blowing agents used in expanded polypropylene tray production. Thermoformers serving Benelux retail chains are retrofitting extrusion lines with carbon dioxide or nitrogen physical foaming systems. Small-to-mid scale producers without capital access face stranded asset risk on existing foam tray capacity.
Direct-to-consumer frozen meal subscription services are fragmenting historic institutional catering procurement concentration. Ghost kitchen operators in London and Paris are specifying smaller cavity counts and modified atmosphere lidding compatibility that diverges from food service aggregator standards. This channel proliferation is forcing tray manufacturers to maintain parallel SKU portfolios with incompatible tooling investments.
Dual-Ovenable Trays and Containers Market Segmentation
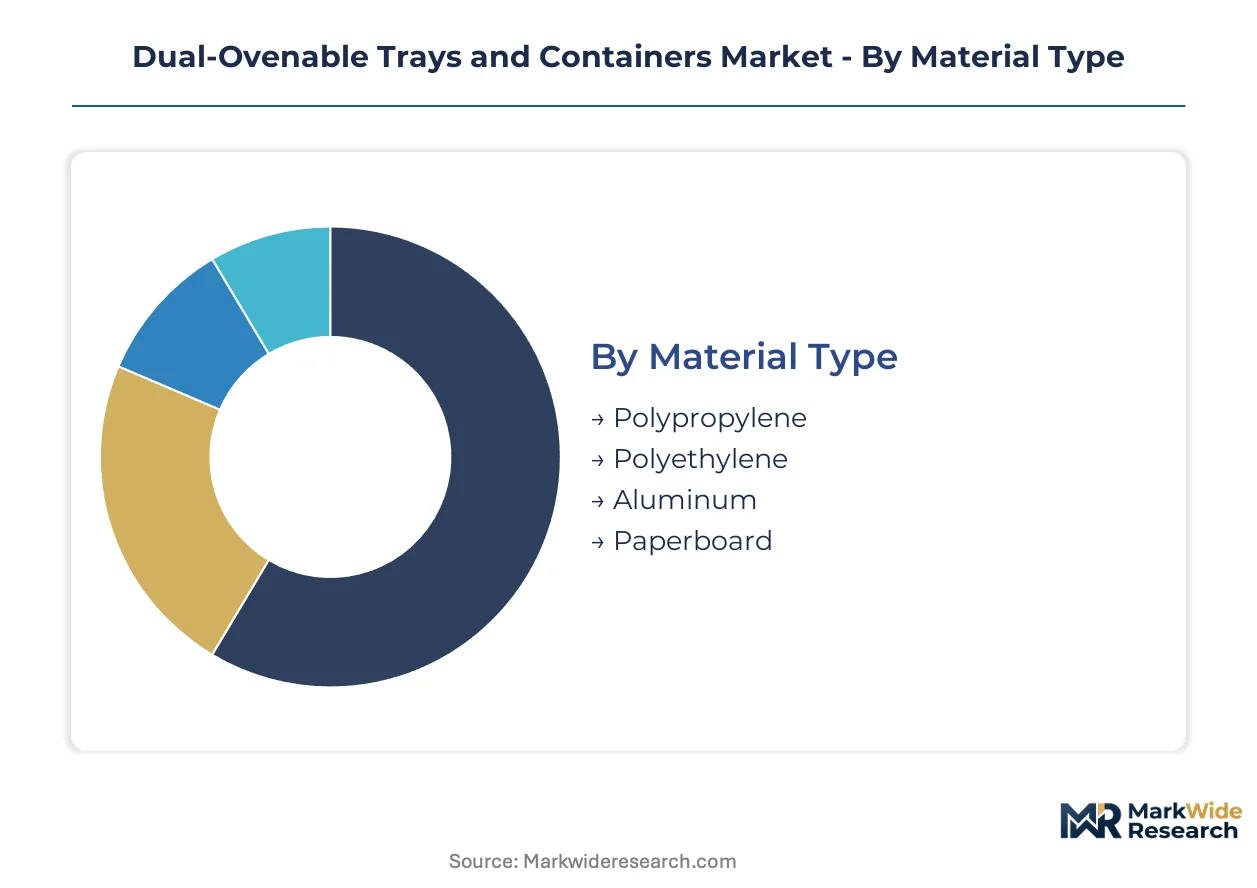
Material chemistry and end-use thermal requirements dictate procurement specifications across dual-ovenable packaging. Segment boundaries are blurring as food service aggregators demand retail-grade aesthetics and retail channels adopt food service scale.
Material Type:
Substitution pressure from fiber-based alternatives and regulatory chemistry bans is fragmenting historic polymer dominance across material categories.
- Polypropylene:Lower specific gravity than competing polymers yields freight cost advantages in frozen supply chains. Quick-service restaurant procurement in the United States and ghost kitchen operators in United Kingdom urban clusters specify this format for impact resistance at minus forty degrees Celsius. EFSA migration limit reviews for oligomers are forcing reformulation without grandfathering provisions.
- Crystallized Polyethylene Terephthalate (CPET):Amorphous-to-crystalline thermal processing enables dimensional stability through two-hundred-twenty-degree Celsius conventional oven exposure. German centralized retail chains mandate certified CPET for private-label ready meals, locking in multi-year thermoforming commitments. California SB 54 implementation rules may classify certain CPET grades as problematic, reshaping investment priorities.
- Aluminum:Metallic thermal conductivity delivers controlled browning performance for premium European retail ready-meal positioning.
- Paperboard:Molded pulp barrier technologies with silicone-oxide coatings navigate tightening EU disposable packaging rules.
Polypropylene retains volume leadership; CPET holds the steepest expansion curve.
End User:
Procurement consolidation patterns diverge sharply between contract-manufactured scale and fragmented direct purchasing.
- Food Service:Ghost kitchen infrastructure expansion in Paris and London requires freezer-to-oven compatibility without repackaging. Delivery-only operators specify smaller cavity counts and modified atmosphere lidding that diverges from aggregator standards.
- Retail:Centralized supermarket procurement in Germany favors certified ovenable solutions under strict packaging ordinances. Private-label ready meal specifications demand custom cavity geometries with multi-year supply agreements.
- Hospitality:Hotel chain breakfast programs and banquet operations prioritize stackability and lid-seal reliability for holding applications.
- Catering:Institutional buyers historically dominated procurement volumes; food service aggregators are collapsing this concentration.
Food Service is capturing specification authority fastest; Retail maintains the deepest margin pools.
Application:
Temperature performance requirements and presentation standards create tiered specification intensity across use cases.
- Prepared Meals:Contract manufacturers specify dual-ovenable trays with custom cavity geometries and lidding compatibility. This application captures the deepest margin pools through multi-year supply agreements with retail and food service channels.
- Frozen Foods:Extended cold chain exposure demands superior impact resistance at frozen temperatures, favoring polypropylene formulations.
- Bakery Products:Conventional oven browning requirements drive aluminum laminate specification in European retail aisles.
- Takeaway:Ghost kitchen and delivery-aggregator compatibility requirements are fragmenting historic SKU standardization.
Prepared Meals commands premium positioning; Takeaway is climbing the fastest on channel proliferation.
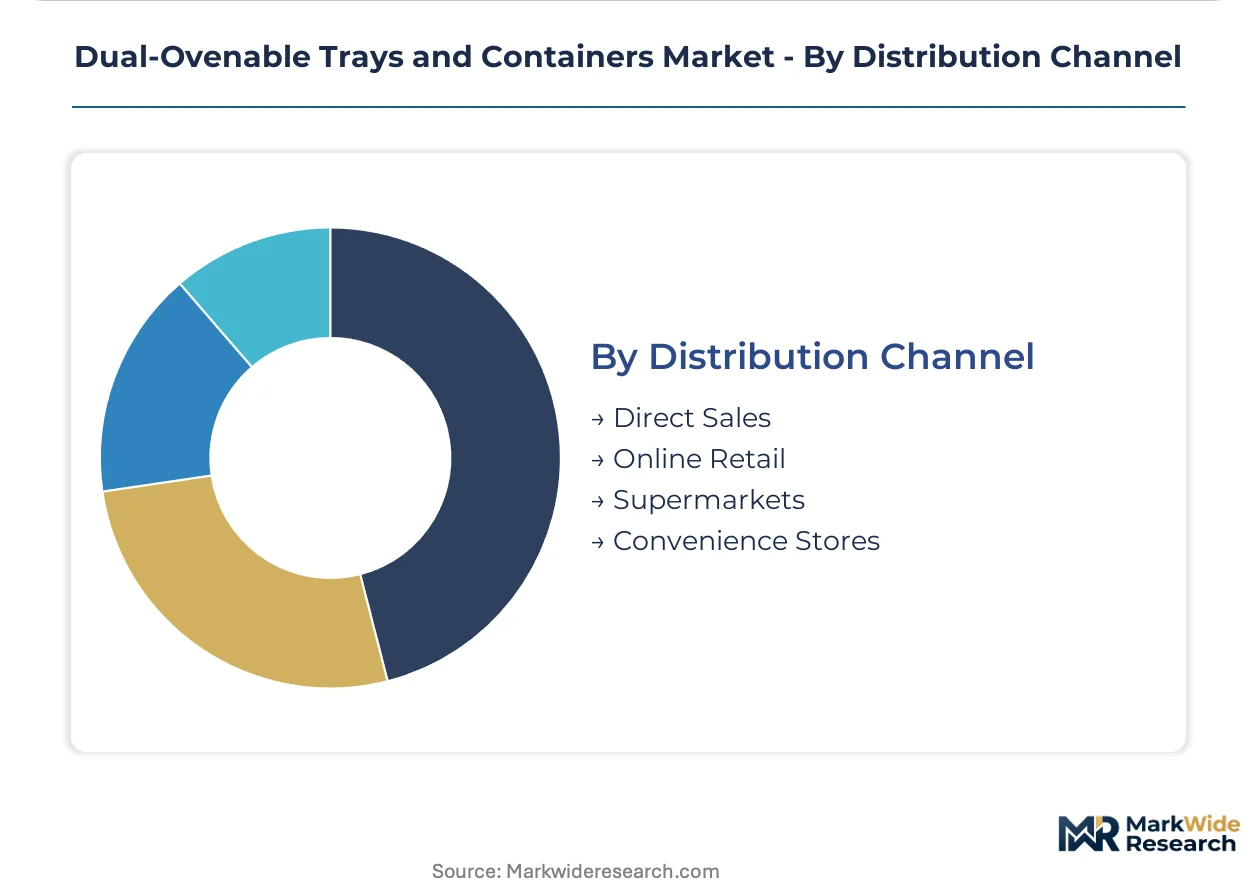
Distribution Channel:
Channel control determines specification authority and margin capture across the value chain.
- Direct Sales:Thermoforming specialists in Northern Italy and Southern Germany maintain direct relationships with contract manufacturers for custom tool engineering. CAD-CAM talent concentration enables proprietary cavity geometry development.
- Online Retail:Direct-to-consumer frozen meal subscription services are fragmenting historic institutional catering procurement concentration.
- Supermarkets:German retail chains mandate certified ovenable packaging for private-label programs, locking in supply commitments.
- Convenience Stores:Smaller format requirements and rapid inventory turns favor standardized tray dimensions over custom specifications.
Direct Sales holds the highest margin capture; Online Retail is expanding most quickly on subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure underwrites Europe's dominance in dual-ovenable distribution, while German rail links to Central European thermoforming clusters enable rapid response to retail procurement cycles.
Germany
Centralized retail chains and strict packaging ordinances favor certified ovenable solutions. The EU Single-Use Plastics Directive amendments force CPET reformulation across thermoforming operations. Northern Italy and Southern Germany host specialized CAD-CAM talent pools for custom cavity geometry development.
United States
Quick-service restaurant procurement consolidation compresses supplier margins while ghost kitchen operators accelerate polypropylene tray adoption. FDA 21 CFR 177.1630 compliance pathways govern olefin polymer migration studies. Chicago and Dallas-Fort Worth logistics hubs concentrate frozen meal distribution networks serving delivery-only operators.
France
Prepared meal manufacturers accelerate qualification of silicone-oxide barrier coatings to replace legacy fluoropolymer chemistries. ECHA authorization processes for alternative barrier formulations create first-mover advantages. The Paris urban cluster drives ghost kitchen infrastructure expansion with freezer-to-oven compatibility requirements.
United Kingdom
Food service aggregators collapse historic institutional catering procurement concentration. London ghost kitchen operators specify smaller cavity counts and modified atmosphere lidding compatibility. Birmingham and Manchester distribution centers fragment SKU standardization across delivery-aggregator channels.
Netherlands
Benelux retail chains mandate retrofitting of extrusion lines with carbon dioxide physical foaming systems under EU F-Gas Regulation phase-down schedules. Rotterdam's port infrastructure enables integrated cold chain handoffs to European ready-meal manufacturers. Eindhoven thermoforming specialists navigate EFSA migration limit recertification for established CPET grades.
Dual-Ovenable Trays and Containers Market Vendor Landscape
Concentration sits with diversified packaging conglomerates and specialized thermoforming operators. The vendor base spans three tiers: integrated multinationals with polymer supply control, regional thermoformers with custom tool engineering capabilities, and niche barrier technology specialists. Strategic archetypes include scale-driven substrate producers, CAD-CAM-enabled custom geometry developers, and coating equipment specialists capturing fluoropolymer transition windows. Dominant competitive moves encompass backward integration into polymer compounding and strategic partnerships with ghost kitchen infrastructure operators.
Among North American fabricators, Sealed Air Corporation and Sabert Corporation occupy positions within the scale-driven tier, with the latter anchoring quick-service supply chain relationships. Huhtamaki Oyj represents the fiber-based platform archetype navigating EU disposable packaging constraints. These three exemplify divergent material strategies—polymer dominance, thermoforming scale, and fiber substitution—each capturing distinct specification authority across retail and food service channels.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Sabert Corporation |
| Huhtamaki Oyj |
| Berry Global, Inc. |
| Genpak, LLC |
| Sonoco Products Company |
| Pactiv LLC |
| DuPont Teijin Films |
| Amcor Plc |
| Others |
Supply Flow & Price Mechanics
FDA 21 CFR 177.1630 compliance pathways gate both supplier qualification and price tiering simultaneously, as eighteen-to-twenty-four month migration study timelines create certification premiums that separate validated olefin polymer grades from untested alternatives. This regulatory threshold concentrates pricing power with thermoformers holding active FDA master files, while buyers without multi-year contract volumes absorb disproportionate qualification costs.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with three-tier pricing separating custom cavity geometries from standardized tray formats across premium, standard, and economy levels. Price differentiation rests on EFSA migration certification status and ghost kitchen contract scale, with certified CPET grades commanding fifteen-to-twenty percent premiums over uncertified polypropylene alternatives. Cost compression in mid-scale thermoforming is intensifying because propylene monomer volatility forces hedging costs onto producers lacking backward integration. Quick-service restaurant procurement teams exhibit highest price sensitivity due to consolidated buying power, while German retail chains prioritize certification reliability over unit economics.
Supply Chain Analysis
Just-in-time inventory strategies prevail among ghost kitchen operators requiring freezer-to-oven compatibility without safety stock, whereas German retail chains maintain strategic stockpiles to buffer thermoforming tool engineering lead times. Geographic supply concentration centers on Germany, Austria, and Northern Italy, where foil rolling capacity and CAD-CAM talent pools cluster. Raw material dependencies draw from propylene monomer feedstocks, aluminum foil laminates, and silicone-oxide barrier coatings. Single-source vulnerability runs through European foil rolling capacity concentrated in German and Austrian mills. Distribution runs through Rotterdam port cold chain handoffs to Benelux retail consolidation points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized thermoforming tool engineering capability sits with concentrated talent pools in Northern Italy and Southern Germany, creating asymmetric access to custom cavity geometry development that determines contract manufacturer lock-in. This scarcity dynamic rewards early positioning in barrier coating qualification and non-fluorinated formulation validation.
For Market Incumbents: Fortify multi-year supply agreements with German centralized retail chains by accelerating EFSA migration limit recertification ahead of oligomer reformulation deadlines. Prioritize backward integration into polymer compounding to offset propylene monomer volatility exposure. Sabert Corporation's quick-service restaurant anchoring demonstrates how channel control defends margin position against food service aggregator procurement consolidation. For New Entrants and Emerging Players: Differentiate on fiber-based ovenable platforms navigating EU Single-Use Plastics Directive compliance windows ahead of CPET reclassification risk. Target California SB 54 implementation preparation as the most penetrable regulatory white space, where certified recyclable alternatives face specification vacuum before rule finalization. Pursue strategic partnerships with ghost kitchen infrastructure operators in London and Paris urban clusters as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across carbon dioxide physical foaming system retrofits mandated by EU F-Gas Regulation phase-down schedules. Long-term viability favors suppliers with validated non-fluorinated barrier chemistries and established ECHA authorization pathways. Acquisition targets should display thermoforming scale with custom tool engineering capabilities in Northern Italy or Southern Germany. Watch EFSA migration limit review publication timelines as the critical signal for reformulation cost inflection across established CPET grade portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Non-Fluorinated Barrier Qualification | Silicone-oxide coating validation captures specification windows as perfluoroalkyl substances face ECHA restriction. |
| Physical Foaming Retrofit | Carbon dioxide extrusion line conversion eliminates hydrofluorocarbon blowing agent exposure under EU F-Gas phase-down. |
| Custom Cavity Geometry Development | CAD-CAM tool engineering in Northern Italy locks contract manufacturers into multi-year prepared meal supply agreements. |
| Ghost Kitchen Channel Partnership | Direct relationships with delivery-only operators in London and Paris fragment historic food service aggregator procurement concentration. |
| Fiber-Based Platform Scale-Up | Molded pulp barrier technologies navigate tightening EU disposable packaging rules ahead of CPET reclassification risk. |
Methodological Framework
Operator-level perspectives from thermoforming plant managers, quick-service restaurant procurement directors, ghost kitchen supply chain leads, and retail private-label packaging specification managers anchored the qualitative base. Secondary validation drew from FDA 21 CFR filings, EFSA migration limit review publications, EU F-Gas Regulation implementation schedules, and German packaging ordinance enforcement records. Bottom-up tray volume estimates triangulated against top-down prepared meal market sizing across material chemistry and end-use thermal requirement dimensions.
Sensitivity analysis tested propylene monomer price volatility scenarios, EFSA recertification timeline delays, and California SB 54 reclassification probability weights across the projection horizon. The analytical framework modeled segmentation dimensions spanning material type, end user procurement pattern, application temperature performance, and distribution channel control. CAGRs derived from installed thermoforming capacity utilization rates, ghost kitchen infrastructure expansion trajectories, and centralized retail chain private-label program commitments. Industry-specific forecast inputs incorporated EU Single-Use Plastics Directive amendment implementation pacing and ECHA authorization queue processing speeds.
The analysis sits within stated boundaries; outcomes outside maintained FDA compliance pathway stability and EU regulatory enforcement consistency would require recalibration. Forecasts reflect assumptions regarding propylene feedstock availability, aluminum foil rolling capacity maintenance, and barrier coating equipment specialist capacity expansion. Revision becomes warranted when EFSA migration limit thresholds or California SB 54 implementation rules cross published proposal-to-finalization thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
2 Piece Cans Market
Containers
Pinch Grip Jars Market
Containers
Stackable Container Market
Containers
Multi-Layer Blow Molded Containers Market
Containers
Rotomolded Containers Market
Containers
Insert Trays Market
Containers
Intermediate Bulk Container Liner Market
Containers
Wooden Barrels Market
Containers
Laminated Bulk Bins Market
Containers
Global Flexitanks Market
Containers
PS Containers Market
Containers
Jars Market
Containers
Modular Container Market
Containers
In-Mold Labelled Containers Market
Containers
APAC Container Technology Market
Containers
Jerry Cans Market