
 Paperboard Tray Market | 2026-2036
Paperboard Tray Market Size, Share, and Industry Trends Forecast 2026-2036
Paperboard Tray Market Insights
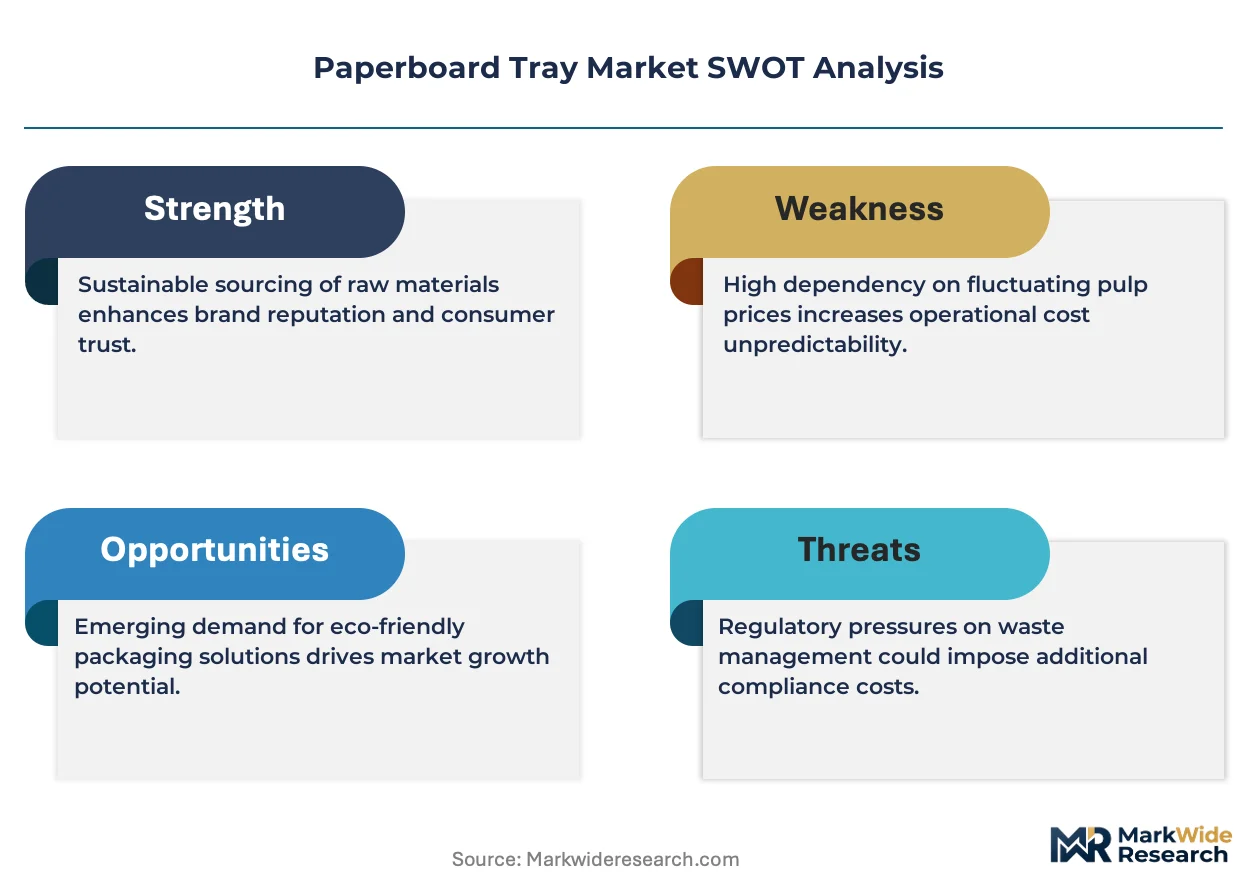
REACH compliance is broadening the cost-of-entry calculus for coated paperboard grades entering European food contact applications. Huhtamaki Oyj leverages its thermoforming technology leadership to sustain premium positioning across frozen food channels. International Paper Company anchors North American supply through integrated pulp-to-converting operations. Mondi plc differentiates via barrier-coated kraft solutions that navigate extended shelf-life requirements without plastic laminates.
Paperboard trays are rigid, foldable containers manufactured from bleached or unbleached wood pulp fibers, typically ranging from 200 to 400 gsm in basis weight, engineered to carry, display, and protect consumer goods through distribution and retail. Their primary commercial purpose centers on replacing expanded polystyrene and plastic thermoformed alternatives in temperature-stable and chilled food logistics. Recycled paperboard and solid bleached sulfate currently occupy the largest volume positions, though coated paperboard captures disproportionate margin pools where grease and moisture barriers command price premiums. Frozen foods packaging and fresh produce packaging represent the fastest-expanding tray application categories, driven by retailer sustainability mandates and e-grocery fulfillment formats.
The EU Green Deal and F-Gas Regulation shape material innovation priorities, while FDA food contact notifications govern US market access for novel barrier coatings. ECHA substance restrictions and evolving PFAS thresholds in the EU are forcing reformulation of conventional oil-resistant treatments. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and secure dual-hemisphere product registrations.
Market Dynamics
EU Packaging and Packaging Waste Regulation enforcement is accelerating material substitution away from plastic thermoforms, compressing conversion timelines for food processors and retail chains across Germany, France, and Italy.
Growth Catalysts
- EU Green Deal packaging mandates:Germany's retail sector faces binding plastic reduction targets that elevate paperboard tray specifications in ready-meal and frozen food categories.
- Barrier-coated kraft innovation:Advances in aqueous and bio-based coatings eliminate plastic laminate requirements for extended shelf-life applications.
- E-grocery fulfillment expansion:Temperature-stable paperboard formats capture share in last-mile delivery configurations for fresh produce and chilled prepared foods.
Market Restraints
- Pulp fiber cost volatility:Bleached softwood pulp prices swing with Nordic supply disruptions and energy input spikes at Scandinavian mills.
- Coating chemistry constraints:ECHA PFAS restrictions force reformulation of conventional oil-resistant treatments, extending R&D cycles.
- Moisture barrier performance gaps:High-humidity cold chain segments retain plastic alternatives where fiber-based barriers fail shelf-life specifications.
Strategic Opportunities
- India foodservice penetration:Quick-service restaurant chains and cloud kitchens adopt paperboard trays under FSSAI packaging guidelines.
- Pharmaceutical secondary packaging:Unit-dose blister support trays convert from PVC to solid bleached sulfate for compliance with EU MDR traceability requirements.
- Digital printing integration:Inline variable-data decoration enables batch-level customization for promotional and regulatory labeling without plate costs.
Industry Challenges
- Thermoforming technician scarcity:Tooling optimization and forming-parameter calibration require specialized skills concentrated at legacy packaging engineering programs.
- Dual-hemisphere registration complexity:FDA food contact notifications and EU REACH dossiers demand parallel compliance documentation for export-oriented converters.
- Legacy equipment retrofit costs:Existing plastic thermoforming lines require capital-intensive modification to handle fiber-based feedstocks at commercial speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paperboard Tray Market |
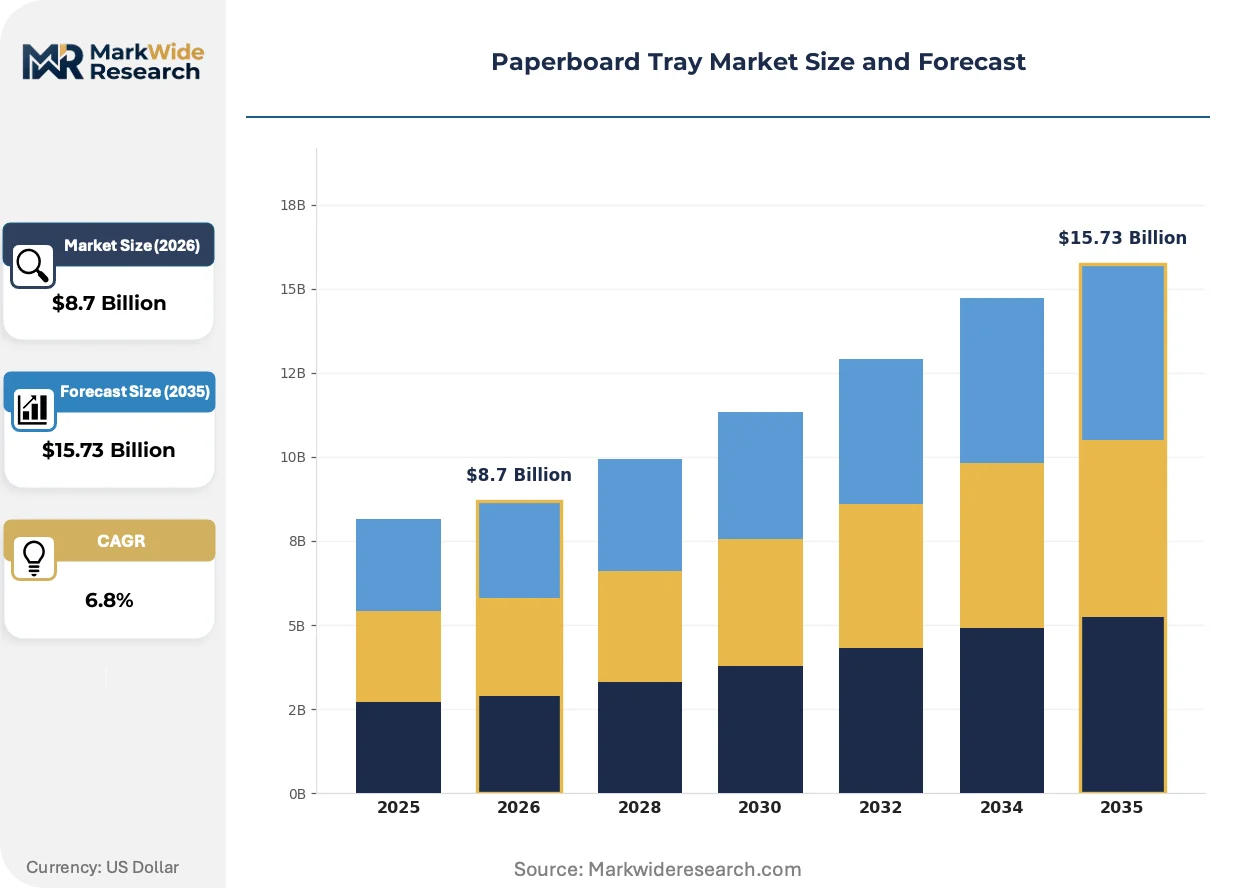
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Virgin Paperboard, Recycled Paperboard, Coated Paperboard, Solid Bleached Sulfate, Solid Unbleached Sulfate Tray Application: Frozen Foods Packaging, Bakery Packaging, Fresh Produce Packaging, Confectionery Packaging, Pharmaceutical Packaging End User Industry: Food Processing Companies, Confectionery Manufacturers, Pharmaceutical Labs, Cosmetic Producers, Household Goods Manufacturers Packaging Type: Clamshell Trays, Compartmentalized Trays, Partitioned Trays, Sleeve Trays, Printed Trays |
| Companies Covered | Huhtamaki Oyj, International Paper Company, Mondi plc, Smurfit WestRock plc, Graphic Packaging Holding Company, DS Smith plc, Stora Enso Oyj, Billerud AB, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paperboard Tray Market Trends and Innovations
Active barrier technologies and regulatory chemistry restrictions are compressing product development cycles while opening premium positioning for compliant material platforms.
Water-based oxygen barrier coatings are rewriting competitive access to modified-atmosphere packaging segments previously reserved for multi-layer plastic structures. Frozen seafood and premium meat processors in the Netherlands and Denmark adopt these platforms at pilot scale. The technology is rewriting margin distribution by collapsing the premium historically attached to ethylene vinyl alcohol laminates.
REACH Article 33 substance disclosure thresholds tightened through ECHA 2023-2024 guidance, forcing inventory audits across coated paperboard supply chains. Converters face documentation burdens for slip agents and optical brighteners in food-contact grades. German retail private-label programs most acutely feel compliance pressure, accelerating supplier consolidation toward integrated pulp-to-converting operations with captive chemistry control.
Direct-store-delivery networks for bakery and deli categories are consolidating procurement around consolidated tray-plus-lid configurations. Regional bakery cooperatives in Spain and Portugal abandon loose tray purchases in favor of pre-assembled, retail-ready formats. This consolidation concentrates volume with converters offering integrated thermoforming and lidding capabilities, compressing spot-market opportunities for standalone tray suppliers.
Paperboard Tray Market Segmentation
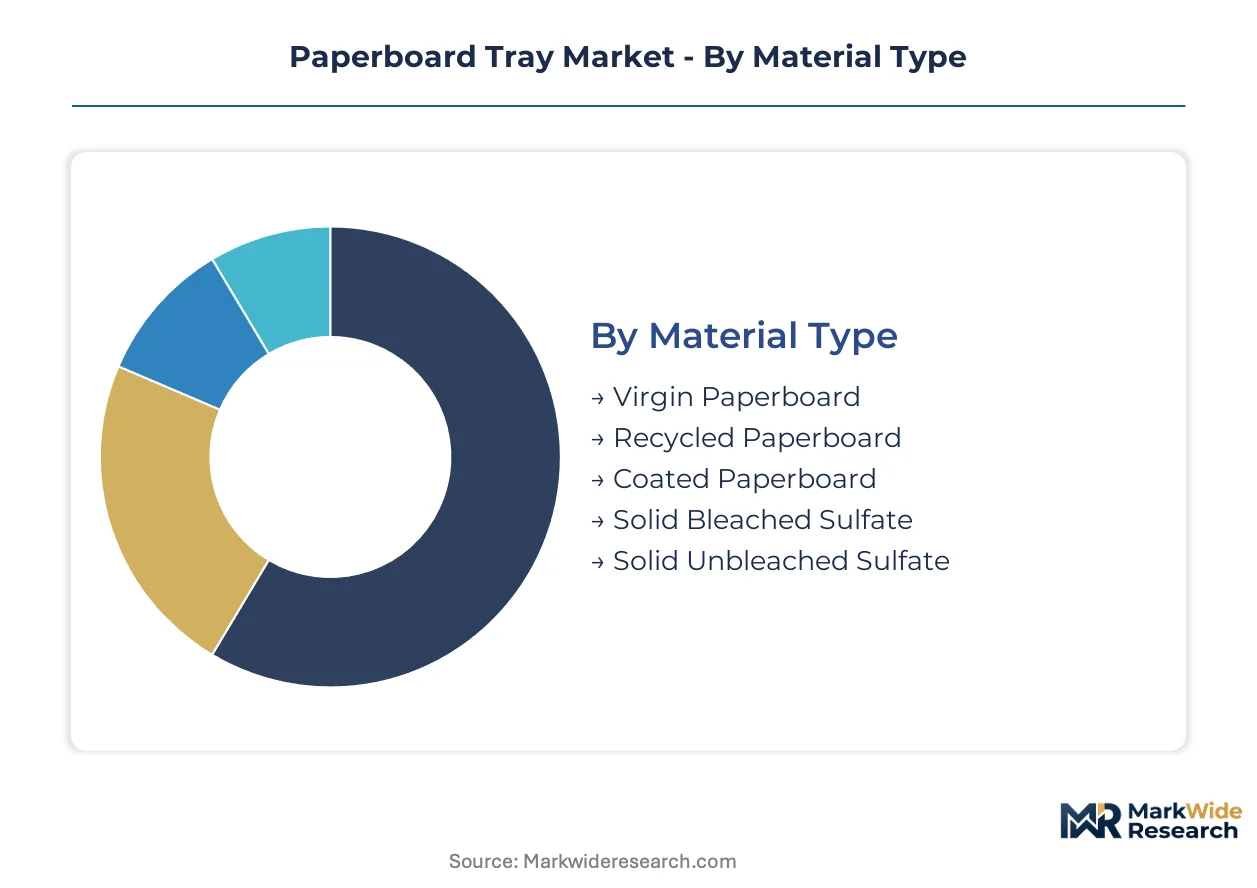
Paperboard tray specifications diverge sharply across temperature exposure, barrier requirements, and retail display formats. Material selection and structural design choices determine compliance eligibility for food contact applications and pharmaceutical traceability mandates.
Material Type:
Thermoforming compatibility and surface chemistry define the specification hierarchy across pulp fiber sources and coating architectures.
- Coated Paperboard:Aqueous and bio-based barrier layers replace plastic laminates for grease and moisture resistance. Frozen food processors in Germany specify these grades to meet retailer plastic-reduction targets under EU Packaging and Packaging Waste Regulation.
- Recycled Paperboard:Post-consumer fiber content ranges from 80% to 100% in standard grades, with de-inked pulp processing limiting food-contact eligibility to secondary packaging or non-fatty applications. Cost positioning drives adoption in bakery and dry goods segments across Spain and Italy.
- Virgin Paperboard:Uncontaminated fiber streams from bleached or unbleached kraft pulping deliver consistent caliper and printability for high-graphic retail applications.
- Solid Bleached Sulfate:Bleached hardwood and softwood kraft fibers provide premium brightness and stiffness for pharmaceutical blister support trays requiring EU MDR traceability compliance.
- Solid Unbleached Sulfate:Natural kraft coloration and superior tear strength suit industrial and agricultural packaging where print aesthetics matter less than structural integrity.
Recycled paperboard leads on scale; coated paperboard leads on momentum.
Tray Application:
End-use thermal regimes and shelf-life specifications dictate barrier investment and structural geometry choices.
- Frozen Foods Packaging:Deep-freeze stability to minus 40 degrees Celsius requires low-moisture-content board and crack-resistant creasing. Dutch and Danish seafood processors pilot water-based oxygen barrier coatings for modified-atmosphere configurations.
- Fresh Produce Packaging:Breathable fiber structures with controlled moisture transmission extend shelf life for berries and leafy greens in e-grocery fulfillment channels.
- Bakery Packaging:Grease-resistant treatments and anti-fog windowing balance product visibility with fat-barrier performance for in-store bakery programs.
- Confectionery Packaging:High-stiffness grades support intricate die-cut windows and premium tactile finishes for seasonal gift assortments.
- Pharmaceutical Packaging:Solid bleached sulfate trays provide dimensional stability for unit-dose blister cards under EU MDR serialization requirements.
Frozen foods packaging commands the steepest expansion trajectory; fresh produce packaging gains share fastest in direct-to-consumer channels.
End User Industry:
Regulatory exposure and procurement scale separate volume buyers from specification-driven niche adopters.
- Food Processing Companies:Ready-meal and frozen food manufacturers drive coated paperboard volume through retailer sustainability mandates in Germany and France. REACH compliance documentation requirements favor suppliers with captive pulp and chemistry control.
- Pharmaceutical Labs:Secondary packaging for clinical trial materials and commercial drug distribution requires batch-level traceability and tamper-evident tray designs under EU MDR.
- Confectionery Manufacturers:Seasonal volume spikes and premium positioning needs favor converters with digital printing integration for promotional versioning.
- Cosmetic Producers:Rigid paperboard trays replace plastic inserts for skincare and fragrance sets, driven by brand sustainability commitments rather than regulatory pressure.
- Household Goods Manufacturers:Durable goods packaging prioritizes cost-minimized recycled grades with basic structural protection.
Food processing companies anchor volume demand; pharmaceutical labs generate the highest specification premiums.
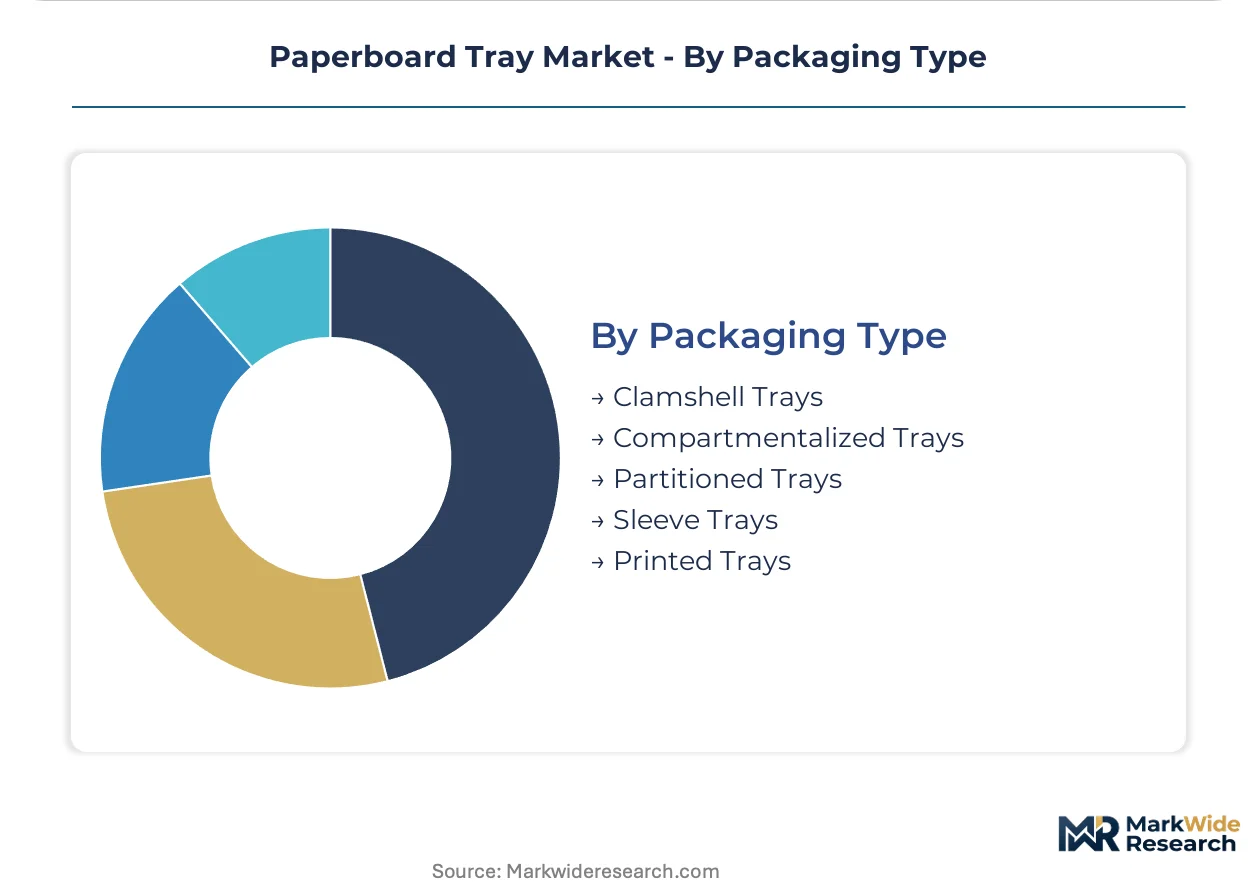
Packaging Type:
Structural complexity and assembly automation compatibility determine tooling investment and line-speed economics.
- Clamshell Trays:Hinged lid-and-base designs eliminate separate lidding components and reduce assembly labor. Spanish and Portuguese bakery cooperatives consolidate procurement around pre-assembled retail-ready formats.
- Compartmentalized Trays:Multi-cavity thermoformed structures separate sauce, starch, and protein components in ready-meal applications. Tooling complexity limits supplier base to converters with advanced forming-parameter calibration.
- Partitioned Trays:Removable or fixed dividers accommodate mixed-SKU retail configurations for deli and prepared food segments.
- Sleeve Trays:Open-top designs with wraparound carton sleeves balance structural protection with material minimization for ambient shelf-stable products.
- Printed Trays:Inline flexographic or digital decoration enables batch-level customization without plate costs, supporting promotional and regulatory labeling requirements.
Clamshell trays dominate unit volume; compartmentalized trays climb fastest as ready-meal processors automate assembly lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pulp mill technicians and thermoforming engineers concentrate in Nordic regions and German industrial clusters, anchoring supply-side capacity for barrier-coated grades.
Germany
Retail chains enforce binding plastic-reduction targets that elevate paperboard tray specifications in ready-meal and frozen food categories. EU Packaging and Packaging Waste Regulation compliance deadlines compress conversion timelines for food processors. The Rhine-Ruhr industrial corridor hosts integrated pulp-to-converting operations with captive chemistry control.
United States
Frozen food processors and e-grocery fulfillment networks drive demand for temperature-stable fiber formats. FDA food contact notifications govern market access for novel barrier coatings. The Pacific Northwest pulp mill cluster supplies bleached softwood fiber to Midwest converting operations.
Netherlands
Seafood and premium meat processors pilot water-based oxygen barrier coatings for modified-atmosphere packaging configurations. ECHA substance disclosure thresholds tighten through 2023-2024 guidance, forcing inventory audits. The Port of Rotterdam logistics hub concentrates cold chain distribution infrastructure.
India
Quick-service restaurant chains and cloud kitchens adopt paperboard trays under FSSAI packaging guidelines. The country's national food safety regulator mandates material compliance for food contact applications. The Mumbai-Pune industrial belt hosts emerging converting capacity for foodservice disposables.
France
Pharmaceutical secondary packaging converts from PVC to solid bleached sulfate for EU MDR traceability requirements. The national pharmaceutical regulator enforces serialization mandates for unit-dose blister support trays. The Lyon-Grenoble pharmaceutical cluster drives specification premiums for compliant grades.
Paperboard Tray Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across coating chemistry and thermoforming capability domains. The vendor base organizes around three strategic archetypes: integrated forest products groups with captive pulp supply, specialized packaging converters with barrier-coating expertise, and diversified materials conglomerates with cross-sector scale. Consolidation pressures favor players with dual-hemisphere compliance documentation and in-house chemistry control. Capacity expansion and strategic partnerships dominate competitive moves as converters retrofit legacy plastic thermoforming lines.
Within the integrated forest products tier, International Paper Company and Stora Enso Oyj exemplify archetypes with upstream pulp control and downstream converting integration. Mondi plc occupies a position among barrier-coated kraft specialists navigating extended shelf-life requirements. These three represent distinct competitive vectors: North American scale, Nordic fiber access, and specialty coating innovation.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| International Paper Company |
| Mondi plc |
| Smurfit WestRock plc |
| Graphic Packaging Holding Company |
| DS Smith plc |
| Stora Enso Oyj |
| Billerud AB |
| Sonoco Products Company |
| Others |
Pricing and Supply Chain Analysis
Thermoforming technician scarcity in the Rhine-Ruhr corridor and Nordic pulp mill regions widens labor-cost differentials between integrated pulp-to-converting operations and standalone converters, compressing margin spreads across premium, standard, and economy pricing tiers for paperboard trays.
Pricing Analysis
Bundled tray-plus-lid configurations versus unbundled component sourcing splits pricing models across the market. Three-tier pricing structure across premium, standard, and economy levels differentiates by barrier coating sophistication and REACH compliance documentation depth. Price differentiation stems from certification grade for EU food contact and volume scale commitments from retail chains. Pricing pressure intensifies in standard grades as recycled fiber input costs swing with Nordic energy spikes. Quick-service restaurant chains in India exhibit highest price sensitivity; pharmaceutical labs in France show least sensitivity due to EU MDR compliance premiums.
Supply Chain Analysis
Reverse-logistics flows for coated paperboard scrap and thermoforming offcuts concentrate in German and Dutch recycling networks, feeding de-inked pulp back into secondary grades. Geographic supply concentrates in Sweden, Finland, and Germany for bleached softwood pulp and barrier-coating chemistry. Raw material dependencies rest on Nordic pulp fiber, aqueous barrier formulations, and optical brighteners for food-contact grades. Single-source vulnerability runs through Scandinavian pulp mill concentration for premium fiber streams. Distribution runs through direct-store-delivery networks for bakery cooperatives and consolidated procurement channels for frozen food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play between EU regulatory compliance costs and Indian foodservice expansion under FSSAI guidelines, where labor and fiber input differentials create margin expansion opportunities for dual-hemisphere operators.
For Market Incumbents: Cement barrier-coating chemistry control through captive pulp supply or backward integration into aqueous formulation production. Defend against emerging pure-play coating specialists by locking long-term offtake agreements with German retail private-label programs. Capacity addition in the Mumbai-Pune industrial belt captures Indian quick-service restaurant growth while EU facilities focus on REACH-compliant premium grades. For New Entrants and Emerging Players: Launch via digital printing-integrated converting services targeting seasonal confectionery versioning and promotional batch customization. White-space targets include pharmaceutical secondary packaging for EU MDR compliance and cloud kitchen disposables under FSSAI guidelines. The most penetrable segment is Indian foodservice trays, where brand recognition gaps favor agile local production. For Investors and Strategic Acquirers: Integrated forest products groups with Nordic fiber access are the most active acquirer in this space, consolidating barrier-coating specialists to secure chemistry control. Long-term viability hinges on dual-hemisphere registration capabilities spanning FDA notifications and REACH dossiers. Watch for ECHA PFAS threshold tightening as the inflection signal for coating reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barrier Chemistry | Captive aqueous coating production secures margin pools as ECHA restrictions force supplier consolidation. |
| Digital Printing Infrastructure Deployment | Inline variable-data decoration captures confectionery versioning demand without plate-change delays. |
| Dual-Hemisphere Compliance Registration | Parallel FDA and REACH documentation unlocks export-oriented converter acquisition premiums. |
| Tray-Plus-Lid Configuration Integration | Pre-assembled retail-ready formats consolidate Spanish and Portuguese bakery cooperative procurement. |
| Indian Foodservice Capacity Buildout | FSSAI-compliant production in the Mumbai-Pune belt captures quick-service restaurant chain expansion. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with thermoforming engineers, coating chemistry R&D directors, retail packaging procurement managers, and food processing supply chain planners with secondary validation. Sources included EU Packaging and Packaging Waste Regulation enforcement documentation, ECHA substance restriction guidance, FSSAI packaging compliance circulars, Nordic pulp mill production disclosures, and customs trade data for coated paperboard grades. Bottom-up segment sizing and top-down market triangulation cross-validated volume estimates across material type, tray application, and end-user industry dimensions.
Segment-weighting approaches distributed value and volume across coated versus recycled versus virgin paperboard grades, frozen foods versus fresh produce versus pharmaceutical applications, and food processing versus pharmaceutical lab versus cosmetic producer end users. CAGRs derived from trend extrapolation of pulp fiber cost trajectories, regulatory compliance timeline compression, and e-grocery fulfillment format adoption curves. Forecast inputs incorporated barrier coating technology diffusion rates and thermoforming line retrofit investment cycles across European and North American converter bases.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA PFAS threshold acceleration or Nordic pulp supply disruption scenarios. Projections reflect documented assumptions on regulatory enforcement timelines and coating chemistry substitution rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paper Honeycomb Market
Paper & Paperboard Packaging
Asia-Pacific Paper Cone Market
Paper & Paperboard Packaging
Envelope Market
Paper & Paperboard Packaging
Middle East Corrugated Packaging Market
Paper & Paperboard Packaging
Paper IBC Container Market
Paper & Paperboard Packaging
Paperboard Clamshell Boxes Market
Paper & Paperboard Packaging
China Corrugated Packaging Market
Paper & Paperboard Packaging
Composite Cardboard Tube Packaging Market
Paper & Paperboard Packaging
Corrugated Boxes Market
Paper & Paperboard Packaging
Paper Packaging Market
Paper & Paperboard Packaging
Mailer Box Market
Paper & Paperboard Packaging
Paper Tubes Market
Paper & Paperboard Packaging
India Paper Packaging Market
Paper & Paperboard Packaging
North America Paper Bags Market
Paper & Paperboard Packaging
Compostable Paper Tray Market
Paper & Paperboard Packaging
White Sack Kraft Paper Market