
 Aircraft Wheels Market | 2026-2036
Aircraft Wheels Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Wheels Market Analysis
Commercial aviation's rebound from pandemic lows is decoupling from military aviation's sustained modernization cycle, creating divergent demand profiles across the installed base. Safran Landing Systems leverages its integrated brake and wheel architecture to anchor European narrowbody programs, while Honeywell International Inc. sustains aftermarket dominance through its global MRO channel network. Collins Aerospace differentiates via advanced thermal barrier coatings that extend wheel life on high-cycle regional routes.
Aircraft wheels are forged or cast structural assemblies, typically machined from 7000-series aluminum alloys or magnesium forgings, designed to support static and dynamic loads during taxi, takeoff, and landing operations while integrating with carbon or steel brake stacks. Main wheels and brake assemblies command the largest share of OEM and aftermarket revenue, as these components bear the highest kinetic energy dissipation requirements and most frequent overhaul intervals. Composite material wheels represent the fastest-growing segment, driven by weight reduction targets on next-generation single-aisle platforms where every kilogram translates to fuel savings over aircraft life.
FAA airworthiness directives and EASA certification specifications govern fatigue life limits, thermal overload thresholds, and non-destructive testing protocols for all civil aircraft wheels entering service or overhaul. Military operators face additional MIL-STD requirements for corrosion resistance and battle damage tolerance that extend qualification timelines but lock in supplier relationships. Stakeholders must monitor how emerging sustainable aviation fuel mandates and associated combustion temperature profiles reshape thermal management specifications in wheel and brake system designs.
Market Dynamics
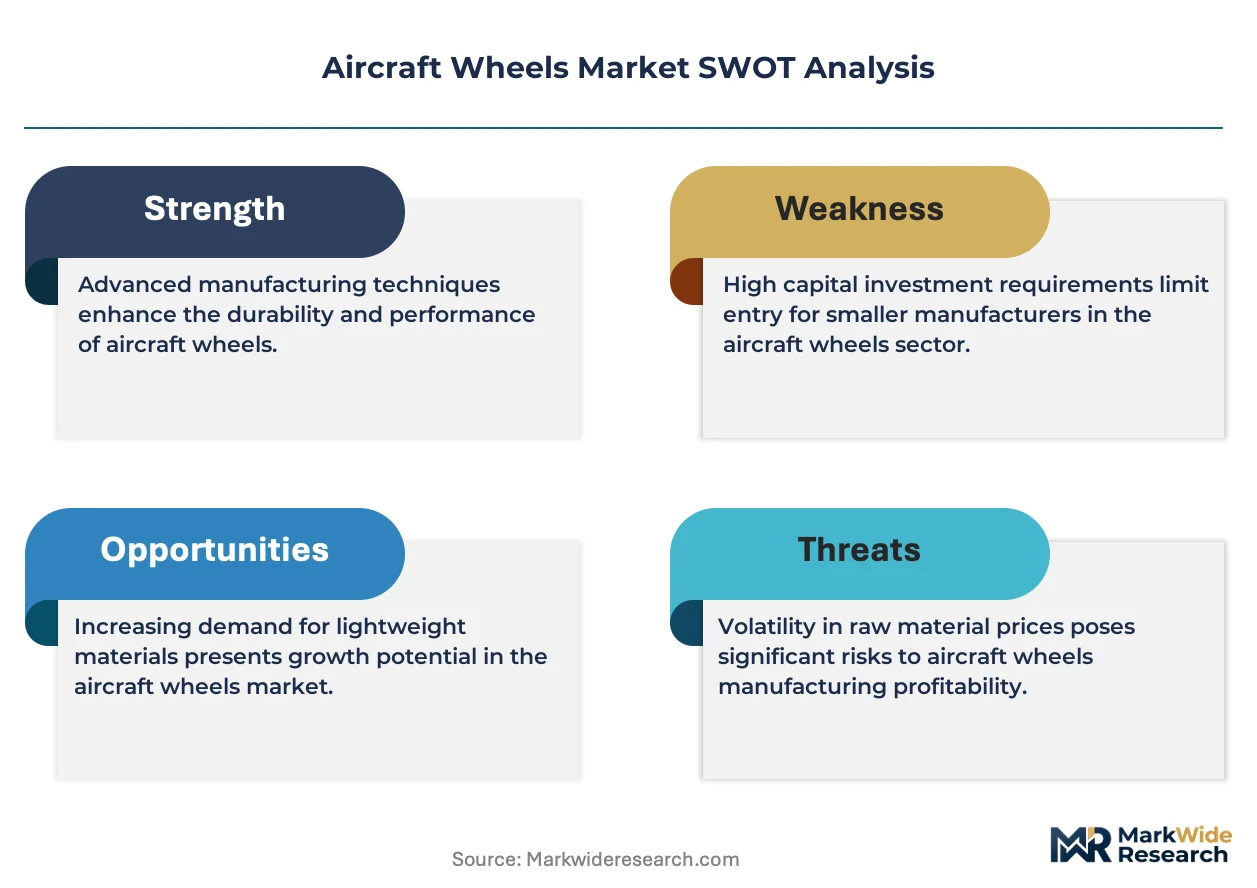
FAA and EASA airworthiness directives on thermal management and fatigue life are compressing qualification timelines for forged aluminum and titanium alloy wheel designs, forcing suppliers to accelerate testing protocols while maintaining structural integrity standards.
Growth Catalysts
- NATO Defense Budget Expansion:Military aviation procurement across member states is creating sustained demand for battle-damage-tolerant wheel assemblies with corrosion-resistant specifications under MIL-STD requirements.
- Regional MRO Hub Retrofit Activity:United States-based maintenance facilities are driving replacement wheel assembly volumes through narrowbody fleet modernization programs and brake system upgrade cycles.
- Carbon Brake Stack Integration:Next-generation thermal management architectures are extending wheel life on high-cycle routes, reducing overhaul frequency and total cost of ownership for operators.
Market Restraints
- Aluminum Alloy Price Volatility:7000-series aluminum and magnesium forging input costs fluctuate with energy-intensive smelting operations, squeezing margin structures for wheel manufacturers.
- Supplier Concentration in Forging Capacity:Limited qualified aerospace forging facilities in Germany and Japan create bottleneck risks for OEM qualification of new wheel designs.
- Thermal Barrier Coating Durability Limits:Current ceramic coating technologies degrade prematurely under sustained aviation fuel combustion temperatures, requiring premature wheel retirement.
Strategic Opportunities
- India Commercial Aviation Expansion:IndiGo and Air India fleet growth creates demand for narrowbody wheel assemblies with localized MRO support infrastructure.
- Sustainable Aviation Fuel Compatibility:Higher combustion temperature profiles from SAF blends necessitate redesigned thermal management specifications, opening retrofit markets for upgraded wheel architectures.
- Additive Manufacturing Convergence:Topology-optimized titanium wheel geometries combined with in-situ monitoring sensors enable predictive maintenance models for cargo operators.
Industry Challenges
- Non-Destructive Testing Technician Shortage:Eddy current and ultrasonic inspection expertise for fatigue crack detection remains scarce across FAA-certified repair stations.
- Dual Certification Timeline Compression:Simultaneous FAA and EASA qualification pathways for new composite wheel designs extend development cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Wheels Market |
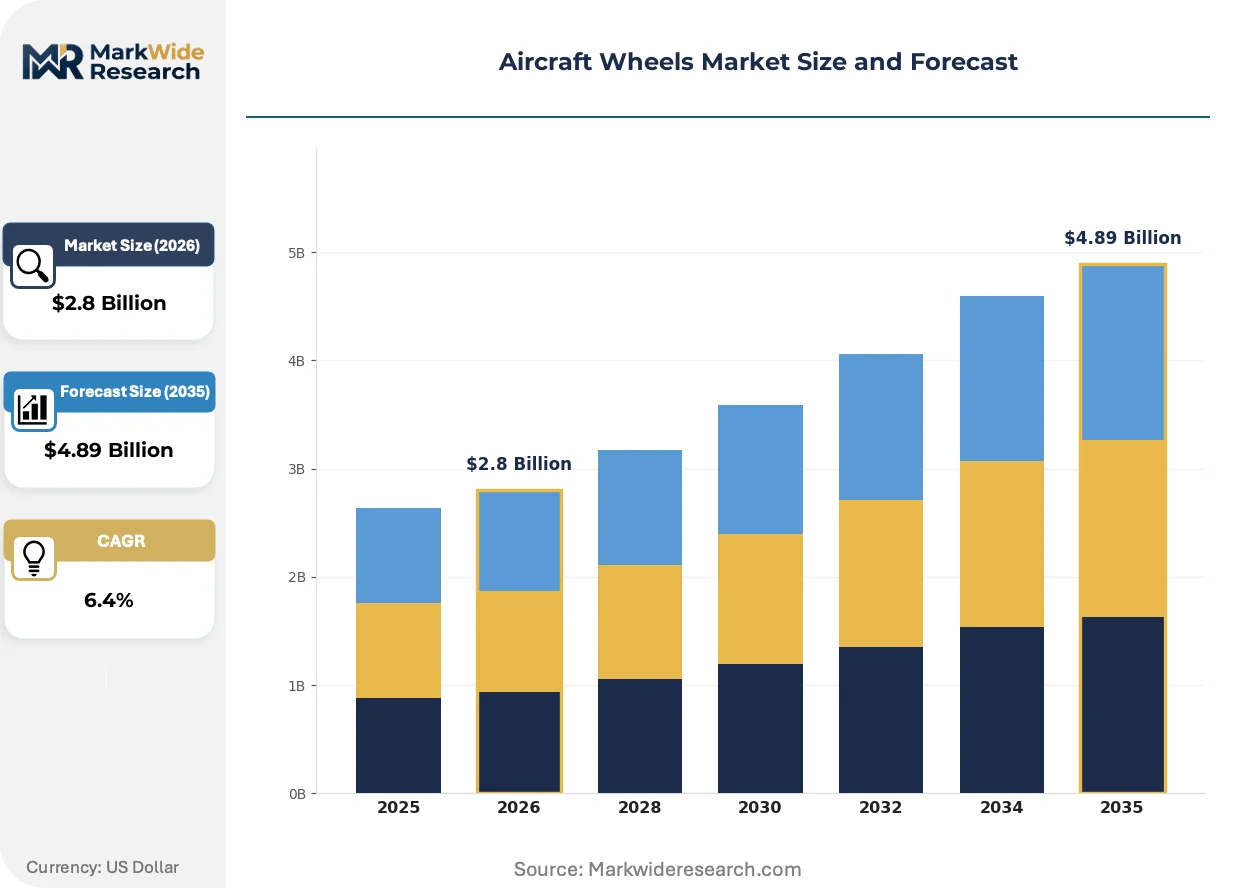
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Main Wheels, Nose Wheels, Brake Assemblies, Tire Assemblies Material: Aluminum, Steel, Composite Materials, Magnesium End User: Commercial Aviation, Military Aviation, Private Jets, Cargo Transport Application: Landing Gear, Taxiing, Takeoff, Landing |
| Companies Covered | Honeywell International Inc., Safran Landing Systems, Collins Aerospace, Parker Hannifin Corporation, Crane Aerospace & Electronics, Beringer Aero, Meggitt PLC, Raytheon Technologies Corporation, NMG Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Wheels Market Emerging Trajectories
Wheel architectures are fragmenting into modular subsystems that separate structural, thermal, and sensing functions, enabling incremental upgrades without full assembly replacement and compressing aftermarket service intervals.
Composite material wheels incorporating carbon fiber-reinforced polymer rims with titanium bearing housings are modularizing maintenance protocols for next-generation single-aisle platforms. Low-cost carriers in Southeast Asia are specifying these architectures for their high-utilization fleets. The technology is modularizing supplier relationships by allowing airlines to source brake, wheel, and sensor modules from competing vendors rather than locked integrated systems.
EASA certification specification updates on thermal overload thresholds are mandating real-time temperature monitoring integration for all new wheel designs entering European-registered fleets. Manufacturers must now embed fiber-optic sensors during the forging process. Narrowbody operators serving Mediterranean hubs face the most acute compliance pressure, accelerating their replacement schedules ahead of regulatory deadlines.
Airline procurement departments are unbundling wheel and brake system contracts that were historically sole-sourced from integrated landing system suppliers. Maintenance cost transparency tools are enabling competitive bidding for overhaul services. North American regional carriers pioneered this shift, with their model now spreading to European hybrid operators seeking to decouple initial equipment purchase from lifetime service agreements.
Aircraft Wheels Market Segmentation
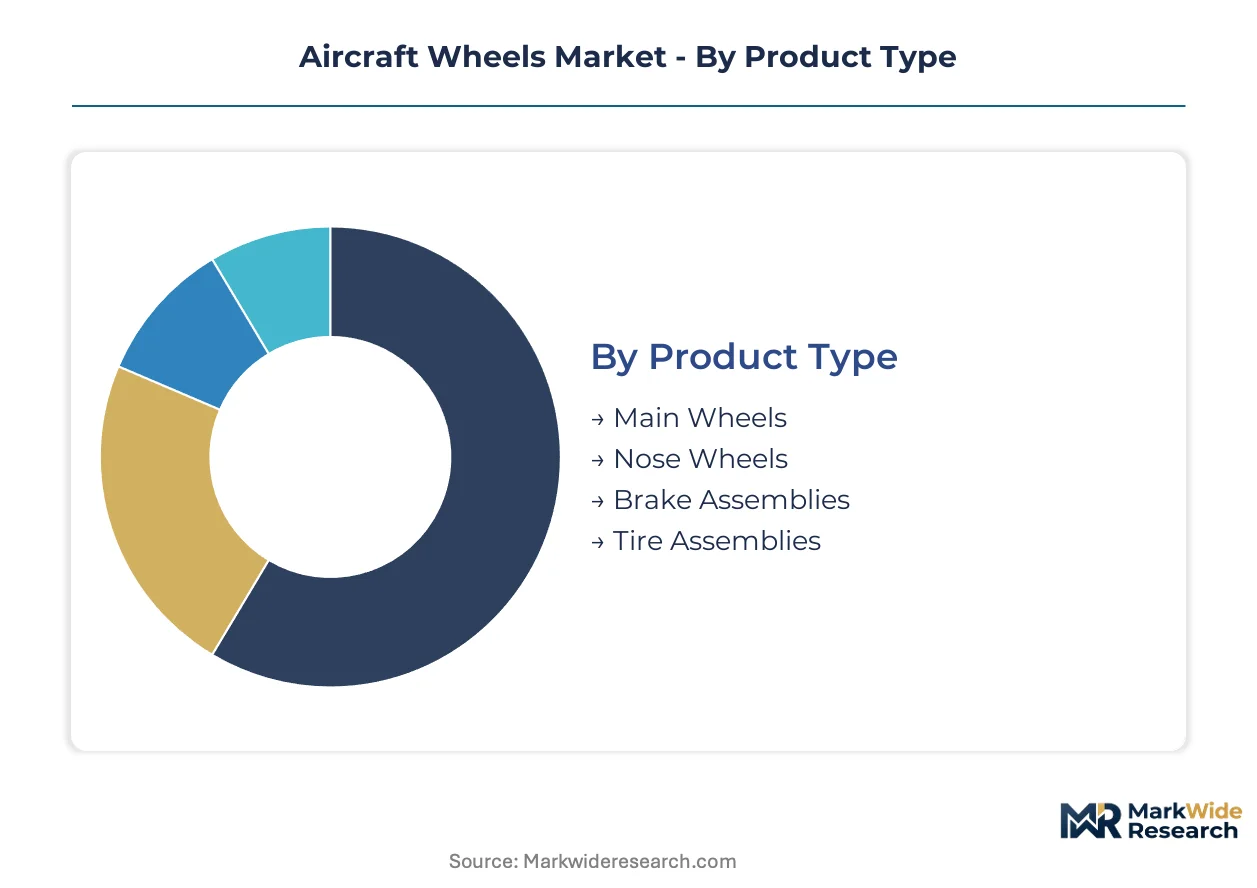
Aircraft wheels segment across multiple technical and operational dimensions that determine procurement patterns, certification pathways, and aftermarket service economics. Each segmentation layer reveals distinct margin structures and supplier concentration dynamics that shape competitive positioning.
Product Type:
Capital intensity varies sharply across wheel assemblies, with integrated brake-wheel systems demanding the heaviest upfront tooling investment for thermal qualification.
- Main Wheels:Forged aluminum or titanium structures supporting maximum static aircraft weight during ground operations. Boeing and Airbus narrowbody backlogs in the United States concentrate demand for high-cycle main wheel configurations rated for carbon brake integration.
- Brake Assemblies:Kinetic energy dissipation systems comprising carbon or steel brake stacks mated to wheel hubs. Regional MRO hubs drive replacement volumes as operators upgrade from steel to carbon configurations for weight reduction.
- Nose Wheels:Smaller-diameter steering assemblies with lower thermal loading requirements. These units command simpler forging specifications but higher steering mechanism integration costs.
- Tire Assemblies:Inflatable tire and tube combinations mounted to wheel rims. Fleet operators in high-utilization routes specify these for frequent replacement cycles separate from wheel overhaul intervals.
Main wheels absorb the bulk of installed capacity; brake assemblies are expanding most quickly.
Material:
Raw material selection governs forging facility qualification timelines and thermal performance ceilings across operational profiles.
- Aluminum:7000-series forged alloys delivering strength-to-weight ratios for narrowbody and widebody platforms. EASA thermal overload specifications are compressing qualification windows for new aluminum wheel designs entering European-registered fleets.
- Composite Materials:Carbon fiber-reinforced polymer rims with titanium bearing housings enabling modular maintenance protocols. Southeast Asian low-cost carriers specify these architectures for high-utilization operations seeking fuel burn reductions.
- Magnesium:Lightweight forged options for regional aircraft where weight savings outweigh corrosion sensitivity concerns. These forgings require specialized handling protocols at limited qualified facilities.
- Steel:Legacy material retained for select military applications requiring battle-damage tolerance under MIL-STD specifications. Procurement concentrates in NATO defense modernization programs.
Aluminum dominates current installed base; composite materials are climbing the fastest.
End User:
Customer type determines certification pathway complexity and contract structure preferences across procurement organizations.
- Commercial Aviation:Scheduled passenger carriers operating narrowbody and widebody fleets under FAA and EASA part 121 regulations. United States-based operators are unbundling wheel-brake contracts historically sole-sourced from integrated suppliers.
- Military Aviation:Defense operators requiring corrosion-resistant, battle-damage-tolerant assemblies under MIL-STD qualification. NATO member state budget expansions are sustaining demand independent of commercial replacement cycles.
- Cargo Transport:Dedicated freighter operators prioritizing predictive maintenance and total cost of ownership metrics. Additive manufacturing convergence with embedded sensors is opening retrofit opportunities for this segment.
- Private Jets:Business aviation operators with lower utilization rates and extended overhaul intervals. Procurement concentrates through OEM completion centers rather than independent MRO channels.
Commercial aviation commands the largest procurement volumes; military aviation is gaining share fastest.
Application:
Operational phase dictates load spectrum severity and thermal management requirements that differentiate wheel design specifications.
- Landing:Maximum kinetic energy dissipation events requiring robust thermal barrier coatings and fatigue-rated structures. Mediterranean hub operators face acute EASA compliance pressure for real-time temperature monitoring integration.
- Takeoff:High-speed rotation under full aircraft weight with centrifugal loading considerations. Wheel designs for this phase emphasize bearing durability and seal integrity against foreign object debris.
- Taxiing:Sustained low-speed operation with steering-induced side loads and thermal cycling. Nose wheel assemblies bear disproportionate stress during extended ground delays.
- Landing Gear:System-level integration encompassing structural, hydraulic, and electronic interfaces. This application scope extends beyond wheels to complete retraction and extension mechanisms.
Landing applications absorb the greatest engineering resources; takeoff configurations are seeing the steepest specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special aerospace economic zones in the United States concentrate forging capacity and MRO infrastructure, while Germany and Japan host qualified facilities serving European and Asian OEM qualification pathways respectively.
United States
Boeing narrowbody backlogs and regional MRO hub retrofit programs drive replacement wheel assembly volumes. FAA airworthiness directives on thermal management compress qualification timelines for forged aluminum designs. Wichita, Kansas and Seattle-Tacoma aerospace clusters concentrate brake system upgrade cycles and carbon brake integration work.
Germany
Limited qualified aerospace forging facilities create bottleneck risks for OEM qualification of new wheel designs. EASA certification specifications on thermal overload thresholds mandate real-time temperature monitoring integration. Munich and Hamburg industrial zones anchor supplier relationships for corrosion-resistant military specifications under NATO procurement.
Japan
Specialized magnesium forging handling protocols concentrate at limited qualified facilities serving regional aircraft programs. METI industrial standards govern fatigue life testing protocols for 7000-series aluminum wheel architectures. Nagoya aerospace manufacturing corridor hosts precision machining operations for bearing housing integration.
India
IndiGo and Air India fleet expansion creates demand for narrowbody wheel assemblies with localized MRO support infrastructure. BIS certification alignment with FAA and EASA standards streamlines import substitution pathways. Bangalore and Hyderabad aviation clusters develop predictive maintenance capabilities for cargo operator retrofit programs.
United Kingdom
Defense budget expansion sustains demand for battle-damage-tolerant wheel assemblies independent of commercial replacement cycles. Military aviation procurement under MIL-STD specifications locks in supplier relationships with extended qualification timelines. Bristol and Derby aerospace zones concentrate brake-wheel system integration for NATO member state programs.
Aircraft Wheels Market Vendor Landscape
Top-tier vendors anchor integrated landing system supply, while mid-tier specialists occupy modular component niches. The vendor base stratifies between full-system integrators and forging specialists serving qualification-constrained supply chains. Three archetypes dominate: aerospace conglomerates with brake-wheel integration capabilities, precision forging houses with thermal management expertise, and sensor-embedded composite specialists. Competitive moves concentrate on strategic partnerships for SAF-compatible thermal architectures and geographic expansion into India MRO infrastructure.
Within the integrated systems tier, Honeywell International Inc. and Safran Landing Systems occupy positions exemplifying aftermarket channel dominance and European narrowbody program anchoring respectively. Collins Aerospace represents the thermal barrier coating specialization archetype, while Parker Hannifin Corporation and Meggitt PLC sit within the precision component fabrication segment serving dual-use military-commercial qualification pathways.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Safran Landing Systems |
| Collins Aerospace |
| Parker Hannifin Corporation |
| Crane Aerospace & Electronics |
| Beringer Aero |
| Meggitt PLC |
| Raytheon Technologies Corporation |
| NMG Aerospace |
| Others |
Supply Flow & Price Mechanics
Sustainable aviation fuel mandates in the European Union and United States gate both qualified forging supply and premium-tier pricing access for thermal-management-compliant wheel architectures. Operators seeking SAF-compatible brake-wheel systems face compressed qualification timelines and elevated certification costs that concentrate pricing power among dual-certified suppliers.
Pricing Analysis
Lead-time-driven pricing stratifies across premium, standard, and economy tiers, with expedited FAA-EASA dual certification commanding substantial premiums over spot inventory from single-qualified sources. Price differentiation rests on thermal barrier coating durability and embedded sensor integration, with full-system integrators capturing margin premiums over modular component vendors. Cost compression in aluminum-forged standard tiers is intensifying because of energy-intensive smelting volatility, while cargo operators show least price sensitivity due to total-cost-of-ownership procurement models.
Supply Chain Analysis
India's domestic-content mandates under the PLI scheme and BIS certification alignment are reshaping sourcing patterns for narrowbody wheel assemblies serving IndiGo and Air India fleet expansion. Manufacturing gravity centers on Germany, Japan, and the United States, with 7000-series aluminum and titanium bearing housings drawing from specialized aerospace forging facilities. Single-source vulnerability concentrates in limited qualified magnesium handling protocols, while distribution runs through OEM integrated channels and independent MRO hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft wheels sector sits in a materials-transition phase, with composite-reinforced polymer rims displacing legacy forged aluminum on next-generation single-aisle platforms.
For Market Incumbents: Hedge against additive manufacturing disintermediation by securing captive forging capacity in India and Germany, while accelerating SAF-compatible thermal architecture R&D to defend certification timelines against emerging composite specialists. For New Entrants and Emerging Players: EASA real-time temperature monitoring mandates in Europe open a window for sensor-embedded wheel module specialists to capture retrofit demand from Mediterranean narrowbody operators ahead of regulatory deadlines, with localized MRO partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: NATO defense budget expansion announcements are the leading indicator that military-qualified forging assets will command scarcity premiums over the coming decade, with vertically integrated brake-wheel specialists in the United Kingdom and Germany representing priority acquisition profiles.| Strategic Initiative | Industry Significance |
|---|---|
| SAF-Compatible Thermal Architecture Development | EASA and FAA mandates on combustion temperature profiles necessitate redesigned wheel specifications for European-registered fleets. |
| India MRO Infrastructure Partnership | Bangalore and Hyderabad aviation clusters require localized brake-wheel overhaul capabilities to serve IndiGo and Air India expansion. |
| Additive Manufacturing Capability Buildout | Topology-optimized titanium geometries with embedded sensors enable predictive maintenance models for cargo operator retrofit programs. |
| Dual Certification Timeline Compression | Simultaneous FAA and EASA qualification pathways for composite designs extend development cycles, favoring incumbent resources. |
| Carbon Brake Stack Integration Investment | Next-generation thermal management architectures extend wheel life on high-cycle routes, reducing overhaul frequency for operators. |
Methodological Framework
Independent corroboration across FAA airworthiness directive filings, EASA certification specification updates, and NATO procurement announcements underwrites the qualitative findings. Primary interviews with landing system procurement officers at scheduled carriers, brake-wheel engineering directors at Tier 1 suppliers, and MRO operations managers at regional hubs combined with secondary validation from customs trade data, SEC aerospace segment disclosures, and METI industrial standards documentation. Bottom-up fleet installation base analysis and top-down defense budget appropriation tracking triangulate volume estimates.
Rate-of-change decomposition across the projection horizon isolates military modernization cycles, commercial replacement waves, and SAF regulatory phase-ins as distinct momentum contributors. Segmentation dimensions modeled include material architecture, end-user procurement type, and thermal management specification tier, with CAGRs derived from installed base turnover rates and qualification pipeline visibility. Forecast inputs incorporate Boeing and Airbus narrowbody delivery schedules and regional MRO hub capacity expansion plans.
Caveats apply where aluminum alloy price volatility, forging facility bottleneck events, or thermal barrier coating durability failures could materially shift the outlook. Forecasts reflect assumptions on regulatory timeline adherence and supplier qualification success rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Wind Tunnel Market
Aircraft
Southeast Asia Business Jet Market
Aircraft
Drone Turbojet Engine Market
Aircraft
Europe Aircraft Engines Market
Aircraft
Asia-Pacific Aircraft Manufacturing Market
Aircraft
Aircraft Mounts Market
Aircraft
Fiber-Optic Strain Sensing Systems for Composite Wing Structures Market
Aircraft
Aircraft Container & Pallet Loader Market
Aircraft
Middle-East and Africa Freighter Aircraft Market
Aircraft
Asia-Pacific Business Jet Market
Aircraft
Light Electric Aircraft Market
Aircraft
India Aviation Market
Aircraft
Commercial Aircraft Wing Market
Aircraft
Global Aircraft Heat Exchanger Market
Aircraft
Asia-Pacific Aircraft Windshield Wiper and Washer System Market
Aircraft
Onboard Oxygen Generating System (OBOGS) Market