
 Commercial Aircraft Wing Market | 2026-2036
Commercial Aircraft Wing Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Wing Market Analysis
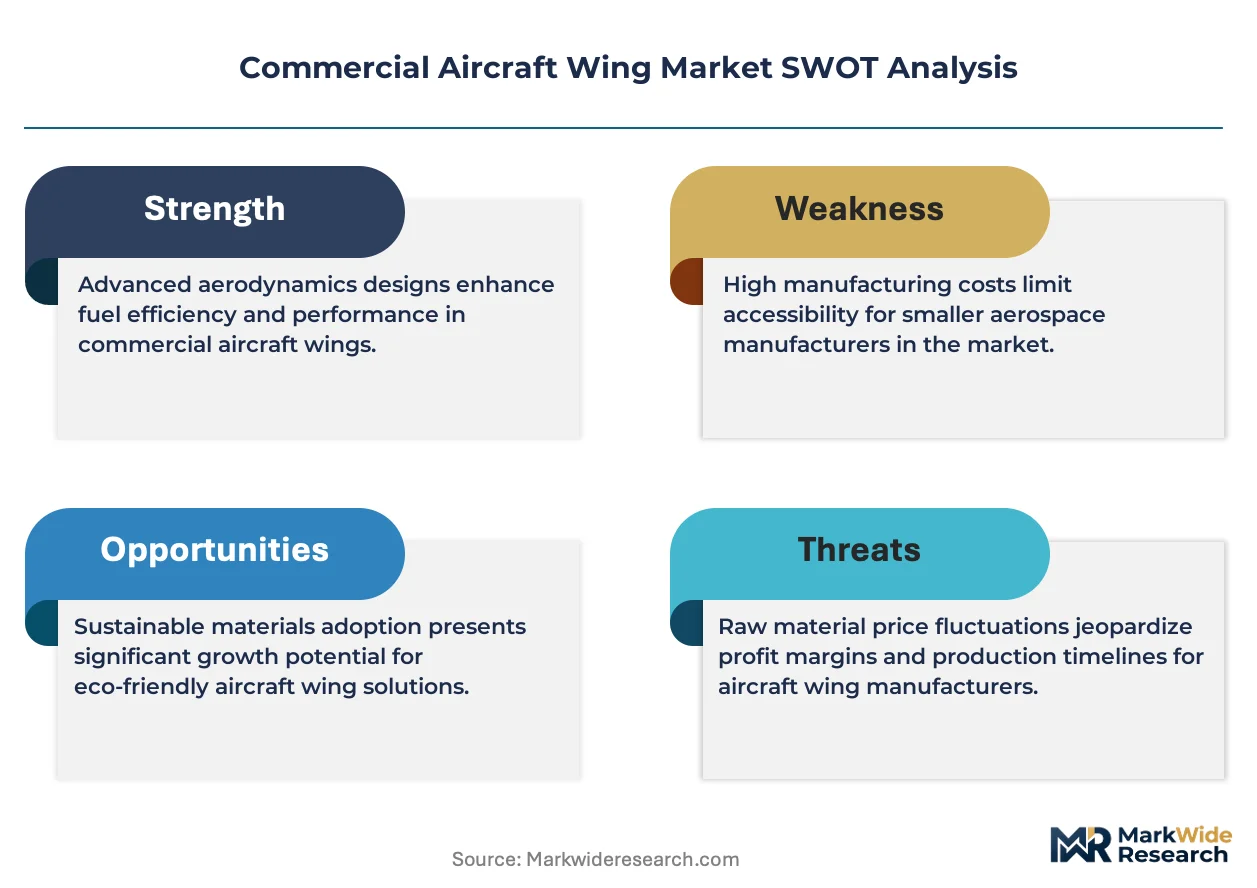
Skilled aerospace composite technician availability is collapsing across major manufacturing clusters, constraining output expansion for advanced wing programs. Spirit AeroSystems leverages its Wichita-centered fabrication network to dominate narrow-body wing shipsets for Boeing's single-aisle platforms. GKN Aerospace Services Limited anchors European supply capability through its Bristol and Munich facilities, specializing in carbon fiber wing structures for Airbus A350 and A320neo families. Premium Aerotec competes on automated fiber placement technology, sustaining German manufacturing competitiveness in high-lift devices and fixed trailing edges.
A commercial aircraft wing is the primary lifting surface of a fixed-wing aircraft, typically constructed from aluminum alloys, carbon fiber reinforced polymers, or hybrid material stacks, and integrates spars, ribs, skins, and control surfaces to generate aerodynamic lift while housing fuel systems and flight control actuators. Its industrial purpose centers on enabling efficient cruise performance, structural integrity under limit loads, and integration of next-generation high-lift devices for reduced approach speeds. Fixed wing configurations remain the volume backbone across civil aviation applications, where single-aisle programs generate the majority of unit demand. Composite materials represent the fastest-growing material category, as OEMs pursue weight reduction targets and corrosion resistance for long-haul platforms, while aluminum alloys retain cost advantages in high-rate narrow-body production where margin pools concentrate at Tier-1 forging and extrusion suppliers.
FAA airworthiness standards under 14 CFR Part 25 and EASA CS-25 certification requirements govern structural substantiation, fatigue life, and damage tolerance for transport category wing designs, directly shaping material selection and testing protocols. The EU Green Deal emissions trajectory and ICAO Carbon Offsetting and Reduction Scheme for International Aviation are forcing airframe manufacturers to prioritize lightweight wing architectures that reduce fuel burn per available seat-mile. Stakeholders must monitor evolving certification timelines for novel thermoplastic composite wing concepts and assess supplier readiness for rate increases on next-generation single-aisle programs before committing capital to dedicated tooling and autoclave capacity.
Market Dynamics
Material certification bottlenecks for thermoplastic composite wing structures are compressing supplier qualification timelines while OEMs accelerate single-aisle rate ramp-ups. The collision between FAA damage tolerance mandates and available autoclave capacity is forcing Tier-1 fabricators into capital-intensive tooling bets before demand certainty firms.
Growth Catalysts
- EU Green Deal emissions trajectory:Binding carbon intensity targets for aviation are compelling airframe manufacturers to prioritize lightweight wing architectures that reduce fuel burn per available seat-mile.
- Narrow-body fleet renewal cycles:Airlines in the United States, China, and India are simultaneously phasing out aging 737NG and A320ceo platforms, concentrating procurement pull for next-generation wing shipsets.
- Automated fiber placement:German and Japanese equipment suppliers are deploying multi-tow AFP heads that cut layup times for complex wing spar geometries by half versus traditional hand layup.
Market Restraints
- Carbon fiber precursor cost volatility:Acrylonitrile feedstock prices swing with oil markets, compressing margin pools for composite wing fabricators locked into fixed-price OEM contracts.
- Wichita-Kansas supply concentration:Spirit AeroSystems' dominance in Boeing narrow-body wing shipsets creates single-source vulnerability for the highest-volume commercial programs.
- Thermoset recycling limitations:Epoxy-based wing structures face end-of-life disposal constraints under evolving EU waste framework directives, threatening circular economy claims.
Strategic Opportunities
- India defense-civil crossover:Hindustan Aeronautics Limited is expanding composite wing fabrication capacity for military programs, creating transferable skills base for future A320neo family subcontracting.
- Thermoplastic welding:Out-of-autoclave consolidation via ultrasonic and induction welding is converging with robotic handling to enable wing panel assembly without massive capital equipment footprints.
- FAA streamlined certification pathways:New policy frameworks for composite damage tolerance are reducing testing burden for derivative wing designs, accelerating aftermarket retrofit programs.
Industry Challenges
- Aerospace composite technician scarcity:Vacuum bagging, ply orientation, and cure cycle management skills are retiring faster than vocational programs in Wichita, Bristol, and Hamburg can replenish.
- 14 CFR Part 25 substantiation timelines:Full-scale wing fatigue testing and damage tolerance demonstrations stretch 18-36 months, misaligning with OEM rate ramp schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Wing Market |
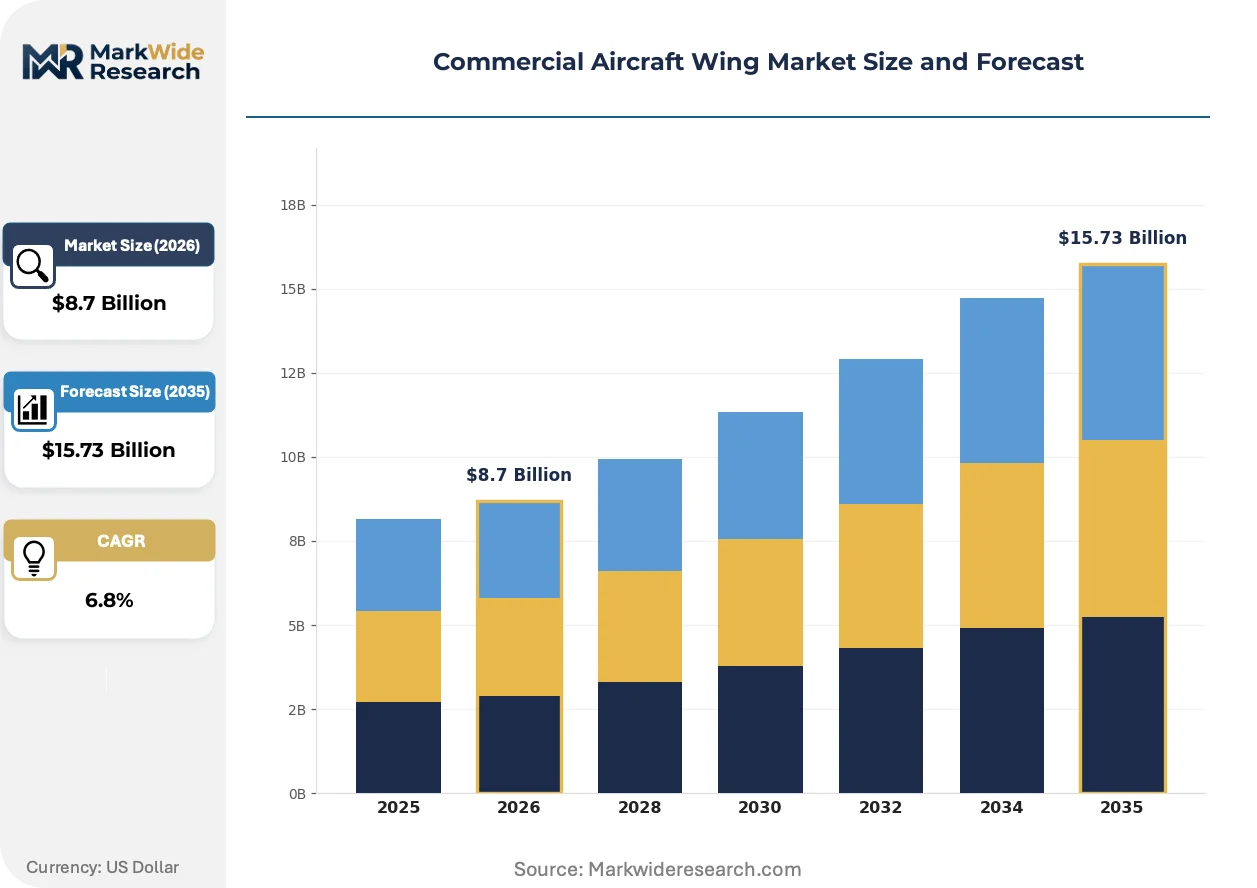
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Wing, Foldable Wing, Elliptical Wing, Delta Wing Material: Aluminum Alloys, Composite Materials, Titanium Alloys, Steel Alloys Application: Civil Aviation, Military Aviation, Cargo Transport, Business Aviation End User: OEMs, Tier-1 Suppliers, Airlines, Maintenance Service Providers |
| Companies Covered | Spirit AeroSystems Inc., Precision Castparts Corp., Arconic Inc., Triumph Group Inc., GKN Aerospace Services Limited, Premium Aerotec, Aernnova Aerospace S.A., FACC AG, Daher Socata SAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Wing Market Emerging Trajectories
Digital thread integration from design to factory floor is collapsing rework rates for complex wing assemblies while enabling real-time quality traceability demanded by regulators. Three developments are compressing competitive positioning.
Thermoplastic composite wing structures are miniaturizing autoclave requirements through out-of-autoclave consolidation using ultrasonic welding and induction heating. Airbus and Boeing engineering teams are qualifying carbon fiber PEEK and PPS wing ribs and access panels for A350 and 777X follow-on programs. The technology is miniaturizing capital barriers for new market entrants who cannot access 30-meter autoclaves, redistributing fabrication capacity toward lower-tier suppliers with robotic welding cells.
EASA CS-25 amendments on damage tolerance and fatigue resistance are mandating probabilistic life assessment methods that exceed traditional safe-life calculations for aluminum wing structures. European OEMs must now demonstrate crack growth predictability under spectrum loading across 90,000 simulated flight cycles. The regulation is accelerating material transitions toward carbon fiber reinforced polymers in German and French wing fabrication clusters where automated inspection protocols are already certified.
Airline technical procurement teams are unbundling wing heavy maintenance from OEM power-by-the-hour contracts, creating independent MRO channels for control surface overhaul and structural repair. Lufthansa Technik and ST Engineering are building dedicated composite wing repair stations in Singapore and Germany to capture this disintermediated spend. The shift is most visible in Asia-Pacific where rapid narrow-body fleet growth is outpacing OEM service network expansion.
Commercial Aircraft Wing Market Segmentation
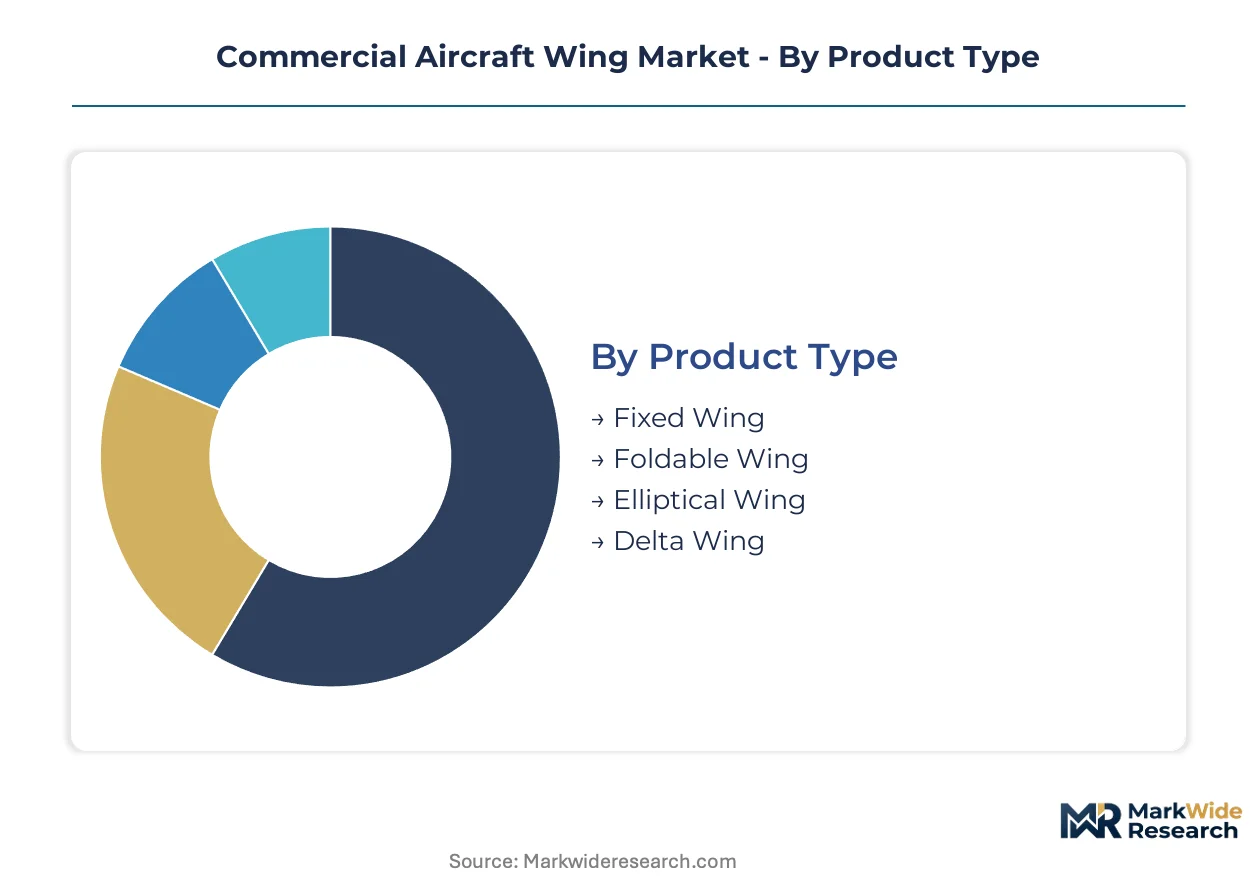
Wing procurement flows through distinct technical and commercial channels, with material selection and end-user relationships determining margin capture and tooling requirements. Each segmentation axis reveals where supply bottlenecks concentrate and which configurations command premium positioning.
Product Type:
Channel mix varies sharply by configuration complexity, with fixed-wing shipsets dominating high-rate narrow-body contracts and specialized geometries flowing through engineering-intensive development programs.
- Fixed Wing:Conventional cantilever designs integrate spars, ribs, and skins into permanent structural configurations optimized for cruise efficiency. Boeing 737 MAX and Airbus A320neo programs in the United States and France are pulling record volumes, though Wichita supply concentration creates single-source vulnerability for the highest-volume platforms.
- Foldable Wing:Hinged outer panel mechanisms enable carrier-based operations and hangar-constrained parking, requiring complex actuation systems and reinforced hinge fittings. United States Navy F/A-18 and F-35C programs at Northrop Grumman drive specialized demand, with folding mechanisms adding 15-20% fabrication cost premium over fixed equivalents.
- Elliptical Wing:Planform geometry distributes lift efficiently across span, historically prominent in British Spitfire heritage designs and modern UAV applications.
- Delta Wing:Triangular planform eliminates conventional tail surfaces, concentrating demand in supersonic military platforms and experimental civil concepts.
Fixed-wing configurations dominate installed base. Foldable-wing engineering is where expansion concentrates for defense-civil crossover programs.
Material:
Cost tier stratification separates legacy aluminum programs from composite-intensive next-generation platforms, with titanium and steel occupying specialized niches where temperature or impact resistance overrides weight targets.
- Aluminum Alloys:7XXX and 2XXX series alloys deliver proven damage tolerance and straightforward repair protocols for high-rate production environments. Airbus A320neo final assembly in Hamburg and Toulouse continues specifying aluminum lower wing skins, with German forging suppliers like Otto Fuchs maintaining capacity leadership for extruded spar caps.
- Composite Materials:Carbon fiber reinforced polymer systems achieve 20-25% weight reduction over aluminum equivalents while eliminating galvanic corrosion. Boeing 787 and Airbus A350 programs have validated automated fiber placement at Spirit AeroSystems Wichita and GKN Aerospace Bristol, though acrylonitrile precursor cost volatility compresses margins for fabricators locked into fixed-price OEM contracts.
- Titanium Alloys:High strength-to-weight ratio and thermal stability suit engine pylon attachments and hot-section proximity applications.
- Steel Alloys:Landing gear attachment fittings and high-load hinge points require steel's yield strength despite density penalties.
Aluminum alloys retain volume leadership on narrow-body rate ramps. Composite materials are climbing the fastest as EASA damage tolerance mandates accelerate CFRP adoption.
Application:
Customer type and fleet renewal cycles determine procurement timing, with civil aviation commanding unit volumes and military programs driving technology insertion.
- Civil Aviation:Commercial transport category aircraft from single-aisle to wide-body platforms generate the majority of wing shipset demand. United States, China, and India airlines are simultaneously phasing out aging 737NG and A320ceo fleets, concentrating procurement pull for next-generation wing assemblies through 2035.
- Military Aviation:Fighter, bomber, and surveillance platforms prioritize maneuver load cases and signature management over fuel efficiency. Lockheed Martin F-35 production in Texas and Northrop Grumman B-21 development in California sustain specialized composite fabrication capacity with limited civil crossover.
- Cargo Transport:Dedicated freighter conversions and factory-built cargo aircraft emphasize high-cycle fatigue resistance.
- Business Aviation:Gulfstream and Dassault Falcon programs in Georgia and France demand complex wing geometries at lower volumes.
Civil aviation dominates order backlogs. Military aviation is where technology transfer originates for composite manufacturing advances.
End User:
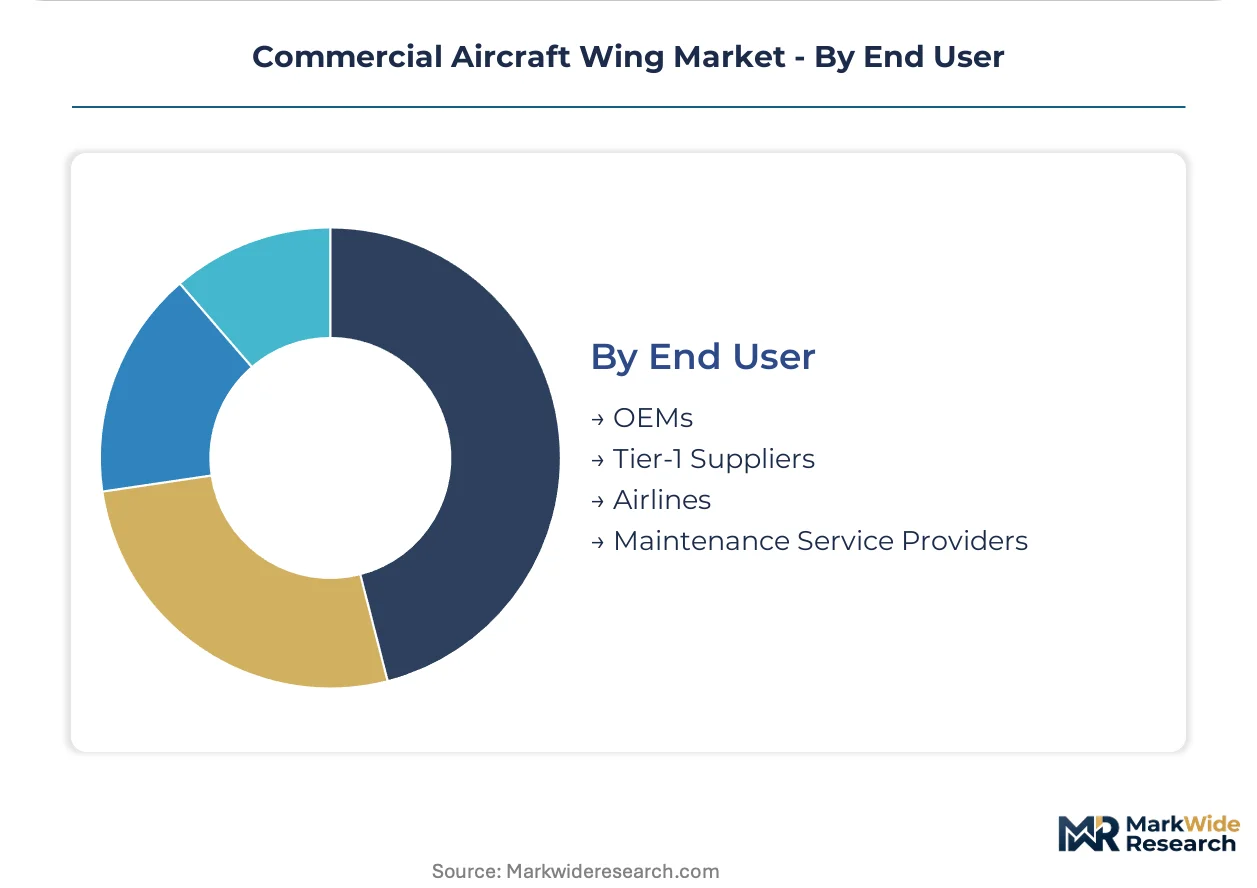
Supply chain position determines technical risk allocation and capital intensity, with OEMs and Tier-1 suppliers commanding fabrication while airlines and MROs capture aftermarket value.
- OEMs:Boeing and Airbus retain wing design authority and final assembly integration, directly controlling critical aerodynamic surfaces for flagship programs. Boeing's 777X composite wing center in Everett represents multi-billion-dollar captive capacity, while Airbus Hamburg maintains parallel A350 wing box fabrication.
- Tier-1 Suppliers:Spirit AeroSystems, GKN Aerospace, and Premium Aerotec execute detail fabrication and subassembly under OEM technical direction. Spirit's Wichita-centered network dominates Boeing narrow-body wing shipsets, creating geographic concentration risk that FAA and Department of Defense procurement officers are monitoring.
- Airlines:Technical procurement teams are unbundling wing heavy maintenance from power-by-the-hour contracts, creating independent MRO channels.
- Maintenance Service Providers:Lufthansa Technik and ST Engineering are building dedicated composite wing repair stations in Germany and Singapore.
Tier-1 suppliers dominate fabrication output. Airlines and MROs are where aftermarket revenue pools are disintermediating from OEM service networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wing procurement patterns diverge sharply by geography, with narrow-body fleet renewal dominating United States and Chinese order books while European demand tilts toward wide-body composite architectures and Indian sourcing concentrates on defense-civil skill transfer.
United States
Boeing's 737 MAX and 777X production lines anchor North American wing fabrication capacity, with Spirit AeroSystems' Wichita-centered network processing record volumes for single-aisle shipsets. FAA 14 CFR Part 25 certification mandates on damage tolerance are accelerating material transitions toward carbon fiber reinforced polymer systems. Everett, Washington hosts Boeing's composite wing center for wide-body programs, representing multi-billion-dollar captive capacity that federal procurement officers monitor for single-source vulnerability.
China
Airlines in Beijing, Shanghai, and Guangzhou are phasing out aging 737NG and A320ceo fleets simultaneously, concentrating procurement pull for next-generation wing assemblies through 2035. The country's national aviation regulator aligns with ICAO Carbon Offsetting and Reduction Scheme standards, forcing airframe manufacturers to prioritize lightweight architectures. COMAC's Shanghai facilities are building transferable composite fabrication skills for future A320neo family subcontracting opportunities.
Germany
Airbus Hamburg maintains parallel A350 wing box fabrication alongside A320neo final assembly, with Otto Fuchs retaining capacity leadership for extruded aluminum spar caps. EASA CS-25 amendments on damage tolerance are mandating probabilistic life assessment methods that exceed traditional safe-life calculations. Premium Aerotec's automated fiber placement technology sustains Bavarian manufacturing competitiveness in high-lift devices and fixed trailing edges.
United Kingdom
GKN Aerospace Services Limited anchors European supply capability through its Bristol facility, specializing in carbon fiber wing structures for Airbus A350 and A320neo families. The EU Green Deal emissions trajectory compels airframe manufacturers to prioritize fuel-efficient architectures. Filton and Munich engineering teams are qualifying carbon fiber PEEK and PPS wing ribs for follow-on programs, redistributing fabrication capacity toward lower-tier suppliers with robotic welding cells.
India
Hindustan Aeronautics Limited is expanding composite wing fabrication capacity for military programs, creating transferable skills base for future civil subcontracting. The country's national aviation regulator enforces structural substantiation protocols aligned with ICAO standards. Bangalore and Hyderabad clusters are where defense-civil crossover investments are concentrating, with technical training institutes racing to replenish vacuum bagging and ply orientation skills retiring faster than vocational programs can replace.
Commercial Aircraft Wing Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidation pressure intensifying as OEMs demand rate flexibility and material certification depth. The upper tier commands design authority and final assembly integration for flagship programs, while mid-scale fabricators compete on automated fiber placement speed and out-of-autoclave welding capabilities. Two strategic archetypes dominate: captive OEM wing centers with multi-billion-dollar fixed investments, and independent Tier-1 shipset suppliers with geographic concentration risk. Competitive moves center on backward integration into carbon fiber precursor supply and capacity expansion in lower-cost manufacturing clusters.
Among United States-based fabricators, Spirit AeroSystems Inc. and Triumph Group Inc. exemplify the Tier-1 shipset supplier archetype, occupying positions where narrow-body program volumes create scale advantages but single-source vulnerability concerns persist. GKN Aerospace Services Limited represents the European integrated specialist model, sitting within a transnational engineering network that spans Bristol and Munich. These three anchors illustrate how competitive positioning stratifies between rate-driven narrow-body specialists and wide-body composite technology leaders.
| Leading Market Players |
|---|
| Spirit AeroSystems Inc. |
| Precision Castparts Corp. |
| Arconic Inc. |
| Triumph Group Inc. |
| GKN Aerospace Services Limited |
| Premium Aerotec |
| Aernnova Aerospace S.A. |
| FACC AG |
| Daher Socata SAS |
| Others |
Supply Flow & Price Mechanics
Eighteen-month qualification timelines for thermoplastic composite wing structures concentrate pricing power with incumbent Tier-1 fabricators possessing certified autoclave capacity, while OEM rate ramp schedules compress supplier margins through fixed-price offtake contracts.
Pricing Analysis
Long-term offtake contracts dominate Boeing and Airbus wing shipset procurement, locking Spirit AeroSystems and GKN Aerospace into fixed-price agreements that transfer acrylonitrile feedstock volatility risk downstream. Price differentiation rests on certification tier—FAA damage tolerance qualification commands premium positioning over EASA-equivalent baselines—and volume scale, where narrow-body rate commitments above 50 shipsets monthly unlock tooling amortization efficiencies. Pricing pressure stems from OEM consolidation of supplier panels, squeezing margin pools for composite fabricators without backward integration into carbon fiber precursor supply. Cargo conversion specialists exhibit highest price sensitivity due to aftermarket budget constraints, while flagship wide-body programs show lowest sensitivity given fuel-burn optimization premiums.
Supply Chain Analysis
Ninety-day carbon fiber precursor inventory cycles at Wichita and Bristol fabrication centers expose the supply chain to acrylonitrile price swings tied to oil market volatility. Manufacturing gravity centers on the United States, Germany, and the United Kingdom, with Spirit AeroSystems' Kansas operations drawing from Japanese and US carbon fiber feedstock. Raw material dependencies span acrylonitrile monomer, epoxy resin systems, and automated fiber placement equipment sourced from German and Japanese suppliers. Single-source vulnerability concentrates in Spirit AeroSystems' narrow-body wing monopoly, creating FAA-monitored geographic risk. Distribution runs through OEM technical direction contracts to Tier-1 subassembly, with final integration captive at Boeing Everett and Airbus Hamburg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities are expanding as airlines unbundle wing heavy maintenance from OEM power-by-the-hour contracts, creating independent MRO niches for composite repair specialists.
For Market Incumbents: Shield rate flexibility through captive autoclave capacity expansion in lower-cost manufacturing clusters, while deepening certification investment in thermoplastic welding protocols to outpace FAA streamlined pathways. Threat substitution from out-of-autoclave robotic cells demands preemptive technology licensing to Tier-2 suppliers. Backward integration into carbon fiber precursor supply anchors margin defense against acrylonitrile volatility. For New Entrants and Emerging Players: Anchor in aftermarket composite wing repair stations serving Asia-Pacific narrow-body fleet growth, where OEM service network expansion lags behind airline technical procurement unbundling. The most penetrable white space sits in Singapore and Bangalore MRO clusters lacking certified damage tolerance inspection protocols. Go-to-market positioning should emphasize FAA-EASA dual certification to capture cross-regional airline contracts. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because OEM supplier panel reduction is concentrating fabrication output among rate-capable Tier-1s with certified automated fiber placement capacity. Acquisition targets should display robotic welding cell deployment and thermoplastic composite qualification pipelines. The signal to watch is EASA CS-25 amendment implementation timelines accelerating material transitions beyond incumbent capacity cushions.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Welding Qualification | Out-of-autoclave consolidation via ultrasonic welding miniaturizes capital barriers for new market entrants. |
| Backward Integration into Precursor Supply | Captive acrylonitrile sourcing insulates margin pools from oil-linked feedstock volatility. |
| Automated Fiber Placement Capacity Expansion | Multi-tow AFP heads at Premium Aerotec cut layup times for complex wing spar geometries. |
| Aftermarket MRO Network Buildout | Lufthansa Technik and ST Engineering capture disintermediated spend from unbundled airline contracts. |
| Dual FAA-EASA Certification Investment | Streamlined damage tolerance pathways reduce testing burden for derivative wing retrofit programs. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with aerospace composite technicians, Tier-1 supplier procurement directors, FAA certification engineers, and airline technical fleet managers; and secondary validation through FAA 14 CFR Part 25 filings, EASA CS-25 amendment documentation, OEM supplier conference disclosures, and carbon fiber trade flow data. Bottom-up wing shipset demand modeling triangulated against top-down OEM production rate announcements.
Across the projection horizon, the analytical framework segmented volume and value outputs by material category, aircraft platform class, and end-user supply chain position. CAGRs were derived from production rate ramp schedules and fleet renewal cycle phasing. Industry-specific forecast inputs incorporated acrylonitrile price elasticity and automated fiber placement equipment deployment curves.
Decision-makers should treat outputs as directional under assumptions of sustained narrow-body rate ramps and stable certification timelines; material deviation in thermoplastic qualification progress or Wichita supply disruption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aviation Crew Management System Market
Aircraft
Firefighting Aircraft Market
Aircraft
Military Multirole Aircraft Market
Aircraft
Europe Light and Very Light Jets Market
Aircraft
Autonomous Aircraft Propulsion Systems Market
Aircraft
India Winglets Market
Aircraft
Global Business Aircraft Market
Aircraft
Aerospace Turbojet Market
Aircraft
Asia-Pacific Business Jet Market
Aircraft
Aircraft Flight Control Computers Market
Aircraft
France Aviation Market
Aircraft
Aircraft Anchoring System Market
Aircraft
Commercial Aircraft Landing Gear Market
Aircraft
Flap Track Fairing Drag Reduction Upgrade Kits Market
Aircraft
Search and Rescue Helicopter Market
Aircraft
Asia-Pacific Aircraft Windshield Wiper and Washer System Market