
 Aircraft Radome Market | 2026-2036
Aircraft Radome Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Radome Market Analysis
US-based defense contractors is recalibrating composite radome output to align with Pentagon procurement schedules for next-generation airborne early warning platforms. General Dynamics Mission Systems leverages vertically integrated testing facilities to accelerate qualification cycles for multi-band radar-transparent structures. Raytheon Technologies Corporation sustains long-term supply agreements with fixed-wing military OEMs across multiple NATO programs. Saint-Gobain anchors European radome material supply through specialized quartz fiber formulations certified for high-temperature nosecone applications.
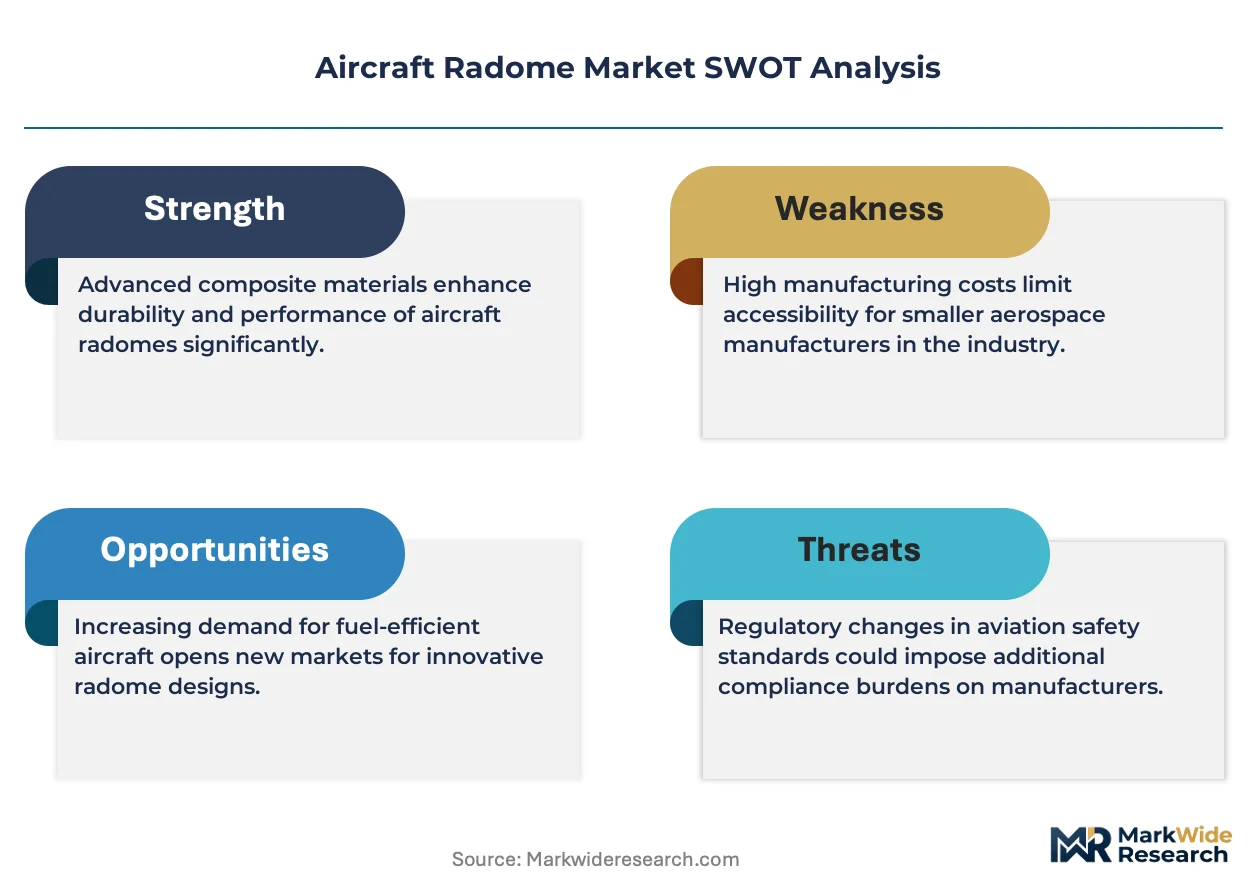
An aircraft radome constitutes a structural enclosure mounted on an aircraft's nose or leading edge, engineered from dielectric composites such as quartz fiber-reinforced cyanate ester or E-glass epoxy laminates to permit unimpeded electromagnetic wave transmission while withstanding aerodynamic loads, hail impact, and thermal shock. The component shields weather radar, SATCOM, and electronic warfare antennae from environmental degradation during all flight phases. Military product types command premium pricing due to stealth-compatible frequency-selective surface integration and ballistic survivability requirements. Carbon fiber material grades are displacing legacy fiberglass in business jet and helicopter nose assemblies where weight reduction directly improves payload-range economics.
The FAA mandates lightning strike protection and hail impact resistance under Part 25 airworthiness standards, while EASA's CS-25 certification framework imposes equivalent dielectric consistency thresholds for European-registered commercial fleets. Military operators face additional MIL-STD-810 environmental testing and ITAR-controlled export restrictions that constrain supplier eligibility for cross-border programs. Stakeholders must monitor evolving 5G terrestrial spectrum allocations, as adjacent-band interference risks are forcing radome redesigns to maintain radar transparency across congested frequency environments.
Market Dynamics
Defense procurement acceleration across NATO member states is compressing qualification timelines for multi-band radar-transparent structures, forcing suppliers to recalibrate composite manufacturing capacity against fixed-wing and rotorcraft platform schedules.
Growth Catalysts
- FAA Part 25 airworthiness directives:Updated lightning strike protection mandates for nose-mounted enclosures are triggering replacement cycles across narrow-body commercial fleets registered in the United States.
- Quartz fiber-reinforced cyanate ester formulations:Advanced dielectric composites certified for high-temperature nosecone applications are penetrating fighter and surveillance platform specifications.
- Frequency-selective surface integration:Stealth-compatible radome designs for electronic warfare antennae are commanding premium positioning within military procurement channels.
Market Restraints
- ITAR-controlled export restrictions:Cross-border supplier eligibility constraints limit material sourcing flexibility for international collaborative defense programs.
- Quartz fiber supply concentration:Specialized high-purity fiber formulations depend on limited European material science infrastructure.
- Adjacent-band 5G interference:Terrestrial spectrum congestion is forcing costly radome redesigns to maintain radar transparency across congested frequency environments.
Strategic Opportunities
- Business jet weight reduction mandates:Carbon fiber material grades displacing legacy fiberglass in helicopter and executive aircraft nose assemblies improve payload-range economics.
- EASA CS-25 certification harmonization:Dielectric consistency thresholds for European-registered commercial fleets create standardization pathways for multi-continental OEM supply agreements.
- SATCOM antenna integration:Convergence of weather radar and satellite communication functions within single nosecone enclosures opens retrofit potential for existing airframes.
Industry Challenges
- MIL-STD-810 environmental testing protocols:Extended qualification cycles for thermal shock and hail impact resistance compress available production windows against delivery schedules.
- Multi-band electromagnetic transparency engineering:Shortage of specialized composite design talent capable of optimizing dielectric properties across X-band through Ku-band frequencies constrains development throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Radome Market |
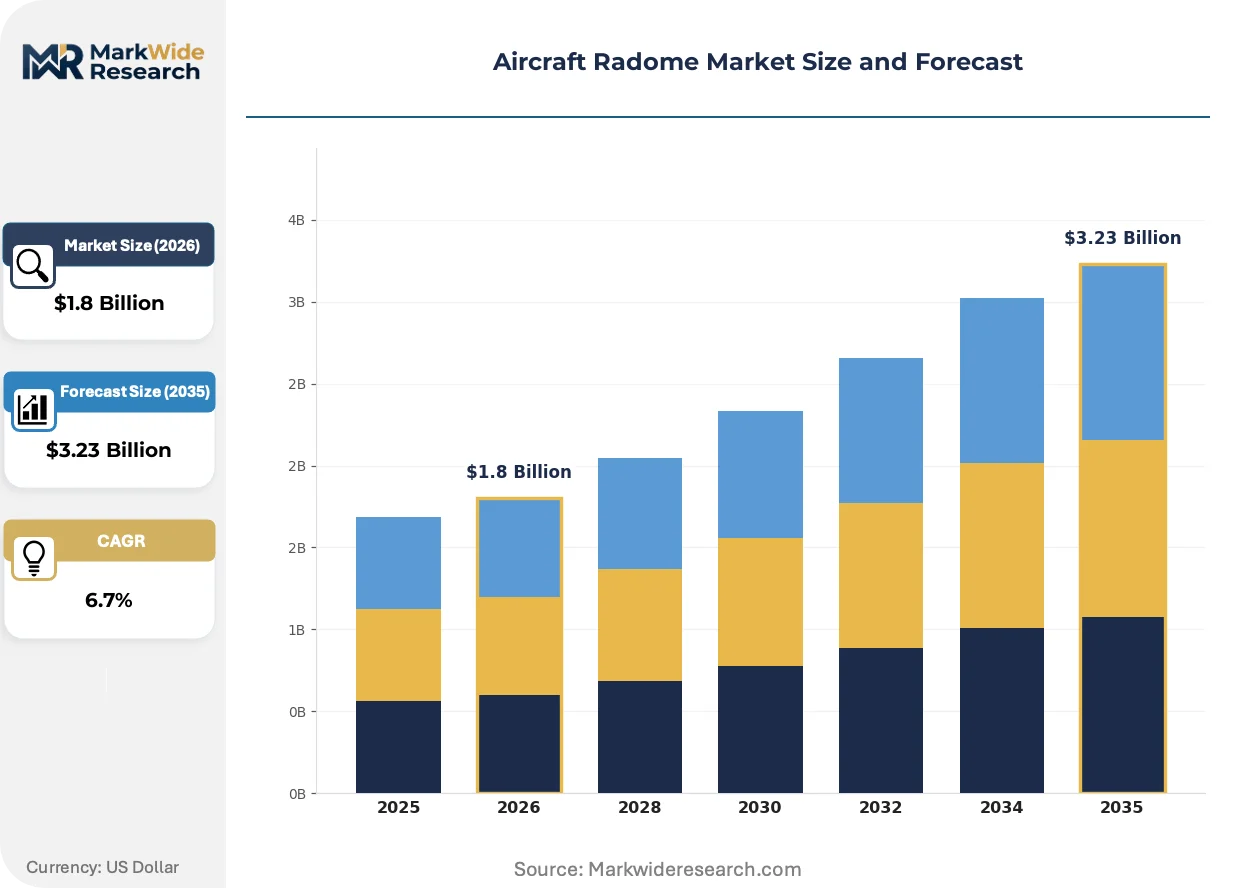
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial, Military, Business Jet, Helicopter Material: Fiberglass, Carbon Fiber, Polymer, Metal Installation Type: Retrofit, Line Fit, OEM, Aftermarket End User: Airlines, Military Operators, Private Operators, Leasing Companies |
| Companies Covered | General Dynamics Mission Systems, Inc, Raytheon Technologies Corporation, Saint-Gobain, Astronics Corporation, Meggitt PLC, FACC AG, Northrop Grumman Corporation, Jenoptik, Nordam Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Radome Market Emerging Trajectories
Material science breakthroughs and spectrum management pressures are actively restructuring how radome manufacturers balance electromagnetic performance against structural survivability requirements.
Frequency-selective surface technology is converging with quartz fiber-reinforced cyanate ester substrates to enable radar transparency at specific bands while maintaining structural integrity. Military airborne early warning platforms are adopting these integrated structures at accelerated procurement cadences. This convergence is compressing the traditional separation between electromagnetic engineering and composite manufacturing disciplines within supplier organizations.
EASA's CS-25 certification framework imposes dielectric consistency thresholds that exceed prior-generation FAA Part 25 requirements for European-registered commercial fleets. Manufacturers serving dual-certification markets must maintain parallel testing protocols. Wide-body OEMs with transatlantic operational profiles are absorbing the compliance burden through dedicated qualification engineering teams.
Platform operators are unbundling radome replacement from heavy maintenance visits and contracting directly with specialized composite shops for nosecone refurbishment. This channel shift bypasses traditional airframe OEM aftermarket networks. The pattern is most visible in United States-based regional airline fleets managing narrow-body replacement cycles against stretched MRO capacity.
Aircraft Radome Market Segmentation
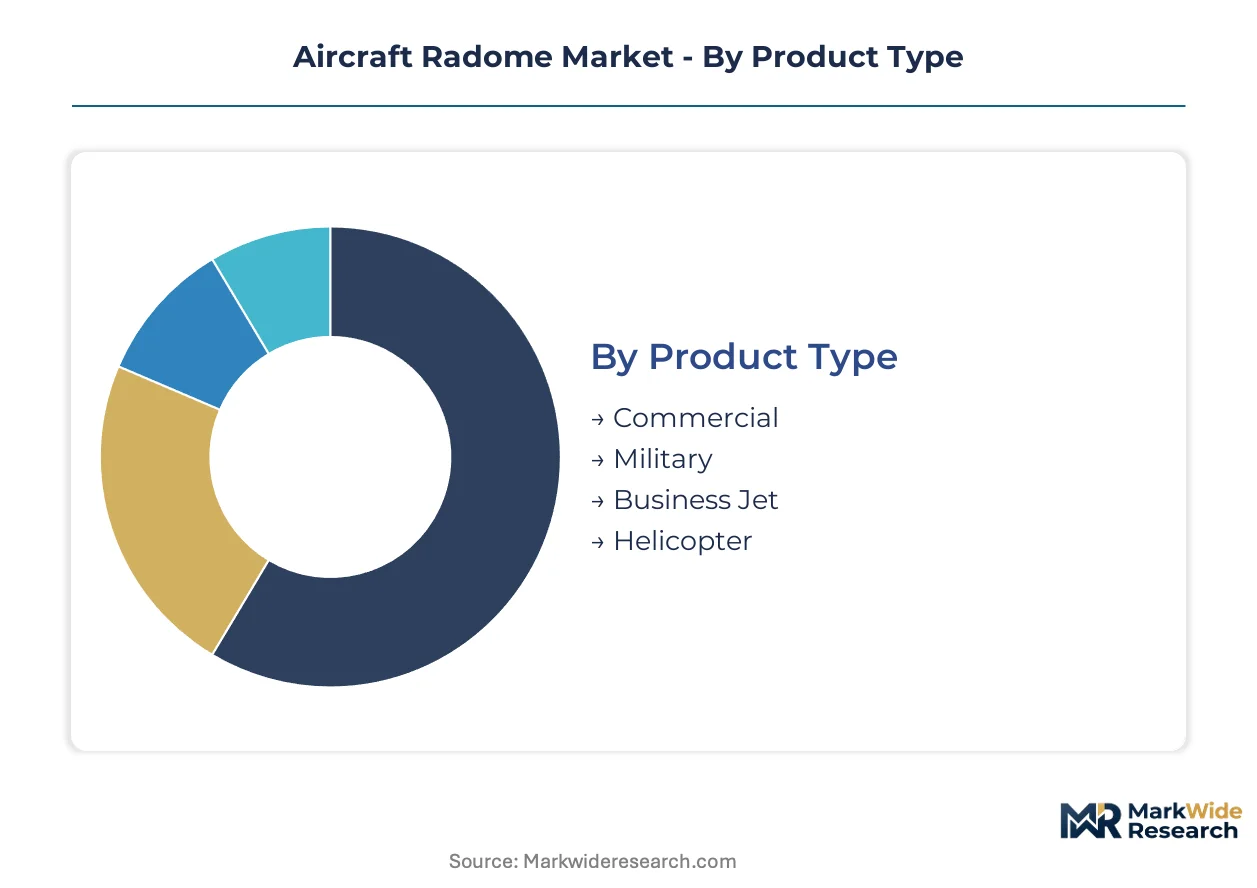
Radome procurement patterns diverge sharply across platform types and installation channels, with upgrade cycles and certification requirements creating distinct demand profiles. Material selection and end-user economics further fragment supplier strategies across this aerospace component market.
Product Type:
Fleet replacement schedules and platform-specific certification burdens determine volume concentration across radome categories.
- Commercial:Narrow-body replacement cycles in United States-based airline fleets sustain steady demand for nose-mounted weather radar enclosures. FAA Part 25 lightning strike mandates trigger refurbishment orders independent of heavy maintenance visits.
- Military:Frequency-selective surface integration for stealth-compatible electronic warfare platforms commands premium positioning. NATO procurement acceleration compresses qualification timelines for multi-band radar-transparent structures across fighter and surveillance programs.
- Business Jet:Carbon fiber grades displace legacy fiberglass in executive aircraft nose assemblies where weight reduction directly improves payload-range economics.
- Helicopter:Compact dielectric enclosures for rotorcraft weather radar and SATCOM integration face distinct hail impact and vibration resistance specifications.
Commercial sits at the top of the volume ranking, with Military climbing the fastest.
Material:
Dielectric performance requirements and thermal loading profiles stratify material selection across temperature extremes and electromagnetic transparency demands.
- Quartz Fiber:High-purity formulations certified for fighter nosecone applications withstand thermal shock while maintaining X-band through Ku-band transparency. European material science infrastructure concentrates supply of these specialized fiber grades.
- Carbon Fiber:Lightweight composites penetrate business jet and helicopter segments where payload-range economics justify material cost premiums over fiberglass alternatives.
- Fiberglass:E-glass epoxy laminates retain cost-sensitive commercial retrofit applications despite gradual displacement in performance-driven platforms.
- Polymer:Emerging thermoplastic formulations target rapid-manufacturing scenarios for unmanned aerial vehicle radome production.
Quartz Fiber captures the steepest expansion trajectory as military specifications tighten, while Fiberglass retains the largest installed base.
Installation Type:
Channel economics and certification responsibility allocation determine margin structures across procurement pathways.
- Line Fit:OEM production line integration requires dielectric consistency certification under EASA CS-25 and FAA Part 25 parallel protocols for transatlantic aircraft programs.
- Retrofit:Direct contracting between regional airlines and specialized composite shops bypasses traditional airframe OEM aftermarket networks during narrow-body replacement cycles.
- OEM:Original equipment specifications for new platform introductions demand vertically integrated testing facilities to accelerate qualification cycles.
- Aftermarket:Refurbishment demand concentrates in United States-based MRO capacity constraints, with operators unbundling radome replacement from scheduled heavy maintenance.
Line Fit dominates value concentration, with Retrofit gaining share fastest as channel structures shift.
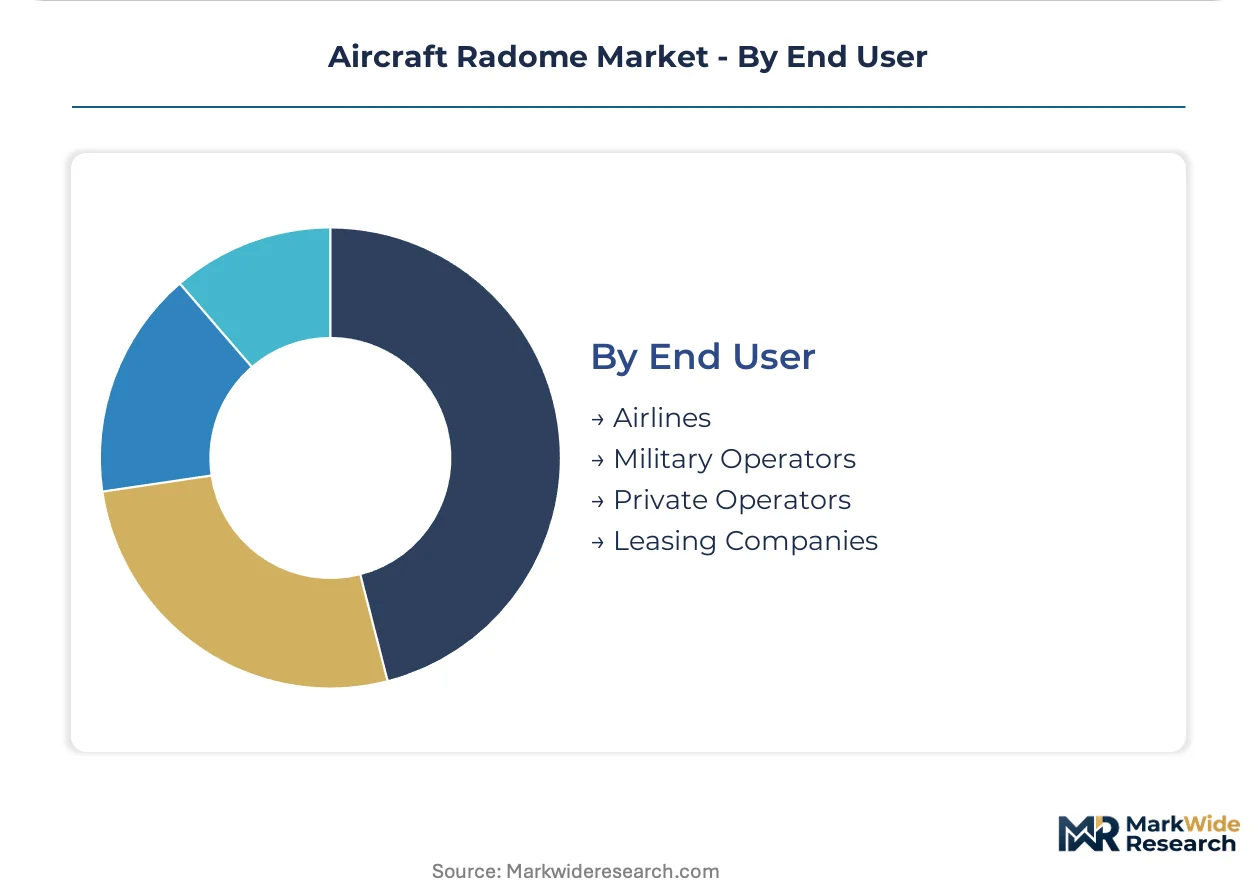
End User:
Procurement authority and fleet scale create divergent specification power across customer categories.
- Airlines:United States-registered narrow-body operators manage replacement cycles against stretched MRO capacity, driving direct composite shop contracting patterns.
- Military Operators:ITAR-controlled export restrictions constrain supplier eligibility for cross-border NATO collaborative programs, limiting sourcing flexibility.
- Private Operators:Business jet and helicopter owner-operators prioritize weight-reduction specifications in carbon fiber material selection for payload-range optimization.
- Leasing Companies:Asset return condition requirements and transition cost minimization influence radome condition standards across lease term boundaries.
Airlines represent the largest addressable base, with Military Operators expanding most quickly through NATO fleet modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States sustains heavier radome procurement volume than Germany, yet French material science infrastructure supplies critical quartz fiber formulations that NATO defense programs require for multi-band radar-transparent structures.
United States
Narrow-body replacement cycles at domestic airlines and Pentagon procurement schedules for airborne early warning platforms drive sustained demand. FAA Part 25 airworthiness directives on lightning strike protection trigger refurbishment orders independent of heavy maintenance visits. Oklahoma-based MRO clusters concentrate specialized composite shops that bypass traditional airframe OEM networks.
Germany
Defense procurement acceleration across NATO programs compresses qualification timelines for fighter nosecone applications. EASA CS-25 certification frameworks impose dielectric consistency thresholds exceeding prior-generation requirements. Bavarian aerospace clusters anchor European testing infrastructure for high-temperature composite validation.
France
Specialized quartz fiber supply chains concentrate around Saint-Gobain's European material science operations for military specifications. French national procurement agencies coordinate cross-border collaborative defense programs subject to ITAR-controlled export restrictions. Toulouse aerospace corridors integrate radome production with wider airframe assembly ecosystems.
United Kingdom
BAE Systems-led fighter programs and surveillance platform modernization sustain demand for stealth-compatible frequency-selective surface integration. UK Ministry of Defence procurement schedules align with NATO-wide fleet replacement timelines. South West England aerospace clusters host composite manufacturing facilities serving transatlantic certification markets.
Japan
Domestic defense procurement for airborne early warning and fighter platforms drives specialized radome demand. METI industrial policy supports domestic composite material capabilities for aerospace applications. Nagoya aerospace corridors concentrate supplier networks aligned with Mitsubishi Heavy Industries platform schedules.
Aircraft Radome Market Vendor Landscape
United States producers anchor the defense-tier supply base; European specialists hold material science and testing infrastructure advantages. The vendor configuration splits between vertically integrated prime contractors and specialized composite fabricators serving aftermarket channels. Three archetypes dominate: defense primes with captive radome divisions, independent composite specialists with EASA/FAA dual certification, and material science suppliers controlling quartz fiber formulations. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification timelines compress against delivery schedules.
Among United States-based defense contractors, General Dynamics Mission Systems, Inc. and Raytheon Technologies Corporation exemplify the prime-contractor archetype with integrated testing and supply chain control. Saint-Gobain occupies a distinct position as a European material science anchor supplying specialized fiber formulations across NATO programs. These three entities represent the structural concentration points through which procurement flows for multi-band radar-transparent structures consolidate.
| Leading Market Players |
|---|
| General Dynamics Mission Systems, Inc |
| Raytheon Technologies Corporation |
| Saint-Gobain |
| Astronics Corporation |
| Meggitt PLC |
| FACC AG |
| Northrop Grumman Corporation |
| Jenoptik |
| Nordam Group |
| Others |
Supply Flow & Price Mechanics
NATO defense procurement programs anchor pricing power for multi-band radar-transparent structures, with contract-based long-term offtake agreements dominating military tiers while commercial retrofit channels absorb spot-market volatility. Quartz fiber supply concentration in European material science infrastructure feeds premium positioning for fighter nosecone specifications, whereas carbon fiber grades face cost compression from capacity additions serving business jet weight-reduction mandates.
Pricing Analysis
Capacity additions in United States-based composite manufacturing are reshaping price floors for commercial retrofit channels as regional airlines unbundle radome replacement from heavy maintenance visits. Three-tier pricing structure across military-specification, dual-certification commercial, and economy retrofit levels separates ITAR-controlled programs from EASA/FAA parallel-certified production and aftermarket refurbishment. Pricing pressure stems from stretched MRO capacity compressing turnaround premiums for direct composite shop contracting. Airlines represent the most price-sensitive buyer segment, while Pentagon procurement schedules sustain inelastic demand for stealth-compatible frequency-selective surface integration.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale defense procurement demand through vertically integrated testing facilities, while specialized composite shops serve fragmented aftermarket retrofit contracts. Geographic supply concentrates in France for quartz fiber formulations, the United States for carbon fiber prepregs, and Germany for high-temperature composite validation infrastructure. Raw material dependencies rest on cyanate ester resin systems, specialized quartz fiber grades, and lightning strike protection mesh. Single-source vulnerability around European quartz fiber supply creates exposure to ITAR-controlled export restrictions. Distribution runs through prime contractor captive divisions for military programs and independent MRO networks for commercial refurbishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily through defense fleet modernization cycles that sustain long-term procurement visibility across NATO member states.
For Market Incumbents: Acquire specialized composite testing facilities to compress qualification timelines against compressed Pentagon delivery schedules. Secure backward integration into quartz fiber supply through partnership structures with European material science infrastructure. Carbon fiber displacement threats in business jet segments require capacity positioning in lightweight laminate production to defend payload-range economics advantages. For New Entrants and Emerging Players: The premium-to-economy price gap in dual-certification commercial radomes offers white-space entry for independent fabricators with EASA CS-25 and FAA Part 25 parallel capabilities. Target United States-based regional airline direct contracting channels bypassing traditional airframe OEM aftermarket networks. Pursue SATCOM antenna integration retrofit opportunities as channel structures shift toward unbundled nosecone refurbishment. For Investors and Strategic Acquirers: Defense primes with captive radome divisions are the most active acquirer in this space, consolidating testing infrastructure and material supply control. Mid-cap composite specialists with dual-certification capabilities represent the optimal acquisition target archetype for platform diversification. Monitor 5G terrestrial spectrum allocation decisions as the signal to watch for radome redesign cycle inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quartz Fiber Supply | Captive access to Saint-Gobain's European formulations insulates against ITAR export constraints. |
| Dual-Certification Testing Facility Expansion | Parallel EASA CS-25 and FAA Part 25 validation accelerates transatlantic OEM qualification cycles. |
| Frequency-Selective Surface R&D Partnership | Stealth-compatible electronic warfare integration commands premium positioning in NATO procurement channels. |
| Direct Airline Contracting Channel Development | Bypassing traditional MRO networks captures margin from unbundled narrow-body replacement demand. |
| Carbon Fiber Capacity Buildout for Business Jets | Lightweight nosecone production serves payload-range economics priorities in executive aviation segments. |
Methodological Framework
Coverage spans the United States, France, Germany, the United Kingdom, and Japan, with primary inputs from each market cluster combining interviews with defense procurement officers, composite manufacturing engineers, FAA certification specialists, airline fleet managers, and MRO operations directors. Secondary validation draws from FAA Part 25 airworthiness directive filings, EASA CS-25 certification databases, Pentagon budget justification documents, NATO cooperative program announcements, and customs trade data for quartz fiber and cyanate ester resin movements. Bottom-up platform-level demand modeling triangulates against top-down military and commercial aerospace production forecasts.
Segmentation granularity extends to product type, material grade, installation channel, and end-user category across the projection horizon. Platform-specific replacement cycles, defense procurement schedules, and certification timeline assumptions inform volume and value outputs. CAGRs derive from compounded annual platform delivery projections adjusted for radome content per airframe and aftermarket refurbishment frequency. Industry-specific forecast inputs include NATO fleet modernization timelines and FAA lightning strike mandate compliance deadlines.
Caveats apply where 5G spectrum reallocation decisions, ITAR regulatory modifications, or quartz fiber supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions regarding defense budget continuity and commercial aviation recovery trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Afterburner Market
Aircraft
Light and Very Light Jets Market
Aircraft
Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems Market
Aircraft
Military Aircraft Market
Aircraft
Commercial Aerospace Market
Aircraft
Europe Attack Helicopter Market
Aircraft
Asia-Pacific Commercial Aircraft Market
Aircraft
North America Business Jet Market
Aircraft
Vietnam Business Jets and Helicopters Market
Aircraft
Europe Light and Very Light Jets Market
Aircraft
Turboprop Aircraft Market
Aircraft
Global Aircraft Tugs Market
Aircraft
United States Aerospace and Defense Market
Aircraft
Aircraft Window Frame Market
Aircraft
Evtol (Electric Vertical Takeoff and Landing) Airplane Market
Aircraft
Supersonic Jet Market