
 Aircraft Leasing Market | 2026-2036
Aircraft Leasing Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Leasing Market Analysis
Next-generation propulsion technology is reshaping how aircraft lessors structure portfolio risk and residual value calculations. AerCap Holdings N.V. dominates wide-body lease placements through its scale and manufacturer relationships. SMBC Aviation Capital Limited anchors narrow-body exposure across Asian flag carriers and low-cost operators. BOC Aviation Limited leverages its state-backed capital structure to compete on long-dated finance lease terms.
Aircraft leasing denotes the commercial practice where a lessor purchases an aircraft from a manufacturer or prior operator and grants an airline or cargo operator exclusive use rights for a defined term in exchange for periodic rental payments; lease rates typically reference aircraft age, engine cycle limits, maintenance reserve requirements, and residual value curves indexed to appraiser benchmarks. The primary purpose is to convert capital-intensive aviation assets into operating expenses, preserving airline liquidity for route expansion while transferring residual value risk to specialized lessors. Narrow-body leases generate the highest transaction velocity due to fleet commonality and secondary market depth, while operating leases command premium margins over finance structures because lessors retain residual exposure and remarketing optionality. Wet lease demand surges during seasonal peaks and operational disruptions, though long-term operating leases still capture the deepest institutional capital pools.
FAA airworthiness directives and EASA type certification standards govern lease-embedded technical compliance obligations, while ICAO's Carbon Offsetting and Reduction Scheme for International Aviation shapes lessor fleet renewal timelines and end-of-life asset strategies. Lessors must monitor how EU Green Deal-aligned sustainable aviation fuel mandates and emerging EPA emissions benchmarks alter aircraft valuation curves and lessee credit assessments. Stakeholders should track which regulatory jurisdictions accelerate phase-out timelines for older engine architectures, as this determines portfolio concentration risk and remarketing liquidity across regional markets.
Market Dynamics
ICAO carbon offset standards and next-generation engine technology are compressing aircraft residual value curves and forcing lessors to accelerate portfolio turnover timelines.
Growth Catalysts
- EU Green Deal mandates:Sustainable aviation fuel blending requirements under EU Green Deal legislation are compelling European flag carriers to lease newer-generation narrow-bodies with certified SAF compatibility, expanding lessor placement pipelines.
- Low-cost carrier fleet expansion:Southeast Asian budget airlines are tripling operating lease commitments to fund route densification without balance-sheet aircraft ownership.
- Pratt & Whitney GTF engine architecture:Geared turbofan technology delivers 16% fuel efficiency gains over prior generation, making GTF-equipped A320neo and A220 families the preferred collateral for institutional lease financing.
Market Restraints
- Titanium supply concentration:Russian and Chinese smelters control 70% of aerospace-grade titanium sponge output, exposing lessors to airframe production delays and delivery slippage risk.
- Interest rate volatility:Central bank policy shifts in Ireland, Singapore, and the United States have widened lease-rate factor spreads, compressing lessor net operating yields on long-dated placements.
- End-of-life asset stranding:Pre-2020 engine architectures face accelerating phase-out timelines under EPA and EASA emissions benchmarks, trapping residual value in aging narrow-body portfolios.
Strategic Opportunities
- India domestic aviation liberalization:UDAN regional connectivity schemes and airport privatization are spawning new airline entrants with pure operating-lease fleet strategies and no legacy owned assets.
- Freighter conversion demand:E-commerce parcel volume growth is absorbing retired passenger wide-bodies through passenger-to-freighter programs, creating remarketing liquidity for lessor end-of-lease assets.
- CSRD-aligned green financing:EU Corporate Sustainability Reporting Directive disclosure requirements are channeling institutional capital toward ESG-certified lease structures with carbon-linked pricing mechanisms.
Industry Challenges
- Airworthiness directive compliance latency:FAA and EASA safety bulletins on GTF engine durability are forcing unscheduled shop visits, disrupting lessee cash flows and triggering lease renegotiation disputes.
- Technical records standardization:Fragmented documentation formats across MRO providers in Ireland, Singapore, and the United States complicate aircraft redelivery inspections and residual value verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Leasing Market |
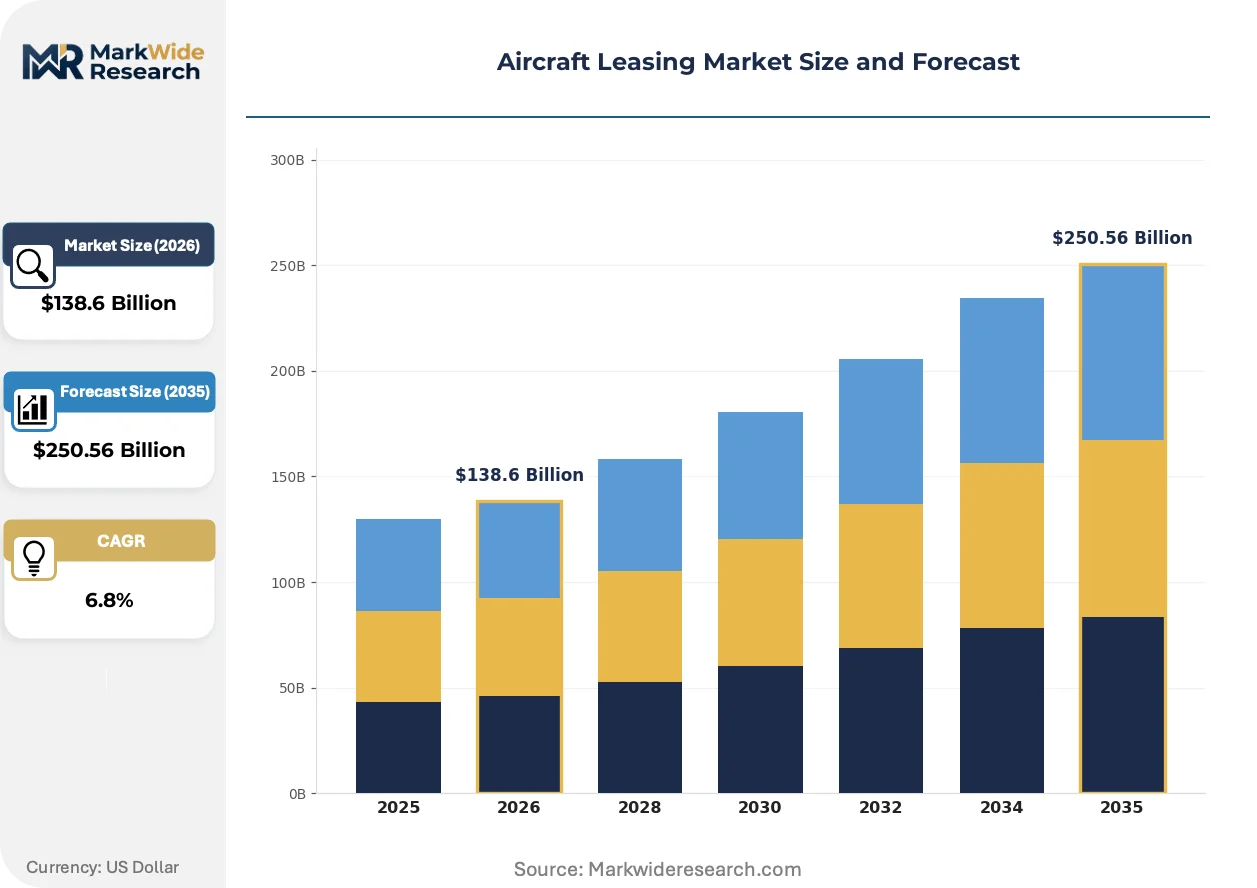
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $250.56 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Narrow-body, Wide-body, Regional, Cargo Leasing Model: Operating Lease, Finance Lease, Wet Lease, Dry Lease End User: Airlines, Cargo Operators, Charter Services, Aircraft Manufacturers Lease Duration: Short-term, Medium-term, Long-term, Specialized |
| Companies Covered | BOC Aviation Limited, Aviation Capital Group LLC, AerCap Holdings N.V., Dubai Aerospace Enterprise Ltd., BBAM LLC, Air Lease Corporation, Avolon Holdings Limited, Macquarie AirFinance, SMBC Aviation Capital Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Leasing Market Emerging Trajectories
Propulsion technology hybridization and regulatory carbon accounting are rewriting how lessors underwrite aircraft risk and structure lease terms.
Hybrid-electric propulsion architecture is hybridizing regional aircraft design, with turbogenerator-battery systems enabling 30-minute electric-only flight segments. Lessors targeting 19-50 seat commuter operators are pre-positioning capital for 2028-2030 type certification timelines. This technology is hybridizing residual value models by introducing battery cycle-life depreciation alongside traditional engine-hour metrics.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant system retrofits on existing in-service fleets, raising maintenance reserve escrow requirements. Lessors now embed F-Gas compliance cost pass-through clauses in lease rate factors. Narrow-body operators with aging environmental control systems face the steepest escrow adjustments.
Airlines are unbundling power-by-the-hour maintenance contracts from lease agreements, negotiating direct OEM service deals and reducing lessor margin capture on aftermarket services. This disintermediation concentrates in Asia-Pacific flag carriers with established MRO subsidiaries. Singapore Airlines and Cathay Pacific have led the decoupling trend, compressing lessor ancillary revenue pools.
Aircraft Leasing Market Segmentation
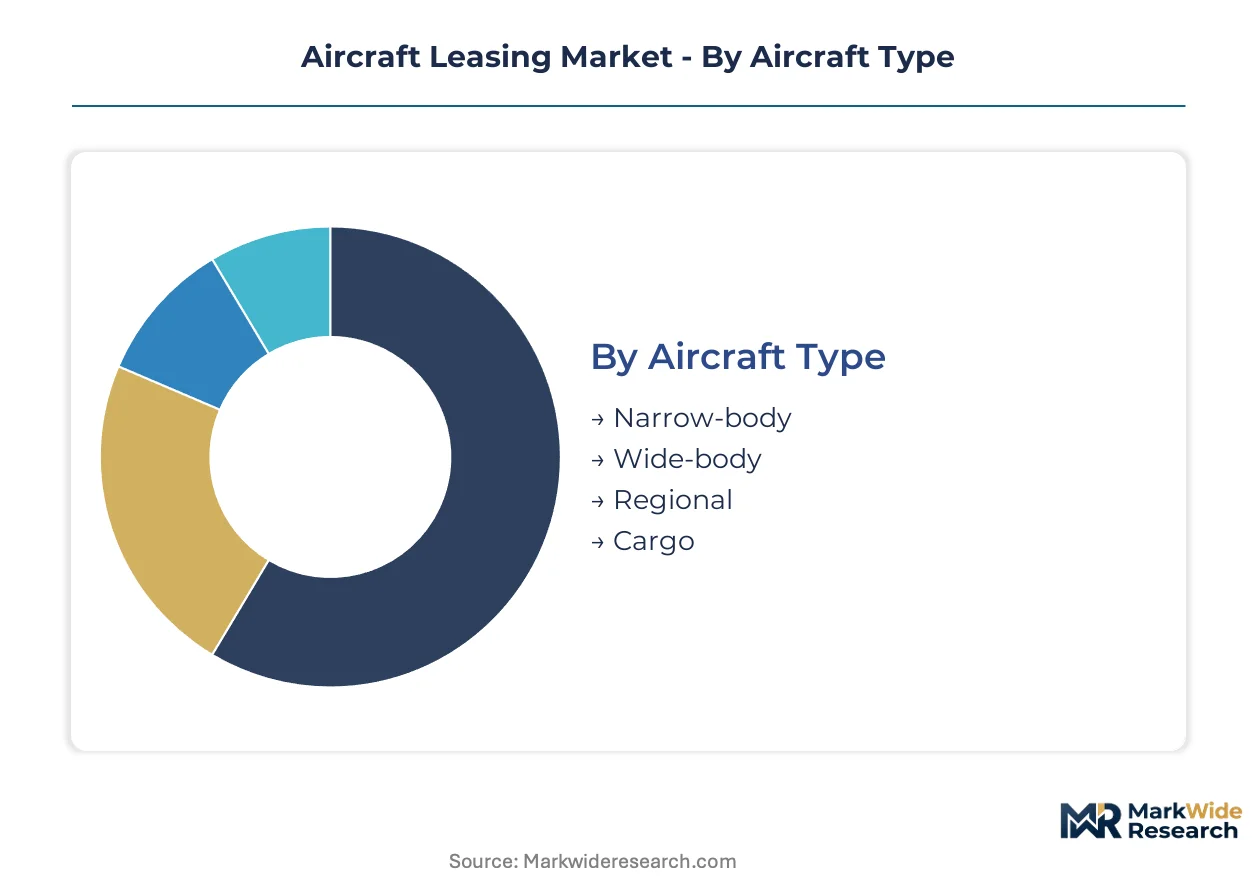
Aircraft leasing segmentation reveals how capital allocation, risk appetite, and regulatory exposure vary across contract structures and asset classes. Lessors calibrate portfolio mix across these dimensions to optimize yield curves and residual value protection.
Aircraft Type:
Narrow-body assets turn over fastest due to fleet commonality and secondary market depth, while wide-body placements cycle slowest on longer amortization schedules and thinner remarketing liquidity.
- Narrow-body:Single-aisle configurations dominate unit transaction velocity. Southeast Asian low-cost carriers concentrate demand for A320neo and 737 MAX families, driven by route densification mandates and Pratt & Whitney GTF engine efficiency benchmarks.
- Wide-body:Twin-aisle aircraft command premium lease rates but extended placement timelines. AerCap Holdings N.V. anchors placement pipelines for 787 and A350 families across Asia-Pacific flag carriers seeking transpacific route restoration.
- Regional:Turboprop and small-jet categories serve thin-route economics. Indian UDAN connectivity schemes concentrate demand for ATR-72 and E-Jet families among new regional entrants.
- Cargo:Dedicated freighter assets absorb converted passenger wide-bodies. E-commerce parcel volume growth drives placement demand for 777-300ERSF and A330P2F conversions.
Narrow-body dominates installed base. Cargo is where expansion concentrates.
Leasing Model:
Operating leases capture the widest institutional capital pools by transferring residual risk to lessors, while finance leases concentrate among state-backed competitors with balance-sheet capacity for long-dated exposure.
- Operating Lease:Lessors retain ownership and remarketing optionality. Ireland's Dublin aviation finance cluster anchors global placement volume, with SMBC Aviation Capital Limited structuring terms across Asian flag carriers and budget operators.
- Finance Lease:Lessees assume residual risk through purchase obligations. BOC Aviation Limited leverages state-backed capital to compete on long-dated terms, concentrating placements among Chinese and Southeast Asian carriers seeking ownership conversion pathways.
- Wet Lease:Full-service arrangements include crew, maintenance, and insurance. Seasonal demand spikes and operational disruptions drive short-term placements across European charter markets.
- Dry Lease:Aircraft-only structures place operational burden on lessees. Long-haul cargo operators favor this model for fleet flexibility without crew provisioning complexity.
Operating lease dominates installed base. Wet lease is where expansion concentrates.
End User:
Airlines generate the deepest placement pipelines through fleet renewal cycles, while cargo operators concentrate growth in converted wide-body absorption.
- Airlines:Passenger carriers drive core demand across narrow-body and wide-body categories. EU Green Deal mandates compel European flag carriers toward newer-generation assets with certified SAF compatibility.
- Cargo Operators:Dedicated freight carriers absorb end-of-lease passenger conversions. Amazon Air and DHL Express anchor placement demand for 767-300BCF and A321P2F programs.
- Charter Services:Ad-hoc passenger and cargo providers favor short-term wet lease structures. Seasonal tour operators and humanitarian relief agencies concentrate demand spikes.
- Aircraft Manufacturers:OEMs utilize lease structures for production financing and customer transition support. Airbus and Boeing deploy in-house leasing arms for residual value risk management on new type introductions.
Airlines dominate installed base. Cargo operators are where expansion concentrates.
Lease Duration:
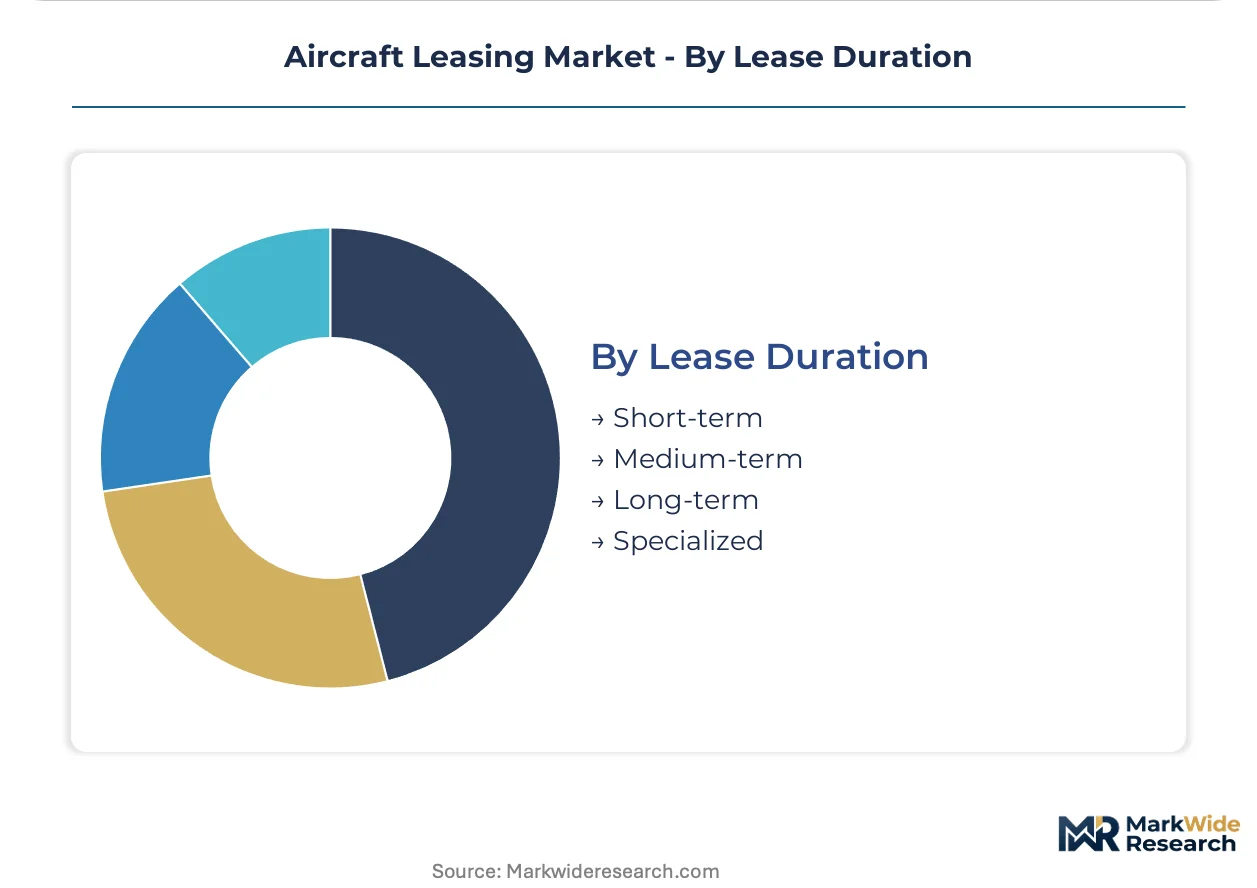
Medium-term structures balance yield optimization with remarketing flexibility, while specialized durations address regulatory transition and conversion timelines.
- Short-term:Contracts under 12 months serve seasonal capacity and operational recovery. Wet lease providers structure these around crew availability and maintenance reserve escrows.
- Medium-term:Three-to-seven year placements optimize lessor yield curves. Narrow-body operating leases concentrate in this band, matching airline fleet planning horizons with institutional investor maturity preferences.
- Long-term:Ten-to-twelve year finance leases align with wide-body economic lives. State-backed lessors dominate this tier through competitive rate factors and residual value guarantees.
- Specialized:Non-standard durations address freighter conversion cycles and emissions compliance deadlines. EU F-Gas Regulation phase-down schedules and ICAO carbon offset timelines drive bespoke structuring.
Medium-term dominates installed base. Specialized is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ireland exports aircraft leasing services to carriers across Asia-Pacific and Europe through Dublin's aviation finance cluster, generating placement volume that shapes global fleet renewal timelines.
United States
US cargo operators absorb converted passenger wide-bodies for e-commerce parcel networks. FAA airworthiness directives on next-generation engine durability force unscheduled maintenance and disrupt lease cash flows. Dallas-Fort Worth anchors freighter conversion demand through specialized MRO facilities serving Amazon Air and DHL Express.
Ireland
European flag carriers lease SAF-compatible narrow-bodies to meet EU Green Deal blending mandates. CSRD disclosure requirements channel institutional capital toward ESG-certified lease structures. Dublin's aviation finance cluster concentrates operating lease origination, with SMBC Aviation Capital structuring terms across Asian budget carriers.
China
Domestic carriers seek long-dated finance leases with ownership conversion pathways. State-backed capital from policy banks enables competitive rate factors on ten-to-twelve year placements. BOC Aviation leverages this structure to anchor placement pipelines among Southeast Asian operators.
India
UDAN regional connectivity schemes spawn new airline entrants with pure operating-lease fleet strategies. DGFT import duty waivers on leased aircraft reduce cost barriers for budget operators. Mumbai and Delhi-NCR concentrate lessor representative offices serving IndiGo and SpiceJet renewal cycles.
Singapore
Asia-Pacific flag carriers decouple power-by-the-hour contracts from lease agreements, negotiating direct OEM service deals. Central bank policy shifts widen lease-rate factor spreads and compress net operating yields. Changi anchors technical records standardization efforts across MRO providers serving regional lessor portfolios.
Aircraft Leasing Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a consolidated tier-one segment and fragmented mid-tier. AerCap Holdings N.V. and SMBC Aviation Capital Limited anchor wide-body and narrow-body placement pipelines respectively, while state-backed lessors compete on long-dated finance lease terms. Strategic archetypes include scale-driven portfolio lessors, state-sponsored capital providers, and specialized freighter conversion platforms. Competitive moves concentrate on portfolio diversification into cargo assets and geographic expansion toward Indian and Southeast Asian carrier relationships.
Within the scale-driven tier, AerCap Holdings N.V. and SMBC Aviation Capital Limited exemplify channel-controlling positioning through manufacturer relationships and Asian flag carrier access. BOC Aviation Limited occupies a distinct archetype as a state-sponsored capital provider competing on long-dated finance lease structures. These three entities anchor the competitive landscape by representing divergent funding models—institutional capital deployment, Japanese banking conglomerate backing, and Chinese policy bank support—each shaping lease rate factors and residual value assumptions across regional markets.
| Leading Market Players |
|---|
| BOC Aviation Limited |
| Aviation Capital Group LLC |
| AerCap Holdings N.V. |
| Dubai Aerospace Enterprise Ltd. |
| BBAM LLC |
| Air Lease Corporation |
| Avolon Holdings Limited |
| Macquarie AirFinance |
| SMBC Aviation Capital Limited |
| Others |
Supply Flow & Price Mechanics
Titanium supply concentration from Russian and Chinese smelters determines both lease-rate factor spreads across technology generations and the geographic clustering of lessor origination activity around Dublin and Singapore financing hubs. Lessors price this single-source dependency into maintenance reserve escrows and residual value curves, compressing margins on long-dated placements while amplifying regional arbitrage opportunities.
Pricing Analysis
The technology-generation pricing gap between Pratt & Whitney GTF-equipped narrow-bodies, pre-2020 engine architectures, and hybrid-electric regional aircraft in development defines lessor portfolio stratification. Three-tier pricing structure across new-generation, current-generation, and end-of-life assets reflects fuel efficiency certification tiers and EPA emissions benchmarks. Pricing pressure stems from central bank rate volatility in Ireland and Singapore widening lease-rate factor spreads. Southeast Asian low-cost carriers exhibit highest price sensitivity due to thin-margin route economics, while Asia-Pacific flag carriers with MRO subsidiaries negotiate least aggressively on base rates.
Supply Chain Analysis
Supplier-financing facilities extended by Boeing and Airbus to tier-one lessors compress working capital cycles and accelerate delivery slot commitments. Aerospace-grade titanium sponge draws from Russian VSMPO-AVISMA and Chinese Baoji Titanium, while engine core components rest on Japanese and German precision manufacturing. Single-source vulnerability concentrates in titanium sponge smelting, with 70% of output controlled by two national supply bases. Distribution runs through Dublin aviation finance cluster origination to airline lessees across Asia-Pacific and European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ICAO carbon offset standards and next-generation engine technology are disrupting residual value models and forcing portfolio turnover acceleration across the analysis window.
For Market Incumbents: Harden residual value protection through accelerated narrow-body remarketing into Indian UDAN regional connectivity schemes and Southeast Asian low-cost carrier expansion. Deepen manufacturer relationships for GTF-equipped A320neo family priority delivery slots before EPA emissions phase-out timelines trap pre-2020 engine architectures. Vertical integration into freighter conversion platforms absorbs end-of-lease wide-body assets. For New Entrants and Emerging Players: Pursue cargo operator relationships for 777-300ERSF and A330P2F conversion placements as e-commerce parcel volume absorbs retired passenger wide-bodies. Target specialized lease durations tied to EU F-Gas Regulation compliance deadlines and ICAO carbon offset timelines where incumbent lessors lack structuring flexibility. Anchor go-to-market strategy through CSRD-aligned green financing certification to capture institutional capital seeking ESG-certified lease structures. For Investors and Strategic Acquirers: EU Green Deal SAF mandate implementation reshapes the acquisition landscape toward lessors with certified sustainable aviation fuel compatibility portfolios and carbon-linked pricing mechanisms. Long-term viability centers on fleet technology positioning across the projection horizon rather than current placement volume. Target acquisition archetype: mid-tier lessors with concentrated GTF-equipped narrow-body exposure and established Asian flag carrier relationships. Monitor FAA airworthiness directive issuance frequency on next-generation engine durability as inflection indicator for unscheduled maintenance reserve drawdowns.| Strategic Initiative | Industry Significance |
|---|---|
| Freighter Conversion Platform Investment | Amazon Air and DHL Express absorption of 767-300BCF conversions creates remarketing liquidity for aging wide-body assets. |
| GTF-Equipped Narrow-Body Portfolio Expansion | Pratt & Whitney engine architecture delivers 16% fuel efficiency gains that satisfy EU Green Deal SAF blending mandates. |
| CSRD-Aligned Green Financing Certification | EU Corporate Sustainability Reporting Directive disclosure requirements channel institutional capital toward ESG-certified lease structures. |
| Indian UDAN Connectivity Scheme Partnership | DGFT import duty waivers on leased aircraft reduce cost barriers for new regional airline entrants with pure operating-lease strategies. |
| Power-by-the-Hour Decoupling Resistance | Singapore Airlines and Cathay Pacific direct OEM service deals compress lessor ancillary revenue pools and threaten margin capture. |
Methodological Framework
A spread of perspectives from aircraft lessor portfolio managers, airline fleet planning executives, MRO technical records specialists, and aviation finance legal counsel converged on the working assumptions underlying this analysis. Primary interviews with Dublin-based origination teams and Singapore leasing operations supplemented secondary validation through FAA airworthiness directive filings, EASA type certification databases, ICAO carbon offset scheme documentation, and SEC 10-K disclosures from publicly traded lessors. Bottom-up lease transaction aggregation and top-down fleet projection triangulation anchored market sizing.
Demand-supply-balance framing across the analysis window calibrated placement pipeline assumptions against manufacturer delivery slot allocations and airline fleet renewal cycles. Segmentation dimensions modeled include aircraft type, leasing model, end user category, and lease duration tier, with regional regulatory cluster as an additional aviation-specific dimension. CAGRs derived from lease rate factor trajectory analysis and residual value curve interpolation. Forecast inputs incorporated GTF engine adoption curves and EU F-Gas Regulation retrofit timelines.
Macroeconomic conditions sit as an overlay; deviation in central bank policy rates, aerospace-grade titanium pricing, or ICAO carbon offset enforcement stringency would shift the trajectory. Forecasts reflect documented assumptions regarding fleet renewal timelines and lessor capital availability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Middle East and Africa Aviation Market
Aircraft
North America Aircraft Band Clamps Market
Aircraft
Aviation Crew Management System Market
Aircraft
Aircraft Wheels Brakes Market
Aircraft
Aircraft Cables Market
Aircraft
Commercial Aircraft Overhead Stowage Bins Market
Aircraft
Australia Aviation Market
Aircraft
Aircraft Seals Market
Aircraft
Asia-Pacific Helicopters Market
Aircraft
Helicopter Flight Control Systems Market
Aircraft
Europe Business Jet Market
Aircraft
Japan Aircraft Windshield Wiper and Washer System Market
Aircraft
Asia-Pacific Aircraft Manufacturing Market
Aircraft
Commercial Aircraft Fadec Market
Aircraft
Global Aircraft Heat Exchanger Market
Aircraft
Global Aircraft Design and Engineering Market