
 Iran Insulin Drugs and Delivery Devices Market | 2026-2036
Iran Insulin Drugs and Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Iran Insulin Drugs and Delivery Devices Market Insights
Biosimilar-grade insulin formulations is bifurcating the competitive landscape between originator multinationals and emerging local manufacturers. Novo Nordisk A/S leverages its recombinant DNA manufacturing heritage to sustain premium positioning in rapid-acting analogs. Sanofi anchors the long-acting segment through basal insulin portfolios distributed via hospital procurement channels. Eli Lilly and Company differentiates through concentrated insulin formulations serving severe insulin resistance populations in tertiary care centers.
Iran Insulin Drugs and Delivery Devices encompasses recombinant human insulin and insulin analogs formulated for subcutaneous, intravenous, or inhalation delivery, typically stabilized at pH 6.9–7.8 with zinc hexamer complexes to ensure pharmacokinetic predictability across temperature-variable storage conditions. The category serves glycemic control in Type 1 and Type 2 diabetes mellitus, with delivery precision directly correlating to HbA1c outcomes and complication reduction. Long-acting insulin occupies the largest revenue pool due to once-daily dosing adherence advantages, while insulin delivery pens represent the fastest-growing format as home care protocols expand beyond hospital settings. Rapid-acting insulin competes intensely in perioperative and gestational diabetes applications where meal-time glucose excursions require tight correction.
Iran's Food and Drug Administration (IFDA) regulates insulin import licensing and cold chain certification, directly constraining which formulations enter the market and at what batch-release cadence. The Ministry of Health's universal health insurance framework shapes demand through reimbursement tiers that favor domestic biosimilars over imported originator products. The Atomic Energy Organization of Iran's radioisotope infrastructure indirectly supports local peptide synthesis capabilities relevant to insulin precursor production. Stakeholders must monitor how IFDA bioequivalence requirements evolve for pen injector interchangeability and whether home care reimbursement expansions accelerate pump adoption against disposable syringe dominance.
Market Dynamics
IFDA import licensing constraints are compressing cold chain certification timelines, forcing distributors to consolidate warehousing partnerships around Tehran's pharmaceutical logistics clusters while provincial hospitals accelerate biosimilar procurement.
Growth Catalysts
- Universal Health Insurance Reimbursement Tiers:The Ministry of Health's preferential coverage for domestic biosimilars is redirecting procurement volumes toward local manufacturing partnerships.
- Tehran Endocrinology Center Expansion:Satellite referral networks in Mashhad and Isfahan are extending hospital-based diabetes management protocols into outpatient settings.
- Radioisotope Peptide Synthesis Infrastructure:The Atomic Energy Organization of Iran's technical capabilities are shortening precursor production lead times for recombinant insulin manufacturing.
Market Restraints
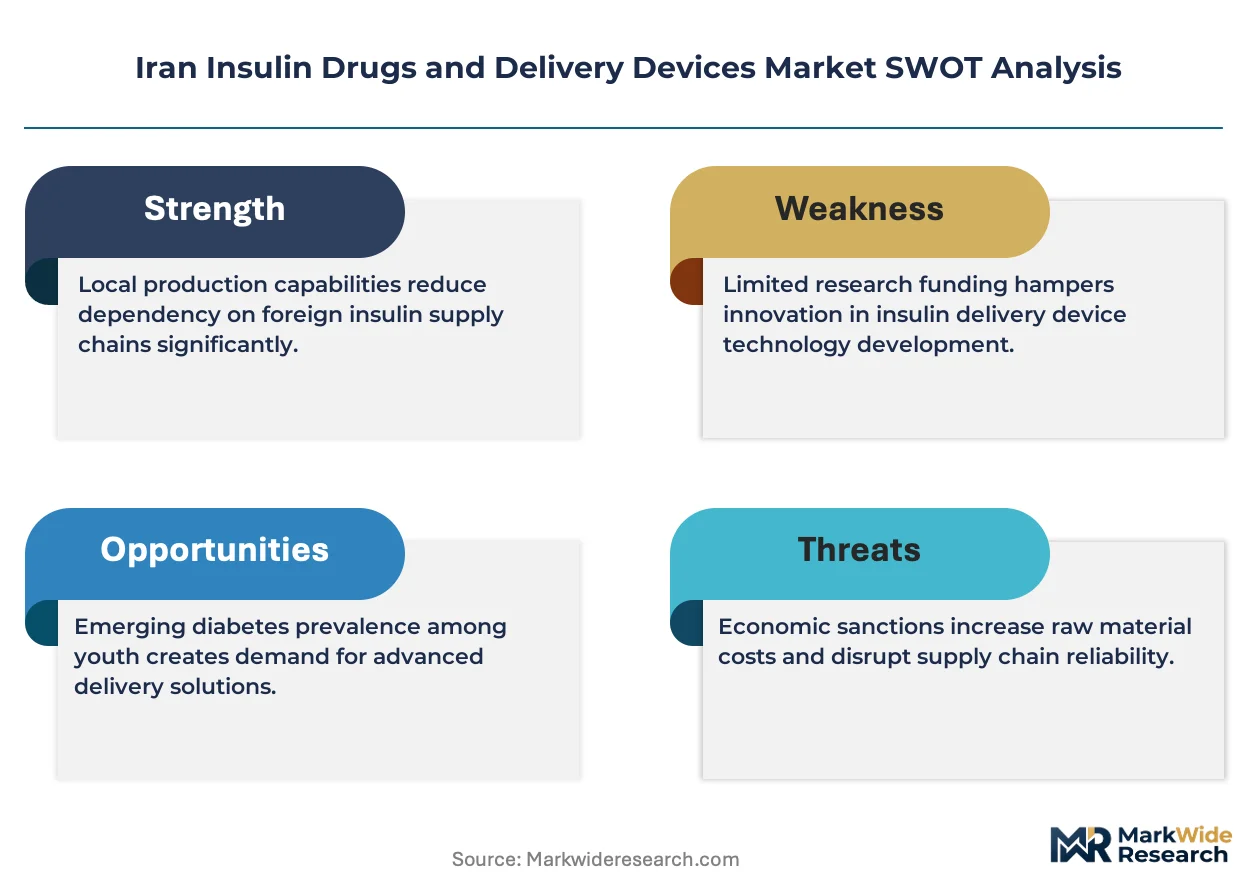
- Cold Chain Input Cost Volatility:Refrigerated transport and zinc hexamer stabilization materials face price instability due to sanctions-compressed import channels.
- Originator Supply Concentration:European and North American multinationals control rapid-acting analog formulations, creating dependency risk for tertiary care centers.
- IFDA Batch-Release Friction:Extended bioequivalence documentation requirements delay pen injector interchangeability approvals.
Strategic Opportunities
- Home Care Channel Penetration:Disposable insulin delivery pens are capturing volume from hospital-administered syringes as self-monitoring protocols expand.
- Concentrated Insulin Formulations:Severe insulin resistance populations in tertiary centers require U-500 and U-1000 analogs currently undersupplied.
- Provincial Health Network Integration:Rural clinic partnerships in Kermanshah and Tabriz remain underpenetrated for long-acting basal insulin distribution.
Industry Challenges
- Peptide Synthesis Talent Scarcity:Recombinant DNA process engineering expertise concentrates in Tehran's biotechnology institutes, constraining regional production scale-up.
- Legacy Syringe System Integration:Hospital procurement systems optimized for vial-and-syringe workflows resist pen injector and pump technology migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iran Insulin Drugs and Delivery Devices Market |
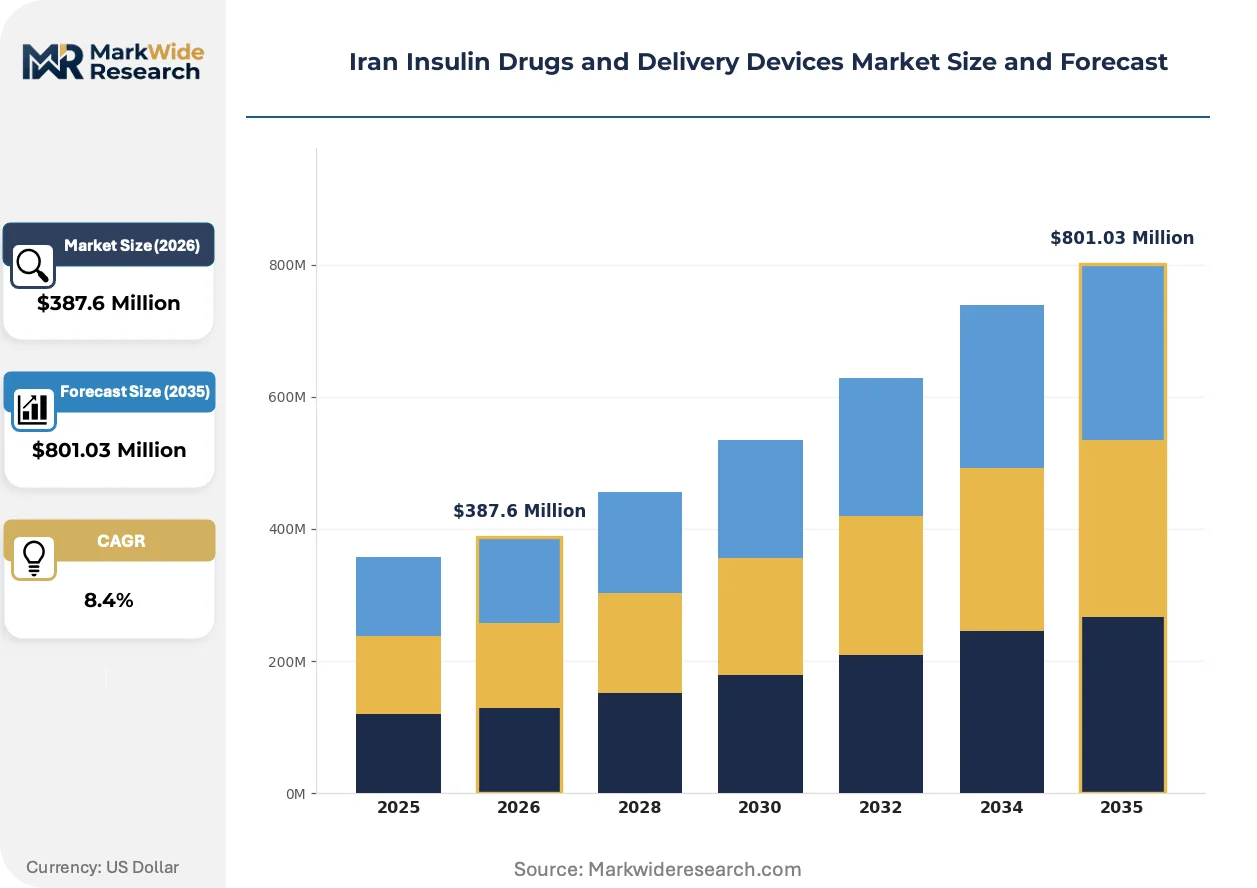
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $801.03 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid-Acting Insulin, Long-Acting Insulin, Premixed Insulin, Insulin Delivery Pens End User: Hospitals, Clinics, Home Care, Pharmacies Formulation: Injectable, Inhalable, Micro-needles, Patch Delivery Method: Vial, Pen Injector, Pump, Disposable Syringe |
| Companies Covered | Novo Nordisk A/S, Sanofi, Eli Lilly and Company, Gan & Lee Pharmaceuticals, Medtronic, Becton Dickinson and Company, Biocon, Abbott Laboratories, Roche Diagnostics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iran Insulin Drugs and Delivery Devices Market Trends and Innovations
Delivery format diversification is compressing traditional device categories while regulatory pressure on interchangeability standards accelerates formulation innovation.
Connected pen injector technology is fragmenting the conventional distinction between disposable and reusable delivery systems. Tertiary care centers in Tehran are piloting Bluetooth-enabled dose-logging devices that sync with electronic health records. This convergence of drug delivery and data capture is fragmenting procurement decisions across separate IT and pharmacy budgets.
IFDA bioequivalence guidelines for pen injector interchangeability are tightening documentation requirements for pharmacokinetic matching studies. Local manufacturers must now submit extended stability data under temperature-variable storage conditions. The long-acting insulin segment faces the steepest compliance burden as basal analogs require 24-hour glucose clamp validation protocols.
Home care protocols are displacing hospital-centered administration as the default diabetes management model. Provincial health networks now train community health workers in pen injector technique, shifting reimbursement toward outpatient pharmacy channels. This transition is most visible in Isfahan's integrated care pilot, where satellite clinics manage Type 2 titration without tertiary referral.
Iran Insulin Drugs and Delivery Devices Market Segmentation
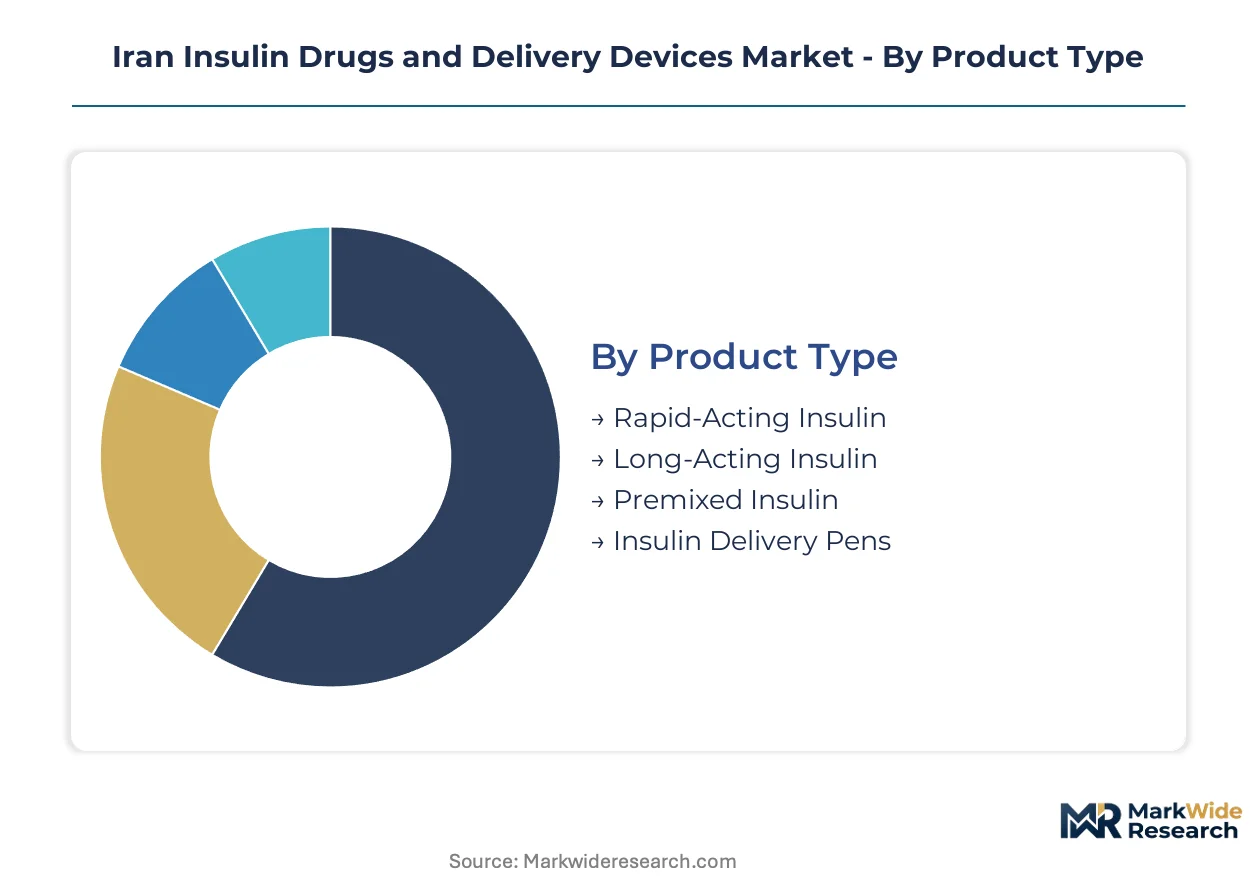
Segmentation in Iran's insulin market reveals how IFDA reimbursement tiers and cold chain constraints reshape competitive positioning across formulation types. Each dimension carries distinct margin implications as hospital procurement yields to home care channels.
Product Type:
Margin pools concentrate in analog formulations where biosimilar substitution lags and originator pricing holds.
- Rapid-Acting Insulin:Ultra-short onset analogs formulated with insulin lispro or aspart achieve peak plasma concentration within 60-90 minutes. Tehran's specialized endocrinology centers drive demand for perioperative and gestational diabetes protocols where tight glucose excursion control is non-negotiable. IFDA batch-release friction for pen injector interchangeability constrains local manufacturer entry.
- Long-Acting Insulin:Basal analogs utilizing insulin glargine or detemir provide 24-hour pharmacokinetic coverage with once-daily dosing. Provincial health networks in Mashhad and Isfahan prioritize this segment for outpatient titration programs. The segment commands premium reimbursement positioning under universal health insurance tiers.
- Premixed Insulin:Fixed-ratio combinations of neutral protamine Hagedorn and regular insulin simplify dosing for Type 2 populations with limited self-monitoring capacity.
- Insulin Delivery Pens:Disposable and reusable pen injector systems integrate dose-dialing mechanisms with 3mL cartridge standardization.
Long-acting insulin holds installed capacity. Insulin delivery pens is rotating up the share rankings.
End User:
Channel economics diverge sharply between centralized hospital procurement and fragmented retail pharmacy distribution.
- Hospitals:Tertiary care centers in Tehran manage severe insulin resistance cases requiring concentrated U-500 formulations and intravenous protocols. These institutions anchor originator multinationals' volume commitments through multi-year tender structures.
- Home Care:Self-administration protocols are expanding fastest as provincial networks train community health workers in pen injector technique. Isfahan's integrated care pilot demonstrates Type 2 titration without tertiary referral, shifting reimbursement toward outpatient pharmacy channels.
- Clinics:Satellite referral networks extend diabetes management protocols from Tehran's endocrinology centers into secondary cities.
- Pharmacies:Retail distribution points face working capital constraints from cold chain maintenance requirements and IFDA import licensing delays.
Hospitals retain originator contract concentration. Home care is climbing the fastest.
Formulation:
Technology maturity curves separate established injectable platforms from experimental delivery modalities.
- Injectable:Subcutaneous delivery via vial, pen, or pump dominates volume. Zinc hexamer stabilization at pH 6.9-7.8 ensures pharmacokinetic predictability across Iran's temperature-variable storage conditions.
- Inhalable:Pulmonary insulin delivery via dry powder inhaler eliminates injection burden but faces IFDA respiratory safety documentation requirements.
- Micro-needles:Dissolving microneedle arrays promise pain reduction and cold chain elimination through solid-state formulation.
- Patch:Transdermal iontophoretic or chemical penetration enhancer systems remain pre-commercial in Iranian regulatory pathways.
Injectable holds installed capacity. Micro-needles is rotating up the share rankings.
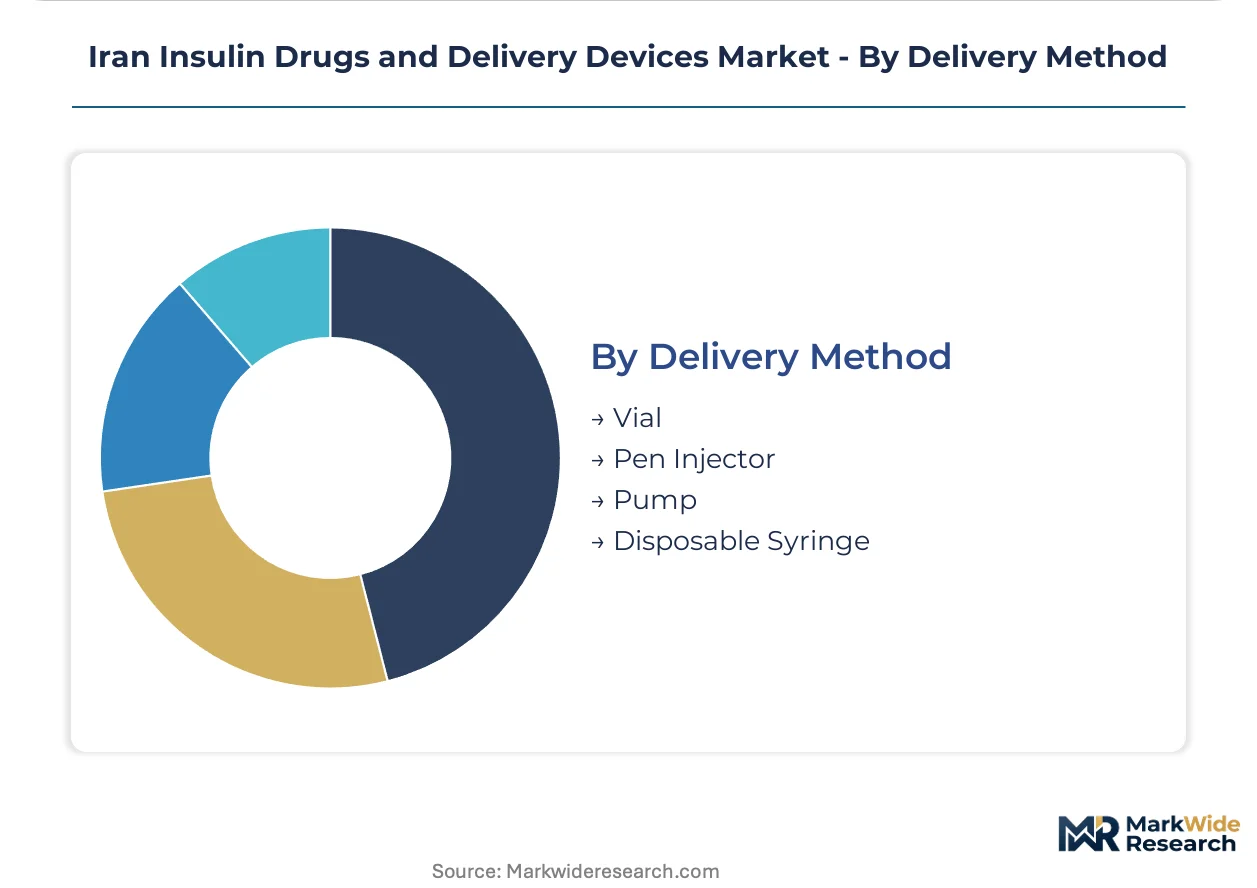
Delivery Method:
Device format selection directly determines patient adherence outcomes and HbA1c trajectory.
- Pen Injector:Disposable and reusable systems with dose memory and Bluetooth connectivity are capturing volume from hospital-administered syringes. Tehran tertiary centers pilot dose-logging devices syncing with electronic health records.
- Pump:Continuous subcutaneous insulin infusion systems serve Type 1 populations requiring basal-bolus automation. Reimbursement expansion debates center on whether home care protocols will accelerate pump adoption.
- Vial:10mL multi-dose containers remain procurement-optimized for high-volume hospital settings with pharmacy compounding workflows.
- Disposable Syringe:Legacy U-100 and U-40 syringe systems face resistance from pen injector migration but persist in cost-sensitive provincial allocations.
Vial holds installed capacity. Pen injector is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iran's insulin market operates under chronic import dependency, with domestic biosimilar production expanding to offset foreign exchange constraints on originator imports. Provincial health networks now drive distribution geography.
Tehran Province
Tehran's specialized endocrinology centers generate concentrated demand for rapid-acting analogs in perioperative and gestational diabetes protocols. IFDA batch-release certification for cold chain imports funnels through Imam Khomeini Hospital's pharmaceutical logistics cluster. The Shahr-e-Qods biotechnology corridor hosts recombinant DNA process engineering talent pools that supply precursor synthesis to local manufacturers.
Khorasan Razavi Province
Mashhad's satellite referral clinics extend hospital-based diabetes management into outpatient settings with emphasis on long-acting basal insulin titration. The Ministry of Health's universal health insurance framework channels reimbursement preferentially toward domestic biosimilars in this province. Mashhad Medical University anchors provincial training programs for community health worker pen injector certification.
Isfahan Province
Isfahan's integrated care pilot demonstrates Type 2 diabetes management without tertiary referral, shifting volume toward home care channels. Provincial health network procurement now favors disposable insulin delivery pens over legacy vial-and-syringe systems. The Isfahan University of Medical Sciences coordinates satellite clinic partnerships across rural districts in Kashan and Najafabad.
East Azerbaijan Province
Tabriz remains underpenetrated for long-acting insulin distribution despite elevated Type 2 prevalence in aging industrial worker populations. The provincial health network faces working capital constraints from cold chain maintenance requirements and IFDA import licensing delays. Tabriz University of Medical Sciences is expanding community health worker deployment to reduce tertiary center referral burdens.
Kermanshah Province
Kermanshah's rural clinic network presents untapped opportunity for basal insulin outpatient protocols as home care reimbursement expands. The Atomic Energy Organization of Iran's regional radioisotope infrastructure indirectly supports peptide synthesis capabilities relevant to local manufacturing partnerships. Kermanshah University of Medical Sciences pilots self-monitoring training programs in district health houses.
Iran Insulin Drugs and Delivery Devices Market Competitive Landscape
Listed multinationals compete with private specialists across formulation tiers and delivery device categories. The market structure concentrates around three to four originator firms controlling rapid-acting analog supply, while emerging local manufacturers capture share in long-acting biosimilars through Ministry of Health procurement preferences. Strategic archetypes include recombinant DNA heritage multinationals, regional biosimilar specialists, and medical device technology licensors. Competitive moves center on hospital tender consolidation and local production joint ventures to navigate IFDA import licensing constraints.
Among recombinant DNA heritage multinationals, Novo Nordisk A/S and Sanofi occupy positions exemplifying premium rapid-acting and long-acting formulation strategies respectively. Eli Lilly and Company represents the concentrated insulin formulation archetype serving severe insulin resistance populations in tertiary care centers. Gan & Lee Pharmaceuticals anchors the regional biosimilar specialist tier alongside Biocon, both exemplifying manufacturing partnerships accelerated by Iran's import substitution policies. Medtronic and Becton Dickinson and Company sit within the delivery device technology layer where pen injector and pump system innovation intersects with IFDA interchangeability requirements.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Sanofi |
| Eli Lilly and Company |
| Gan & Lee Pharmaceuticals |
| Medtronic |
| Becton Dickinson and Company |
| Biocon |
| Abbott Laboratories |
| Roche Diagnostics |
| Others |
Pricing and Supply Chain Analysis
Long-term hospital tender contracts lock in multi-year insulin supply commitments for Tehran's tertiary care centers, anchoring price visibility against volatile import licensing timelines and cold chain input fluctuations. These structured procurement agreements concentrate purchasing power within the Ministry of Health's universal health insurance framework, compressing margin flexibility for distributors while securing originator analog access for specialized endocrinology protocols.
Pricing Analysis
Hospital procurement committees anchor a three-tier pricing structure across premium originator analogs, standard biosimilars, and economy-grade human insulin. Price differentiation rests on IFDA bioequivalence certification tier and cold chain compliance grade, with rapid-acting formulations commanding premium positioning due to batch-release scarcity. Cost compression in the biosimilar tier is intensifying because local manufacturers absorb zinc hexamer stabilization material volatility. Retail pharmacy channels exhibit highest price sensitivity, while tertiary care centers prioritize supply security over unit cost.
Supply Chain Analysis
Port congestion along Bandar Abbas pharmaceutical logistics corridors elevates inbound costs for temperature-controlled insulin imports originating from European and Indian manufacturing hubs. Supply concentration draws from Denmark, France, and India for originator formulations, while recombinant DNA precursor synthesis feeds from Iran's domestic Shahr-e-Qods biotechnology corridor. Single-source vulnerability permeates rapid-acting analog supply, with European multinationals controlling proprietary lispro and aspart production. Distribution runs through Tehran's Imam Khomeini Hospital pharmaceutical cluster before provincial satellite network dispersal.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected pen injector technology convergence with electronic health record integration creates a regulatory inflection point, accelerating reimbursement shifts from hospital-administered vials toward outpatient self-monitoring protocols. This technological disruption compounds with IFDA interchangeability guideline tightening to reshape competitive entry barriers.
For Market Incumbents: Shield rapid-acting analog market share through accelerated pen injector bioequivalence dossier submissions ahead of IFDA documentation deadline tightening. Secure backward integration into recombinant DNA precursor synthesis via Atomic Energy Organization of Iran partnership structures to offset import licensing friction. Defend against local biosimilar encroachment by anchoring concentrated U-500 formulation exclusivity in tertiary care tenders. For New Entrants and Emerging Players: Community health worker training service gaps in Kermanshah and East Azerbaijan provincial networks present white-space entry vectors where originator multinationals under-serve rural clinic infrastructure. Target long-acting basal insulin distribution partnerships with district health houses bypassing Tehran-centric logistics clusters. Pursue go-to-market alignment with Ministry of Health import substitution policy incentives for domestic manufacturing joint ventures. For Investors and Strategic Acquirers: Regional biosimilar specialists with established IFDA cold chain certification and radioisotope peptide synthesis capabilities represent acquisition target archetypes positioned for universal health insurance reimbursement tier expansion. Long-term viability hinges on pen injector interchangeability approval velocity outpacing originator patent lifecycle extension strategies. Monitor IFDA batch-release cadence acceleration as inflection signal for biosimilar market share inflection.| Strategic Initiative | Industry Significance |
|---|---|
| IFDA Bioequivalence Dossier Advancement | Accelerates pen injector interchangeability approval timelines against originator defense strategies. |
| Domestic Precursor Synthesis Scale-Up | Reduces import dependency for recombinant DNA manufacturing through Atomic Energy Organization partnerships. |
| Provincial Health Network Integration | Extends long-acting insulin distribution into Kermanshah and Tabriz rural clinic infrastructure. |
| Connected Pen Injector Development | Captures Bluetooth-enabled dose-logging demand from Tehran tertiary care EHR integration pilots. |
| Concentrated Formulation Portfolio Expansion | Serves severe insulin resistance populations in tertiary centers currently undersupplied with U-500 analogs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of IFDA regulatory filings, Ministry of Health procurement databases, and hospital formulary records, cross-validated through structured interviews with endocrinology department heads, pharmaceutical logistics managers, regulatory affairs specialists, and provincial health network procurement officers. Bottom-up patient volume modeling triangulates against top-down insulin consumption estimates from universal health insurance reimbursement claims data.
Segmentation dimensions modeled span product type (rapid-acting, long-acting, premixed, delivery devices), end user channel (hospitals, home care, clinics, pharmacies), formulation technology (injectable, inhalable, micro-needles), and delivery method (pen injector, pump, vial, syringe). CAGRs derive from patient population growth trajectories, reimbursement tier expansion rates, and biosimilar substitution elasticity parameters calibrated against historical analog market penetration patterns.
Underlying assumptions cover sustained IFDA import licensing throughput, universal health insurance reimbursement tier stability, and cold chain infrastructure maintenance capacity, with deviation risk concentrated in sanctions-compressed input material availability and pen injector interchangeability approval timeline slippage. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Somatropin Market
Biopharmaceuticals
Global Endocrinology Drugs Market
Biopharmaceuticals
Combination Antibody Therapy Market
Biopharmaceuticals
Global Staphylococcal Infection Drugs Market
Biopharmaceuticals
Global Swine Fever Vaccine Market
Biopharmaceuticals
NF-KB Inhibitors Market
Biopharmaceuticals
Europe Monoclonal Antibodies Market
Biopharmaceuticals
Rivaroxaban Market
Biopharmaceuticals
Benzbromarone API Market
Biopharmaceuticals
Progesterone Market
Biopharmaceuticals
Europe Insulin Delivery Devices Market
Biopharmaceuticals
Human Combinatorial Antibody Libraries (Hucal) Market
Biopharmaceuticals
Amphotericin B Market
Biopharmaceuticals
Linaclotide API Market
Biopharmaceuticals
Brazil Generic Drug Market
Biopharmaceuticals
Global Oncology/Cancer Drugs Market