
 Cardiac Assist Devices Market | 2026-2036
Cardiac Assist Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Assist Devices Market Intelligence
Hospital-based procurement is bifurcating from cardiology clinic purchasing as high-acuity patients require prolonged mechanical circulatory support. Abbott Laboratories dominates durable ventricular assist device platforms through its HeartMate product architecture. Medtronic PLC competes with centrifugal flow pump designs that reduce thrombogenicity profiles. Berlin Heart GmbH specializes in pediatric mechanical support systems for bridge-to-transplant indications.
Cardiac assist devices comprise electromechanical pumps, cannulation systems, and control consoles designed to supplement or replace native cardiac output, typically operating at flow rates between 5 and 10 liters per minute depending on patient hemodynamic status. Ventricular assist devices represent the largest installed base segment due to established reimbursement for destination therapy and bridge-to-transplant protocols. Extracorporeal membrane oxygenation is expanding fastest among percutaneous configurations deployed in catheterization laboratories for acute cardiogenic shock. Total artificial heart systems occupy a narrow but high-margin niche constrained by surgical complexity and donor organ allocation dynamics.
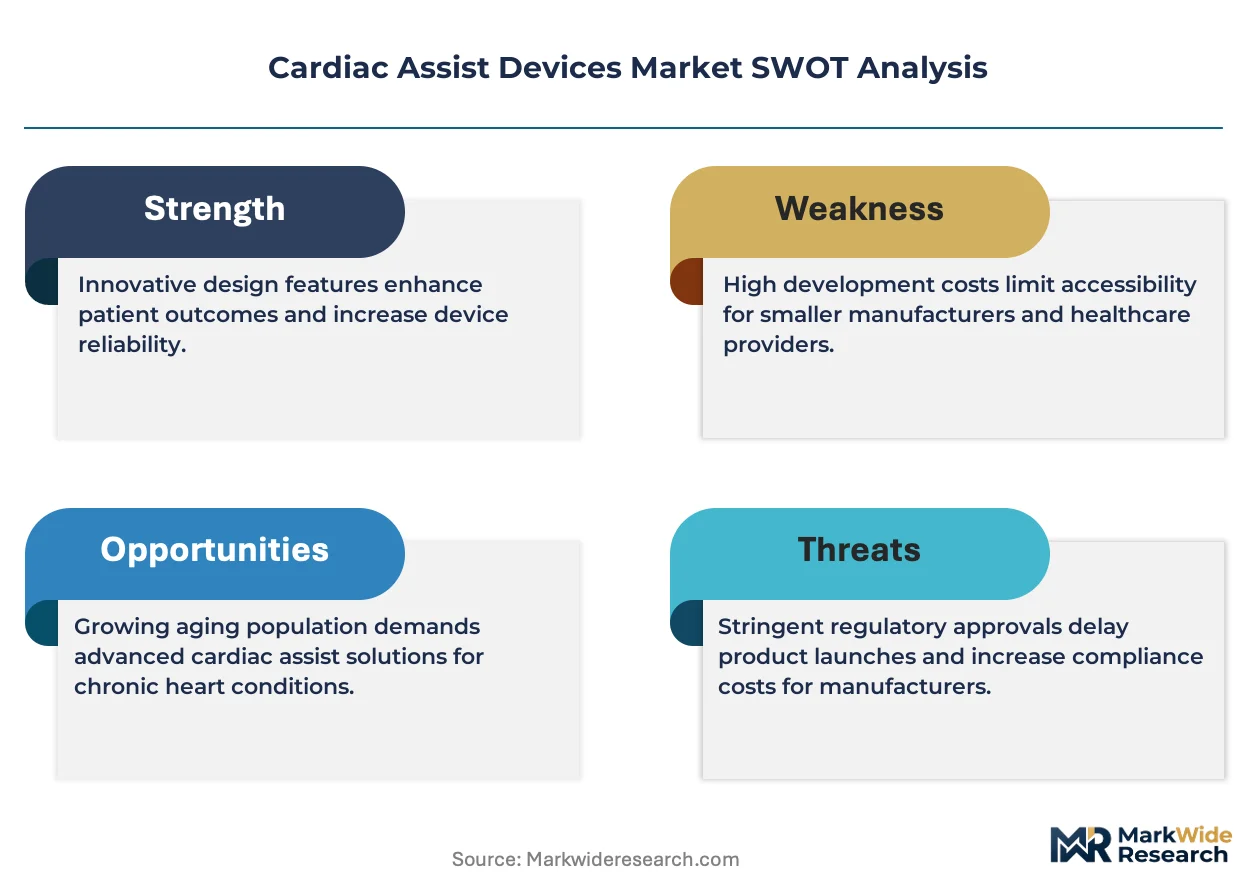
FDA premarket approval and EU MDR notified body conformity assessments impose extensive clinical trial obligations on mechanical circulatory support manufacturers. Japan's PMDA requires separate domestic investigational studies for implantable cardiac assist platforms, fragmenting regulatory approval timelines across major markets. Stakeholders must monitor evolving CMS reimbursement determinations for outpatient VAD management and EU F-Gas Regulation implications for device sterilization supply chains.
Market Dynamics
Hospital procurement committees now prioritize hemocompatibility metrics over legacy flow specifications, compressing vendor qualification timelines and elevating centrifugal pump architectures over axial designs in tender evaluations.
Growth Catalysts
- Destination Therapy Reimbursement:CMS coverage determinations in the United States have expanded Medicare eligibility for long-term ventricular assist device implantation beyond bridge-to-transplant protocols.
- Aging Demographics:Japan's super-aged population profile generates sustained demand for durable mechanical circulatory support as heart failure incidence rises among patients ineligible for cardiac transplantation.
- EU MDR Harmonization:Streamlined conformity assessment pathways for active implantable medical devices reduce redundant clinical testing burdens across European notified body jurisdictions.
Market Restraints
- Biocompatible Polymer Costs:Specialized medical-grade polycarbonate urethanes for pump housings face price volatility tied to petrochemical feedstock fluctuations.
- Single-Source Sterilization:Ethylene oxide sterilization capacity concentrates in contract facilities clustered around Frankfurt and Minneapolis, creating geographic supply vulnerability.
- Battery Chemistry Limitations:Lithium-ion cell energy density constraints restrict patient mobility and mandate frequent transcutaneous power transfers.
Strategic Opportunities
- Pediatric Mechanical Support:Bridge-to-transplant indications for adolescent patients remain underserved relative to adult populations, with specialized cannulation systems commanding premium positioning.
- Catheterization Laboratory Deployment:Percutaneous ventricular assist configurations enable acute cardiogenic shock intervention without sternotomy, opening interventional cardiology channels.
- Japanese Domestic Trials:PMDA requirements for separate investigational studies create first-mover advantages for manufacturers establishing local clinical evidence portfolios.
Industry Challenges
- Biomedical Engineering Talent:Specialized expertise in computational fluid dynamics for blood-handling surfaces remains concentrated among academic medical centers and select device manufacturers.
- Regulatory Documentation Burden:FDA premarket approval submissions for novel pump designs require extensive thrombogenicity testing protocols that extend development timelines.
- Legacy System Interoperability:New control console architectures must maintain backward compatibility with implanted pumps from prior device generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Assist Devices Market |
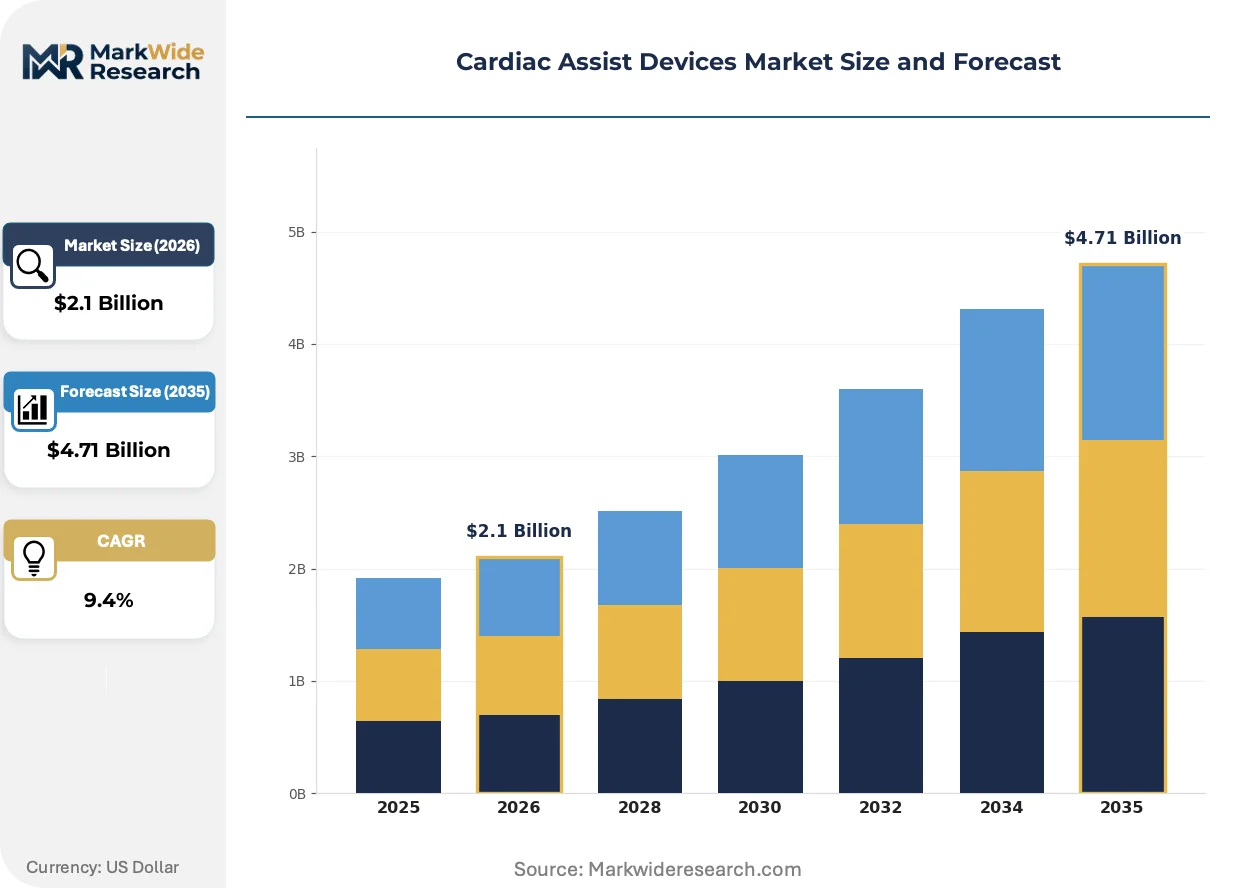
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.71 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intra-aortic Balloon Pump, Ventricular Assist Device, Total Artificial Heart, Extracorporeal Membrane Oxygenation End User: Cardiology Clinics, Hospitals, Outpatient Centers, Home Care Settings Technology: Mechanical Circulatory Support, Percutaneous Devices, Biomaterials, Sensors Application: Heart Failure, Myocardial Infarction, Cardiogenic Shock, Post-Surgical Support |
| Companies Covered | Abbott Laboratories, Medtronic PLC, Teleflex Incorporated, Berlin Heart GmbH, Getinge AB, Terumo Corporation, Abiomed, LivaNova PLC, Jarvik Heart, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Assist Devices Market Strategic Shifts & Innovations
Magnetic levitation bearings and fully magnetically suspended rotors are redefining hemocompatibility benchmarks, eliminating mechanical wear surfaces that historically generated thromboembolic complications.
Centrifugal flow pump technology with magnetically levitated impellers is supplanting axial-flow designs in hospital procurement specifications. Transplant centers in Germany and the United States now mandate levitated bearing systems in durable VAD tenders. This architectural shift compresses market positioning for manufacturers dependent on mechanical bearing platforms.
EU F-Gas Regulation phase-down schedules are forcing sterilization process revalidation across European manufacturing facilities. Ethylene oxide alternatives including nitrogen dioxide and vaporized hydrogen peroxide gain regulatory traction. German notified bodies lead conformity assessment precedent for novel sterilization modalities in active implantable device production.
Catheterization laboratory purchasing committees now source percutaneous mechanical circulatory support through bundled procedure contracts rather than capital equipment acquisition. Interventional cardiologists in Japan and the United States favor rental-per-case models for temporary ventricular assist configurations. This consumption pattern shift elevates service infrastructure capabilities over device manufacturing scale in vendor selection criteria.
Cardiac Assist Devices Market Segmentation
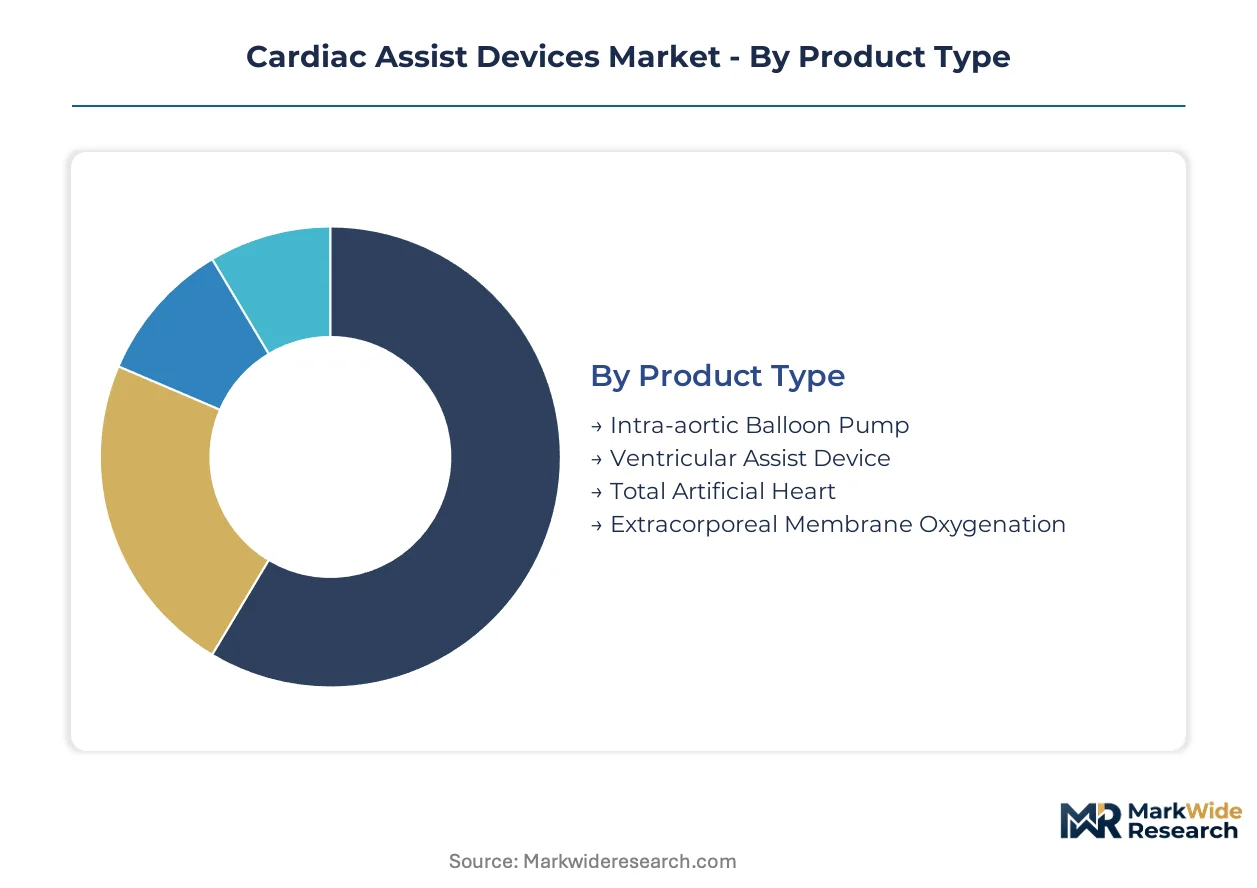
Segmentation in cardiac assist devices reveals distinct procurement patterns across acute versus chronic care settings. Hospital purchasing committees evaluate hemocompatibility metrics differently than outpatient clinic administrators, while regulatory pathways fragment by implant duration and invasiveness.
Product Type:
Ventricular assist devices and intra-aortic balloon pumps dominate domestic hospital procurement in the United States and Germany, whereas total artificial heart systems concentrate in specialized transplant centers with established bridge-to-transplant protocols.
- Ventricular Assist Device:Electromechanical pumps supplementing native ventricular function through continuous or pulsatile flow architectures. Demand concentrates in United States transplant centers where CMS reimbursement for destination therapy has matured beyond bridge-to-transplant indications; centrifugal flow designs with magnetically levitated impellers now displace axial configurations in tender specifications.
- Extracorporeal Membrane Oxygenation:Integrated pump-oxygenator systems providing both cardiac and respiratory support through percutaneous or central cannulation. Japanese catheterization laboratories drive percutaneous configuration adoption for acute cardiogenic shock intervention; bundled procedure contracts favor rental-per-case models over capital acquisition.
- Intra-aortic Balloon Pump:Counterpulsation devices augmenting coronary perfusion through balloon inflation synchronized with cardiac cycle.
- Total Artificial Heart:Biventricular replacement systems occupying narrow surgical niche constrained by anatomical fit requirements and donor organ allocation dynamics.
Ventricular assist devices hold the largest share; momentum sits with extracorporeal membrane oxygenation configurations.
End User:
Cost tier differentiation separates capital-intensive hospital implantation from recurring outpatient management revenue streams.
- Hospitals:Acute care facilities with cardiac surgery programs and heart transplant capabilities. Procurement committees in German university hospitals and United States academic medical centers prioritize hemocompatibility metrics over legacy flow specifications; centrifugal pump architectures with magnetic levitation bearings now dominate durable VAD tenders.
- Cardiology Clinics:Specialized outpatient facilities managing chronic heart failure patients. Japanese cardiology clinics in Tokyo and Osaka generate sustained demand for VAD patient monitoring services; PMDA reimbursement frameworks for outpatient mechanical circulatory support management are expanding eligibility criteria.
- Outpatient Centers:Ambulatory surgical facilities performing percutaneous device implantation.
- Home Care Settings:Patient residence environments requiring portable power systems and caregiver training protocols.
Hospitals capture the dominant revenue position; outpatient centers are climbing the fastest as interventional cardiology channels expand.
Technology:
Volume concentration in mechanical circulatory support contrasts with emerging sensor integration for real-time hemodynamic monitoring.
- Mechanical Circulatory Support:Pump-based systems replacing or supplementing native cardiac output through extracorporeal or implantable configurations. United States manufacturing clusters around Minneapolis and German production facilities near Frankfurt supply centrifugal flow platforms; EU MDR conformity assessments for active implantable devices impose extensive clinical evidence requirements.
- Percutaneous Devices:Catheter-delivered systems enabling mechanical support without sternotomy. Demand concentrates in Japanese and United States catheterization laboratories where interventional cardiologists favor temporary configurations for acute cardiogenic shock; rental-per-case commercial models displace traditional capital equipment purchasing.
- Biomaterials:Blood-contacting surfaces including medical-grade polycarbonate urethanes and heparin coatings.
- Sensors:Hemodynamic monitoring components enabling pump speed modulation and thrombosis detection.
Mechanical circulatory support maintains installed base dominance; percutaneous devices show steepest expansion trajectory.
Application:
Customer type stratification separates emergency intervention from elective chronic disease management.
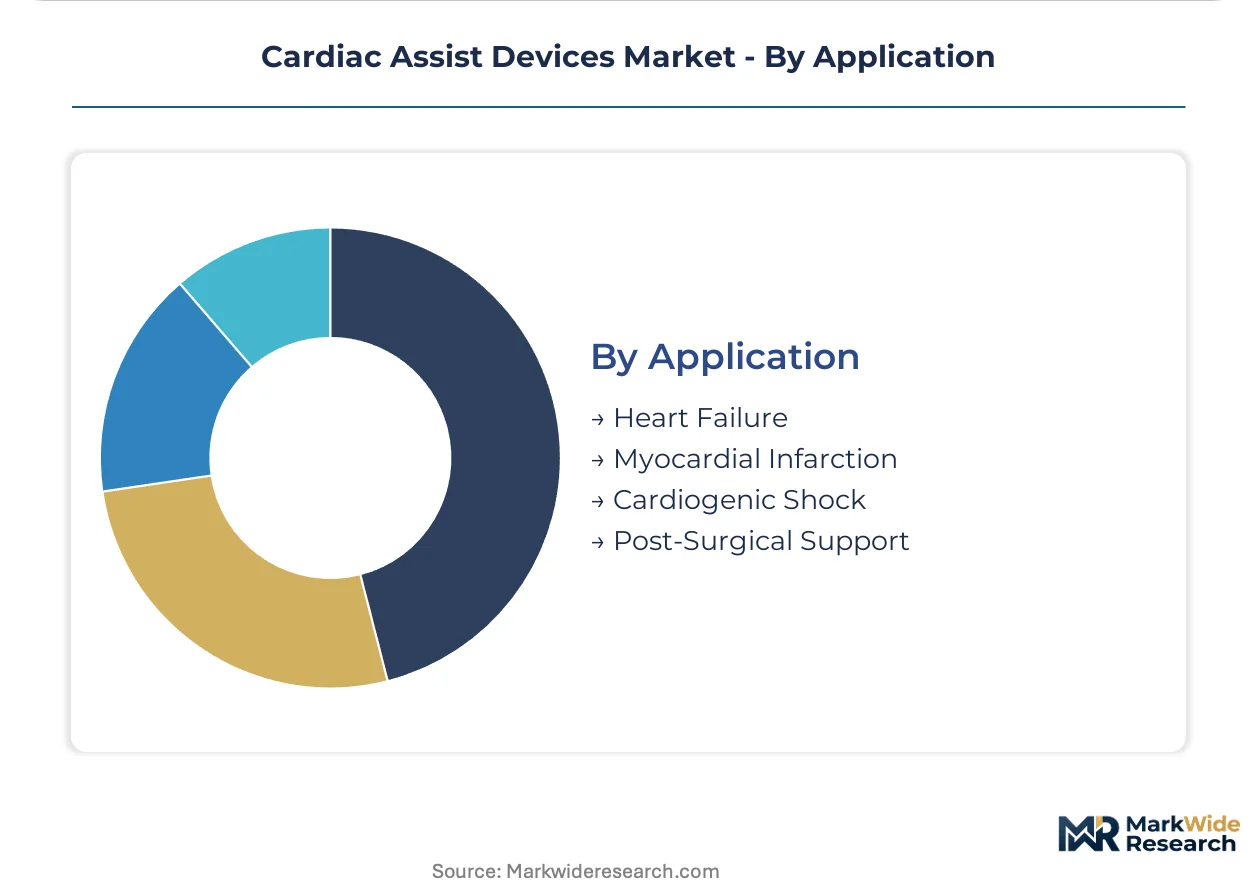
- Heart Failure:Chronic pump dysfunction requiring durable mechanical support or transplant candidacy evaluation. United States Medicare coverage determinations have expanded destination therapy eligibility beyond bridge-to-transplant protocols; aging demographics in Japan generate sustained demand for long-term ventricular assist device implantation.
- Cardiogenic Shock:Acute circulatory collapse requiring temporary mechanical support. German and United States emergency departments deploy percutaneous ventricular assist configurations for rapid stabilization; catheterization laboratory purchasing committees source through bundled procedure contracts.
- Myocardial Infarction:Acute coronary events with subsequent mechanical complications.
- Post-Surgical Support:Temporary circulatory assistance following cardiac surgery procedures.
Heart failure applications command the largest share; cardiogenic shock intervention is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturing clusters export centrifugal flow pump platforms to United States transplant centers, while Japanese catheterization laboratories import percutaneous configurations from Minneapolis-based production facilities.
United States
Medicare destination therapy coverage and aging heart failure populations drive procurement volumes. FDA premarket approval pathways impose extensive thrombogenicity testing on novel pump designs. Minneapolis-St. Paul manufacturing corridors concentrate HeartMate production and control console assembly operations.
Germany
University hospital procurement committees prioritize magnetically levitated bearing systems in durable VAD tenders. EU MDR conformity assessments and F-Gas Regulation sterilization requirements tighten clinical evidence standards. Frankfurt-area contract sterilization facilities cluster around ethylene oxide processing capacity.
Japan
Super-aged demographics generate sustained demand for long-term mechanical circulatory support among transplant-ineligible patients. PMDA requires separate domestic investigational studies, fragmenting approval timelines. Tokyo and Osaka cardiology clinics expand outpatient VAD management reimbursement eligibility.
United Kingdom
NHS England specialized commissioning frameworks concentrate total artificial heart implantation in established transplant centers. MHRA alignment with EU MDR post-Brexit maintains clinical evidence requirements. London academic medical centers participate in multinational mechanical circulatory support registries.
China
Rising heart failure incidence among urban aging populations expands hospital procurement budgets for ventricular assist devices. NMPA Class III medical device registration requires domestic clinical trials for implantable pumps. Shanghai and Beijing cardiac surgery programs develop indigenous centrifugal flow platforms.
Cardiac Assist Devices Market Key Industry Players
Player mix skews toward diversified medical technology conglomerates with active implantable device portfolios. Market structure concentrates around three durable VAD platforms with established destination therapy reimbursement. Strategic archetypes include full-line cardiovascular device manufacturers, specialized mechanical circulatory support pure-plays, and diversified critical care equipment suppliers. Competitive moves center on magnetic levitation technology licensing and catheterization laboratory service infrastructure expansion.
Among diversified cardiovascular device manufacturers, Abbott Laboratories and Medtronic PLC exemplify conglomerate-tier positioning through integrated pump-control console architectures. Berlin Heart GmbH occupies a specialist position in pediatric mechanical support systems. These three anchors illustrate the market's bifurcation between scale-driven platform consolidation and indication-specific segmentation.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic PLC |
| Teleflex Incorporated |
| Berlin Heart GmbH |
| Getinge AB |
| Terumo Corporation |
| Abiomed |
| LivaNova PLC |
| Jarvik Heart, Inc. |
| Others |
Cost & Logistics Intelligence
Ninety-day pump housing inventory cycles concentrate pricing power among polycarbonate urethane suppliers in the Frankfurt and Minneapolis manufacturing corridors, compressing margins for device assemblers while amplifying cost pass-through leverage for medical-grade polymer producers serving FDA and EU MDR compliance pathways.
Pricing Analysis
Centrifugal flow platforms with magnetically levitated impellers command 40-60% premiums over legacy axial-flow designs in United States hospital tenders. Pricing stratifies across premium levitated-bearing systems, standard mechanical-bearing configurations, and economy-grade intra-aortic balloon pumps. Cost compression in mechanical-bearing tiers is intensifying as German procurement committees mandate hemocompatibility specifications that disqualify older architectures. Cardiology clinics exhibit highest price sensitivity due to bundled reimbursement constraints, while transplant centers prioritize performance metrics over acquisition cost.
Supply Chain Analysis
Port congestion on transatlantic lanes from Rotterdam to Newark elevates inbound logistics costs for German-manufactured control consoles and pump assemblies destined for United States academic medical centers. Supply concentrates in Germany for centrifugal flow platforms, the United States for HeartMate production clusters, and Japan for PMDA-compliant component sourcing. Raw material dependencies center on medical-grade polycarbonate urethanes, lithium-ion battery cells, and ethylene oxide sterilization capacity. Single-source sterilization vulnerability clusters around Frankfurt-area contract facilities. Distribution runs through hospital procurement committees and GPO contracts in the United States, with direct manufacturer-to-transplant-center relationships dominating German university hospital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-entrenchment defensive moat. FDA premarket approval timelines and PMDA domestic trial requirements create structural barriers that compound incumbent advantages through clinical evidence accumulation.
For Market Incumbents: Compound market position by deepening backward integration into magnetically levitated bearing manufacturing and securing captive sterilization capacity ahead of EU F-Gas Regulation phase-downs. Threats from percutaneous device entrants in catheterization laboratory channels demand preemptive service infrastructure investments. Prioritize certification maintenance for destination therapy reimbursement eligibility.
For New Entrants and Emerging Players: CE marking fast-track pathways for active implantable devices offer the most penetrable entry vector for European market access. Target pediatric mechanical support systems in German and United States transplant centers where specialized cannulation needs remain underserved. Pursue hospital system partnership models that bundle device provision with clinical training protocols.
For Investors and Strategic Acquirers: Long-term, this sits as a demographic-trend play because super-aged population profiles in Japan and aging heart failure incidence in Western markets generate sustained demand elasticity. Acquisition targets should display magnetic levitation technology portfolios and established notified body relationships. Watch CMS reimbursement determinations for outpatient VAD management as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Levitation Technology Licensing | Abbott and Medtronic patent portfolios control hemocompatibility benchmarks that define tender specifications. |
| PMDA Domestic Trial Investment | Japanese regulatory requirements fragment approval timelines and reward first-movers with market exclusivity windows. |
| Catheterization Laboratory Service Infrastructure | Rental-per-case commercial models displace capital equipment purchasing and elevate vendor selection criteria toward clinical support capabilities. |
| Sterilization Process Revalidation | EU F-Gas Regulation compliance necessitates nitrogen dioxide and vaporized hydrogen peroxide alternatives with German notified body precedent. |
| Pediatric Cannulation System Development | Berlin Heart's specialized positioning demonstrates premium capture potential in bridge-to-transplant indications for adolescent patients. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with cardiac surgeons, hospital purchasing committee members, biomedical engineering directors, and GPO contracts managers; and secondary validation through FDA PMA filings, EMA MDR submission databases, CMS Medicare coverage determinations, and hospital procurement contract registries. Bottom-up installed base modeling and top-down reimbursement flow analysis were triangulated against manufacturer production disclosures.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, end user, technology platform, and application indication, with regional regulatory cluster overlays for FDA, EU MDR, and PMDA pathways. CAGRs were derived from patient population epidemiology, reimbursement expansion trajectories, and device replacement cycle assumptions. Forecast inputs incorporated magnetic levitation adoption curves and catheterization laboratory deployment rates.
Underlying assumptions cover destination therapy reimbursement stability, sterilization capacity continuity, and polymer feedstock price bands, with deviation risk concentrated in CMS policy shifts, EU F-Gas Regulation enforcement timing, and PMDA trial protocol modifications. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Epinephrine Auto-Injectors Market
Cardiovascular Devices
South Korea Cardiovascular Devices Market
Cardiovascular Devices
Cardiac Catheters Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
Fractional Flow Reserve-Computed Tomography (FFR-CT) Market
Cardiovascular Devices
Stent-Assisted Coiling Market
Cardiovascular Devices
Cardiogenic Shock Treatment Market
Cardiovascular Devices
Global Cardiac Output Monitoring Devices Market
Cardiovascular Devices
Global Transcranial Doppler Ultrasound Market
Cardiovascular Devices
Cardiovascular Catheter Market
Cardiovascular Devices
Canada Cardiovascular Devices Market
Cardiovascular Devices
China Vascular Grafts Market
Cardiovascular Devices
Cardiac Ablation Technologies Market
Cardiovascular Devices
Cardiac Medical Device Market
Cardiovascular Devices
Absorbable Heart Stent Market
Cardiovascular Devices
Self-Expanding Stents Market