
 Non-Steroidal Anti-Inflammatory Drugs (Nsaids) Market | 2026-2036
Non-Steroidal Anti-Inflammatory Drugs (Nsaids) Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Steroidal Anti-Inflammatory Drugs (Nsaids) Market Intelligence
Pharmaceutical manufacturing talent with expertise in continuous flow chemistry and green synthesis is rotating toward NSAID active pharmaceutical ingredient production, easing cost pressures on older synthetic routes. Pfizer Inc. leverages its integrated global manufacturing network to sustain bulk ketoprofen supply across multiple continents. Bayer AG anchors European distribution of diclofenac formulations through its established pharmacy and hospital channels. Sun Pharmaceutical Industries Ltd. competes on cost-engineered ibuprofen exports to emerging markets.
Non-steroidal anti-inflammatory drugs constitute a chemically diverse class of cyclooxygenase-inhibiting therapeutics, encompassing propionic acid derivatives, acetic acid derivatives, and enolic acid derivatives, with molecular weights typically ranging from 206 to 357 g/mol and oral bioavailability spanning 50% to almost complete absorption depending on specific agent and formulation. These agents function primarily as analgesic, antipyretic, and anti-inflammatory interventions across acute and chronic conditions. Ibuprofen and naproxen dominate over-the-counter revenue pools in retail pharmacy channels, while meloxicam captures expanding prescription volume in rheumatology and long-term orthopedics therapy. The hospital pharmacy segment maintains higher per-unit pricing for parenteral NSAID formulations administered in perioperative and emergency settings.
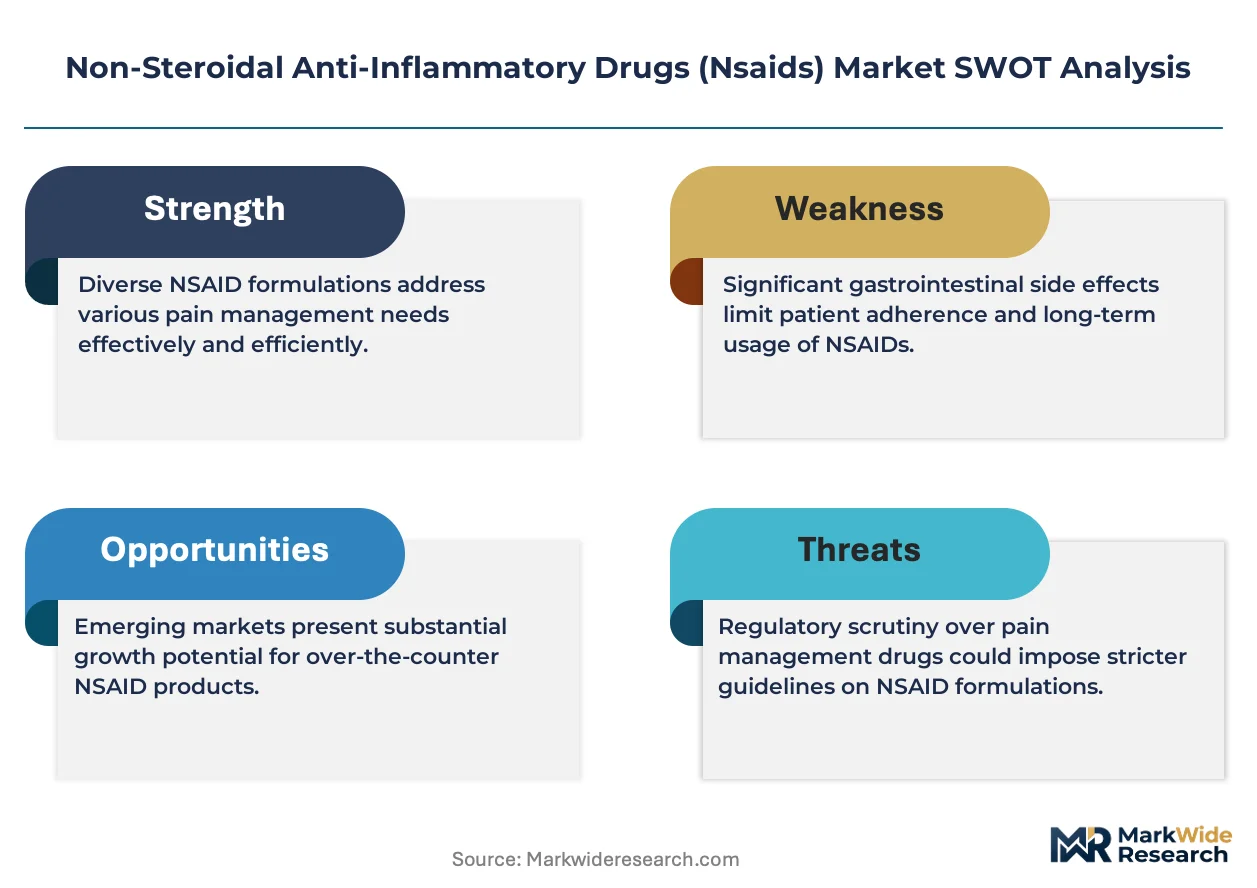
The FDA enforces cardiovascular and gastrointestinal risk evaluation and mitigation strategies for prescription-strength NSAIDs, directly influencing label claims and physician prescribing patterns. The EMA's Pharmacovigilance Risk Assessment Committee periodically reviews renal and hepatic safety signals, shaping formulary decisions across EU member state hospital systems. Stakeholders must monitor evolving cardiovascular outcome trial data and corresponding regulatory label revisions to anticipate shifts in preferred-agent status among prescriber specialties.
Market Dynamics
FDA cardiovascular risk labeling mandates are compressing prescription volumes for legacy NSAIDs while redirecting R&D investment toward gastroprotective formulations and selective COX-2 inhibitors.
Growth Catalysts
- Aging Demographics:Japan's super-aged population sustains chronic pain medication volumes, with rheumatology and orthopedics driving hospital formulary expansion.
- REACH Green Chemistry Incentives:European manufacturers adopt continuous flow synthesis for ketoprofen and naproxen to reduce solvent waste and energy intensity.
- Topical Formulation Advances:Transdermal diclofenac patches capture perioperative pain management share from oral generics in German and US hospital systems.
Market Restraints
- API Supply Concentration:China dominates ibuprofen and naproxen intermediate production, exposing formulators to export license volatility and freight cost spikes.
- Cardiovascular Black-Box Requirements:FDA-mandated warnings for prescription NSAIDs constrain physician prescribing in coronary artery disease populations.
- Biologic Substitution:TNF-alpha inhibitors and IL-6 pathway blockers displace NSAIDs in refractory rheumatoid arthritis maintenance therapy.
Strategic Opportunities
- Fixed-Dose Combinations:Proton pump inhibitor-NSAID co-formulations address EMA gastrointestinal safety concerns while extending patent protection.
- Hospital Parenteral Expansion:IV ketorolac and diclofenac formulations command premium pricing in US ambulatory surgical centers.
- Indian Domestic Market:CDSCO streamlined approval pathways enable faster launch of novel topical delivery systems for osteoarthritis.
Industry Challenges
- Continuous Manufacturing Talent Scarcity:Pharmaceutical engineering programs produce insufficient process chemists trained in flow reactor scale-up.
- Cross-Contamination Controls:Shared NSAID API facilities require costly dedicated production lines to meet EMA good manufacturing practice standards for highly potent compounds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Steroidal Anti-Inflammatory Drugs (Nsaids) Market |
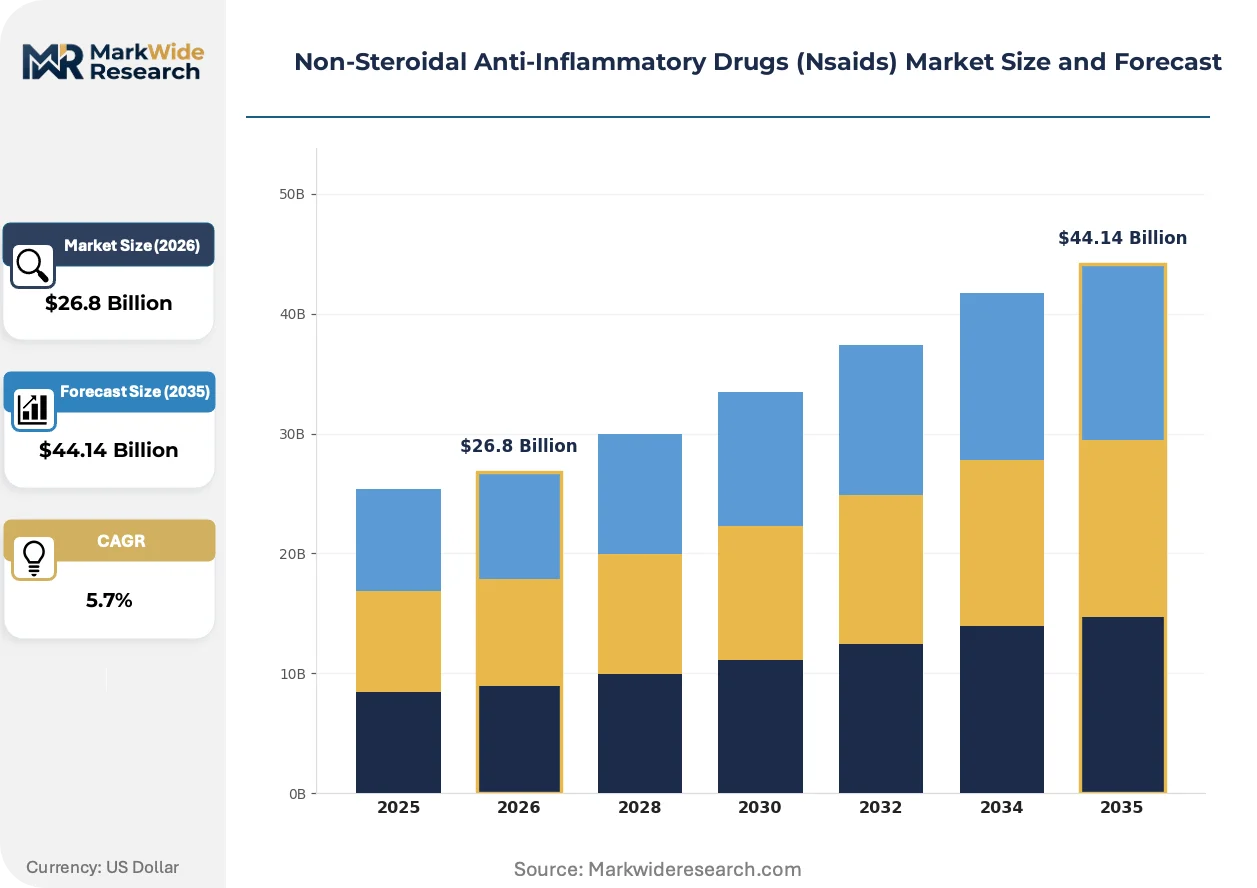
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $44.14 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ibuprofen, Naproxen, Diclofenac, Indomethacin, Ketoprofen, Meloxicam Therapy Area: Rheumatology, Orthopedics, Dentistry, Neurology, Sports Medicine, Pulmonology End User: Hospitals, Ambulatory Surgery Centers, Clinics, Pharmacies, Specialized Care Centers Distribution Channel: Retail Pharmacies, Online Pharmacies, Hospital Pharmacies, Drug Stores, Direct Sales |
| Companies Covered | Pfizer Inc., Bayer AG, Johnson & Johnson, Sanofi S.A., Haleon plc, Viatris Inc., Teva Pharmaceutical Industries Ltd., GSK plc, Sun Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Steroidal Anti-Inflammatory Drugs (Nsaids) Market Strategic Shifts & Innovations
Formulation science and manufacturing process innovation are restructuring competitive advantage in NSAID supply, with differentiation shifting from molecule exclusivity to delivery precision and production economics.
Microfluidic-enabled continuous manufacturing is supplanting batch reactor synthesis for propionic acid derivatives. Contract manufacturers in Germany and Switzerland deploy these systems to halve solvent consumption and accelerate batch release timelines. This technology is compressing cost structures for generic ibuprofen while enabling just-in-time API supply to European hospital networks.
EMA Pharmacovigilance Risk Assessment Committee periodic safety signal reviews now mandate renal function monitoring protocols for long-term NSAID therapy. German and French hospital systems have integrated these requirements into electronic prescribing workflows. Rheumatology practices respond by favoring intermittent dosing regimens and shorter prescription durations.
Hospital pharmacy consolidation across the United States concentrates purchasing authority within integrated delivery networks. These entities negotiate direct contracts with API suppliers, bypassing traditional wholesale distribution. The shift is most visible in Texas and Florida health systems, where perioperative ketorolac procurement now routes through centralized network formularies rather than individual facility buyers.
Non-Steroidal Anti-Inflammatory Drugs (Nsaids) Market Segmentation
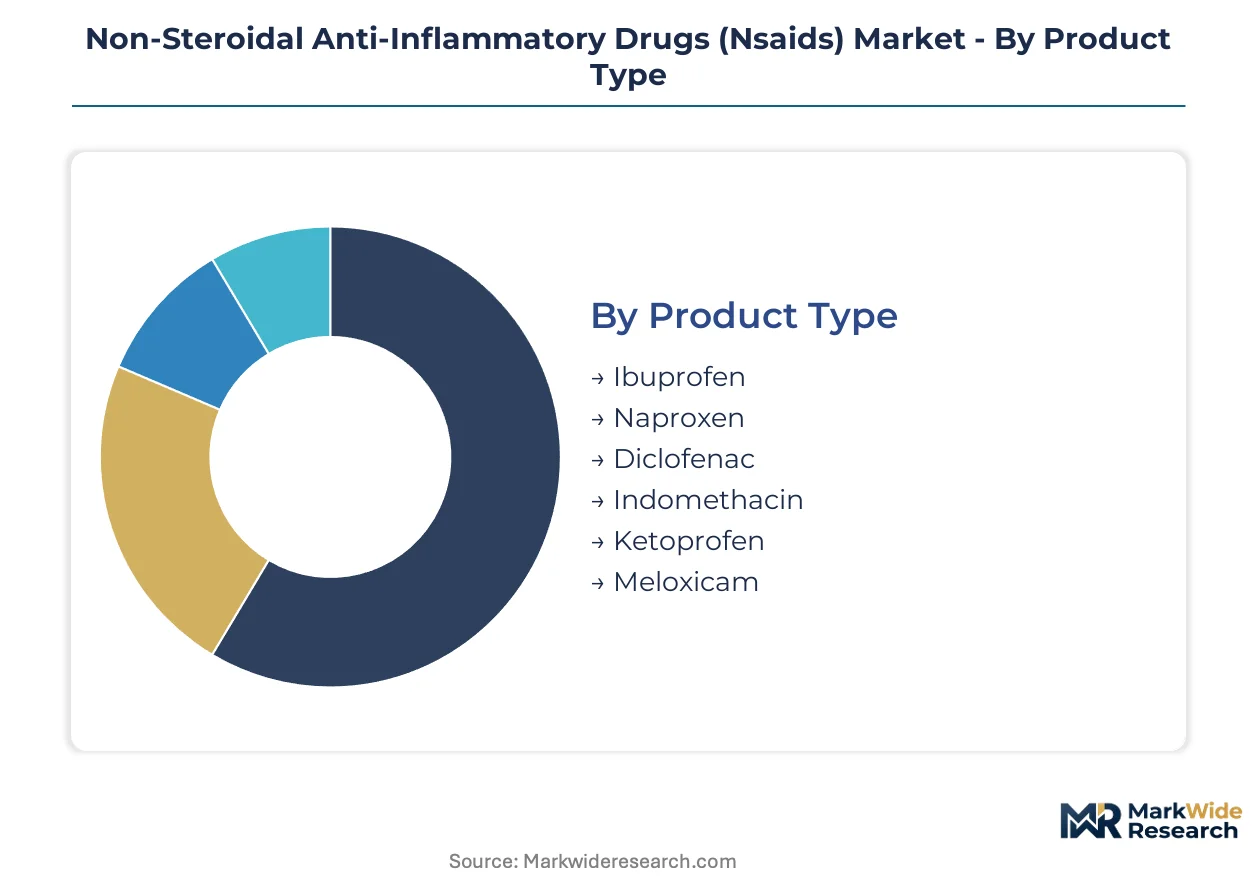
NSAID market segmentation reveals distinct procurement patterns across therapeutic applications and distribution channels. Hospital formulary decisions and retail pharmacy purchasing authority create divergent margin structures within each segment category.
Product Type:
Propionic acid derivatives dominate domestic consumption in established markets, while acetic acid derivatives and enolic acid derivatives drive export volume to emerging economies.
- Ibuprofen:The most widely consumed propionic acid derivative with molecular weight 206 g/mol and near-complete oral bioavailability. Demand concentrates in United States retail pharmacy channels where OTC formulations command shelf space leadership; FDA cardiovascular labeling requirements constrain prescription strength expansion.
- Naproxen:Longer half-life propionic acid derivative enabling twice-daily dosing regimens. German hospital systems favor naproxen for chronic rheumatology maintenance; EMA gastrointestinal safety protocols favor proton pump inhibitor co-prescription.
- Diclofenac:Acetic acid derivative with potent COX inhibition and established parenteral formulations. Indian domestic production supplies Southeast Asian export markets.
- Indomethacin:Non-selective COX inhibitor with pronounced central nervous system penetration. Specialized perioperative applications in Japanese hospital networks.
- Ketoprofen:Propionic acid derivative with documented efficacy in acute pain management. Continuous flow synthesis adoption in Swiss contract manufacturing.
- Meloxicam:Preferential COX-2 inhibitor with improved gastrointestinal tolerability profile. Rheumatology prescription volume expansion in United States Medicare populations.
Ibuprofen holds the largest share; momentum sits with meloxicam.
Therapy Area:
Orthopedic and rheumatology applications generate the highest per-patient medication burden, while dentistry and sports medicine drive acute episodic consumption patterns.
- Rheumatology:Chronic inflammatory joint disease management requiring long-term NSAID therapy. Japanese super-aged populations sustain volume; biologic substitution pressures constrain growth in refractory cases.
- Orthopedics:Post-surgical pain management and osteoarthritis symptom control. German hospital perioperative protocols favor parenteral ketorolac and diclofenac; transdermal patch adoption accelerates in ambulatory settings.
- Dentistry:Acute post-extraction and periodontal pain management. United States oral surgery practices favor short-course ibuprofen with acetaminophen combination.
- Neurology:Tension-type headache and migraine adjunctive therapy. Limited by cardiovascular risk warnings in coronary artery disease patients.
- Sports Medicine:Acute soft tissue injury and overuse syndrome management. Topical formulation preference among collegiate athletic programs.
- Pulmonology:Pleuritic chest pain and cystic fibrosis-related arthropathy. Narrow prescriber base limits commercial significance.
Orthopedics generates the highest absolute volume; rheumatology faces the steepest biologic substitution pressure.
End User:
Hospital procurement concentrates purchasing authority through integrated delivery networks, while retail pharmacy channels fragment demand across independent and chain operators.
- Hospitals:Inpatient and emergency department administration of parenteral formulations. Texas and Florida health systems centralize ketorolac procurement through network formularies.
- Ambulatory Surgery Centers:Same-day surgical procedures driving IV NSAID demand. United States Medicare reimbursement codes favor cost-effective perioperative analgesia.
- Clinics:Outpatient chronic pain management with prescription renewal authority. Rheumatology and orthopedic specialty clinics dominate.
- Pharmacies:OTC ibuprofen and naproxen self-selection with pharmacist consultation. German pharmacy channel maintains professional dispensing requirements.
- Specialized Care Centers:Pain management and palliative care facilities with high-dose authorization. Regulated distribution limits commercial scale.
Hospitals command premium pricing; ambulatory surgery centers represent the steepest expansion trajectory.
Distribution Channel:
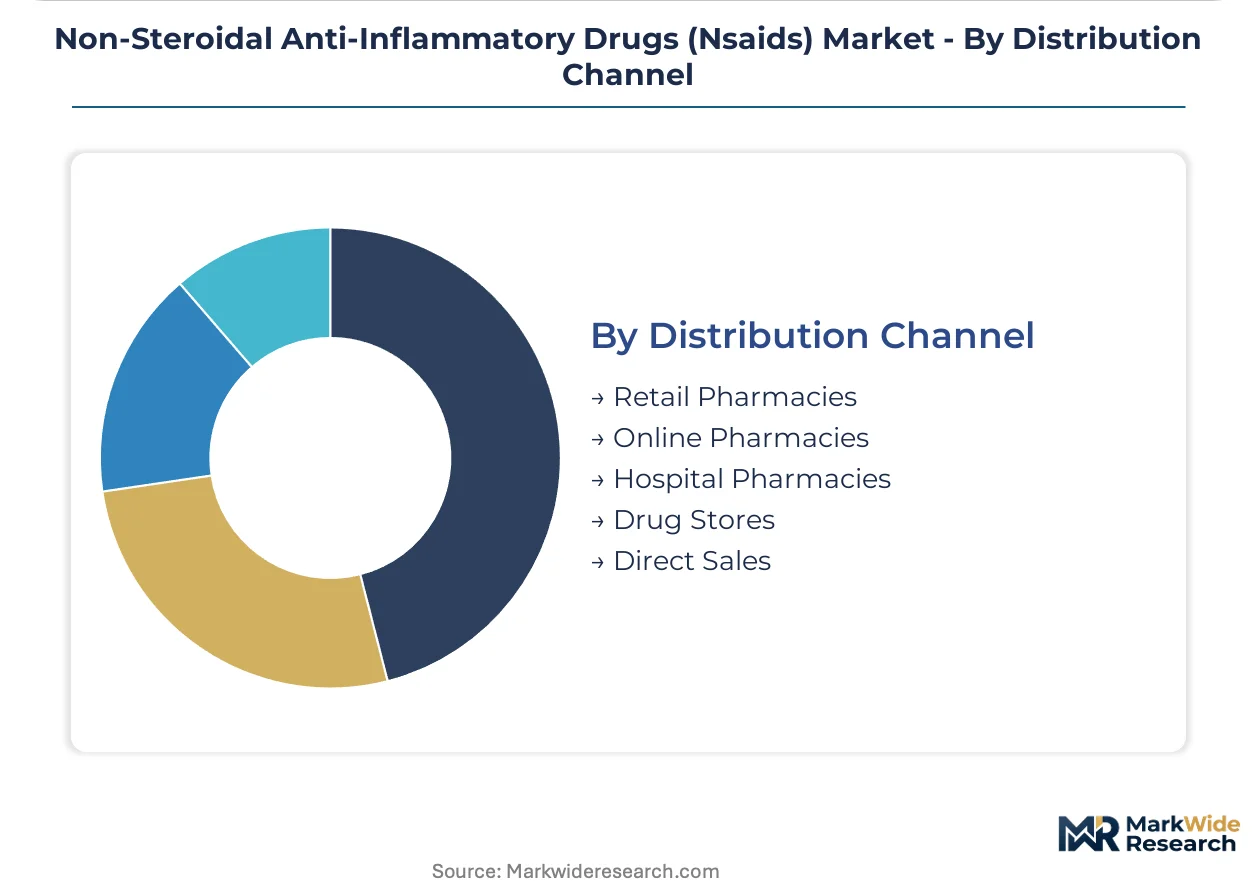
Channel selection determines margin capture, with direct sales and hospital pharmacies bypassing wholesale markups that characterize retail distribution.
- Retail Pharmacies:Brick-and-mortar OTC and prescription dispensing with pharmacist counseling. United States chain consolidation concentrates shelf space negotiations.
- Online Pharmacies:Mail-order prescription fulfillment and direct-to-consumer OTC sales. Indian CDSCO streamlined approvals enable faster novel topical launches.
- Hospital Pharmacies:Captive dispensing within integrated delivery networks. German and French electronic prescribing workflows integrate EMA renal monitoring protocols.
- Drug Stores:Convenience-focused OTC analgesic purchasing with limited professional consultation. Price competition intensifies among generic ibuprofen suppliers.
- Direct Sales:Manufacturer contracts with integrated delivery networks and ambulatory surgery center chains. Bypasses traditional wholesale distribution entirely.
Hospital pharmacies capture the highest per-unit value; online pharmacies are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cardiovascular risk labeling mandates are compressing prescription volumes in the United States while redirecting formulation priorities toward gastroprotective alternatives. Hospital procurement patterns and aging demographics create divergent growth trajectories across major pharmaceutical markets.
United States
Medicare rheumatology populations sustain chronic NSAID consumption despite cardiovascular black-box warnings. Texas and Florida health systems centralize ketorolac procurement through integrated delivery network formularies. Ambulatory surgical centers in these states favor IV formulations for same-day procedures.
Germany
German hospital systems favor naproxen for chronic rheumatology maintenance with proton pump inhibitor co-prescription protocols. EMA Pharmacovigilance Risk Assessment Committee renal monitoring requirements integrate into electronic prescribing workflows across Bavaria and North Rhine-Westphalia. Swiss contract manufacturers supply continuous flow-synthesized ketoprofen to German pharmacy channels.
Japan
Super-aged demographics sustain the highest per-capita NSAID consumption globally, with rheumatology and orthopedics driving hospital formulary expansion. PMDA periodic safety reviews shape prescriber preferences toward intermittent dosing regimens. Tokyo and Osaka medical centers anchor specialized perioperative indomethacin applications.
India
CDSCO streamlined approval pathways accelerate novel topical delivery system launches for osteoarthritis management. Domestic ibuprofen production supplies Southeast Asian export markets from Gujarat and Maharashtra manufacturing clusters. Sun Pharmaceutical Industries Ltd. competes on cost-engineered formulations across emerging economies.
Switzerland
Swissmedic regulatory standards enforce stringent good manufacturing practice requirements for highly potent NSAID compounds. Basel and Zurich host contract manufacturing operations deploying microfluidic continuous synthesis for propionic acid derivatives. These facilities halve solvent consumption while supplying just-in-time API to European hospital networks.
Non-Steroidal Anti-Inflammatory Drugs (Nsaids) Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the NSAID market structure. Tier-one players leverage captive API production and established hospital distribution channels to defend margin positions. Specialist manufacturers compete through continuous flow chemistry expertise and topical formulation differentiation. Dominant competitive moves include backward integration into ketoprofen intermediate production and fixed-dose combination portfolio expansion.
Within the integrated multinational tier, Pfizer Inc. and Bayer AG occupy anchor positions through global manufacturing networks and pharmacy channel dominance. Sun Pharmaceutical Industries Ltd. exemplifies the emerging market specialist archetype with cost-engineered ibuprofen export capabilities. These three entities collectively represent the spectrum from premium branded formulations to volume generic supply.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Bayer AG |
| Johnson & Johnson |
| Sanofi S.A. |
| Haleon plc |
| Viatris Inc. |
| Teva Pharmaceutical Industries Ltd. |
| GSK plc |
| Sun Pharmaceutical Industries Ltd. |
| Others |
Cost & Logistics Intelligence
China's ibuprofen intermediate capacity utilization above 85 percent anchors global price floors for propionic acid derivatives, compressing margins for European batch-reactor operators while rewarding Indian formulators with integrated backward positions. This scale concentration forces German and Swiss contract manufacturers toward continuous flow premiums to escape commodity pricing gravity.
Pricing Analysis
United States hospital procurement contracts for parenteral ketorolac command 40-60 percent premiums over German pharmacy-channel naproxen, reflecting integrated delivery network purchasing concentration against fragmented retail competition. Three-tier pricing structure across premium, standard, and economy levels separates patented COX-2 formulations from continuous flow-synthesized generics and legacy batch-process commodities. Cost compression in oral ibuprofen intensifies because Chinese API export license volatility disrupts just-in-time supply assumptions. Ambulatory surgery centers exhibit highest price sensitivity due to Medicare reimbursement code constraints, while Japanese rheumatology clinics accept premium meloxicam pricing for gastrointestinal tolerability advantages.
Supply Chain Analysis
Just-in-time API procurement dominates European hospital networks sourcing from Swiss microfluidic facilities, while United States integrated delivery networks maintain strategic stockpiles against Chinese export disruption risks. China, India, and Switzerland concentrate active pharmaceutical ingredient production, with Gujarat and Maharashtra clusters feeding Southeast Asian formulation demand. Raw material dependencies include isobutylbenzene for ibuprofen synthesis, 2-naphthol for naproxen intermediates, and thionyl chloride for acetic acid derivative chlorination. Single-source vulnerability concentrates in Chinese ibuprofen intermediate supply, exposing formulators to freight cost spikes and environmental compliance shutdowns. Distribution runs through direct manufacturer contracts with hospital networks, bypassing wholesale markups that characterize retail pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA cardiovascular risk labeling and EMA pharmacovigilance protocols creates substantial switching costs for prescriber specialties, defending incumbent positions against generic erosion.
For Market Incumbents: Consolidate API supply security through captive ketoprofen intermediate production or long-term offtake agreements with Swiss continuous flow manufacturers. Acquire topical formulation capabilities to capture perioperative pain management share shifting from oral generics, as transdermal diclofenac patches displace hospital parenteral volumes in German and United States ambulatory settings. For New Entrants and Emerging Players: Differentiate on green chemistry credentials by deploying REACH-compliant continuous synthesis for naproxen and ketoprofen, capturing European hospital procurement preference for reduced solvent waste profiles. Target Indian domestic osteoarthritis topical delivery systems through CDSCO streamlined approval pathways, leveraging cost-engineered manufacturing against Sun Pharmaceutical's established export dominance. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors contract manufacturers with microfluidic continuous flow expertise and established European hospital network relationships. Five-to-ten year viability hinges on regulatory moat sustainability around cardiovascular safety labeling complexity. The acquisition target archetype combines Swiss or German continuous synthesis assets with topical formulation development pipelines. Watch FDA outcome trial data releases for selective COX-2 agents as inflection indicators for gastroprotective formulation valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ketoprofen Intermediates | Pfizer's captive supply chains insulate European hospital contracts from Chinese export volatility. |
| Continuous Flow Manufacturing Scale-Up | Swiss contract manufacturers halve solvent consumption while accelerating EMA batch release timelines. |
| Fixed-Dose Combination Portfolio Expansion | Proton pump inhibitor-NSAID co-formulations extend patent protection while addressing EMA gastrointestinal safety mandates. |
| Topical Delivery System Development | Transdermal diclofenac patches capture perioperative share from oral generics in German hospital systems. |
| Hospital System Direct Contracting | Texas and Florida integrated delivery networks bypass wholesale distribution for ketorolac procurement. |
Research Approach
Initial hypotheses were tested against primary input from formulary directors at United States integrated delivery networks, EMA regulatory affairs specialists, German hospital procurement managers, and Indian CDSCO registration consultants, then refined against secondary validation from FDA cardiovascular safety labeling archives, EMA Pharmacovigilance Risk Assessment Committee periodic review documents, ClinicalTrials.gov outcome trial registrations, and customs trade data for ibuprofen intermediate flows. Bottom-up patient volume modeling and top-down pharmaceutical expenditure triangulation converged on segment-level estimates.
Variance decomposition across the projection horizon isolates volume drivers from price mix effects, with segmentation dimensions spanning chemical class, dosage form, administration route, therapy area, and regional regulatory cluster. CAGRs derive from fitted growth curves anchored to demographic projections and prescriber specialty survey data. Continuous manufacturing adoption rates and biologic substitution elasticities in rheumatology constitute key forecast sensitivity inputs.
The analysis sits within stated boundaries; outcomes outside sustained FDA cardiovascular risk labeling stringency or abrupt Chinese environmental compliance enforcement would require recalibration. Forecasts reflect documented assumptions regarding prescriber adherence to intermittent dosing protocols and hospital pharmacy consolidation trajectories. Revision becomes warranted when biologic substitution rates in refractory rheumatoid arthritis cross thresholds that invalidate NSAID maintenance therapy volume projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Oridonin Market
Pharmaceutical Ingredients
Anti-Allergic Agent Ingredients Market
Pharmaceutical Ingredients
Global Chlorpheniramine Maleate Market
Pharmaceutical Ingredients
Global Penicillin Drug Market
Pharmaceutical Ingredients
MEK Inhibitors Market
Pharmaceutical Ingredients
India Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Pharmaceutical Suspension Market
Pharmaceutical Ingredients
France Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Rizatriptan Market
Pharmaceutical Ingredients
Tranexamic Acid API Market
Pharmaceutical Ingredients
Pharmaceutical Propellants Market
Pharmaceutical Ingredients
Furosemide Market
Pharmaceutical Ingredients
Pharma Grade Ibuprofen API Market
Pharmaceutical Ingredients
Global Small Molecule API Market
Pharmaceutical Ingredients
Global Fibrate Drugs Market
Pharmaceutical Ingredients
Global Aspirin Market