
 Large Molecule Drug Substance CDMO Market | 2026-2036
Large Molecule Drug Substance CDMO Market Size, Share, and Industry Trends Forecast 2026-2036
Large Molecule Drug Substance CDMO Market Intelligence
Single-use bioreactor systems are restructuring capital deployment across mammalian cell culture facilities, cutting facility build-out timelines by half compared to stainless-steel equivalents. Samsung Biologics leverages its Songdo campus to anchor high-volume antibody drug substance output for global innovators. Lonza Group sustains leadership in microbial expression systems through specialized capacity at its Visp, Switzerland site. Thermo Fisher Scientific competes across both clinical and commercial scales with integrated analytical testing bundled into drug substance programs.
Large molecule drug substance CDMO services encompass the development and manufacture of active pharmaceutical ingredients derived from living cells, including recombinant proteins and monoclonal antibodies produced via mammalian or microbial fermentation at scales from 1,000 to 20,000 liters, with primary purpose being the supply of GMP-grade biological intermediates for downstream formulation into injectable therapeutics. Monoclonal antibodies occupy the dominant product category by revenue commitment, reflecting their entrenched role in oncology and immunology portfolios. Process development services capture premium margins as sponsors seek to de-risk cell line stability and titer optimization before locking in commercial supply agreements. Fill and finish operations remain structurally tighter in capacity than upstream drug substance production, creating bottleneck economics for integrated providers.
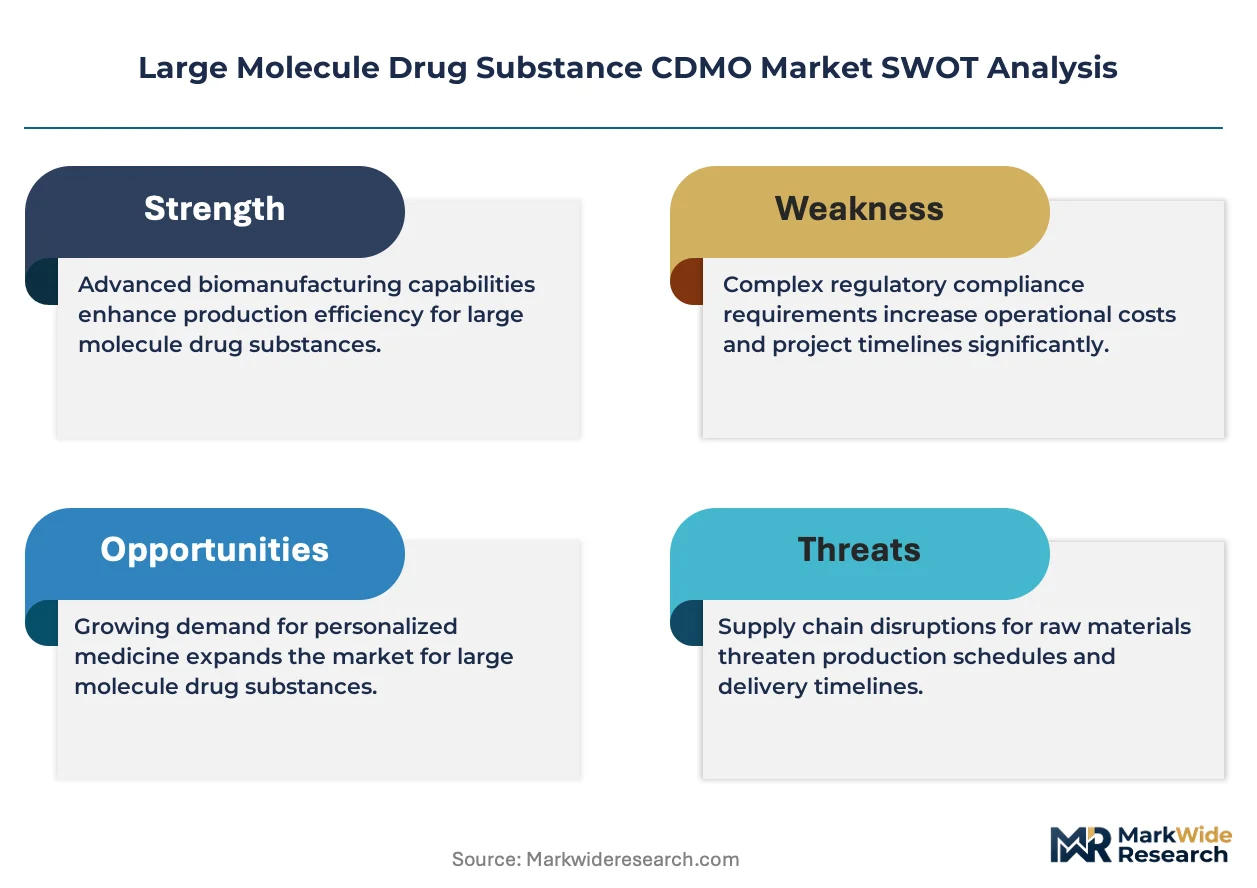
FDA's quality metrics guidance and EMA's good manufacturing practice Annex 1 revisions are elevating contamination control standards, forcing CDMOs to validate closed-system processing and rapid microbial detection methods as preconditions for commercial supply contracts. The EU AI Act and evolving FDA expectations for computer system validation are layering digital governance requirements atop physical quality systems. Stakeholders must weigh captive manufacturing investments against outsourcing flexibility as regulatory divergence between FDA and EMA inspection protocols complicates single-site global supply strategies.
Market Dynamics
Single-use bioreactor systems are compressing facility build timelines and redistributing capital deployment across mammalian cell culture infrastructure, forcing CDMOs to restructure their capacity expansion strategies around disposable technologies rather than fixed stainless-steel assets.
Growth Catalysts
- FDA Quality Metrics Guidance:The agency's tightened contaminant control standards are mandating closed-system processing validation, creating contract pull-through for CDMOs with advanced microbial detection capabilities.
- Oncology Portfolio Expansion:Biopharmaceutical innovators are accelerating monoclonal antibody pipeline commitments, driving demand for multi-thousand-liter mammalian cell culture capacity.
- Songdo Cluster Concentration:South Korea's purpose-built biomanufacturing hub is attracting global sponsor investment through integrated drug substance-to-drug product infrastructure.
Market Restraints
- Plastics Supply Concentration:Single-use bioreactor film and bag assemblies depend on concentrated polymer resin suppliers, exposing CDMOs to input cost volatility and lead time extension.
- EMA-FDA Inspection Divergence:Differing enforcement protocols between European and American regulators complicate single-site global supply qualification, forcing redundant facility investments.
- Prokaryotic Expression Limitations:Microbial systems at Visp-scale facilities cannot produce complex glycosylated antibodies, segmenting addressable demand by molecule class.
Strategic Opportunities
- Switzerland's Specialized Niche:Swissmedic's streamlined biosimilar approval pathways position the Visp corridor for high-complexity microbial-derived protein contracts.
- Integrated Analytical Bundling:CDMOs combining drug substance production with in-house mass spectrometry and bioassay validation capture premium pricing through reduced tech transfer friction.
- EU AI Act Compliance Services:Automated process control and machine learning-driven titer optimization tools create new advisory revenue streams as sponsors face computerized system validation mandates.
Industry Challenges
- Cell Line Development Expertise Scarcity:Qualified molecular biologists capable of stable clone selection and productivity screening command compensation premiums that compress CDMO margins.
- GMP Annex 1 Implementation Timeline:EMA's revised contamination control requirements demand facility retrofit investments with compressed validation windows ahead of enforcement deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Large Molecule Drug Substance CDMO Market |
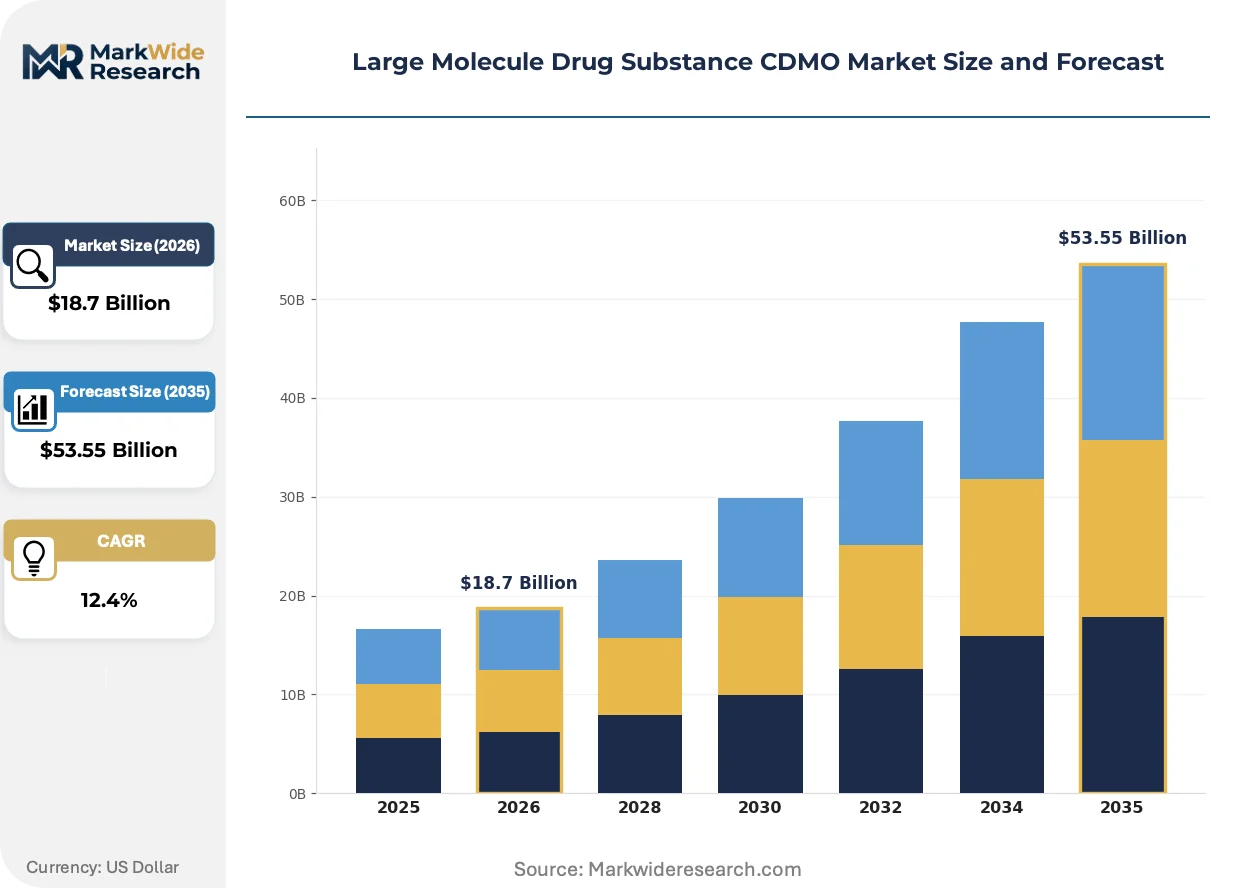
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $53.55 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
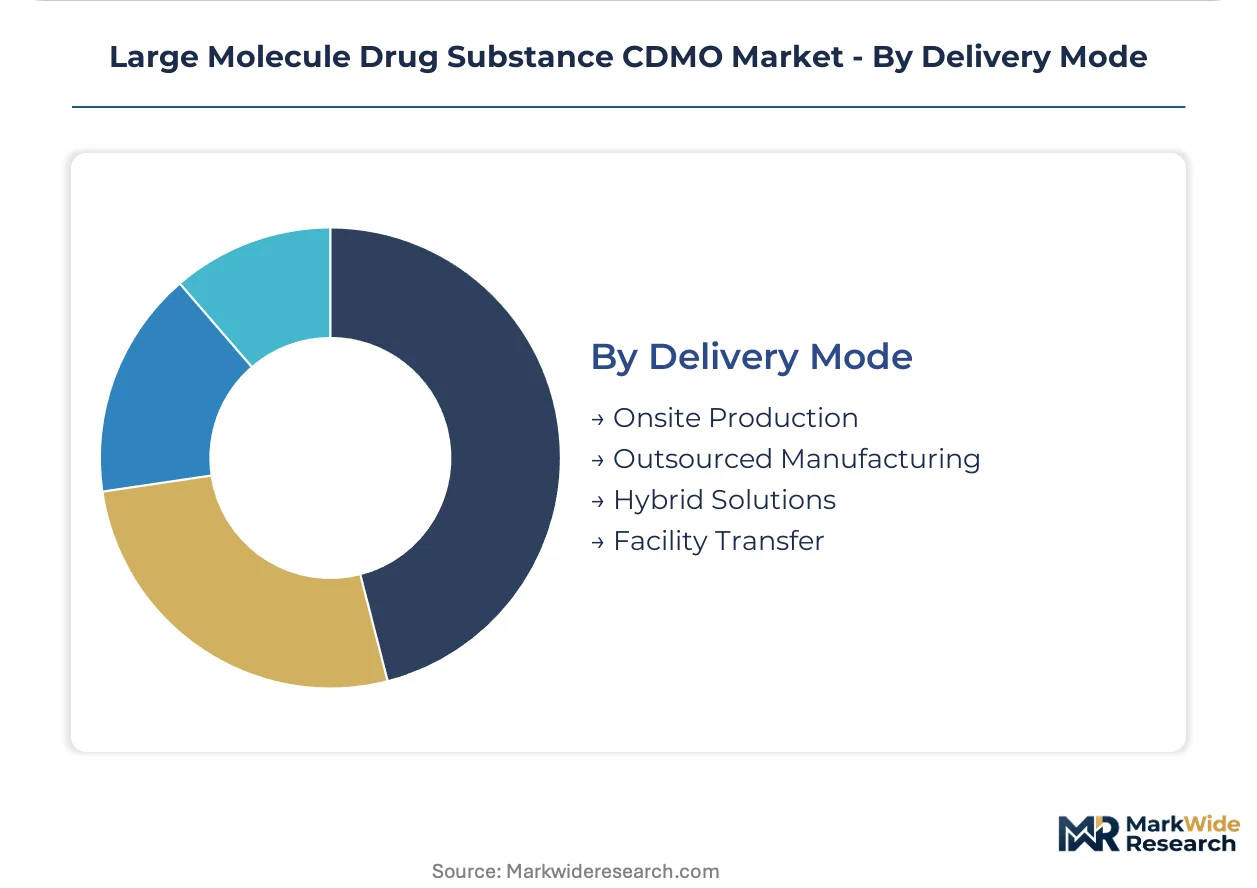
| Segmentation | Service Type: Process Development, Analytical Testing, Fill & Finish, Quality Assurance Product Type: Monoclonal Antibodies, Proteins, Vaccines, Hormones End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Research Organizations Delivery Mode: Onsite Production, Outsourced Manufacturing, Hybrid Solutions, Facility Transfer |
| Companies Covered | Samsung Biologics, Boehringer Ingelheim, Lonza Group, AGC Biologics, Eurofins Scientific, Thermo Fisher Scientific, Catalent, FUJIFILM Diosynth Biotechnologies, WuXi Biologics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Large Molecule Drug Substance CDMO Market Strategic Shifts & Innovations
Process intensification and digital manufacturing layers are restructuring how biological drug substance capacity is designed, operated, and validated across clinical-to-commercial transitions.
Continuous perfusion bioreactor technology is absorbing development-stage investment that previously flowed to fed-batch expansion. Mid-cap biotech sponsors are adopting perfusion for Phase III material generation to compress timeline-to-BLA. This shift is absorbing engineering talent from traditional batch process teams and reshaping CDMO technical service offerings toward integrated perfusion process development.
EMA's Annex 1 revision on sterile manufacturing is mandating barrier isolation and rapid microbial detection system installation. The regulation forces CDMOs to validate closed processing architectures before commercial contract award. Mammalian cell culture suites in the United States and Switzerland are retrofitting isolator technology ahead of European inspection schedules.
Sponsor procurement functions are consolidating vendor panels around integrated drug substance-to-drug product providers. Small and mid-cap innovators are abandoning multi-site sourcing strategies in favor of single-accountability partnerships. This concentration is most visible in the United States, where sponsors prioritize CDMOs with bundled analytical, regulatory, and fill-finish capabilities.
Large Molecule Drug Substance CDMO Market Segmentation
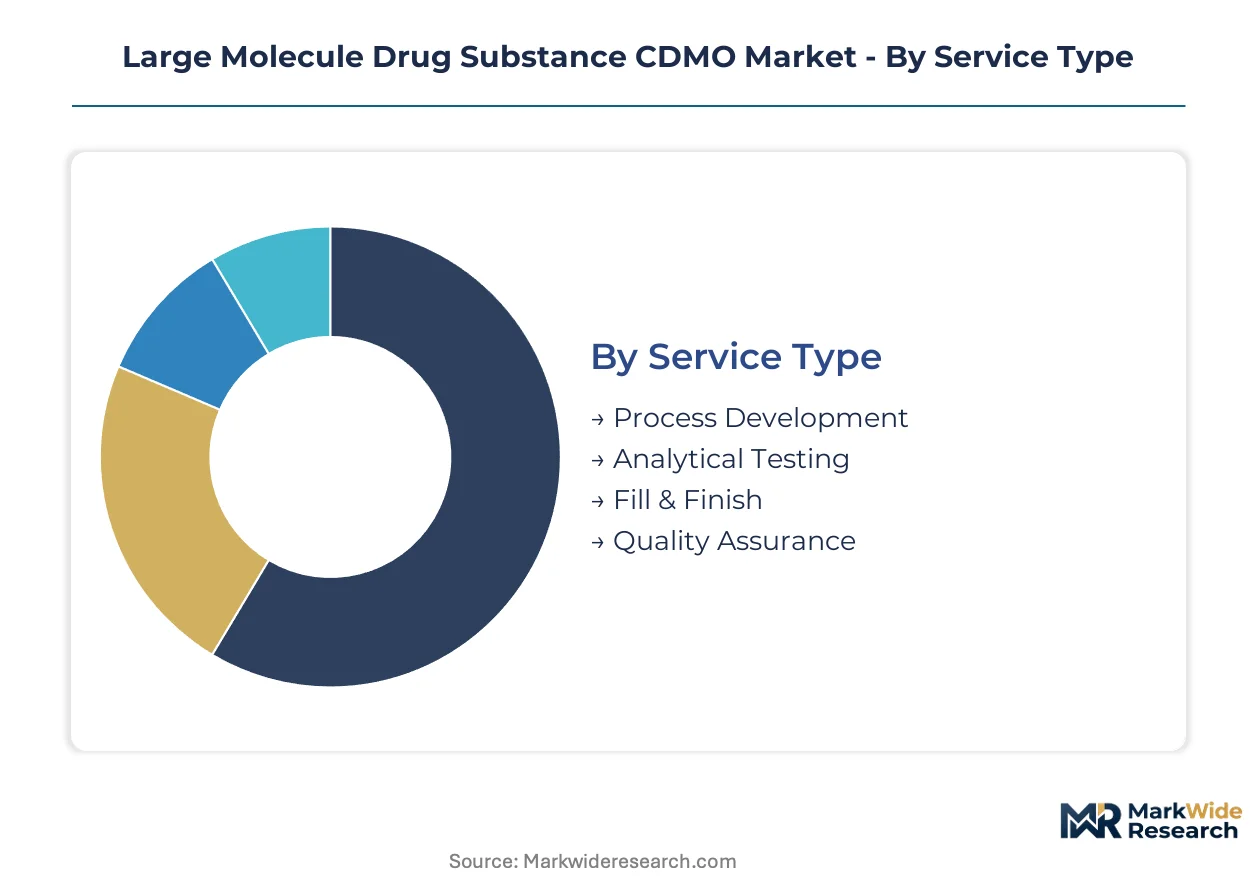
Large molecule drug substance CDMO procurement splits sharply between high-volume commercial supply agreements and premium-margin development services. Sponsors select segments based on pipeline maturity, regulatory filing timelines, and internal manufacturing asset availability.
Service Type:
Volume-heavy production services anchor commercial revenue, while premium-margin advisory functions concentrate in early-phase development.
- Process Development:Cell line engineering, media optimization, and scale-up validation services command pricing premiums tied to titer achievement milestones. Sponsors in the United States and Switzerland outsource these functions to de-risk IND-enabling timelines before locking commercial capacity.
- Analytical Testing:Mass spectrometry, bioassay validation, and stability protocol design absorb substantial CDMO technical staffing. Korean sponsors bundle these services with drug substance production to reduce tech transfer friction to global filing authorities.
- Fill & Finish:Aseptic processing and final container closure operations face tighter capacity constraints than upstream production.
- Quality Assurance:GMP compliance documentation and regulatory submission support functions scale with commercial manufacturing volume.
Mature deployment sits with Process Development. Newer deployment is concentrated in Quality Assurance as EMA Annex 1 and FDA quality metrics guidance force expanded validation documentation.
Product Type:
Complex glycosylation requirements segment addressable demand between mammalian and microbial expression platforms.
- Monoclonal Antibodies:Full-length immunoglobulins requiring post-translational modification dominate capacity commitments at multi-thousand-liter mammalian facilities. Oncology and immunology portfolios in the United States and South Korea drive the steepest expansion trajectory for this segment.
- Proteins:Recombinant cytokines, enzymes, and fusion proteins span expression system types based on structural complexity. Swiss microbial facilities at Visp-scale capacity capture non-glycosylated protein contracts.
- Vaccines:Viral vector and recombinant subunit manufacturing requires dedicated containment infrastructure.
- Hormones:Peptide and protein hormone production leverages established microbial expression platforms.
Established revenue concentration rests with Monoclonal Antibodies. Emerging sponsor interest is flowing toward Vaccines as mRNA and viral vector platforms expand.
End User:
Customer scale determines contract structure, with large-cap pharmas negotiating multi-site frameworks and emerging biotechs seeking single-accountability partnerships.
- Pharmaceutical Companies:Top-tier sponsors consolidate vendor panels around integrated drug substance-to-drug product providers. Procurement functions in the United States prioritize CDMOs with bundled analytical and fill-finish capabilities.
- Biotechnology Firms:Mid-cap innovators lacking captive manufacturing infrastructure drive outsourcing penetration rates. South Korean biotech clusters leverage Songdo campus proximity for integrated supply.
- Research Institutions:Academic and government laboratories require small-scale GMP batches for investigator-initiated trials.
- Contract Research Organizations:CROs subcontract manufacturing capacity to extend service offerings into drug substance production.
Contract value concentrates with Pharmaceutical Companies. Fastest-growing engagement volumes are appearing among Biotechnology Firms.
Delivery Mode:
Sponsor asset strategies segment procurement between captive, outsourced, and transitional manufacturing models.
- Onsite Production:Sponsors with existing biomanufacturing assets reserve capacity for commercial supply of established products. Large-cap pharmas in Switzerland maintain Visp-region facilities for microbial-derived pipeline candidates.
- Outsourced Manufacturing:Full reliance on CDMO capacity dominates among emerging biotechs and asset-light strategics. Korean sponsors exploit Songdo cluster concentration for antibody drug substance supply.
- Hybrid Solutions:Split manufacturing across captive and contracted sites complicates regulatory filing strategies.
- Facility Transfer:Tech transfer of established processes to new CDMO sites follows sponsor M&A or capacity rationalization decisions.
Prevalent sourcing structure favors Outsourced Manufacturing. Rising complexity is appearing in Hybrid Solutions as sponsors balance flexibility against single-site risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical outsourcing demand concentrates in jurisdictions with mature regulatory frameworks and purpose-built manufacturing infrastructure. Facility investments track sponsor pipeline commitments across three continents.
United States
Oncology and immunology portfolios from Boston and San Francisco biotech clusters drive multi-thousand-liter mammalian capacity commitments. FDA quality metrics guidance mandates closed-system processing validation for commercial supply contracts. Greater Boston hosts integrated drug substance-to-drug product campuses serving emerging biotech sponsors seeking single-accountability partnerships.
Switzerland
Microbial-derived protein contracts from European biosimilar developers concentrate capacity at Visp-scale facilities. Swissmedic streamlined approval pathways accelerate time-to-market for complex non-glycosylated therapeutics. The Basel-Visp corridor anchors specialized expression system expertise unavailable at mammalian-focused sites.
South Korea
Songdo campus concentration attracts global sponsor investment through bundled analytical and regulatory capabilities. MFDS alignment with FDA inspection protocols reduces dual-filing friction for export-bound production. Incheon Free Economic Zone infrastructure supports integrated clinical-to-commercial transitions for antibody drug substance programs.
Germany
EMA Annex 1 implementation timelines force facility retrofit investments ahead of enforcement deadlines. German biotech procurement functions prioritize CDMOs with validated rapid microbial detection systems. The Rhine-Main and Munich clusters concentrate process development talent for cell line stability optimization.
China
Domestic biopharma pipeline expansion absorbs regional mammalian cell culture capacity at WuXi Biologics-scale campuses. NMPA good manufacturing practice convergence with ICH standards enables parallel filing strategies for international sponsors. Shanghai and Suzhou biomanufacturing hubs integrate single-use bioreactor technology at clinical-to-commercial scale.
Large Molecule Drug Substance CDMO Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated providers commanding premium positioning in bundled service procurement. Market structure tilts toward scale-driven consolidation at the commercial manufacturing tier, while development-stage services retain fragmentation. Three archetypes dominate: mammalian cell culture specialists with multi-thousand-liter stainless-steel and single-use assets, microbial expression system providers with bacterial and yeast platforms, and integrated analytical-to-fill-finish operators. Competitive moves concentrate on capacity expansion through purpose-built campuses and strategic partnerships for tech transfer acceleration.
Among Asia-Pacific headquartered operators, Samsung Biologics exemplifies the scale-driven commercial manufacturing archetype through its Songdo campus concentration. Lonza Group represents the specialized microbial expression segment with Swiss-based bacterial and yeast platform expertise. Thermo Fisher Scientific occupies the integrated service tier, bundling drug substance production with analytical testing capabilities across clinical and commercial scales.
| Leading Market Players |
|---|
| Samsung Biologics |
| Boehringer Ingelheim |
| Lonza Group |
| AGC Biologics |
| Eurofins Scientific |
| Thermo Fisher Scientific |
| Catalent |
| FUJIFILM Diosynth Biotechnologies |
| WuXi Biologics |
| Others |
Cost & Logistics Intelligence
Polymer resin feedstock costs for single-use bioreactor film assemblies cascade through three distinct pricing tiers, with high-volume commercial mammalian cell culture contracts absorbing premium markups while development-stage microbial programs at Swiss facilities negotiate standard-rate structures. South Korean sponsors leveraging Songdo campus proximity capture modest logistics savings that partially offset raw material volatility.
Pricing Analysis
Volume-heavy commercial manufacturing commands premium pricing against development-stage services, with contract value scaling nonlinearly above 10,000-liter production commitments. Price differentiation rests on GMP certification tier and integrated analytical bundling, where bundled mass spectrometry and bioassay validation justify 15-20% uplifts over standalone drug substance quotes. Cost compression in early-phase process development is intensifying because sponsor procurement functions are consolidating vendor panels and demanding milestone-based payment structures. Emerging biotechs without captive manufacturing assets exhibit highest price sensitivity, while large-cap pharmas prioritize single-accountability partnerships over unit cost minimization.
Supply Chain Analysis
Qualified molecular biologists capable of stable clone selection and productivity screening concentrate in the United States, Switzerland, and Germany, creating compensation premiums that feed into service pricing. The supply chain draws from concentrated polymer resin suppliers for single-use bioreactor assemblies, with film and bag production anchored in specialized chemical manufacturing clusters. Single-source vulnerability in plastics supply exposes CDMOs to input cost volatility and lead time extension. Distribution runs through sponsor-directed logistics networks, with cold-chain requirements for GMP-grade biological intermediates dictating regional fulfillment center placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-use bioreactor technology is displacing stainless-steel infrastructure across mammalian cell culture facilities, compressing facility build timelines and redistributing capital deployment strategies. This transition phase rewards operators with validated closed-system processing capabilities ahead of FDA and EMA enforcement deadlines.
For Market Incumbents: Deepen backward integration into polymer resin supply through long-term offtake agreements with specialized film manufacturers, insulating margin structures from raw material volatility. Add multi-thousand-liter single-use capacity at Songdo-scale campuses to defend against emerging biotech sponsors consolidating vendor panels around integrated drug substance-to-drug product providers. Prioritize rapid microbial detection system installation ahead of EMA Annex 1 enforcement timelines. For New Entrants and Emerging Players: Continuous perfusion bioreactor expertise offers entry into Phase III material generation contracts, where mid-cap biotech sponsors seek timeline compression to BLA submission. Target Swiss microbial expression niches for non-glycosylated protein contracts, exploiting Swissmedic streamlined biosimilar pathways underserved by mammalian-focused incumbents. Lead with EU AI Act compliance advisory services as sponsors face computerized system validation mandates. For Investors and Strategic Acquirers: CDMO facility retrofit announcements for barrier isolation and closed-system validation are the leading indicator that regulatory compliance spending is accelerating and integrated providers will capture disproportionate contract flow. Position for 5-10 year horizon consolidation around operators with bundled analytical-to-fill-finish capabilities. Monitor sponsor procurement function consolidation toward single-accountability partnerships as the primary demand signal.| Strategic Initiative | Industry Significance |
|---|---|
| Single-Use Capacity Expansion | Songdo and Visp-scale campuses compress facility build timelines while meeting FDA closed-system mandates. |
| Integrated Analytical Bundling | Mass spectrometry and bioassay validation capabilities reduce tech transfer friction for sponsor procurement functions. |
| Perfusion Process Development | Continuous bioreactor expertise captures Phase III material generation from timeline-pressured mid-cap biotechs. |
| Regulatory Compliance Services | EU AI Act advisory creates new revenue streams as sponsors face computerized system validation requirements. |
| Cell Line Development Investment | Stable clone selection capabilities command premium pricing amid qualified molecular biologist scarcity. |
Research Approach
Document review covered FDA quality metrics guidance, EMA Annex 1 revisions, and MFDS inspection protocol alignments, complemented by interviews with drug development executives, regulatory affairs leads, CDMO procurement managers, and GMP compliance officers across the United States, Switzerland, and South Korea. Secondary validation drew from FDA filings, EMA submission databases, ClinicalTrials.gov records, and CDMO capacity expansion announcements. Bottom-up service segment sizing and top-down market triangulation were cross-referenced for consistency.
Historical capacity utilization patterns were cross-referenced against panel input from facility engineering directors and sponsor supply chain heads to anchor projection assumptions. Segmentation modeling spanned service type, product class, expression system, and regional regulatory cluster dimensions across the analysis window. CAGRs were derived from sponsor pipeline commitment trajectories, facility investment disclosures, and outsourcing penetration rate shifts. Industry-specific inputs included monoclonal antibody oncology portfolio expansion rates and single-use bioreactor adoption curves.
Several conditions sit outside the modeled scope, including unforeseen regulatory divergence between FDA and EMA inspection protocols, abrupt polymer resin supply disruptions, and sponsor M&A-driven facility transfer decisions. Forecasts reflect assumptions regarding continued biopharmaceutical outsourcing momentum and stable ICH guideline convergence. Material deviation in sponsor vendor consolidation patterns or single-use technology adoption rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Global Aspirin Market
Pharmaceutical Ingredients
Global Glycine Supplement Market
Pharmaceutical Ingredients
China Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Prescription Hair Loss and Hair Removal Drugs Market
Pharmaceutical Ingredients
Taxifolin Market
Pharmaceutical Ingredients
Pharmaceutical Suspension Market
Pharmaceutical Ingredients
Germany Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Piperacillin Sodium API Market
Pharmaceutical Ingredients
Pharma Grade Ibuprofen API Market
Pharmaceutical Ingredients
Diosmin API Market
Pharmaceutical Ingredients
Lidocaine Hydrochloride Market
Pharmaceutical Ingredients
Scopolamine Market
Pharmaceutical Ingredients
Celecoxib API Market
Pharmaceutical Ingredients
Global Sugar-Based Excipients Market
Pharmaceutical Ingredients
Growth Hormone Inhibiting Hormone Drugs Market
Pharmaceutical Ingredients
Furosemide Market