
 Scopolamine Market | 2026-2036
Scopolamine Market Size, Share, and Industry Trends Forecast 2026-2036
Scopolamine Market Outlook
The scopolamine market is expanding along a widening gap between premium transdermal patches and commodity oral tablets. Novartis AG leverages its transdermal manufacturing expertise to sustain pricing power in hospital procurement channels. GlaxoSmithKline plc anchors the motion sickness segment through established retail pharmacy relationships. Caleb Pharmaceuticals, Inc. competes on cost in emerging markets with basic oral formulations.
Scopolamine is a tropane alkaloid derived primarily from Datura and Brugmansia species, functioning as a competitive antagonist at muscarinic acetylcholine receptors to suppress vestibular-mediated nausea and vomiting. The compound exists as a hygroscopic, viscous liquid at room temperature with a molecular weight of 303.35 g/mol, and its primary commercial purpose centers on preventing motion sickness and perioperative emesis through central nervous system depression of the vomiting reflex. Patch formulations command the dominant margin pool due to complex matrix polymer engineering and extended-release kinetics that protect against generic substitution. Oral tablets retain volume leadership in cost-sensitive anesthesia premedication protocols across Asia-Pacific and Latin American markets. Injectable solutions occupy a narrow but defensible niche in emergency department settings where rapid antiemetic onset supersedes convenience considerations.
The FDA regulates scopolamine transdermal systems under bioequivalence protocols that require pharmacokinetic bridging studies for abbreviated new drug applications, while the EMA enforces comparable standards through its Committee for Medicinal Products for Human Use. REACH compliance in Europe constrains alkaloid extraction solvent choices, elevating production costs for API manufacturers serving dual markets. Stakeholders must monitor evolving FDA guidance on in vitro permeation testing methodologies, as these standards will determine which generic entrants can validate therapeutic equivalence without costly clinical endpoint studies.
Market Dynamics
FDA bioequivalence tightening for transdermal generics is compressing competitive entry timelines while hospital procurement consolidation amplifies pricing leverage for established patch manufacturers.
Growth Catalysts
- Postoperative nausea protocols:Ambulatory surgical centers in the United States are embedding scopolamine patches into standardized antiemetic order sets, creating recurring demand tied to procedure volume expansion.
- REACH solvent compliance:European extraction standards are elevating API production costs for dual-market suppliers, inadvertently protecting margin pools for compliant manufacturers with validated alkaloid sourcing chains.
- Matrix polymer engineering:Advances in pressure-sensitive adhesive kinetics are extending patch wear time from 72 to 96 hours, improving patient compliance in motion sickness prophylaxis.
Market Restraints
- Alkaloid supply concentration:Datura and Brugmansia cultivation clusters in India and China expose API manufacturers to climate-induced yield volatility and regional export restriction risk.
- Transdermal manufacturing capex:Validated coating and lamination lines require eight-figure capital commitments, creating barriers for generic entrants seeking FDA abbreviated new drug approval.
- Oral tablet substitution:Ondansetron generics are displacing scopolamine in cost-sensitive anesthesia premedication across Latin American and Asia-Pacific hospital systems.
Strategic Opportunities
- Pediatric motion sickness:Underpenetrated demand among children aged 4-12 presents white space for weight-dosed patch formulations with modified surface area geometry.
- Telehealth prescription channels:Direct-to-patient distribution models are emerging for pre-travel prophylaxis, bypassing traditional retail pharmacy intermediaries in United States markets.
- IRA drug pricing provisions:Medicare negotiation timelines for small-molecule drugs create incentive windows for transdermal delivery innovation ahead of 2029 eligibility triggers.
Industry Challenges
- In vitro permeation validation:FDA draft guidance on Franz cell testing methodologies is forcing reformulation cycles for abbreviated new drug application filers without clinical endpoint bridging data.
- Alkaloid extraction workforce:Specialized botanists and natural product chemists with Datura processing expertise are scarce in European and North American labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scopolamine Market |
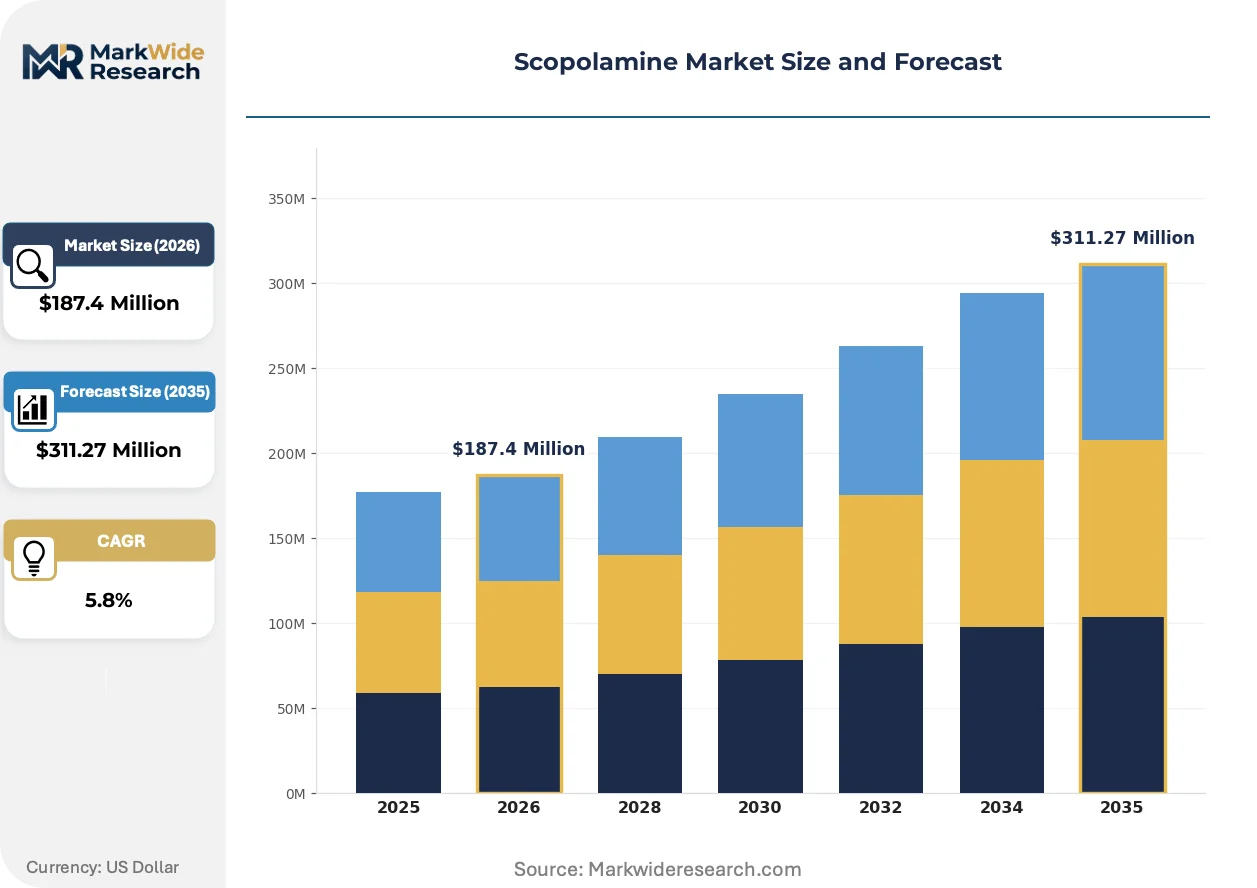
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Patch, Oral Tablet, Solution Therapy Area: Motion Sickness, Postoperative Nausea, IBS, Anesthesia Formulation: Extended Release, Immediate Release, Combination Formulation, Transdermal Distribution Channel: Pharmacies, Hospitals, Online Stores, Drug Stores |
| Companies Covered | GlaxoSmithKline plc, Novartis AG, Caleb Pharmaceuticals, Inc., Perrigo Company plc, Alchem International, Baxter International Inc., Phytex Australia, Myungmoon Pharma Co., LTD., Teva Pharmaceutical Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scopolamine Market Strategic Shifts
Formulation science and regulatory science are converging to redefine competitive moats in scopolamine delivery, with bioequivalence methodology becoming as strategically significant as the molecule itself.
Microneedle array technology is unifying transdermal delivery precision with patient self-administration convenience. Hospital systems in Germany and Japan are piloting dissolvable hyaluronic acid microneedles for perioperative nausea prophylaxis. This convergence is compressing the traditional patch-to-injectable efficacy gap while enabling dose titration previously impossible with matrix-based systems.
EMA's evolving stance on in vitro permeation testing as a primary bioequivalence surrogate is reshaping generic entry economics. The Committee for Medicinal Products for Human Use now accepts enhanced physicochemical characterization in lieu of clinical endpoint studies for certain transdermal modifications. European generic manufacturers with advanced analytical capabilities are responding by accelerating ANDA-equivalent filings ahead of formal guideline finalization.
Hospital procurement consolidation is compressing supplier rosters and unbundling antiemetic purchasing from broader anesthesia contracts. Integrated delivery networks in Texas and California are negotiating multi-year scopolamine patch commitments with price-volume tiers tied to ambulatory surgery growth projections. This behavioral shift is most visible in United States markets where health system merger activity has concentrated buying power among ten national platforms.
Scopolamine Market Segmentation
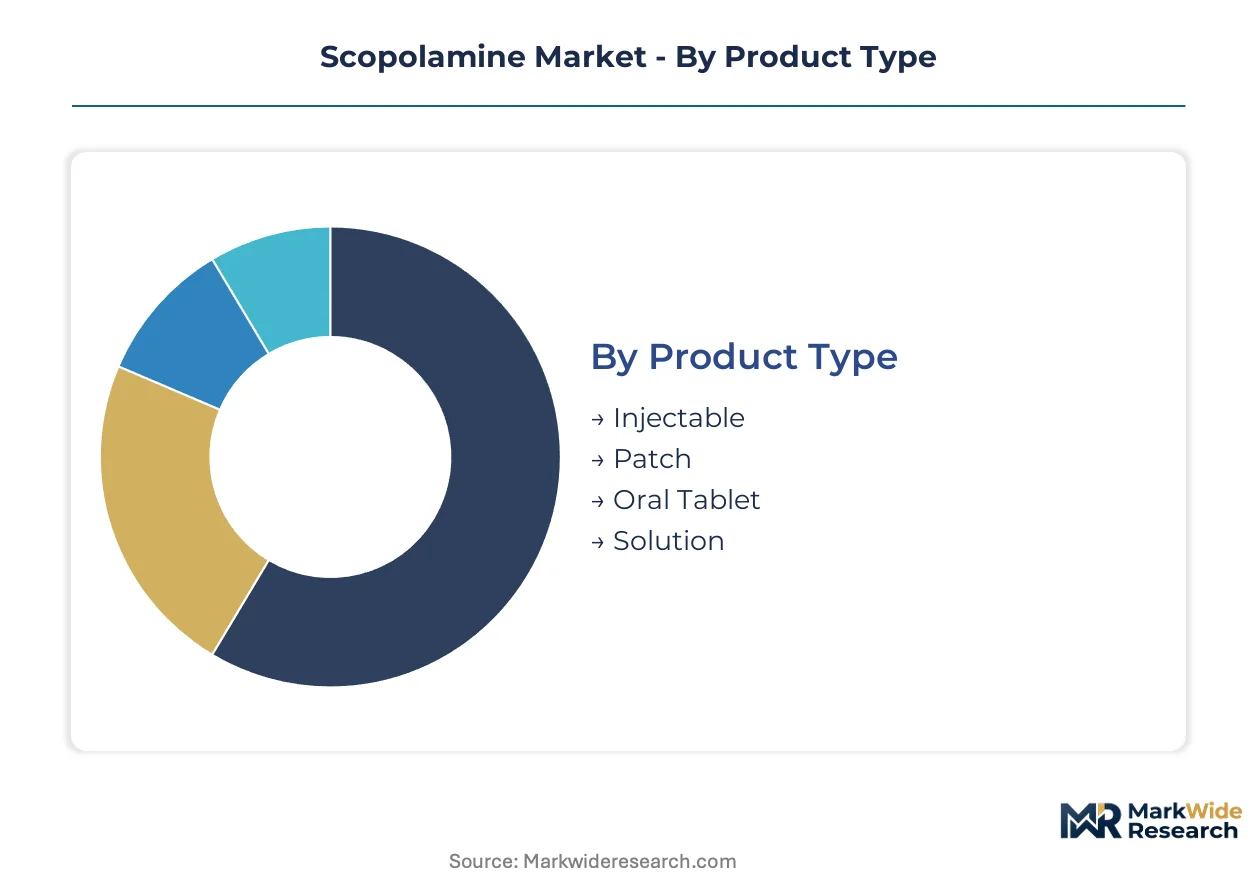
Scopolamine's therapeutic versatility fragments the market across delivery technologies and clinical settings, with each segment carrying distinct regulatory burdens and margin profiles. Understanding these divisions reveals where pricing power concentrates and where commoditization pressures dominate.
Product Type:
FDA bioequivalence protocols for transdermal systems impose steeper validation requirements than oral or injectable formats, creating tiered competitive barriers across delivery modalities.
- Patch:Matrix polymer systems with pressure-sensitive adhesive kinetics enable 72-96 hour wear time. Hospital procurement in the United States embeds patches into standardized antiemetic protocols, locking in recurring demand tied to ambulatory surgery volumes. Leading the category by volume: Patch. Growing fastest: Patch.
- Oral Tablet:Compressed scopolamine hydrobromide formulations dominate cost-sensitive anesthesia premedication across Asia-Pacific and Latin American hospital systems where ondansetron generics have displaced premium alternatives.
- Injectable:Parenteral solutions occupy emergency department settings requiring rapid antiemetic onset, with narrow but defensible positioning where convenience yields to speed.
- Solution:Liquid formulations serve compounding pharmacies and specialized pediatric applications where dose flexibility supersedes standardized dosing.
Patch technology commands margin leadership through manufacturing complexity; oral tablets retain volume dominance in emerging markets.
Therapy Area:
Clinical application determines reimbursement pathways and prescriber behavior, with perioperative protocols offering more predictable demand than consumer-directed indications.
- Postoperative Nausea:Ambulatory surgical centers in the United States are standardizing scopolamine patch inclusion in multimodal antiemetic order sets, creating procedure-volume-linked demand expansion.
- Motion Sickness:Consumer-directed prophylaxis for air and sea travel sustains retail pharmacy distribution, with telehealth channels emerging for pre-travel prescriptions bypassing traditional intermediaries.
- Anesthesia:Premedication protocols in cost-constrained health systems favor oral scopolamine where formulary committees prioritize acquisition cost over nursing convenience.
- IBS:Off-label utilization for irritable bowel syndrome-related nausea remains limited by restricted prescriber awareness and absence of formal indication expansion.
Postoperative nausea generates the steadiest revenue stream; motion sickness carries highest consumer marketing expenditure.
Formulation:
Release kinetics differentiate manufacturing sophistication requirements, with extended-release technologies demanding specialized equipment investments that filter competitive participation.
- Transdermal:Matrix-based systems with validated in vitro permeation profiles anchor premium pricing through bioequivalence barriers that generic entrants struggle to surmount.
- Extended Release:Polymer-engineered depot formulations reduce dosing frequency for chronic nausea management, improving adherence in long-term therapy contexts.
- Immediate Release:Conventional tablet disintegration profiles serve acute episodic needs where rapid onset outweighs duration considerations.
- Combination Formulation:Co-formulated antiemetics with scopolamine plus additional agents address refractory cases through synergistic receptor targeting.
Transdermal systems capture the widest gross margins; immediate release formats face steepest price erosion.
Distribution Channel:
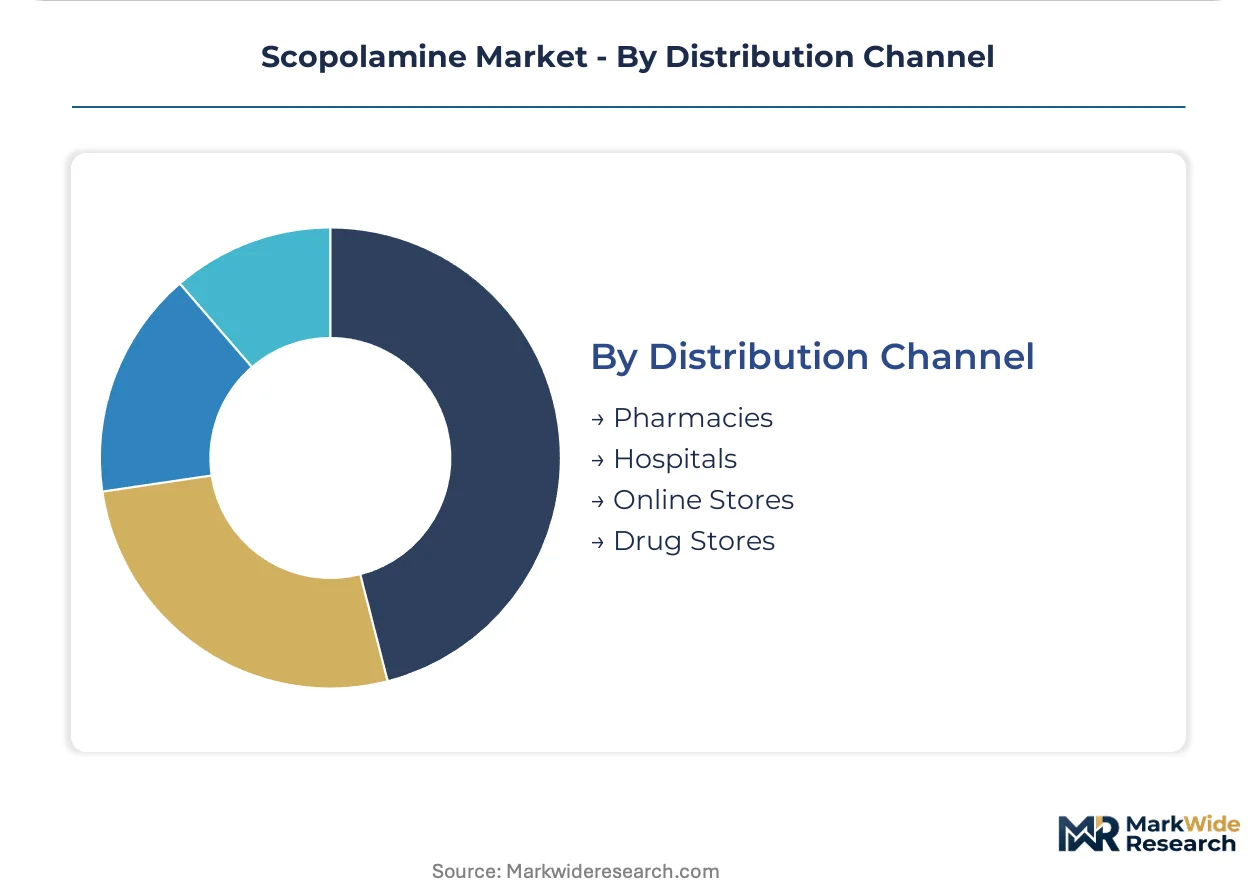
Channel selection determines customer access economics and inventory carrying requirements, with institutional procurement consolidating supplier relationships faster than retail fragmentation.
- Hospitals:Integrated delivery networks in Texas and California negotiate multi-year patch commitments with volume-tiered pricing tied to surgery growth projections.
- Pharmacies:Community and outpatient settings handle prescription fulfillment for discharge patients and pre-travel prophylaxis seekers.
- Drug Stores:Over-the-counter motion sickness segments in select markets sustain shelf-space competition against alternative antiemetics.
- Online Stores:Direct-to-patient distribution models are emerging for pre-travel prophylaxis, leveraging telehealth prescribing to bypass retail pharmacy intermediaries.
Hospitals concentrate purchasing power most intensely; online channels show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyderabad anchors scopolamine API manufacturing through Alchem International's extraction facilities, drawing on Andhra Pradesh's Datura cultivation corridors to supply hospital systems across three continents.
United States
Ambulatory surgical centers in Texas and California embed scopolamine patches into standardized antiemetic protocols, locking in procedure-volume-linked demand. The FDA's tightened bioequivalence standards for transdermal generics compress competitive entry timelines for abbreviated new drug applications. Integrated delivery networks in the Dallas-Fort Worth metro negotiate multi-year patch commitments with volume-tiered pricing tied to surgery growth projections.
Germany
Hospital systems in Bavaria and North Rhine-Westphalia pilot dissolvable hyaluronic acid microneedles for perioperative nausea prophylaxis. REACH compliance constrains alkaloid extraction solvent choices, elevating production costs for API manufacturers serving dual European and North American markets. The Frankfurt-Rhine-Main pharmaceutical cluster hosts formulation specialists advancing pressure-sensitive adhesive kinetics for extended-release transdermal systems.
India
Datura and Brugmansia cultivation clusters in Madhya Pradesh and Rajasthan expose API manufacturers to climate-induced yield volatility and regional export restriction risk. The Central Drugs Standard Control Organization regulates scopolamine formulations under Schedule H, requiring prescription-only distribution for oral and injectable formats. Hyderabad's bulk drug manufacturing corridor concentrates natural product extraction expertise, with Alchem International operating validated alkaloid processing lines.
Japan
Chubu region hospitals adopt matrix polymer patches for motion sickness prophylaxis in maritime and aviation sectors. The Pharmaceuticals and Medical Devices Agency enforces comparable bioequivalence standards to the FDA through its Committee on Drug Evaluation. Osaka-Kobe pharmaceutical formulation clusters engineer extended-release kinetics improving patient compliance in long-therapy contexts.
Australia
Phytex Australia operates specialized botanical extraction facilities serving Asia-Pacific hospital procurement channels with oral tablet and solution formulations. The Therapeutic Goods Administration aligns transdermal bioequivalence protocols with FDA and EMA methodologies, streamlining multi-market registration pathways. Melbourne's pharmaceutical manufacturing zone concentrates natural product chemistry expertise for tropane alkaloid processing.
Scopolamine Market Competitive Environment
Capital-heavy transdermal patch manufacturers compete with asset-light oral tablet specialists across divergent margin pools. The market structures around three tiers: multinational pharmaceutical conglomerates with validated coating and lamination infrastructure, regional API-to-formulation integrators controlling alkaloid supply chains, and commodity generics producers serving cost-constrained anesthesia protocols. Consolidation pressures concentrate among hospital procurement channels, while manufacturing complexity filters generic participation in premium delivery formats. Dominant competitive moves include strategic partnerships between patch developers and polymer engineering firms, plus backward integration into Datura cultivation by API suppliers seeking yield security.
Within the multinational conglomerate tier, Novartis AG and GlaxoSmithKline plc exemplify divergent strategic positioning—one leveraging transdermal manufacturing expertise for hospital procurement channels, the other anchoring retail pharmacy relationships in consumer-directed motion sickness segments. Caleb Pharmaceuticals, Inc. occupies a position among cost-focused oral formulation specialists competing in emerging markets where ondansetron displacement pressures intensify. Baxter International Inc. and Teva Pharmaceutical Industries Limited represent diversified healthcare conglomerates with portfolio breadth spanning multiple antiemetic delivery modalities.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Novartis AG |
| Caleb Pharmaceuticals, Inc. |
| Perrigo Company plc |
| Alchem International |
| Baxter International Inc. |
| Phytex Australia |
| Myungmoon Pharma Co., LTD. |
| Teva Pharmaceutical Industries Limited |
| Others |
Value Chain & Pricing Dynamics
REACH solvent compliance in Europe gates qualified supply for dual-market API manufacturers while simultaneously restricting premium-tier pricing access to REACH-validated producers with compliant alkaloid extraction chains.
Pricing Analysis
Procedure-volume-linked pricing anchors hospital procurement contracts in the United States, with integrated delivery networks negotiating multi-year patch commitments tied to ambulatory surgery growth projections. Three-tier pricing structure across premium transdermal, standard oral, and economy generic segments reflects bioequivalence validation burden and manufacturing complexity. Cost compression in oral tablet tiers is intensifying because ondansetron generics are displacing scopolamine in anesthesia premedication across Latin American and Asia-Pacific hospital systems. Asia-Pacific formulary committees exhibit highest price sensitivity; United States hospital procurement managers show lowest sensitivity due to nursing convenience premiums embedded in patch protocols.
Supply Chain Analysis
FDA and EMA bioequivalence certification gates API supplier qualification, filtering participation to manufacturers with validated in vitro permeation testing capabilities and documented alkaloid sourcing chains. Supply concentrates in India, China, and Germany, with Hyderabad's extraction facilities and Frankfurt-Rhine-Main formulation clusters serving distinct value chain segments. Raw material dependencies center on Datura and Brugmansia biomass, pressure-sensitive adhesive polymers, and specialized coating solvents. Single-source vulnerability runs through climate-dependent cultivation corridors in Madhya Pradesh and Rajasthan. Distribution runs through hospital procurement channels, retail pharmacy networks, and emerging direct-to-patient telehealth platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into Datura cultivation has become the decisive upstream lever in this vertical-integration race, as API manufacturers seek yield security against climate-induced supply volatility.
For Market Incumbents: Anchor hospital procurement relationships through multi-year volume-tiered contracts tied to ambulatory surgery growth projections. Defend against microneedle array substitutes by accelerating matrix polymer engineering investments for extended 96-hour wear time. Prioritize REACH compliance certification to maintain dual-market European and North American access. For New Entrants and Emerging Players: Pediatric motion sickness patients aged 4-12 represent an underserved buyer archetype with white-space potential for weight-dosed patch formulations. Target telehealth prescription channels for pre-travel prophylaxis bypassing traditional retail pharmacy intermediaries. Pursue FDA abbreviated new drug applications with enhanced physicochemical characterization to exploit evolving bioequivalence guidance. For Investors and Strategic Acquirers: FDA draft guidance finalization on in vitro permeation testing methodologies is the leading indicator that generic entry economics will shift decisively toward analytical-capability-heavy manufacturers. Position for 5-10 year horizon consolidation around REACH-compliant API-to-formulation integrators with captive alkaloid sourcing. Monitor EMA Committee for Medicinal Products for Human Use guideline evolution as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Captive Datura supply chains in Andhra Pradesh insulate Alchem International against climate yield volatility. |
| Microneedle Array Development | Dissolvable hyaluronic acid systems in German hospital pilots compress patch-to-injectable efficacy gaps. |
| REACH Compliance Certification | Validated solvent extraction protocols unlock premium-tier European hospital procurement access. |
| Telehealth Channel Establishment | Direct-to-patient distribution models bypass retail pharmacy intermediaries in United States markets. |
| Pediatric Formulation Extension | Weight-dosed patch geometries address underpenetrated demand among children aged 4-12. |
Study Parameters
Multi-period observation of FDA abbreviated new drug application filings, EMA Committee for Medicinal Products for Human Use guideline evolution, and hospital procurement contract structures anchored the trend analysis, supplemented by interviews with API manufacturing executives, transdermal formulation scientists, hospital pharmacy directors, and alkaloid supply chain managers. Secondary validation drew from FDA bioequivalence guidance documents, REACH compliance databases, ClinicalTrials.gov perioperative nausea protocols, and customs trade data for Datura biomass movements. Bottom-up patch volume modeling and top-down antiemetic market sizing were triangulated for consistency.
Input-output matrices structured demand drivers across delivery technology, therapy area, formulation release kinetics, and distribution channel dimensions. CAGRs were derived from procedure volume elasticity modeling and price-volume tier negotiations in integrated delivery networks. Forecast inputs included ambulatory surgery growth projections, alkaloid yield variance ranges, and bioequivalence validation timeline assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA guidance finalization timing, climate-induced Datura yield shocks, and microneedle technology adoption curves. A model refresh is warranted upon material change in transdermal bioequivalence regulatory standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Pharmaceutical Hot Melt Extrusion Market
Pharmaceutical Ingredients
Global Active Pharmaceutical Ingredients CDMO Market
Pharmaceutical Ingredients
Penciclovir API Market
Pharmaceutical Ingredients
Flurbiprofen Market
Pharmaceutical Ingredients
Duloxetine API Market
Pharmaceutical Ingredients
Tranexamic Acid API Market
Pharmaceutical Ingredients
Calcium Gluconate Market
Pharmaceutical Ingredients
Active Pharmaceutical Ingredient for Cancer Market
Pharmaceutical Ingredients
Citicoline Market
Pharmaceutical Ingredients
Global Fibrate Drugs Market
Pharmaceutical Ingredients
Cyclooxygenase 2 Inhibitor Market
Pharmaceutical Ingredients
Pharmaceutical Suspension Market
Pharmaceutical Ingredients
Silver Sulfadiazine Market
Pharmaceutical Ingredients
Global Pharmaceutical Excipients Market
Pharmaceutical Ingredients
Oxycodone Drugs Market
Pharmaceutical Ingredients
North America Active Pharmaceutical Ingredients Market