
 Piperacillin Sodium API Market | 2026-2036
Piperacillin Sodium API Market Size, Share, and Industry Trends Forecast 2026-2036
Piperacillin Sodium API Market Insights
Capital-intensity divergence between fermentation-scale manufacturers and formulation specialists is redrawing competitive boundaries in piperacillin sodium API supply. Qilu Pharmaceutical leverages vertically integrated fermentation infrastructure to dominate bulk intermediate output. Fresenius Kabi anchors European hospital contract demand through sterile injectable specialization. Aurobindo Pharma competes on cost-optimized oral-grade capacity serving generic formulation clients.
Piperacillin sodium API is a semisynthetic broad-spectrum penicillin antibiotic active pharmaceutical ingredient, synthesized from 6-aminopenicillanic acid via acylation with piperacillin acid chloride, typically supplied as a sterile lyophilized powder meeting USP/EP endotoxin limits below 0.06 EU/mg for parenteral use against gram-negative and anaerobic pathogens. Injectable formulations lead value capture due to hospital-critical administration routes and sterility-assurance costs, while lyophilized formats command premium positioning over liquid alternatives for stability-sensitive supply chains. Therapy-area segmentation clusters around antimicrobial applications, with hospital infections representing the fastest-growing demand node as multidrug-resistant Pseudomonas strains expand treatment protocols.
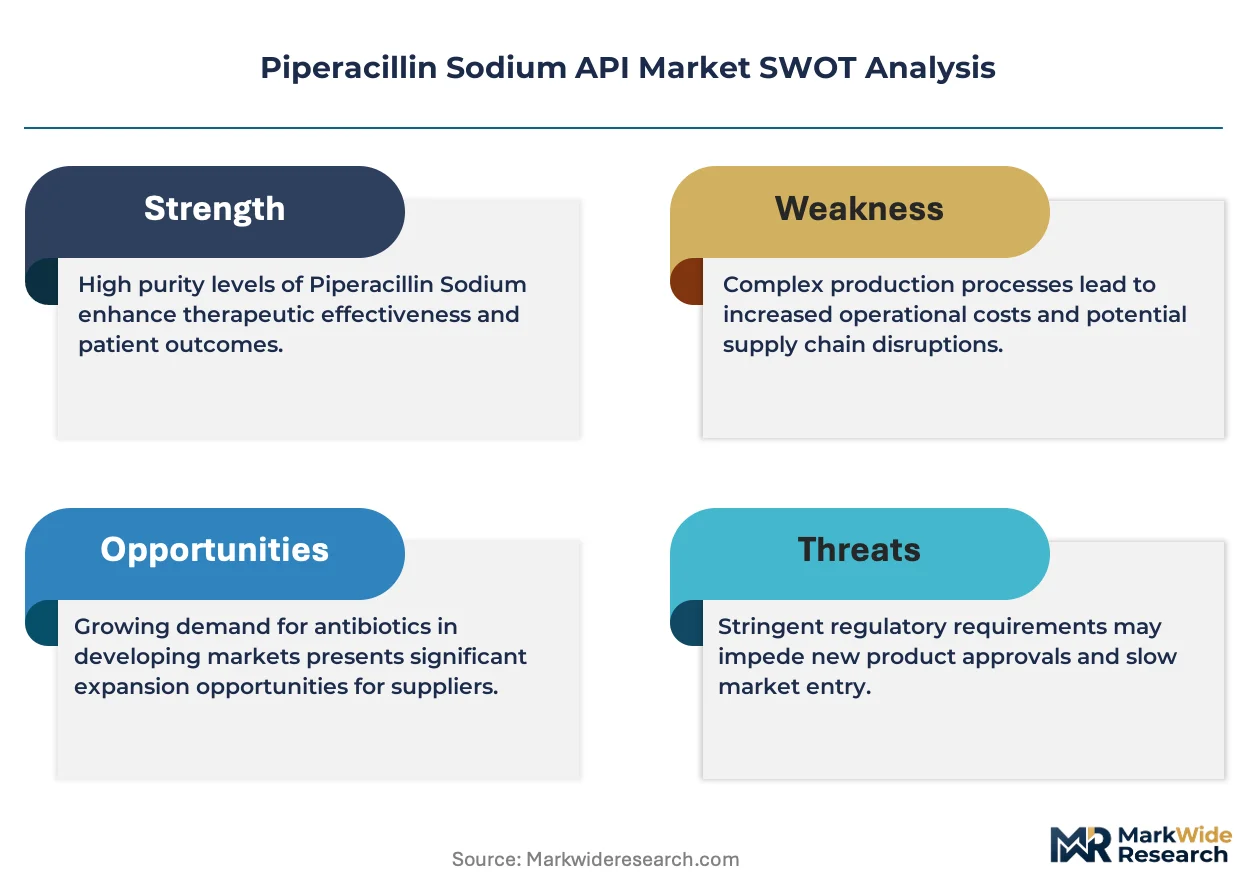
US FDA, EMA, and China's NMPA enforce divergent sterile API validation requirements that fragment compliance architectures and raise barrier costs for cross-border suppliers. India's CDSCO aligns with ICH Q7 guidelines but adds local stability-testing mandates that delay market entry timelines. Stakeholders must monitor regulatory harmonization negotiations between FDA and NMPA while building redundant sterile manufacturing footprints to preserve contract eligibility across jurisdictions.
Market Dynamics
Fermentation-scale manufacturing concentration in Shandong and Gujarat is redrawing competitive boundaries, as sterile API validation costs force mid-tier suppliers toward contract manufacturing exits.
Growth Catalysts
- US FDA Endotoxin Standards:Tightened sterile API requirements below 0.06 EU/mg are consolidating demand toward validated manufacturers with redundant sterile footprints.
- Hospital Pharmacy Centralization:Injectable antibiotic procurement through hospital group purchasing organizations concentrates volume with API suppliers holding sterile lyophilization capability.
- Pseudomonas Resistance Protocols:Multidrug-resistant strain expansion in intensive care units is widening piperacillin-tazobactam combination therapy indications.
Market Restraints
- 6-APA Feedstock Volatility:Penicillin G potassium price swings from Chinese fermentation plants transmit directly to piperacillin sodium cost structures.
- Sterile Manufacturing Concentration:Bulk lyophilized API output clusters among three Shandong-based producers, creating single-source vulnerability for European formulation clients.
- Carbapenem Substitution:Meropenem and imipenem formulations displace piperacillin combinations in sepsis protocols at tertiary hospitals with broad-spectrum resistance concerns.
Strategic Opportunities
- Southeast Asia Hospital Buildout:Vietnam and Indonesia are expanding ICU bed capacity without domestic sterile API infrastructure, creating import-dependent demand nodes.
- EMA Regulatory Tailwind:The EU's pharmaceutical strategy for critical medicines lists beta-lactam APIs as strategic, opening procurement preference windows for compliant suppliers.
- Continuous Manufacturing Convergence:Integration of process analytical technology with single-use bioreactor systems enables smaller-batch sterile output with reduced validation overhead.
Industry Challenges
- Sterile Process Engineer Scarcity:Aseptic filling and lyophilization specialization shortages in Indian pharmaceutical clusters delay facility commissioning timelines.
- Cross-Jurisdictional Compliance Burden:Simultaneous USP, EP, and NMPA validation requirements force redundant stability testing protocols that compress margin structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Piperacillin Sodium API Market |
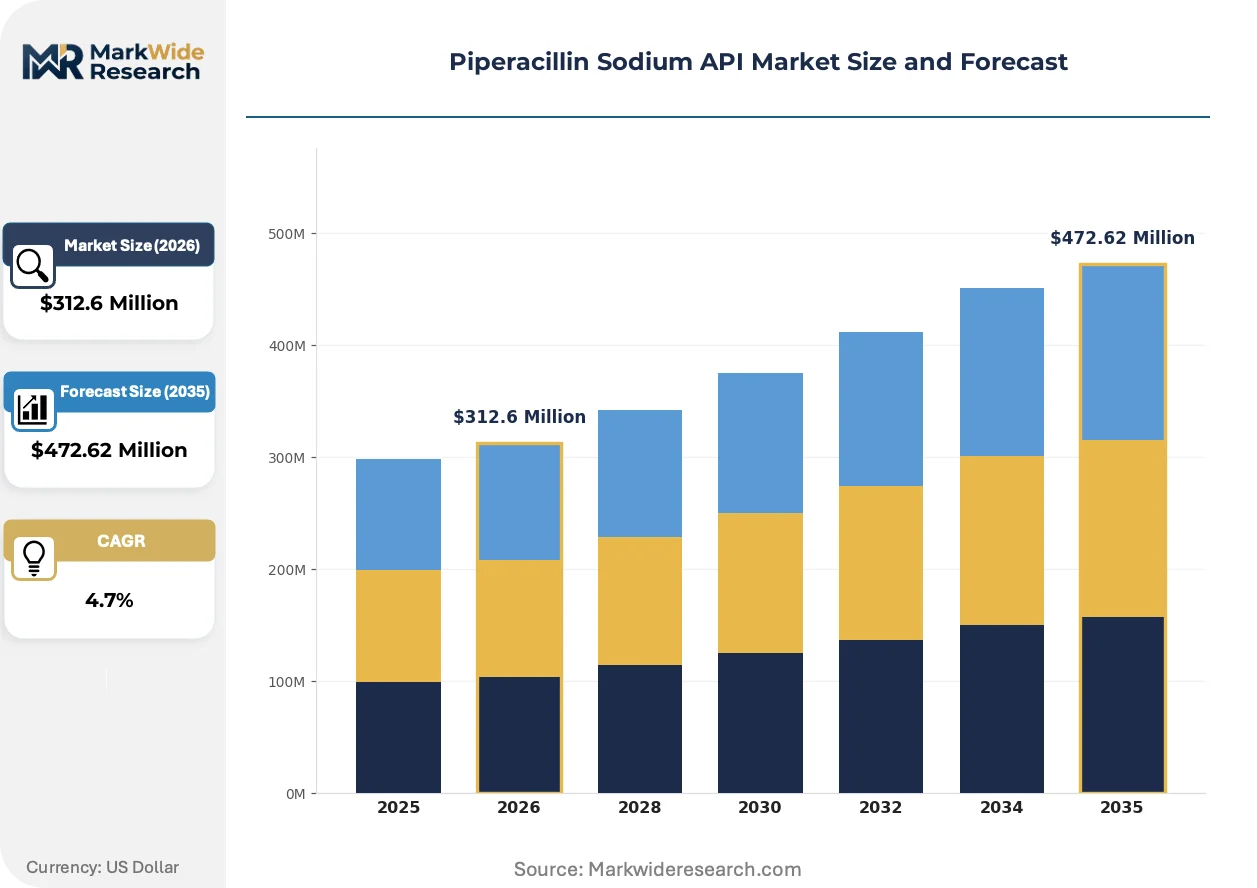
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $472.62 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Oral, Powder, Solution Therapy Area: Antibiotic, Antiinfective, Antimicrobial, Hospital Infections End User: Pharmacies, Hospitals, Clinics, Research Laboratories Formulation: Sterile, Non-Sterile, Lyophilized, Liquid |
| Companies Covered | Qilu Pharmaceutical, Pfizer Healthcare, Fresenius Kabi, Aurobindo Pharma, Sandoz, NCPC, Hunan Kelun Pharmaceutical, Yuhan Corporation, Nectar Lifesciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piperacillin Sodium API Market Trends and Innovations
Antibiotic API manufacturing is splitting between mass fermentation commodity output and precision sterile formulation, with technology choices determining which tier suppliers can access.
Single-use bioreactor systems for beta-lactam fermentation are bifurcating the supplier base. Large-scale stainless-steel facilities in Shandong and Hebei maintain 10,000+ liter batch economies for 6-APA intermediates. Mid-tier Indian manufacturers adopt 2,000-liter single-use trains to reduce cross-contamination validation burdens for niche cephalosporin and penicillin derivatives. This technology split is compressing the middle tier of fermentation specialists who lack scale or flexibility advantages.
EMA's revised Annex 1 sterile manufacturing guidelines impose real-time environmental monitoring mandates for Grade A filling zones. European formulation contractors must retrofit isolator technology or exit parenteral antibiotic compounding. German and Italian sterile injectable specialists are absorbing compliance costs through five-year hospital contract extensions, locking out Asian API suppliers without European filling partnerships.
Hospital procurement consortia in France and Spain are consolidating antibiotic purchasing through centralized tender platforms. Regional pharmacy cooperatives replace individual hospital negotiations, compressing supplier lists to three validated API sources per therapeutic class. This concentration is most visible in Andalusia and Catalonia, where public health system integration has eliminated spot-market API purchases entirely.
Piperacillin Sodium API Market Segmentation
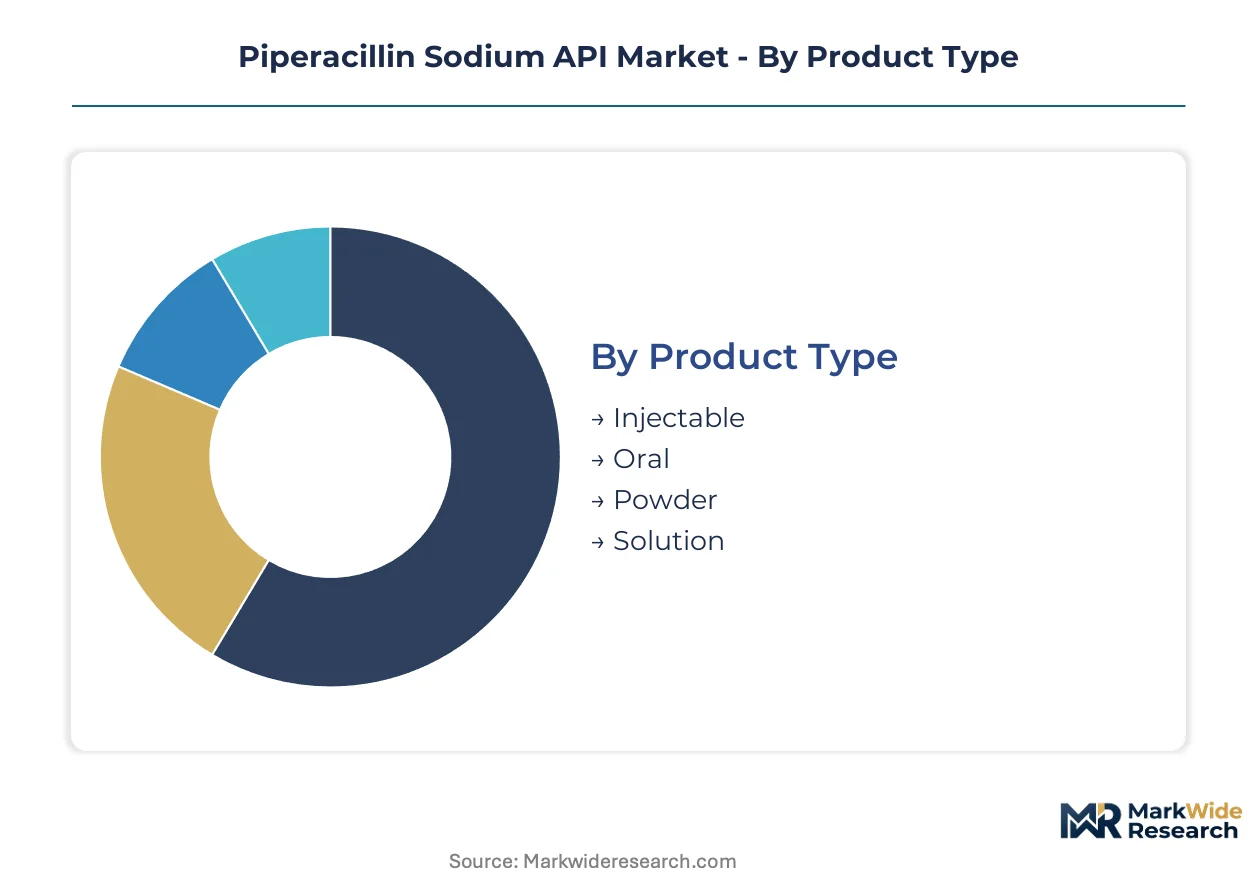
Piperacillin sodium API demand fragments across administration routes, sterility grades, and institutional procurement channels. Each segment carries distinct validation burdens and geographic concentration patterns that determine supplier viability.
Product Type:
Injectable formats dominate export flows to regulated markets, while oral grades serve cost-sensitive domestic formulation. Powder and solution variants split between hospital-critical and outpatient channels.
- Injectable:Sterile lyophilized vials meeting USP endotoxin limits below 0.06 EU/mg command premium positioning in European hospital contracts. Demand concentrates in Germany and Italy as EMA Annex 1 compliance costs eliminate spot-market sourcing.
- Oral:Capsule-grade API with reduced sterility assurance requirements serves generic formulation clients in India and Southeast Asia. Cost-optimized capacity in Gujarat feeds regional distributors serving outpatient antibiotic protocols.
- Powder:Bulk lyophilized intermediate for reconstitution at compounding pharmacies. Shandong fermentation clusters supply this grade to Middle Eastern hospital systems without domestic sterile infrastructure.
- Solution:Ready-to-infuse liquid formulations for ICU settings. Limited shelf stability restricts this segment to domestic supply chains with rapid distribution networks.
Injectable holds the largest share; momentum sits with powder formats as hospital buildout accelerates in import-dependent regions.
Therapy Area:
Clinical application determines regulatory pathway and pricing tier, with hospital-critical indications justifying sterility premium.
- Antibiotic:Broad-spectrum penicillin classification drives formulary inclusion across WHO essential medicines lists. Procurement through centralized hospital tenders in France and Spain concentrates volume with validated suppliers.
- Antiinfective:Combination therapy with tazobactam for beta-lactamase coverage. Pseudomonas resistance protocols in US intensive care units are widening indication breadth for this segment.
- Antimicrobial:Prophylactic surgical applications in orthopedic and abdominal procedures. EMA strategic medicines designation opens procurement preference windows for compliant European manufacturers.
- Hospital Infections:Nosocomial pneumonia and bloodstream infection protocols. Vietnam and Indonesia ICU expansion without domestic API infrastructure creates import-dependent demand nodes climbing the fastest.
Antibiotic maintains formulary dominance; hospital infections is gaining share fastest as multidrug-resistant strain protocols proliferate.
End User:
Procurement centralization varies sharply by institution type, fragmenting supplier access patterns.
- Pharmacies:Retail and hospital dispensaries with varying sterility requirements. European hospital pharmacy centralization through group purchasing organizations concentrates volume with API suppliers holding redundant sterile footprints.
- Hospitals:Tertiary care systems with in-house compounding capabilities. US 340B program eligibility and EMA strategic procurement lists create dual-track compliance requirements for contract suppliers.
- Clinics:Outpatient infusion centers and surgical day units. Limited cold-chain infrastructure in Southeast Asian markets favors lyophilized stability over liquid alternatives.
- Research Laboratories:Investigational compound supply and resistance surveillance programs. Small-batch sterile output with reduced validation overhead enables single-use bioreactor suppliers to serve this niche.
Hospitals capture the greatest procurement volume; research laboratories present the steepest expansion trajectory as antimicrobial resistance monitoring intensifies.
Formulation:
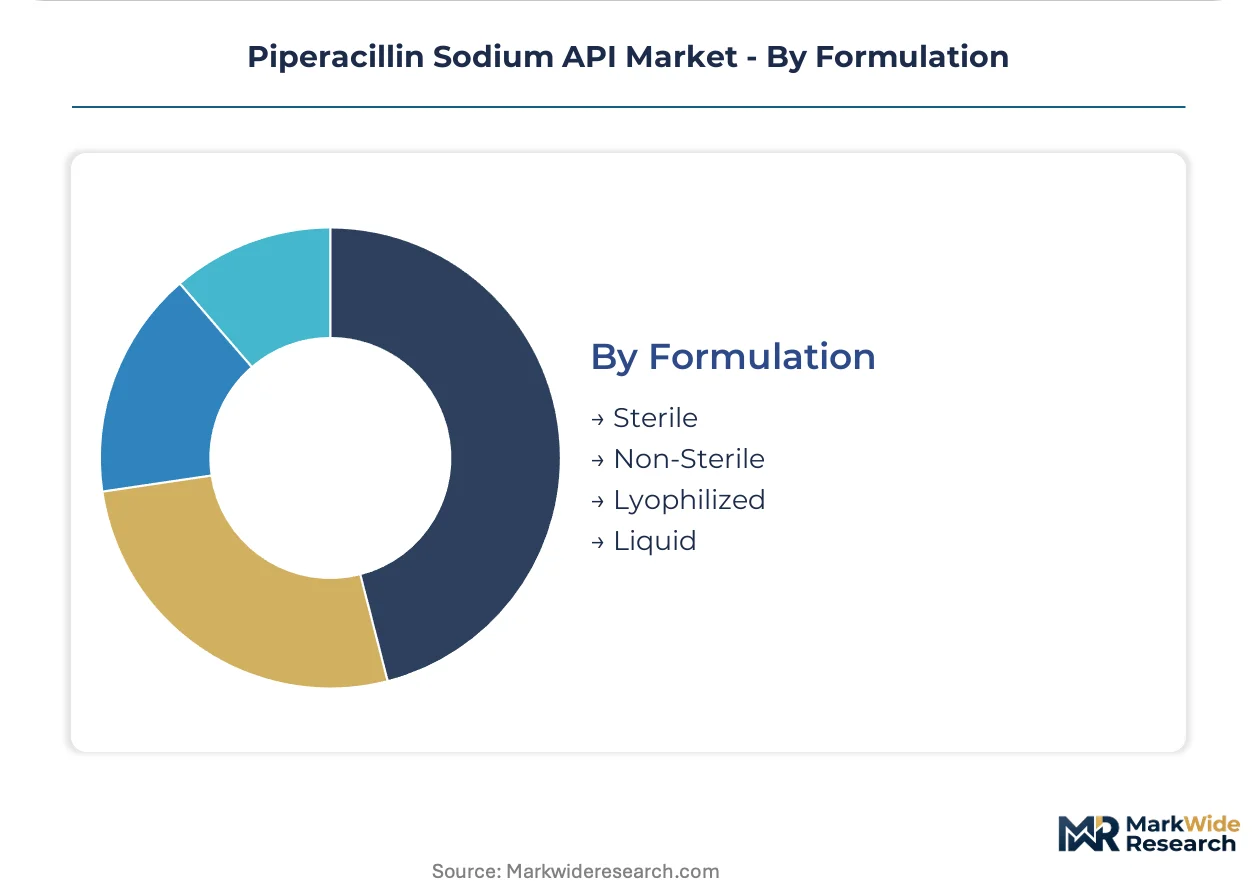
Manufacturing technology choice determines which regulatory jurisdictions remain accessible to suppliers.
- Sterile:Aseptic filling and terminal sterilization for parenteral administration. Real-time environmental monitoring mandates under EMA Annex 1 are forcing retrofit investments or market exits among European formulation contractors.
- Non-Sterile:Oral-grade API with reduced bioburden specifications. Indian CDSCO stability-testing mandates delay market entry timelines despite alignment with ICH Q7 guidelines.
- Lyophilized:Freeze-dried powder for extended shelf stability. Three Shandong-based producers cluster bulk output, creating single-source vulnerability for European formulation clients.
- Liquid:Ready-to-use solutions requiring cold-chain distribution. German and Italian sterile injectable specialists absorb compliance costs through five-year hospital contract extensions, locking out Asian suppliers without European filling partnerships.
Sterile formulations command premium positioning; lyophilized formats are expanding most quickly as supply chain resilience priorities reshape procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry between German hospital procurement consortia and Shandong fermentation clusters is redrawing API trade flows. European formulation contractors absorb sterility-validation premiums while Chinese bulk manufacturers capture intermediate volume.
United States
Hospital group purchasing organizations concentrate injectable antibiotic procurement with FDA-validated suppliers holding redundant sterile footprints. The US FDA's tightened endotoxin standards below 0.06 EU/mg are consolidating demand toward manufacturers with isolator technology. New Jersey and Massachusetts formulation specialists absorb compliance costs through five-year 340B program contract extensions.
China
Shandong and Hebei fermentation clusters dominate 6-APA intermediate output for piperacillin sodium synthesis. The NMPA's sterile API validation requirements are fragmenting compliance architectures for cross-border suppliers. Qilu Pharmaceutical leverages vertically integrated infrastructure in Jinan to anchor bulk lyophilized API production for Middle Eastern hospital systems.
Germany
EMA Annex 1 environmental monitoring mandates force retrofit investments among sterile injectable contractors. The EU pharmaceutical strategy for critical medicines lists beta-lactam APIs as strategic, opening procurement preference windows. Fresenius Kabi anchors European hospital contract demand through Bad Homburg-based sterile formulation specialization.
India
Gujarat and Maharashtra fermentation facilities supply cost-optimized oral-grade API to Southeast Asian generic formulation clients. CDSCO stability-testing mandates delay market entry timelines despite alignment with ICH Q7 guidelines. Aurobindo Pharma competes on capacity serving regional distributors while facing sterile process engineer scarcity in Hyderabad clusters.
Vietnam
ICU bed expansion without domestic sterile API infrastructure creates import-dependent demand nodes for lyophilized formats. Limited cold-chain infrastructure favors stability-sensitive powder over liquid alternatives. Ho Chi Minh City hospital procurement is climbing fastest as multidrug-resistant Pseudomonas protocols proliferate in tertiary care systems.
Piperacillin Sodium API Market Competitive Landscape
Concentration sits with fermentation-scale manufacturers possessing vertically integrated 6-APA supply chains and sterile formulation specialists holding EMA-validated isolator technology. Mid-tier suppliers lacking either scale advantage or regulatory certification face contract manufacturing exits. Three strategic archetypes dominate: Chinese bulk intermediate producers, European hospital-contract injectable specialists, and Indian cost-optimized oral-grade suppliers. Competitive moves center on sterile manufacturing footprint expansion and five-year hospital contract lock-ins.
Within the fermentation-scale tier, Qilu Pharmaceutical and NCPC exemplify Chinese producers leveraging Shandong-based infrastructure for bulk intermediate output. Among sterile formulation specialists, Fresenius Kabi occupies a position representing European hospital-contract anchoring through EMA-compliant injectable capacity. Aurobindo Pharma sits within the cost-optimized tier, serving generic formulation demand from Indian manufacturing clusters.
| Leading Market Players |
|---|
| Qilu Pharmaceutical |
| Pfizer Healthcare |
| Fresenius Kabi |
| Aurobindo Pharma |
| Sandoz |
| NCPC |
| Hunan Kelun Pharmaceutical |
| Yuhan Corporation |
| Nectar Lifesciences |
| Others |
Pricing and Supply Chain Analysis
EMA Annex 1 sterile manufacturing guidelines gate both supply qualification and price differentiation simultaneously, as real-time environmental monitoring mandates force retrofit investments that stratify API suppliers across premium validated tiers and marginal spot-market players. Hospital procurement consortia in France and Spain concentrate volume with manufacturers holding redundant sterile footprints, compressing margins for mid-tier competitors lacking isolator technology or European filling partnerships.
Pricing Analysis
The customization-premium spread separates sterile lyophilized vials configured to EMA-validated specifications from standard oral-grade powder serving cost-sensitive generic formulation clients. Pricing stratifies across premium, standard, and economy tiers based on endotoxin certification level below 0.06 EU/mg and geographic delivery cost to regulated markets. Cost compression in the oral-grade tier is intensifying because Indian CDSCO stability-testing mandates delay market entry despite ICH Q7 alignment. Generic formulation clients in Southeast Asia exhibit highest price sensitivity, while European hospital group purchasing organizations absorb sterility-assurance premiums for parenteral administration routes.
Supply Chain Analysis
6-APA intermediate concentration in Shandong and Hebei province fermentation clusters creates single-source vulnerability for European formulation clients dependent on Chinese bulk output. Raw material supply draws from penicillin G potassium fermentation, piperacillin acid chloride acylation reagents, and sterile lyophilization excipients. Tariff exposure on beta-lactam API imports into the European Union threatens margin structures for contract manufacturers without localized filling partnerships. Distribution runs through hospital group purchasing organizations in Germany and Italy, with spot-market channels collapsing as EMA compliance costs eliminate non-validated suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Piperacillin sodium API sits in early-cycle expansion as multidrug-resistant Pseudomonas protocols proliferate across Vietnam and Indonesia ICU buildouts, creating import-dependent demand nodes without domestic sterile infrastructure.
For Market Incumbents: Consolidate sterile manufacturing footprint expansion in Shandong and Gujarat to anchor bulk intermediate output against carbapenem substitution threats in sepsis protocols. Deepen backward integration into 6-APA captive supply to buffer penicillin G potassium price volatility from Chinese fermentation plants. Lock in five-year hospital contract extensions through European formulation partnerships to defend against Asian suppliers lacking EMA-validated isolator technology.
For New Entrants and Emerging Players: Anchor in Vietnam and Indonesia hospital procurement channels where ICU bed expansion outpaces domestic sterile API infrastructure. Target research laboratory supply niches enabled by single-use bioreactor systems with reduced validation overhead for antimicrobial resistance surveillance programs. Pursue continuous manufacturing convergence with process analytical technology to bypass large-scale stainless-steel facility capital requirements.
For Investors and Strategic Acquirers: EMA's pharmaceutical strategy for critical medicines listing beta-lactam APIs as strategic reshapes the acquisition landscape toward European hospital-contract anchoring positions. Long-term viability over the next decade hinges on sterile process engineer access and redundant regulatory footprints across FDA, EMA, and NMPA jurisdictions. Acquire mid-tier Indian manufacturers with CDSCO-aligned capacity serving Southeast Asian generic demand. Monitor NMPA-FDA harmonization negotiations as the signal for cross-border supply consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Sterile Manufacturing Footprint Expansion | Isolator technology investments in Shandong secure EMA Annex 1 compliance for European hospital contracts. |
| Backward Integration into 6-APA Supply | Captive penicillin G potassium fermentation buffers feedstock volatility from Chinese intermediate markets. |
| Continuous Manufacturing Adoption | Single-use bioreactor integration with PAT enables niche batch output with reduced validation overhead. |
| Five-Year Hospital Contract Lock-In | German and Italian GPO extensions absorb compliance costs while excluding Asian suppliers without local filling partnerships. |
| Research Laboratory Channel Development | Small-batch sterile output serves antimicrobial resistance surveillance programs with faster regulatory pathways. |
Research Methodology
A standing panel of sterile process engineers, hospital procurement managers, regulatory affairs leads, and API manufacturing executives provided ongoing calibration across primary interview rounds and secondary validation. Primary fieldwork combined structured conversations with fermentation-scale manufacturers in Shandong and Gujarat, formulation specialists in Bad Homburg and New Jersey, and group purchasing organization contract directors in France and Spain. Secondary sources encompassed FDA 483 inspection observations, EMA GMP non-compliance reports, CDSCO submission databases, and customs trade flow records for beta-lactam API movements. Bottom-up volume builds across administration routes, sterility grades, and institutional channels triangulated against top-down therapeutic class expenditure estimates.
Consistency checks validated projection outputs against external benchmarks including hospital antibiotic procurement databases, GPO contract award disclosures, and sterile API import volumes into the European Union and United States. The analytical framework modeled segmentation across injectable versus oral administration routes, sterile versus non-sterile manufacturing technology, and regional regulatory clusters spanning FDA, EMA, and NMPA jurisdictions. CAGRs derived from volume trajectory analysis incorporating ICU bed expansion rates, multidrug-resistant strain surveillance data, and formulary inclusion protocols for piperacillin-tazobactam combination therapy.
Underlying assumptions cover sustained endotoxin standard enforcement below 0.06 EU/mg, continued 6-APA supply concentration in Chinese fermentation clusters, and stable hospital pharmacy centralization trends, with deviation risk concentrated in carbapenem substitution acceleration or NMPA-FDA regulatory harmonization breakthrough. Practitioners should keep alternative scenarios live as Pseudomonas resistance protocol evolution and Southeast Asian hospital buildout completion rates shift demand node geography.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Pharmaceutical Indicator Strips Market
Pharmaceutical Ingredients
Cyprosin Market
Pharmaceutical Ingredients
Amphetamine Drug Market
Pharmaceutical Ingredients
Medicinal Chemistry for Drug Discovery Market
Pharmaceutical Ingredients
Pharmaceutical Thermal Analysis Market
Pharmaceutical Ingredients
Flurbiprofen Market
Pharmaceutical Ingredients
Cyclooxygenase 2 Inhibitor Market
Pharmaceutical Ingredients
Pemetrexed Market
Pharmaceutical Ingredients
Global Small Molecule API Market
Pharmaceutical Ingredients
Global Barbiturate Drugs Market
Pharmaceutical Ingredients
Antibiotics Active Pharmaceutical Ingredient (API) Market
Pharmaceutical Ingredients
Fosfomycin Trometamol Powder Market
Pharmaceutical Ingredients
Global Cephalosporin Drugs Market
Pharmaceutical Ingredients
Originator Small Molecule Drug Market
Pharmaceutical Ingredients
Asia-Pacific Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceutical Ingredients
Prescription Hair Loss and Hair Removal Drugs Market