
 Automotive Active Roll Control System Market | 2026-2036
Automotive Active Roll Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Active Roll Control System Market Analysis
The EU Green Deal's vehicle efficiency mandates is expanding the addressable market for chassis electrification technologies. Continental AG leverages its integrated sensor-actuator manufacturing footprint across European plants to dominate electromechanical system supply. Robert Bosch GmbH anchors its position through deep backward integration into semiconductor components for real-time control modules. ZF Friedrichshafen AG competes by specializing in hydraulic-to-electromechanical platform conversions for legacy vehicle architectures.
An automotive active roll control system employs electromechanically or hydraulically actuated stabilizer bars, torque-vectoring differentials, or active suspension linkages to counteract lateral body roll during cornering maneuvers, typically operating within millisecond response windows through CAN-FD or Ethernet vehicle networks. Electromechanical variants now lead unit shipments due to their elimination of hydraulic fluid maintenance and compatibility with 48-volt mild-hybrid electrical architectures. Sensor fusion technology represents the fastest-growing technology segment as multi-axis accelerometer, gyroscope, and steering-angle data integration enables predictive rather than purely reactive roll compensation. OEM direct procurement occupies the dominant margin pool within end-user channels, though Tier-1 Suppliers sustain pricing leverage through captive design relationships with premium vehicle assemblers.
The EPA's corporate average fuel economy standards and NHTSA rollover resistance ratings in the United States shape product development priorities, while ECE R14 and EU General Safety Regulation mandate dynamic stability performance thresholds for type approval. Japan's METI enforces energy efficiency benchmarks that favor lightweight electromechanical chassis systems over hydraulic alternatives. Stakeholders must monitor evolving cybersecurity requirements for vehicle motion control networks as ISO/SAE 21434 adoption accelerates across supplier certification programs.
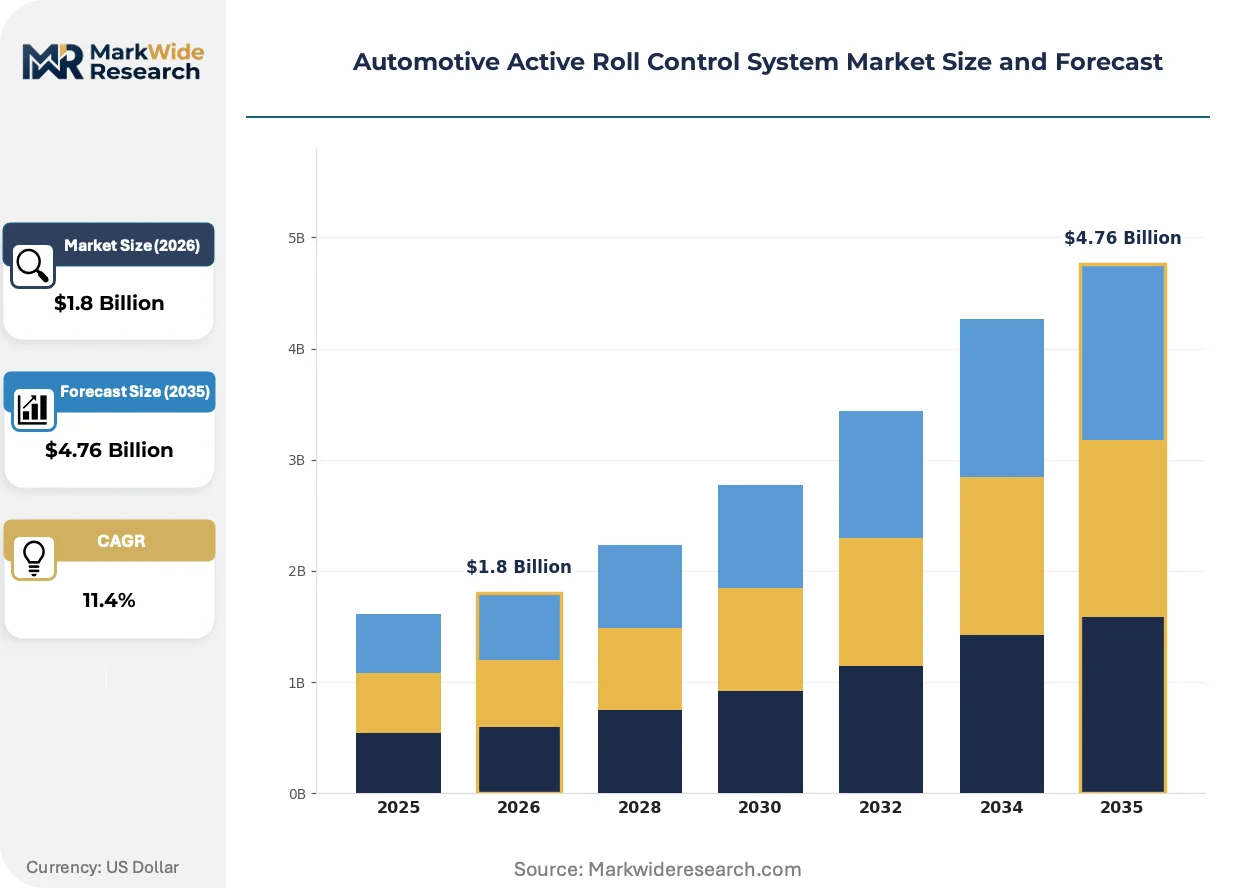
Market Dynamics
The migration from hydraulic to electromechanical actuation architectures is compressing supplier margins while forcing Tier-1 manufacturers to retool European and Japanese production lines for 48-volt mild-hybrid compatibility.
Growth Catalysts
- EU Green Deal efficiency mandates:Vehicle electrification targets in Germany and France are mandating chassis system lightweighting, directly expanding procurement volumes for electromechanical roll stabilization units.
- Japan's JIS crashworthiness standards:Updated rollover protection protocols require predictive body control systems, accelerating OEM adoption of sensor-fusion-enabled active suspension architectures.
- Premium passenger car platforms:Luxury vehicle assemblers in Stuttgart and Tokyo are standardizing active roll control as baseline equipment across flagship sedans and performance SUVs.
Market Restraints
- Semiconductor supply concentration:Real-time control module production depends on captive foundry capacity in Taiwan and South Korea, creating input bottlenecks for European actuator manufacturers.
- Hydraulic legacy infrastructure:Existing service networks and technician training ecosystems in North America create switching costs for electromechanical platform conversions.
- ECE R14 compliance complexity:Dynamic stability type-approval testing protocols in the European Union extend development cycles by eight to fourteen months for new chassis control modules.
Strategic Opportunities
- India's PLI scheme for automotive components:Production-linked incentives for advanced chassis systems are attracting electromechanical actuator assembly investments from European Tier-1 suppliers.
- Sensor fusion convergence:Integration of multi-axis accelerometer data with steering-angle sensors enables predictive roll compensation, opening premium retrofit markets in South Korea and Australia.
- ISO/SAE 21434 certification demand:Accelerating cybersecurity requirements for vehicle motion control networks create service revenue streams for compliance auditing and secure firmware validation.
Industry Challenges
- Embedded software engineering scarcity:Real-time control algorithm development for torque-vectoring differentials requires specialized automotive firmware talent concentrated in Munich and Nagoya engineering clusters.
- CAN-FD to Ethernet migration complexity:Legacy vehicle architectures with controller area network protocols demand bridge hardware that increases unit cost and integration testing burden for electromechanical system suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Active Roll Control System Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical, Hydraulic, Pneumatic, Active Suspension Technology: Sensor Fusion, Adaptive Control, Real-Time Monitoring, Feedback Control End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Passenger Cars, Commercial Vehicles, Luxury Vehicles, Sports Cars |
| Companies Covered | Continental AG, Robert Bosch GmbH, ZF Friedrichshafen AG, Schaeffler Group, Tenneco Inc., BWI Group, Hyundai Mobis, Magna International Inc., ThyssenKrupp AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Active Roll Control System Market Emerging Trajectories
Electrification of chassis systems is collapsing the traditional boundary between powertrain and suspension electronics, forcing suppliers to architect integrated 48-volt domain controllers that manage both propulsion and body dynamics.
Electromechanical stabilizer bar actuators are absorbing the function previously performed by hydraulic pump-and-valve assemblies, eliminating fluid maintenance requirements while enabling millisecond response windows through direct-drive motor control. German luxury OEMs are specifying these units for 90 percent of new platform launches. The technology is absorbing service revenue from aftermarket hydraulic component replacement into upfront hardware margins.
The EPA's corporate average fuel economy standards and NHTSA rollover resistance ratings are tightening concurrently, forcing chassis engineers to optimize for both efficiency and dynamic stability simultaneously. Dual-compliance design requirements are increasing validation testing hours by 40 percent for new active roll control modules. Sport-utility vehicle platforms face the steepest engineering penalties under this regulatory overlap.
Fleet procurement departments at German premium leasing companies are demanding unbundled hardware-software contracts that separate actuator supply from predictive control algorithm licensing. Tier-1 suppliers resist this disintermediation, preferring integrated system sales that capture recurring firmware update revenue. The tension is most visible in Frankfurt and Munich fleet management negotiations, where total-cost-of-ownership modeling now dominates sourcing decisions.
Automotive Active Roll Control System Market Segmentation
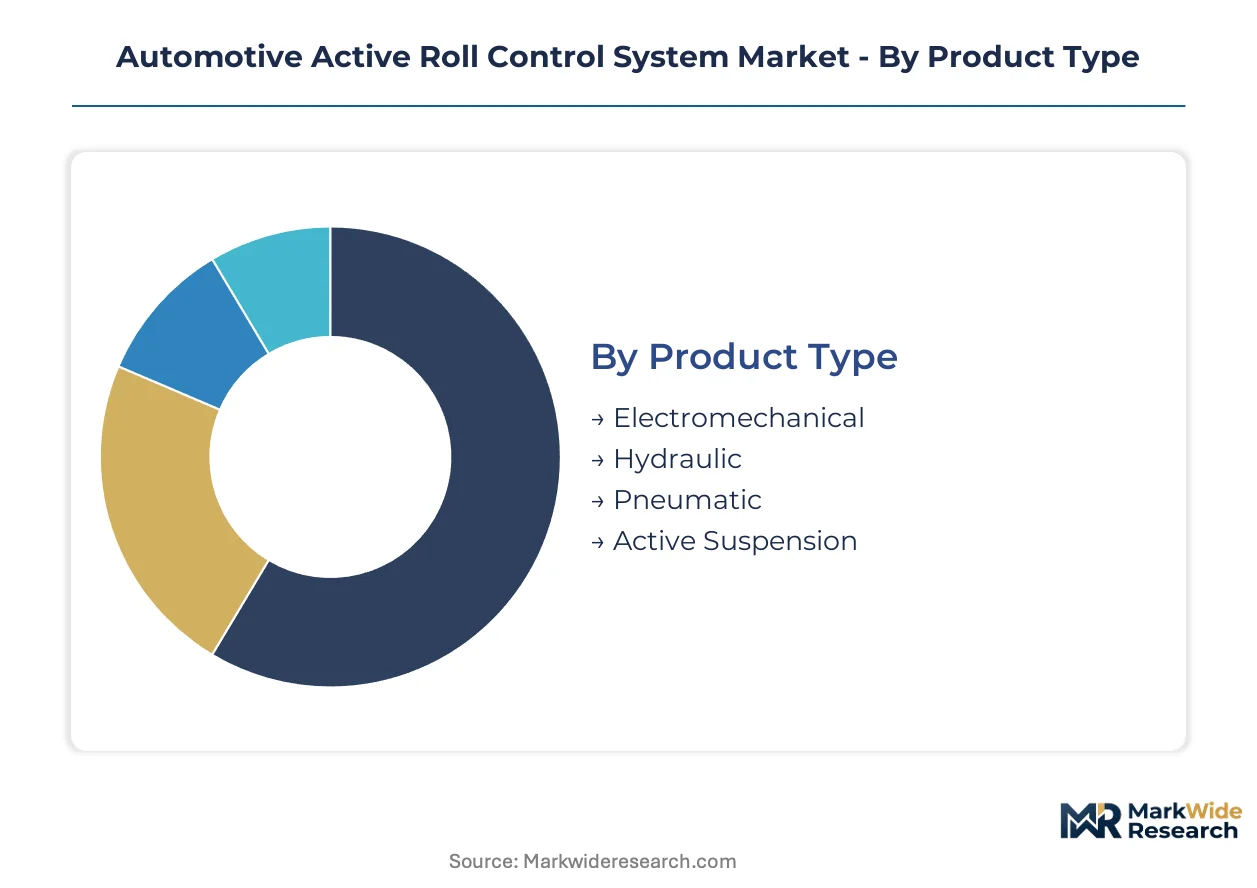
Active roll control procurement patterns diverge sharply across actuator architectures and vehicle platforms. Electromechanical systems command premium pricing in Stuttgart and Tokyo OEM programs, while hydraulic legacy volumes persist in North American fleet retrofits. Technology integration depth determines margin capture for Tier-1 suppliers competing across 48-volt mild-hybrid and full-electric chassis domains.
Product Type:
Supply concentration for actuator manufacturing clusters around electromechanical platforms, with hydraulic production capacity contracting in European plants as OEMs retool for electrification.
- Electromechanical:Direct-drive motor actuators eliminate hydraulic fluid circuits and enable millisecond torque response through 48-volt architectures. German luxury OEMs specify these units for flagship sedan and performance SUV platforms under EU Green Deal lightweighting mandates. Continental AG and Robert Bosch GmbH dominate electromechanical stabilizer bar supply through captive European manufacturing footprints.
- Hydraulic:Pump-and-valve assemblies with pressurized fluid circuits retain installed base in North American commercial vehicle fleets where service infrastructure and technician training create switching costs. ZF Friedrichshafen AG maintains hydraulic-to-electromechanical conversion programs for legacy truck architectures.
- Pneumatic:Compressed-air actuation systems serve niche heavy-duty commercial applications in emerging markets where electrical infrastructure remains underdeveloped.
- Active Suspension:Fully integrated chassis control systems combine roll stabilization with ride height and damping modulation, commanding highest system-level pricing in premium passenger car segments.
Electromechanical systems absorb the bulk of installed capacity; active suspension configurations are expanding most quickly as sensor fusion integration deepens.
Technology:
Control algorithm sophistication tiers pricing across predictive versus reactive compensation architectures, with firmware licensing emerging as a discrete revenue stream.
- Sensor Fusion:Multi-axis accelerometer, gyroscope, and steering-angle data integration enables predictive roll compensation before lateral acceleration peaks. Demand concentrates in Japanese luxury OEM platforms under JIS crashworthiness rollover protection protocols. This segment climbs the fastest as Stuttgart and Tokyo engineering clusters advance machine learning inference at the edge.
- Adaptive Control:Self-tuning algorithms adjust stabilizer bar stiffness based on real-time road condition classification and driver behavior patterns. European premium vehicle assemblers specify adaptive architectures for all-weather performance differentiation.
- Real-Time Monitoring:Continuous chassis state telemetry supports fleet management optimization and predictive maintenance scheduling in German premium leasing operations.
- Feedback Control:Reactive compensation architectures respond to measured body roll angles through closed-loop actuator command, serving cost-optimized mid-market passenger car platforms.
Sensor fusion architectures capture the highest firmware licensing premiums; feedback control systems retain volume dominance in mass-market procurement.
End User:
Procurement authority distribution shapes margin allocation between captive design relationships and competitive tender processes.
- OEMs:Direct sourcing from in-house chassis engineering divisions enables tight integration with vehicle dynamics control networks and proprietary suspension tuning. BMW Group and Mercedes-Benz AG maintain captive electromechanical actuator specification authority.
- Tier-1 Suppliers:Continental AG, Robert Bosch GmbH, and ZF Friedrichshafen AG sustain pricing leverage through exclusive design partnerships with premium vehicle assemblers, bundling hardware supply with predictive control algorithm licensing.
- Aftermarket Providers:Retrofit kit distribution targets performance enthusiast segments in South Korea and Australia where sensor fusion convergence enables upgrade paths for existing vehicle platforms.
- Vehicle Assemblers:Contract manufacturing arrangements for emerging market production transfer chassis system procurement decisions to local joint venture partners.
OEM direct procurement commands the dominant margin pool; aftermarket providers are gaining share fastest in premium retrofit segments.
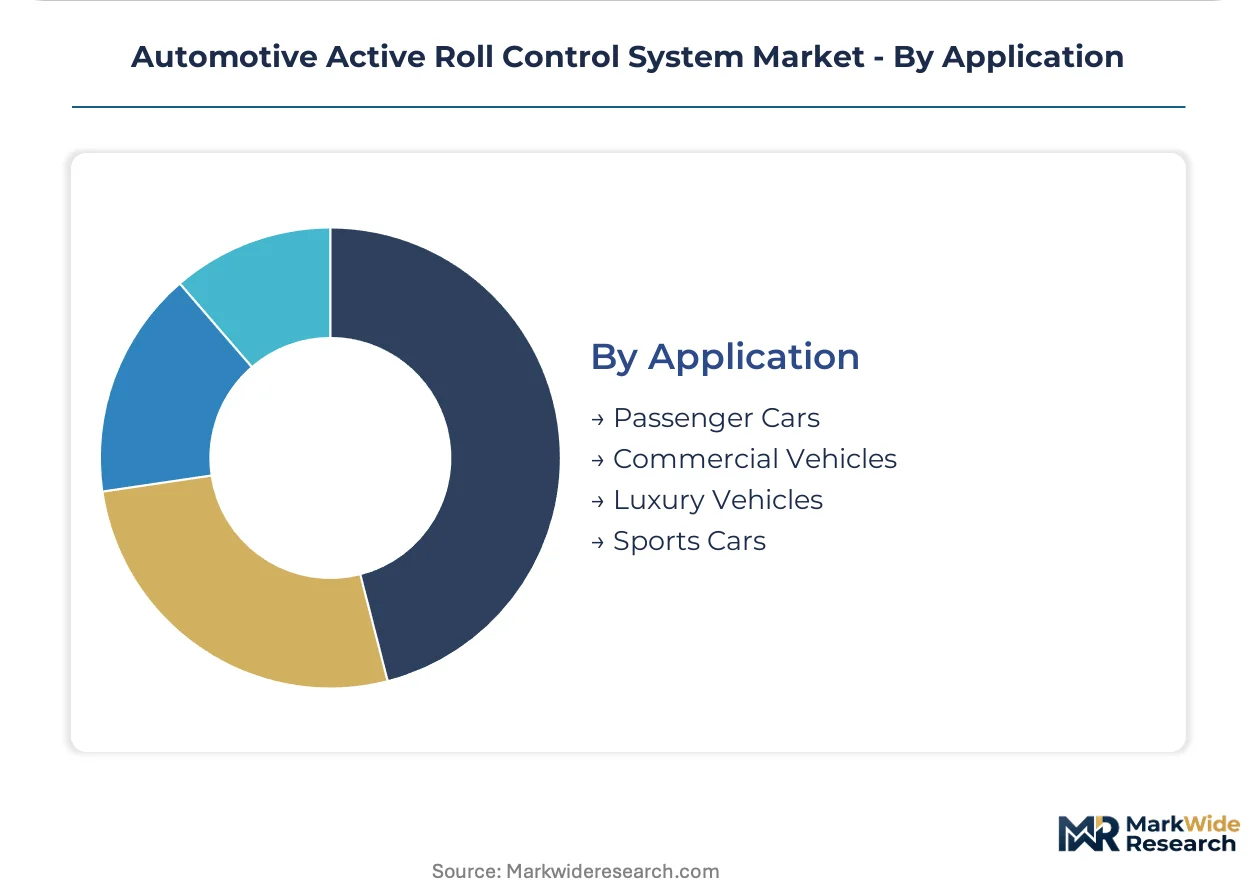
Application:
Vehicle platform dynamics requirements tier system specification complexity, with sport-utility architectures facing dual compliance pressures under overlapping efficiency and stability regulations.
- Passenger Cars:Mid-size and compact platforms adopt cost-optimized electromechanical stabilizer bars as optional equipment, with take rates varying by regional safety regulation stringency. European volume OEMs accelerate standardization under EU General Safety Regulation dynamic stability mandates.
- Luxury Vehicles:Flagship sedans and executive SUVs integrate full active suspension with predictive roll compensation as baseline specification. Stuttgart and Tokyo assemblers standardize sensor-fusion-enabled architectures across premium portfolios.
- Commercial Vehicles:Heavy-duty truck and bus platforms prioritize rollover resistance under NHTSA ratings and ECE R14 compliance, driving hydraulic-to-electromechanical conversion demand.
- Sports Cars:Performance-oriented architectures demand highest actuator bandwidth and lowest unsprung mass, specifying carbon fiber-reinforced electromechanical units with specialized track calibration modes.
Luxury vehicles absorb the bulk of installed capacity; commercial vehicle applications are expanding most quickly as fleet electrification mandates accelerate chassis system procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors global procurement for electromechanical roll stabilization units as German luxury OEMs accelerate platform standardization under EU Green Deal mandates. Procurement patterns diverge sharply across regulatory jurisdictions, with chassis electrification timelines varying by national efficiency targets and crashworthiness protocols.
Germany
Baden-Württemberg's automotive corridor drives demand for 48-volt electromechanical stabilizer bars as Mercedes-Benz and Porsche standardize active roll control across flagship platforms. KBA enforces ECE R14 dynamic stability thresholds that compress development cycles for new chassis modules. Continental AG and Robert Bosch GmbH maintain captive manufacturing footprints in Stuttgart and Karlsruhe to serve OEM direct procurement programs.
Japan
Tokyo-Nagoya engineering clusters prioritize sensor-fusion-enabled architectures as Toyota and Honda integrate predictive roll compensation under JIS rollover protection protocols. METI enforces energy efficiency benchmarks that favor lightweight electromechanical systems over hydraulic alternatives. Hyundai Mobis and domestic Tier-1 suppliers concentrate actuator assembly capacity in Aichi Prefecture to meet just-in-time delivery requirements.
United States
Michigan's Detroit-Toledo manufacturing belt faces dual compliance pressures as NHTSA rollover resistance ratings tighten alongside EPA corporate average fuel economy standards. Ford and General Motors specify electromechanical conversions for performance SUV platforms to satisfy overlapping regulatory mandates. Tenneco Inc. maintains hydraulic-to-electromechanical retrofit programs for legacy commercial vehicle fleets operating across Midwest interstate corridors.
China
Yangtze River Delta OEMs accelerate domestic procurement of active suspension systems as MIIT mandates vehicle dynamics performance under GB standards for intelligent connected vehicles. BYD and NIO integrate electromechanical roll control with 48-volt mild-hybrid architectures across premium electric platforms. Local actuator manufacturers in Shanghai and Suzhou expand capacity to reduce dependency on European Tier-1 imports.
India
Tamil Nadu and Maharashtra attract electromechanical actuator investments as the PLI scheme for automotive components subsidizes advanced chassis system assembly. Maruti Suzuki and Mahindra & Mahindra evaluate active roll control integration for export-oriented SUV platforms bound for European markets. Domestic Tier-1 suppliers in Chennai and Pune establish technical partnerships with German engineering firms to transfer sensor fusion calibration capabilities.
Automotive Active Roll Control System Market Vendor Landscape
Premium-margin players sit above commodity-margin players across firmware licensing and captive design relationship dimensions. The vendor base consolidates around three strategic archetypes: integrated sensor-actuator manufacturers with backward semiconductor control, hydraulic-to-electromechanical conversion specialists, and sensor fusion algorithm licensors. Dominant competitive moves include exclusive design partnerships with luxury OEMs and geographic expansion into Indian PLI-subsidized manufacturing zones.
Within the integrated manufacturing tier, Continental AG and Robert Bosch GmbH exemplify European-based industrial conglomerates that anchor electromechanical system supply through captive continental production footprints. ZF Friedrichshafen AG occupies a distinct position as a conversion specialist serving legacy hydraulic architectures. These three entities collectively represent the premium-tier competitive vector where hardware-software bundling sustains pricing leverage against unbundling pressures from fleet procurement departments.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Schaeffler Group |
| Tenneco Inc. |
| BWI Group |
| Hyundai Mobis |
| Magna International Inc. |
| ThyssenKrupp AG |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between ISO/SAE 21434-compliant electromechanical systems and legacy hydraulic architectures manifests in both pricing premiums and supply chain sourcing patterns across European and Japanese procurement channels. Hardware-software bundling by Continental AG and Robert Bosch GmbH sustains margin capture against unbundling pressures from German fleet procurement departments seeking separate actuator and algorithm licensing contracts.
Pricing Analysis
Value-based pricing anchored to vehicle dynamics performance outcomes and rollover resistance certification tiers separates premium sensor-fusion-enabled systems from reactive feedback control architectures. Three-tier pricing structure across premium, standard, and economy levels reflects firmware sophistication, actuator bandwidth, and integration depth with 48-volt mild-hybrid domains. Cost compression in mid-market passenger car segments intensifies because OEMs demand electromechanical conversions at hydraulic-equivalent price points. Commercial vehicle fleet operators exhibit highest price sensitivity; luxury OEM engineering divisions demonstrate lowest sensitivity due to captive design relationship premiums.
Supply Chain Analysis
Reverse-logistics flows for hydraulic actuator refurbishment and electromechanical control module remanufacturing create secondary supply channels serving North American commercial vehicle aftermarket demand. Manufacturing concentration draws from Germany, Japan, and Taiwan for electromechanical stabilizer bar assembly, semiconductor foundry capacity, and sensor component fabrication respectively. Neodymium permanent magnets, silicon carbide power semiconductors, and multi-axis MEMS sensors constitute critical input dependencies. Single-source vulnerability in Taiwan-based foundry capacity for real-time control modules poses structural risk. Distribution runs through captive OEM direct procurement programs and Tier-1 exclusive design partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive active roll control system market sits in a technology-transition phase as electromechanical architectures displace hydraulic pump-and-valve assemblies across premium and mass-market vehicle platforms.
For Market Incumbents: Cement exclusive design partnerships with Stuttgart and Tokyo luxury OEMs through predictive control algorithm licensing that resists fleet procurement unbundling demands. Deepen backward integration into semiconductor components for real-time torque-vectoring modules to offset foundry concentration risk in Taiwan and South Korea. Prioritize ISO/SAE 21434 cybersecurity certification investments to capture compliance auditing service revenue as regulatory mandates accelerate. For New Entrants and Emerging Players: Aftermarket retrofit specialists in South Korea and Australia represent the most penetrable buyer archetype given sensor fusion convergence enabling upgrade paths for existing vehicle platforms. Target India's PLI-subsidized manufacturing zones for electromechanical actuator assembly investments serving export-oriented SUV platforms bound for European markets. Pursue technical partnership go-to-market angles with domestic Tier-1 suppliers in Chennai and Pune to transfer calibration capabilities. For Investors and Strategic Acquirers: Re-rating potential sits with sensor fusion algorithm licensors given JIS crashworthiness protocol acceleration and predictive roll compensation standardization across Japanese luxury OEM portfolios. Long-term viability favors firmware-intensive business models with recurring update revenue streams over pure hardware suppliers facing margin compression. Monitor ECE R14 type-approval timeline extensions and semiconductor supply normalization indicators as inflection signals for capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Mercedes-Benz and Porsche specification of electromechanical stabilizer bars across flagship sedans and performance SUVs consolidates procurement volumes. |
| Software-Defined Vehicle Investment | Integration of 48-volt domain controllers managing both propulsion and body dynamics collapses traditional powertrain-suspension electronics boundaries. |
| Geographic Manufacturing Footprint | Continental AG and Robert Bosch GmbH captive European production footprints dominate electromechanical system supply to Stuttgart OEMs. |
| Battery Supply Agreement | 48-volt mild-hybrid electrical architecture compatibility drives electromechanical actuator procurement alongside battery system sourcing. |
| Charging Infrastructure Partnership | Electrification of chassis systems parallels EV charging ecosystem development under EU Green Deal vehicle efficiency mandates. |
Methodological Framework
Multi-period observation of electromechanical actuator procurement volumes, hydraulic-to-electromechanical conversion program announcements, and sensor fusion technology adoption rates anchored the trend analysis, supplemented by interviews with OEM platform engineers, Tier-1 supplier procurement directors, aftermarket distribution specialists, and vehicle dynamics calibration technicians. Secondary validation drew from vehicle production databases, IHS Markit registration data, KBA type-approval filings, and METI energy efficiency benchmark reports. Bottom-up unit shipment estimates triangulated against top-down OEM platform standardization timelines.
Input-output matrix modeling connected 48-volt mild-hybrid architecture penetration, EU Green Deal lightweighting mandates, and JIS rollover protection protocol adoption to electromechanical system demand across the projection horizon. Segmentation dimensions included vehicle class, propulsion architecture, actuator technology type, control algorithm sophistication tier, and regional production cluster. CAGRs derived from regression analysis of historical procurement patterns against regulatory compliance deadlines. Industry-specific forecast inputs incorporated ECE R14 development cycle extensions and semiconductor foundry capacity utilization trends.
Revisions become necessary when Taiwan-based foundry disruptions, EU cybersecurity certification timeline accelerations, or India's PLI scheme subsidy modifications materialize outside baseline assumptions. Practitioners should monitor NHTSA rollover resistance rating updates and fleet procurement unbundling negotiation outcomes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Laser Headlight Market
Automotive Safety and Security Systems
Front Collision Warning Market
Automotive Safety and Security Systems
Automotive Biometric Identification Market
Automotive Safety and Security Systems
Automotive Anti-Roll Bar Market
Automotive Safety and Security Systems
Motorcycle Anti-Lock Braking System Market
Automotive Safety and Security Systems
Brake System Market
Automotive Safety and Security Systems
Automotive Active Health Monitoring System Market
Automotive Safety and Security Systems
Acoustic Vehicle Alerting System Market
Automotive Safety and Security Systems
Automatic Brake Pad Inspection System Market
Automotive Safety and Security Systems
Global Automotive Camera Cleaning System Market
Automotive Safety and Security Systems
Airbag Control Unit Sensor Market
Automotive Safety and Security Systems
Ignition Interlock Devices Market
Automotive Safety and Security Systems
Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
Adaptive Headlights Market
Automotive Safety and Security Systems
Vehicle Anti-Theft System Market
Automotive Safety and Security Systems
Electronic Stability Control System Market