
 Middle East and Africa Automotive Adaptive Lighting System Market | 2026-2036
Middle East and Africa Automotive Adaptive Lighting System Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Automotive Adaptive Lighting System Market Outlook
Matrix beam certification is redrawing competitive boundaries across the region. Valeo Group leverages its European regulatory heritage to anchor premium OEM contracts in the GCC. HELLA KGaA Hueck & Co. sustains technology leadership through in-house LED module production. Osram Licht AG dominates aftermarket retrofit channels with localized distribution partnerships.
Automotive adaptive lighting systems integrate sensor arrays, electronic control units, and variable-intensity light sources to dynamically adjust beam patterns based on vehicle speed, steering angle, and ambient conditions, typically operating within color temperature ranges of 4,000K to 6,000K for optimal road surface illumination. These systems primarily enhance nighttime driving safety while reducing glare for oncoming traffic. LED technology occupies the dominant share due to thermal efficiency advantages in high-temperature climates across the Arabian Peninsula. SUVs command disproportionate adaptive lighting penetration given their higher average transaction prices and manufacturer willingness to bundle advanced safety packages. Fleet owners represent an emerging demand node as rental and limousine operators standardize on visibility-enhancing specifications to differentiate service tiers.
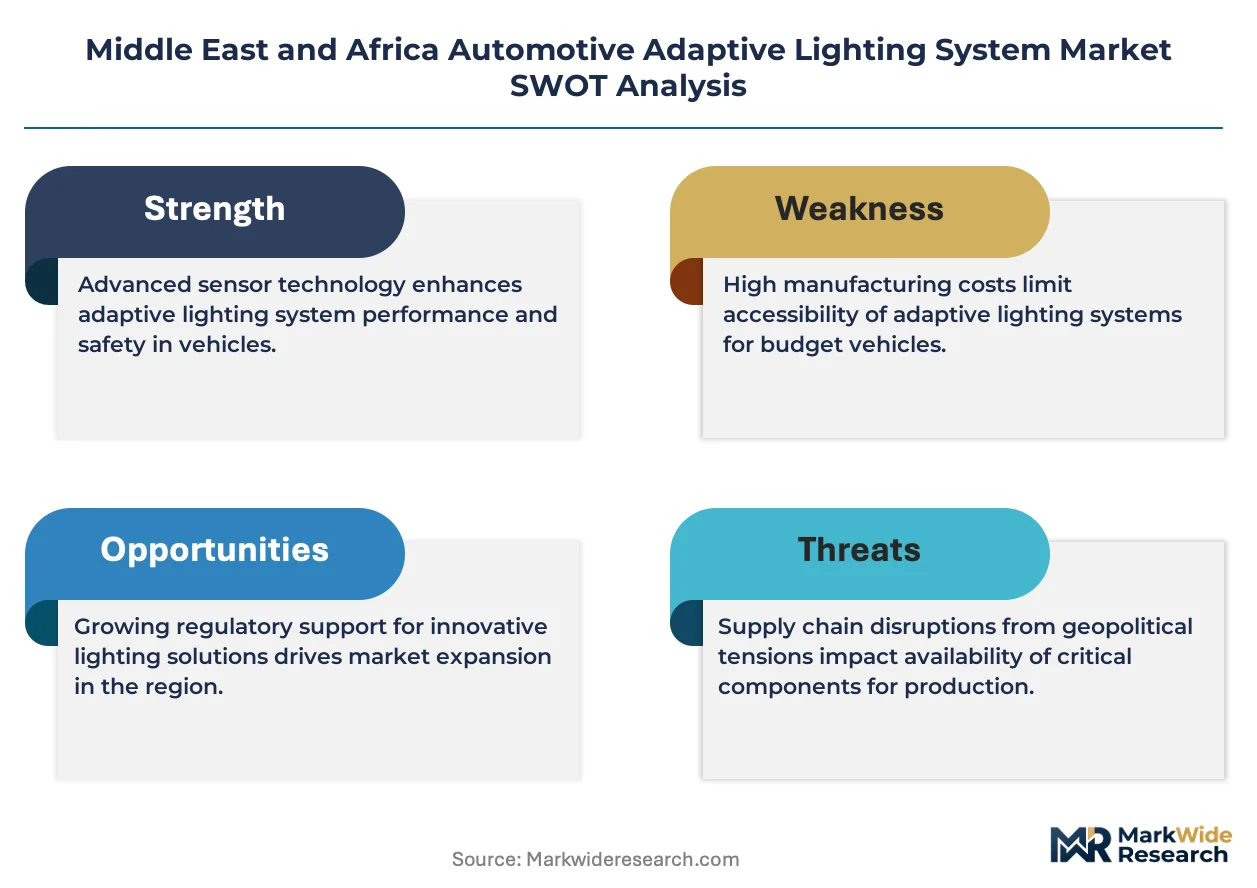
South Africa's National Regulator for Compulsory Specifications mandates headlamp performance testing under local road conditions, while UAE's Emirates Authority for Standardization and Metrology adopts UN ECE harmonized requirements for adaptive front lighting systems. Saudi Standards, Metrology and Quality Organization enforces electromagnetic compatibility protocols that shape ECU supplier qualification timelines. Stakeholders must monitor evolving Gulf state homologation timelines against European type-approval synchronization to optimize product launch sequencing.
Market Dynamics
Matrix LED module production is concentrating among European-tier suppliers with GCC homologation experience, compressing qualification timelines for Saudi and UAE fleet tenders while elevating technical barriers for second-tier entrants.
Growth Catalysts
- UN ECE harmonization via UAE's ESMA:Emirates Authority for Standardization and Metrology adoption of adaptive front lighting protocols reduces dual-certification burden for OEMs serving Gulf markets.
- Luxury SUV transaction prices:Premium vehicle segments in Saudi Arabia and the UAE absorb adaptive lighting hardware costs without margin compression.
- South Africa's NRCS alignment mandates:National Regulator for Compulsory Specifications enforcement of headlamp performance testing under local road conditions creates certified aftermarket demand.
Market Restraints
- ECU electromagnetic compatibility testing:Saudi Standards, Metrology and Quality Organization protocols extend supplier qualification timelines by 8-14 months.
- High-temperature LED thermal management:Arabian Peninsula ambient conditions above 50°C accelerate phosphor degradation and drive module replacement frequency.
- Matrix beam sensor array costs:Camera and radar integration for dynamic beam shaping adds substantial hardware expense relative to static adaptive systems.
Strategic Opportunities
- Egypt and Morocco fleet electrification:North African commercial vehicle operators are specifying adaptive lighting for premium coach and logistics segments.
- Aftermarket retrofit channel expansion:Osram's localized distribution partnerships demonstrate scalable pathways for tier-2 cities across the GCC.
- Sensor-to-light convergence:Integration of LiDAR point clouds with matrix beam controllers enables predictive road illumination.
Industry Challenges
- Embedded software validation cycles:Functional safety certification for ECUs under ISO 26262 stretches development timelines.
- Legacy halogen infrastructure:Existing service bay equipment across South Africa's independent aftermarket requires capital investment for LED calibration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Automotive Adaptive Lighting System Market |
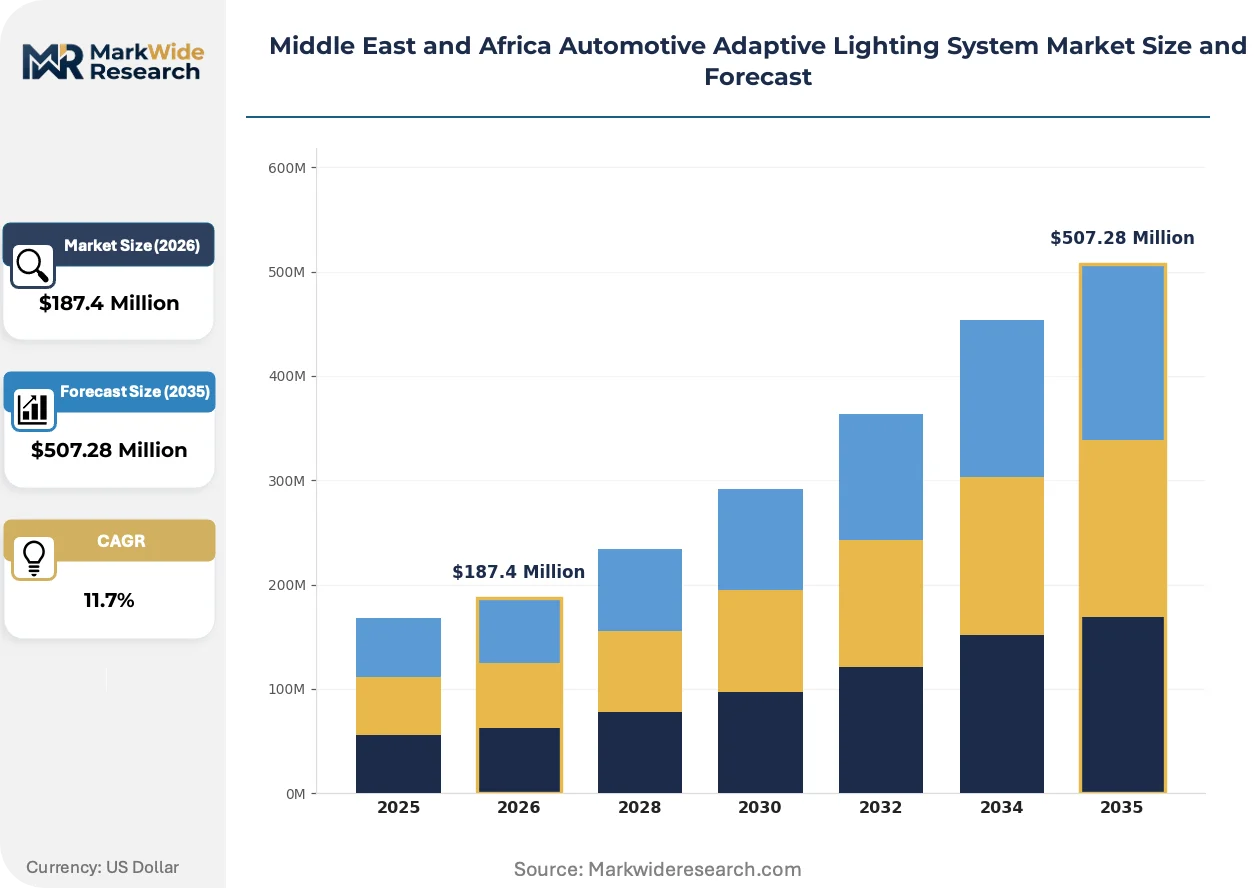
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LED, HID, Halogen, Laser Vehicle Type: SUVs, Sedans, Hatchbacks, Trucks End User: Consumers, Vehicle Manufacturers, Fleet Owners, Dealerships Light Distribution: Adaptive, Dynamic, Static, AFS |
| Companies Covered | HELLA KGaA Hueck & Co., Valeo Group, Hyundai Mobis, Magneti Marelli SpA, Koito Manufacturing Co. Ltd, Stanley Electric Co. Ltd, Osram Licht AG, ZKW Group, Koninklijke Philips N.V., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Automotive Adaptive Lighting System Market Strategic Shifts
Digital light processing is compressing optical component footprints while regulatory synchronization across Gulf states is accelerating homologation throughput. Demand patterns are fragmenting as fleet operators displace individual owners in technology adoption sequencing.
Micro-LED pixel arrays are miniaturizing. These solid-state emitters enable 25,000+ individually addressable light points for glare-free high beam operation. Saudi premium SUV manufacturers are integrating them across 2024-2026 model year refreshes. The technology is miniaturizing projector module volumes by 40% while expanding beam pattern resolution.
UAE's ESMA has adopted UN ECE R48 and R123 amendments for adaptive front lighting systems without national deviation clauses. This eliminates parallel testing requirements for European-certified suppliers. GCC-based OEM sourcing teams are consolidating supplier lists to those with pre-existing European type-approval documentation.
Fleet procurement managers in Saudi Arabia and the UAE are unbundling lighting specifications from full trim packages. Rental and limousine operators now issue standalone tenders for visibility-enhancing configurations. This behavior is most visible in Dubai's premium chauffeur segment where standardized matrix LED distinguishes service tiers.
Middle East and Africa Automotive Adaptive Lighting System Market Segmentation
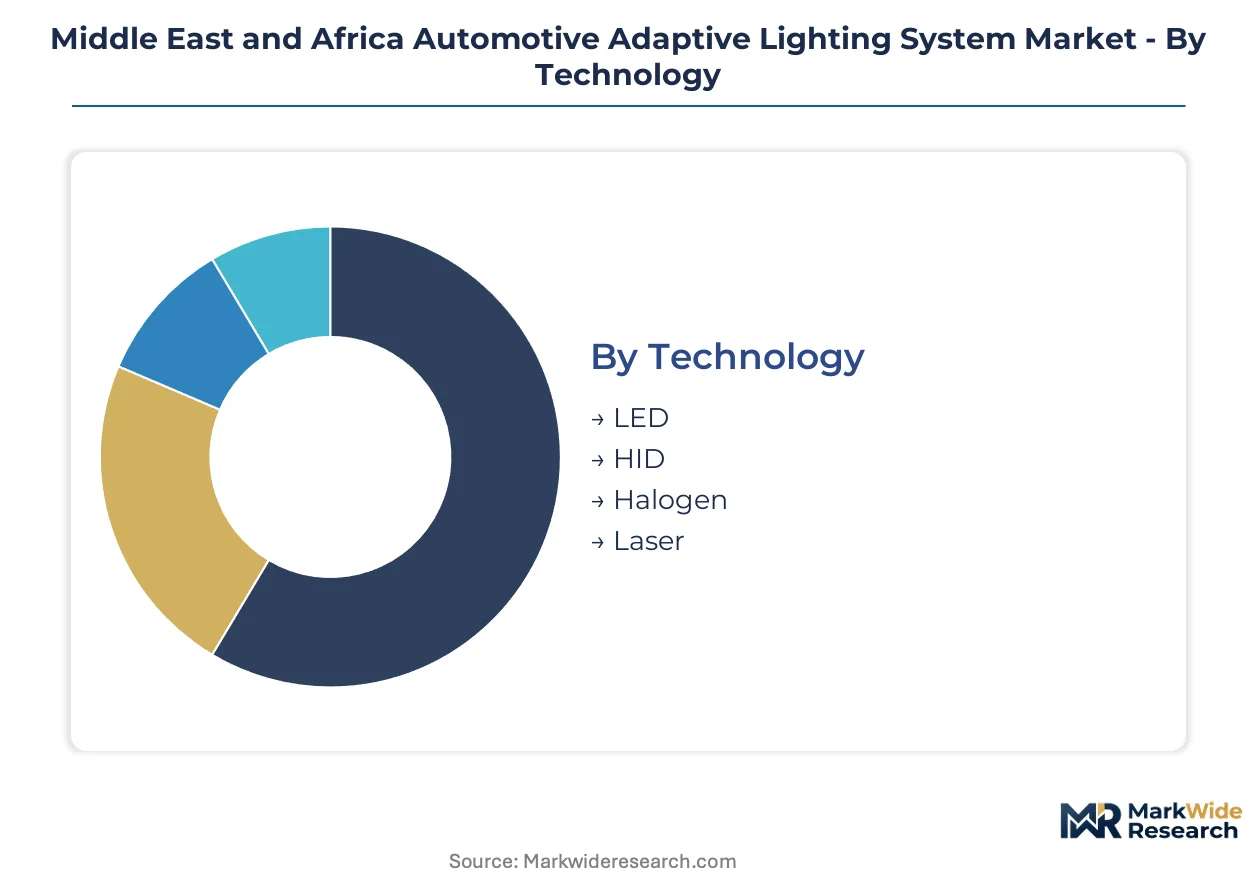
Adaptive lighting procurement channels in the Middle East and Africa diverge sharply by segment. OEMs dominate technology and vehicle type flows, while fleet owners and dealerships reshape end-user distribution in Saudi Arabia and the UAE.
Technology:
Channel concentration varies by thermal performance and retrofit compatibility, with OEM direct supply dominating premium tiers and aftermarket distributors capturing replacement demand.
- LED:Solid-state emitters operating at 4,000K-6,000K color temperature with active thermal management for ambient conditions exceeding 50°C. Saudi and UAE premium SUV manufacturers specify LED matrix modules for new vehicle programs, while fleet operators in Dubai's chauffeur segment standardize on LED retrofit packages to differentiate service tiers. By volume, LED leads. By growth pace, laser is climbing the fastest.
- HID:High-intensity discharge arc lamps with xenon gas fill and ballast-driven ignition, requiring 3-5 second warm-up cycles. Demand concentrates in South Africa's certified aftermarket channel where NRCS alignment mandates create replacement pull for older vehicle parc.
- Halogen:Tungsten-halogen regenerative cycle bulbs with standardized H-series bases, serving price-sensitive replacement demand across Egypt and Morocco's independent service networks.
- Laser:Coherent light amplification through diode-pumped solid-state arrays, extending high-beam range beyond 600 meters. GCC luxury OEMs integrate laser supplementary units in flagship SUV headlamp clusters.
Cost tier separation is pronounced: laser and LED occupy premium OEM channels, HID and halogen flow through aftermarket distributors serving legacy vehicle populations.
Vehicle Type:
Application severity and average transaction price determine adaptive lighting bundling rates across passenger and commercial categories.
- SUVs:High-mount lamp positioning and elevated hood lines necessitate dynamic leveling systems with pitch compensation. Saudi Arabia and UAE premium SUV fleets absorb matrix LED hardware costs without margin compression, driving disproportionate technology penetration. SUVs anchor regional adaptive lighting volume. Hatchbacks are gaining share fastest in Morocco's compact fleet electrification programs.
- Sedans:Lower beltline profiles with integrated bumper-mount fog lamp positions, typically specified with static adaptive systems in mid-luxury trims across South Africa's assembly plants.
- Hatchbacks:Compact form factors with limited engine bay thermal dissipation space, constraining LED module sizing in Egypt's domestically assembled vehicle programs.
- Trucks:Heavy-duty applications with 24V electrical architectures and vibration-resistant housing requirements, specified for long-haul logistics fleets crossing Arabian Peninsula desert corridors.
Margin structure inverts by application: SUVs and trucks command hardware premiums, while sedans and hatchbacks drive volume scale for module suppliers.
End User:
Customer type shapes specification authority and procurement timing, with fleet managers increasingly displacing individual consumers in technology adoption sequencing.
- Consumers:Individual purchasers selecting adaptive lighting through trim package bundling at point of sale. Saudi and UAE retail buyers prioritize matrix LED visibility features in premium SUV configurations.
- Vehicle Manufacturers:OEM engineering teams sourcing adaptive lighting systems for platform integration. GCC-based sourcing teams consolidate supplier lists to European-tier vendors with pre-existing UN ECE type-approval documentation.
- Fleet Owners:Rental and limousine operators issuing standalone tenders for visibility-enhancing configurations. Dubai's premium chauffeur segment has standardized matrix LED as a service tier differentiator.
- Dealerships:Authorized retail networks offering certified retrofit installations. Osram's localized distribution partnerships demonstrate scalable pathways for tier-2 cities across the GCC.
Procurement concentration is shifting: fleet owners now specify adaptive lighting independently of OEM trim packages, fragmenting traditional channel structures.
Light Distribution:
Functional complexity tiers separate static beam shaping from predictive illumination systems, with regulatory harmonization accelerating advanced category adoption.
- Adaptive:Sensor-driven beam pattern adjustment responding to steering angle, vehicle speed, and ambient light conditions. UAE ESMA adoption of UN ECE R123 amendments eliminates parallel testing requirements for European-certified suppliers deploying adaptive systems in Gulf markets.
- Dynamic:Real-time matrix beam modulation with individual LED pixel control for glare-free high beam operation. Saudi premium SUV manufacturers integrate micro-LED pixel arrays across model year refreshes.
- Static:Fixed beam pattern with manual leveling adjustment, serving cost-constrained vehicle programs in Egypt and Morocco's entry segments.
- AFS:Adaptive Front-lighting Systems with cornering light supplementation and country-specific beam pattern switching. South Africa's NRCS mandates headlamp performance testing under local road conditions for AFS certification.
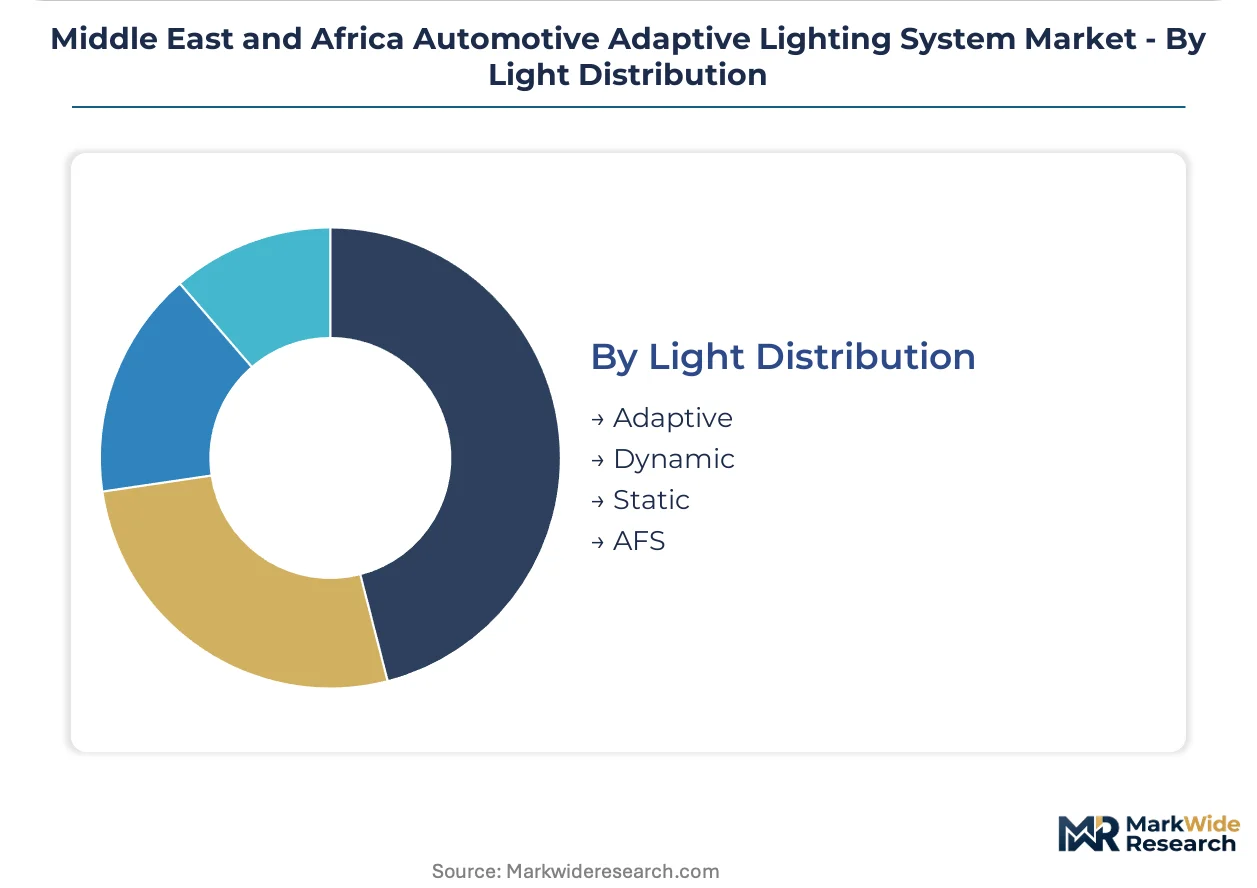
Technology maturity curves diverge: static systems dominate current installed base, while dynamic and AFS categories are expanding most quickly in GCC premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and French automotive lighting suppliers dominate export flows into Gulf Cooperation Council markets, with Dubai and Jeddah serving as primary distribution nodes for matrix LED modules across the Arabian Peninsula.
Saudi Arabia
Riyadh-based premium SUV fleets absorb matrix LED hardware costs without margin compression, driving disproportionate technology penetration in the Kingdom's luxury vehicle segment. SFDA enforces electromagnetic compatibility protocols that shape ECU supplier qualification timelines for adaptive front lighting systems. Jeddah's Red Sea port logistics corridor channels European-certified lighting modules into Saudi assembly plants and aftermarket distribution networks.
United Arab Emirates
Dubai's premium chauffeur segment has standardized matrix LED as a service tier differentiator, with fleet procurement managers unbundling lighting specifications from full trim packages. MOHAP-aligned ESMA adopts UN ECE R48 and R123 amendments without national deviation clauses, eliminating parallel testing requirements for European-certified suppliers. Abu Dhabi's industrial free zones host regional headquarters for tier-1 lighting suppliers serving GCC markets.
South Africa
The National Regulator for Compulsory Specifications mandates headlamp performance testing under local road conditions, creating certified aftermarket demand for HID replacement in older vehicle parc. NRCS alignment standards enforce stricter headlamp beam pattern verification than European baseline requirements. Gauteng province's automotive assembly corridor concentrates adaptive lighting integration for mid-luxury sedan programs serving domestic and export markets.
Egypt
North African commercial vehicle operators specify adaptive lighting for premium coach and logistics segments as fleet electrification programs expand. The country's national standards body maintains type-approval pathways for LED retrofit packages in domestically assembled vehicle programs. Cairo-Alexandria industrial corridor channels aftermarket lighting distribution into Nile Delta manufacturing zones and Red Sea port export routes.
Morocco
Compact hatchback fleet electrification programs are gaining adaptive lighting share fastest among North African markets, driven by European OEM platform localization. The country's automotive regulator harmonizes with UN ECE frameworks to facilitate export-oriented production. Tangier-Med port logistics cluster serves as transshipment hub for lighting modules bound for West African markets.
Middle East and Africa Automotive Adaptive Lighting System Market Competitive Environment
Listed leaders compete with private specialists across technology tier and geographic certification breadth. European-tier suppliers with GCC homologation experience compress qualification timelines for Saudi and UAE fleet tenders, elevating technical barriers for second-tier entrants. Three archetypes dominate: matrix beam technology originators, thermal management specialists for high-temperature climates, and aftermarket retrofit channel operators. Consolidation pressure manifests through supplier list narrowing by GCC-based OEM sourcing teams and capacity expansion into Dubai free zone logistics hubs.
Within the European heritage tier, HELLA KGaA Hueck & Co. and Valeo Group exemplify archetypes of regulatory-anchored market position, with the former representing in-house LED module production capabilities and the latter leveraging type-approval documentation for premium OEM contract security. Osram Licht AG occupies a distinct aftermarket-focused position, demonstrating scalable distribution pathways through localized partnerships. Hyundai Mobis represents the integrated tier, sitting within conglomerate-affiliated supply structures that bundle lighting with broader vehicle electronics portfolios.
| Leading Market Players |
|---|
| HELLA KGaA Hueck & Co. |
| Valeo Group |
| Hyundai Mobis |
| Magneti Marelli SpA |
| Koito Manufacturing Co. Ltd |
| Stanley Electric Co. Ltd |
| Osram Licht AG |
| ZKW Group |
| Koninklijke Philips N.V. |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with European tier-1 suppliers lock in both matrix LED module access and price visibility for GCC-based OEM sourcing teams, compressing qualification timelines while freezing hardware costs across Saudi and UAE fleet tender cycles.
Pricing Analysis
Technology-generation pricing gaps separate micro-LED pixel arrays from conventional LED matrix modules and legacy HID retrofit packages. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal management certification grade and UN ECE type-approval documentation completeness. Cost compression in economy-tier halogen replacement channels is intensifying because Egyptian and Moroccan independent service networks prioritize price over beam pattern precision. Fleet procurement managers in Dubai's chauffeur segment exhibit lowest price sensitivity, while South African aftermarket distributors serving legacy vehicle parc face acute margin pressure.
Supply Chain Analysis
Jeddah's Red Sea port congestion and container availability constraints on the Asia-Europe trade lane elevate inbound logistics costs for LED driver ICs and phosphor substrates sourced from East Asian foundries. Module assembly concentrates in Germany, Czech Republic, and Slovakia, with European-tier suppliers drawing from Taiwan and South Korea for semiconductor content. Single-source vulnerability in automotive-grade MCU supply creates qualification bottleneck risk for ECU suppliers seeking Saudi Standards, Metrology and Quality Organization electromagnetic compatibility certification. Distribution runs through Dubai's Jebel Ali free zone logistics hubs for GCC aftermarket penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet procurement consolidation across Saudi Arabia and UAE rental and limousine operators has shifted buyer power toward standardized matrix LED tender specifications, fragmenting traditional OEM trim-package bundling.
For Market Incumbents: Fortify regulatory-anchored market position by accelerating UN ECE R123 amendment pre-certification for micro-LED pixel arrays ahead of Gulf state homologation synchronization. Deepen backward integration into phosphor substrate sourcing to offset thermal degradation replacement frequency in Arabian Peninsula ambient conditions exceeding 50°C. Prioritize channel control through exclusive distribution partnerships with Dubai-based tier-2 city aftermarket networks. For New Entrants and Emerging Players: ESMA-aligned certification fast-track for adaptive front lighting systems eliminates parallel testing burden and compresses market entry timelines against European heritage competitors. White-space targets concentrate in Egypt and Morocco's premium coach electrification programs and South Africa's certified HID aftermarket replacement channel. Penetrable segment: North African commercial vehicle fleet operators specifying adaptive lighting independently of OEM platforms. Go-to-market angle: localized thermal management validation under 50°C+ ambient testing protocols. For Investors and Strategic Acquirers: European-tier specialists with captive LED module production and pre-existing GCC homologation documentation represent the most defensible acquisition archetype for long-term viability across the 5-10 year projection horizon. Signal to monitor: Gulf state regulatory synchronization velocity against European type-approval timelines as inflection indicator for supplier consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| UN ECE R123 Pre-Certification Investment | ESMA adoption without deviation clauses eliminates parallel testing for European-certified suppliers entering UAE markets. |
| Phosphor Substrate Backward Integration | Captive supply of thermal-resistant materials reduces replacement frequency under Arabian Peninsula ambient conditions. |
| Dubai Free Zone Logistics Hub Expansion | Jebel Ali cluster enables scalable aftermarket distribution into Saudi tier-2 cities and Red Sea port networks. |
| Micro-LED Pixel Array Platform Standardization | 25,000+ individually addressable light points enable glare-free high beam operation for Saudi premium SUV refreshes. |
| Fleet Procurement Direct Partnership | Dubai chauffeur segment tenders now unbundle lighting specifications from full OEM trim packages. |
Study Parameters
Desk research of vehicle production databases, UN ECE type-approval registries, and Gulf state regulatory gazettes preceded structured interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors in Jeddah and Dubai, and fleet procurement managers at Saudi rental operators. Primary fieldwork combined with secondary validation from customs records and IHS Markit registration data. Bottom-up module shipment estimates triangulated against top-down vehicle production forecasts across the analysis window.
Variance decomposition separates technology penetration rates, vehicle class mix shifts, and regional regulatory harmonization velocity as primary forecast drivers. Segmentation dimensions modeled include light source technology, vehicle type, end-user procurement channel, and light distribution complexity tier across the projection horizon. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns, with inputs from thermal management degradation curves and fleet replacement cycles.
Underlying assumptions cover Gulf Cooperation Council luxury vehicle penetration stability, European regulatory synchronization timelines, and phosphor substrate supply continuity, with deviation risk concentrated in Saudi electromagnetic compatibility protocol revisions and Egyptian currency volatility affecting aftermarket import costs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Smart Security Device Market
Automotive Safety and Security Systems
Automotive Knock Sensor Market
Automotive Safety and Security Systems
Automotive Biometric Access System Market
Automotive Safety and Security Systems
Airbag Control Unit Sensor Market
Automotive Safety and Security Systems
Automotive Inertial Systems Market
Automotive Safety and Security Systems
Wearable Motorcycle Airbags Market
Automotive Safety and Security Systems
Latin America Airbag Systems Market
Automotive Safety and Security Systems
Automotive Occupant Sensing System Market
Automotive Safety and Security Systems
Motorcycle Start Stop Systems Market
Automotive Safety and Security Systems
North America Airbag Systems Market
Automotive Safety and Security Systems
Vehicle Barrier System Market
Automotive Safety and Security Systems
Global Automotive Parking Sensors Market
Automotive Safety and Security Systems
Global Highway Driving Assist Market
Automotive Safety and Security Systems
Crane Collision Avoidance Devices Market
Automotive Safety and Security Systems
Global Automotive Knee Airbags Market
Automotive Safety and Security Systems
Automotive Door Guards Market