
 Automotive Inflatable Seat Belt Market | 2026-2036
Automotive Inflatable Seat Belt Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Inflatable Seat Belt Market Outlook
Germany is tilting toward expanded inflatable seat belt production capacity as domestic automakers prioritize advanced occupant protection. Autoliv Inc leverages its integrated airbag-to-seat-belt manufacturing platform to sustain cost advantages across European supply chains. ZF Friedrichshafen AG anchors its position through R&D intensity in pyrotechnic inflator miniaturization for belt-integrated systems. Hyundai Mobis Co., Ltd competes by extending its safety module portfolio into adaptable inflation architectures for diverse vehicle platforms.
Automotive inflatable seat belts are woven restraint systems incorporating cylindrical airbag chambers that deploy from the belt webbing during collision events, typically using cold-gas inflators to achieve full pressure within 40 milliseconds. These systems distribute crash forces across the occupant's torso and reduce rib compression injuries compared to conventional three-point restraints, serving primarily as supplemental protection in frontal and offset impacts. Seat Belt Airbag configurations command premium positioning due to their complexity and dual-function design, while OEM end-user channels dominate volume as factory-installed equipment with longer qualification cycles than aftermarket retrofits. Nylon material grades occupy the mainstream for tensile strength and foldability, though Kevlar-reinforced variants are gaining traction in motorsport and armored vehicle applications where cut-through resistance matters.
NHTSA's Federal Motor Vehicle Safety Standards govern inflatable seat belt performance thresholds in the United States, while ECE R16 regulations administered by European type-approval authorities dictate webbing strength and inflator reliability benchmarks for vehicles sold across EU member states. Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces compatible occupant-protection criteria that Japanese automakers reference for domestic and export production. Stakeholders must monitor how divergent timing between U.S. and European regulatory updates affects platform engineering budgets and homologation timelines.
Market Dynamics
NHTSA's evolving FMVSS crash-test protocols are compressing OEM qualification timelines while forcing simultaneous compliance across multiple regulatory jurisdictions, reshaping how suppliers allocate R&D budgets and production capacity.
Growth Catalysts
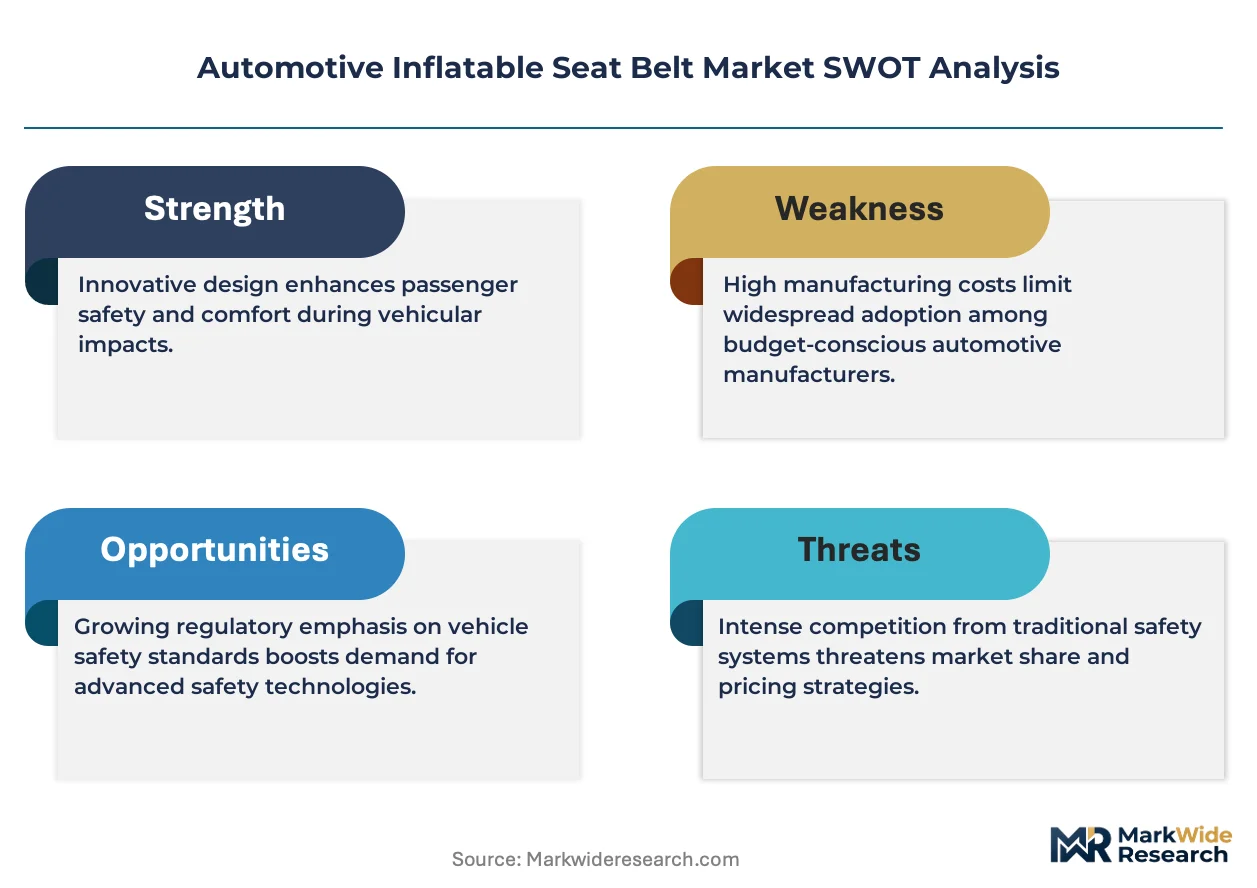
- FMVSS 208 Compliance Pressure:NHTSA's updated occupant-protection thresholds mandate advanced restraint systems in frontal impact scenarios, pushing automakers toward integrated inflatable belt architectures.
- Pyrotechnic Inflator Miniaturization:Advances in cold-gas generator density enable 40-millisecond deployment cycles without increasing webbing bulk, expanding fitment across compact vehicle platforms.
- German Premium OEM Standardization:BMW and Mercedes-Benz factory-install inflatable rear-seat belts across multiple model lines, creating reference specifications that tier-two suppliers must match.
Market Restraints
- Kevlar Fiber Cost Volatility:Motorsport-grade reinforcement materials face price instability tied to aerospace composite demand, compressing margins for cut-through-resistant belt variants.
- European Inflator Supply Concentration:Pyrotechnic component manufacturing clusters in southern Germany and Austria, creating single-source vulnerability for tier-one integrators.
- ECE R16 Homologation Friction:Divergent timing between European type-approval updates and NHTSA rulemaking forces parallel certification tracks, duplicating engineering expenditure.
Strategic Opportunities
- India Fleet Safety Mandates:Central Motor Vehicles Rules amendments for commercial vehicle occupant protection create first-mover advantage for localized inflatable belt assembly.
- Autonomous Vehicle Cabin Architectures:Convergence of inflatable restraints with biometric seat sensors enables adaptive deployment algorithms for non-traditional seating positions.
- Aftermarket Retrofit Channels:Certified installation networks for armored vehicle upfitters represent uncaptured volume outside OEM factory-install qualification cycles.
Industry Challenges
- Cross-Disciplinary Talent Scarcity:Integration of textile engineering, pyrotechnics, and automotive safety systems requires hybrid skill sets concentrated in Stuttgart and Detroit metro areas.
- Legacy Seat Frame Compatibility:Retrofitting inflatable belt retractors into existing B-pillar architectures demands structural reinforcement beyond standard safety-module swap protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Inflatable Seat Belt Market |
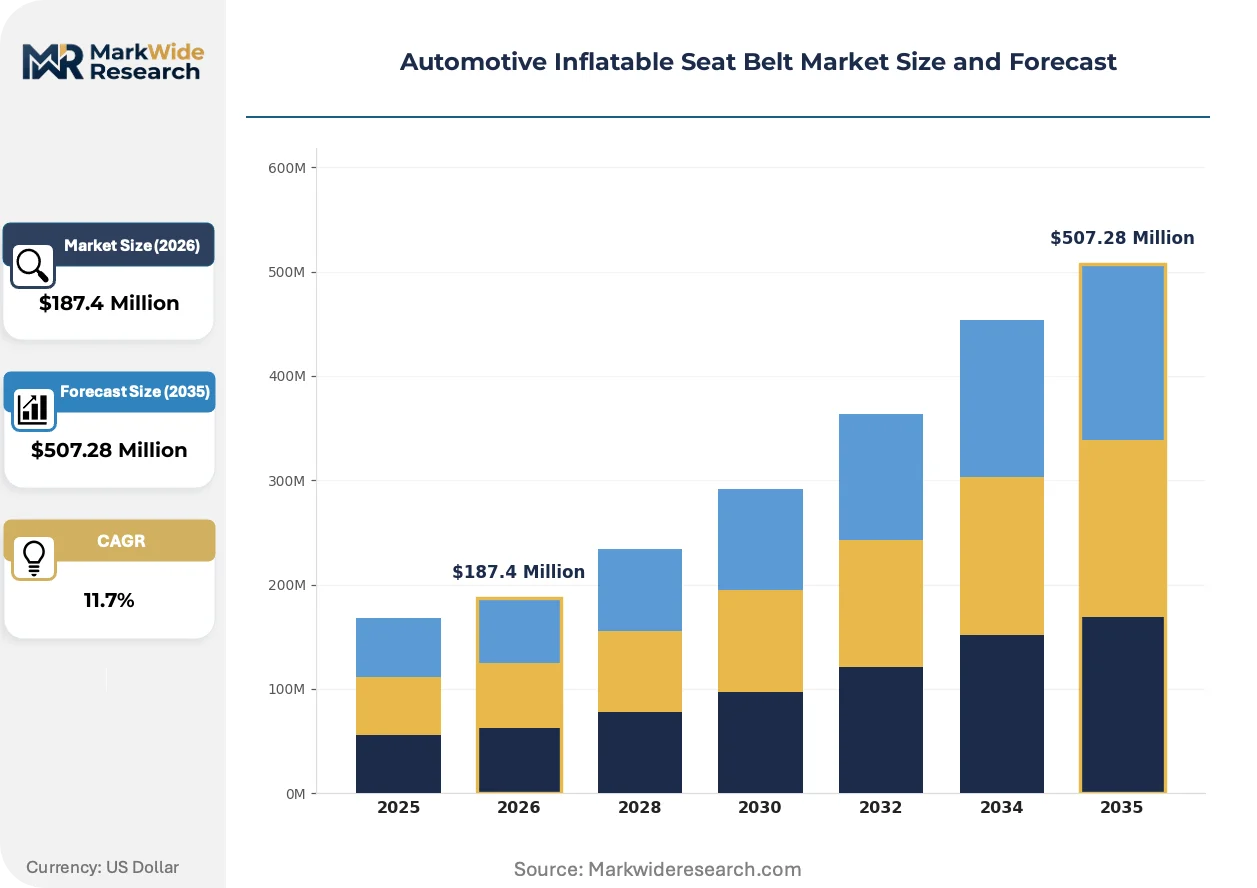
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Inflatable Lumbar, Seat Belt Airbag, Adaptable End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Managers Installation Type: Integrated, Retrofitted, Customized, Standardized Material: Nylon, Polyester, Polyurethane, Kevlar |
| Companies Covered | Continental AG, Hyundai Mobis Co., Ltd, Autoliv Inc, Takata Corporation, Joyson Safety Systems, Ford Motor Company, ZF Friedrichshafen AG, Key Safety Systems, Toyoda Gosei Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Inflatable Seat Belt Market Strategic Shifts
Three forces are actively restructuring competitive positioning: sensor fusion enabling predictive deployment, regulatory divergence forcing dual-track engineering, and procurement centralization among mega-fleets rewriting specification authority.
Multi-axis accelerometer arrays woven directly into seat belt webbing are digitizing crash-detection response. Tier-one suppliers embed MEMS sensors that communicate with vehicle CAN bus architectures, enabling pre-tensioning milliseconds before physical impact. German luxury OEMs are adopting these architectures fastest, compressing the deployment-advantage window for competitors still using discrete sensor modules.
ECE R16's 2024 amendments to webbing elongation standards are forcing material reformulation across European supply chains. The regulation reduces permissible stretch under load, requiring denser nylon weaves that complicate folding geometry for cylindrical airbag chambers. Italian and Spanish seat suppliers are responding with hybrid Kevlar-nylon laminates that maintain packability while meeting tensile thresholds.
Fleet procurement centralization at rental and ride-hail operators is displacing individual OEM specification authority. Enterprise buyers like Avis Budget Group and Uber mandate uniform safety equipment across multi-brand vehicle pools, forcing suppliers to engineer single SKUs compatible with disparate seat architectures. This concentration is most visible in Florida and Arizona fleet registration hubs, where volume commitments override brand-specific integration preferences.
Automotive Inflatable Seat Belt Market Segmentation
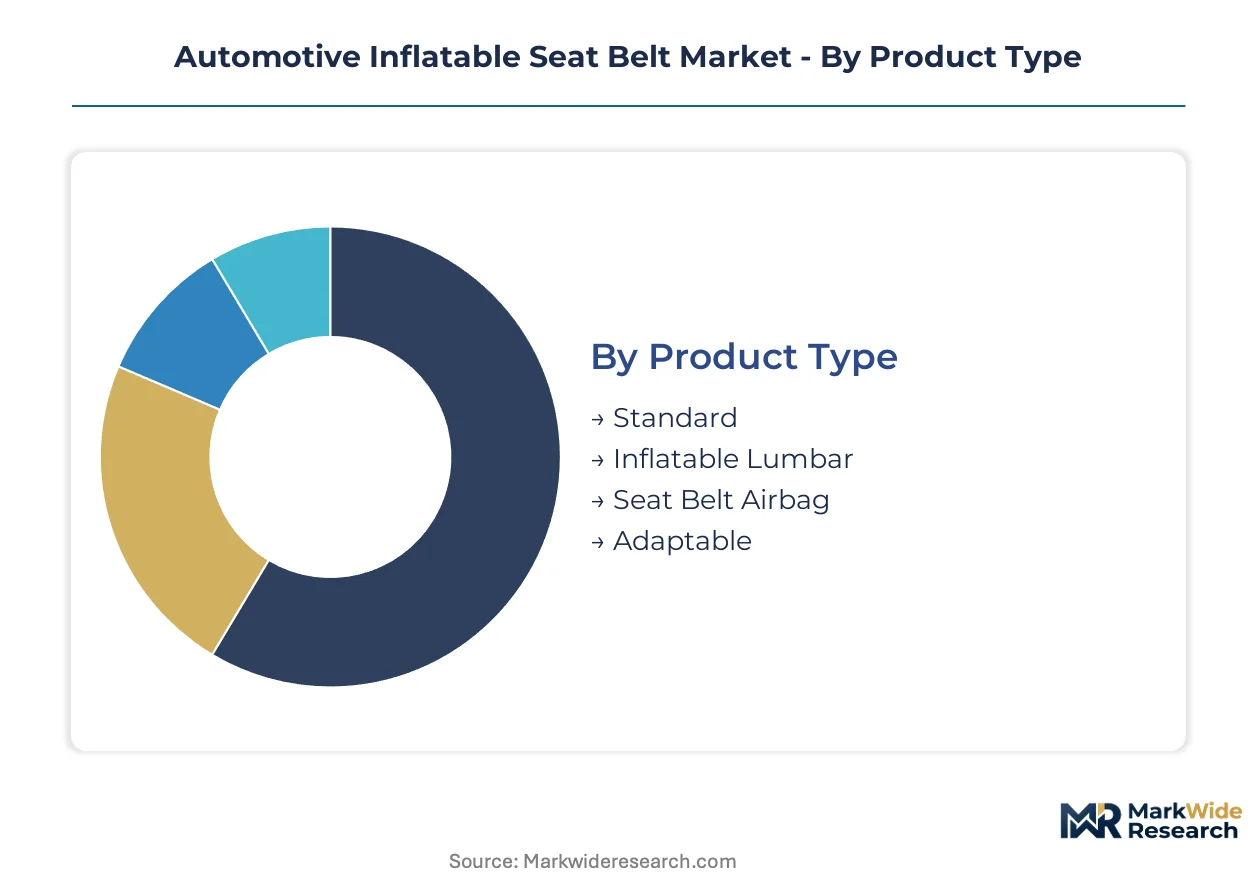
Automotive inflatable seat belts fragment across four structural dimensions that determine manufacturing complexity, certification pathways, and margin architecture. Product type and material selection drive unit economics, while installation type and end-user channel shape go-to-market strategies and warranty exposure.
Product Type:
Use-case spectrum spans from basic occupant protection to adaptive systems responding to crash severity and occupant physiology.
- Seat Belt Airbag:Cylindrical airbag chambers deploy from webbing within 40 milliseconds using cold-gas inflators, distributing crash forces across the torso. BMW and Mercedes-Benz factory installations across rear-seat positions in German premium vehicles establish the performance benchmark tier-two suppliers must replicate.
- Adaptable:Modular architectures accommodate varying seat geometries and occupant sizes through adjustable inflation profiles. Hyundai Mobis extends its safety module portfolio into these configurations for diverse vehicle platforms where standardized fitment proves impractical.
- Standard:Conventional three-point restraint systems without inflatable augmentation serve cost-sensitive vehicle segments where regulatory minimums suffice.
- Inflatable Lumbar:Lower-back focused inflation chambers address specific injury patterns in frontal impacts, currently limited to specialized commercial vehicle applications.
Established volume favors Seat Belt Airbag; emerging adoption favors Adaptable.
End User:
Customer concentration determines qualification cycles, specification authority, and aftermarket service obligations.
- OEMs:Factory-installed equipment carries longer qualification cycles than aftermarket channels but commands premium positioning through integrated vehicle safety architectures. NHTSA FMVSS compliance pressure accelerates integration timelines across US-based manufacturing.
- Fleet Managers:Enterprise procurement centralization at rental and ride-hail operators mandates uniform safety equipment across multi-brand pools, displacing individual OEM specification authority in volume aggregation.
- Aftermarket Providers:Certified installation networks serve armored vehicle upfitters and retrofit applications outside factory-install protocols.
- Vehicle Assemblers:Contract manufacturing arrangements for regional production facilities require modular safety system sourcing compatible with localized seat architectures.
OEM channels anchor current revenue; fleet procurement is climbing the fastest.
Installation Type:
Integration depth dictates structural reinforcement requirements and homologation pathway complexity.
- Integrated:Factory-engineered retractor and inflator modules designed into B-pillar structures from vehicle development inception.
- Retrofitted:Post-manufacture installation into existing seat frames demands supplemental structural reinforcement beyond standard swap protocols.
- Customized:Application-specific configurations for motorsport, armored vehicles, and specialized commercial transport.
- Standardized:Universal-fit modules engineered for cross-platform compatibility in high-volume fleet applications.
Integrated systems dominate safety performance; retrofitted channels show steepest expansion trajectory in commercial vehicle mandates.
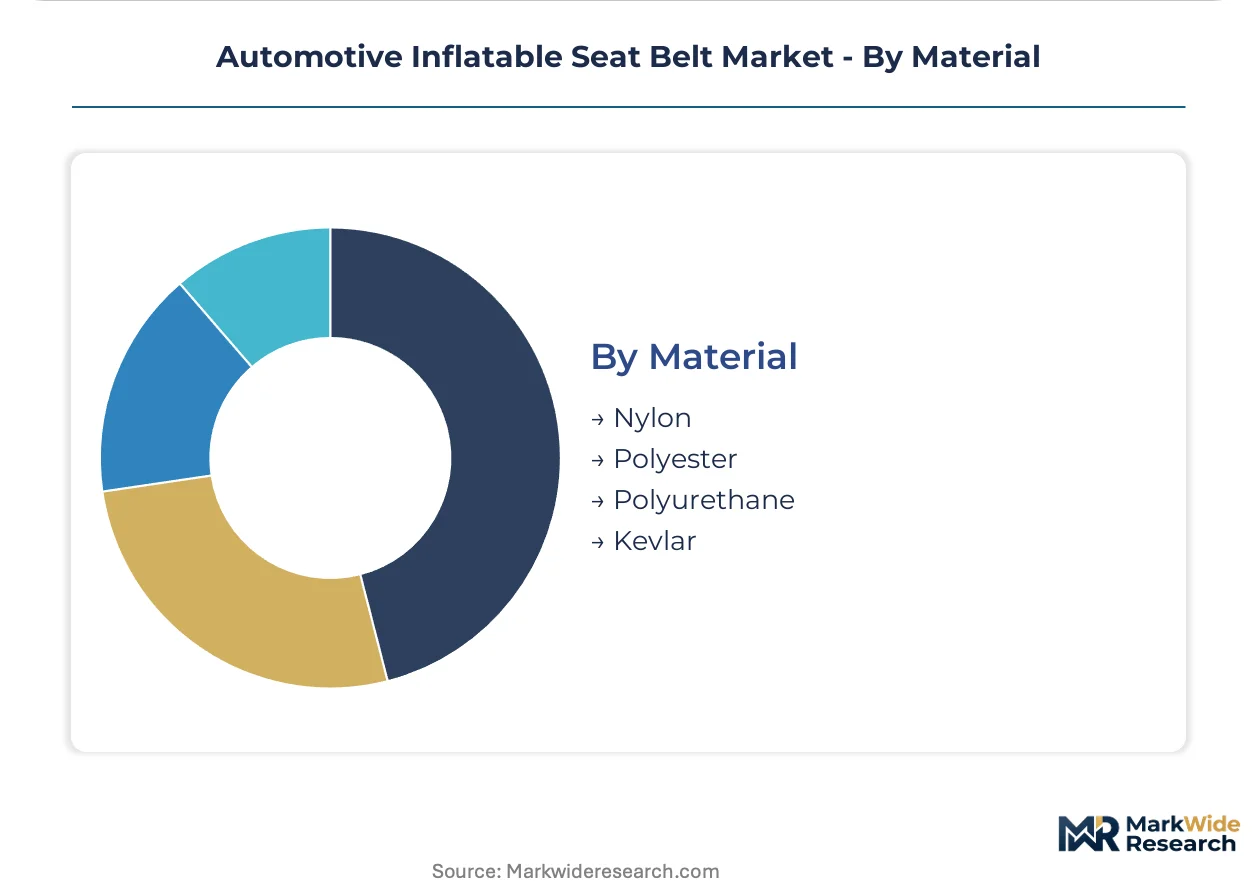
Material:
Textile selection balances tensile strength, foldability for cylindrical chamber packing, and cut-through resistance under load.
- Nylon:Mainstream grades occupy volume production for tensile strength and foldability compatibility with cold-gas inflator deployment geometry.
- Kevlar:Motorsport and armored vehicle applications demand cut-through resistance where belt abrasion against structural components threatens integrity.
- Polyester:Cost-optimized alternatives in price-sensitive vehicle segments where regulatory minimums override performance margins.
- Polyurethane:Coating and sealing applications rather than primary webbing, addressing gas retention in inflatable chamber construction.
Nylon maintains production dominance; Kevlar-reinforced variants gain share fastest in specialized protection segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bremerhaven automotive terminal anchors German export capacity for safety system components bound for North American assembly plants. This deepwater infrastructure underwrites Continental AG and ZF Friedrichshafen AG's just-in-time supply to BMW Spartanburg and Mercedes-Benz Tuscaloosa.
United States
NHTSA's FMVSS 208 compliance deadlines compress OEM qualification timelines for inflatable belt architectures. The agency's updated occupant-protection thresholds mandate advanced restraint systems in frontal impact scenarios. Detroit's safety engineering cluster concentrates tier-one integration capacity for Ford Motor Company and General Motors.
Germany
BMW and Mercedes-Benz factory-install inflatable rear-seat belts across multiple model lines, establishing reference specifications tier-two suppliers must replicate. ECE R16 amendments administered by KBA reduce permissible webbing elongation under load. Stuttgart's pyrotechnic engineering corridor anchors Autoliv Inc and ZF Friedrichshafen AG inflator miniaturization programs.
Japan
Toyoda Gosei Co., Ltd extends safety module production for domestic OEM export programs. METI's occupant-protection criteria enforce compatible standards Japanese automakers reference for North American and European production. Nagoya's automotive components belt concentrates textile-to-inflator integration expertise.
China
Domestic OEMs accelerate inflatable belt adoption as GB standards align with UN ECE technical prescriptions. MIIT's vehicle safety regulations mandate advanced restraint penetration in premium passenger segments. Shanghai's Yangtze River Delta manufacturing corridor hosts Joyson Safety Systems assembly for export and domestic fitment.
South Korea
Hyundai Mobis Co., Ltd leverages captive supply relationships with Hyundai Motor Group for platform-integrated inflatable architectures. MFDS automotive safety guidelines reference UN ECE frameworks for type-approval harmonization. Seoul Capital Area R&D campuses concentrate adaptive inflation algorithm development.
Automotive Inflatable Seat Belt Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying pyrotechnic inflators and woven webbing. The market structures around three to five dominant full-system suppliers with captive inflator capacity, while textile weavers and cold-gas generator fabricators occupy fragmented upstream tiers. Two strategic archetypes predominate: integrated safety module manufacturers with backward control over inflator production, and specialized belt assembly houses dependent on external pyrotechnic sourcing. Competitive moves concentrate on R&D intensity in deployment speed miniaturization and cross-platform modular architectures reducing SKU complexity.
Within the integrated tier, Autoliv Inc, ZF Friedrichshafen AG, and Hyundai Mobis Co., Ltd exemplify divergent geographic anchoring strategies. Autoliv represents the Stockholm-based safety systems conglomerate with consolidated airbag-to-seat-belt manufacturing platforms. ZF Friedrichshafen anchors German engineering intensity in automotive supply, occupying a position defined by pyrotechnic component density. Hyundai Mobis sits within Korean chaebol-integrated supply structures, exemplifying captive OEM relationship models.
| Leading Market Players |
|---|
| Continental AG |
| Hyundai Mobis Co., Ltd |
| Autoliv Inc |
| Takata Corporation |
| Joyson Safety Systems |
| Ford Motor Company |
| ZF Friedrichshafen AG |
| Key Safety Systems |
| Toyoda Gosei Co., Ltd |
| Others |
Value Chain & Pricing Dynamics
The Bremerhaven automotive terminal's freight cost dynamics amplify supply concentration effects, as German pyrotechnic component manufacturing clusters in southern Germany and Austria create pricing power for inflator suppliers while forcing downstream tier-one integrators to absorb logistics premiums or pass through to OEM buyers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment scale. NHTSA FMVSS 208 compliance pressure intensifies cost compression in the standard tier as OEMs demand dual-certification belts without proportional price acceptance. Fleet procurement centralization at rental and ride-hail operators shows highest price sensitivity, while German luxury OEMs exhibit lowest sensitivity due to integrated safety architecture positioning.
Supply Chain Analysis
Upward feedstock flows draw from nylon polymer production concentrated in Germany, China, and the United States, with cold-gas generator fabrication resting on sodium azide and nitroguanidine chemical supply chains. European inflator supply concentration in southern Germany and Austria creates single-source vulnerability for tier-one integrators. Distribution runs through just-in-time automotive safety module networks anchored at Bremerhaven for transatlantic OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive inflatable seat belt market fragmentation creates entry niches as fleet procurement centralization displaces traditional OEM specification authority and demands cross-platform compatible safety modules.
For Market Incumbents: Insulate margin position through captive pyrotechnic inflator production and accelerated R&D in 40-millisecond deployment miniaturization. Kevlar fiber cost volatility from aerospace composite demand threatens cut-through-resistant belt variant profitability; backward integration into nylon polymer sourcing or long-term offtake agreements with German chemical suppliers anchors input cost stability. For New Entrants and Emerging Players: Pursue aftermarket retrofit channels for armored vehicle upfitters and commercial vehicle fleet mandates in India, where Central Motor Vehicles Rules amendments create first-mover advantage outside OEM factory-install qualification cycles. Certified installation network partnerships with regional safety equipment distributors provide the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated safety module manufacturers with backward control over inflator production and established FMVSS 208 certification pathways. Long-term viability hinges on adaptive inflation algorithm capabilities for autonomous vehicle cabin architectures. Watch for sensor fusion patent filings as inflection indicator for predictive deployment technology maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Pyrotechnic Inflator Miniaturization R&D | Enables 40-millisecond deployment cycles across compact vehicle platforms without webbing bulk increase. |
| Fleet Procurement Centralization Response | Single SKU engineering for Avis Budget Group and Uber multi-brand vehicle pools displaces OEM specification authority. |
| India Localized Assembly Investment | Central Motor Vehicles Rules amendments for commercial vehicle occupant protection create regulatory-aligned capacity. |
| Sensor Fusion Patent Portfolio Buildout | MEMS sensor integration with vehicle CAN bus architectures compresses deployment-advantage window for competitors. |
| Kevlar-Nylon Hybrid Material Development | ECE R16 webbing elongation amendments force denser weaves that maintain packability for cylindrical airbag chambers. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket safety equipment distributors, and dealership operations managers. Secondary validation drew from NHTSA FMVSS filings, ECE R16 type-approval databases, vehicle production registries, and customs trade records. Bottom-up segment sizing triangulated against top-down market aggregation across product type, material grade, installation architecture, and end-user channel dimensions.
Calibration against historical deployment timelines and regulatory compliance cycles anchored the analytical framework across the projection horizon. Segmentation modeling captured seat belt airbag versus adaptable system architectures, nylon versus Kevlar-reinforced material grades, integrated versus retrofitted installation types, and OEM versus fleet versus aftermarket end-user channels. CAGRs derived from slope analysis of technology adoption curves and regulatory mandate implementation schedules, with pyrotechnic inflator miniaturization progress and fleet procurement centralization velocity as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, polymer feedstock pricing, and cross-border logistics costs would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timing and technology cost curves. Cross-checking against IHS Markit vehicle registration data and supplier revenue disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Collision Mitigation Technology Market
Automotive Safety and Security Systems
Vehicle Speed Monitoring System Market
Automotive Safety and Security Systems
Video Event Data Recorder Market
Automotive Safety and Security Systems
Asia Pacific Lane Departure Warning Systems Market
Automotive Safety and Security Systems
Global Car Radar Detectors Market
Automotive Safety and Security Systems
Smart Motorcycle Helmet Market
Automotive Safety and Security Systems
Automotive Brake Actuation Systems Market
Automotive Safety and Security Systems
Global Automotive Fog Lights Market
Automotive Safety and Security Systems
Brake Override System Market
Automotive Safety and Security Systems
Vehicle Barrier System Market
Automotive Safety and Security Systems
Biometric Vehicle Access System Market
Automotive Safety and Security Systems
Crane Collision Avoidance Devices Market
Automotive Safety and Security Systems
Speed Bumps & Humps Market
Automotive Safety and Security Systems
Automotive Radar Market
Automotive Safety and Security Systems
ICE Start and Stop System Market
Automotive Safety and Security Systems
Automatic Emergency Braking Market