
 Automotive Biometric Identification Market | 2026-2036
Automotive Biometric Identification Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Biometric Identification Market Analysis
Aftermarket service revenue from biometric system recalibration and sensor replacement is tilting toward OEM-captive programs. Continental AG anchors its position through backward integration into fingerprint sensor module production. Synaptics Incorporated competes by specializing in capacitive touch controllers optimized for automotive temperature ranges. Fingerprint Cards AB extends its footprint via partnerships with Tier-1 suppliers seeking compact biometric form factors.
Automotive biometric identification encompasses physiological and behavioral authentication technologies—fingerprint capacitive arrays, infrared facial mapping, iris pattern recognition, and voice spectral analysis—deployed to verify driver identity and authorize vehicle functions with false acceptance rates below 0.001 percent in production-grade systems. Fingerprint recognition dominates current installations due to mature semiconductor supply chains and established automotive qualification protocols. Facial recognition represents the fastest-expanding segment as cabin-mounted infrared cameras enable continuous driver monitoring without physical contact. Cloud-based deployment architectures capture growing interest among fleet operators seeking centralized authentication management across distributed vehicle assets.
The National Highway Traffic Safety Administration shapes U.S. product requirements through driver distraction and safety performance criteria, while the EU AI Act imposes risk-classification obligations on biometric systems deployed in European vehicles. Japan's Ministry of Economy, Trade and Industry coordinates domestic standards alignment with ISO/IEC 30107 presentation attack detection protocols. Stakeholders must decide whether to prioritize edge-computing architectures for latency-sensitive authentication or pursue hybrid models balancing real-time performance with over-the-air update flexibility.
Market Dynamics
Automotive biometric identification is consolidating around multimodal authentication architectures as premium OEMs race to differentiate cabin experiences while NHTSA and EU AI Act compliance deadlines compress deployment timelines. This structural pressure favors suppliers with captive sensor production and automotive-grade qualification capabilities.
Growth Catalysts
- EU AI Act risk-classification mandates:European vehicle manufacturers must deploy presentation-attack-resistant biometric systems by enforcement deadlines, accelerating procurement of ISO/IEC 30107-compliant infrared facial mapping modules.
- Fleet operator centralization:Commercial vehicle operators in Germany and Japan are adopting cloud-based authentication management to reduce unauthorized vehicle use across distributed assets.
- Infrared camera cost curves:Cabin-mounted driver monitoring systems are scaling as automotive-qualified time-of-flight sensors achieve cost parity with capacitive fingerprint arrays.
Market Restraints
- Automotive semiconductor supply concentration:Fingerprint sensor module production depends on qualified foundry capacity concentrated in Taiwan and South Korea, creating allocation risk during demand surges.
- GDPR biometric data processing friction:European privacy regulators impose purpose-limitation requirements on facial recognition data retention, complicating cloud-architecture deployment for multinational fleets.
- Capacitive array temperature limitations:Fingerprint sensors face performance degradation below minus twenty degrees Celsius, restricting reliable deployment in Nordic and Canadian markets without heating subsystems.
Strategic Opportunities
- India commercial vehicle underpenetration:The country's long-haul trucking sector lacks biometric ignition interlocks, presenting first-mover advantage for suppliers partnering with domestic OEMs.
- Voice spectral analysis convergence:Natural-language processing chipsets are integrating with cabin microphones to enable continuous driver authentication without dedicated hardware.
- Japan METI standards alignment:Domestic coordination with ISO presentation-attack protocols is accelerating export certification for Japanese biometric suppliers targeting European OEM programs.
Industry Challenges
- Automotive cybersecurity certification timelines:UN ECE R155 compliance for biometric data transmission systems extends validation cycles by eight to fourteen months.
- Multimodal sensor fusion expertise scarcity:Systems engineers capable of integrating infrared, capacitive, and acoustic authentication streams command premium compensation in Stuttgart, Detroit, and Nagoya labor markets.
- Legacy vehicle architecture retrofit complexity:Pre-2020 vehicle electronics lack CAN-FD bandwidth for real-time biometric processing, fragmenting aftermarket opportunity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Biometric Identification Market |
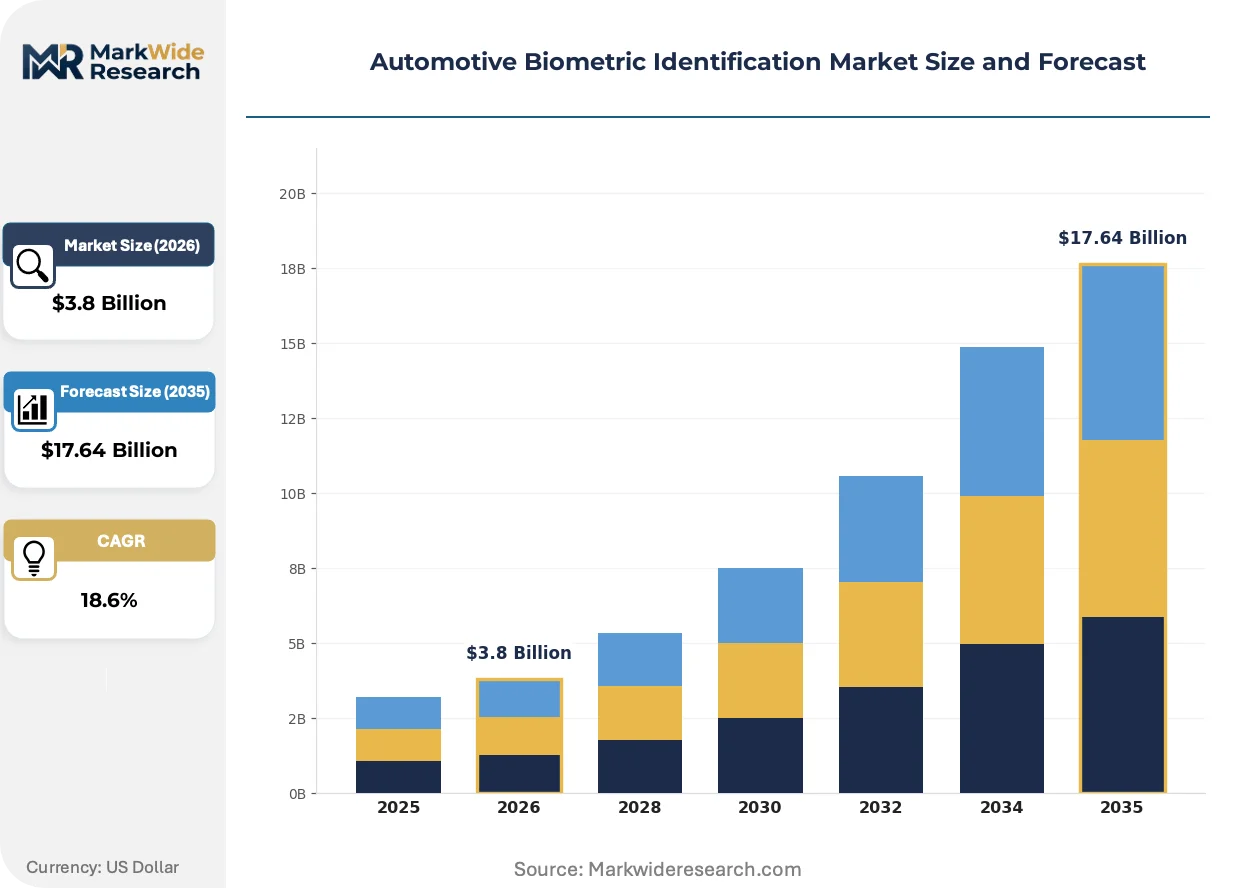
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fingerprint Recognition, Facial Recognition, Iris Recognition, Voice Recognition End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Access Control, Driver Monitoring, Vehicle Personalization, Anti-Theft Systems Deployment: Embedded Systems, Cloud-Based Solutions, Edge Computing, Hybrid Solutions |
| Companies Covered | Synaptics Incorporated, Continental AG, Fujitsu Limited, Fingerprint Cards AB, Methode Electronics, VOXX International Corporation, Hitachi Ltd., Safran S.A., HID Global Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Biometric Identification Market Emerging Trajectories
Software-defined authentication is displacing hardware-centric biometric deployment as automakers prioritize over-the-air update flexibility and feature subscription monetization. This shift compresses sensor hardware margins while expanding recurring revenue pools.
Infrared facial mapping is virtualizing driver identity verification through cabin-mounted time-of-flight cameras that capture three-dimensional facial geometry without physical contact. Luxury OEMs in Germany and Japan are adopting this technology for continuous authentication during vehicle operation. The architecture is virtualizing the traditional ignition-key paradigm by enabling seamless driver-profile switching and personalized cabin pre-configuration.
The EU AI Act imposes conformity-assessment obligations on biometric systems deployed in European vehicles, requiring third-party audit trails for algorithmic decision-making. Automotive suppliers must maintain technical documentation demonstrating false-acceptance-rate performance below 0.001 percent. Premium passenger vehicle programs face the steepest compliance burden as they deploy the most sophisticated multimodal configurations.
Subscription-based feature activation is restructuring how fleet operators procure biometric capabilities, with authentication-as-a-service models displacing perpetual hardware licenses. Commercial vehicle lessors in the United States are piloting per-driver-per-month pricing for centralized identity management. This pattern is most visible in North American heavy-truck segments where asset utilization tracking drives procurement decisions.
Automotive Biometric Identification Market Segmentation
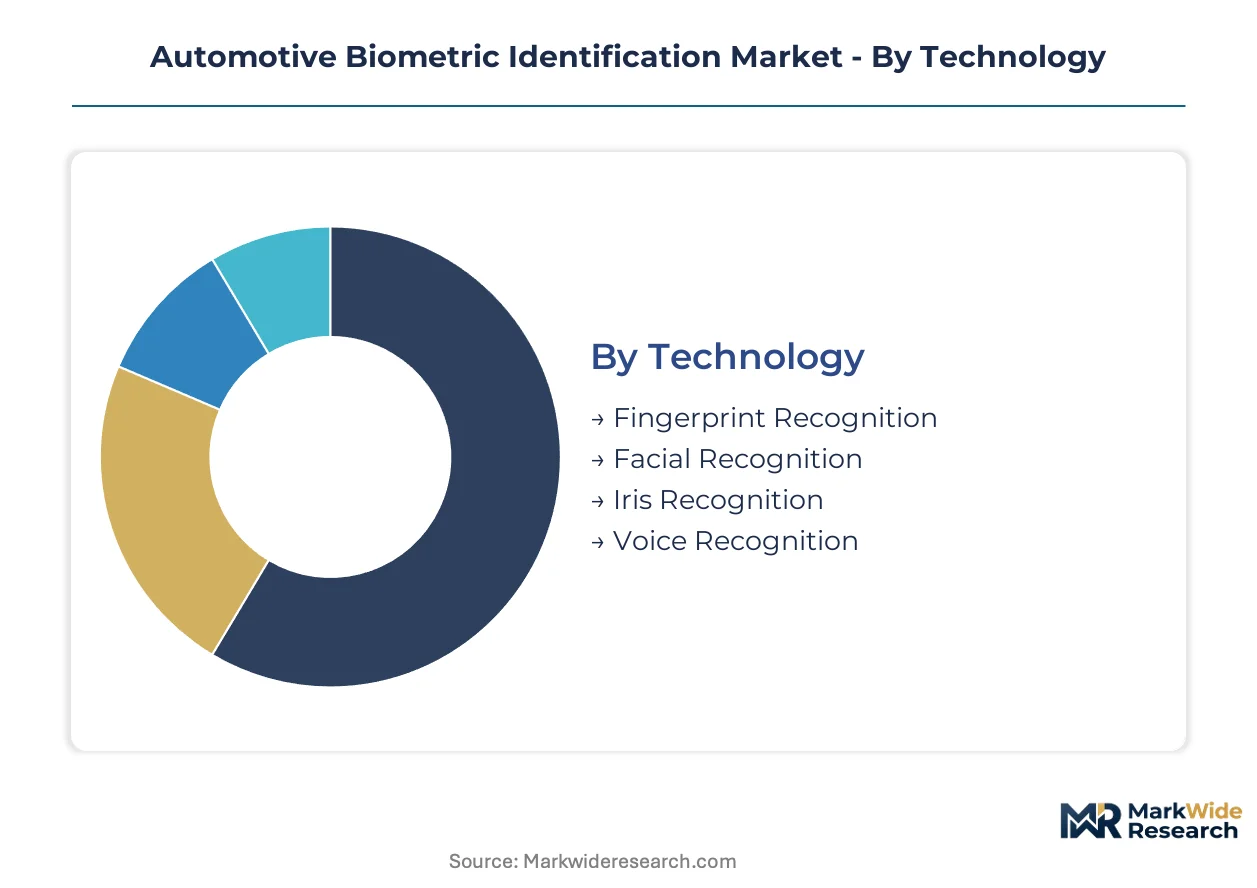
Automotive biometric identification segments diverge sharply in aftermarket service intensity. Fingerprint modules demand periodic recalibration; facial recognition systems require lens cleaning protocols and firmware updates. Tier-1 suppliers structure service contracts around these divergent maintenance profiles.
Technology:
After-sales service intensity varies dramatically across biometric modalities, with contact-based sensors generating higher replacement part revenue than contactless alternatives.
- Fingerprint Recognition:Capacitive sensor arrays authenticate through dermal ridge patterns with false acceptance rates below 0.001 percent. German luxury OEMs concentrate procurement here for ignition interlock applications, though Nordic deployments require heating subsystems to counter minus-twenty-degree performance degradation.
- Facial Recognition:Infrared time-of-flight cameras capture three-dimensional facial geometry without physical contact. Japanese automakers lead cabin-mounted driver monitoring adoption, scaling production as automotive-qualified sensors achieve cost parity with capacitive alternatives.
- Iris Recognition:Near-infrared scanners map unique patterns in the colored portion of the eye. Medical-grade accuracy attracts high-security fleet operators in the United States.
- Voice Recognition:Spectral analysis of vocal characteristics enables hands-free authentication. Natural-language processing chipsets from consumer electronics are migrating into automotive cabin microphones.
By volume, fingerprint recognition leads. By growth pace, facial recognition is expanding most quickly.
End User:
Margin structures differentiate sharply across the value chain, with captive sensor production conferring pricing power on integrated module manufacturers.
- OEMs:Premium passenger vehicle manufacturers specify multimodal architectures directly, consolidating procurement power. BMW and Mercedes-Benz programs in Germany drive ISO/IEC 30107 compliance requirements downstream.
- Tier-1 Suppliers:Continental AG and similar integrators assemble fingerprint modules from captive semiconductor production. Their backward integration into sensor manufacturing captures margin that would otherwise flow to component vendors.
- Aftermarket Providers:Service networks recalibrate sensors and replace degraded capacitive arrays. Revenue concentrates in OEM-captive programs rather than independent channels.
- Vehicle Assemblers:Contract manufacturers in emerging markets install biometric hardware specified by brand owners. Their procurement flexibility is constrained by pre-qualified supplier lists.
By installed base, OEMs dominate. By expansion trajectory, Tier-1 suppliers are gaining share fastest through vertical integration strategies.
Application:
Functional criticality determines certification burden, with safety-linked applications facing extended UN ECE R155 validation timelines.
- Access Control:Door and ignition unlocking via biometric verification replaces physical keys. European deployments must satisfy EU AI Act risk-classification mandates for presentation-attack resistance.
- Driver Monitoring:Continuous authentication during vehicle operation enables distraction detection and personalized safety interventions. NHTSA guidelines in the United States accelerate sensor deployment for drowsiness alerts.
- Vehicle Personalization:Seat position, climate, and infotainment preferences activate upon driver identification. This convenience feature carries lighter regulatory burden than safety-critical applications.
- Anti-Theft Systems:Biometric immobilizers prevent unauthorized engine starts. Indian commercial vehicle fleets represent underpenetrated demand for this application.
By deployment volume, access control leads. By regulatory tailwind, driver monitoring is climbing the fastest.
Deployment:
Architecture choices trade latency sensitivity against over-the-air update flexibility, with fleet operators and individual owners diverging in preference.
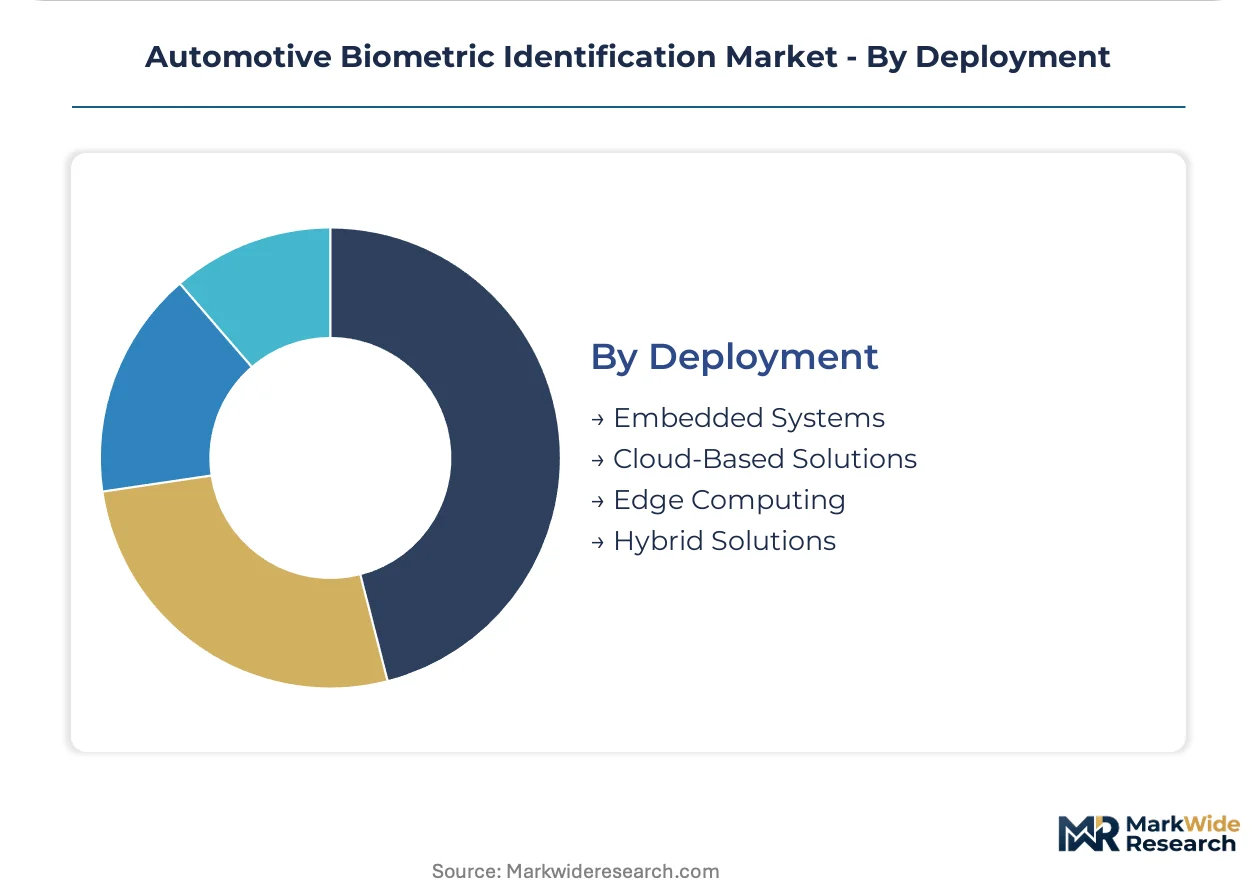
- Embedded Systems:Dedicated hardware processors execute authentication within the vehicle. German OEMs favor this architecture for deterministic response times in safety-critical functions.
- Cloud-Based Solutions:Centralized servers manage identity verification across distributed vehicle assets. Commercial lessors in the United States pilot subscription-based authentication-as-a-service models.
- Edge Computing:Local processing with periodic cloud synchronization balances real-time performance and update flexibility. Japanese METI standards alignment accelerates export certification for these hybrid architectures.
- Hybrid Solutions:Dual-path authentication routes critical functions through embedded processors while delegating convenience features to cloud infrastructure. GDPR biometric data processing friction in Europe complicates this architecture's deployment.
By current installation share, embedded systems lead. By strategic interest among fleet operators, cloud-based solutions are gaining traction fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for automotive biometric systems varies sharply across geographies. Fleet operators in Germany and Japan absorb premium pricing for multimodal architectures, while commercial buyers in India and Brazil prioritize cost-optimized fingerprint modules for theft prevention.
United States
Heavy-truck lessors drive cloud-based authentication-as-a-service pilots with per-driver subscription models. NHTSA driver distraction guidelines mandate cabin-mounted monitoring for drowsiness alerts. Detroit's Tier-1 engineering clusters concentrate multimodal sensor fusion expertise for premium OEM programs.
Germany
Luxury automakers specify ISO/IEC 30107-compliant infrared facial mapping for ignition interlock and continuous driver verification. EU AI Act risk-classification deadlines compress procurement cycles for presentation-attack-resistant modules. Stuttgart's supplier ecosystem anchors captive fingerprint sensor production through backward-integrated manufacturing.
Japan
Domestic OEMs scale cabin-mounted time-of-flight cameras as automotive-qualified sensors achieve cost parity with capacitive alternatives. METI coordinates standards alignment with ISO presentation-attack detection protocols for export certification. Nagoya's automotive electronics corridor concentrates driver-monitoring system integration expertise.
India
Long-haul trucking fleets represent underpenetrated demand for biometric ignition interlocks and anti-theft immobilizers. Central Motor Vehicles Rules amendments are accelerating commercial vehicle safety equipment mandates. Tamil Nadu and Maharashtra automotive clusters attract first-mover suppliers partnering with domestic OEMs for localized production.
South Korea
Semiconductor foundries supply qualified capacitive sensor arrays to German and Japanese Tier-1 integrators. The country's national automotive safety regulator aligns domestic certification with UN ECE R155 cybersecurity requirements. Seoul's electronics manufacturing belt concentrates fingerprint module assembly capacity for export markets.
Automotive Biometric Identification Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. The vendor base organizes around three distinct archetypes: semiconductor specialists with captive sensor production, Tier-1 integrators assembling multimodal modules, and component suppliers seeking compact form factor partnerships. Competitive moves center on backward integration into fingerprint sensor manufacturing and strategic alliances with luxury OEM programs in Germany and Japan.
Among the semiconductor-specialist tier, Synaptics Incorporated and Fingerprint Cards AB exemplify component suppliers optimizing capacitive controllers for automotive temperature ranges and compact biometric form factors respectively. Continental AG anchors the Tier-1 integrator archetype through in-house production of fingerprint sensor modules. These three entities collectively represent the competitive structure: specialists defending technology differentiation, integrators capturing margin through upstream control, and module manufacturers scaling through automotive qualification protocols.
| Leading Market Players |
|---|
| Synaptics Incorporated |
| Continental AG |
| Fujitsu Limited |
| Fingerprint Cards AB |
| Methode Electronics |
| VOXX International Corporation |
| Hitachi Ltd. |
| Safran S.A. |
| HID Global Corporation |
| Others |
Supply Flow & Price Mechanics
Qualified foundry capacity concentrated in Taiwan and South Korea anchors cost structures for capacitive fingerprint arrays, pushing margin capture toward Tier-1 integrators with captive semiconductor production. OEMs purchasing discrete sensor modules face pricing pressure from allocation risk during demand surges, while backward-integrated suppliers defend margin pools through in-house manufacturing.
Pricing Analysis
After-sales service revenue from sensor recalibration and module replacement drives lifetime value in this market. Three-tier pricing structure across premium, standard, and economy levels separates ISO/IEC 30107-certified multimodal systems from single-modality configurations and basic fingerprint interlocks. Cost compression in capacitive sensor arrays is intensifying because automotive-qualified time-of-flight cameras achieve cost parity with legacy fingerprint technology. Fleet operators in North America show least price sensitivity for subscription-based authentication-as-a-service models, while Indian commercial vehicle buyers prioritize economy-tier hardware for theft prevention.
Supply Chain Analysis
Extended payment terms from German and Japanese OEMs to Tier-1 integrators compress working capital cycles for component suppliers. Semiconductor fabrication draws from Taiwan, South Korea, and Japan for qualified automotive sensor production. Raw material dependencies include silicon wafers, infrared optics substrates, and specialized capacitive coating materials. Single-source vulnerability around automotive-grade time-of-flight sensor supply creates allocation risk during OEM program ramps. Distribution runs through captive OEM service networks rather than independent aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across deployment architectures and regional regulatory regimes creates niche opportunities for specialized entrants. Demand-side shift toward software-defined authentication with over-the-air update capability is splintering procurement patterns between embedded-system purists and cloud-architecture adopters.
For Market Incumbents: Pre-empt margin erosion in discrete sensor modules by deepening captive production of fingerprint semiconductor arrays. Consolidate procurement relationships with luxury OEM programs in Stuttgart and Nagoya before compliance deadlines compress supplier selection windows. Threat from natural-language processing chipsets migrating into cabin microphones demands accelerated voice-authentication R&D investment. For New Entrants and Emerging Players: Establish a beachhead in Indian commercial vehicle anti-theft systems where long-haul trucking fleets lack biometric ignition interlocks. White-space targets include voice spectral analysis integration and edge-computing architectures for GDPR-constrained European fleets. Go-to-market angle should emphasize localized production partnerships with Tamil Nadu and Maharashtra automotive clusters. For Investors and Strategic Acquirers: Capital is best deployed toward Tier-1 integrators with automotive-grade qualification capabilities and existing OEM program relationships. Long-term viability favors suppliers positioned for multimodal sensor fusion as regulatory mandates expand. Signal to watch is EU AI Act enforcement action against non-compliant biometric deployments as inflection indicator for consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captures margin pools from semiconductor specialists while securing allocation priority during demand surges. |
| ISO/IEC 30107 Certification Investment | Unlocks European OEM procurement channels ahead of EU AI Act enforcement deadlines. |
| Cloud-Based Authentication Platform Launch | Enables subscription revenue from fleet operators seeking centralized identity management. |
| Partnership with Domestic OEMs in India | Secures first-mover positioning in underpenetrated commercial vehicle anti-theft segment. |
| Multimodal Sensor Fusion R&D Expansion | Addresses scarcity premium for systems engineers capable of integrating infrared, capacitive, and acoustic streams. |
Methodological Framework
Operator-level perspectives from Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet operations managers anchored the qualitative base. Primary interviews combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings, and regulatory submission records. Bottom-up modeling of installed biometric systems triangulated against top-down OEM program announcements.
Scenario-bracketing framed the analytical approach across the projection horizon. Segmentation dimensions modeled include biometric modality, vehicle class, deployment architecture, OEM tier, and regional regulatory cluster. CAGRs derived from unit shipment trajectories and content-per-vehicle scaling assumptions. Industry-specific inputs encompassed NHTSA guideline implementation timelines and EU AI Act risk-classification compliance schedules.
Sensitivities concentrate around automotive semiconductor supply allocation, GDPR enforcement patterns on biometric data retention, and fleet operator adoption curves for subscription-based models. Forecasts reflect documented assumptions on regulatory deadline adherence and sensor cost curve trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Air Brake System Market
Automotive Safety and Security Systems
Automotive Anti Lock Braking System and Electronic Stability Control Market
Automotive Safety and Security Systems
Driver Alert System Market
Automotive Safety and Security Systems
North America Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Asia-Pacific Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Global Automotive Backup Camera Market
Automotive Safety and Security Systems
Automotive Perimeter Lighting System Market
Automotive Safety and Security Systems
Biometric Vehicle Access System Market
Automotive Safety and Security Systems
Global Automotive Terrain Response System Market
Automotive Safety and Security Systems
Automotive Smart Helmet Market
Automotive Safety and Security Systems
Wearable Motorcycle Airbags Market
Automotive Safety and Security Systems
Global Automotive Curtain Airbags Market
Automotive Safety and Security Systems
Automotive Anti-Roll Bar Market
Automotive Safety and Security Systems
Automotive Immobilizer Market
Automotive Safety and Security Systems
Driving Armor Market
Automotive Safety and Security Systems
Automotive Smart Security Device Market