
 Two Wheeler Anti-Lock Braking System Market | 2026-2036
Two Wheeler Anti-Lock Braking System Market Size, Share, and Industry Trends Forecast 2026-2036
Two Wheeler Anti-Lock Braking System Market Analytics
Aftermarket distribution networks across South Asia and Latin America are reshaping how component suppliers reach independent repair channels. Robert Bosch GmbH leverages its sensor manufacturing scale to dominate European OEM supply relationships. ZF Friedrichshafen AG anchors its position through hydraulic valve specialization for premium motorcycle platforms. Continental AG competes by extending its automotive ABS intellectual property into compact two-wheeler architectures.
A two-wheeler anti-lock braking system modulates hydraulic pressure through wheel-speed sensors and solenoid valves to prevent wheel lock during deceleration, typically operating at response intervals below 15 milliseconds. The system serves primarily to reduce stopping distances on low-friction surfaces and maintain directional stability during emergency braking maneuvers. Electronic ABS configurations now lead unit shipments across the technology dimension, while hydraulic systems retain margin concentration in performance motorcycle segments. Scooter installations within the end-user dimension represent the fastest-expanding category as urban mobility platforms mandate fleet-wide fitment.
India's Ministry of Road Transport and Highways enforces ABS fitment through the Central Motor Vehicles Rules, while the European Union applies UNECE R78 braking performance standards to type-approved two-wheelers. The US National Highway Traffic Safety Administration maintains FMVSS No. 122 motorcycle braking requirements that indirectly pressure ABS adoption through stopping-distance benchmarks. Stakeholders must monitor how Indonesia's national transport safety agency and Brazil's CONTRAN evolve local homologation rules as these jurisdictions represent the next wave of regulatory-driven replacement demand.
Market Dynamics
The Two Wheeler Anti-Lock Braking System Market faces intense pressure from India's mandatory ABS regulations under the Central Motor Vehicles Rules, which now compel single-channel system adoption across the world's largest two-wheeler production base.
Growth Catalysts
- Indonesian Ride-Hailing Fleet Mandates:Urban mobility platforms operating dense scooter networks in Jakarta and Surabaya now require ABS fitment across their entire commercial fleets, creating concentrated demand pull.
- Central Motor Vehicles Rules (India):Mandatory single-channel ABS requirements for all new two-wheelers above 125cc have eliminated non-ABS production lines at major domestic manufacturers.
- Electronic ABS Architecture:Sensor-integrated electronic configurations are displacing hydraulic alternatives in mass-market scooter segments, reducing unit cost curves and enabling broader fitment.
Market Restraints
- Sensor Supply Concentration:Wheel-speed sensor manufacturing clusters heavily in East Asian semiconductor foundries, exposing ABS module assemblers to single-source vulnerability.
- Copper and Rare Earth Volatility:Solenoid valve production depends on copper winding materials and neodymium-based magnetic components subject to commodity price swings.
- UNECE R78 Compliance Burden:European type-approval testing protocols for two-wheeler braking performance impose extended homologation timelines that delay new market entrants.
Strategic Opportunities
- Brazilian CONTRAN Rule Evolution:Pending updates to the country's national traffic council regulations may replicate Indian mandatory ABS frameworks, opening replacement demand in Latin America's largest two-wheeler fleet.
- Aftermarket Channel Penetration:Independent repair networks across South Asia and Latin America remain underpenetrated for ABS retrofit kits, creating white space for component suppliers.
- Dual-Channel and Cornering ABS Convergence:Integration of inertial measurement units with hydraulic modulation is enabling premium motorcycle platforms to adopt automotive-grade safety performance.
Industry Challenges
- Embedded Software Certification:Functional safety validation under ISO 26262 standards for ABS control algorithms requires specialized automotive software engineering talent that remains scarce in South Asian manufacturing hubs.
- Legacy Two-Wheeler Fleet Integration:Retrofit ABS installation on pre-regulation vehicles demands mechanical compatibility solutions for drum brake architectures that dominate Indonesia's and India's existing parc.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two Wheeler Anti-Lock Braking System Market |
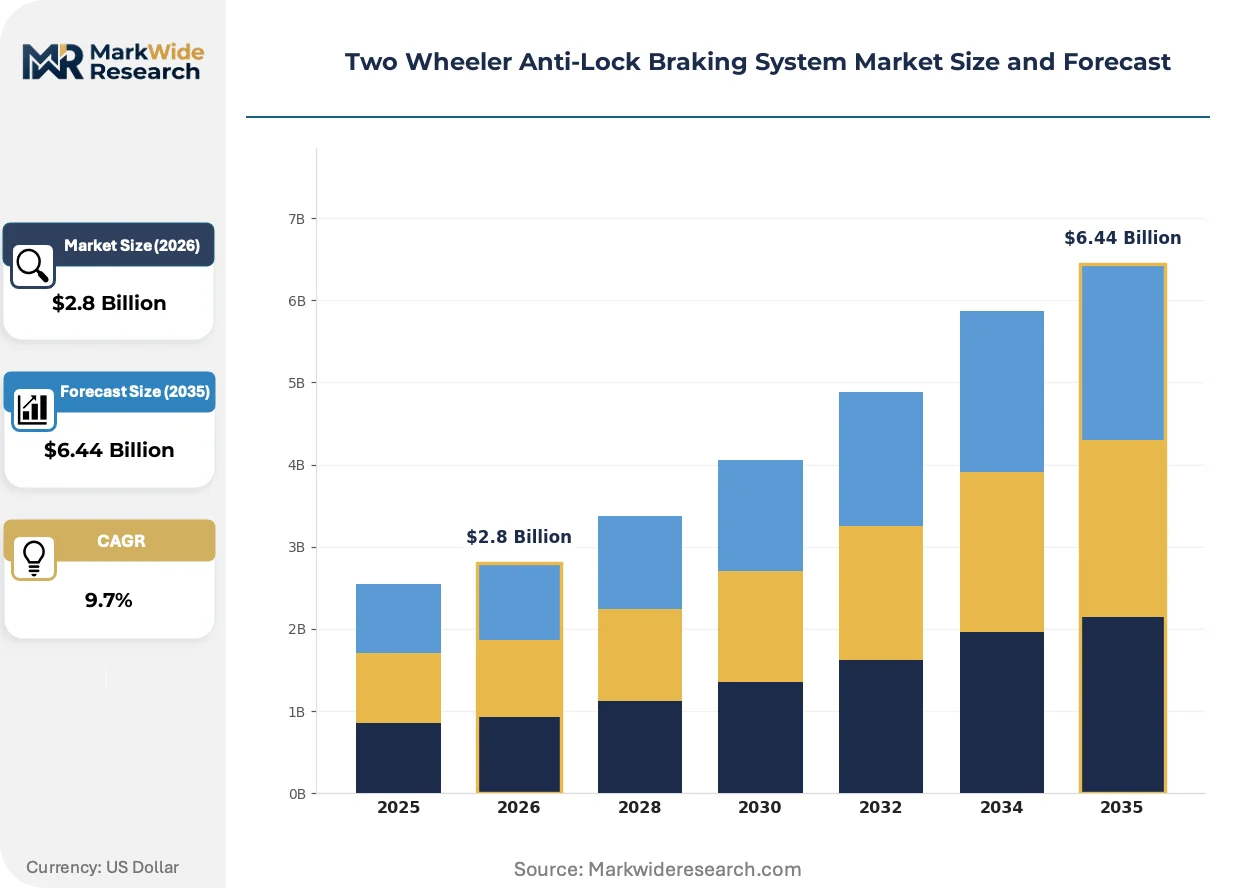
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
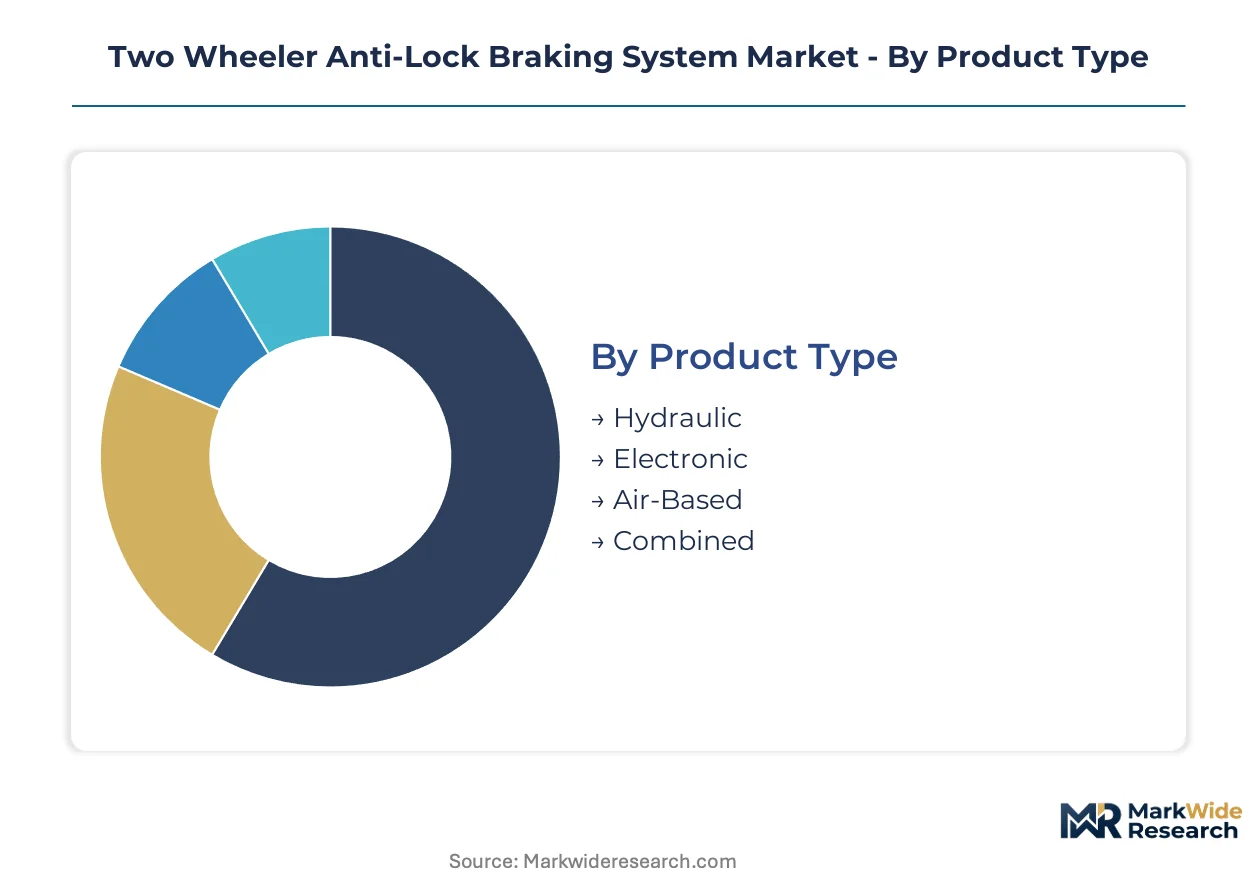
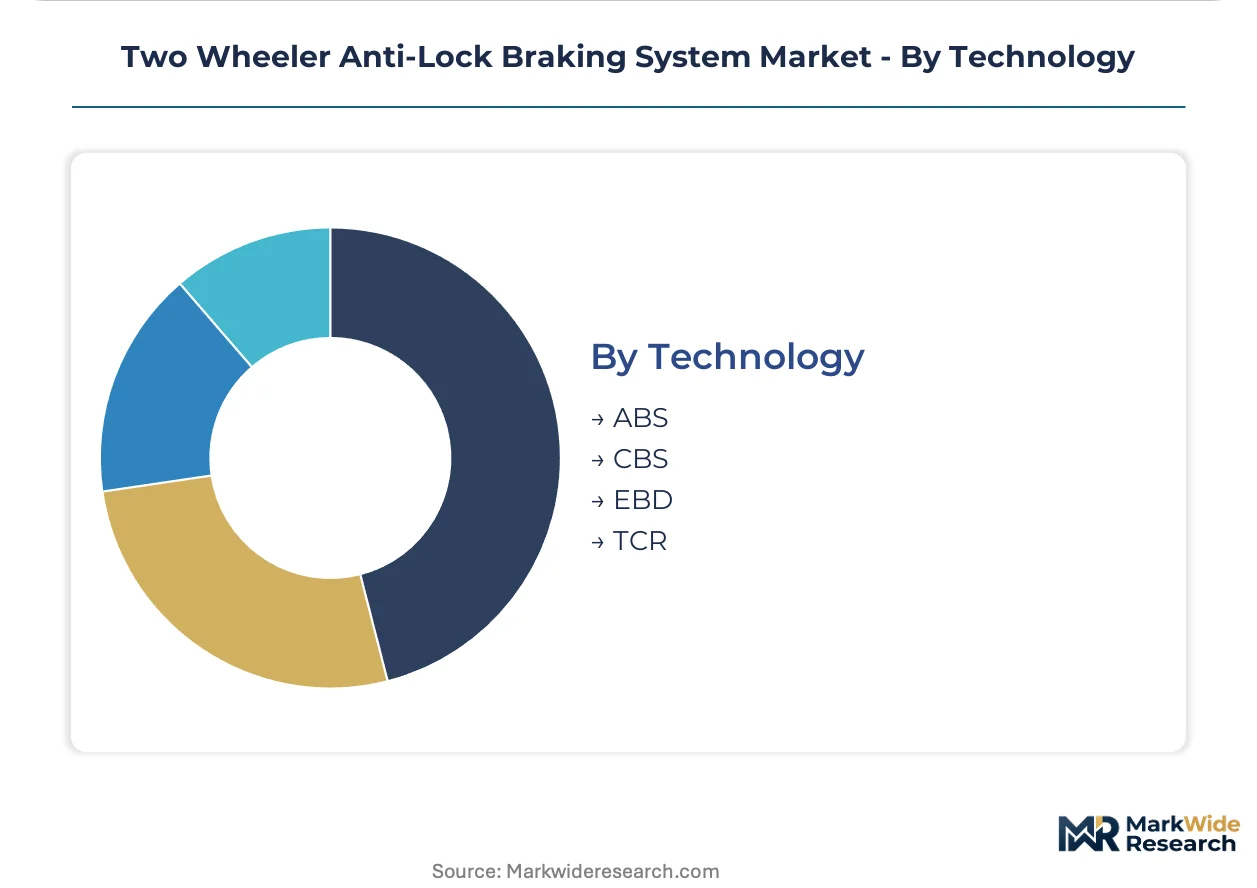
| Segmentation | Product Type: Hydraulic, Electronic, Air-Based, Combined End User: Motorcycles, Scooters, E-Bikes, ATVs Installation Type: OEM, Aftermarket, Retrofit, Custom Technology: ABS, CBS, EBD, TCR |
| Companies Covered | ZF Friedrichshafen AG, Hitachi Astemo, Ltd., Robert Bosch GmbH, Nissin Kogyo, BWI Group, Continental AG, AISIN SEIKI Co., Ltd., Mando Corporation, Brembo S.p.A, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two Wheeler Anti-Lock Braking System Market Evolving Landscape
Three distinct forces are compressing development cycles and redrawing competitive boundaries in two-wheeler braking systems. Technology virtualization, regulatory harmonization, and procurement consolidation are converging to reshape how suppliers capture value.
Sensor fusion architectures are virtualizing traditional hydraulic ABS control logic by replacing mechanical pressure modulation with predictive algorithms. Premium motorcycle manufacturers in Germany and Japan are adopting these systems for their flagship platforms. This virtualization is compressing hardware component counts while elevating software intellectual property as the primary value determinant.
UNECE R78 braking performance standards are harmonizing type-approval requirements across European Union member states and influencing regulatory frameworks in Southeast Asian markets. The regulation's stopping-distance benchmarks indirectly mandate ABS fitment by rendering non-ABS configurations technically non-compliant. Scooter manufacturers targeting export markets are responding by pre-fitting ABS across their entire product lines regardless of domestic regulatory status.
Fleet procurement by urban mobility platforms is consolidating buyer power and unbundling traditional OEM-supplier relationships. Ride-hailing operators in Indonesia and India now negotiate direct ABS supply agreements independent of motorcycle manufacturers. This disintermediation is most visible in Jakarta's commercial scooter corridors, where platform-specified braking systems override factory-standard configurations.
Two Wheeler Anti-Lock Braking System Market Segmentation
Segmentation in two-wheeler ABS reveals how technology maturity, regulatory pressure, and fleet procurement patterns concentrate value across distinct hardware configurations. Understanding these divisions exposes where suppliers can defend margin positions and where cost compression dominates purchasing decisions.
Product Type:
Mature hydraulic architectures coexist with emerging electronic configurations as semiconductor integration redefines system economics.
- Hydraulic:Mechanical pressure modulation through solenoid valves and pump assemblies delivers proven reliability for performance motorcycle platforms. European and Japanese premium manufacturers specify these systems for their flagship models, though sensor integration requirements are elevating bill-of-material costs.
- Electronic:Sensor-integrated architectures replace mechanical modulation with algorithm-driven brake control, reducing component counts while enabling predictive intervention. Mass-market scooter manufacturers in India and Indonesia are standardizing these configurations as single-channel mandates eliminate purely hydraulic alternatives.
- Air-Based:Compressed air actuation serves heavy commercial three-wheeler segments in South Asian logistics corridors where hydraulic fluid contamination risks persist.
- Combined:Hybrid architectures merge hydraulic backup with electronic primary control for export-market type-approval redundancy.
Hydraulic systems retain volume leadership in premium displacement classes; electronic configurations hold the steepest expansion curve as mandatory fitment spreads through Asian mass markets.
End User:
Customer type segmentation tracks how commercial fleet procurement is diverging from individual consumer purchasing patterns.
- Motorcycles:Internal combustion and electric powertrains above 125cc displacement carry regulatory-mandated ABS across Indian, European, and Southeast Asian jurisdictions. Ride-hailing fleet operators in Jakarta and Surabaya now specify dual-channel systems for their commercial motorcycle pools.
- Scooters:Step-through architectures dominate urban mobility platform procurement, with Gojek and Grab mandating fleet-wide ABS fitment ahead of regulatory deadlines. Electronic single-channel systems are displacing drum brake alternatives in Indonesian and Vietnamese manufacturing lines.
- E-Bikes:Low-speed electric two-wheelers below 25 km/h thresholds remain exempt from ABS mandates in most jurisdictions, though European type-approval creep is extending requirements into higher-speed categories.
- ATVs:Off-road recreational and utility quadricycles specify ABS for premium segments, with Canadian and Australian agricultural applications driving specialized waterproof module demand.
Scooter installations command the largest unit volumes; motorcycle platforms generate the highest per-unit system values.
Installation Type:
Channel structure reflects how regulatory timing creates distinct aftermarket windows across mature and emerging compliance regimes.
- OEM:Factory-fit systems integrate ABS modules during motorcycle assembly, with Indian and Indonesian manufacturers now engineering single-channel ABS as standard architecture rather than optional equipment.
- Aftermarket:Independent repair channels in Brazil and Mexico distribute ABS retrofit kits for pre-regulation fleets, though sensor calibration complexity limits penetration.
- Retrofit:Mechanical adaptation kits enable drum brake conversion for legacy parc vehicles, particularly in Indonesian scooter fleets where platform mandates outpace natural replacement cycles.
- Custom:Performance tuning segments in Germany and Japan specify upgraded dual-channel and cornering ABS for track-day and touring applications.
OEM channels dominate current throughput; aftermarket and retrofit segments are gaining share fastest as regulatory replacement waves mature.
Technology:
Functional integration is blurring traditional boundaries between anti-lock, distribution, and traction control systems.
- ABS:Core wheel-speed sensor and solenoid valve architecture prevents lock-up during deceleration, with response intervals below 15 milliseconds now standard across electronic configurations.
- CBS:Combined braking systems mechanically link front and rear circuits, serving as a cost-reduced alternative where full ABS mandates have not yet taken effect.
- EBD:Electronic brake force distribution modulates pressure bias between axles, typically integrated as a software layer within ABS control modules.
- TCR:Traction control regulation extends ABS sensor infrastructure to manage rear wheel spin during acceleration, converging with inertial measurement unit integration in premium platforms.
Standalone ABS retains installed base dominance; integrated EBD-TCR configurations are climbing the fastest as motorcycle electronics platforms consolidate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Ministry of Road Transport and Highways anchors regulatory momentum through Central Motor Vehicles Rules mandating single-channel ABS on two-wheelers above 125cc, reshaping production standards across the world's largest motorcycle manufacturing base.
India
Domestic OEMs have eliminated non-ABS production lines entirely as Central Motor Vehicles Rules compliance became non-negotiable. The Pune-Chennai industrial corridor concentrates module assembly operations, where Tier-1 suppliers co-locate with Hero MotoCorp and TVS Motor manufacturing plants to minimize logistics friction.
Indonesia
Jakarta-based ride-hailing platforms Gojek and Grab mandate fleet-wide ABS fitment ahead of regulatory deadlines, creating concentrated demand pull for electronic single-channel systems. The Bekasi-Tangerang manufacturing belt hosts scooter assembly operations where platform-specified braking configurations now override factory-standard equipment.
Germany
Premium motorcycle manufacturers specify dual-channel and cornering ABS for flagship platforms, leveraging KBA type-approval expertise to accelerate homologation timelines. The Stuttgart-Munich engineering corridor concentrates ABS control algorithm development, where functional safety validation under ISO 26262 standards attracts specialized automotive software talent.
Japan
Hitachi Astemo and Nissin Kogyo anchor domestic supply relationships through sensor-integrated electronic architectures displacing hydraulic alternatives. The Aichi-Gunma industrial zone concentrates precision solenoid valve manufacturing, where METI-supported R&D consortia advance predictive braking algorithms for export-market type-approval.
Brazil
CONTRAN regulatory evolution signals potential mandatory ABS frameworks replicating Indian compliance structures, opening replacement demand in Latin America's largest two-wheeler fleet. The São Paulo industrial belt hosts independent repair networks distributing retrofit kits for pre-regulation vehicle parc conversion.
Two Wheeler Anti-Lock Braking System Market Competitive Landscape
Full-line system integrators and component specialists split the market between turnkey module supply and targeted sub-assembly provision. The vendor base concentrates around three strategic archetypes: sensor-scale manufacturers leveraging semiconductor foundry relationships, hydraulic valve specialists commanding premium motorcycle fitment, and diversified automotive suppliers extending passenger-car ABS intellectual property into compact two-wheeler architectures. Dominant competitive moves include backward integration into wheel-speed sensor manufacturing and strategic partnerships with urban mobility platforms for fleet-specified system procurement.
Within the diversified automotive tier, Robert Bosch GmbH and Continental AG exemplify scale-driven positions, while ZF Friedrichshafen AG occupies a specialist niche in hydraulic modulation. Hitachi Astemo, Ltd. and Nissin Kogyo anchor Japanese-origin supply relationships through co-development partnerships with domestic OEMs. Brembo S.p.A represents the performance-segment archetype, with Mando Corporation and BWI Group situating within the mid-tier module assembly space.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Hitachi Astemo, Ltd. |
| Robert Bosch GmbH |
| Nissin Kogyo |
| BWI Group |
| Continental AG |
| AISIN SEIKI Co., Ltd. |
| Mando Corporation |
| Brembo S.p.A |
| Others |
Value Network & Pricing Analysis
The Bekasi-Tangerang manufacturing belt concentrates electronic ABS module assembly for Indonesian ride-hailing fleets, where platform-mandated procurement volumes compress unit economics and shift pricing power toward fleet operators negotiating direct supply agreements.
Pricing Analysis
Price spreads between German-engineered dual-channel systems and mass-market Indian single-channel units span three performance tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade, with UNECE R78 type-approval commanding premium positioning. Cost compression in economy tiers intensifies because semiconductor foundry capacity constraints elevate sensor costs. Fleet procurement teams at Gojek and Grab exhibit highest price sensitivity; premium motorcycle OEMs in Stuttgart and Munich demonstrate lowest.
Supply Chain Analysis
Tariff exposure between China and Southeast Asian assembly hubs dominates supply chain risk assessment for wheel-speed sensor procurement. Manufacturing concentrates in China, Japan, and Germany, with module assembly drawing from Taiwanese semiconductor foundries and Japanese precision valve operations. Solenoid valve production rests on copper winding materials and neodymium-based magnetic components. Single-source vulnerability persists in East Asian sensor manufacturing clusters. Distribution runs through Tier-1 supplier co-location agreements with Hero MotoCorp and TVS Motor assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
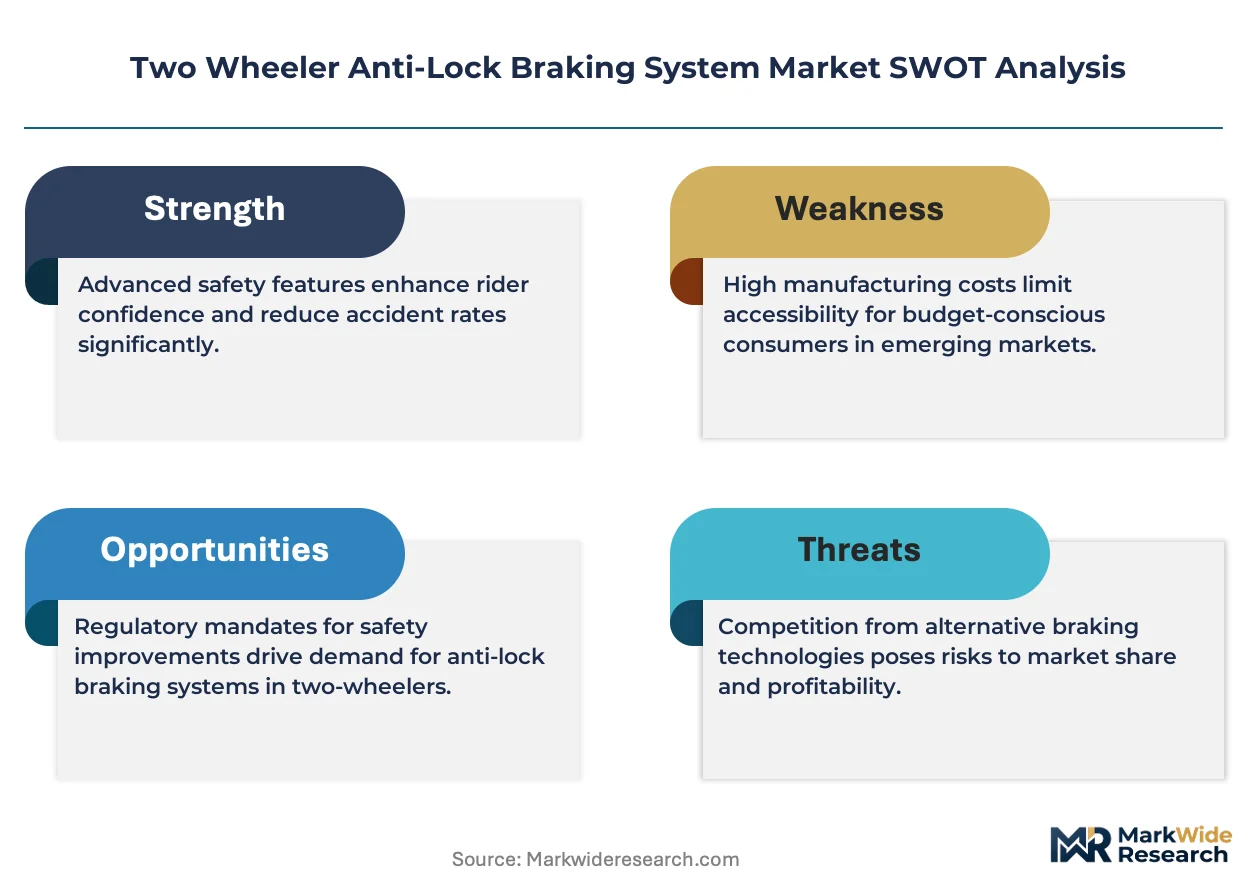
The Two Wheeler Anti-Lock Braking System Market functions as a regulatory-moat story where Central Motor Vehicles Rules entrenchment creates high switching costs for OEMs locked into approved supplier relationships.
For Market Incumbents: Harden sensor manufacturing scale advantages through backward integration into wheel-speed semiconductor fabrication, insulating against East Asian foundry concentration risk. Expand captive supply of solenoid valve copper windings to neutralize commodity volatility. Lock in multi-year fleet procurement contracts with Jakarta-based mobility platforms before Brazilian CONTRAN mandates replicate Indian regulatory frameworks and attract new entrants. For New Entrants and Emerging Players: Build out aftermarket retrofit kit distribution for Brazil's pre-regulation scooter parc, where independent repair network penetration remains lowest among major two-wheeler markets. Target drum brake mechanical adaptation solutions for Indonesian legacy fleets where platform mandates outpace natural replacement cycles. Pursue direct technical service partnerships with São Paulo-based independent distributors rather than OEM supply relationships. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because mandatory ABS frameworks are propagating from India through Southeast Asia toward Latin America, creating decade-long replacement demand visibility. Acquisition targets should display ISO 26262 functional safety certification capabilities and established urban mobility platform relationships. Watch for Indonesian national transport safety agency rule finalization as the inflection signal for Southeast Asian demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive wheel-speed sensor production insulates Robert Bosch GmbH and Continental AG from East Asian foundry concentration risk. |
| Fleet Procurement Direct Agreements | Gojek and Grab platform-specified ABS configurations disintermediate traditional OEM-supplier relationships in Jakarta. |
| Dual-Channel ABS Platform Standardization | Premium motorcycle manufacturers in Germany consolidate electronic-hydraulic architectures for UNECE R78 compliance efficiency. |
| Aftermarket Retrofit Channel Expansion | Brazilian independent repair networks address pre-regulation vehicle parc conversion ahead of CONTRAN rule evolution. |
| ISO 26262 Functional Safety Certification | Software validation capabilities attract scarce automotive engineering talent to Stuttgart-Munich and Aichi-Gunma development clusters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with ABS module procurement managers at Hero MotoCorp and TVS Motor, fleet operations directors at Gojek and Grab, and Tier-1 supplier engineering leads in the Pune-Chennai corridor. Secondary validation drew from Central Motor Vehicles Rules filings, UNECE R78 type-approval databases, Indonesian industrial production statistics, and CONTRAN regulatory dockets. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Calibration across the analysis window employed technology-segmented adoption curves weighted by regulatory enforcement timelines and fleet procurement contract visibility. Modeled dimensions spanned product type, end-user category, installation channel, and technology integration level, with additional stratification by displacement class and regional homologation cluster. CAGRs derived from slope-consistent trajectory fitting against historical penetration benchmarks. Forecast inputs incorporated ride-hailing fleet expansion schedules and rare earth commodity price stress scenarios.
Stress conditions across neodymium price volatility, Indonesian regulatory acceleration, and Brazilian CONTRAN implementation delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding sensor foundry capacity expansion and urban mobility platform procurement continuity. Material shifts in UNECE R78 harmonization scope or Indian CMVS displacement threshold adjustments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Rear Occupant Alert System Market
Automotive Safety and Security Systems
Automotive ABS and ESC Market
Automotive Safety and Security Systems
Adaptive Headlights Market
Automotive Safety and Security Systems
Global Automotive Camera Cleaning System Market
Automotive Safety and Security Systems
ABS Sensors Market
Automotive Safety and Security Systems
Automotive Collision Avoidance Systems Market
Automotive Safety and Security Systems
Europe Pedestrian Detection Systems Market
Automotive Safety and Security Systems
Anti-Lock Braking System (ABS) Market
Automotive Safety and Security Systems
Biometric in the Automotive Market
Automotive Safety and Security Systems
Automotive Pedestrian Protection System Market
Automotive Safety and Security Systems
Global Automotive Fog Lights Market
Automotive Safety and Security Systems
Driver Attention Alert Systems Market
Automotive Safety and Security Systems
LAMEA Hill-Start Assist System Market
Automotive Safety and Security Systems
Occupant Classification System Market
Automotive Safety and Security Systems
Global Automotive Defogger System Market
Automotive Safety and Security Systems
Automotive Crash Barriers Market