
 China Traffic Sign Recognition Market | 2026-2036
China Traffic Sign Recognition Market Size, Share, and Industry Trends Forecast 2026-2036
China Traffic Sign Recognition Market Outlook
China's dual carbon goals and MIIT fuel-economy mandates for new energy vehicles is pivoting procurement priorities across the supply chain. Continental AG anchors its position through deep manufacturing scale in Jiangsu province. Huawei Technologies Co., Ltd. differentiates via in-house AI chip design and 5G-V2X integration. Denso Corporation sustains competitiveness through captive sensor production and long-standing relationships with Japanese-Chinese joint-venture OEMs.
Traffic sign recognition encompasses camera-based systems that detect, classify, and interpret road signs using convolutional neural networks operating at frame rates exceeding 30 fps with sub-100-millisecond latency, primarily serving collision avoidance and regulatory compliance functions in intelligent vehicles. Deep learning architectures now dominate algorithm development as automakers demand higher accuracy in adverse weather conditions. Tier-1 Suppliers represent the most concentrated buyer segment, while Smart City Solutions deployment is expanding fastest as municipal governments integrate recognition data into centralized traffic management platforms.
MIIT certification rules, GB standards for intelligent connected vehicles, and SAMR data security regulations collectively shape product design, software update protocols, and cross-border data handling requirements for recognition system vendors. The National Information Security Standardization Technical Committee is drafting additional technical specifications for automotive visual perception data. Stakeholders must monitor evolving GB standard drafts and provincial smart city procurement timelines to align R&D roadmaps with compliance deadlines.
Market Dynamics
MIIT mandates for intelligent connected vehicles are tightening software validation requirements while Yangtze River Delta manufacturing clusters concentrate Tier-1 supplier procurement. Deep learning architectures now dominate algorithm development as automakers demand higher accuracy in adverse weather conditions.
Growth Catalysts
- Dual carbon policy framework:MIIT fuel-economy mandates for new energy vehicles are pivoting procurement priorities across the entire supply chain toward electrified platforms.
- 5G-V2X infrastructure deployment:Municipal governments in Shanghai and surrounding Jiangsu and Zhejiang provinces are integrating recognition data into centralized traffic management platforms.
- Convolutional neural network advancement:Frame rates exceeding 30 fps with sub-100-millisecond latency now enable collision avoidance functions previously unattainable with conventional computer vision.
Market Restraints
- Sensor cost volatility:CMOS image sensor and automotive-grade GPU pricing fluctuations compress Tier-1 supplier margins on volume contracts.
- Regional supply concentration:Jiangsu province hosts over half of domestic recognition system manufacturing, creating vulnerability to localized logistics disruptions.
- Cross-border data friction:SAMR data security regulations impose strict handling requirements on visual perception data collected by foreign-owned joint ventures.
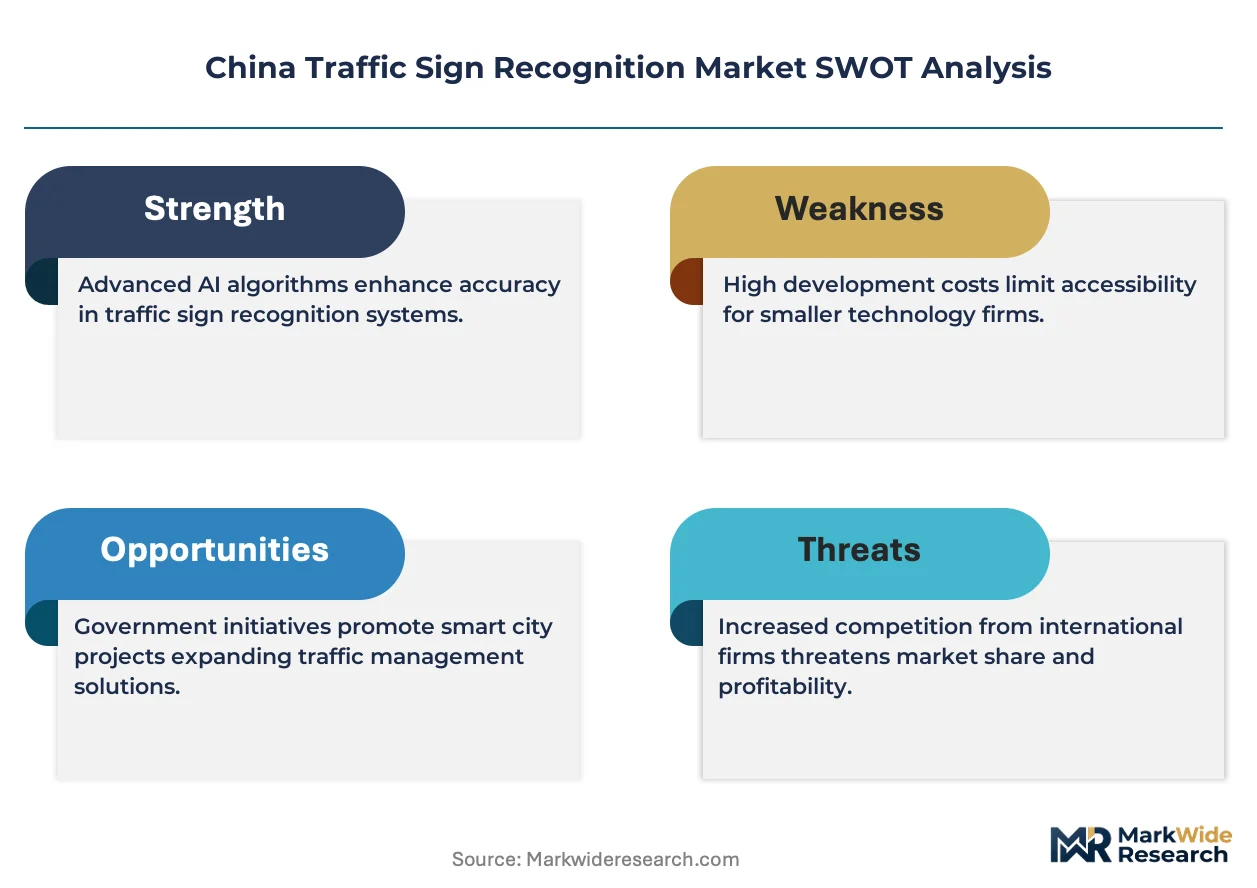
Strategic Opportunities
- Smart City Solutions expansion:Provincial procurement timelines in Zhejiang and Anhui are accelerating municipal integration of recognition data into traffic signal optimization systems.
- AI chip design convergence:In-house neural processing unit development is unifying perception and decision layers, reducing dependency on imported silicon.
- GB standard evolution:National Information Security Standardization Technical Committee draft specifications create first-mover advantage for compliant vendors ahead of mandatory adoption.
Industry Challenges
- Embedded systems talent scarcity:Shortage of engineers with combined expertise in automotive functional safety and deep learning model optimization constrains R&D velocity.
- Certification timeline compression:MIIT certification rules for over-the-air software updates require continuous validation cycles that extend product launch schedules.
- Legacy platform integration:Retrofitting recognition systems into existing ADAS architectures without full electrical/electronic redesign creates engineering complexity.
Report Scope
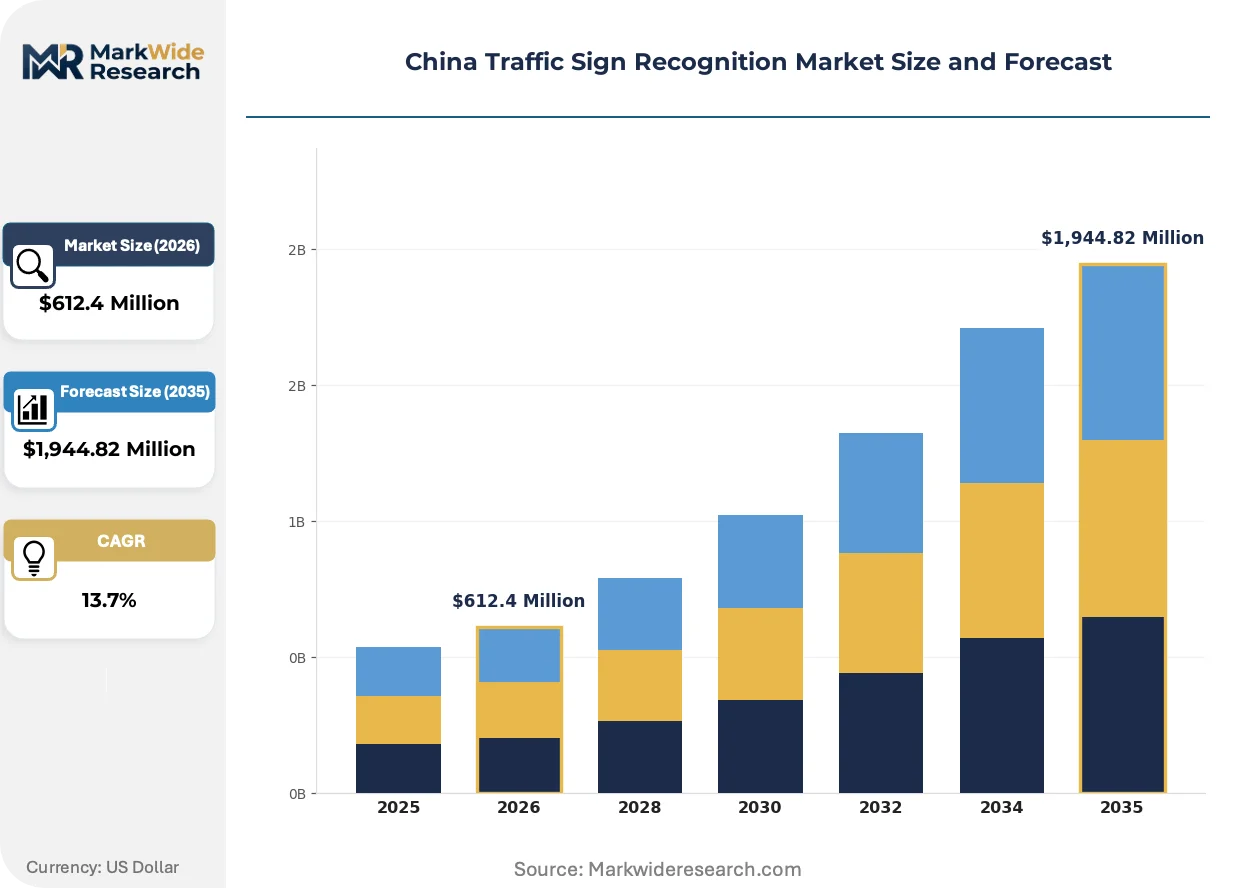
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Traffic Sign Recognition Market |
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,944.82 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Computer Vision, Deep Learning, Image Processing End User: Automotive OEMs, Tier-1 Suppliers, Traffic Management Authorities, Fleet Operators Application: Autonomous Vehicles, Driver Assistance Systems, Traffic Analytics, Smart City Solutions Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Edge |
| Companies Covered | Denso Corporation, Valeo SA, Huawei Technologies Co., Ltd., Autoliv Inc., ZF Friedrichshafen AG, Continental AG, Mobileye, Hella GmbH & Co KGaA, Robert Bosch GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Traffic Sign Recognition Market Strategic Shifts
Edge computing migration and multimodal sensor fusion are compressing latency requirements while GB standard drafts reshape product architecture roadmaps. Algorithm developers face pressure to demonstrate adverse-weather robustness ahead of regulatory deadlines.
Multimodal perception stacks are unifying camera, lidar, and radar inputs into single neural network architectures. Tier-1 suppliers serving Japanese-Chinese joint-venture OEMs are adopting these fused systems fastest to meet collision avoidance performance guarantees. This unifying architecture is compressing the traditional separation between hardware sensor providers and software algorithm vendors into integrated perception platforms.
MIIT mandates for intelligent connected vehicles now require documented software update protocols and traceable validation datasets. The industrial consequence is mandatory investment in cybersecurity management systems and data logging infrastructure. Automotive OEMs in the Yangtze River Delta cluster are responding by establishing captive software validation centers to maintain certification continuity.
Buyer concentration among Tier-1 suppliers has compressed procurement cycles from annual to quarterly review schedules. Direct OEM engagement with algorithm developers is displacing traditional semiconductor distributor channels in advanced driver assistance platform sourcing. This pattern is most visible in Shanghai and surrounding Jiangsu province, where Continental AG and Denso Corporation maintain deep manufacturing relationships.
China Traffic Sign Recognition Market Segmentation
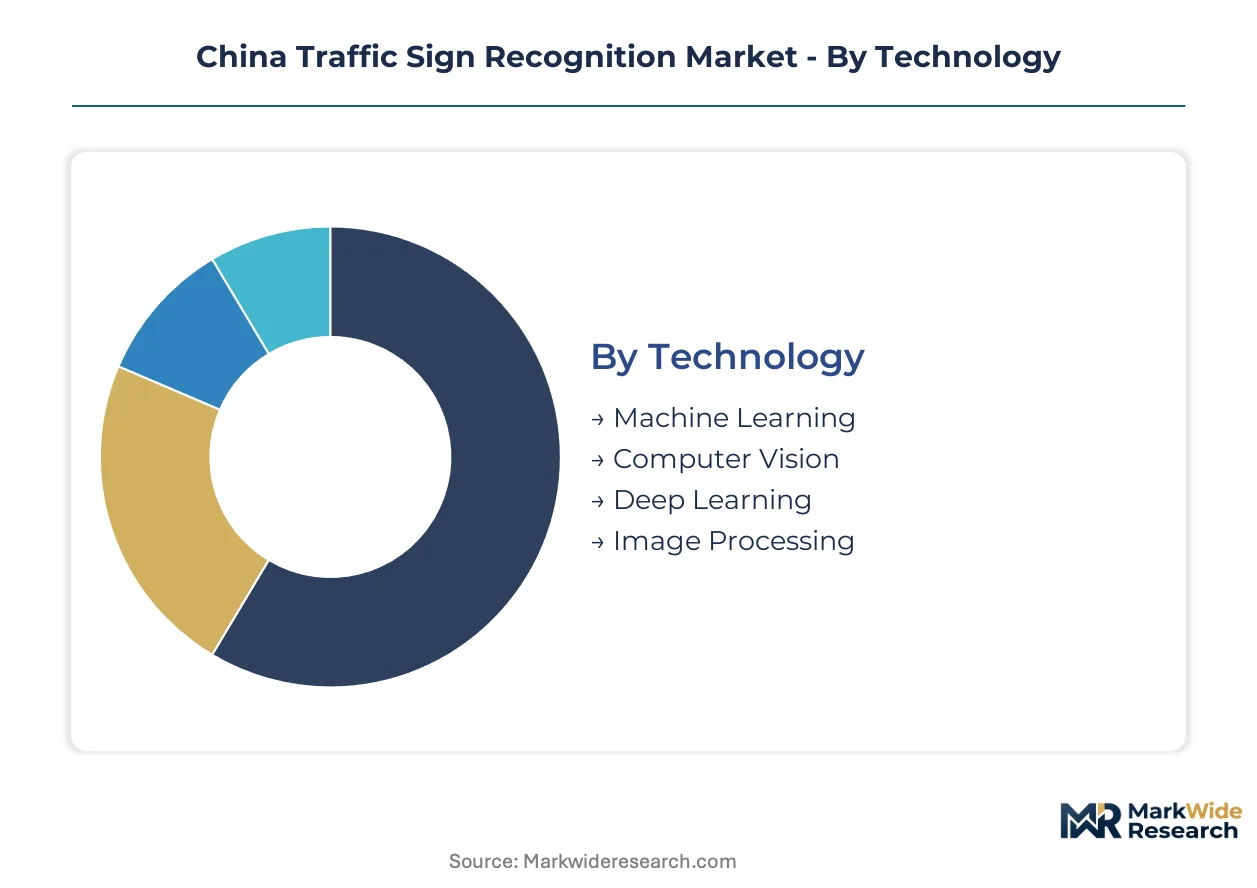
Recognition system architectures fragment across four interdependent dimensions. Technology choices determine latency budgets and weather robustness. End-user concentration in Yangtze River Delta manufacturing clusters shapes procurement scale and certification requirements.
Technology:
Deep learning architectures concentrate engineering talent and capital investment in Jiangsu province development centers, compressing legacy algorithm timelines.
- Deep Learning:Convolutional neural networks process frames exceeding 30 fps with sub-100-millisecond latency. MIIT software validation mandates for intelligent connected vehicles are tightening documentation requirements for these architectures in Shanghai-based OEM validation centers.
- Computer Vision:Conventional feature-extraction methods persist in cost-sensitive fleet retrofit applications. Demand concentrates among traffic management authorities in Zhejiang province seeking proven compliance without neural network retraining overhead.
- Machine Learning:Support vector machine and random forest classifiers serve legacy platform integration where computational budgets constrain neural deployment.
- Image Processing:Preprocessing pipelines for noise reduction and contrast enhancement underpin all recognition stacks regardless of downstream classifier choice.
Today's leader: Deep Learning. Tomorrow's challenger: Computer Vision in cost-optimized municipal deployments.
End User:
Procurement authority distributes unevenly, with Tier-1 suppliers capturing volume through captive relationships while traffic authorities expand fastest.
- Tier-1 Suppliers:These integrators consolidate camera modules, processing units, and validation datasets into ADAS platform subsystems. Quarterly procurement reviews have replaced annual cycles in Yangtze River Delta manufacturing clusters as OEMs accelerate platform refresh timelines.
- Traffic Management Authorities:Municipal governments in Anhui and Zhejiang provinces are integrating recognition data into centralized signal optimization systems. Provincial procurement timelines are accelerating faster than automotive contract cycles.
- Automotive OEMs:Direct engagement with algorithm developers is displacing traditional semiconductor distributor channels for advanced driver assistance platforms.
- Fleet Operators:Commercial vehicle managers deploy retrofit recognition systems for regulatory compliance and insurance cost reduction.
Volume concentrates with Tier-1 Suppliers. Margins expand fastest with Traffic Management Authorities.
Application:
Functional requirements diverge sharply between collision-avoidance latency budgets and analytics aggregation tolerances.
- Driver Assistance Systems:Real-time sign classification feeds speed-limit adaptation and lane-keeping assistance. MIIT mandates for fuel-economy compliance in new energy vehicles are pivoting procurement priorities toward these integrated platforms.
- Smart City Solutions:Aggregated recognition data optimizes signal timing and incident response. Deployment is expanding fastest as municipal governments in Shanghai and surrounding provinces integrate perception layers into traffic management platforms.
- Autonomous Vehicles:L4/L5 platforms demand redundant perception stacks with fail-operational guarantees.
- Traffic Analytics:Post-processed sign inventory and compliance monitoring serve urban planning and enforcement optimization.
Regulatory pull favors Driver Assistance Systems. Infrastructure investment elevates Smart City Solutions.
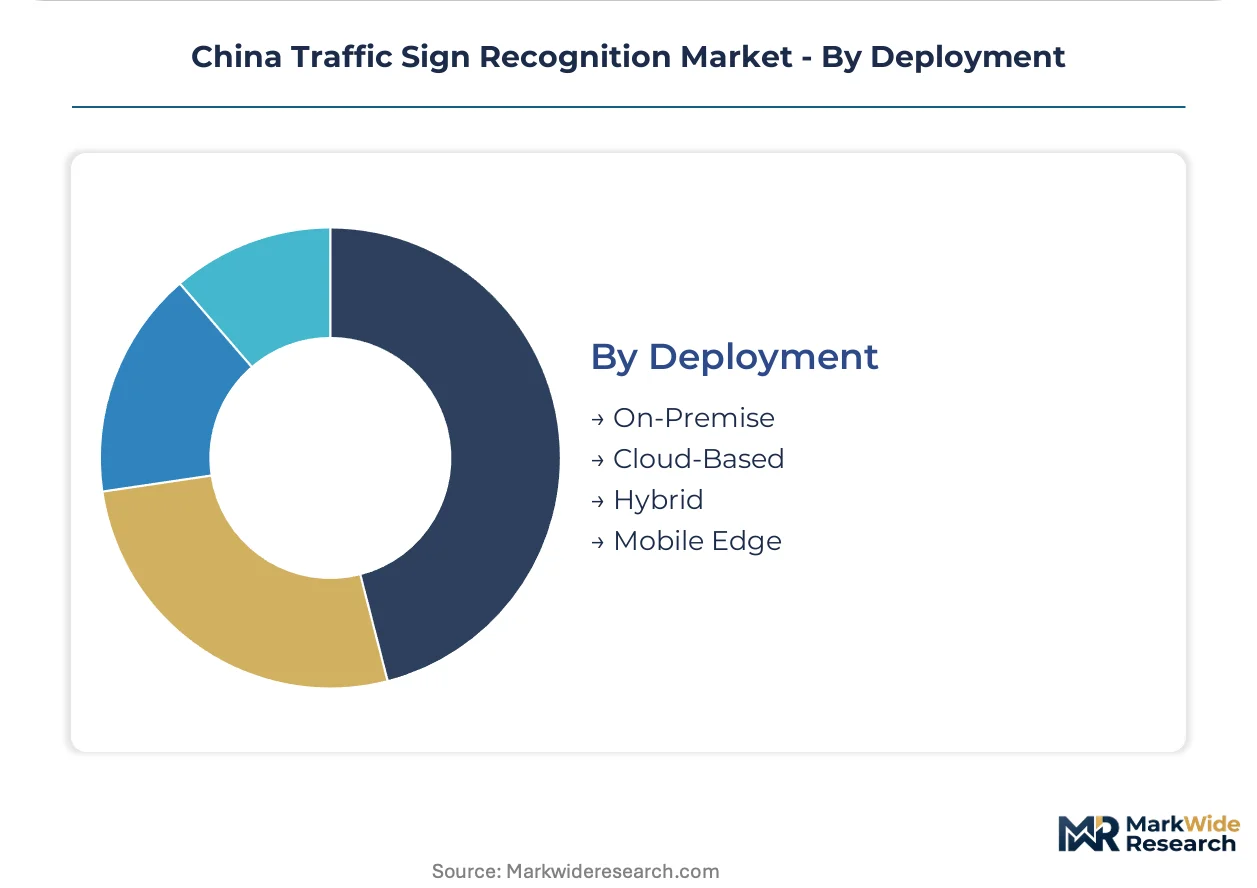
Deployment:
Edge migration is compressing cloud dependency as latency requirements tighten and data security regulations harden.
- Mobile Edge:In-vehicle neural processing units unify perception and decision layers, reducing dependency on imported silicon and satisfying SAMR data security regulations on cross-border visual perception handling.
- Hybrid:Split architectures process time-critical classification locally while uploading aggregated analytics to municipal cloud platforms. This configuration dominates smart city procurement in Jiangsu and Zhejiang provinces balancing latency against centralized optimization.
- On-Premise:Dedicated server installations serve traffic management centers with high-throughput corridor monitoring requirements.
- Cloud-Based:Centralized processing persists in pilot deployments and low-budget analytics applications where latency tolerance permits.
Architecture is settling on Hybrid for smart city scale. Mobile Edge is gaining share fastest in automotive platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Traffic sign recognition technology first achieved commercial scale in Germany during the early 2000s through Bosch and Continental ADAS programs. Chinese deployment accelerated after 2015 as MIIT mandates for intelligent connected vehicles created regulatory pull. Manufacturing gravity now concentrates in the Yangtze River Delta cluster where Tier-1 suppliers anchor production networks.
Yangtze River Delta
Shanghai-based OEM validation centers drive procurement of sub-100-millisecond latency systems for collision avoidance platforms. MIIT fuel-economy mandates for new energy vehicles tighten software documentation requirements for neural network architectures. Continental AG maintains deep manufacturing relationships across Jiangsu province while Huawei Technologies anchors AI chip design in the cluster.
Pearl River Delta
Shenzhen's electronics manufacturing base supplies CMOS image sensors and neural processing units to recognition system integrators. SAMR data security regulations impose strict handling protocols on visual perception data collected by foreign-owned joint ventures. Municipal governments in Guangdong province pilot smart city integration of traffic signal optimization with recognition data feeds.
Beijing-Tianjin-Hebei
Autonomous vehicle testing corridors in Beijing demand redundant perception stacks with fail-operational guarantees for L4/L5 platforms. The National Information Security Standardization Technical Committee drafts GB standard specifications for automotive visual perception data in the capital. State-owned automotive groups establish captive software validation centers to maintain MIIT certification continuity.
Sichuan-Chongqing
Western China manufacturing expansion targets cost-sensitive fleet retrofit applications with conventional feature-extraction methods. Provincial smart city procurement timelines in Chongqing accelerate municipal integration of recognition data into traffic management platforms. Local traffic management authorities prioritize proven compliance without neural network retraining overhead.
Shandong Peninsula
Heavy commercial vehicle production in Shandong province drives retrofit recognition system deployment for regulatory compliance and insurance cost reduction. GB standards for intelligent connected vehicles shape product design requirements for domestic truck OEMs. Industrial clusters around Qingdao host emerging Tier-2 suppliers serving fleet operator procurement cycles.
China Traffic Sign Recognition Market Competitive Environment
Premium-margin players sit above commodity-margin players across validation depth and software certification capabilities. The vendor base stratifies into three tiers: multinational Tier-1 integrators with captive OEM relationships, Chinese technology conglomerates with in-house silicon capabilities, and specialized sensor module suppliers serving retrofit markets. Two dominant competitive moves define current positioning: establishment of captive software validation centers to satisfy MIIT certification timelines, and backward integration into neural processing unit design to reduce imported silicon dependency.
Among multinational Tier-1 integrators, Continental AG and Denso Corporation exemplify archetypes with deep manufacturing scale in Jiangsu province and long-standing relationships with joint-venture OEMs. Huawei Technologies Co., Ltd. occupies a distinct position through in-house AI chip design and 5G-V2X integration capabilities. These three entities represent the primary competitive anchors shaping procurement patterns in the Yangtze River Delta cluster.
| Leading Market Players |
|---|
| Denso Corporation |
| Valeo SA |
| Huawei Technologies Co., Ltd. |
| Autoliv Inc. |
| ZF Friedrichshafen AG |
| Continental AG |
| Mobileye |
| Hella GmbH & Co KGaA |
| Robert Bosch GmbH |
| Others |
Value Chain & Pricing Dynamics
Quarterly procurement reviews by Yangtze River Delta OEMs are compressing supplier margins and forcing recognition system vendors toward modular architectures that accommodate rapid platform refreshes without full redesign cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by MIIT certification depth and neural processing performance. Premium tiers command sustained margins through documented software validation datasets and cybersecurity management system investments, while economy tiers face intensifying cost compression from CMOS image sensor price volatility. Tier-1 suppliers serving Japanese-Chinese joint-venture OEMs exhibit lowest price sensitivity due to captive relationship structures, whereas fleet retrofit operators in Shandong province drive hardest bargain negotiations.
Supply Chain Analysis
Embedded systems engineering talent scarcity in Jiangsu and Zhejiang provinces constrains R&D velocity and inflates compensation costs for Tier-1 development centers. Manufacturing gravity anchors in China for neural processing unit packaging and final system integration, with South Korea and Taiwan supplying advanced CMOS image sensors and automotive-grade GPU silicon. Single-source vulnerability around imported neural processing units creates exposure to SAMR data security regulation enforcement, while distribution runs through direct OEM engagement displacing traditional semiconductor distributor channels in Shanghai-based procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on backward integration into AI chip design and the premium-tier shift toward fail-operational perception stacks for autonomous vehicle platforms.
For Market Incumbents: Deepen captive software validation center investments in the Yangtze River Delta to compress MIIT certification timelines and defend against emerging Chinese technology conglomerants with in-house silicon capabilities. Anchor manufacturing scale through long-term foundry agreements for neural processing units, reducing exposure to imported GPU pricing volatility. Prioritize GB standard compliance pre-positioning ahead of mandatory National Information Security Standardization Technical Committee specification adoption. For New Entrants and Emerging Players: Municipal traffic management authorities in Anhui and Chongqing represent the most penetrable buyer archetype, with procurement timelines accelerating faster than automotive contract cycles and conventional feature-extraction methods still acceptable for proven compliance without neural retraining overhead. Target cost-optimized hybrid deployment architectures balancing edge latency against centralized analytics aggregation. Pursue provincial smart city integration partnerships as the primary go-to-market pathway, bypassing Tier-1 supplier consolidation barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized sensor module suppliers possessing GB standard pre-certification and established relationships with state-owned automotive groups in Beijing-Tianjin-Hebei. Long-term viability favors vendors with unified perception-decision architectures that reduce imported silicon dependency across the projection horizon. Monitor MIIT draft specification publication timelines as the critical inflection signal for compliance-driven procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI Chip Design Convergence | In-house neural processing unit development reduces dependency on imported silicon and satisfies SAMR data handling requirements. |
| Captive Software Validation Centers | Yangtze River Delta OEMs establish dedicated facilities to maintain MIIT certification continuity for over-the-air updates. |
| Smart City Integration Partnerships | Municipal governments in Zhejiang and Anhui accelerate procurement of hybrid edge-cloud recognition systems for signal optimization. |
| Multimodal Sensor Fusion Platforms | Tier-1 suppliers unify camera, lidar, and radar inputs to meet collision avoidance performance guarantees for joint-venture OEMs. |
| GB Standard Pre-Compliance Positioning | First-mover investment in National Information Security Standardization Technical Committee draft specifications ahead of mandatory adoption. |
Study Parameters
Direct dialogue with Tier-1 supplier procurement officers, OEM platform engineers, municipal traffic management authorities, and embedded systems R&D directors grounded qualitative assessment in operational reality. Secondary validation drew from MIIT regulatory filings, GB standard draft publications, SAMR data security guidance documents, and vehicle production databases. Bottom-up segmentation modeling triangulated against top-down market sizing across technology, end-user, application, and deployment dimensions.
Segment-level value outputs across deep learning, computer vision, machine learning, and image processing architectures fed into platform aggregation models. Technology adoption curves, MIIT mandate implementation timelines, and provincial smart city procurement schedules served as primary forecast inputs. CAGRs derived from elasticity-adjusted penetration rates across driver assistance systems, smart city solutions, autonomous vehicles, and traffic analytics applications.
Underlying measurement precision varies by segment; Tier-1 supplier and automotive OEM categories carry tighter precision than emerging traffic management authority deployments given data availability asymmetry. Forecasts reflect documented assumptions regarding GB standard adoption velocity and 5G-V2X infrastructure rollout pace. Material deviation in MIIT certification timeline compression or neural processing unit import restriction enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automatic High Beam Control Market
Automotive Safety and Security Systems
Side Guard Door Beam Market
Automotive Safety and Security Systems
Europe Automotive Night Vision System Market
Automotive Safety and Security Systems
Biometric Vehicle Access System Market
Automotive Safety and Security Systems
Germany Airbag Systems Market
Automotive Safety and Security Systems
Automotive Rear View Mirror Market
Automotive Safety and Security Systems
Anti-Fog Lights Market
Automotive Safety and Security Systems
Motorcycle E-Call Market
Automotive Safety and Security Systems
Global Car Radar Detectors Market
Automotive Safety and Security Systems
Seat Belt Pretensioner and Load Limiter Market
Automotive Safety and Security Systems
China Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Vehicle Anti-Theft System Market
Automotive Safety and Security Systems
Automotive Door Guards Market
Automotive Safety and Security Systems
Automotive HD/Imaging Radar Market
Automotive Safety and Security Systems
Automotive Anti-Pinch Power Window System Market
Automotive Safety and Security Systems
United States Automotive Collision Avoidance Systems Market