
 Latin America Airbag Systems Market | 2026-2036
Latin America Airbag Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Airbag Systems Market Foresight
Light commercial vehicle fleets are repositioning safety specifications upward across Latin America. Autoliv Inc dominates manufacturing scale for curtain airbag modules serving Brazilian OEMs. ZF Friedrichshafen AG leverages its TRW heritage in electronic crash sensor architectures. Denso Corporation anchors supply relationships with Japanese-brand vehicle assemblers operating in Mexico.
Latin America airbag systems comprise inflatable restraint modules, gas generators, and electronic control units designed to deploy within milliseconds of collision detection, typically using sodium azide or compressed gas propellants to cushion occupants during frontal, side, or rollover impacts. Frontal airbags sustain the largest installed base across the region, though side and curtain variants are capturing faster growth as multi-chamber configurations penetrate mid-market vehicle platforms. Sensor-based technology leads innovation investment, while mechanical systems retain residual aftermarket share in older vehicle parc retrofit applications.
CONTRAN regulations in Brazil mandate minimum airbag fitment standards for new vehicle homologation, while Mexico's NOM standards align with U.S. FMVSS 208 provisions for export-bound production. Argentina's CNRT enforces comparable occupant protection requirements that shape Tier-1 supplier product portfolios. Stakeholders must monitor evolving side-impact test protocols and the gradual extension of knee airbag requirements beyond premium vehicle segments.
Market Dynamics
Brazil's CONTRAN mandates are compressing deployment timelines for multi-chamber airbag configurations, forcing Tier-1 suppliers to reconfigure production lines around side-impact and knee-protection modules faster than original equipment refresh cycles.
Growth Catalysts
- CONTRAN Phase-In Requirements:Brazil's traffic safety council mandates front and side airbag fitment for all new vehicle homologations, pulling demand from mid-range passenger vehicle platforms previously equipped with driver-only configurations.
- Export Corridor Concentration:Mexican vehicle assemblers supplying North American markets must comply with FMVSS 208 provisions, standardizing advanced airbag architectures across production lines serving cross-border OEM contracts.
- Sodium Azide Propellant Substitution:Compressed gas and hybrid inflator technologies are displacing traditional pyrotechnic systems, reducing particulate emissions during deployment and simplifying end-of-life vehicle disposal compliance.
Market Restraints
- Electronic Component Import Dependency:Crash sensor microcontrollers and accelerometer modules concentrate in Asian semiconductor foundries, exposing Latin American module assemblers to lead-time volatility and currency mismatch risks.
- Argentina's Foreign Exchange Controls:CNRT-mandated safety equipment imports face payment processing delays through the country's central bank, stretching working capital cycles for distributors serving Buenos Aires and Córdoba assembly plants.
- Residual Mechanical System Aftermarket:Older vehicle parc in Colombia and Peru retains spring-loaded mechanical trigger mechanisms, limiting addressable market expansion for electronic control unit retrofit kits.
Strategic Opportunities
- Chilean Fleet Renewal Programs:Santiago's urban congestion pricing schemes and commercial vehicle age limits are accelerating replacement demand for light trucks with curtain airbag specifications.
- Multi-Chamber Integration:Convergence of frontal, side, and roof-rail modules into single electronic control architectures creates white space for suppliers capable of unified sensor fusion software.
- ANVISA Medical Device Crossover:Brazil's health regulator oversight of occupant injury data is generating procurement specifications from ambulance and emergency vehicle converters for specialized restraint systems.
Industry Challenges
- Embedded Software Certification:ISO 26262 functional safety validation for airbag deployment algorithms requires specialized automotive software engineers scarce in São Paulo and Monterrey labor markets.
- Gas Generator Thermal Testing:Propellant stability validation under high-altitude Andean conditions demands extended climatic chamber protocols, compressing development schedules for suppliers without captive test facilities.
- Legacy Vehicle Electrical Architecture Compatibility:Retrofit module integration with 1990s-era wiring harnesses lacking controller area network bus capability forces costly custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Airbag Systems Market |
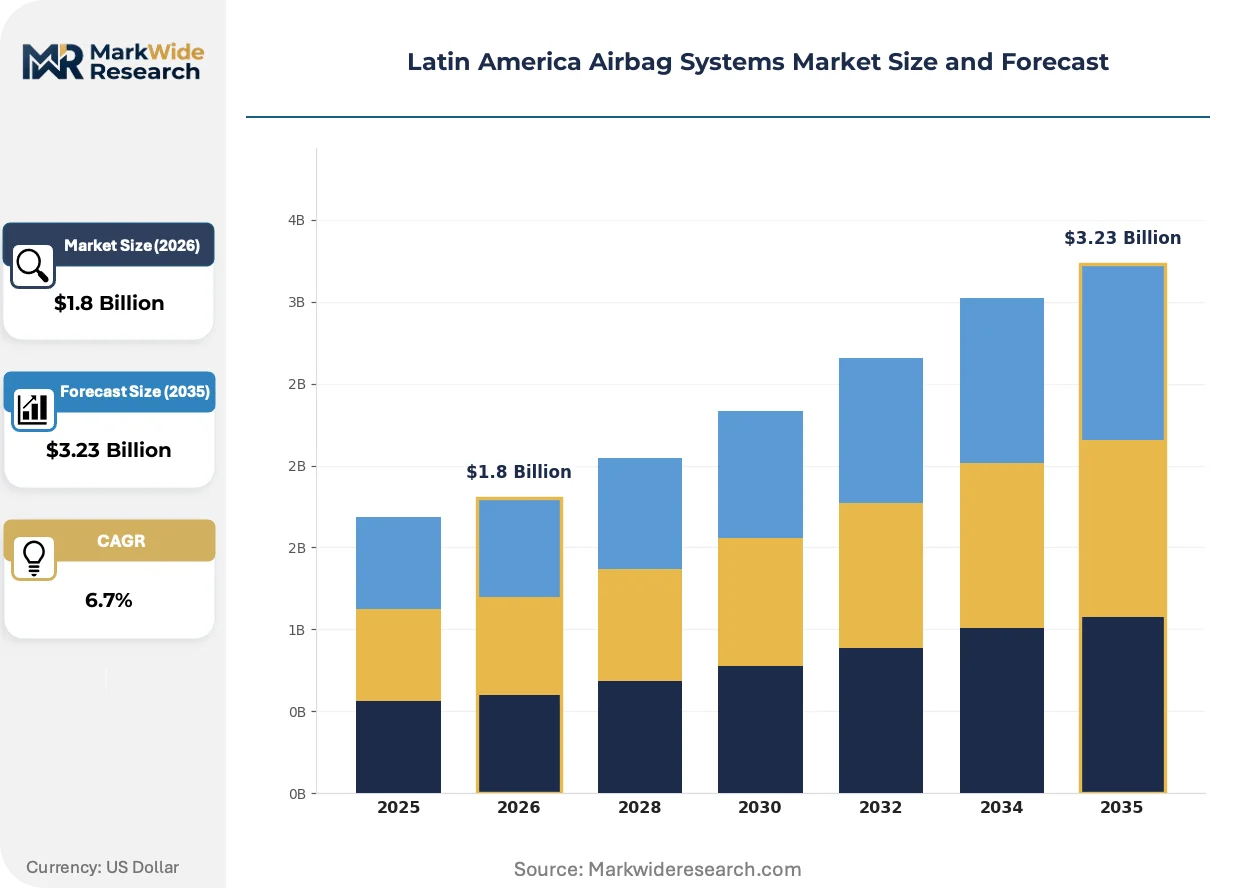
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frontal Airbags, Side Airbags, Knee Airbags, Curtain Airbags End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Mechanical, Electronic, Hybrid, Sensor-Based Installation Type: Factory Installed, Retrofit, Modular, Integrated |
| Companies Covered | Denso Corporation, Takata, ZF Friedrichshafen AG, Toshiba Corporation, Key Safety Systems, Hyundai Mobis Co Ltd, Continental AG, ZF TRW, Autoliv Inc, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Airbag Systems Market Shifts & Advancements
Sensor fusion architectures and compressed gas propellants are displacing legacy pyrotechnic systems, while regulatory test protocols expand beyond frontal impact to encompass oblique pole and far-side collision scenarios.
Advanced capacitive occupant classification systems are absorbing the detection workload previously handled by mechanical weight sensors in passenger seat applications. Mid-market Brazilian OEMs are adopting these modules to enable intelligent airbag suppression for child seats without adding wiring complexity. The technology is absorbing margin pressure from commodity inflator competition by shifting value toward software-defined restraint logic.
Argentina's CNRT has aligned side-impact test protocols with UNECE R95 standards, requiring door-mounted thorax protection in all new vehicle categories from 2026. This regulatory convergence is compressing supplier qualification timelines for curtain airbag modules previously certified only to Brazilian CONTRAN specifications. Tier-1 manufacturers serving Mercosur markets are consolidating regional product portfolios around dual-certified architectures.
Fleet procurement managers in Mexico's commercial vehicle sector are unbundling safety equipment specification from base chassis contracts, creating direct purchasing relationships with airbag module suppliers. This channel disintermediation is visible most acutely in Guanajuato's automotive cluster, where logistics fleet operators negotiate volume agreements for side-curtain retrofits independent of OEM dealer networks. The shift is fragmenting traditional aftermarket distribution through parts wholesalers.
Latin America Airbag Systems Market Segmentation
Airbag system procurement patterns diverge sharply across vehicle production channels in Latin America. OEM integration timelines, regulatory certification requirements, and aftermarket retrofit complexity create distinct demand profiles that suppliers must navigate simultaneously.
Product Type:
Standardization dominates frontal and side configurations while knee and curtain variants demand platform-specific engineering customization.
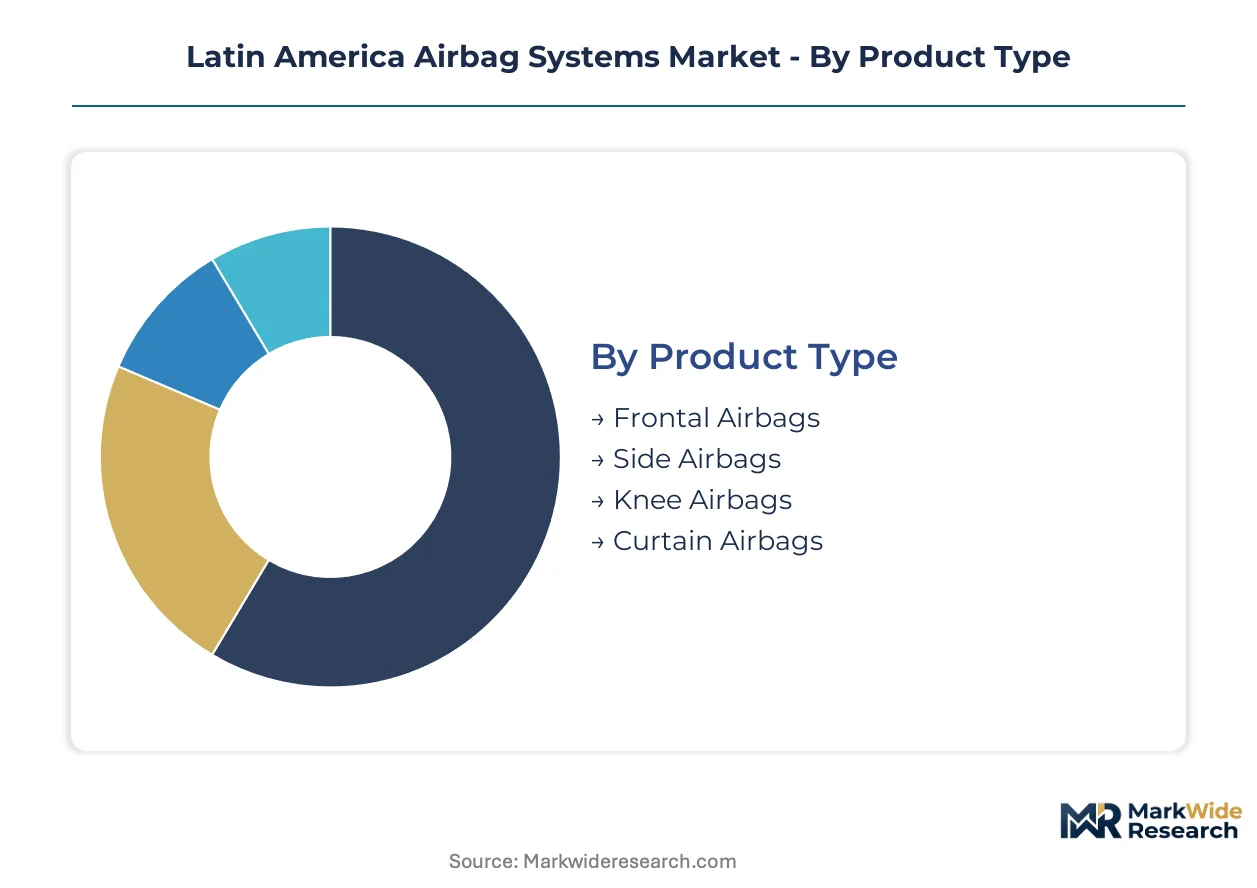
- Frontal Airbags:Dual-stage pyrotechnic inflators with tethers and vents constitute the baseline specification across Brazilian and Mexican assembly lines. CONTRAN mandates compress deployment into entry-level passenger vehicles previously omitting passenger-side modules.
- Curtain Airbags:Roof-rail mounted tubular designs with dual-chamber inflation profiles protect occupants during rollover sequences. Mexican export corridors to the United States accelerate fitment across light truck platforms serving commercial fleet operators.
- Side Airbags:Seat-mounted thorax protection modules with compressed gas generators.
- Knee Airbags:Lower dashboard-integrated restraint systems with specialized tether geometries.
Most installed capacity flows through Frontal Airbags. Expansion is steepest in Curtain Airbags.
End User:
Volume concentration sits with direct vehicle assembler contracts while margin capture shifts toward specialized Tier-1 module integrators.
- OEMs:Brand-holding manufacturers specify complete restraint system architectures across model platforms. Brazilian OEMs consolidate procurement around single-source electronic control unit suppliers capable of CONTRAN homologation support.
- Tier-1 Suppliers:Module integrators like Autoliv and ZF Friedrichshafen manage inflator-to-sensor subsystem marriage. These suppliers absorb design liability for deployment timing calibration while maintaining direct engineering relationships with semiconductor foundries.
- Vehicle Assemblers:Contract manufacturers in Mexico's Bajío region execute final module installation per OEM build specifications.
- Aftermarket Providers:Independent distributors serving Colombia and Peru's aging vehicle parc with mechanical trigger retrofits.
Procurement volume concentrates with OEMs. Tier-1 Suppliers capture the steepest margin expansion trajectory.
Technology:
Electronic architectures displace mechanical heritage systems while hybrid configurations bridge legacy fleet retrofit requirements.
- Electronic:Microcontroller-driven deployment algorithms process accelerometer and pressure sensor inputs within 15-30 milliseconds. Mexican assembly plants serving FMVSS 208 markets standardize these architectures across all export-bound production.
- Sensor-Based:Capacitive occupant classification and multi-axis crash detection fusion represent the leading investment category. Brazilian OEMs adopt these modules to enable intelligent suppression for child seats without wiring harness redesign.
- Hybrid:Combined pyrotechnic and compressed gas inflator systems.
- Mechanical:Spring-loaded ball-and-spring trigger mechanisms in residual aftermarket applications.
Production volume flows through Electronic systems. Sensor-Based configurations are climbing the fastest.
Installation Type:
Factory integration captures value chain margin while retrofit channels address regulatory compliance gaps in aging fleet segments.
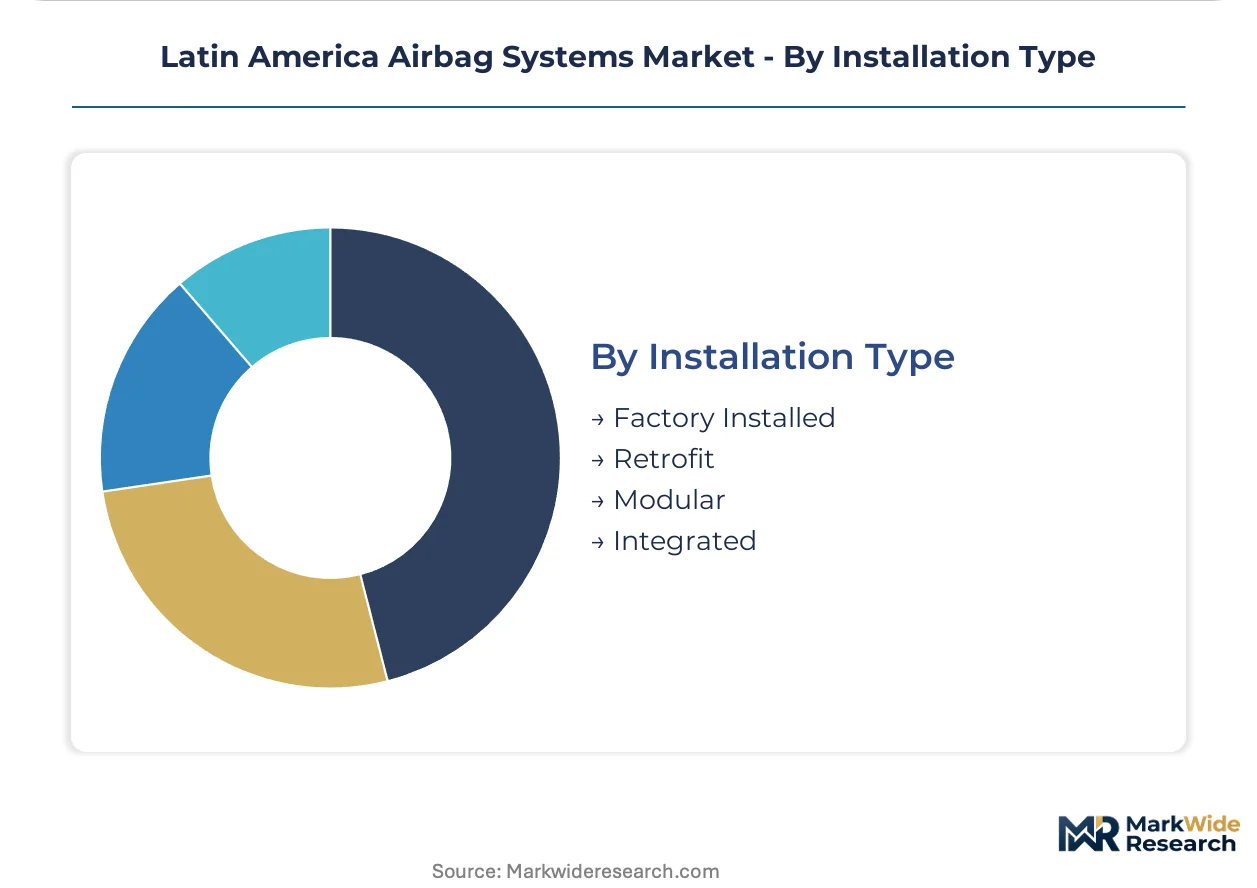
- Factory Installed:Modules married to steering column, dashboard, and pillar structures during body-in-white assembly. Brazilian OEMs execute this integration at Betim and São Bernardo do Campo plants with CONTRAN-certified quality protocols.
- Integrated:Single electronic control architecture governing multi-chamber deployment sequences. Argentine assembly plants adopt these configurations to satisfy CNRT alignment with UNECE R95 side-impact protocols.
- Modular:Swappable inflator and sensor subsystems for service replacement.
- Retrofit:Post-manufacture installation in commercial fleet vehicles through Santiago's congestion pricing compliance programs.
Assembly line capacity concentrates in Factory Installed systems. Integrated architectures gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between Brazil's stringent CONTRAN mandates and Mexico's export-oriented compliance standards has concentrated production capacity in jurisdictions where cost-of-compliance gaps favor large-scale module assembly. Vehicle assemblers migrate final integration toward Mexican export corridors while Brazilian plants absorb design liability for multi-chamber homologation.
Brazil
CONTRAN mandates for front and side airbags pull fitment into mid-range passenger vehicles at Betim and São Bernardo do Campo assembly complexes. ANVISA oversight of occupant injury data shapes procurement from specialized restraint system suppliers. São Paulo state's Tier-1 supplier cluster manages sodium azide substitution toward compressed gas inflators.
Mexico
FMVSS 208 alignment for North American export contracts standardizes advanced electronic architectures across Guanajuato and Nuevo León production lines. The Bajío automotive cluster concentrates curtain airbag module demand from logistics fleet operators negotiating direct volume agreements. Monterrey-based assemblers absorb currency mismatch risks from Asian semiconductor foundry dependencies.
Argentina
CNRT alignment with UNECE R95 side-impact protocols compresses supplier qualification timelines for door-mounted thorax protection modules. Foreign exchange controls through the central bank stretch working capital cycles for distributors serving Córdoba assembly plants. Buenos Aires procurement managers consolidate regional product portfolios around dual-certified architectures.
Chile
Santiago's urban congestion pricing schemes and commercial vehicle age limits accelerate replacement demand for light trucks with curtain airbag specifications. Fleet renewal programs create direct purchasing channels independent of traditional aftermarket wholesalers. The metropolitan region's emergency vehicle converters generate specialized restraint system demand under ANVISA-influenced procurement standards.
Colombia
Aging vehicle parc retains spring-loaded mechanical trigger mechanisms, limiting addressable market expansion for electronic control unit retrofit kits. Residual aftermarket demand concentrates in Bogotá and Medellín independent distributor networks. Import dependency for crash sensor microcontrollers exposes module assemblers to lead-time volatility from Asian semiconductor supply chains.
Latin America Airbag Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with module integrators absorbing design liability for deployment timing calibration while vehicle assemblers execute final installation per OEM build specifications. The supplier base concentrates around electronic control unit consolidation and multi-chamber integration capabilities. Two strategic archetypes dominate: scale-driven inflator manufacturers with captive gas generator capacity, and software-defined restraint specialists capturing margin through sensor fusion algorithms. Competitive moves center on strategic partnerships with semiconductor foundries and geographic expansion toward Mexican export corridors.
Within the integrated module tier, Autoliv Inc anchors manufacturing scale for curtain airbag configurations serving Brazilian OEMs, while ZF Friedrichshafen AG occupies a position leveraging TRW heritage in electronic crash sensor architectures. Denso Corporation exemplifies supply relationship anchoring with Japanese-brand vehicle assemblers operating in Mexico. These three entities represent distinct geographic and technological positioning archetypes without overlapping strategic footprints.
| Leading Market Players |
|---|
| Denso Corporation |
| Takata |
| ZF Friedrichshafen AG |
| Toshiba Corporation |
| Key Safety Systems |
| Hyundai Mobis Co Ltd |
| Continental AG |
| ZF TRW |
| Autoliv Inc |
| Others |
Supply & Pricing Matrix
Sodium azide commodity pricing fluctuations cascade through Latin American airbag module manufacturing, compressing margins on pyrotechnic inflators while compressed gas alternatives capture pricing premiums from OEMs seeking simplified end-of-life disposal compliance.
Pricing Analysis
Distributor markups in Brazil's aftermarket channel widen spreads between factory-direct OEM contracts and independent retrofit installations serving Colombia's aging vehicle parc. Three-tier pricing structure across premium sensor-fusion architectures, standard electronic control units, and economy mechanical trigger systems separates CONTRAN-certified modules from uncertified imports. Cost compression in entry-level frontal airbag configurations is intensifying because Brazilian OEMs consolidate procurement around single-source suppliers. Fleet operators in Mexico's Bajío cluster demonstrate lowest price sensitivity due to FMVSS 208 compliance requirements, while independent distributors in Peru face acute margin pressure from currency volatility.
Supply Chain Analysis
Workforce availability constraints in São Paulo's Tier-1 supplier cluster and Monterrey's assembly corridor compress production scalability for electronic control unit manufacturers. Manufacturing gravity centers on Brazil for CONTRAN homologation support, Mexico for North American export integration, and Argentina for Mercosur dual-certified architectures. Crash sensor microcontrollers and accelerometer modules draw from Asian semiconductor foundries, creating single-source vulnerability for Latin American module assemblers. Distribution runs through OEM direct contracts for factory-installed systems, with fragmented independent channels handling aftermarket retrofit demand in Andean markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America airbag systems function as a regulatory compounder where CONTRAN's phase-in mandates for side-impact protection create structural demand expansion regardless of vehicle sales cyclicality.
For Market Incumbents: Extend sensor fusion software capabilities toward unified multi-chamber architectures before Argentine CNRT alignment with UNECE R95 compresses qualification timelines for door-mounted thorax modules. Deepen captive gas generator capacity in São Paulo state to offset sodium azide substitution cost pressures. Defend against fleet procurement disintermediation in Guanajuato by embedding direct volume agreement templates within OEM platform contracts. For New Entrants and Emerging Players: Launch via direct purchasing relationships with Santiago logistics fleet operators bypassing traditional aftermarket wholesalers under urban congestion pricing compliance deadlines. Target Chilean emergency vehicle converters seeking ANVISA-influenced specialized restraint specifications as the most penetrable white space. Prioritize compressed gas inflator technology licensing to sidestep pyrotechnic propellant regulatory complexity. For Investors and Strategic Acquirers: Asymmetric upside sits with software-defined restraint specialists capturing margin through capacitive occupant classification algorithms rather than commodity inflator manufacturing. Long-term viability favors acquisition targets with ISO 26262 functional safety validation capabilities and existing CONTRAN homologation relationships. Monitor ANVISA procurement specification expansion into ambulance and emergency vehicle segments as inflection indicator for specialized system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Chamber Integration Investment | Unified electronic control architectures capture value from CONTRAN-mandated side-impact module expansion across Brazilian OEM platforms. |
| Compressed Gas Inflator Transition | Propellant substitution reduces particulate emissions and simplifies disposal compliance for Mexico's FMVSS 208 export production. |
| Sensor Fusion Software Development | Capacitive occupant classification modules shift value toward intelligent suppression logic for child seat detection. |
| Direct Fleet Procurement Channel | Bypassing OEM dealer networks in Guanajuato captures margin from logistics operators unbundling safety specifications. |
| Dual-Certified Architecture Consolidation | Mercosur portfolio unification around CONTRAN and UNECE R95 standards compresses supplier qualification overhead. |
Research Methodology
Bottom-up vehicle production modeling reconciled against top-down Tier-1 supplier shipment tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier-1 procurement directors, aftermarket distributors, and CONTRAN homologation specialists combined with secondary validation from vehicle registration databases, customs trade records, and regulatory filing repositories. Triangulation across production volume estimates and module content-per-vehicle assumptions anchors market sizing precision.
Input-output matrices mapped inflator manufacturing capacity against OEM integration timelines across the projection horizon. Segmentation dimensions modeled include product type, end-user channel, technology architecture, and installation configuration alongside vehicle class and regional regulatory cluster. CAGRs derive from regression analysis of historical fitment rates projected against mandate phase-in schedules and export corridor production forecasts. Industry-specific inputs incorporate semiconductor lead-time volatility and propellant technology substitution curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended foreign exchange control regimes or accelerated sodium azide regulatory bans. Projections reflect assumptions regarding CONTRAN enforcement consistency and FMVSS 208 alignment maintenance. Material deviation in semiconductor foundry allocation patterns or Mercosur regulatory harmonization timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Smart Motorcycle Helmet Market
Automotive Safety and Security Systems
Global Automotive Fog Lights Market
Automotive Safety and Security Systems
Automotive Crash Sensor Market
Automotive Safety and Security Systems
Global Electronic Brake Force Distribution System Market
Automotive Safety and Security Systems
Automotive Whiplash Protection Equipment Market
Automotive Safety and Security Systems
Automotive Knock Sensor Market
Automotive Safety and Security Systems
Biometric Driver Identification System Market
Automotive Safety and Security Systems
Global Motorcycle Advanced Driver Assistance System (ADAS) Market
Automotive Safety and Security Systems
Automotive Airbag Gas Generators Market
Automotive Safety and Security Systems
Global Automotive Curtain Airbags Market
Automotive Safety and Security Systems
Car Camera Cleaning Systems Market
Automotive Safety and Security Systems
Automotive Active Health Monitoring System Market
Automotive Safety and Security Systems
Global Highway Driving Assist Market
Automotive Safety and Security Systems
Asia-Pacific Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automatic Emergency Braking Market