
 Adventure Motorcycle Market | 2026-2036
Adventure Motorcycle Market Size, Share, and Industry Trends Forecast 2026-2036
Adventure Motorcycle Market Analysis
Subscription-based motorcycle leasing and asset-light ownership models is reconfiguring competitive dynamics by lowering entry barriers for younger riders. BMW leverages its vertically integrated drivetrain capabilities to sustain premium positioning across multi-terrain segments. Yamaha anchors its volume strategy through emerging-market distribution density. KTM specializes in high-displacement off-road architectures that dominate European endurance racing circuits.
An adventure motorcycle combines long-travel suspension, large fuel capacity, and protective bodywork to enable sustained travel across paved highways and unimproved surfaces, with engine displacements typically spanning 250cc to over 1000cc. The category serves dual commercial purposes: recreational expedition touring for consumers and fleet mobility for remote-area commercial operators. The 401cc-750cc engine displacement band captures the largest volume pool as manufacturers balance power-to-weight ratios against fuel economy mandates. Adventure Riding Modes technology commands disproportionate margin contribution because integrated terrain-response systems require proprietary software calibration. The Enduro product type occupies a mature niche with slower growth but durable aftermarket parts revenue.
Euro 5+ standards enforced by the European Commission and EPA tailpipe regulations in the United States are tightening particulate and NOx limits, compelling manufacturers to redesign combustion chambers and exhaust after-treatment systems. India's BIS certification requirements for two-wheelers add a parallel compliance layer for exporters targeting that production hub. Stakeholders must monitor how emissions rule convergence across Brussels, Washington, and New Delhi reshapes engine platform standardization decisions.
Market Dynamics
Engine displacement architecture is fracturing under divergent emissions mandates, forcing manufacturers to maintain parallel combustion platforms while electrification timelines remain uncertain across key production hubs.
Growth Catalysts
- Euro 5+ particulate limits:Exhaust after-treatment R&D is redirecting supplier investment toward ceramic catalytic substrates and precision fuel mapping, creating technical moats for early-compliant manufacturers.
- Intercity commuter displacement:Compact car owners in congested corridors are migrating to 400cc-750cc adventure motorcycles for fuel economy and lane-splitting flexibility.
- Remote-area fleet mobility:Mining and agricultural operators across the Australian Outback and Canadian North are standardizing on large-displacement enduro platforms for unpaved access routes.
Market Restraints
- Aluminum and rare-earth magnet volatility:Suspension component and electric motor supply chains face input cost swings that compress margin on mid-displacement models.
- Indian production concentration:Royal Enfield and domestic OEMs anchor volume manufacturing in Tamil Nadu and Rajasthan, creating geographic single-point vulnerability for export-dependent brands.
- Combustion-electric platform stranding risk:Manufacturers maintaining dual development tracks face R&D duplication without clarity on which architecture achieves regulatory longevity.
Strategic Opportunities
- Brazilian tariff arbitrage:ANVISA streamlined import procedures for two-wheeler subassemblies, opening assembly-joint-venture pathways for brands lacking Mercosur manufacturing presence.
- Adventure Riding Modes software licensing:Terrain-response calibration IP can generate recurring revenue through over-the-air updates and tiered feature unlocks.
- Subscription-based asset-light ownership:Younger riders in German and French urban centers are bypassing traditional financing for monthly access models that bundle insurance and maintenance.
Industry Challenges
- Embedded software validation timelines:Adventure Riding Modes integration with ABS and traction control requires ISO 26262 functional safety certification cycles that delay model launches by 8-14 months.
- Powertrain engineer scarcity:Combustion-electric hybrid architecture expertise concentrates at BMW and KTM, forcing competitors to poach talent or outsource critical calibration work.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adventure Motorcycle Market |
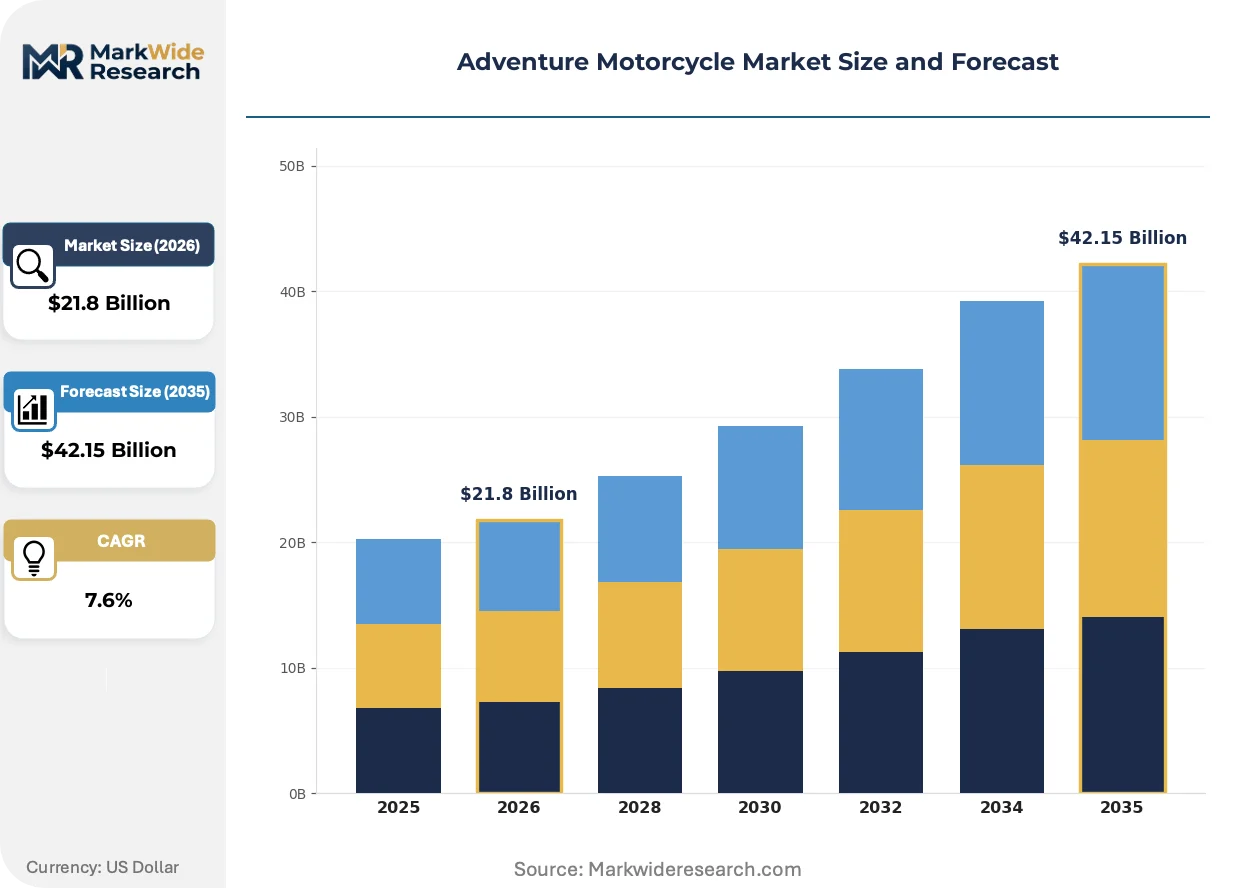
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $42.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dual-Sport, Touring, Enduro, Adventure Engine Displacement: 250cc-400cc, 401cc-750cc, 751cc-1000cc, 1000cc+ Technology: ABS, Traction Control, Adventure Riding Modes, Connectivity Distribution Channel: Online Retail, Dealerships, Specialty Stores, Direct Sales |
| Companies Covered | Yamaha, Triumph, BMW, Royal Enfield, Kawasaki, KTM, Ducati, CFMoto, Honda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adventure Motorcycle Market Emerging Trajectories
Connected-vehicle telemetry and predictive maintenance algorithms are redefining aftermarket revenue models, while regulatory fragmentation accelerates platform specialization rather than standardization.
Semi-active suspension with magnetorheological dampers is rendering obsolete fixed-rate coil-spring setups across the 750cc+ segment. BMW and Ducati fit these systems as standard on 2024 touring variants, compressing development timelines for mid-tier suppliers unable to license Bosch or Showa valve technology. The capability gap is forcing consolidation among independent suspension houses.
EPA tailpipe regulations in the United States are tightening evaporative emissions testing for motorcycles above 280cc, compelling manufacturers to redesign fuel tank venting and charcoal canister integration. California Air Resources Board enforcement patterns indicate 49-state homologation will no longer suffice for national distribution. The compliance burden falls heaviest on low-volume importers lacking captive testing facilities.
Direct-to-consumer configuration tools are displacing traditional dealership inventory models for premium adventure motorcycles. Buyers in the United Kingdom and Netherlands now specify luggage systems, lighting packages, and ergonomic adjustments online before factory allocation. This shift concentrates working capital risk with OEMs while reducing dealer floorplan financing exposure.
Adventure Motorcycle Market Segmentation

Adventure motorcycle segmentation reveals divergent service economics across product architectures. After-sales intensity varies sharply by displacement band and technology integration, reshaping how manufacturers structure dealer incentives and warranty reserves.
Product Type:
After-sales service intensity escalates with terrain specialization, as suspension rebuild intervals and protective component replacement schedules fragment maintenance revenue predictability across the four product architectures.
- Dual-Sport:Lightweight frames and long-travel suspension accommodate both highway commuting and moderate off-road use. Demand concentrates in Brazilian and Southeast Asian urban peripheries where unpaved arterial roads dominate last-mile connectivity, with ANVISA import streamlining accelerating assembly-joint-venture formation for this accessible price tier.
- Touring:Full fairings, heated grips, and integrated luggage systems prioritize multi-day highway comfort. German and French long-distance commuters are displacing compact cars for intercity corridors, drawn by fuel economy advantages and lane-splitting flexibility in congested metropolitan access routes.
- Enduro:Competition-derived chassis with minimal bodywork serve closed-course and trail riding. Australian Outback mining operators standardize on these platforms for unpaved site access, generating durable aftermarket parts revenue despite slower unit growth.
- Adventure:Combines touring amenities with genuine off-road capability through reinforced subframes and skid plates. This architecture captures the largest volume pool as manufacturers balance power-to-weight ratios against tightening emissions mandates across Euro 5+ jurisdictions.
Touring holds the largest share; momentum sits with Adventure as commuter displacement accelerates.
Engine Displacement:
Cost tier stratification determines regulatory exposure, with smaller displacement bands facing divergent homologation burdens across EPA, Euro 5+, and BIS certification regimes.
- 250cc-400cc:Single-cylinder architectures dominate emerging market entry segments. Indian production anchors volume for domestic consumption and African export markets, though BIS compliance layers add parallel certification overhead for foreign brands sourcing from Tamil Nadu and Rajasthan facilities.
- 401cc-750cc:Parallel-twin and inline-triple configurations balance fuel economy with highway passing power. This band captures the steepest expansion trajectory as compact car owners in congested European and North American corridors migrate to mid-displacement motorcycles for daily intercity commuting.
- 751cc-1000cc:Larger parallel-twins and V-twins serve experienced riders seeking continent-crossing range. EPA evaporative emissions testing tightening above 280cc forces fuel tank venting redesigns that compress margin for low-volume importers lacking captive testing infrastructure.
- 1000cc+:Premium inline-fours and V-twins with semi-active suspension and comprehensive electronics packages. BMW and Ducati dominate this tier through magnetorheological damper integration, creating capability gaps for mid-tier suppliers unable to license Bosch or Showa valve technology.
401cc-750cc holds the largest share; 250cc-400cc is gaining share fastest in price-sensitive emerging markets.
Technology:
Margin concentration tracks software integration depth, with proprietary calibration IP generating recurring revenue potential through over-the-air update architectures.
- ABS:Regulatory-mandated across major markets with variant-specific calibration requirements. Euro 5+ enforcement patterns indicate 49-state US homologation no longer suffices for national distribution, burdening low-volume importers with redundant certification cycles.
- Traction Control:Wheel-slip mitigation through throttle intervention and ignition retard. ISO 26262 functional safety certification delays model launches by 8-14 months when integrated with terrain-response systems, compressing competitive windows for late entrants.
- Adventure Riding Modes:Integrated terrain-response calibration combining throttle mapping, suspension damping, and ABS thresholds. This technology commands disproportionate margin contribution and enables tiered feature unlocks through subscription licensing models in German and French urban centers.
- Connectivity:Telematics integration for predictive maintenance and stolen-vehicle recovery. Direct-to-consumer configuration tools in the United Kingdom and Netherlands now bundle connectivity packages with factory-allocated builds, concentrating working capital risk with OEMs.
ABS holds the largest share; Adventure Riding Modes is climbing the fastest as software differentiation intensifies.
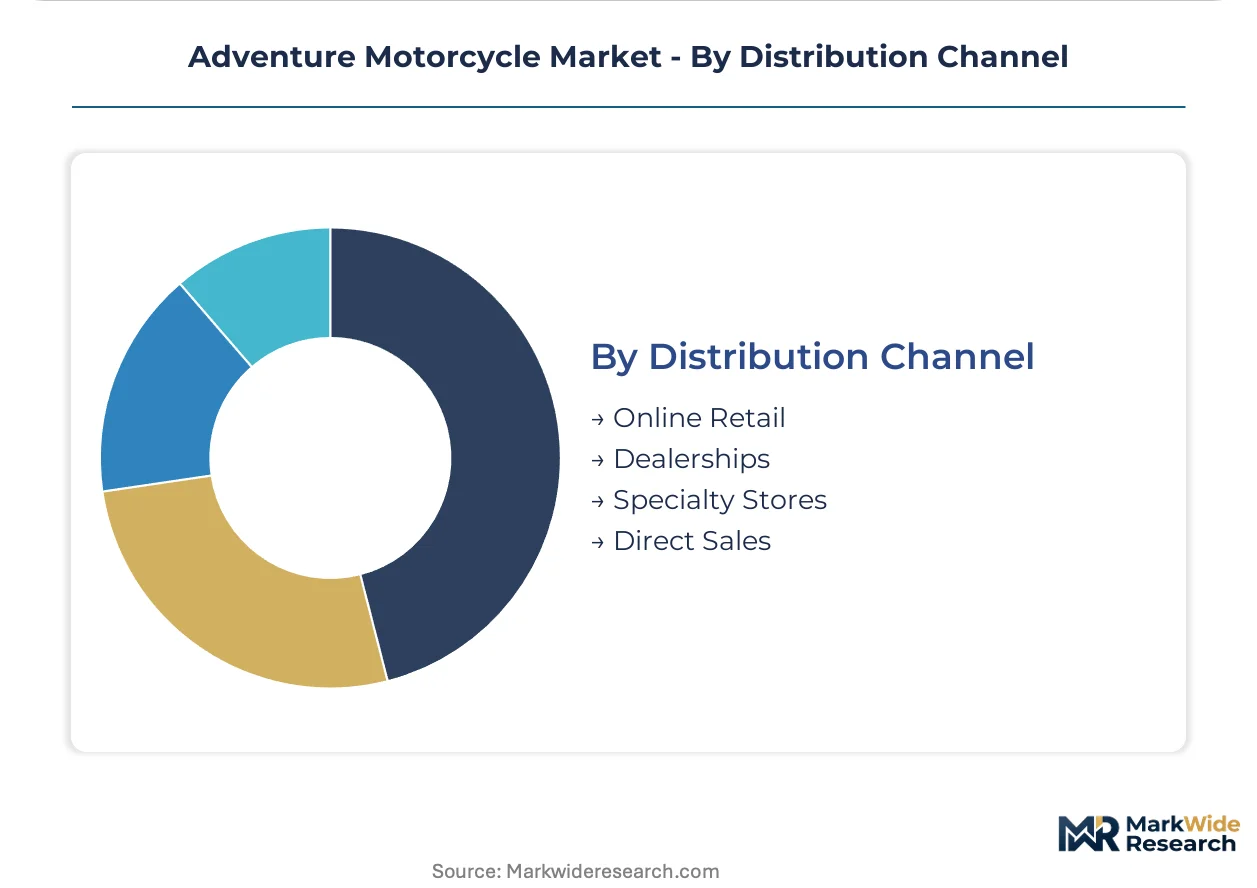
Distribution Channel:
Customer type fragmentation separates recreational purchasers seeking tactile evaluation from fleet operators prioritizing specification efficiency and volume pricing.
- Online Retail:Third-party platforms aggregating inventory across multiple brands and geographies. Brazilian tariff arbitrage through ANVISA-streamlined subassembly imports enables direct-to-consumer fulfillment for brands lacking Mercosur manufacturing presence.
- Dealerships:Traditional floorplan financing models with physical inventory exposure. Working capital risk is shifting toward OEMs as direct-to-consumer configuration tools in the United Kingdom and Netherlands reduce dealer inventory carrying requirements.
- Specialty Stores:Focused off-road and touring specialists with technical service depth. Australian Outback and Canadian North mining fleet operators rely on these channels for field-service capability in remote operating environments.
- Direct Sales:Factory-owned channels with configuration-to-delivery workflows. This model concentrates margin capture with OEMs while enabling subscription-based asset-light ownership bundles targeting younger riders in German and French metropolitan areas.
Dealerships hold the largest share; momentum sits with Direct Sales as configuration tools displace traditional inventory models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Long-distance commuters and touring riders concentrate demand in Germany and France, while Indian production hubs supply volume for emerging market entry segments. Regulatory divergence across EPA, Euro 5+, and BIS certification regimes fragments engine platform standardization. Industrial clusters in Tamil Nadu and Rajasthan anchor export manufacturing for brands targeting African and Southeast Asian markets.
United States
Intercity commuters in congested coastal corridors displace compact cars with mid-displacement adventure motorcycles for lane-splitting flexibility. EPA evaporative emissions testing above 280cc forces fuel tank venting redesigns that burden low-volume importers. California's Air Resources Board enforcement patterns now drive 50-state homologation requirements rather than 49-state compliance.
Germany
Urban professionals in Berlin and Munich adopt subscription-based asset-light ownership models bundling insurance and maintenance. KBA vehicle certification mandates integrate ISO 26262 functional safety standards for Adventure Riding Modes technology. Bavaria's manufacturing corridor hosts vertically integrated drivetrain specialists serving premium multi-terrain segments.
India
Domestic brands anchor volume production for 250cc-400cc entry segments serving domestic and African export markets. BIS two-wheeler certification adds parallel compliance overhead for foreign OEMs sourcing from Tamil Nadu facilities. Rajasthan's industrial belt concentrates forging and casting suppliers supporting Royal Enfield's vertically integrated supply chain.
Brazil
ANVISA streamlined import procedures for two-wheeler subassemblies enable assembly-joint-venture formation for brands lacking Mercosur manufacturing presence. São Paulo's urban periphery generates dual-sport demand where unpaved arterial roads dominate last-mile connectivity. Minas Gerais hosts emerging distribution hubs serving the southeastern commuter corridor.
Australia
Mining operators across the Outback standardize on large-displacement enduro platforms for unpaved site access routes. State-level vehicle safety regulations vary in ADR compliance interpretation across Queensland and Western Australia. Perth and Brisbane specialty stores concentrate field-service capability for remote-area fleet maintenance contracts.
Adventure Motorcycle Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered price bands defined by software integration depth and displacement architecture. Market structure concentrates margin capture among vertically integrated drivetrain specialists and emerging-market volume producers. Three archetypes dominate: premium multi-terrain integrators, emerging-market scale manufacturers, and off-road racing-derived specialists. Competitive moves center on Adventure Riding Modes software licensing and direct-to-consumer configuration tools displacing traditional dealership inventory models.
Within the premium multi-terrain tier, BMW and Ducati exemplify vertically integrated positioning through magnetorheological damper integration and proprietary terrain-response calibration. Yamaha anchors emerging-market volume strategy through distribution density in Southeast Asian and Latin American corridors. KTM occupies the off-road racing-derived specialist archetype, with Austrian engineering heritage informing high-displacement endurance platform development.
| Leading Market Players |
|---|
| Yamaha |
| Triumph |
| BMW |
| Royal Enfield |
| Kawasaki |
| KTM |
| Ducati |
| CFMoto |
| Honda |
| Others |
Supply Flow & Price Mechanics
Tamil Nadu's production clusters anchor global volume for 250cc-400cc entry segments, concentrating forging and casting capacity that shapes pricing power across mid-displacement tiers. Rajasthan's supplier belt feeds Royal Enfield's captive supply chain, creating cost advantages that ripple through export markets and compress margin room for non-integrated competitors.
Pricing Analysis
Aluminum LME-linked contracts with quarterly indexation dominate suspension component procurement, passing commodity volatility through to OEM cost structures. Three-tier pricing structure across premium, standard, and economy levels separates magnetorheological damper-equipped flagships from fixed-rate coil-spring mid-tiers and basic dual-sport entry models. Cost compression in the 401cc-750cc band is intensifying because BIS certification overhead layers onto Euro 5+ compliance spending for exporters sourcing from Indian facilities. Fleet operators across Australian mining corridors exhibit lowest price sensitivity due to uptime guarantees, while Southeast Asian urban commuters drive hardest bargain on sticker price.
Supply Chain Analysis
Bosch and Showa valve technology licensing concentrates among premium tier suppliers, with mid-tier suspension houses facing consolidation pressure from capability gaps. Magnetorheological damper production draws from German and Japanese precision manufacturing clusters, while ceramic catalytic substrate sourcing rests on South Korean and German ceramics specialists. Single-source vulnerability runs through rare-earth magnet supply for electric motor development tracks. Distribution runs through direct-to-consumer configuration tools in the United Kingdom and Netherlands alongside traditional dealership floorplan networks.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adventure motorcycle demand tracks commuter vehicle replacement cycles, with compact car owner migration to two-wheelers accelerating as urban congestion intensifies across European and North American corridors.
For Market Incumbents: Insulate margin position through backward integration into magnetorheological damper production and captive software calibration IP for Adventure Riding Modes terrain-response systems. Threat from subscription-based asset-light ownership models demands counter-positioning via bundled after-sales service contracts that lock in recurring revenue streams. For New Entrants and Emerging Players: Build out assembly-joint-venture presence in Brazil leveraging ANVISA-streamlined subassembly import pathways to bypass Mercosur tariff barriers. White-space sits with 250cc-400cc dual-sport segments serving Southeast Asian urban peripheries where unpaved arterial roads dominate last-mile connectivity. Go-to-market angle should emphasize field-service capability partnerships with Australian Outback mining fleet operators. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming two-wheeler divisions lacking scale in software-defined vehicle architectures. Long-term viability favors vertically integrated drivetrain specialists with proprietary terrain-response calibration IP and emerging-market distribution density. Signal to watch is EPA evaporative emissions enforcement patterns above 280cc that would strand 49-state homologation strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Adventure Riding Modes Software Licensing | Tiered feature unlocks through over-the-air updates generate recurring revenue from German and French urban subscribers. |
| Magnetorheological Damper Integration | Bosch and Showa valve technology licensing creates capability moats that compress development timelines for mid-tier competitors. |
| Direct-to-Consumer Configuration Tools | Factory-allocated builds in the United Kingdom and Netherlands concentrate working capital risk with OEMs while reducing dealer exposure. |
| Assembly-Joint-Venture Formation | ANVISA-streamlined Brazilian import procedures enable Mercosur market access without captive manufacturing footprint. |
| Subscription-Based Asset-Light Ownership | Monthly access models bundling insurance and maintenance target younger riders bypassing traditional financing in Berlin and Munich. |
Methodological Framework
Desk research of customs trade databases, EPA certification filings, and KBA vehicle registration statistics preceded structured interviews with OEM platform engineers, Tier 1 suspension supplier procurement leads, aftermarket distributor operations heads, and mining fleet maintenance directors across Australian Outback and Canadian North operating environments. Secondary validation drew from Euro 5+ regulatory impact assessments, BIS two-wheeler certification documentation, and ANVISA import procedure amendments. Bottom-up unit volume estimates triangulated against top-down market value reconstructions.
Assumptions held fixed include prevailing emissions enforcement patterns across EPA, Euro 5+, and BIS jurisdictions, while electrification timeline uncertainty and aluminum commodity volatility were treated as scenario variables. Segmentation modeling spanned product architecture, engine displacement band, technology integration depth, and distribution channel structure across the projection horizon. CAGRs derived from regression analysis against macroeconomic indicators and regulatory compliance cost trajectories. Industry-specific inputs incorporated suspension component lead time dynamics and embedded software validation cycle durations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese electric two-wheeler specialists or accelerated EPA timeline shifts would shift outcomes. Quarterly review of KBA certification backlogs, ANVISA import approval velocities, and aluminum LME forward curves is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Motorcycle Instrument Cluster Market
Bikes and Motorcycles
UAE Motorcycle ADAS Market
Bikes and Motorcycles
Global Hybrid Bicycles Market
Bikes and Motorcycles
Denmark E-Bike Market
Bikes and Motorcycles
North America Bicycle Market
Bikes and Motorcycles
Shock Absorber Market
Bikes and Motorcycles
Global Two Wheeler Accessories Market
Bikes and Motorcycles
Fixed Gear Bikes Market
Bikes and Motorcycles
E-Mountain Bike Market
Bikes and Motorcycles
Motorcycle Drivetrain Market
Bikes and Motorcycles
Two Wheeler Switches Market
Bikes and Motorcycles
Motorcycles, Scooters and Mopeds Market
Bikes and Motorcycles
Smart Electric Bikes Market
Bikes and Motorcycles
Emission Control Catalyst for Motorcycle Market
Bikes and Motorcycles
Asia-Pacific Ride on Bikes Market
Bikes and Motorcycles
Europe E Bike Market