
 Motorcycle Filter Market | 2026-2036
Motorcycle Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Filter Market Analytics
High-efficiency nanofiber media is redrawing the competitive map for premium replacement filters. K&N Engineering leverages its cotton-gauze recharge technology to dominate the performance aftermarket across North American and European channels. Mann+Hummel anchors industrial-scale capacity for OEM supply contracts with major motorcycle manufacturers. MAHLE competes through integrated filtration systems that bundle air, oil, and fuel modules under single part numbers.
A motorcycle filter is a fluid or air purification component engineered from pleated cellulose paper, synthetic melt-blown fibers, or sintered metal mesh, designed to remove particulate and chemical contaminants from intake air, lubricating oil, fuel, or hydraulic circuits to protect engine longevity and emission compliance. Air filters using synthetic fiber media command the widest margin pools due to extended service intervals and dust-loading capacity advantages over conventional paper. Oil filters for street motorcycles represent the most mature segment with standardized spin-on canister designs, while off-road applications drive demand for foam pre-filters that withstand extreme dust ingress. Aftermarket providers increasingly specialize in direct-to-consumer channels that bypass traditional dealership networks.
The US EPA enforces emission durability requirements that mandate filter performance over defined vehicle lifetimes, while the EU F-Gas Regulation and REACH framework restrict certain chemical treatments in filter media production. India's BIS certification for automotive components creates compliance barriers for imported aftermarket products. Stakeholders must monitor regulatory divergence between emission durability standards and material restriction protocols when configuring regional product portfolios and sourcing strategies.
Market Dynamics
The motorcycle filter market is undergoing a structural compression between tightening emission durability mandates and the proliferation of nanofiber media technologies that extend replacement intervals, forcing suppliers to compete on performance longevity rather than volume turnover.
Growth Catalysts
- EPA Emission Durability Rules:US federal requirements mandate filter performance across defined vehicle lifetimes, compelling OEMs to specify higher-grade media and creating aftermarket upgrade demand as fleets age.
- India Two-Wheeler Density:The country's sustained two-wheeler ownership growth and expanding service infrastructure generate replacement filter pull that outpaces most developed markets.
- Nanofiber Media Adoption:Synthetic melt-blown and electrospun fiber layers deliver superior dust-loading capacity, allowing extended service intervals that command premium positioning in performance aftermarket channels.
Market Restraints
- Cellulose Paper Cost Volatility:Pulp feedstock price swings and energy-intensive pleating processes compress margin pools for conventional filter manufacturers serving economy-tier segments.
- Supply Concentration in Filter Media:Specialty synthetic fiber production clusters in Germany and Japan, creating geographic single-source risk for tier-two assemblers without captive media capabilities.
- Euro 5 Technical Limitation:The regulation's particulate count thresholds approach the filtration efficiency ceiling of standard cellulose media without synthetic layer upgrades, forcing premature obsolescence of legacy product lines.
Strategic Opportunities
- India BIS Certification Barrier:Import compliance requirements for automotive components create protected domestic manufacturing opportunities for local producers with certified testing infrastructure.
- Direct-to-Consumer Channel Convergence:E-commerce platforms and specialty retailer networks bypass traditional dealership distribution, capturing margin previously allocated to multi-tier wholesale structures.
- Integrated Filtration Modules:Bundled air-oil-fuel systems under single part numbers reduce inventory complexity for fleet operators and create switching costs against component-only competitors.
Industry Challenges
- Nanofiber Process Engineering Talent:Electrospinning and melt-blowing specialization remains concentrated among materials science graduates with polymer processing experience, constraining rapid capacity scaling.
- REACH Compliance Timeline:ECHA substance restrictions on certain chemical treatments in filter media require reformulation cycles that extend new product introduction schedules by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Filter Market |
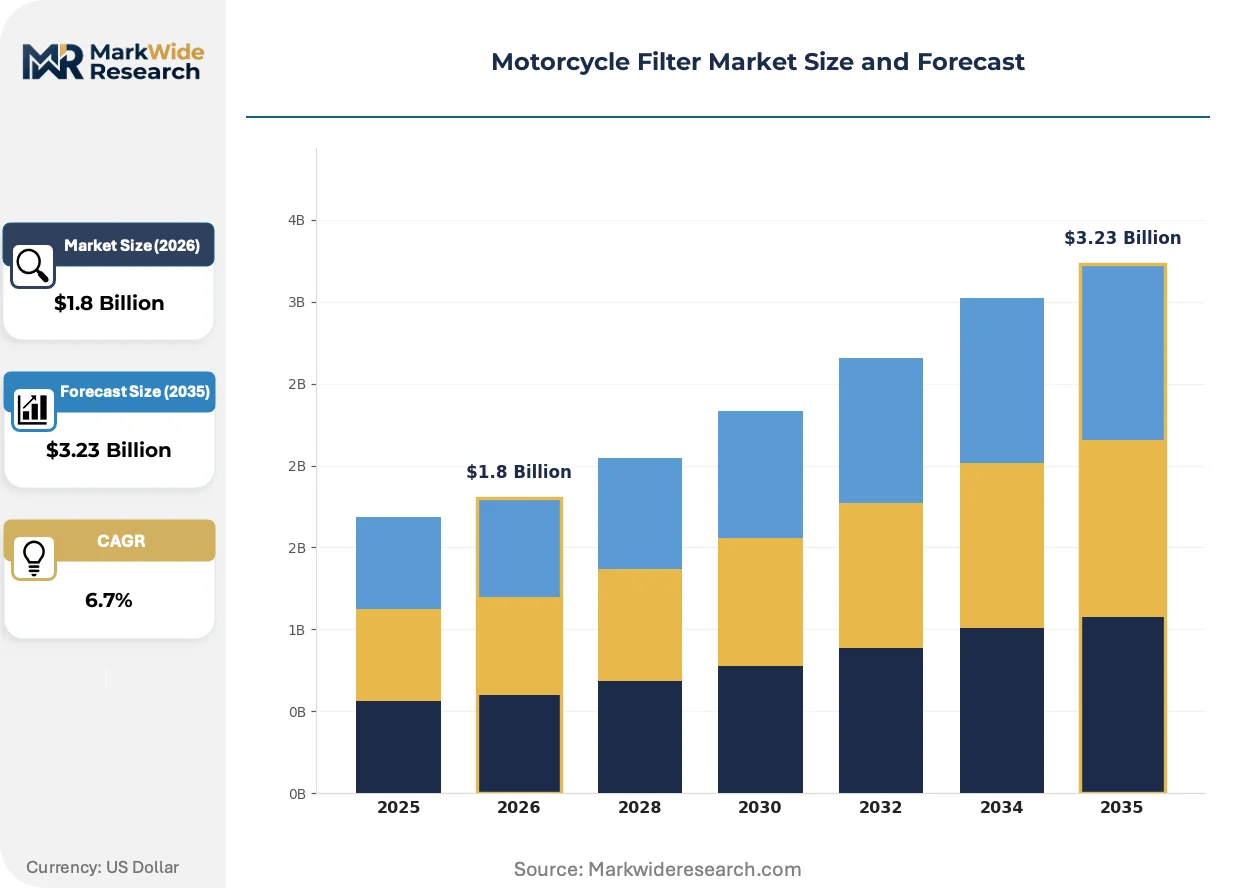
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil Filters, Air Filters, Fuel Filters, Hydraulic Filters Material: Paper, Synthetic Fiber, Metal, Foam End User: OEMs, Aftermarket Providers, Dealerships, Repair Shops Application: Street Motorcycles, Off-Road Motorcycles, Touring Motorcycles, Sports Motorcycles |
| Companies Covered | K&N Engineering, BMC Air Filters, Uni Filter, Mann+Hummel, MAHLE, Hiflofiltro, Pipercross Performance Filters, DNA Filters, Roki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Filter Market Evolving Landscape
Filter media technology and distribution architecture are diverging simultaneously, with performance-tier synthetic materials gaining share while procurement patterns fragment across traditional and digital channels.
Synthetic nanofiber layers laminated to cellulose substrates are fragmenting the historical premium-mass market boundary. Performance aftermarket buyers and commercial fleet operators specify these composites for extended drain intervals, compressing the addressable market for conventional paper-only products while expanding absolute margin per unit. The technology is fragmenting established supplier hierarchies as materials science entrants bypass legacy pleating equipment constraints.
REACH substance restrictions and the EU F-Gas Regulation are eliminating certain fluorinated treatments previously used for water repellency in air filter media. Filter manufacturers reformulate with silicone-based alternatives or uncoated high-density synthetics, accelerating R&D spend across European production facilities. Off-road motorcycle segments face the steepest adaptation curve due to extreme dust ingress requirements that historically relied on prohibited chemistries.
Aftermarket procurement through mobile-enabled service platforms is displacing traditional parts counter relationships. Independent repair shops in India and Southeast Asia source filters through B2B marketplaces that aggregate inventory visibility and compress order-to-delivery cycles. The behavior shift concentrates purchasing power among platform operators, forcing filter brands to allocate trade marketing spend toward digital shelf optimization rather than distributor rebate programs.
Motorcycle Filter Market Segmentation
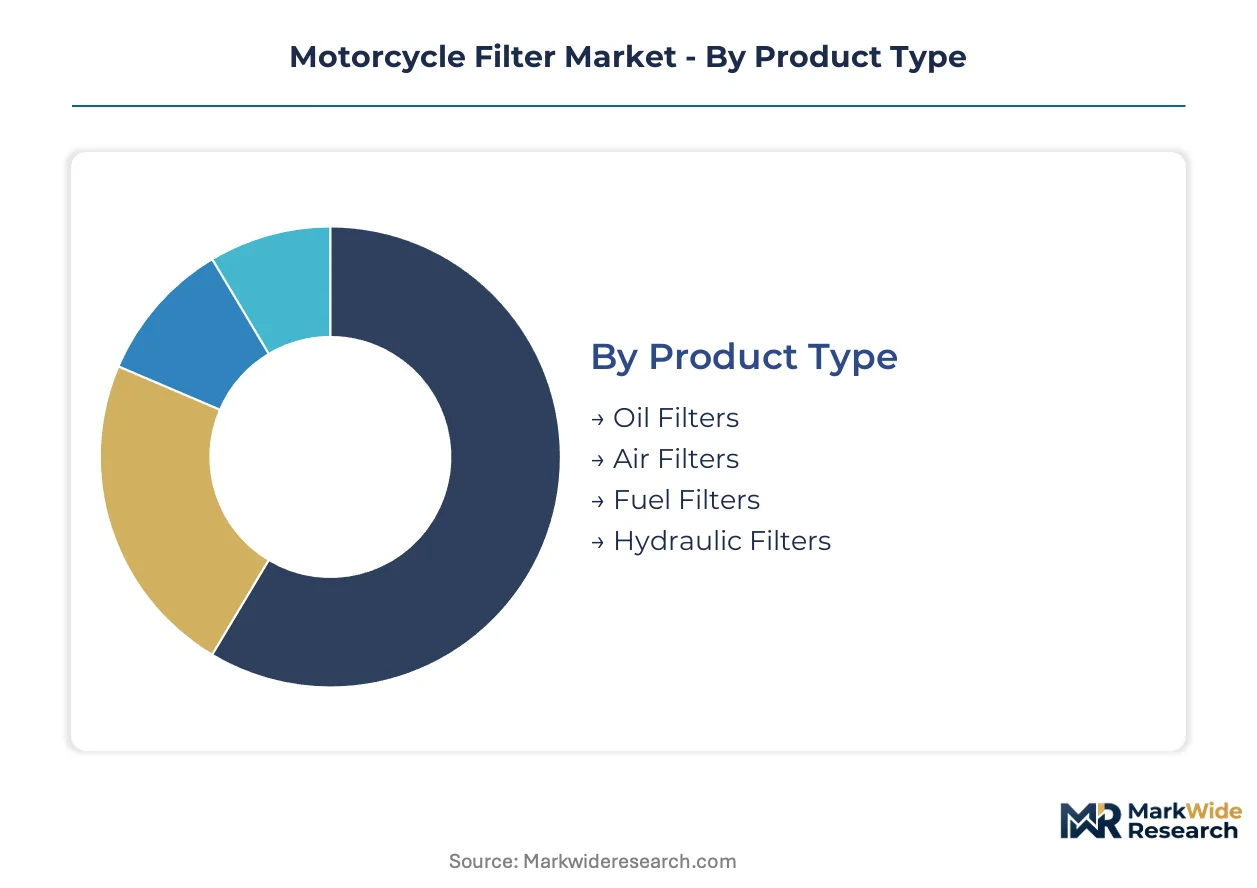
Filter segmentation determines margin architecture and replacement cadence across motorcycle service ecosystems. Media composition and distribution channel each impose distinct technical and commercial constraints on supplier positioning.
Product Type:
Synthetic media substitution threatens conventional oil filter economics most acutely, while air filter premiumization accelerates through nanofiber layer adoption.
- Oil Filters:Spin-on canister designs with cellulose or synthetic media protect crankcase lubrication circuits from metallic debris and oxidation byproducts. Street motorcycle fleets in India and Southeast Asia generate the densest replacement pull due to high annual mileage and severe stop-start operating conditions.
- Air Filters:Pleated cellulose or synthetic fiber elements remove particulate from intake air, with nanofiber laminates commanding extended service intervals. EPA emission durability rules and Euro 5 particulate count thresholds compel OEM specification of high-efficiency media, compressing demand for paper-only legacy designs.
- Fuel Filters:Sintered metal or synthetic fiber media separate water and particulate from gasoline or diesel delivery systems. Direct injection motorcycle adoption elevates filtration precision requirements.
- Hydraulic Filters:High-pressure synthetic media protect clutch and brake actuation circuits from contamination. Niche volume concentrates in touring and sports motorcycle segments with sophisticated hydraulic subsystems.
Oil filters retain volume leadership; air filters hold the steepest expansion curve.
Material:
Cost tier stratification separates captive synthetic fiber production from commodity cellulose sourcing.
- Paper:Cellulose pulp pleated media serves economy-tier replacement demand with standardized efficiency ratings. Pulp feedstock volatility and energy-intensive pleating compress margin pools for manufacturers without scale economies.
- Synthetic Fiber:Melt-blown and electrospun polypropylene or polyester layers deliver superior dust-loading capacity and extended drain intervals. Nanofiber laminates command premium positioning in performance aftermarket channels across North America and Europe.
- Metal:Sintered stainless steel mesh provides reusable filtration for high-performance applications. K&N Engineering dominates this niche through cotton-gauze recharge technology.
- Foam:Open-cell polyurethane pre-filters withstand extreme dust ingress in off-road environments. REACH substance restrictions on fluorinated water repellents force silicone-based reformulation cycles.
Paper retains volume leadership; synthetic fiber holds the steepest expansion curve.
End User:
Channel fragmentation redistributes margin capture from traditional wholesale tiers to direct procurement platforms.
- OEMs:Motorcycle manufacturers specify integrated filtration modules under single part numbers, creating switching costs and long-term supply contracts. Mann+Hummel anchors industrial-scale capacity for these relationships.
- Aftermarket Providers:Independent brands bypass dealership networks through e-commerce and specialty retailer channels. Digital shelf optimization displaces traditional trade marketing spend.
- Dealerships:Authorized service networks rely on OEM-specified replacement filters with captive part numbering systems. India BIS certification creates compliance barriers for imported alternatives.
- Repair Shops:Independent mechanics in India and Southeast Asia aggregate purchasing through mobile-enabled B2B marketplaces that compress order-to-delivery cycles.
Aftermarket providers are gaining share fastest; OEMs retain contract value concentration.
Application:
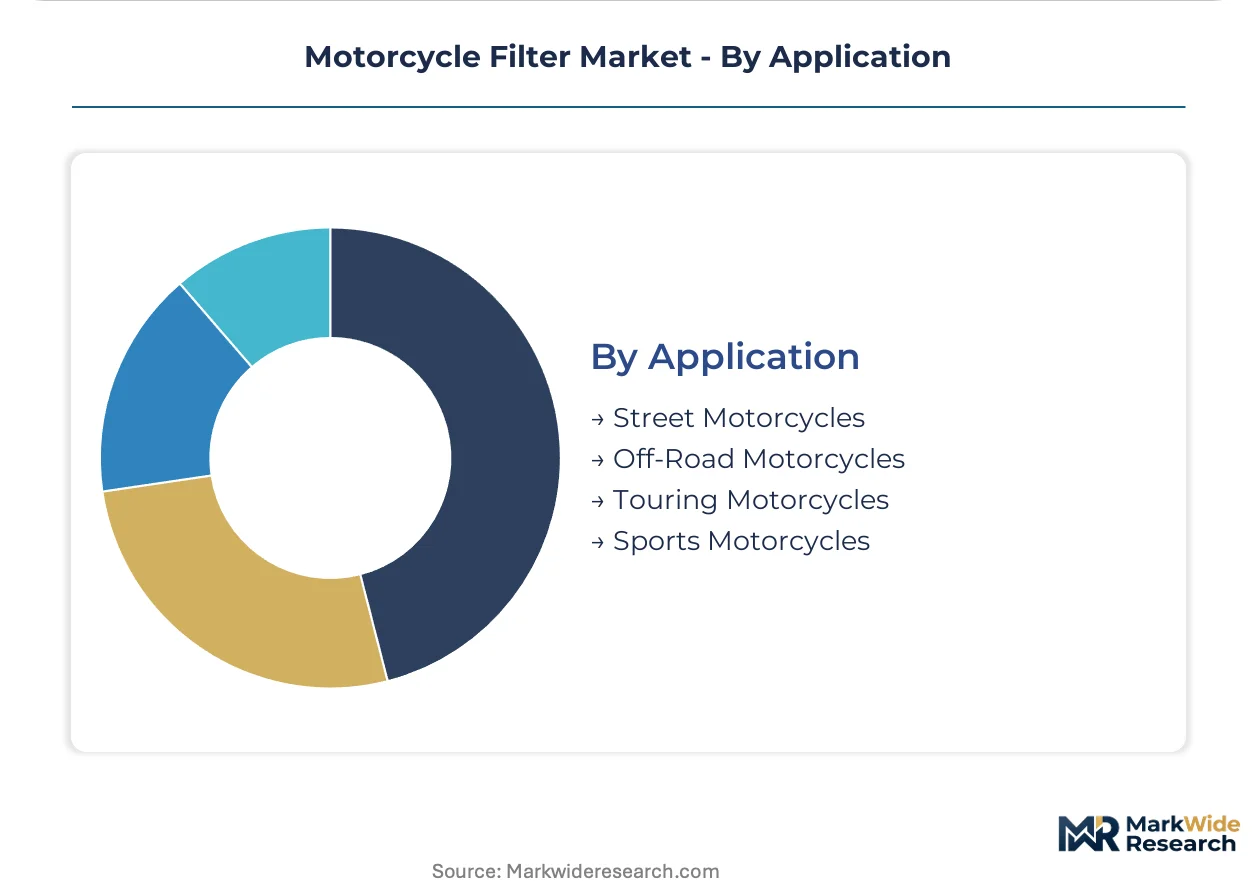
Maturity gradients separate standardized street motorcycle service intervals from specialized off-road and touring specifications.
- Street Motorcycles:High-density urban commuting fleets in India and China generate predictable replacement demand with standardized filter geometries. Euro 5 compliance forces media upgrades across European-registered vehicles.
- Off-Road Motorcycles:Extreme dust ingress environments require foam pre-filters and frequent service intervals. REACH fluorinated treatment bans impose the steepest adaptation curve for water repellency specifications.
- Touring Motorcycles:Long-distance highway operation extends drain intervals and elevates synthetic media adoption. Integrated air-oil-fuel modules reduce inventory complexity for fleet operators.
- Sports Motorcycles:High-revving engines demand premium filtration with low flow restriction. Performance aftermarket channels concentrate in North America and European track-day segments.
Street motorcycles retain volume leadership; off-road applications hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia demonstrate acute price elasticity for economy-tier cellulose filters, while North American and European performance segments absorb nanofiber premiums with minimal volume sensitivity. This demand-elasticity contrast shapes regional supplier strategies and media technology deployment.
United States
Performance aftermarket channels command the steepest nanofiber adoption curves, with EPA emission durability rules mandating filter integrity across defined vehicle lifetimes. The EPA enforces these standards through certification testing protocols that elevate OEM specification grades. California's emissions testing infrastructure and Texas-based distribution hubs concentrate aftermarket logistics capacity for cross-border North American fulfillment.
Germany
Industrial-scale filter media production clusters anchor European supply security, with Mann+Hummel's presence exemplifying captive synthetic fiber capabilities. ECHA REACH substance restrictions on fluorinated water repellents force reformulation cycles across air filter production. Bavaria's automotive supplier ecosystem and Baden-Württemberg's precision manufacturing corridors concentrate electrospinning process engineering talent.
India
Two-wheeler density generates replacement filter pull that outpaces developed markets, with street motorcycle fleets operating under severe stop-start conditions. BIS certification for automotive components creates compliance barriers for imported aftermarket products. Maharashtra's Pune-Nashik manufacturing belt and Tamil Nadu's Chennai industrial corridor concentrate domestic filter assembly capacity for OEM and aftermarket supply.
Japan
Specialty synthetic fiber production maintains geographic concentration risk for tier-two assemblers without captive media capabilities. METI industrial standards and JIS certification frameworks govern filter performance specifications for domestic motorcycle manufacturers. The Kanto region's Tokyo-Yokohama corridor and Chubu's Nagoya industrial zone anchor precision materials processing infrastructure.
Brazil
Latin America's largest motorcycle fleet sustains steady replacement demand through authorized service networks and independent repair channels. ANVISA's automotive component regulations align with Mercosur technical standards for filtration efficiency. São Paulo state's ABC industrial region and Minas Gerais's Belo Horizonte manufacturing cluster concentrate regional distribution and assembly operations.
Motorcycle Filter Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with synthetic nanofiber specialists commanding premium positioning while cellulose-scale manufacturers defend economy-tier volume. The market structure fragments across three tiers: integrated filtration system bundlers, performance aftermarket specialists with recharge technologies, and regional assemblers serving price-sensitive replacement demand. Dominant competitive moves include backward integration into captive synthetic fiber production and direct-to-consumer channel bypass of traditional wholesale tiers.
Within the performance aftermarket tier, K&N Engineering exemplifies technology differentiation through cotton-gauze recharge systems, while Mann+Hummel anchors industrial-scale OEM supply relationships. MAHLE occupies a position representing integrated system bundlers that combine air, oil, and fuel modules under consolidated part numbering. These three archetypes—recharge-technology specialists, scale-driven OEM suppliers, and integrated system providers—capture distinct margin pools across the value chain.
| Leading Market Players |
|---|
| K&N Engineering |
| BMC Air Filters |
| Uni Filter |
| Mann+Hummel |
| MAHLE |
| Hiflofiltro |
| Pipercross Performance Filters |
| DNA Filters |
| Roki |
| Others |
Value Network & Pricing Analysis
Mann+Hummel's industrial-scale captive synthetic fiber production in Germany anchors capacity utilization rates that compress unit economics for tier-two assemblers lacking upstream media control. This scale concentration elevates price floors for nanofiber laminates while forcing cellulose-dependent manufacturers toward thinner margin pools.
Pricing Analysis
EPA emission durability rules and Euro 5 particulate thresholds dictate the pricing tier structure across replacement filter markets. Three-tier pricing structure across premium, standard, and economy levels separates OEM-specified nanofiber modules from aftermarket synthetics and commodity cellulose spin-ons. Pricing pressure stems from pulp feedstock volatility and energy-intensive pleating processes that erode margin pools for paper-only manufacturers. Fleet operators in India demonstrate acute price elasticity for economy-tier cellulose, while North American performance buyers absorb nanofiber premiums with minimal volume sensitivity.
Supply Chain Analysis
Germany and Japan anchor specialty synthetic fiber production for electrospun and melt-blown filter media, creating geographic concentration risk for tier-two assemblers without captive capabilities. Raw material dependencies span polypropylene and polyester polymer feedstocks, cellulose pulp from Nordic and Southeast Asian sources, and silicone-based water repellent formulations substituting banned fluorinated treatments. Single-source vulnerability runs through electrospinning process engineering talent concentrated in Bavaria and the Kanto region. Distribution runs through mobile-enabled B2B marketplaces in India and Southeast Asia alongside traditional OEM captive part networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a regulatory-entrenchment moat where BIS certification barriers and EPA durability mandates create switching costs that protect incumbent positions against low-cost import competition.
For Market Incumbents: Fortify backward integration into captive synthetic fiber production to defend margin pools against cellulose cost volatility and nanofiber process engineering scarcity. Deepen certification infrastructure investments for India BIS and EPA emission durability compliance to extend contract lock-in with OEM specification teams. Prioritize direct-to-consumer channel control through digital shelf optimization as mobile-enabled B2B platforms disintermediate traditional wholesale tiers. For New Entrants and Emerging Players: Aftermarket service platform gaps in India's independent repair shop ecosystem offer white-space entry where incumbent brands under-invest in localized B2B marketplace presence. Target Tamil Nadu's Chennai industrial corridor for domestic assembly partnerships that satisfy BIS certification requirements without full greenfield investment. Pursue foam pre-filter specialization for off-road segments facing REACH fluorinated treatment reformulation cycles that disrupt legacy supplier product lines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated filtration module bundlers that combine air-oil-fuel systems under single part numbers, creating switching costs and multi-year OEM supply contracts. Prioritize acquisition targets with captive electrospinning capabilities and established BIS-certified testing infrastructure in India. Monitor nanofiber media adoption curves in North American performance channels as the inflection signal for premium tier expansion viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Fiber Production | Captive melt-blown capacity insulates margin pools from German and Japanese supply concentration risk. |
| BIS Certification Infrastructure Investment | Domestic testing capabilities unlock protected India aftermarket access against import compliance barriers. |
| Direct-to-Consumer Channel Expansion | Digital shelf optimization captures margin previously allocated to multi-tier wholesale structures. |
| Integrated Filtration Module Development | Single part-number bundling creates switching costs and reduces fleet operator inventory complexity. |
| REACH-Compliant Foam Pre-Filter Reformulation | Silicone-based water repellent substitutes capture off-road share from fluorinated-dependent competitors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with aftermarket distribution managers, OEM procurement leads, independent repair shop owners in India, and filter media process engineers at synthetic fiber production facilities. Secondary validation drew from EPA certification filings, ECHA REACH substance restriction updates, BIS automotive component standards, customs trade data for filter media imports, and motorcycle registration databases across target markets. Bottom-up unit shipment estimates triangulated against top-down value projections.
Across the analysis window, volume and value outputs reflect modeling across filter type, media composition, distribution channel, end-user archetype, and regional regulatory cluster dimensions. CAGRs were derived from segment-level replacement interval assumptions, fleet aging projections, and nanofiber adoption curve penetration rates. Forecast inputs incorporated EPA emission durability compliance timelines, Euro 5 particulate threshold implementation schedules, and India two-wheeler density growth trajectories.
Forecasts assume regulatory continuity in EPA, ECHA REACH, and BIS regimes; material policy shifts would require re-modeling. Specific risks include REACH substance restriction expansion beyond fluorinated treatments, India BIS certification requirement tightening for imported aftermarket products, and pulp feedstock price shock transmission into cellulose filter economics. Recalibration cycles align with material shifts in emission durability mandates, nanofiber process engineering capacity expansion, and mobile-enabled B2B platform penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
South America Two-Wheeler Market
Bikes and Motorcycles
Two-Wheeler Brake Pads Market
Bikes and Motorcycles
Spain E-Bike Market
Bikes and Motorcycles
Fixed Gear Bikes Market
Bikes and Motorcycles
Motorcycle Transmission Control Unit Market
Bikes and Motorcycles
Motorbike Carburetor Market
Bikes and Motorcycles
Motorcycle Tubeless Tire Market
Bikes and Motorcycles
GPS Bike Computers Market
Bikes and Motorcycles
LAMEA Motorcycle ADAS Market
Bikes and Motorcycles
South Africa Two-Wheeler Market
Bikes and Motorcycles
Two Wheeler Kick Lever Market
Bikes and Motorcycles
South Africa E-Bike Market
Bikes and Motorcycles
Two Wheeler Fenders Market
Bikes and Motorcycles
United Arab Emirates E-Bike Market
Bikes and Motorcycles
Shock Absorber Market
Bikes and Motorcycles
China Motorcycle ADAS Market