
 South Africa E-Bike Market | 2026-2036
South Africa E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa E-Bike Market Analytics
Last-mile delivery fleets in Johannesburg and Cape Town is expanding their e-bike procurement as fuel costs and congestion erode van economics. Specialized leverages its premium dealer network to sustain brand positioning in urban commuter segments. Giant Manufacturing anchors volume supply through established South African distribution partnerships. Trek competes on technical service density, with certified repair infrastructure concentrated in Gauteng and Western Cape.
An e-bike integrates an electric motor, rechargeable lithium-ion battery, and pedal-assist or throttle-based propulsion into a bicycle frame, with motor output typically capped at 250W and assisted speeds limited to 25 km/h for road-legal classification in South African traffic codes. The device serves commercial logistics operators and private commuters seeking lower-cost mobility alternatives to internal-combustion transport. Mountain E-Bikes dominate unit sales where trail tourism and recreational riding concentrate around Drakensberg and Western Cape outdoor economies, while City E-Bikes capture the fastest volume growth among Pretoria-Johannesburg corridor commuters. Battery capacity segmentation shows 15Ah configurations leading current shipments as the practical midpoint between range anxiety and purchase price sensitivity across Budget and Mid-Range price tiers.
South Africa's National Regulator for Compulsory Specifications enforces SANS electrical safety standards that determine which lithium-ion battery systems gain market access, while Department of Transport non-motorized transport policy shapes municipal lane allocation and parking infrastructure. Bureau of Standards certification requirements add compliance cost layers that filter lower-specification imports from informal channels. Stakeholders must monitor provincial infrastructure spending commitments and evolving battery recycling obligations to align product portfolios with enforcement trajectories.
Market Dynamics
Fuel price volatility and Gauteng corridor congestion are compressing total cost of ownership differentials between e-bikes and internal-combustion delivery vans, redirecting fleet procurement budgets toward pedal-assist configurations.
Growth Catalysts
- Non-Motorized Transport Frameworks:South Africa's Department of Transport has legitimized e-bike lane access in metropolitan planning, reducing collision risk perceptions among commercial operators.
- Last-Mile Logistics:Johannesburg and Cape Town delivery fleets are substituting vans with cargo e-bikes to bypass peak-hour congestion penalties and parking scarcity.
- Lithium-Ion Cost Curves:Battery pack economics have improved sufficiently to position mid-range 15Ah configurations as the default procurement choice for budget-conscious fleet managers.
Market Restraints
- SANS Certification Barriers:National Regulator for Compulsory Specifications electrical safety standards filter lower-specification imports, elevating compliance costs for price-sensitive entrants.
- Charging Infrastructure Gaps:Municipal parking infrastructure allocations remain concentrated in affluent precincts, leaving township and peri-urban corridors underserved.
- Petrol-Powered Substitutes:Second-hand motorcycle availability in informal channels retains residual appeal among individual commuters despite higher operating costs.
Strategic Opportunities
- Western Cape Trail Tourism:Mountain e-bike penetration around Drakensberg and Cape Winelands outdoor economies remains below saturation, offering expansion headroom for recreational-focused distributors.
- Battery Recycling Mandates:Evolving producer responsibility obligations for lithium-ion end-of-life management will reward early movers with licensed recycling partnerships.
- Direct-to-Fleet Digital Platforms:Subscription and lease-to-own models bypass traditional dealer markups, capturing price-sensitive commercial buyers in Pretoria-Johannesburg corridors.
Industry Challenges
- Certified Technician Scarcity:Trek's repair infrastructure concentration in Gauteng and Western Cape exposes service gaps in KwaZulu-Natal and Eastern Cape provinces.
- Standardization Delays:Interoperability between battery systems and motor controllers remains fragmented, complicating fleet maintenance protocols for multi-brand operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa E-Bike Market |
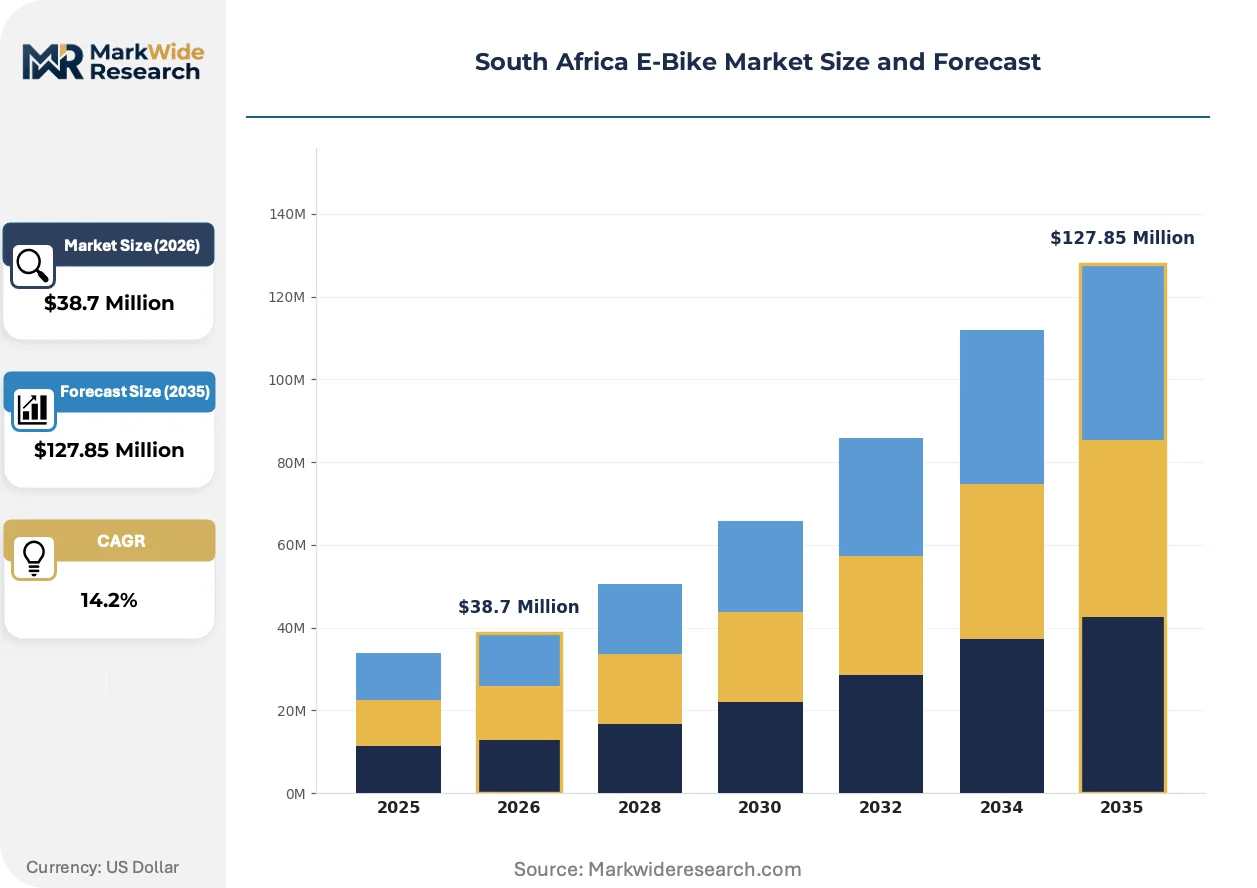
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $127.85 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding E-Bikes, Mountain E-Bikes, City E-Bikes, Hybrid E-Bikes Battery Capacity: 10Ah, 15Ah, 20Ah, 25Ah Price Tier: Budget, Mid-Range, Premium, Luxury Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Merida Industry, Riese & Müller, Specialized, Scott Sports, BH Bikes, Trek, Accell Group, Cannondale, Giant Manufacturing, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa E-Bike Market Evolving Landscape
Removable battery architectures and smart connectivity modules are redefining product differentiation, while provincial infrastructure commitments are reshaping geographic demand distribution.
Swappable battery systems are decentralizing fleet charging logistics by eliminating depot-based infrastructure requirements. Last-mile operators in Johannesburg are adopting hot-swap protocols to sustain continuous vehicle utilization. This architecture is compressing vehicle downtime and enabling smaller fleet footprints per delivery zone.
South Africa's Department of Transport non-motorized transport policy is mandating e-bike lane allocation in municipal spatial planning. The industrial consequence is elevated land-use priority for cycling infrastructure in metropolitan development frameworks. Pretoria-Johannesburg corridor municipalities are responding with dedicated parking bay specifications and intersection signal timing adjustments.
Fleet procurement patterns are fragmenting away from upfront purchase toward operational expenditure models. Commercial buyers are substituting capital-heavy ownership with subscription and managed service contracts. This behavioral pivot is most visible among Gauteng-based logistics operators seeking balance-sheet flexibility amid interest rate volatility.
South Africa E-Bike Market Segmentation
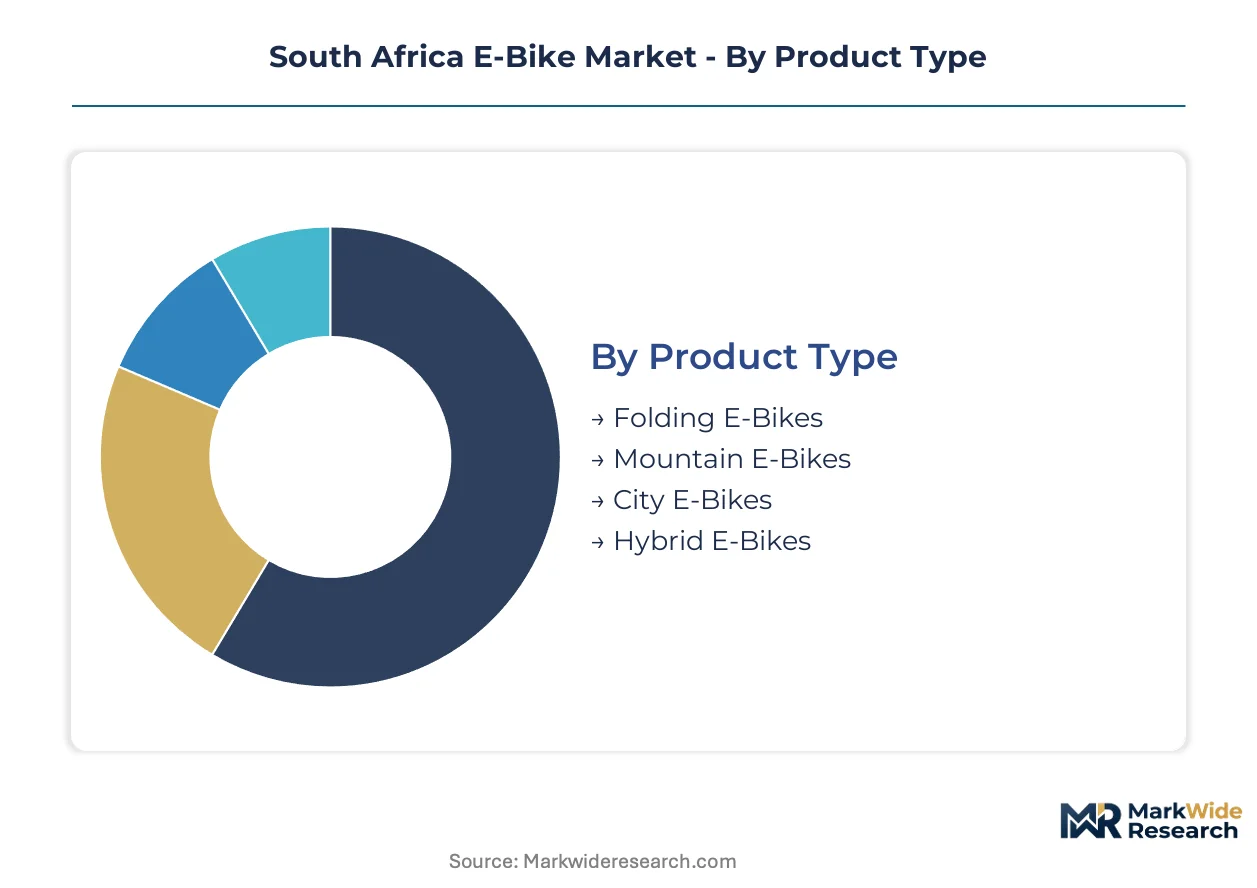
E-bike segmentation in South Africa reflects divergent mobility needs across commercial logistics and recreational applications. Understanding these divides enables stakeholders to align battery specifications, frame geometries, and pricing architectures with distinct buyer economics.
Product Type:
Volume concentrates in recreational trail configurations, while urban commuter formats command premium positioning through fleet procurement scale.
- Mountain E-Bikes:Ruggedized frames with suspension travel exceeding 120mm and torque-rich mid-drive motors dominate Drakensberg and Western Cape trail tourism corridors. Weekend riders in Stellenbosch and Franschhoek outdoor economies sustain replacement cycles despite higher unit costs.
- City E-Bikes:Step-through frames with integrated racks and fenders capture Pretoria-Johannesburg corridor commuter demand where parking scarcity and fuel volatility compress total cost of ownership calculations. These units are expanding most quickly among last-mile delivery fleets seeking balance-sheet flexibility.
- Folding E-Bikes:Compact hinge-frame designs with 20-inch wheels address Gauteng apartment dwellers and multi-modal commuters combining cycling with Rea Vaya bus rapid transit.
- Hybrid E-Bikes:Intermediate tire widths and front suspension forks serve peri-urban riders navigating mixed paved-gravel surfaces in Ekurhuleni and Tshwane municipal boundaries.
Today's leader: Mountain E-Bikes. Tomorrow's challenger: City E-Bikes.
Battery Capacity:
Procurement patterns cluster around range-anxiety thresholds, with fleet managers optimizing between depot charging frequency and upfront capital outlay.
- 15Ah:The practical midpoint between purchase price sensitivity and single-charge range adequacy dominates Budget and Mid-Range tier shipments. Johannesburg logistics operators specify this capacity for standard delivery zones under 40km daily.
- 20Ah:Extended-range configurations with 500Wh+ energy density serve Cape Winelands recreational routes and long-haul commuter corridors where charging infrastructure remains sparse.
- 10Ah:Entry-level lithium-ion packs with 250-300Wh capacity satisfy price-conscious individual buyers in township markets prioritizing affordability over range.
- 25Ah:High-density configurations with 600Wh+ capacity target luxury tier buyers and specialized cargo fleet applications requiring continuous utilization without midday charging.
Procurement gravity centers on 15Ah today. 20Ah configurations are climbing the fastest as range expectations reset upward.
Price Tier:
Margin structures stratify across certification compliance costs, with SANS electrical safety standards filtering informal import channels from formal market participation.
- Mid-Range:15Ah battery configurations with branded motor systems from Bosch or Shimano anchor fleet procurement volumes. These units balance Bureau of Standards certification requirements with acceptable total cost of ownership for Gauteng logistics operators.
- Budget:Unbranded hub motors and generic battery management systems dominate informal retail channels in peri-urban townships, though SANS enforcement is elevating compliance barriers.
- Premium:Integrated frame designs with proprietary motor-battery communication protocols command price multiples through certified service networks concentrated in Gauteng and Western Cape.
- Luxury:Carbon fiber frames and smartphone connectivity modules target affluent recreational buyers in Cape Town's Atlantic Seaboard precincts.
Mid-Range holds current volume leadership. Budget tier faces structural compression from regulatory enforcement.
Distribution Channel:
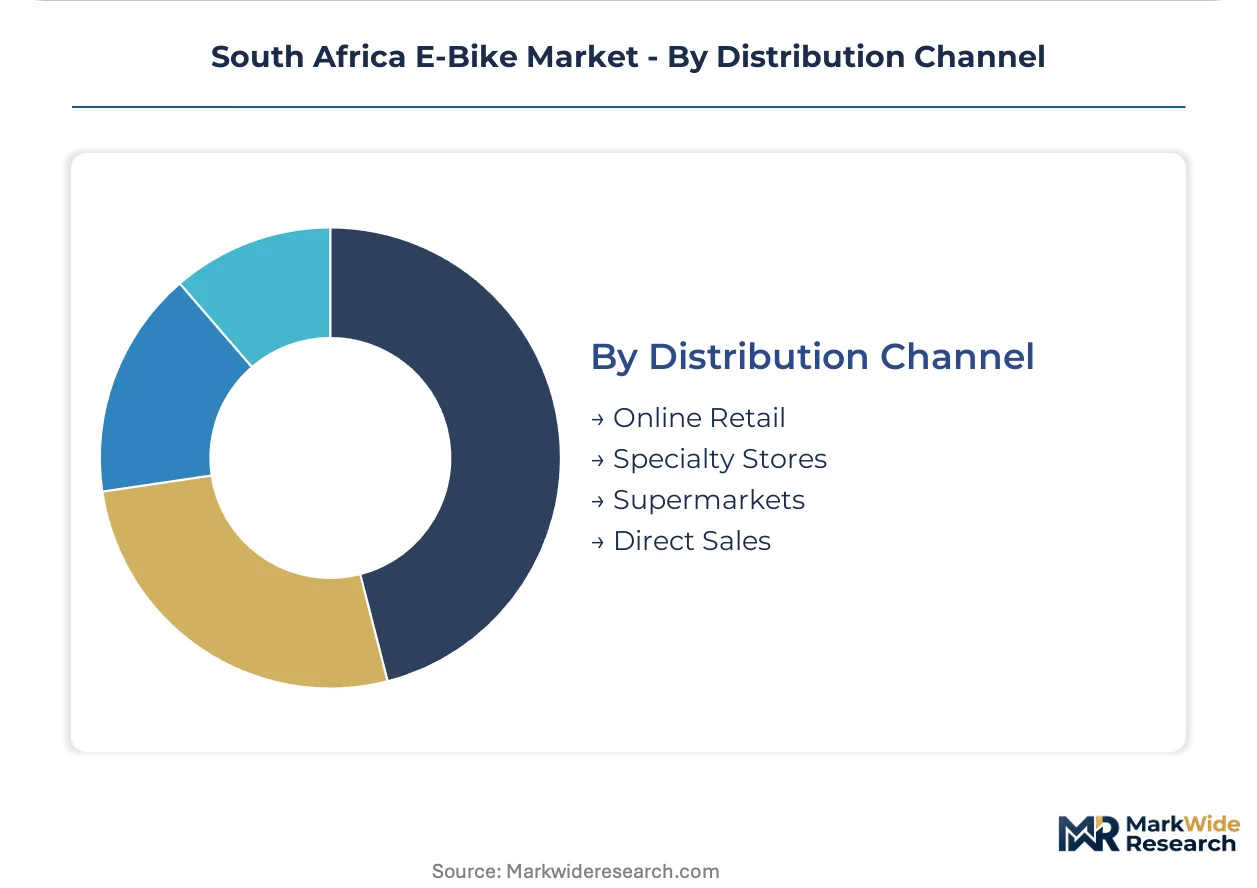
Channel selection determines service capability exposure, with fleet buyers prioritizing technical support density over transaction convenience.
- Specialty Stores:Certified technician networks with spare parts inventory sustain Trek and Giant positioning through post-warranty service revenue. These outlets concentrate in Sandton, Cape Town CBD, and Stellenbosch.
- Direct Sales:Subscription and lease-to-own platforms bypass dealer markups, capturing price-sensitive commercial buyers in Pretoria-Johannesburg corridors seeking operational expenditure treatment.
- Online Retail:E-commerce platforms with warehouse fulfillment serve individual commuters prioritizing price transparency over immediate technical support.
- Supermarkets:Mass retail placement of Budget tier units reaches price-sensitive buyers in township and peri-urban markets with limited specialty store penetration.
Specialty Stores retain service-advantaged positioning. Direct Sales channels are gaining share fastest among fleet procurement decision-makers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gauteng province anchors South African e-bike demand through Johannesburg-Pretoria commuter congestion and last-mile logistics density. Provincial infrastructure spending and municipal lane allocation policies are reshaping geographic deployment patterns across five key sub-regions.
Gauteng Province
Johannesburg and Pretoria corridors concentrate fleet procurement for delivery operators bypassing peak-hour gridlock. The Department of Transport non-motorized transport framework legitimized e-bike lane access in metropolitan planning. Sandton and Tshwane municipalities are deploying dedicated parking bays and adjusted intersection signal timing.
Western Cape
Cape Town's Atlantic Seaboard precincts drive premium recreational demand alongside Stellenbosch-Franschhoek trail tourism economies. Provincial environmental policy prioritizes low-emission mobility in urban spatial frameworks. Cape Winelands outdoor operators are expanding mountain e-bike rental fleets for weekend adventure tourism.
KwaZulu-Natal
Durban's coastal commuter corridors and Drakensberg trail networks sustain dual-use recreational and utility demand. Municipal non-motorized transport integration remains less advanced than Gauteng or Western Cape counterparts. Pietermaritzburg and surrounding townships face certified technician scarcity that limits service network penetration.
Eastern Cape
Port Elizabeth-Gqeberha automotive industry adjacency creates nascent industrial logistics demand for factory-perimeter mobility. Provincial infrastructure budgets allocate minimal cycling-specific capital relative to road maintenance priorities. Nelson Mandela Bay metro is piloting limited e-bike share programs in central business districts.
North West Province
Rustenburg platinum belt mining communities generate individual commuter demand for affordable mobility alternatives to shared taxi services. National Regulator for Compulsory Specifications enforcement filters informal battery imports through border proximity with Botswana. Mahikeng and surrounding peri-urban areas remain underserved by specialty retail and certified repair infrastructure.
South Africa E-Bike Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers balance recreational trail configurations against urban fleet procurement growth. The vendor base stratifies across three tiers: premium integrated-frame specialists, mid-range volume suppliers, and budget-tier assemblers facing regulatory compression. Two strategic archetypes have emerged: certified service network builders and direct-to-fleet platform operators. Geographic expansion through established distribution partnerships and technology licensing for localized battery management systems represent the dominant competitive vectors.
Among European premium specialists, Riese & Müller and Scott Sports exemplify the certified-service archetype through technician-trained retail positioning. Giant Manufacturing anchors the volume-driven tier with distribution scale advantages across multiple provincial markets. Specialized occupies a bridging position between premium recreational and fleet-procurement segments.
| Leading Market Players |
|---|
| Merida Industry |
| Riese & Müller |
| Specialized |
| Scott Sports |
| BH Bikes |
| Trek |
| Accell Group |
| Cannondale |
| Giant Manufacturing |
| Others |
Value Network & Pricing Analysis
Certified lithium-ion battery technician scarcity in Gauteng and Western Cape widens pricing-tier spreads as labor-cost differentials compound with SANS certification compliance burdens across premium and budget segments.
Pricing Analysis
Input-cost pass-through from lithium-ion cell pricing and Bureau of Standards certification fees shapes a three-tier pricing structure across premium, standard, and economy levels. Premium tiers absorb certified technician training costs and proprietary motor-battery communication protocols, while budget tiers face margin compression from SANS enforcement filtering informal imports. Pricing pressure stems from fleet procurement shifting toward operational expenditure models that prioritize total cost of ownership over upfront unit cost. Individual township commuters exhibit highest price sensitivity, whereas Gauteng logistics operators prioritize service network density over transaction price.
Supply Chain Analysis
Workforce availability constraints in Chinese and South Korean battery manufacturing geographies tether South African market supply to East Asian cell production capacity. Lithium carbonate, nickel-manganese-cobalt cathode materials, and battery management system semiconductors constitute critical input dependencies. Single-source vulnerability concentrates in cylindrical cell formats from dominant tier-one suppliers. Distribution runs through established importer-distributor partnerships anchored by Giant Manufacturing and Trek, with direct-to-fleet digital platforms emerging as alternative channel structures.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on lithium-ion cost curve improvements and fleet procurement's pivot toward subscription models that capture recurring revenue premiums.
For Market Incumbents: Hedge against direct-to-fleet platform disintermediation by deepening certified technician networks in KwaZulu-Natal and Eastern Cape service gaps. Secure backward integration into battery management system firmware to reduce proprietary motor-controller interoperability failures that complicate multi-brand fleet maintenance. For New Entrants and Emerging Players: Enter via battery recycling partnerships that anticipate evolving producer responsibility mandates for lithium-ion end-of-life management. Target Western Cape trail tourism rental fleets as the most penetrable white-space segment, leveraging hot-swap subscription models that eliminate depot infrastructure requirements. For Investors and Strategic Acquirers: Logistics technology consolidators represent the most active acquirer in this space, seeking fleet management software capabilities that layer over hardware procurement. Long-term viability hinges on subscription revenue durability and recycling license moats. Watch provincial infrastructure spending commitments as the critical inflection signal for demand trajectory revision.| Strategic Initiative | Industry Significance |
|---|---|
| Swappable Battery Architecture Deployment | Hot-swap protocols eliminate depot charging infrastructure for Johannesburg last-mile operators. |
| Certified Technician Network Expansion | Trek and Giant Manufacturing anchor service density in Gauteng and Western Cape retail footprints. |
| Direct-to-Fleet Digital Platform Launch | Subscription models bypass dealer markups for Pretoria-Johannesburg corridor logistics buyers. |
| Battery Recycling Partnership Licensing | Early movers secure producer responsibility compliance ahead of evolving end-of-life mandates. |
| Provincial Infrastructure Lobbying | Department of Transport non-motorized transport policy shapes municipal lane allocation priorities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with e-bike fleet managers, specialty store technicians, Department of Transport policy officers, and lithium-ion battery distributors with secondary validation. Trade customs records, SANS certification registries, municipal infrastructure budget disclosures, and Bureau of Standards enforcement bulletins anchored bottom-up volume estimates against top-down addressable market calculations.
Historical reference periods spanning pre-policy and post-framework implementation phases anchored the projection horizon across product type, battery capacity tier, price segment, and distribution channel dimensions. CAGRs derived from segment-level growth rate reconciliation against aggregate market value movements, incorporating fleet procurement pattern shifts and provincial infrastructure commitment trajectories as industry-specific demand drivers.
The model holds under stable SANS enforcement intensity and sustained lithium-ion cost improvements; deviation in fuel price volatility spikes or municipal lane allocation delays would shift volume trajectories. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Two Wheeler Suspension System Market
Bikes and Motorcycles
Europe Motorcycle Airbag Market
Bikes and Motorcycles
Motorcycle Wheels Market
Bikes and Motorcycles
Two-Wheeler Motorcycle Market
Bikes and Motorcycles
On-Road Motorcycles Market
Bikes and Motorcycles
UAE Motorcycle ADAS Market
Bikes and Motorcycles
Bicycle Brake Lever Market
Bikes and Motorcycles
United States E-Bike Market
Bikes and Motorcycles
China Motorcycle ADAS Market
Bikes and Motorcycles
Bike Hub Market
Bikes and Motorcycles
Two Wheeler Switches Market
Bikes and Motorcycles
Motorcycle Fairings Market
Bikes and Motorcycles
Three Wheeled Motorcycle Market
Bikes and Motorcycles
UAE Electric Bike Market
Bikes and Motorcycles
Fuel Cell Bikes Market
Bikes and Motorcycles
Spain E-Bike Market