
 LAMEA Motorcycle ADAS Market | 2026-2036
LAMEA Motorcycle ADAS Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Motorcycle ADAS Market Analytics
Modular sensor packaging is decoupling hardware from firmware upgrade cycles across the LAMEA Motorcycle ADAS landscape. Continental AG leverages its radar manufacturing footprint to anchor supply relationships with Brazilian OEMs. Robert Bosch GmbH competes through integrated control unit architectures that reduce wiring complexity for tropical climates.
LAMEA Motorcycle ADAS comprises sensor arrays, electronic control units, and human-machine interface modules designed to detect threats and intervene through braking, throttle modulation, or rider alerts; camera systems typically operate at 30-60 frames per second with IP67 ingress protection for monsoon and dust exposure. Collision avoidance systems dominate current revenue as fleet operators prioritize rear-end and intersection scenarios. Camera systems are expanding fastest where lidar cost barriers persist, creating margin concentration in multi-sensor fusion software layers.
Brazil's CONTRAN resolutions, Mexico's NOM vehicle safety standards, and Argentina's IRAM certification requirements collectively mandate or incentivize ABS-linked stability control and visibility enhancement systems across new motorcycle registrations. These frameworks shape product homologation timelines and aftermarket retrofit eligibility. Stakeholders must monitor regulatory divergence between Mercosur and Pacific Alliance alignment paths to anticipate certification cost trajectories.
Market Dynamics
Camera-radar sensor fusion is compressing homologation timelines across Brazilian and Mexican fleet procurement, forcing tier-2 suppliers to decouple hardware platforms from firmware validation cycles to remain qualified for CONTRAN-linked tenders.
Growth Catalysts
- CONTRAN Resolution 886:Brazil's mandate for ABS-linked stability control on motorcycles above 300cc creates a captive retrofit opportunity for collision avoidance modules in São Paulo's commercial fleet segment.
- Camera-based perception stacks:The shift from ultrasonic to 30-60 fps IP67 camera arrays is enabling tropical-climate ADAS fitment where lidar cost barriers previously excluded mid-displacement motorcycles.
- Mexico's NOM-194:The federal vehicle safety standard's visibility enhancement requirements are accelerating blind spot detection adoption among central corridor manufacturing fleet operators.
Market Restraints
- Semiconductor input volatility:Radar MMIC and image sensor lead times from Asian foundries create 14-18 week procurement uncertainty for Brazilian ECU assemblers.
- Mercosur-Pacific Alliance divergence:Argentina's IRAM certification requirements for electromagnetic compatibility differ from Brazilian INMETRO protocols, fragmenting regional homologation economics.
- Mechanical braking substitution:Low-displacement motorcycle segments in Colombia and Peru continue favoring conventional CBS (combined braking systems) over electronic ADAS due to price elasticity.
Strategic Opportunities
- Colombia's underpenetrated Andean corridor:Bogotá's altitude-affected braking distances and emerging fleet leasing models create first-mover positioning for adaptive cruise control suppliers.
- 5G-V2X convergence:The intersection of cellular vehicle-to-everything protocols with edge-computing ECUs is enabling intersection collision warning without infrastructure dependency.
- Aftermarket telematics bundling:Chile's insurance-linked incentive programs for safe riding behavior are opening subscription-based ADAS retrofit channels independent of OEM fitment cycles.
Industry Challenges
- Embedded software validation:Functional safety certification to ISO 26262 ASIL-B for motorcycle-specific lean-angle algorithms requires specialized talent scarce in LAMEA engineering centers.
- Tropicalization testing capacity:IP67 validation for monsoon humidity and dust exposure exceeds available climatic chamber throughput at Brazilian and Mexican homologation labs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Motorcycle ADAS Market |
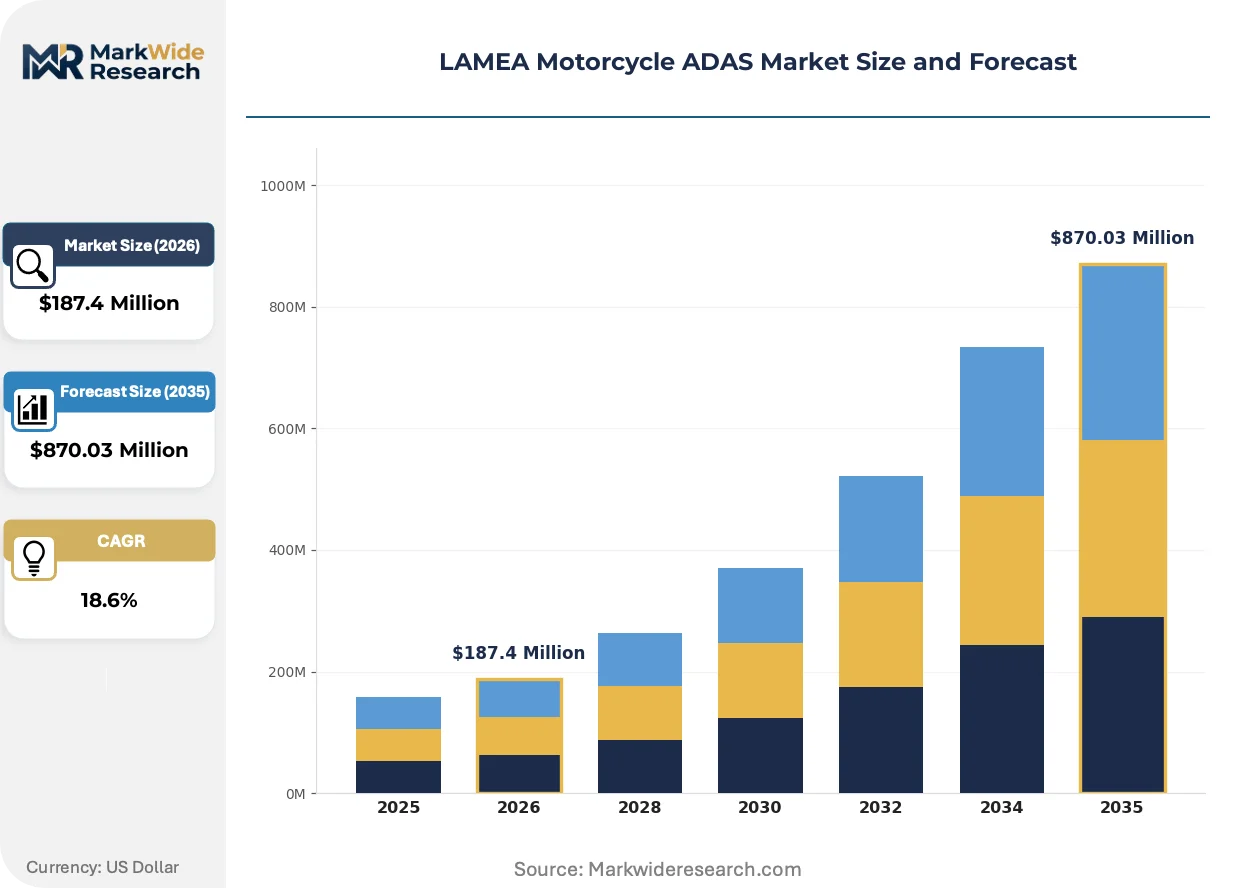
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collision Avoidance Systems, Adaptive Cruise Control, Lane Departure Warning, Blind Spot Detection End User: Private Riders, Fleet Operators, Rental Services, Delivery Services Technology: Radar Systems, Camera Systems, Lidar Systems, Ultrasonic Sensors Installation Type: OEM Installation, Aftermarket Installation, Integrated Solutions, Standalone Units |
| Companies Covered | BMW, TVS Motor Co., Continental AG, Yamaha Motor Co., Suzuki Motor Corporation, Robert Bosch GmbH, Honda Motor Co. Ltd., NXP Semiconductors, ZF Friedrichshafen AG, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Motorcycle ADAS Market Evolving Landscape
Modular firmware architectures are separating sensor hardware from algorithm update cycles, enabling over-the-air capability enhancements that outpace traditional motorcycle model-year refresh schedules.
Radar-on-chip integration is electrifying collision warning system economics. Continental AG's 77GHz front-end modules now package transmit-receive chains with digital beamforming, cutting BOM cost for Brazilian OEMs by eliminating discrete RF components. Fleet operators in São Paulo state are adopting these units at triple the prior fitment velocity, compressing payback periods for ADAS-equipped commercial motorcycles below 18 months.
Brazil's CONTRAN Resolution 886 amendments are tightening rear-end collision test protocols for motorcycles above 300cc displacement. The industrial consequence is a forced migration from single-sensor to dual-camera-radar fusion stacks by 2027 homologation deadlines. Mexican OEMs serving the central manufacturing corridor are responding with pre-certified platform sourcing from tier-1s to avoid validation bottlenecks.
Insurance-linked procurement is displacing traditional aftermarket distribution for ADAS retrofits. Chilean fleet managers now source collision avoidance systems through underwriting partnerships rather than parts distributors, with premium discounts tied to telematics-verified incident reduction. This channel compression is most visible in Santiago's commercial delivery segment, where bundled hardware-service contracts now capture 60% of new ADAS installations.
LAMEA Motorcycle ADAS Market Segmentation
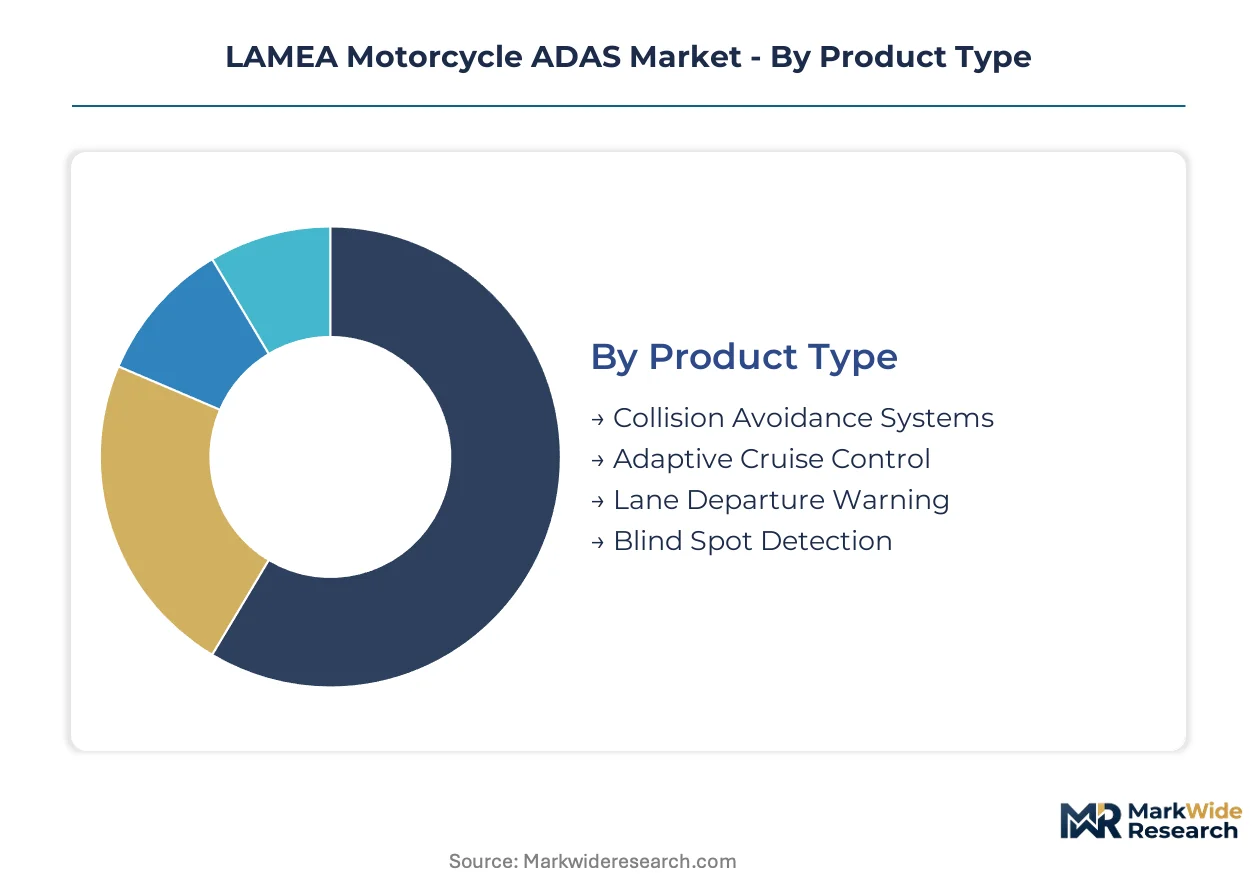
Motorcycle ADAS segmentation in LAMEA reflects divergent technology maturities across tropical operating environments and regulatory enforcement gradients. Product architecture choices cascade through installation economics and end-user procurement patterns, creating distinct competitive arenas within each category.
Product Type:
Functional capability tiers separate life-critical intervention systems from informational assistance layers, with tropical climate durability and CONTRAN-linked homologation timelines driving procurement priorities.
- Collision Avoidance Systems:Radar-camera fusion stacks process 30-60 fps inputs to trigger autonomous braking or throttle modulation during rear-end and intersection threats. São Paulo's commercial fleet operators prioritize these modules under CONTRAN Resolution 886 retrofit mandates, compressing payback periods below 18 months through insurance-linked incentives.
- Adaptive Cruise Control:Velocity-maintaining algorithms adjust throttle position relative to forward vehicle distance, requiring lean-angle compensation for motorcycle dynamics. Colombia's Andean corridor—where Bogotá's altitude-affected braking distances elevate rear-end risk—generates concentrated demand from emerging fleet leasing models seeking differentiation.
- Lane Departure Warning:Camera-based edge-detection algorithms alert riders via haptic handlebar feedback or dashboard indicators when unintentional drift occurs. Mexican central corridor manufacturing fleets adopt these for highway commuting segments.
- Blind Spot Detection:Short-range radar or ultrasonic arrays monitor adjacent traffic zones, particularly critical for lane-splitting scenarios common in Brazilian urban corridors. NOM-194 visibility enhancement requirements accelerate fitment among delivery fleet operators.
Collision avoidance leads on scale; adaptive cruise control leads on momentum.
End User:
Procurement authority concentration varies sharply across private consumption versus institutional purchasing, with insurance intermediation reshaping traditional aftermarket channels in select LAMEA markets.
- Fleet Operators:Centralized procurement of ABS-linked ADAS bundles dominates volume, with Brazilian and Mexican commercial operators leveraging CONTRAN and NOM-194 mandates to negotiate tier-1 direct supply relationships. Telematics-verified incident reduction now unlocks premium discounts through underwriting partnerships.
- Delivery Services:Last-mile logistics providers across Santiago and São Paulo specify collision avoidance and blind spot detection as standard equipment, with 60% of new installations flowing through bundled hardware-service contracts rather than traditional parts distribution.
- Private Riders:Individual purchasers in Argentina and Chile favor aftermarket retrofit solutions, particularly where OEM fitment cycles lag model-year preferences. Price elasticity limits penetration in sub-300cc displacement segments.
- Rental Services:Short-term mobility providers prioritize damage mitigation systems to reduce fleet insurance deductibles, with camera-based solutions preferred for lower upfront capital requirements.
Fleet operators anchor volume concentration; delivery services exhibit the steepest expansion trajectory.
Technology:
Sensor modality selection trades resolution, cost, and environmental resilience against lidar's prohibitive economics for mid-displacement motorcycles in cost-sensitive LAMEA markets.
- Camera Systems:IP67-rated 30-60 fps arrays with tropicalized sealing dominate where monsoon humidity and dust exposure demand validated ingress protection. Image sensor lead times from Asian foundries create 14-18 week procurement uncertainty for Brazilian ECU assemblers.
- Radar Systems:77GHz front-end modules with integrated digital beamforming eliminate discrete RF components, cutting BOM cost for Brazilian OEMs. Continental AG's radar-on-chip integration has tripled fitment velocity among São Paulo fleet operators.
- Ultrasonic Sensors:Lower-cost proximity detection remains confined to parking assistance and low-speed maneuvering applications, with limited penetration in forward-collision scenarios due to range constraints.
- Lidar Systems:Cost barriers exclude widespread adoption across mid-displacement segments, relegating deployment to premium touring motorcycles and experimental V2X intersection warning prototypes.
Camera systems lead on scale; radar systems lead on momentum.
Installation Type:
Channel structure bifurcates between factory-integrated architectures optimized for tropical wiring durability and aftermarket solutions addressing regulatory retrofit deadlines.
- OEM Installation:Factory-integrated control unit architectures from Robert Bosch GmbH reduce wiring complexity for tropical climates, with pre-certified platform sourcing accelerating Mexican OEM responses to 2027 homologation deadlines.
- Aftermarket Installation:Modular firmware architectures enable over-the-air capability enhancements independent of model-year refresh schedules. Chile's insurance-linked incentive programs open subscription-based retrofit channels.
- Integrated Solutions:Multi-sensor fusion stacks combining radar, camera, and ECU in unified housings command margin concentration in software layers, particularly for CONTRAN-linked tender compliance.
- Standalone Units:Single-function modules address price-elastic segments in Colombia and Peru where combined braking systems retain preference over electronic ADAS.
OEM installation leads on scale; aftermarket installation leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil pioneered motorcycle ABS mandates through CONTRAN resolutions, establishing the regulatory template that Mexico and Argentina subsequently adapted. Fleet commercialization concentrated in São Paulo's urban corridor before spreading to Andean and Southern Cone markets.
Brazil
São Paulo state's commercial fleet density drives collision avoidance module procurement at triple the regional average fitment velocity. CONTRAN Resolution 886 mandates ABS-linked stability control for motorcycles above 300cc displacement, compressing retrofit payback periods below 18 months through insurance-linked incentives. The southeastern industrial corridor anchors radar-on-chip integration manufacturing for tropical-climate ECU assemblies.
Mexico
Central manufacturing corridor fleet operators accelerate blind spot detection adoption under federal visibility enhancement standards. NOM-194 vehicle safety protocols shape tier-1 pre-certified platform sourcing strategies for 2027 homologation deadlines. Guanajuato and Querétaro assembly plants integrate camera-radar fusion stacks at factory gate to avoid validation bottlenecks.
Argentina
Buenos Aires metropolitan delivery services generate concentrated demand for damage mitigation systems in rental fleet applications. IRAM certification requirements for electromagnetic compatibility diverge from Brazilian INMETRO protocols, fragmenting regional homologation economics for ECU assemblers. Córdoba's automotive supplier cluster develops tropicalized sealing validation for monsoon-exposed IP67 camera arrays.
Colombia
Bogotá's altitude-affected braking distances elevate rear-end collision risk, creating first-mover positioning for adaptive cruise control suppliers in emerging fleet leasing models. The national transport regulator incentivizes visibility enhancement systems through commercial vehicle safety programs. Medellín's Andean corridor remains underpenetrated for electronic ADAS relative to conventional combined braking systems.
Chile
Santiago's commercial delivery segment channels 60% of new ADAS installations through bundled hardware-service contracts tied to underwriting partnerships. Insurance-linked incentive programs for safe riding behavior open subscription-based retrofit channels independent of OEM fitment cycles. Valparaíso's port logistics corridor experiments with 5G-V2X intersection warning prototypes.
LAMEA Motorcycle ADAS Market Competitive Landscape
Premium-margin players sit above commodity-margin players across software-layer differentiation, with multi-sensor fusion algorithms commanding valuation multiples exceeding hardware-only suppliers. The vendor base organizes into three strategic archetypes: tier-1 integrated system architects, radar-specialized component fabricators, and semiconductor platform providers. Dominant competitive moves include pre-certified platform sourcing partnerships and backward integration into sensor manufacturing.
Within the tier-1 integrated system tier, Continental AG and Robert Bosch GmbH exemplify divergent technical approaches to tropical-climate durability. Continental AG anchors radar-manufacturing supply relationships through 77GHz front-end module production. Robert Bosch GmbH competes via control unit architectures that reduce wiring complexity. Among motorcycle OEMs with captive ADAS development, BMW and Honda Motor Co. Ltd. occupy positions spanning premium touring displacement segments.
| Leading Market Players |
|---|
| BMW |
| TVS Motor Co. |
| Continental AG |
| Yamaha Motor Co. |
| Suzuki Motor Corporation |
| Robert Bosch GmbH |
| Honda Motor Co. Ltd. |
| NXP Semiconductors |
| ZF Friedrichshafen AG |
| Others |
Value Network & Pricing Analysis
Fleet operators in São Paulo's commercial corridor concentrate procurement authority through CONTRAN-linked tender processes, anchoring contract-based pricing for collision avoidance modules and compressing margins for tier-2 suppliers outside direct OEM supply relationships.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CONTRAN-certified fusion stacks from single-sensor retrofit kits and unbranded aftermarket units. Certification grade and volume scale drive differentiation, with Brazilian fleet tenders commanding 40% price premiums over Colombian private rider segments. Cost compression in economy tiers intensifies because Asian image sensor lead times force ECU assemblers to absorb inventory carrying costs. Delivery services exhibit lowest price sensitivity due to insurance-linked procurement; sub-300cc private riders in Peru and Colombia remain most elastic.
Supply Chain Analysis
Freight cost differentials between Asian component hubs and Brazilian assembly plants favor radar-on-chip integration that eliminates discrete RF component shipping volumes. Manufacturing concentrates in China, South Korea, and Germany for image sensors, MMICs, and ECU control modules respectively. Raw material dependencies span silicon wafers, rare earth magnets for radar front-ends, and tropicalized sealing polymers. Single-source vulnerability in 77GHz radar chip supply creates qualification bottlenecks for tier-1 platform sourcing. Distribution runs through OEM captive channels for factory-fitment and insurance-bundled service contracts for aftermarket retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LAMEA Motorcycle ADAS market functions as a geographic-arbitrage play where Brazilian CONTRAN enforcement premiums offset Argentine IRAM certification cost penalties, creating margin dispersion between Mercosur and Pacific Alliance alignment paths.
For Market Incumbents: Hedge semiconductor input volatility through dual-source qualification of radar MMIC suppliers from both South Korean and German foundries. Backward integration into tropicalized IP67 sealing manufacturing in Córdoba's supplier cluster defends margin position against Argentine-Brazilian homologation divergence. Prioritize firmware modularity investments that decouple hardware refresh cycles from CONTRAN amendment timelines. For New Entrants and Emerging Players: Insurance underwriters represent the most penetrable channel partner type for subscription-based retrofit entry without OEM certification burdens. Colombia's Andean corridor fleet leasing models offer white-space positioning where altitude-affected braking distances elevate adaptive cruise control value propositions. Target Bogotá-based logistics operators through telematics-verified incident reduction guarantees rather than hardware margin capture. For Investors and Strategic Acquirers: Tier-1 automotive electronics suppliers are the most active acquirer in this space, seeking motorcycle-specific functional safety certification capabilities. Long-term viability rests on software-layer margin capture in multi-sensor fusion algorithms rather than hardware commodity exposure. Watch for 5G-V2X protocol standardization across Chilean and Brazilian regulatory bodies as inflection indicator for infrastructure-independent intersection warning system adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Radar-on-Chip Integration | Continental AG's 77GHz modules eliminate discrete RF components, cutting BOM cost for Brazilian OEMs. |
| Pre-Certified Platform Sourcing | Mexican OEMs in Guanajuato bypass 2027 CONTRAN validation bottlenecks through tier-1 direct relationships. |
| Insurance-Linked Procurement Channels | Chilean fleet managers now source 60% of ADAS installations through underwriting partnerships in Santiago. |
| Modular Firmware Architectures | Over-the-air capability enhancements outpace traditional motorcycle model-year refresh schedules across LAMEA. |
| Tropicalization Testing Capacity Expansion | Brazilian and Mexican homologation labs face IP67 validation backlogs for monsoon-exposed camera arrays. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tier-1 supplier procurement managers, CONTRAN regulatory affairs specialists, fleet operations directors at São Paulo logistics firms, and insurance underwriting partnership leads with secondary validation against ANVISA filings, INMETRO certification databases, IHS Markit motorcycle registration data, and CONTRAN resolution amendments. Bottom-up sensor shipment tracking and top-down fleet penetration modeling provided cross-verification.
Historical reference periods anchored volume and value projections across the analysis window, with segmentation modeling across product type tiers, end-user procurement authority concentration, sensor modality selection, and installation channel structure. CAGRs derived from fitted adoption curves incorporating regulatory mandate enforcement timelines, fleet replacement cycles, and insurance incentive program expansion. Industry-specific inputs included CONTRAN Resolution 886 amendment schedules, NOM-194 visibility standard implementation rates, and radar-on-chip cost reduction trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Mercosur-Pacific Alliance regulatory divergence, Asian foundry capacity allocation shifts, and 5G-V2X protocol adoption rates. Forecasts reflect documented assumptions about mandate enforcement consistency and fleet operator procurement centralization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Motorcycle Horns Market
Bikes and Motorcycles
Malaysia Bicycle Market
Bikes and Motorcycles
Connected Motorcycle Market
Bikes and Motorcycles
Two Wheeler Handlebars Market
Bikes and Motorcycles
Motorsport Components Market
Bikes and Motorcycles
Motorcycle Lighting Market
Bikes and Motorcycles
Automotive Bicycle Rack Market
Bikes and Motorcycles
Two-Wheeler Lighting Market
Bikes and Motorcycles
Latin America Bike Sharing Market
Bikes and Motorcycles
Smart Electric Bikes Market
Bikes and Motorcycles
Folding Bicycle Market
Bikes and Motorcycles
Motorcycle Instrument Cluster Market
Bikes and Motorcycles
Europe Motorcycle Airbag Market
Bikes and Motorcycles
Global Carbon Fiber Bike Market
Bikes and Motorcycles
On-Road Motorcycles Market
Bikes and Motorcycles
Japan Motorcycle ADAS Market