
 South America Two-Wheeler Market | 2026-2036
South America Two-Wheeler Market Size, Share, and Industry Trends Forecast 2026-2036
South America Two-Wheeler Market Insights
PROCONVE Phase L7 is pivoting the cost-of-entry calculus for internal combustion two-wheelers across Brazil, forcing manufacturers to retool engine management systems and catalytic converter specifications. Honda Motor Co. Ltd. leverages its dedicated Brazilian R&D center to localize fuel-injection platforms ahead of enforcement timelines. Yamaha Motor Co. Ltd. sustains competitive pressure through its Manaus free-trade-zone assembly operations that compress landed costs for Andean markets. Bajaj Auto Ltd. anchors its South America footprint through aggressive distributor partnerships in Colombia and Peru, competing on total cost of ownership for commercial fleet operators.
Two-wheelers denote motorized vehicles with two inline wheels powered by internal combustion engines or electric motors, typically featuring tubular steel frames, telescopic front forks, and chain or belt final-drive systems rated for payloads between 150 and 300 kilograms. These vehicles serve primarily as affordable individual mobility and light-cargo transport across dense urban corridors and underdeveloped rural road networks. The engine capacity dimension shows 100cc-150cc motorcycles commanding the dominant volume share due to their optimal balance of fuel efficiency and load-bearing capacity for delivery applications. Electric scooters represent the fastest-expanding fuel type segment as municipal zero-emission zones proliferate in Santiago, Bogotá, and São Paulo. Retail stores and authorized dealerships together occupy the principal distribution channel, though online sales are gaining traction for replacement parts and accessories.
Brazil's PROCONVE program and Colombia's Resolution 1111 establish divergent but equally stringent emission certification pathways that manufacturers must navigate for market access. ANVISA in Brazil and the Ministry of Transport in Argentina impose separate homologation requirements for lighting, braking, and noise standards that extend product development cycles by four to eight months. Stakeholders must monitor how Chile's electromobility strategy and Peru's biofuel blending mandates reshape powertrain investment priorities before committing to regional platform architectures.
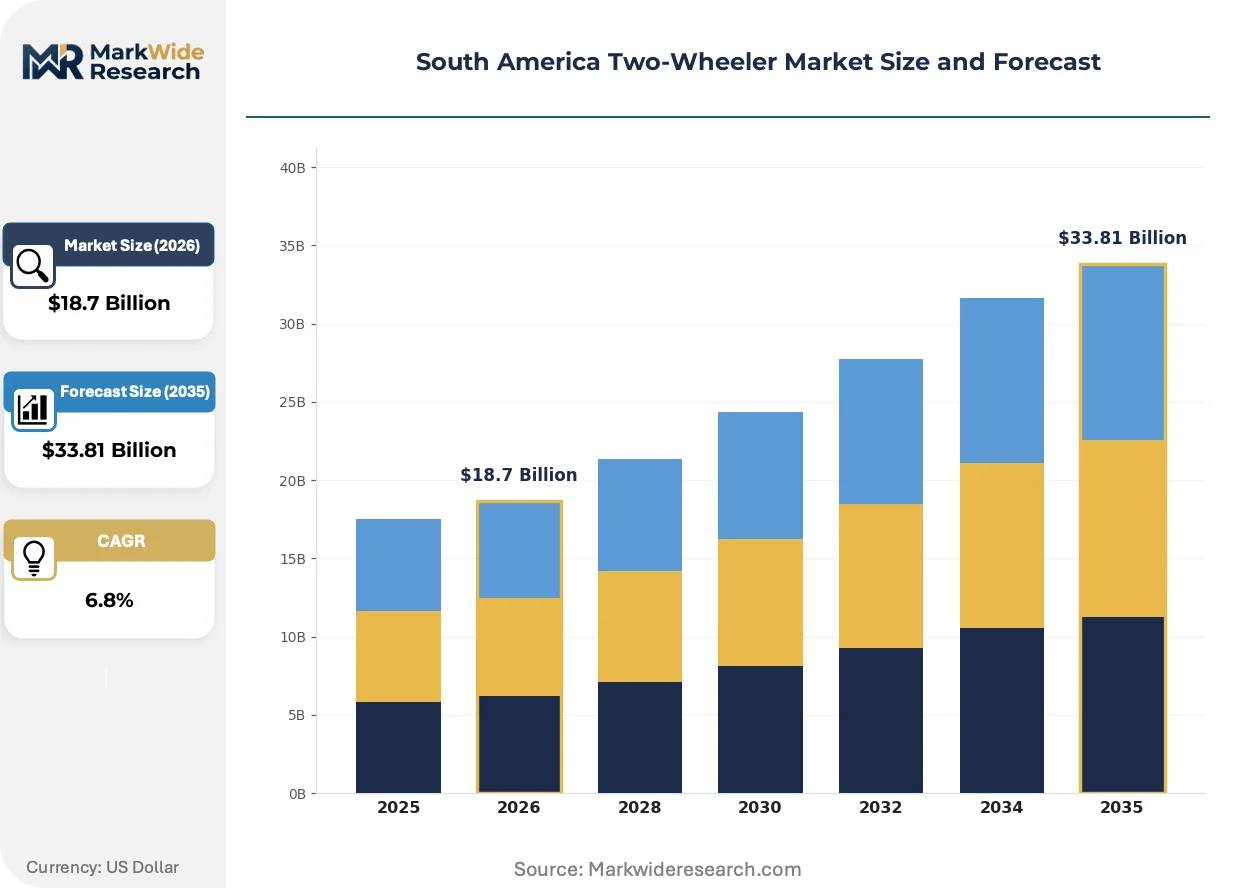
Market Dynamics
PROCONVE Phase L7 is compressing the competitive set for internal combustion two-wheelers across Brazil, forcing engine management system redesigns and catalytic converter upgrades before enforcement deadlines hit.
Growth Catalysts
- Urban congestion:Last-mile delivery fleets in São Paulo and Bogotá are expanding motorcycle procurement as traffic bottlenecks worsen and parking scarcity intensifies for four-wheel commercial vehicles.
- Resolution 1111:Colombia's emission certification pathway is accelerating fuel-injection adoption among Andean assemblers seeking preemptive compliance ahead of neighboring regulatory harmonization.
- Electric powertrains:Municipal zero-emission zones in Santiago and São Paulo are pulling lithium-ion scooter deployment into commercial fleet rotation ahead of consumer adoption curves.
Market Restraints
- Import duty volatility:Argentina's foreign exchange controls and Brazil's industrialized product tax (IPI) fluctuations are compressing margin predictability for Manaus-assembled units crossing borders.
- Semiconductor dependency:Fuel-injection module sourcing concentrates among East Asian foundries, exposing Brazilian and Colombian assemblers to lead-time volatility absent local MEMS fabrication.
- Lead-acid battery substitution:Swappable lithium-ion packs for electric scooters threaten traditional battery aftermarket revenue streams for established dealer networks.
Strategic Opportunities
- Peru's northern corridor:Trujillo and Chiclayo present underpenetrated fleet demand where informal logistics operators still rely on three-wheel conversions rather than purpose-built cargo motorcycles.
- Biofuel blending mandates:Peru's ethanol-gasoline blending requirements create a regulatory tailwind for flex-fuel two-wheeler development distinct from Brazil's pure-gasoline or full-electric pathways.
- Direct-to-fleet sales:Bypassing dealer networks for large delivery contracts is compressing customer acquisition costs for commercial motorcycle lessors targeting Mercado Libre and Rappi operators.
Industry Challenges
- Homologation timeline compression:ANVISA lighting and braking certification cycles now extend product launches by four to eight months, forcing parallel-track development against PROCONVE engine compliance.
- Powertrain platform fragmentation:Simultaneous investment in carburetor-to-fuel-injection transitions, flex-fuel adaptations, and electric architectures is diluting R&D bandwidth across South American engineering centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Two-Wheeler Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scooters, Motorcycles, E-Bikes, Mopeds Engine Capacity: Below 100cc, 100cc-150cc, 150cc-250cc, Above 250cc Fuel Type: Petrol, Diesel, Electric, Hybrid Distribution Channel: Retail Stores, Online Sales, Authorized Dealerships, Others |
| Companies Covered | Honda Motor Co. Ltd., Yamaha Motor Co. Ltd., Bajaj Auto Ltd., Suzuki Motor Corporation, Hero MotoCorp Ltd., Motomel S.A., Dafra Motos, Italika, Shineray Do Brasil SA, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Two-Wheeler Market Trends and Innovations
Battery-swapping infrastructure is rewiring the economics of electric two-wheeler ownership across Andean capitals, separating vehicle purchase from energy procurement in ways that favor fleet operators over individual consumers.
Modular lithium-ion pack architectures are decentralizing charging infrastructure investment away from grid-dependent stations toward distributed battery exchange cabinets. Rappi and iFood delivery cooperatives in São Paulo are adopting swap-to-continue models that eliminate dwell time. This topology is compressing total cost of ownership calculations for electric scooters against their internal combustion equivalents.
Brazil's PROCONVE Phase L7 tailpipe standards are forcing simultaneous fuel-injection and catalytic converter upgrades for all new internal combustion motorcycles above 150cc. The industrial consequence is a bifurcation of product portfolios: premium fuel-injection platforms for southeastern Brazil versus carburetor holdovers for Paraguay and Bolivia re-export markets. Manufacturers with dedicated Brazilian R&D facilities are responding faster than import-dependent competitors.
Fleet procurement departments are consolidating vendor relationships around total cost of ownership metrics rather than sticker price, unbundling maintenance and battery replacement from upfront vehicle acquisition. Large logistics operators in Colombia now negotiate three-year service-inclusive contracts directly with assemblers, bypassing traditional dealer intermediaries. This behavior is most visible in Bogotá's urban delivery corridor where congestion charges on four-wheel vehicles have accelerated two-wheeler fleet rotation.
South America Two-Wheeler Market Segmentation
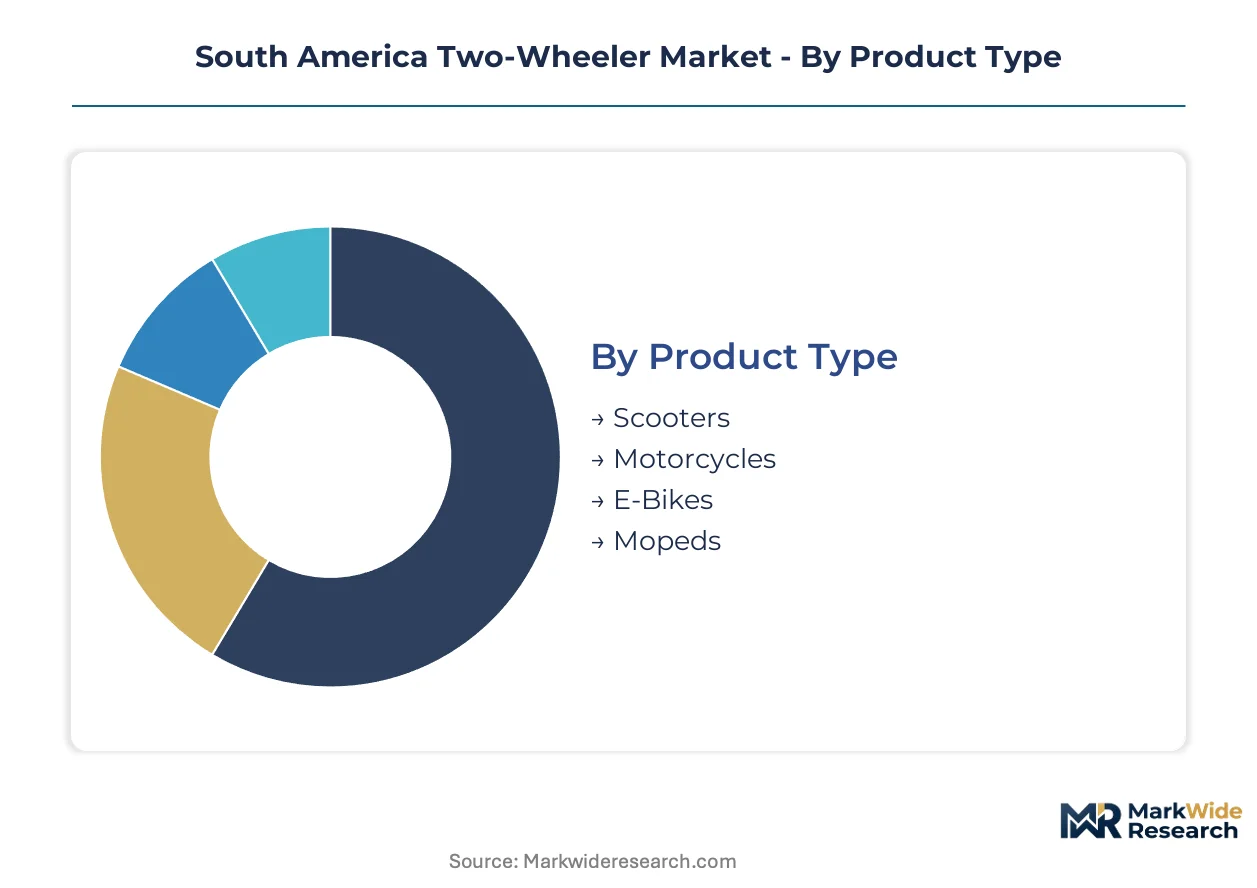
Segmentation in South America tracks how PROCONVE Phase L7 and Resolution 1111 are splitting procurement patterns between compliance-ready fuel-injection platforms and legacy carburetor holdovers. Fleet operators and individual buyers now navigate divergent upgrade cycles across Brazil's southeastern corridor and Colombia's Andean markets.
Product Type:
Replacement-cycle timing varies sharply across vehicle categories as commercial fleets rotate assets faster than individual owners.
- Motorcycles:Tubular steel frames with chain final-drive systems rated for 150-300 kilogram payloads dominate last-mile delivery procurement in São Paulo and Bogotá. Brazil's PROCONVE Phase L7 is compressing carburetor-to-fuel-injection transitions specifically for this segment as enforcement deadlines approach.
- Scooters:Step-through architectures with automatic transmissions concentrate urban commuter demand in Rio de Janeiro and Lima, where parking scarcity and stop-and-go congestion favor compact footprints over load capacity.
- E-Bikes:Pedal-assist electric bicycles with sub-750 watt motors serve informal logistics corridors in Peru's northern cities where three-wheel conversions still outnumber purpose-built cargo vehicles.
- Mopeds:Low-displacement units with speed limiters face declining placement as Brazil's emission standards eliminate the cost advantage of simplified engine management systems.
Volume placements concentrate in Motorcycles; the faster expansion belongs to Scooters.
Engine Capacity:
Cost-tier stratification separates premium fuel-injection platforms from economy carburetor holdovers across Brazilian state markets.
- 100cc-150cc:Single-cylinder air-cooled engines balancing fuel efficiency against load-bearing capacity anchor commercial fleet procurement for Mercado Libre and Rappi operators. This bracket captures the dominant share of Colombia's Resolution 1111 pre-compliance purchasing.
- Below 100cc:Ultra-compact powertrains with minimal catalytic converter requirements persist in Bolivia and Paraguay re-export channels as Brazilian manufacturers bifurcate portfolios around PROCONVE enforcement.
- 150cc-250cc:Liquid-cooled variants with enhanced thermal management serve long-distance courier routes spanning Brazil's southeastern industrial corridor.
- Above 250cc:Multi-cylinder configurations with sophisticated engine management systems concentrate premium consumer demand in São Paulo and Buenos Aires urban centers.
The 100cc-150cc bracket anchors procurement volume; 150cc-250cc platforms are climbing the fastest as fleet operators upsize for cargo density.
Fuel Type:
Application-driven divergence separates municipal zero-emission mandates from commercial range requirements across Andean capitals.
- Electric:Lithium-ion powertrains with swappable battery architectures are gaining share fastest in Santiago and São Paulo, where congestion charges on four-wheel vehicles pull fleet rotation toward two-wheel alternatives. Battery-swapping infrastructure from Rappi and iFood cooperatives eliminates dwell-time penalties.
- Petrol:Gasoline-powered internal combustion engines with port fuel injection now dominate Brazilian compliance-ready procurement as PROCONVE Phase L7 eliminates carburetor pathways.
- Diesel:Compression-ignition variants remain marginal, limited to specialized agricultural and rural freight applications in Argentina's Pampas region.
- Hybrid:Series-hybrid architectures with small displacement range extenders represent experimental placements in Chile's electromobility strategy pilot zones.
Petrol platforms retain volume dominance; Electric powertrains show the steepest expansion trajectory as swap-to-continue models compress total cost of ownership.
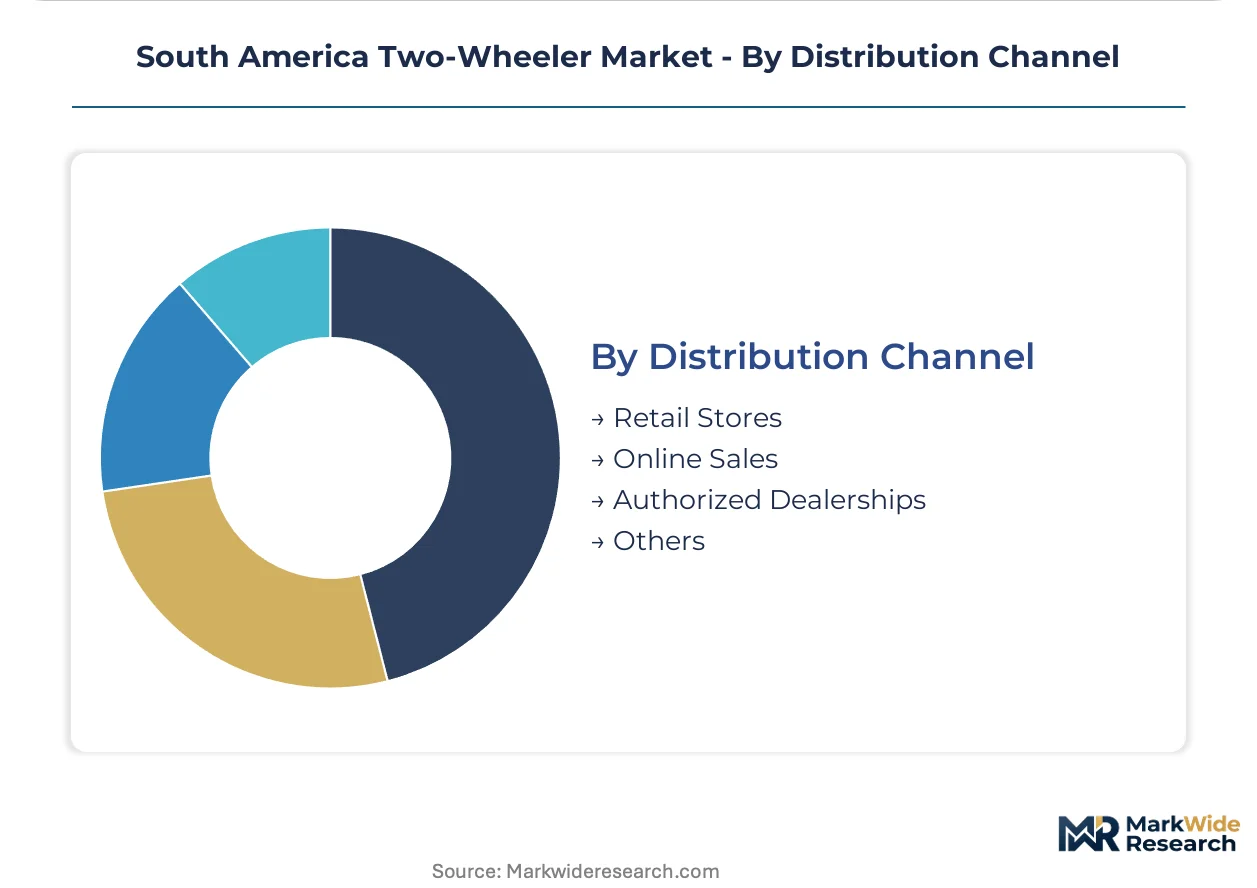
Distribution Channel:
Customer-type stratification separates direct fleet negotiations from individual retail purchasing across South American markets.
- Authorized Dealerships:Manufacturer-certified service networks with ANVISA homologation support concentrate warranty-backed sales in Brazil's southeastern states, where extended product development cycles demand compliant documentation.
- Retail Stores:Independent motorcycle shops with parts-and-service bundling dominate replacement-cycle purchasing in Colombia's secondary cities.
- Online Sales:Digital platforms for replacement parts and accessories are compressing customer acquisition costs for established dealer networks facing swappable battery aftermarket threats.
- Others:Direct-to-fleet contracting bypasses traditional intermediaries for large delivery operators negotiating three-year service-inclusive agreements in Bogotá's urban corridor.
Authorized Dealerships anchor volume placements; Online Sales channels are expanding most quickly for aftermarket components.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manaus Free Trade Zone incentives concentrate assembly operations for Brazilian domestic supply and Andean re-export markets, drawing fuel-injection retooling investments ahead of PROCONVE Phase L7 enforcement timelines.
Brazil
Last-mile delivery fleets in São Paulo and Rio de Janeiro are accelerating motorcycle procurement as urban congestion charges on four-wheel commercial vehicles intensify. ANVISA homologation requirements for lighting and braking systems extend product development cycles by four to eight months. The southeastern industrial corridor spanning São Paulo, Minas Gerais, and Rio de Janeiro states anchors volume demand for 100cc-150cc fuel-injection platforms.
Colombia
Bogotá's urban delivery cooperatives are consolidating vendor relationships around total cost of ownership metrics for three-year service-inclusive contracts. Resolution 1111 emission certification pathways are accelerating fuel-injection adoption among Andean assemblers seeking preemptive compliance. Medellín and Cali secondary markets concentrate replacement-cycle purchasing through independent retail shops with parts-and-service bundling.
Argentina
Foreign exchange controls are compressing margin predictability for Manaus-assembled units crossing borders from Brazil. The Ministry of Transport imposes separate homologation requirements that parallel ANVISA timelines. Buenos Aires urban centers concentrate premium consumer demand for multi-cylinder configurations above 250cc.
Chile
Municipal zero-emission zones in Santiago are pulling lithium-ion scooter deployment into commercial fleet rotation ahead of consumer adoption curves. The national electromobility strategy creates pilot zones for series-hybrid architectures with small displacement range extenders. Battery-swapping infrastructure from delivery cooperatives eliminates dwell-time penalties for Rappi and iFood operators.
Peru
Ethanol-gasoline blending mandates create regulatory tailwinds for flex-fuel two-wheeler development distinct from Brazil's pure-gasoline or full-electric pathways. Trujillo and Chiclayo present underpenetrated fleet demand where informal logistics operators still rely on three-wheel conversions. The northern corridor lacks purpose-built cargo motorcycle distribution networks.
South America Two-Wheeler Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the South American two-wheeler market, creating a tiered structure where scale-driven assemblers with captive R&D facilities hold cost advantages over import-dependent distributors. Market concentration is moderate, with the top tier commanding significant share through localized production while mid-tier players rely on regional distributor partnerships. Two strategic archetypes dominate: multinational manufacturers with dedicated Brazilian engineering centers, and regional assemblers leveraging free-trade-zone cost structures. Competitive moves center on fuel-injection platform localization and direct-to-fleet contracting that bypasses traditional dealer intermediaries.
Among Japanese-origin conglomerates, Honda Motor Co. Ltd. and Yamaha Motor Co. Ltd. exemplify the R&D-anchored archetype through dedicated Brazilian facilities and Manaus free-trade-zone operations respectively. Bajaj Auto Ltd. represents the distributor-partnership model, anchoring Andean market access through aggressive commercial relationships in Colombia and Peru. These three players illustrate how geographic origin and operational structure shape competitive positioning across PROCONVE and Resolution 1111 compliance environments.
| Leading Market Players |
|---|
| Honda Motor Co. Ltd. |
| Yamaha Motor Co. Ltd. |
| Bajaj Auto Ltd. |
| Suzuki Motor Corporation |
| Hero MotoCorp Ltd. |
| Motomel S.A. |
| Dafra Motos |
| Italika |
| Shineray Do Brasil SA |
| Others |
Pricing and Supply Chain Analysis
Lithium-ion cell costs cascade through South American two-wheeler pricing tiers, with fuel-injection module premiums compressing margins for carburetor holdovers in Paraguay and Bolivia re-export channels while electric scooter lease rates undercut ownership economics in São Paulo's zero-emission zones.
Pricing Analysis
Lead-time premiums for fuel-injection platforms with ANVISA homologation documentation command pricing advantages over spot carburetor inventory facing PROCONVE Phase L7 obsolescence. Three-tier pricing structure across premium fuel-injection, standard flex-fuel, and economy carburetor levels separates compliance-ready Brazilian domestic sales from Andean re-export arbitrage. Pricing pressure stems from semiconductor sourcing volatility in East Asian foundries. Fleet operators negotiating direct-to-assembler contracts show least price sensitivity; individual retail buyers in Colombia's secondary markets exhibit highest elasticity.
Supply Chain Analysis
Regional distribution centers in Manaus Free Trade Zone anchor hub-and-spoke patterns radiating toward São Paulo, Bogotá, and Buenos Aires metropolitan corridors. Manufacturing concentrates in Brazil, China, and India; component sourcing draws from Taiwanese semiconductor foundries and Japanese precision engineering suppliers. Raw material dependencies span lithium carbonate, rare-earth magnets, and catalytic converter substrates. Single-source vulnerability in fuel-injection MEMS fabrication exposes Brazilian assemblers to lead-time volatility. Distribution runs through authorized dealership networks with ANVISA certification support, though direct-to-fleet contracting is gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
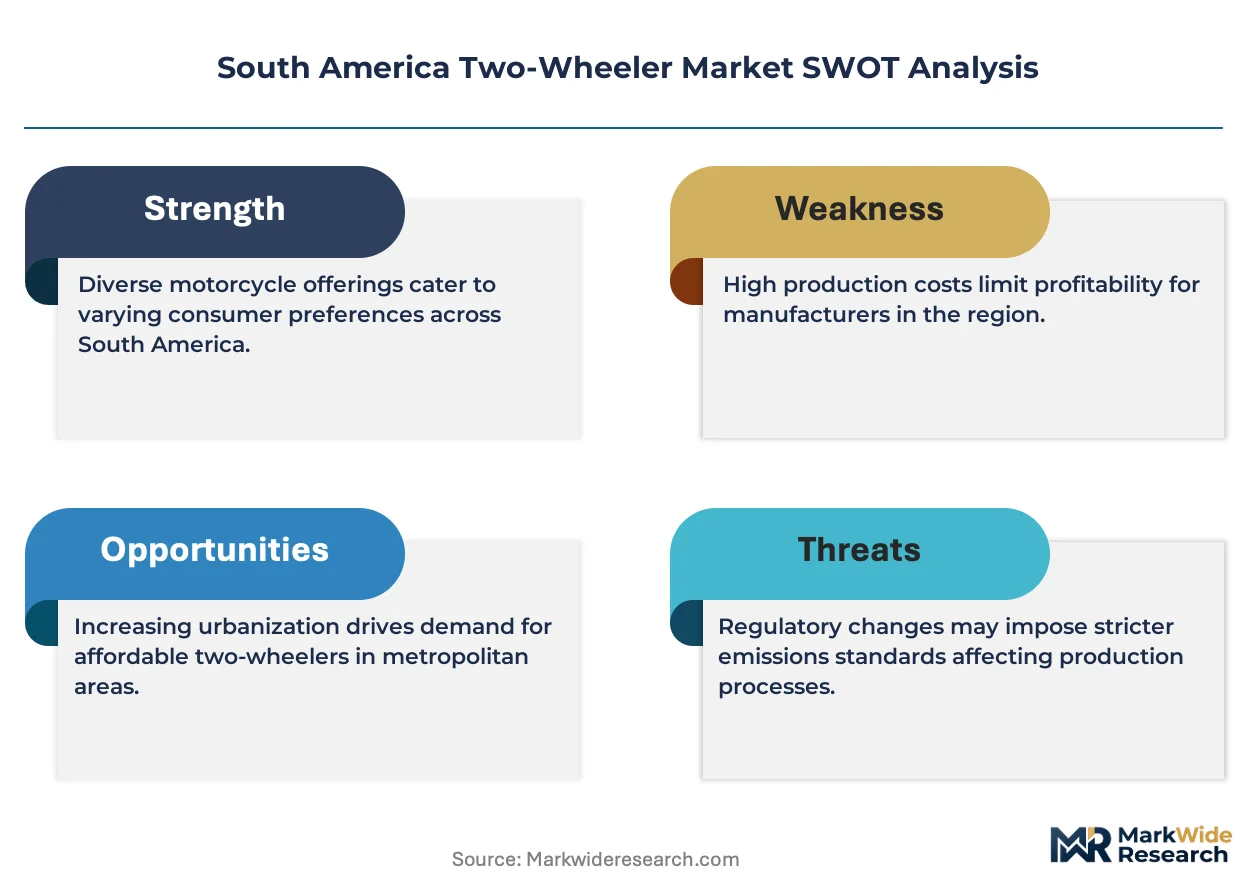
This market is a vertical-integration race: captive control over fuel-injection platform development and battery-swapping infrastructure deployment separates consolidators from margin-compressed assemblers dependent on third-party component sourcing.
For Market Incumbents: Anchor defensive positioning through backward integration into catalytic converter substrate supply and captive R&D facilities in Brazil's southeastern industrial corridor. Threat substitution from electric powertrains with swappable battery architectures demands preemptive fleet partnership lock-in. Prioritize ANVISA homologation pipeline acceleration to compress four-to-eight-month certification cycles. For New Entrants and Emerging Players: Begin with Peru's northern corridor logistics markets in Trujillo and Chiclayo, where three-wheel conversion reliance signals underpenetrated demand for purpose-built cargo motorcycles. Colombia's Resolution 1111 pre-compliance window offers fleet procurement access before regulatory harmonization closes arbitrage. Pursue direct-to-fleet contracting with Mercado Libre and Rappi operator cooperatives, bypassing established dealer network gatekeeping. For Investors and Strategic Acquirers: Honda Motor Co. Ltd.'s dedicated Brazilian R&D center localization pace is the leading indicator that fuel-injection platform readiness will determine acquisition premiums across the analysis window. Long-term viability favors assemblers with captive engineering centers over import-dependent distributors. Target mid-tier regional players with Manaus free-trade-zone cost structures and pending PROCONVE compliance certification. Monitor battery-swapping infrastructure deployment density in Santiago and São Paulo as fleet rotation inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Fuel-Injection Platform Localization | PROCONVE Phase L7 compliance separates Brazilian domestic market access from re-export channel viability. |
| Battery-Swapping Infrastructure Partnership | Rappi and iFood cooperatives in São Paulo eliminate dwell-time penalties for electric scooter fleet operators. |
| Direct-to-Fleet Contracting | Bogotá delivery operators negotiate three-year service-inclusive agreements bypassing traditional dealer intermediaries. |
| Manaus Free Trade Zone Capacity Expansion | Brazilian assembly cost advantages compress landed costs for Andean markets facing Argentina foreign exchange volatility. |
| Flex-Fuel Architecture Development | Peru's ethanol-gasoline blending mandates create regulatory tailwind distinct from Brazil's pure-gasoline or full-electric pathways. |
Research Methodology
Independent corroboration across primary interviews with fleet procurement managers at Mercado Libre and Rappi cooperatives, secondary validation through ANVISA homologation databases and PROCONVE regulatory filings, and customs trade data from Brazil's Manaus Free Trade Zone underwrites the qualitative findings. Plant managers at southeastern Brazilian assembly facilities, distributor partnership leads in Colombia and Peru, and aftermarket service heads at authorized dealership networks provided operational ground-truth. Bottom-up unit shipment tallies triangulate against top-down market value estimates.
Comparable-period anchoring to historical PROCONVE enforcement phases and Resolution 1111 adoption curves structured the projection horizon across the analysis window. Segmentation dimensions span engine capacity brackets, fuel type architectures, and distribution channel structures, with fleet-versus-individual buyer behavior modeled as an industry-specific demand driver. CAGRs derive from regression-adjusted trend extrapolation incorporating regulatory enforcement timeline probabilities. Forecast inputs include municipal zero-emission zone expansion schedules and lithium-ion cell cost trajectory assumptions.
Underlying measurement precision varies by segment; electric powertrain adoption curves carry tighter precision than flex-fuel pathway penetration estimates given policy announcement volatility. Forecasts reflect documented assumptions around PROCONVE Phase L7 enforcement adherence and semiconductor supply normalization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
China E-Bike Market
Bikes and Motorcycles
Latin America Fuel Cell Bikes Market
Bikes and Motorcycles
Two Wheeler Suspension System Market
Bikes and Motorcycles
Australia E- Bike Market
Bikes and Motorcycles
Motorcycle Fuel Hoses Market
Bikes and Motorcycles
Latin America Bike Sharing Market
Bikes and Motorcycles
Automotive Chain Sprockets Market
Bikes and Motorcycles
Africa Two-Wheeler Market
Bikes and Motorcycles
Motorbike Riding Gear Market
Bikes and Motorcycles
Flying Bikes Market
Bikes and Motorcycles
Motorcycle Seat Market
Bikes and Motorcycles
China Two Wheeler Market
Bikes and Motorcycles
Motorcycle Horns Market
Bikes and Motorcycles
United States E-Bike Market
Bikes and Motorcycles
Maxi Scooter Market
Bikes and Motorcycles
Latin America Two-Wheeler Market