
 South Africa Two-Wheeler Market | 2026-2036
South Africa Two-Wheeler Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Two-Wheeler Market Insights
South African assembly plants is realigning component sourcing toward local chassis fabrication and engine kitting operations. Honda Motor Co. Ltd. leverages its established distributor network to dominate the premium commuter segment across Gauteng and Western Cape provinces. TVS Motor Company Limited anchors its position through aggressive dealership penetration in secondary cities and rural KwaZulu-Natal. Bajaj Auto Ltd. competes on price-accessible motorcycles targeting commercial delivery operators in peri-urban townships.
Two-wheelers encompass motorized vehicles with engine displacements typically below 400cc, featuring tubular steel or aluminum alloy frames, chain or belt final-drive systems, and fuel injection or carburetion induction designed for individual mobility and light cargo transport. Petrol motorcycles retain the largest volume share due to established refueling infrastructure and lower upfront acquisition cost, though electric variants are gaining traction among urban delivery fleets seeking operating cost reduction. Scooters occupy the fastest-expanding niche among female commuters and young professionals in Cape Town and Pretoria where step-through ergonomics and automatic transmission reduce rider training barriers. Distribution through franchised dealerships captures the dominant margin pool by bundling financing, insurance, and after-sales service.
South Africa's National Regulator for Compulsory Specifications enforces SABS homologation standards that constrain grey-market imports and protect authorized franchise holders. The Department of Transport's emissions testing protocols under the National Environmental Management Air Quality Act are elevating compliance costs for carbureted petrol imports while creating regulatory space for electric powertrain entry. Stakeholders must monitor National Treasury's evolving import tariff schedules and local content incentive frameworks to determine whether in-house assembly or fully built unit importation delivers superior landed cost economics.
Market Dynamics
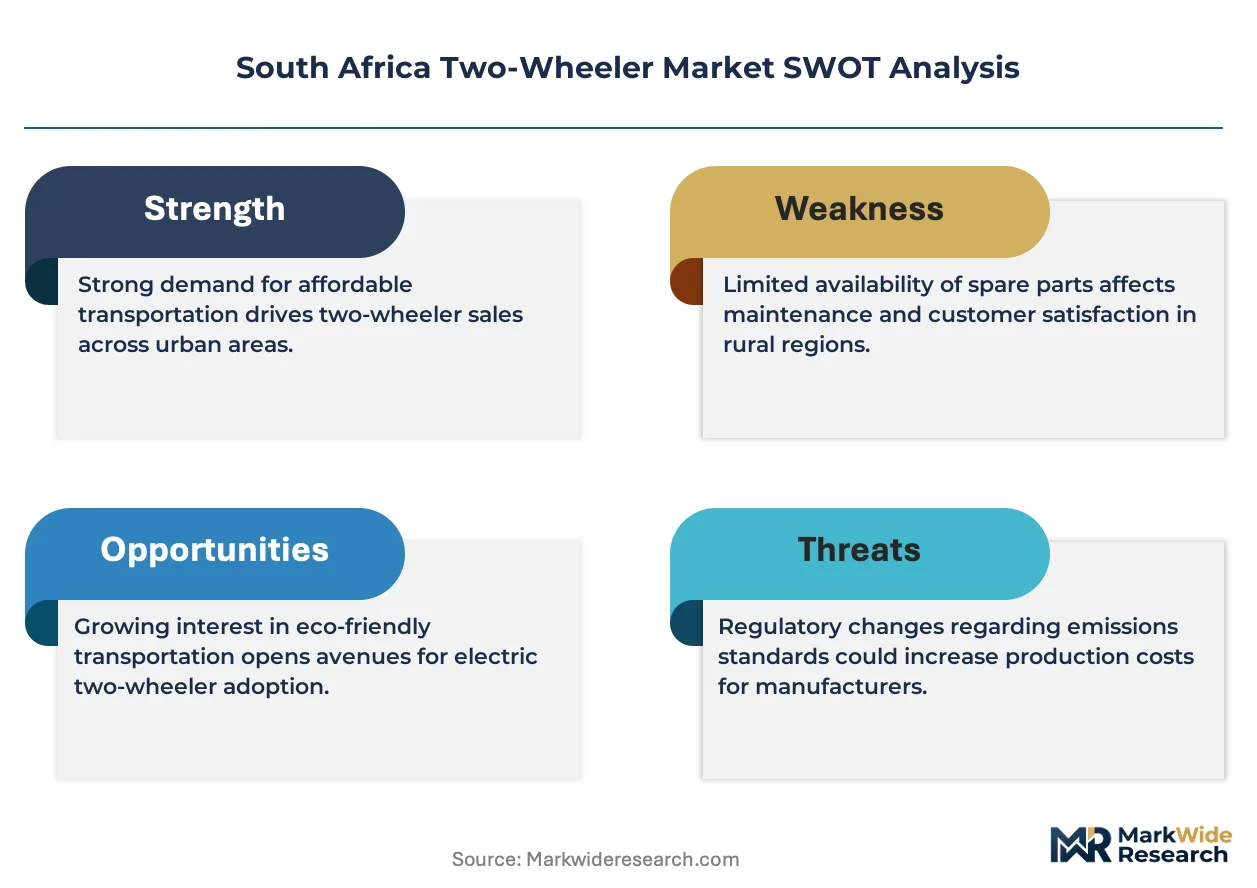
Delivery fleet electrification and National Road Traffic Act amendments are compressing the petrol-dominant supply structure while opening regulatory space for battery-electric powertrains in Gauteng and KwaZulu-Natal.
Growth Catalysts
- Last-mile logistics densification:E-commerce fulfillment networks in Johannesburg and Durban are expanding two-wheeler procurement for parcel and food delivery operations.
- SABS homologation enforcement:Compulsory specifications under the National Regulator for Compulsory Specifications are blocking grey-market imports and protecting authorized franchise margins.
- Urban commuter congestion:Gridlock in Cape Town and Pretoria is pushing private vehicle owners toward motorcycles for time-efficient mobility.
Market Restraints
- Petrol price volatility:Fuel cost swings strain operating budgets for commercial operators running high-mileage delivery fleets.
- Carburetor compliance costs:National Environmental Management Air Quality Act testing protocols are elevating landed costs for older petrol engine imports.
- Charging infrastructure gaps:Sparse public EV charging networks outside metropolitan cores limit electric two-wheeler range confidence.
Strategic Opportunities
- Rural KwaZulu-Natal penetration:Secondary cities and peri-urban townships remain underserved by franchised dealership networks.
- Battery-swapping logistics:Courier fleets in Durban's commercial zone are piloting exchange-station models to eliminate charging downtime.
- Local content incentives:National Treasury tariff schedules are creating assembly economics favoring in-house chassis fabrication over fully built unit imports.
Industry Challenges
- Electric powertrain technician scarcity:Service networks lack certified personnel for battery management system diagnostics and motor controller repair.
- Homologation timeline compression:SABS certification cycles for new electric models lag behind product development schedules from Asian suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Two-Wheeler Market |
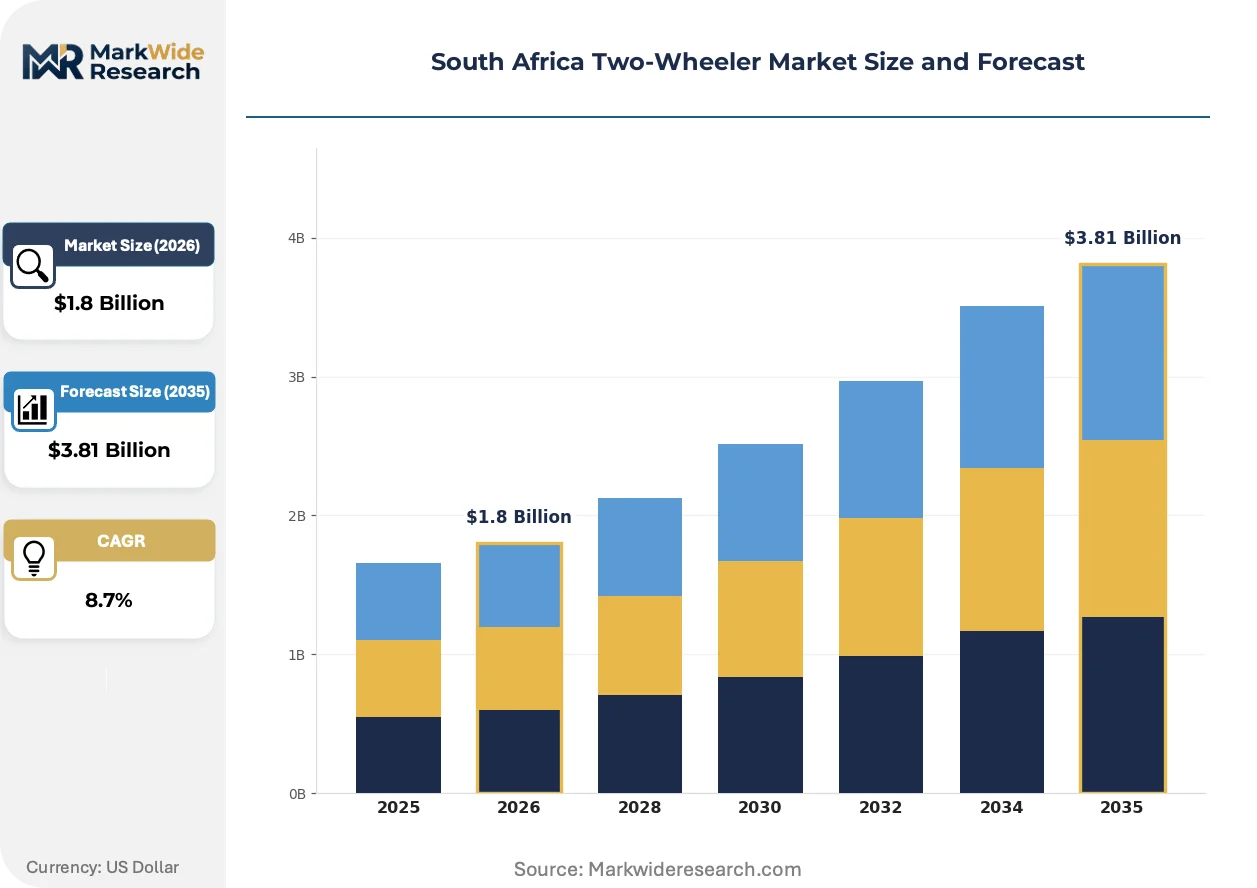
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motorcycles, Scooters, Mopeds, E-bikes End User: Commuters, Delivery Services, Leisure Riders, Commercial Users Fuel Type: Petrol, Diesel, Electric, Hybrid Distribution Channel: Online Retail, Dealerships, Supermarkets, Trade Shows |
| Companies Covered | BMW Motorrad, Honda Motor Co. Ltd., KTM Motorcycles, Yamaha Motor Company Limited, Harley-Davidson, Bajaj Auto Ltd., Suzuki Motor Corporation, TVS Motor Company Limited, Hero MotoCorp Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Two-Wheeler Market Trends and Innovations
Powertrain electrification, regulatory emissions tightening, and fleet procurement professionalization are restructuring competitive advantage away from pure unit sales toward total cost of ownership and service bundling.
Swappable battery architecture is modularizing electric two-wheeler design, allowing delivery operators in Johannesburg to exchange depleted packs at hub stations rather than waiting for plug-in cycles. Food logistics providers are adopting this format fastest, compressing vehicle downtime from hours to minutes and enabling 18-hour daily utilization rates.
South Africa's National Environmental Management Air Quality Act amendments are forcing carbureted petrol imports toward EFI retrofit or exit, with the Department of Transport emissions protocols most heavily affecting small-displacement commercial motorcycles used in peri-urban delivery. Importers are responding by accelerating electric SKU introductions and local assembly partnerships to bypass fully built unit compliance costs.
Fleet procurement is consolidating around total cost of ownership contracts that bundle vehicles, maintenance, and insurance into per-kilometer pricing. Large logistics operators in Gauteng are displacing individual ownership models with operational lease structures, transferring residual value risk to distributors and demanding real-time telematics integration for route optimization.
South Africa Two-Wheeler Market Segmentation
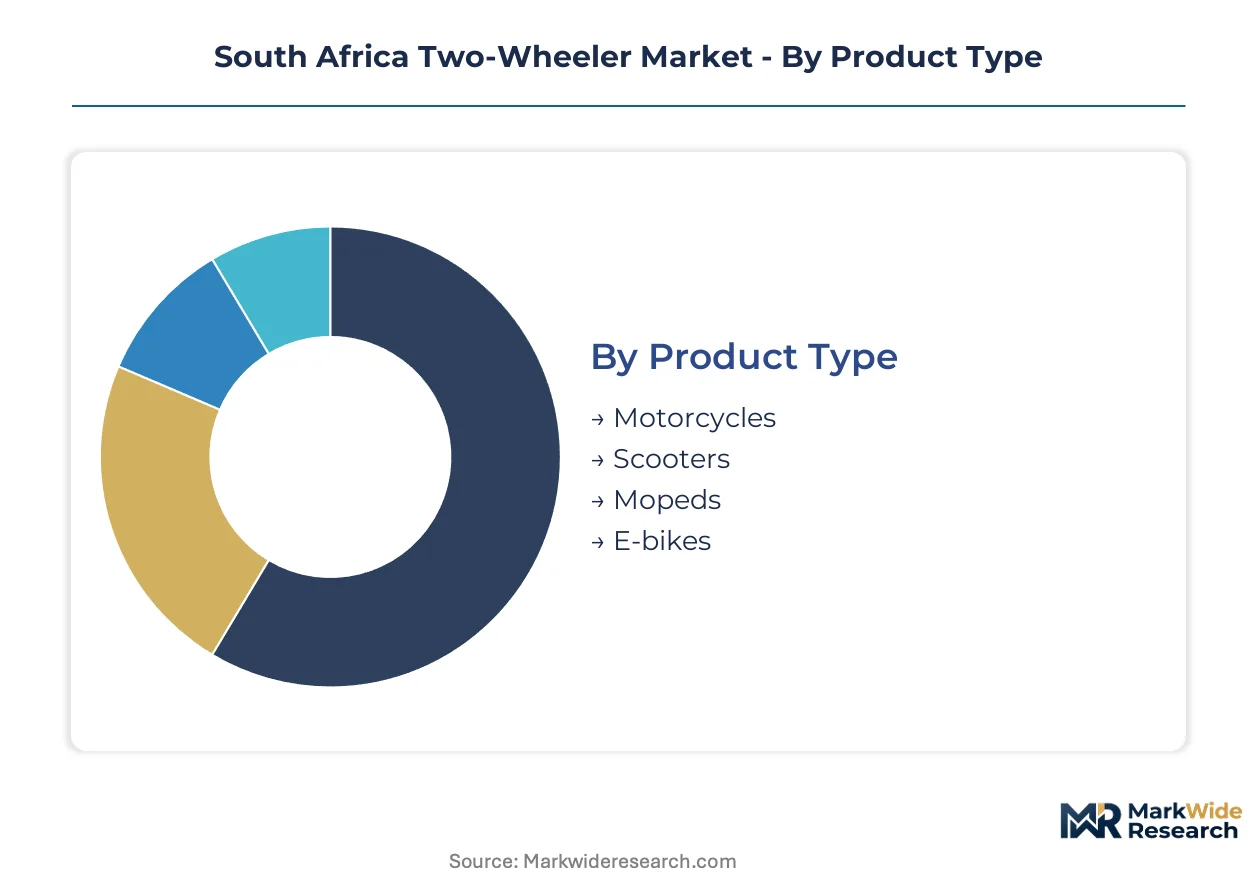
Two-wheeler procurement patterns in South Africa diverge sharply between urban commuter corridors and commercial logistics networks. Understanding these segment boundaries clarifies where distributors capture margin pools and where assemblers face compliance cost pressures.
Product Type:
Supply concentration in Gauteng assembly plants favors chassis fabrication and engine kitting for specific vehicle architectures over others.
- Motorcycles:Tubular steel frames with chain final-drive systems dominate petrol-powered commercial fleets. Demand concentrates in Johannesburg's peri-urban delivery corridors where load capacity and fuel range outweigh acquisition cost sensitivity.
- Scooters:Step-through aluminum alloy chassis with automatic transmission reduce rider training barriers. Cape Town and Pretoria's female commuter demographic and young professional cohort are expanding procurement fastest among urban mobility seekers.
- Mopeds:Sub-50cc displacement units with restricted speed governors serve township short-haul connectivity. KwaZulu-Natal's secondary cities generate residual demand where licensing exemption lowers entry barriers.
- E-bikes:Pedal-assist electric powertrains with removable battery packs target last-mile courier substitution. Battery-swapping pilots in Durban's commercial zone are validating fleet economics against petrol alternatives.
Today's leader: Motorcycles. Tomorrow's challenger: E-bikes.
End User:
Customer procurement sophistication separates volume purchasers demanding total cost of ownership contracts from individual buyers focused on upfront acquisition price.
- Commuters:Individual owners in Cape Town and Pretoria prioritize time-efficient mobility through gridlock. Congestion pricing on major arterials is accelerating modal shift from private cars toward two-wheeled alternatives.
- Delivery Services:Fleet operators in Johannesburg and Durban procure through operational lease structures bundling maintenance, insurance, and telematics. Per-kilometer pricing transfers residual value risk to distributors while demanding 18-hour daily utilization rates.
- Leisure Riders:Weekend touring enthusiasts in Western Cape coastal routes seek displacement above 250cc. This segment carries premium margin potential but remains volume-constrained by discretionary income sensitivity.
- Commercial Users:Peri-urban township enterprises deploy two-wheelers for light cargo transport and mobile vending. SABS homologation enforcement is displacing grey-market imports that previously served this price-sensitive tier.
Delivery Services command the steepest expansion trajectory as e-commerce fulfillment networks densify.
Fuel Type:
Regulatory compliance cost layering under the National Environmental Management Air Quality Act is restructuring landed economics across powertrain categories.
- Petrol:Carbureted and EFI induction systems retain infrastructure advantage through established refueling networks. National Road Traffic Act amendments are elevating homologation costs for older engine architectures while protecting EFI-compliant imports.
- Electric:Battery-electric powertrains with swappable pack architecture are gaining traction among courier fleets seeking operating cost reduction. Charging infrastructure gaps outside metropolitan cores constrain private adoption despite total cost of ownership advantages.
- Diesel:Compression-ignition engines in commercial three-wheeler configurations serve peri-urban freight consolidation. Limited passenger vehicle application restricts segment scale to specialized logistics operators.
- Hybrid:Series-hybrid architectures combining small petrol generators with electric traction motors remain nascent. Technology cost premiums and local service network absence delay meaningful market penetration.
Petrol maintains volume dominance. Electric powertrains are climbing the fastest through fleet procurement professionalization.
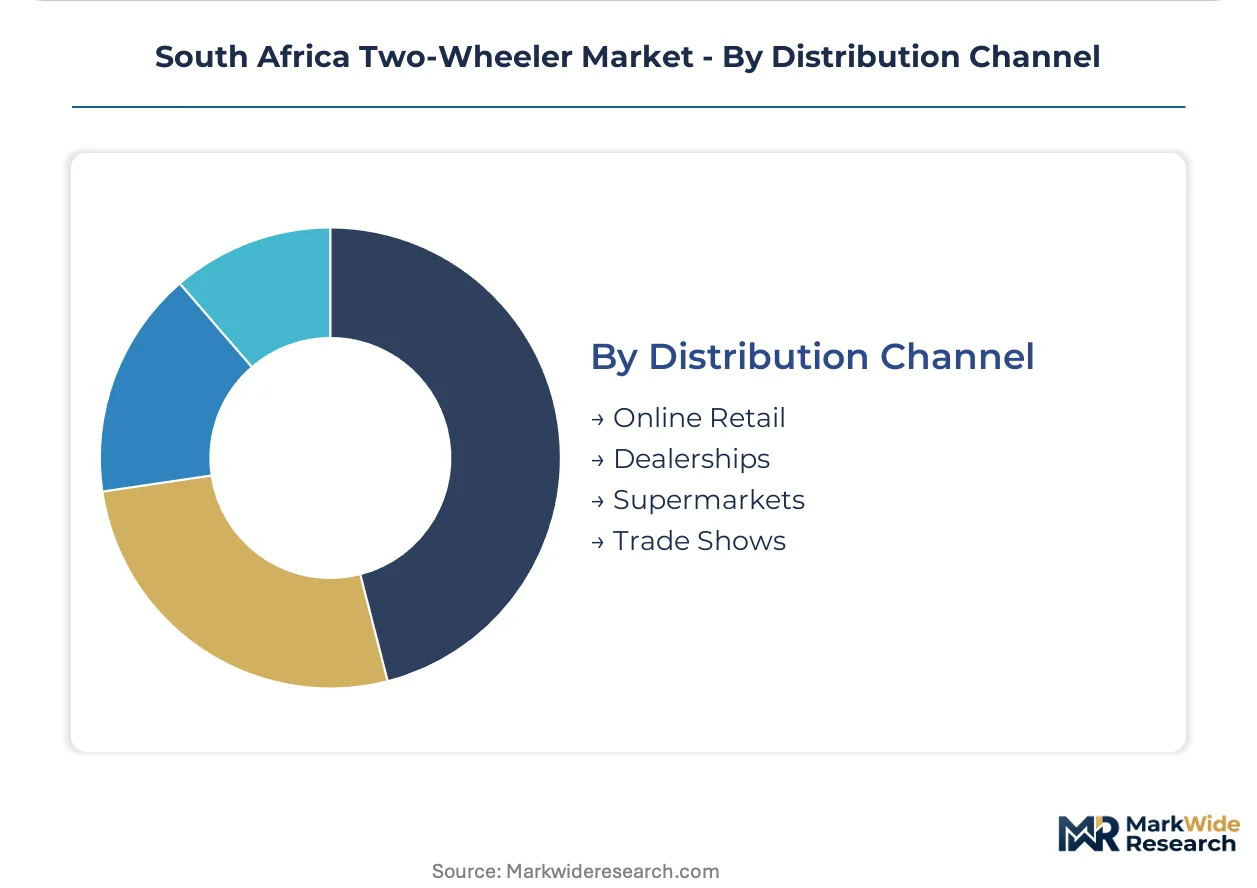
Distribution Channel:
Margin capture concentration favors franchised networks bundling financing and after-sales service over transactional retail formats.
- Dealerships:Authorized franchise holders dominate premium commuter and commercial fleet segments through SABS homologation alignment. Gauteng and Western Cape provinces show the densest network coverage with financing integration.
- Online Retail:Digital direct-to-consumer platforms are emerging for electric two-wheeler brands bypassing traditional distribution. Regulatory uncertainty around grey-market imports constrains category scaling despite price transparency advantages.
- Supermarkets:Mass retail channels capture entry-level moped and e-bike volume through price-promotional positioning. Product range limitations and absence of service bundling restrict segment profitability.
- Trade Shows:Industry exhibition circuits in Johannesburg and Durban concentrate fleet procurement decision-makers for bulk negotiation. Annual calendar alignment with fiscal budgeting cycles creates demand seasonality.
Dealerships anchor current margin pools. Online Retail is gaining share fastest through electric powertrain disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting assembly investment toward provinces where National Treasury local content incentives offset SABS homologation compliance costs. Gauteng's industrial corridor attracts chassis fabrication while coastal logistics hubs favor fully built unit imports.
Gauteng
Johannesburg's peri-urban delivery corridors concentrate commercial motorcycle demand from e-commerce fulfillment networks. The National Environmental Management Air Quality Act elevates compliance costs for carbureted imports entering through OR Tambo logistics zones. Rosslyn's automotive supplier cluster is repurposing stamping capacity for two-wheeler chassis fabrication to capture local content tariff advantages.
KwaZulu-Natal
Durban's port infrastructure handles the largest volume of fully built unit imports for national distribution. National Road Traffic Act amendments are forcing grey-market displacement in township peri-urban zones where informal operators previously dominated. Pinetown's commercial logistics zone hosts battery-swapping pilots for courier fleets seeking to eliminate charging downtime.
Western Cape
Cape Town's congestion pricing on major arterials accelerates modal shift toward scooters among female commuters and young professionals. Provincial transport subsidies for low-emission vehicles complement national SABS homologation enforcement. Stikland's industrial precinct is attracting electric two-wheeler assembly operations targeting premium urban mobility segments.
Mpumalanga
Mining supply chain logistics generate specialized demand for light cargo motorcycles in coal transport corridors. Provincial environmental regulations lag national Air Quality Act stringency, preserving operating cost advantages for existing petrol fleets. Nelspruit's logistics hub serves as distribution gateway for secondary city penetration into neighboring provinces.
South Africa Two-Wheeler Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electric powertrain specialization and fleet service bundling. The market structures around three tiers: premium displacement motorcycles, mass-market commuters, and commercial delivery specialists. Archetypes include Japanese-brand distributors leveraging homologation alignment, Indian-origin assemblers competing on price-accessible fleet economics, and European premium marques targeting leisure displacement segments. Dominant competitive moves encompass local assembly partnerships to bypass fully built unit tariffs and operational lease structures transferring residual value risk to distributors.
Among Japanese-brand distributors, Honda Motor Co. Ltd. and Yamaha Motor Company Limited exemplify the established tier's reliance on SABS-aligned homologation and franchised network density. TVS Motor Company Limited and Bajaj Auto Ltd. occupy the price-competitive commercial segment where aggressive dealership penetration in secondary cities anchors volume position. BMW Motorrad represents the premium leisure archetype where displacement-focused positioning captures margin despite volume constraints.
| Leading Market Players |
|---|
| BMW Motorrad |
| Honda Motor Co. Ltd. |
| KTM Motorcycles |
| Yamaha Motor Company Limited |
| Harley-Davidson |
| Bajaj Auto Ltd. |
| Suzuki Motor Corporation |
| TVS Motor Company Limited |
| Hero MotoCorp Ltd. |
| Others |
Pricing and Supply Chain Analysis
Steel tubing and aluminum alloy frame materials flow from East Asian mills through Durban's port infrastructure, accumulating landed cost layers that stratify final vehicle pricing across premium EFI motorcycles, mid-tier commuter scooters, and price-accessible carbureted mopeds serving township operators.
Pricing Analysis
Distributor margins in franchised dealership networks absorb the dominant value-capture layer, with SABS homologation alignment commanding premium positioning against grey-market alternatives. Price differentiation separates EFI-compliant imports from carbureted legacy stock facing National Environmental Management Air Quality Act compliance penalties. Cost compression in the entry tier intensifies as Indian-origin assemblers compete on fleet procurement economics. Delivery services exhibit lowest price sensitivity due to total cost of ownership contracting, while individual township buyers remain most responsive to upfront acquisition thresholds.
Supply Chain Analysis
Engine kitting operations rest on component flows from India, China, and Thailand, with carburetion systems and EFI modules representing critical technology dependencies. Chassis fabrication inputs include tubular steel from domestic mills and aluminum extrusions from Southeast Asian suppliers. Single-source vulnerability concentrates in electronic fuel injection controllers sourced from Tier 1 automotive electronics houses. Distribution runs through authorized franchise holders bundling financing and after-sales service, though direct-to-fleet operational lease structures are displacing traditional retail channels among large logistics operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's two-wheeler market functions as a regulatory-arbitrage corridor where National Treasury local content incentives in Gauteng assembly zones offset SABS homologation compliance costs that burden fully built unit imports landing through Durban.
For Market Incumbents: Cement homologation-aligned positioning by deepening backward integration into Rosslyn chassis fabrication and securing captive EFI controller supply from established Tier 1 electronics partners. Battery-electric entrants threaten premium commuter margins through fleet service bundling; defend by accelerating swappable battery pilot partnerships with Johannesburg logistics operators before channel lock-in solidifies. For New Entrants and Emerging Players: Enter via battery-swapping infrastructure plays targeting Durban's commercial logistics zone, where courier fleet density validates exchange-station economics against petrol alternatives. Rural KwaZulu-Natal's secondary cities present the most penetrable white-space, with dealership network gaps and SABS enforcement displacing grey-market incumbents. Pursue operational lease structuring with per-kilometer pricing to bypass upfront acquisition barriers among township commercial users. For Investors and Strategic Acquirers: Consolidation pressure builds where electric powertrain service capabilities fragment across unauthorized repair networks lacking battery management system diagnostics expertise. Long-term viability favors assemblers with local content qualification and fleet telematics integration capacity. Target acquisition profile encompasses Gauteng-based chassis fabricators with National Treasury tariff incentive alignment. Watch battery-swapping utilization rates in Durban as the inflection signal for electric powertrain economics crossing threshold viability.| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Partnership | Captures National Treasury tariff advantages while bypassing SABS homologation costs for fully built unit imports. |
| Battery Swapping Infrastructure | Eliminates charging downtime for courier fleets in Durban's commercial logistics zone. |
| Operational Lease Structuring | Transfers residual value risk to distributors while locking in 18-hour daily fleet utilization rates. |
| EFI Retrofit Program | Extends commercial motorcycle service life under National Environmental Management Air Quality Act compliance timelines. |
| Rural Dealership Penetration | Captures grey-market displacement demand in KwaZulu-Natal secondary cities as homologation enforcement tightens. |
Research Methodology
Multiple input streams — distributor operational data, assembly plant sourcing disclosures, and regulatory filing documentation — were reconciled through bottom-up and top-down triangulation. Primary interviews with franchised dealership principals, fleet procurement managers at logistics operators, and component sourcing leads at Gauteng assembly plants informed demand segmentation and pricing structure validation. Secondary sources included National Treasury tariff schedule publications, SABS homologation records, Department of Transport emissions protocol amendments, and customs import declaration data.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled encompass product type, end-user archetype, fuel type, and distribution channel, with provincial regulatory cluster variations incorporated. CAGRs were derived through trend extrapolation adjusted for National Road Traffic Act amendment impacts and fleet electrification adoption curves.
Inputs from SABS certification databases and National Treasury incentive program records were available through the study window; gaps in informal sector transaction data and grey-market import volumes introduce uncertainty bands around township penetration estimates. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and charging infrastructure deployment rates. A small set of named triggers — battery-swapping station utilization thresholds, EFI compliance deadline adherence, and local content qualification thresholds — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Asia-Pacific Motorcycle Market
Bikes and Motorcycles
Flying Bikes Market
Bikes and Motorcycles
Kids Bicycle Market
Bikes and Motorcycles
Latin America Two-Wheeler Market
Bikes and Motorcycles
Connected Motorcycle Market
Bikes and Motorcycles
Bike Hub Market
Bikes and Motorcycles
Fixed Gear Bikes Market
Bikes and Motorcycles
Global Two Wheeler Accessories Market
Bikes and Motorcycles
Two Wheeler Fenders Market
Bikes and Motorcycles
Bicycle Saddles Market
Bikes and Motorcycles
Bike Fenders Market
Bikes and Motorcycles
Motorcycle Headlight Market
Bikes and Motorcycles
Motorcycle Hub Motor Market
Bikes and Motorcycles
Motorcycle Wheels Market
Bikes and Motorcycles
Asia-Pacific Ride on Bikes Market
Bikes and Motorcycles
Two-Wheeler Motorcycle Market