
 Monoclonal Antibodies in Veterinary Health Market | 2026-2036
Monoclonal Antibodies in Veterinary Health Market Size, Share, and Industry Trends Forecast 2026-2036
Monoclonal Antibodies in Veterinary Health Market Intelligence
Buyer concentration among large veterinary hospital chains and corporate clinic networks is expanding as independent practices consolidate under platforms like Mars Veterinary Health and Vetcor. Zoetis Inc. leverages its integrated manufacturing footprint to supply these consolidated buyers directly. Boehringer Ingelheim Vetmedica GmbH anchors European production capacity for veterinary biologics. Merck Animal Health competes through specialty distribution partnerships with academic veterinary centers.
Monoclonal antibodies in veterinary health are recombinant immunoglobulins produced via mammalian cell culture, typically exceeding 95% purity, designed to bind specific antigens in companion and production animals for therapeutic intervention. These biologics primarily serve to modulate immune responses, neutralize pathogens, or block inflammatory cytokines in clinical veterinary settings. Canine monoclonal antibodies dominate current revenue as atopic dermatitis and osteoarthritis therapies achieve label expansion, while feline monoclonal antibodies represent the fastest-growing category as oral and injectable formats overcome historical species-specific formulation barriers. Oncology therapy areas command premium pricing due to limited alternatives and owner willingness to pay, though infectious disease applications sustain higher volume throughput across general practice clinics.
FDA Center for Veterinary Medicine oversees biologic licensing and safety monitoring in the United States, while EMA veterinary medicines guidelines shape European market access requirements for immunological products. USDA APHIS Center for Veterinary Biologics additionally regulates veterinary vaccines and biologics for interstate commerce, creating layered compliance obligations for multi-market suppliers. Stakeholders must monitor evolving biosimilar guidance from FDA and EMA, as patent expiries on pioneer veterinary monoclonal antibodies will soon attract follow-on developers seeking abbreviated approval pathways.
Market Dynamics
Consolidation among veterinary hospital chains is compressing procurement channels and forcing monoclonal antibody suppliers to restructure their commercial operations around direct account management rather than traditional distribution networks.
Growth Catalysts
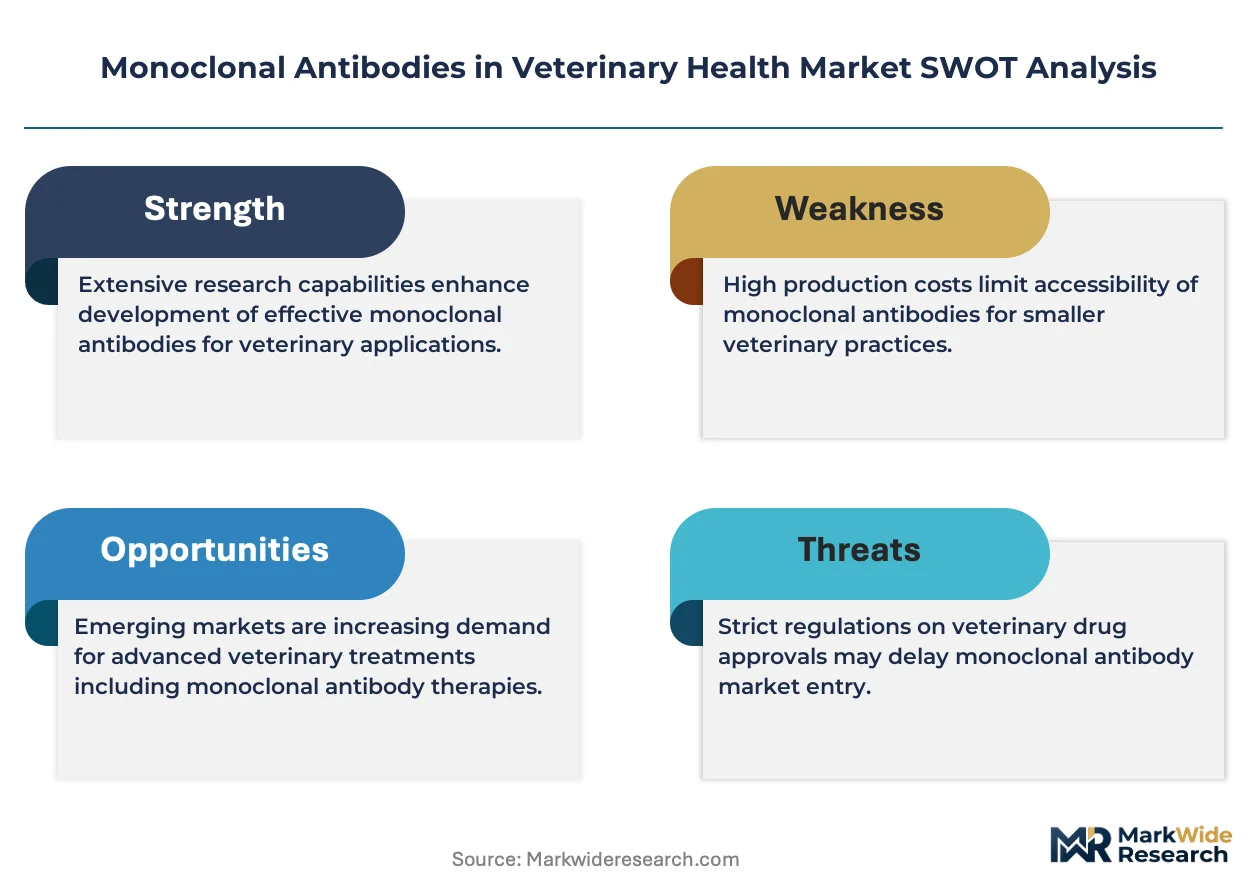
- EMA veterinary medicines guidelines:Streamlined immunological product pathways in Europe accelerate market entry timelines for novel biologics.
- Specialty veterinary hospitals:These facilities in the United States drive premium therapy uptake through advanced diagnostics and owner education programs.
- Mammalian cell culture platforms:Improved expression systems yield higher titers and reduce cost-per-dose for recombinant immunoglobulin production.
Market Restraints
- Cold chain infrastructure gaps:Temperature-controlled distribution networks remain underdeveloped in rural veterinary practice catchments.
- USDA APHIS interstate commerce rules:Layered federal-state compliance creates administrative burden for multi-market biologic shipments.
- Small molecule alternatives:Corticosteroids and cyclosporine retain cost advantage in price-sensitive general practice segments.
Strategic Opportunities
- Feline therapeutic formats:Oral and long-acting injectable presentations overcome historical species-specific formulation barriers.
- Oncology applications:Limited treatment alternatives and high owner willingness-to-pay create premium pricing headroom.
- Academic veterinary center partnerships:Research collaborations generate clinical data supporting label expansion into new indications.
Industry Challenges
- Veterinary biologic manufacturing expertise:Talent scarcity in mammalian cell culture and aseptic processing constrains production scaling.
- Biosimilar guidance uncertainty:Evolving FDA and EMA frameworks for follow-on veterinary monoclonal antibodies complicate development planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monoclonal Antibodies in Veterinary Health Market |
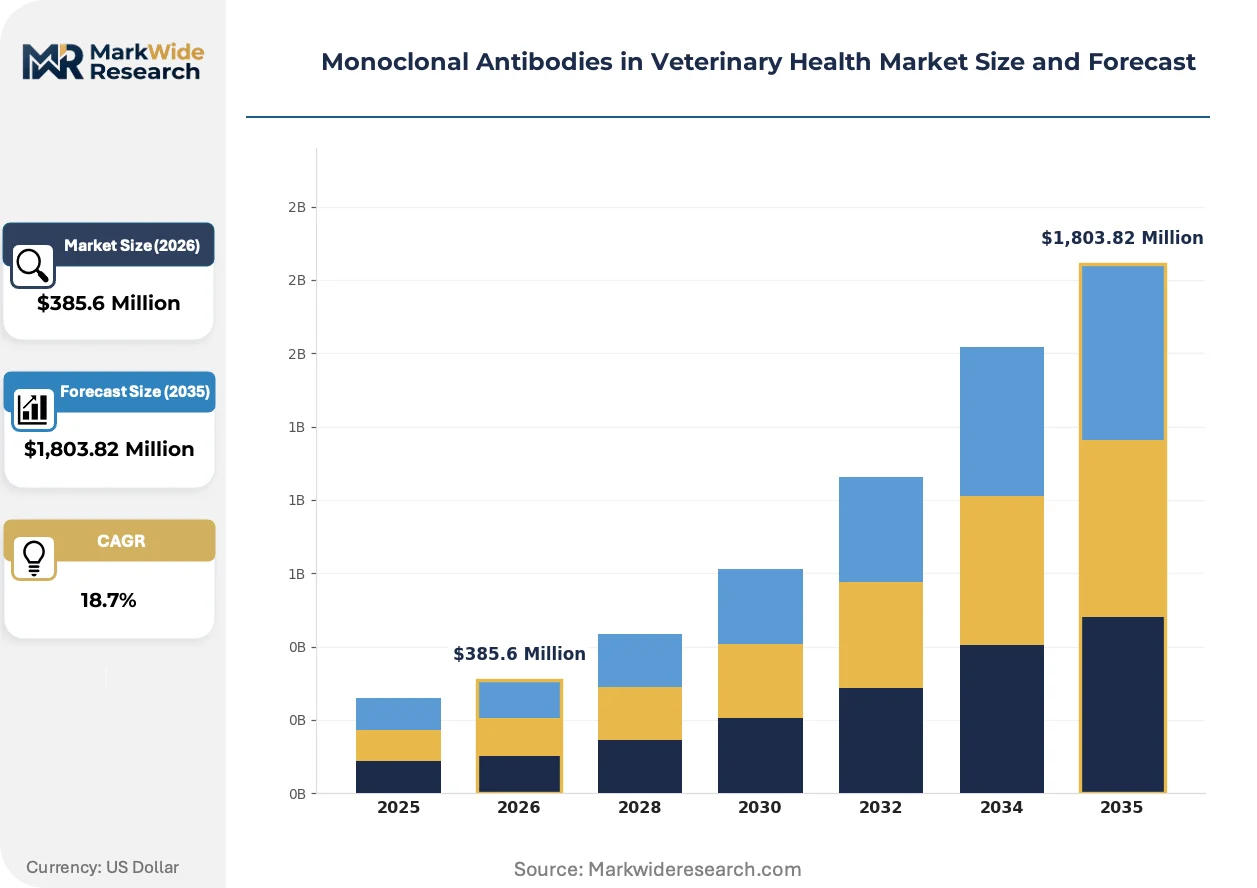
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,803.82 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canine Monoclonal Antibodies, Feline Monoclonal Antibodies, Equine Monoclonal Antibodies, Bovine Monoclonal Antibodies Therapy Area: Infectious Diseases, Autoimmune Disorders, Oncology, Pain Management Formulation: Liquid Form, Lyophilized Powder, Solution, Concentrated Formula Distribution Channel: Online Sales, Veterinary Clinics, Distributors, Pharmacies |
| Companies Covered | Zoetis Inc., Elanco Animal Health Incorporated, Boehringer Ingelheim Vetmedica GmbH, Merck Animal Health, Virbac S.A., Indian Immunologicals Limited, Dechra Pharmaceuticals PLC, Invetx, Inc., Bayer Animal Health GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monoclonal Antibodies in Veterinary Health Market Strategic Shifts & Innovations
Bioprocess intensification and regulatory harmonization efforts are compressing development timelines while shifting competitive advantage toward integrated manufacturing capabilities.
Single-use bioreactor systems are rewriting production economics for veterinary monoclonal antibodies. Contract manufacturing organizations serving mid-tier animal health firms are adopting disposable upstream technologies at accelerating pace. This shift is enabling smaller batch sizes and multi-product flexibility that legacy stainless-steel infrastructure cannot match.
EMA veterinary medicines guidelines on immunological products are harmonizing quality requirements across European member states. The industrial consequence is reduced regulatory fragmentation and faster mutual recognition procedures for biologic approvals. Companion animal oncology segments in Germany and France are responding with earlier therapy adoption and expanded formulary inclusion.
Direct purchasing agreements between consolidated veterinary hospital chains and biologic manufacturers are displacing traditional wholesale distribution in the United States. Specialty and emergency hospitals in metropolitan markets are negotiating formulary exclusivity in exchange for volume commitments. This channel compression is most visible in California and Texas, where corporate practice platforms command significant regional market presence.
Monoclonal Antibodies in Veterinary Health Market Segmentation
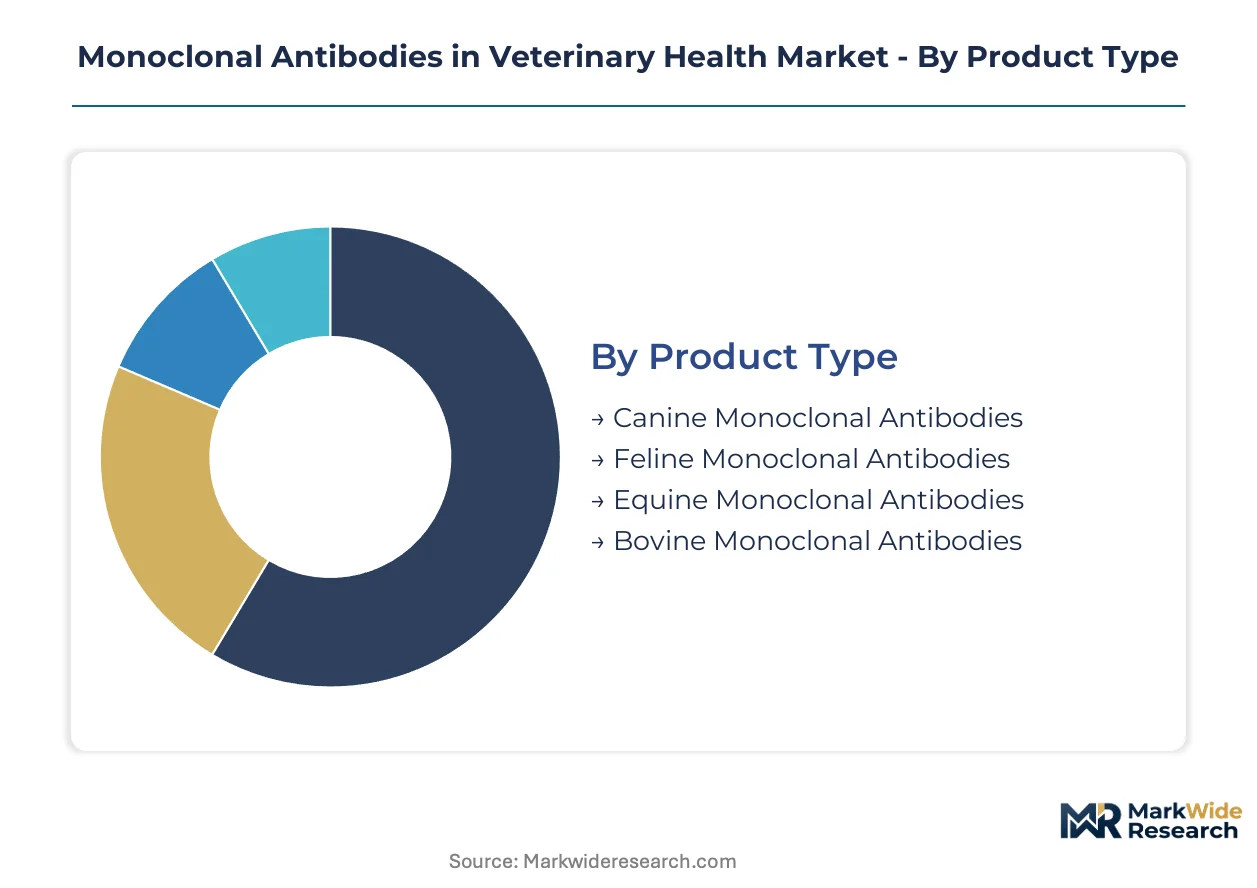
Segmentation in veterinary monoclonal antibodies reveals distinct procurement patterns across species lines and clinical settings. Buyers prioritize formulation stability and cold chain reliability when selecting products for their specific patient populations.
Product Type:
Species-specific therapeutic development drives divergent investment priorities across veterinary pharmaceutical pipelines.
- Canine Monoclonal Antibodies:Recombinant immunoglobulins targeting IL-31 and NGF pathways dominate current revenue, with atopic dermatitis and osteoarthritis applications achieving broad label expansion across United States specialty hospitals. Mars Veterinary Health formulary committees negotiate direct supply agreements for these high-volume therapeutics.
- Feline Monoclonal Antibodies:Oral bioavailability breakthroughs and long-acting injectable formats are overcoming species-specific formulation barriers that historically constrained feline biologic development. California and Texas corporate practice platforms are expanding fastest in this category.
- Equine Monoclonal Antibodies:Large-animal cell culture requirements and lower patient density limit commercial scale.
- Bovine Monoclonal Antibodies:Production animal applications concentrate in USDA-regulated feedlot and dairy operations with distinct regulatory pathways.
Canine monoclonal antibodies lead on scale; feline monoclonal antibodies lead on momentum.
Therapy Area:
Clinical outcome economics and owner willingness-to-pay create tiered pricing architecture across indications.
- Oncology:Checkpoint inhibitors and targeted cytotoxic antibodies command premium reimbursement due to limited treatment alternatives and high emotional investment from companion animal owners. Academic veterinary centers in Massachusetts and Pennsylvania generate the clinical data supporting these premium indications.
- Infectious Diseases:Pathogen-neutralizing antibodies sustain higher volume throughput across general practice clinics, though price sensitivity constrains margin expansion. USDA APHIS interstate commerce rules add administrative burden to multi-state distribution of these products.
- Autoimmune Disorders:Cytokine modulation therapies compete against established corticosteroid protocols.
- Pain Management:NGF pathway inhibitors are displacing NSAID maintenance regimens in osteoarthritis cases.
Oncology commands highest per-dose pricing; infectious diseases delivers greatest prescription volume.
Formulation:
Storage stability and reconstitution requirements determine field deployment feasibility across practice types.
- Liquid Form:Ready-to-use presentations eliminate compounding errors and accelerate clinic workflow, making them preferred by emergency and specialty hospitals in metropolitan United States markets. Cold chain infrastructure gaps in rural catchments constrain penetration.
- Lyophilized Powder:Freeze-dried formats extend shelf life and reduce shipping weight, enabling cost-effective distribution to independent practices without sophisticated refrigeration capacity.
- Solution:Dilute presentations suit high-volume institutional buyers.
- Concentrated Formula:Reduced injection volumes minimize patient stress in feline applications.
Liquid form dominates convenience-driven purchasing; lyophilized powder enables reach into infrastructure-constrained settings.
Distribution Channel:
Channel compression is restructuring how biologic manufacturers reach end-users.
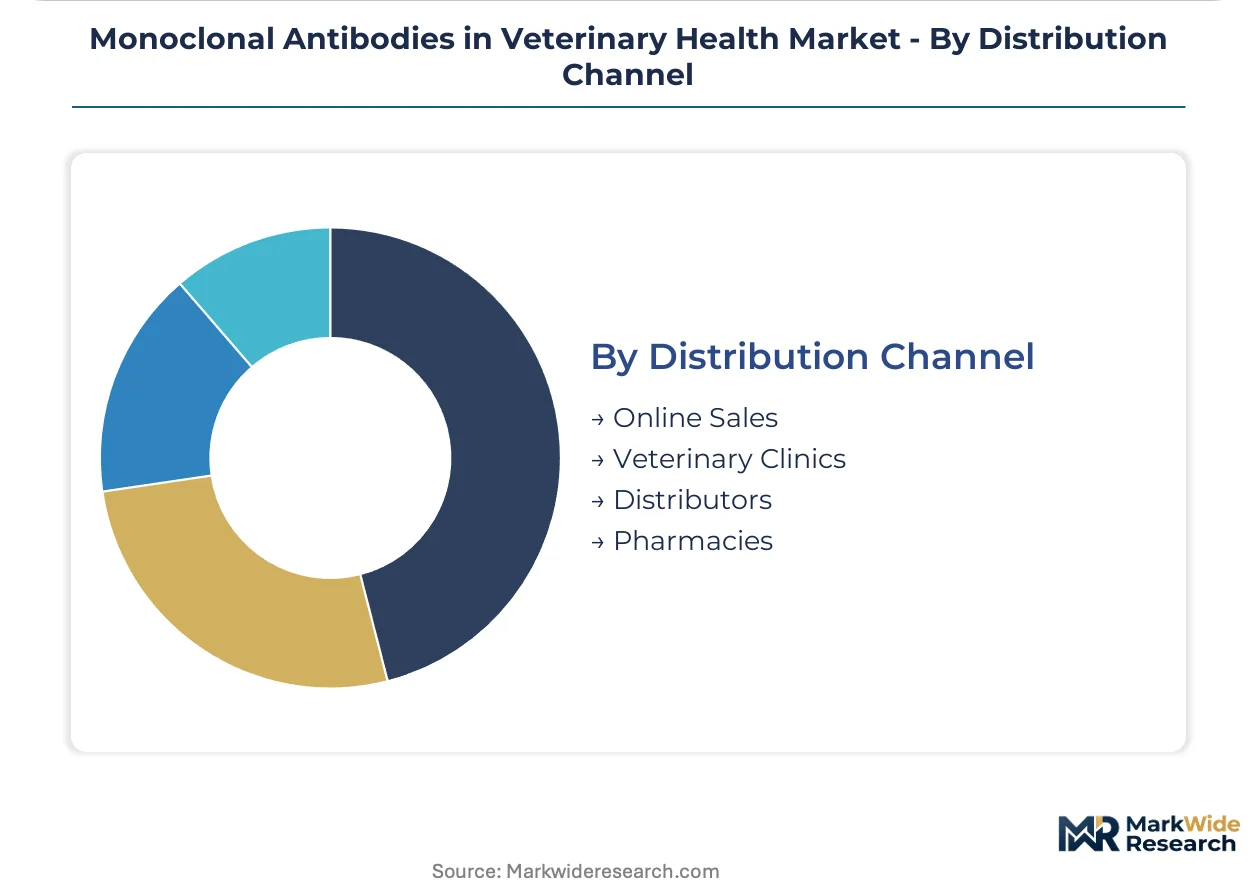
- Veterinary Clinics:Direct purchasing agreements with consolidated hospital chains are displacing traditional wholesale distribution, with corporate platforms like Vetcor negotiating formulary exclusivity in exchange for volume commitments.
- Distributors:Regional veterinary supply houses retain relevance for independent practices and production animal segments where order fragmentation prevents direct manufacturer engagement.
- Online Sales:Telemedicine-enabled prescription fulfillment is expanding fastest among millennial pet owners in urban United States markets.
- Pharmacies:Human pharmacy compounding of veterinary biologics faces FDA Center for Veterinary Medicine enforcement scrutiny.
Veterinary clinics concentrate procurement power; online sales channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates veterinary monoclonal antibody demand through corporate hospital chains, while Germany anchors European production capacity through specialized biologic manufacturing clusters.
United States
Specialty veterinary hospitals in Massachusetts and Pennsylvania drive premium therapy adoption through advanced oncology diagnostics and owner education programs. FDA Center for Veterinary Medicine guidelines streamline biologic licensing pathways for companion animal indications. California and Texas corporate practice platforms negotiate direct purchasing agreements that displace traditional wholesale distribution channels.
Germany
Companion animal oncology segments in Bavaria and North Rhine-Westphalia respond to EMA veterinary medicines harmonization with expanded formulary inclusion. The country's national pharmaceutical regulator enforces quality standards that accelerate mutual recognition procedures across European member states. Baden-Württemberg manufacturing clusters supply recombinant immunoglobulins to consolidated veterinary hospital chains throughout the continent.
France
Île-de-France academic veterinary centers generate clinical data supporting label expansion into novel indications for feline therapeutic formats. EMA veterinary medicines guidelines reduce regulatory fragmentation for immunological products entering French markets. Auvergne-Rhône-Alpes bioprocessing facilities adopt single-use bioreactor systems to enable multi-product manufacturing flexibility.
United Kingdom
Greater London specialty clinics concentrate procurement power through direct account management relationships with biologic manufacturers. The country's national pharmaceutical regulator aligns with EMA frameworks while maintaining distinct post-Brexit submission requirements. Southeast England research partnerships with academic institutions generate evidence supporting canine atopic dermatitis therapy adoption.
Japan
Tokyo metropolitan veterinary hospitals demonstrate elevated willingness-to-pay for oncology applications with limited treatment alternatives. PMDA veterinary biologic oversight creates structured approval pathways distinct from pharmaceutical and agricultural chemical regulations. Osaka-Kansai manufacturing corridors develop mammalian cell culture capacity serving domestic companion animal therapeutic demand.
Monoclonal Antibodies in Veterinary Health Market Key Industry Players
United States producers anchor one tier; German specialists hold manufacturing scale advantages in European supply. The vendor base arranges around three strategic archetypes: integrated pharmaceutical conglomerates with captive biologic divisions, dedicated animal health firms with recombinant protein expertise, and contract manufacturing organizations serving mid-tier innovators. Consolidation among veterinary hospital chains accelerates direct purchasing negotiations, while bioprocess intensification investments compress production economics for mammalian cell culture platforms.
Within the integrated pharmaceutical tier, Zoetis Inc. and Boehringer Ingelheim Vetmedica GmbH occupy positions exemplifying geographic production concentration. Merck Animal Health anchors specialty distribution partnerships with academic veterinary centers. These three entities represent distinct competitive positioning: United States-based direct supply integration, German manufacturing scale, and research collaboration anchoring respectively.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Elanco Animal Health Incorporated |
| Boehringer Ingelheim Vetmedica GmbH |
| Merck Animal Health |
| Virbac S.A. |
| Indian Immunologicals Limited |
| Dechra Pharmaceuticals PLC |
| Invetx, Inc. |
| Bayer Animal Health GmbH |
| Others |
Cost & Logistics Intelligence
Mammalian cell culture media costs cascade through three pricing tiers as recombinant immunoglobulin production scales from stainless-steel to single-use bioreactor platforms. The United States specialty hospital segment absorbs premium markups for liquid-form monoclonal antibodies, while lyophilized formats reach price-sensitive independent practices through regional veterinary distributors.
Pricing Analysis
Capacity additions in Germany and the United States are reshaping price floors for veterinary biologics as Baden-Württemberg manufacturing clusters and Texas production facilities expand mammalian cell culture output. Three-tier pricing structure across premium oncology, standard chronic disease management, and economy infectious disease applications reflects clinical outcome differentiation and owner willingness-to-pay. Pricing pressure stems from corticosteroid and cyclosporine substitution in general practice segments where small molecule alternatives retain cost advantage. Production animal clinics demonstrate highest price sensitivity, while Massachusetts and Pennsylvania academic veterinary centers accept premium positioning for limited-alternative oncology indications.
Supply Chain Analysis
Regional distribution centers in California, Texas, and Bavaria anchor hub-and-spoke cold chain networks reaching specialty hospitals and corporate practice platforms. Germany, the United States, and France concentrate upstream bioprocessing capacity for veterinary monoclonal antibodies, with Baden-Württemberg and Massachusetts clusters feeding downstream formulation sites. Supply chains draw from recombinant protein expression systems, aseptic filling lines, and temperature-controlled logistics infrastructure vulnerable to single-source vulnerability in qualified viral clearance testing. Distribution runs through direct purchasing agreements with consolidated hospital chains displacing traditional wholesale channels, though rural veterinary catchments retain distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in veterinary monoclonal antibodies rests on bioprocess intensification reducing cost-per-dose and oncology premium tiers capturing elevated owner willingness-to-pay for limited-treatment-alternative indications.
For Market Incumbents: Anchor manufacturing scale in single-use bioreactor platforms to defend against contract manufacturing organization cost compression. Secure captive supply of viral clearance testing capacity to mitigate single-source qualification bottlenecks. Deepen direct account management with Mars Veterinary Health and Vetcor formulary committees to lock out biosimilar entrants through volume-commitment exclusivity. For New Entrants and Emerging Players: Independent rural veterinary practices underserved by cold chain infrastructure represent the most penetrable buyer archetype for lyophilized powder formulations requiring minimal refrigeration. California and Texas corporate practice platforms offer faster formulary access for feline therapeutic formats overcoming species-specific barriers. Pursue academic veterinary center research partnerships in Massachusetts and Pennsylvania to generate clinical data supporting label expansion into novel indications. For Investors and Strategic Acquirers: Consolidation pressure builds where manufacturing expertise scarcity constrains production scaling for mammalian cell culture and aseptic processing. Long-term viability favors integrated players with captive biologic divisions over pure-play animal health firms dependent on contract manufacturing. Monitor FDA and EMA biosimilar guidance evolution as the signal indicating abbreviated approval pathway attractiveness for follow-on veterinary monoclonal antibody developers.| Strategic Initiative | Industry Significance |
|---|---|
| Single-Use Bioreactor Adoption | Disposable upstream technologies enable multi-product flexibility that stainless-steel infrastructure cannot match. |
| Direct Purchasing Agreements | Corporate hospital chains negotiate formulary exclusivity displacing traditional wholesale distribution channels. |
| Academic Center Partnerships | Research collaborations with Massachusetts and Pennsylvania institutions generate clinical data supporting label expansion. |
| Feline Format Development | Oral bioavailability breakthroughs overcome species-specific formulation barriers in fastest-growing category. |
| Cold Chain Infrastructure Investment | Temperature-controlled distribution networks address rural veterinary practice catchment gaps constraining penetration. |
Research Approach
Multiple input streams — primary interviews with bioprocess engineers, regulatory affairs specialists, and veterinary hospital procurement directors, alongside secondary validation through FDA Center for Veterinary Medicine filings, EMA veterinary medicines submissions, and USDA APHIS biologic licensing records — were reconciled through bottom-up and top-down triangulation. Conversations with mammalian cell culture facility managers, specialty hospital formulary committees, and regional veterinary distributors informed production capacity and channel structure assessments. Secondary sources included companion animal oncology clinical trial registries, corporate practice platform annual disclosures, and bioprocessing equipment procurement databases.
Data-stream reconciliation across species segments, therapy areas, formulation types, and distribution channels produced volume and value estimates across the projection horizon. Segmentation modeling captured canine, feline, equine, and bovine species lines; oncology, infectious disease, autoimmune, and pain management indications; liquid, lyophilized, solution, and concentrated presentations; and clinic, distributor, online, and pharmacy channels. CAGRs were derived from production capacity expansion timelines, regulatory approval trajectories, and corporate practice platform consolidation rates. Forecast inputs incorporated FDA biosimilar guidance evolution, EMA immunological product harmonization progress, and single-use bioreactor adoption curves.
Underlying measurement precision varies by segment; canine atopic dermatitis and osteoarthritis indications carry tighter precision due to established prescription tracking, while emerging feline therapeutic formats and production animal applications exhibit wider confidence intervals. Forecasts reflect assumptions around regulatory pathway timelines, manufacturing scale-up success rates, and corporate practice platform consolidation velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Medicine
Veterinary Assistive Reproduction Technology Market
Veterinary Medicine
Veterinary Pain Management Market
Veterinary Medicine
Global Companion Animal Pharmaceuticals Market
Veterinary Medicine
Veterinary Orthopedic Medicine Market
Veterinary Medicine
Veterinary Anesthesia Machines Market
Veterinary Medicine
Animal Drugs Market
Veterinary Medicine
ASEAN Rabies Veterinary Vaccines Market
Veterinary Medicine
Global Veterinary Eye Care Market
Veterinary Medicine
US Veterinarians Market
Veterinary Medicine
Veterinary Forceps Market
Veterinary Medicine
Veterinary Anti-Infectives Market
Veterinary Medicine
Global Veterinary Autogenous Vaccines Market
Veterinary Medicine
Veterinary Anesthesia Market
Veterinary Medicine
Global Brucellosis Vaccines Market
Veterinary Medicine
Over-The-Counter (OTC) Veterinary Drugs Market
Veterinary Medicine
Global Veterinary/Animal Vaccines Market