
 Global Veterinary Autogenous Vaccines Market | 2026-2036
Global Veterinary Autogenous Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veterinary Autogenous Vaccines Market Foresight
Demand from livestock farms is shifting toward customized bacterial vaccines as industrial pork and dairy operations prioritize herd-specific pathogen control. Zoetis Inc. leverages its diagnostic-to-vaccine pipeline to anchor autogenous service contracts across major cattle-producing states. Merck Animal Health competes through integrated veterinary laboratory networks that shorten pathogen-to-vaccine turnaround times. Boehringer Ingelheim Animal Health specializes in multivalent autogenous formulations for complex swine respiratory syndromes.
Veterinary autogenous vaccines comprise pathogen-specific immunological preparations manufactured from microorganisms isolated directly from an individual farm or regional outbreak, typically formulated as bacterins or toxoids with aluminum hydroxide adjuvants to elicit targeted humoral immunity. These products serve commercial animal production by addressing bacterial diseases where no commercial licensed vaccine exists or where circulating strains diverge from standard formulations. Bacterin and toxoid products dominate current revenue as mature, well-characterized formats with established regulatory dossiers. Live attenuated autogenous platforms represent the fastest-growing segment as nucleic acid sequencing enables rapid strain attenuation for farm-specific viral challenges. The cattle and swine animal type categories concentrate margin pools due to high per-animal treatment values and recurring multi-dose protocols in intensive production systems.
The FDA Center for Veterinary Medicine regulates autogenous vaccines under conditional licensing frameworks that balance expedited access with batch safety documentation, while the EMA and national EU competent authorities enforce the EU Pharmacovigilance Guidelines for customized immunologicals. ISO 17025 accreditation requirements for autogenous production laboratories are raising compliance costs and consolidating contract manufacturing toward multi-site certified operators. Stakeholders must monitor evolving regulatory convergence between the FDA and EMA on autogenous product traceability standards as transnational livestock corporations seek harmonized supply chains.
Market Dynamics
Regulatory documentation requirements from the FDA and EMA are compressing production timelines while simultaneously consolidating contract manufacturing toward multi-site certified laboratories capable of meeting ISO 17025 accreditation standards.
Growth Catalysts
- EU Pharmacovigilance Guidelines:The EMA's tightened traceability mandates for customized immunologicals are accelerating investment in batch-level digital tracking systems across European autogenous production facilities.
- Nucleic acid sequencing:Rapid strain identification technologies are shortening pathogen-to-vaccine development cycles for farm-specific viral challenges in intensive cattle and swine operations.
- United States:Large-scale dairy and pork producers in Texas, Iowa, and California are driving recurring multi-dose immunization contracts for herd-specific bacterial pathogen control.
Market Restraints
- Aluminum hydroxide adjuvant supply:Concentrated sourcing of this critical formulation component from limited chemical suppliers creates input cost volatility and formulation scheduling risk.
- ISO 17025 compliance costs:Laboratory accreditation requirements for autogenous production are raising fixed cost barriers and pushing smaller regional operators toward exit.
- Live attenuated platform complexity:Technical limitations in rapid attenuation protocols for certain viral families restrict expansion beyond well-characterized bacterin and toxoid formats.
Strategic Opportunities
- Brazil:Underpenetrated beef and poultry sectors present white space for autogenous service contracts as ANVISA develops pathways for farm-specific bacterial vaccines.
- CRISPR-based attenuation:Convergence of gene-editing technologies with nucleic acid sequencing is enabling precision strain modification for complex swine respiratory syndromes.
- Direct veterinary laboratory partnerships:Channel innovation through embedded diagnostic-to-vaccine pipelines is compressing turnaround times and capturing recurring contract value.
Industry Challenges
- Veterinary immunology specialization:Talent scarcity in farm-specific vaccine formulation and regulatory dossier preparation is constraining laboratory expansion timelines.
- Legacy quality management system integration:Multi-site certified operators face execution friction merging paper-based batch records with digital traceability platforms required by tightening FDA documentation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veterinary Autogenous Vaccines Market |
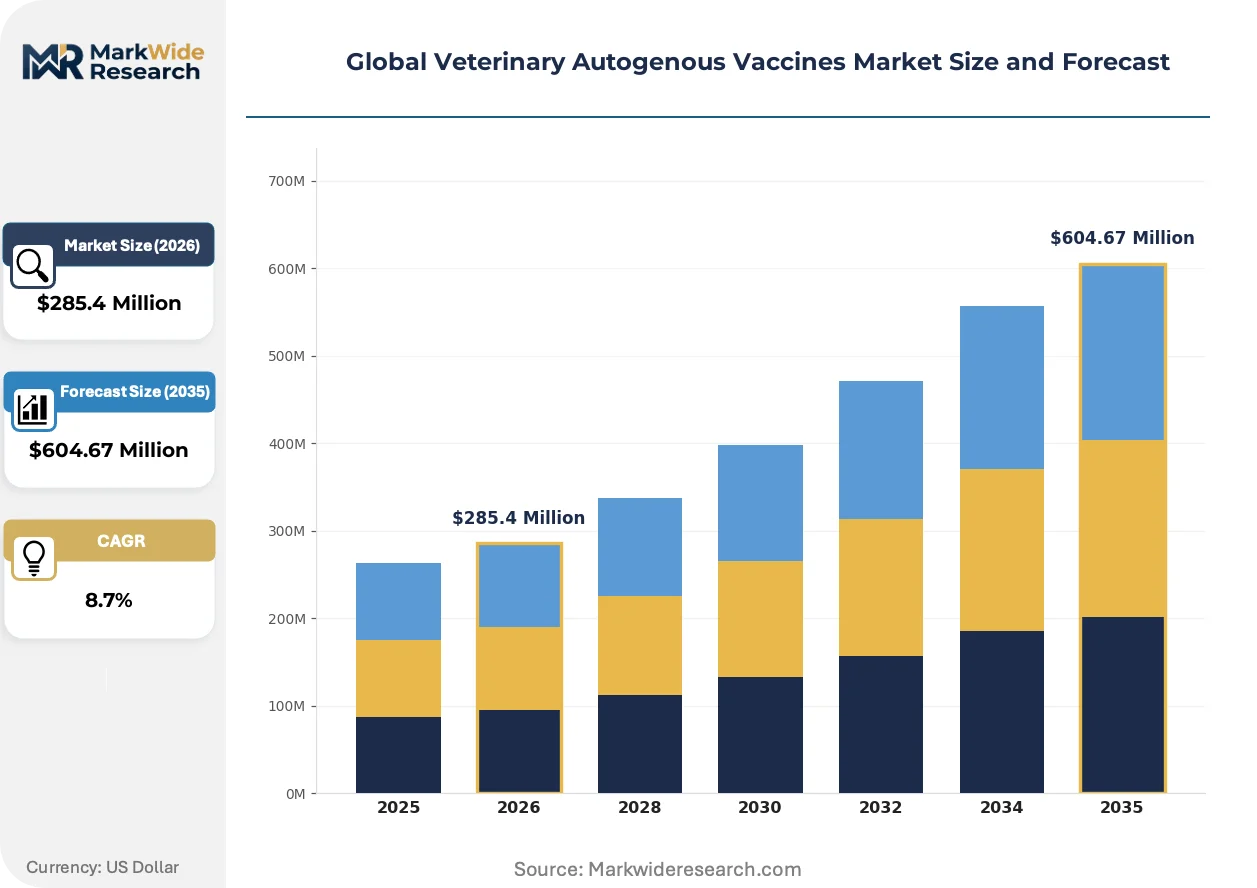
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacterin, Toxoid, Live Attenuated, Subunit, Recombinant Animal Type: Poultry, Swine, Cattle, Aquatic Species, Equine Application: Disease Prevention, Growth Promotion, Reproductive Health, Immunity Enhancement, Parasite Control End User: Veterinary Clinics, Research Institutes, Diagnostic Laboratories, Animal Health Corporations, Livestock Farms |
| Companies Covered | Zoetis Inc., Merck Animal Health, Boehringer Ingelheim Animal Health, Elanco Animal Health, Ceva Sante Animale, HIPRA, Phibro Animal Health Corporation, Vaxxinova, Cambridge Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veterinary Autogenous Vaccines Market Shifts & Advancements
Next-generation sequencing platforms and automated adjuvant formulation systems are compressing development cycles while regulatory convergence between major jurisdictions is reshaping compliance architecture for customized immunological products.
CRISPR-Cas9 gene-editing systems are absorbing the strain attenuation workflow for viral autogenous vaccines, replacing traditional serial passage methods with precision genomic modification. Swine respiratory disease specialists in the United States and Denmark are adopting these platforms at accelerating pace as nucleic acid sequencing costs decline. The technology is absorbing development timelines from months to weeks, enabling rapid response to emerging farm-specific viral variants.
The EU Pharmacovigilance Guidelines for customized immunologicals are mandating real-time adverse event reporting and batch-level digital traceability across European autogenous production networks. This regulatory shift is forcing capital allocation toward integrated quality management systems and automated documentation platforms. Smaller laboratories in Germany and the Netherlands are responding through consortium structures that share compliance infrastructure costs.
Large-scale livestock operations are consolidating procurement authority into centralized veterinary services departments, displacing fragmented individual farm purchasing patterns. This behavioral shift is compressing sales cycles and elevating contract negotiation sophistication among buyers in the United States, Brazil, and Australia. Veterinary service integrators in these markets are capturing margin through multi-year autogenous supply agreements with guaranteed pathogen surveillance components.
Global Veterinary Autogenous Vaccines Market Segmentation
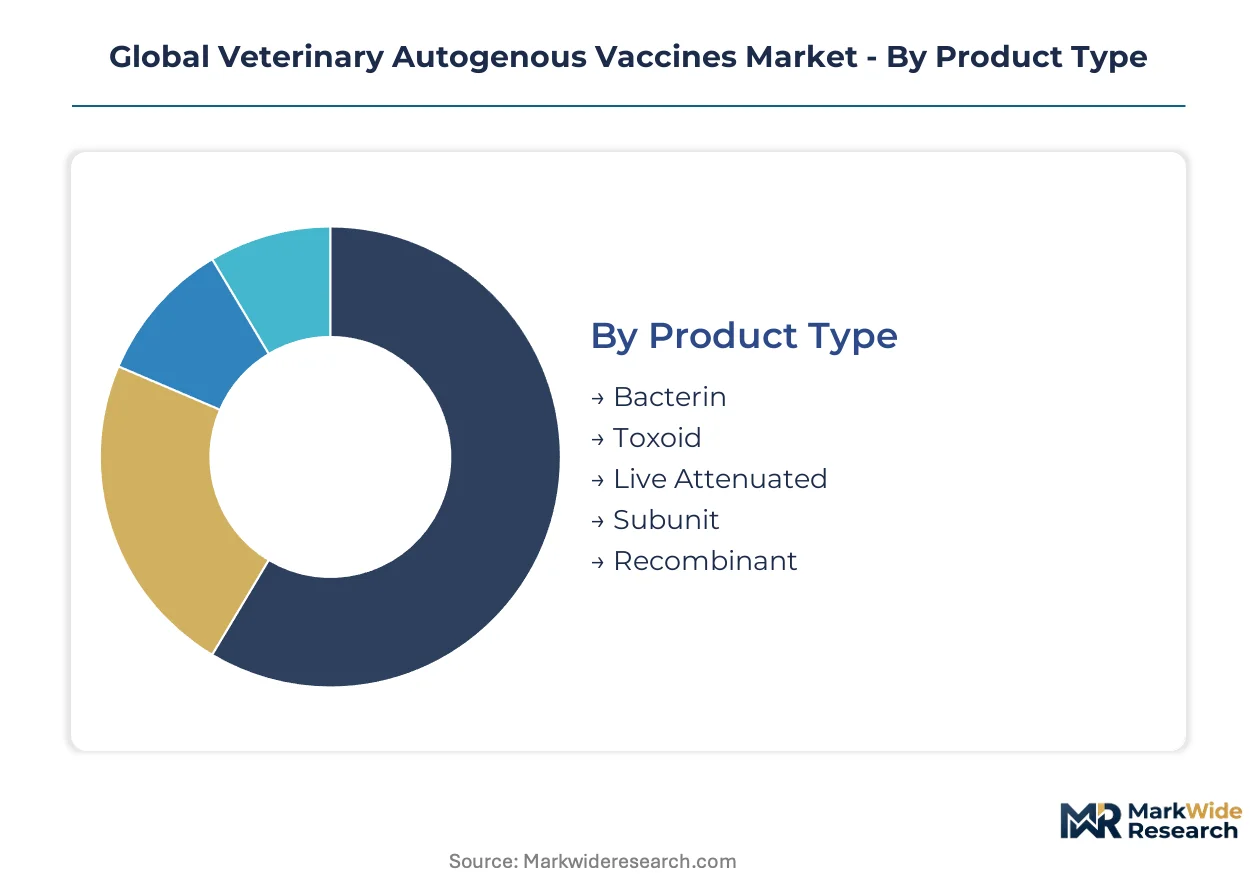
Segmentation in veterinary autogenous vaccines reveals how production capabilities, regulatory pathways, and farm-level disease pressures fragment demand across immunological formats and animal production systems. Manufacturers configure service portfolios around specific pathogen categories and customer scale tiers rather than pursuing horizontal coverage.
Product Type:
Upgrade cycles in autogenous vaccine platforms track regulatory dossier maturity against nucleic acid sequencing cost curves, with established formats retaining volume leadership while gene-editing-enabled categories capture expansion.
- Bacterin:Heat-killed bacterial suspensions formulated with aluminum hydroxide adjuvants constitute the most mature regulatory category with streamlined FDA conditional licensing pathways. Demand concentrates in United States cattle feedlots and Iowa swine operations where farm-specific bacterial isolates drive recurring multi-dose protocols. ISO 17025 accreditation requirements favor multi-site certified operators capable of batch-level documentation.
- Live Attenuated:CRISPR-Cas9 strain modification now displaces serial passage methods, compressing development timelines from months to weeks for farm-specific viral challenges. Swine respiratory disease specialists in Denmark and Texas veterinary networks are adopting these platforms as sequencing costs decline. Technical complexity in rapid attenuation for certain viral families constrains formulation beyond well-characterized pathogen groups.
- Toxoid:Formalin-inactivated exotoxin preparations targeting clostridial diseases in ruminant operations.
- Subunit:Purified antigen formulations selected for defined immune response profiles in high-value equine applications.
- Recombinant:Heterologous expression platforms for complex viral antigens not amenable to conventional propagation methods.
Bacterin sits at the top of the volume ranking, with Live Attenuated climbing the fastest.
Animal Type:
Per-animal treatment economics and disease pressure intensity stratify the addressable market, with intensive production systems justifying customized immunization investments that extensive grazing operations cannot support.
- Cattle:Large-scale dairy and beef feedlot operations in California, Texas, and Wisconsin generate recurring contract value through herd-specific mastitis and respiratory pathogen control. Zoetis diagnostic-to-vaccine pipelines anchor multi-year service agreements across these states. EMA pharmacovigilance traceability mandates are elevating documentation costs for European bovine autogenous programs.
- Swine:Industrial pork production in Iowa, North Carolina, and Denmark drives demand for multivalent respiratory syndrome formulations addressing polymicrobial challenge complexes. Boehringer Ingelheim specializes in complex autogenous combinations for these operations. CRISPR-based attenuation is absorbing development workflows for emerging viral variants in these intensive systems.
- Poultry:Vertical integration in United States broiler and layer sectors creates procurement concentration favorable to autogenous service contracts.
- Equine:Individual animal value supports premium pricing for customized immunologicals in racing and breeding operations.
- Aquatic Species:Emerging category with ANVISA pathway development for Brazilian shrimp and tilapia sectors.
Cattle captures the largest revenue pool, while Swine demonstrates the steepest expansion trajectory.
Application:
Functional positioning of autogenous vaccines follows the shift from growth-promoting antibiotics toward targeted bacterial control in livestock production systems.
- Disease Prevention:Dominant use case addressing farm-specific bacterial pathogens absent from commercial licensed vaccine catalogs. FDA conditional licensing frameworks balance expedited access with batch safety documentation for these applications. United States livestock farms are consolidating procurement authority into centralized veterinary services departments for these programs.
- Reproductive Health:Leptospirosis and campylobacteriosis control in breeding herds commands premium per-dose economics.
- Immunity Enhancement:Adjuvant-optimized priming protocols for youngstock in high-pathogen-load environments.
- Growth Promotion:Residual category contracting as antibiotic growth promoter bans displace metabolic enhancement claims.
- Parasite Control:Limited autogenous application confined to experimental helminth vaccine development in research settings.
Disease Prevention holds the dominant share, with Reproductive Health gaining share fastest.
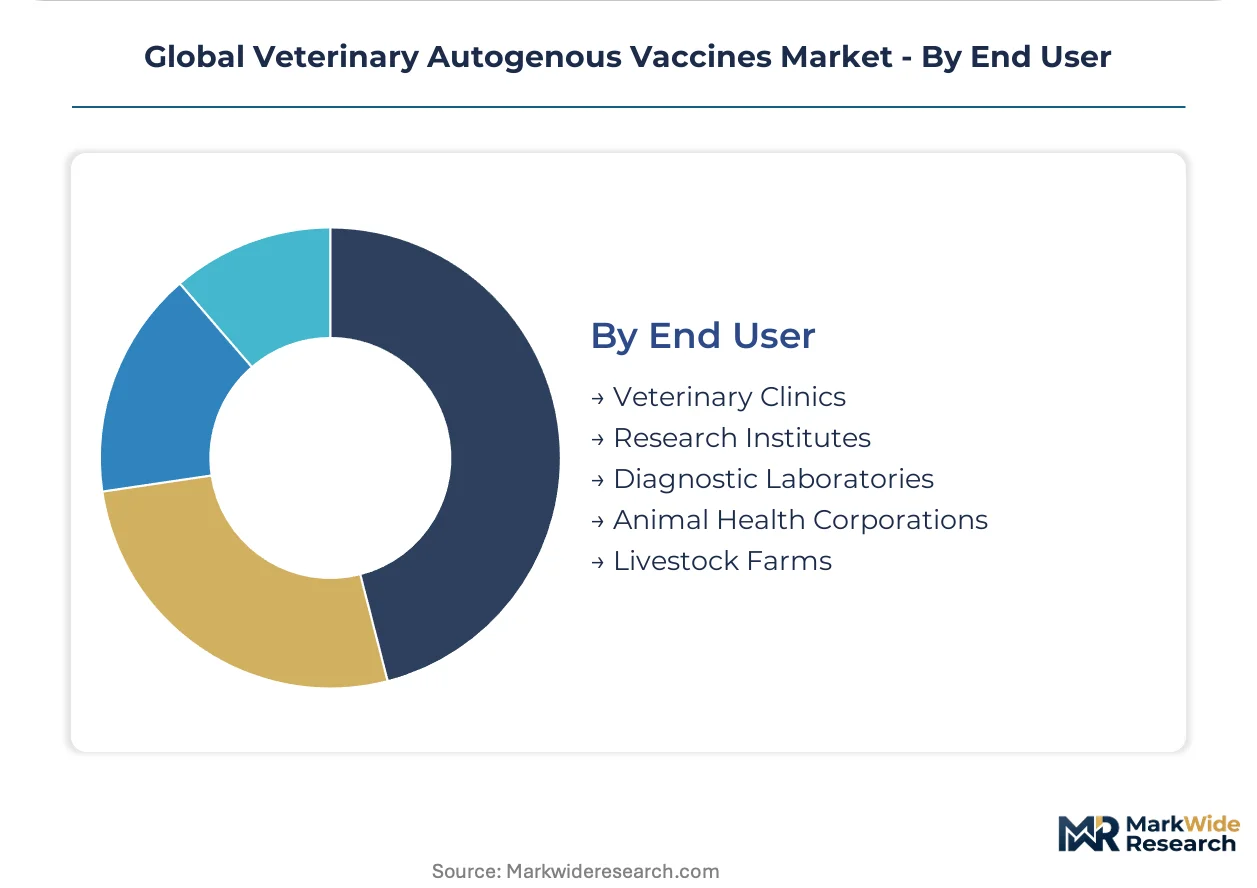
End User:
Channel structure is displacing fragmented farm-level purchasing toward integrated diagnostic-to-vaccine pipelines that compress pathogen-to-immunization turnaround times.
- Livestock Farms:Centralized veterinary services departments at large-scale United States, Brazilian, and Australian operations are consolidating procurement authority into multi-year autogenous supply agreements. These contracts increasingly embed guaranteed pathogen surveillance components. Behavioral sophistication among these buyers is compressing sales cycles and elevating negotiation leverage.
- Diagnostic Laboratories:Embedded laboratory partnerships with nucleic acid sequencing capabilities are capturing recurring contract value through rapid strain identification workflows. Merck Animal Health competes through integrated veterinary laboratory networks that shorten development cycles. ISO 17025 accreditation requirements are raising fixed cost barriers and pushing smaller regional operators toward exit or consortium structures.
- Veterinary Clinics:Mixed-animal practices serving mid-scale operations with limited in-house diagnostic capabilities.
- Animal Health Corporations:Internal autogenous production for captive supply of farm-specific formulations.
- Research Institutes:Experimental formulation development and regulatory dossier preparation for novel platform validation.
Livestock Farms command the volume leadership position, with Diagnostic Laboratories expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as ISO 17025 accreditation costs drive contract manufacturing consolidation toward multi-site certified operators in jurisdictions with harmonized FDA-EMA traceability standards.
United States
Texas and Iowa livestock operations generate concentrated demand for herd-specific bacterial vaccines as large-scale dairy and pork producers consolidate procurement authority. FDA conditional licensing frameworks balance expedited access with batch safety documentation. California veterinary networks anchor diagnostic-to-vaccine pipelines serving feedlot mastitis control programs.
Germany
Lower Saxony and Bavaria house dense clusters of swine and cattle operations requiring customized immunologicals for respiratory syndrome management. EMA pharmacovigilance guidelines mandate real-time adverse event reporting and digital batch traceability. Smaller laboratories in the Netherlands border region are forming consortium structures to share compliance infrastructure costs.
Brazil
Beef feedlots in São Paulo state and poultry vertical integrators in Paraná present underpenetrated white space for autogenous service contracts. ANVISA is developing regulatory pathways for farm-specific bacterial vaccines. São Paulo-based veterinary diagnostic networks are expanding nucleic acid sequencing capacity to capture pathogen identification workflows.
Denmark
Intensive swine production systems drive adoption of CRISPR-based live attenuated platforms for rapid strain modification. National veterinary authorities enforce strict customized immunological traceability aligned with EU guidelines. Copenhagen-area research clusters specialize in multivalent respiratory syndrome formulations for export-oriented pork operations.
Australia
Queensland and New South Wales cattle stations are consolidating procurement into centralized veterinary services departments for regional pathogen control. TGA oversight of autogenous products requires batch-level documentation comparable to EU standards. Sydney and Melbourne diagnostic laboratories are embedding rapid sequencing workflows to compress pathogen-to-vaccine turnaround times.
Global Veterinary Autogenous Vaccines Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated animal health corporations capturing premium contract value through diagnostic-to-vaccine pipelines while regional laboratories compete on turnaround speed. The vendor base concentrates around three strategic archetypes: vertically integrated pharmaceutical majors with captive autogenous divisions, multi-site certified contract manufacturers with ISO 17025 accreditation, and embedded diagnostic laboratories with rapid sequencing capabilities. Capacity expansion and strategic partnerships dominate competitive moves as laboratories seek geographic coverage and sequencing technology access.
Among pharmaceutical majors with integrated service portfolios, Zoetis Inc., Merck Animal Health, and Boehringer Ingelheim Animal Health exemplify the diagnostic-to-vaccine pipeline archetype. These entities occupy positions where pathogen surveillance contracts anchor recurring multi-year supply agreements with large-scale livestock operations. Their geographic footprints span the primary cattle and swine production clusters in the United States, Europe, and Brazil.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Merck Animal Health |
| Boehringer Ingelheim Animal Health |
| Elanco Animal Health |
| Ceva Sante Animale |
| HIPRA |
| Phibro Animal Health Corporation |
| Vaxxinova |
| Cambridge Technologies |
| Others |
Supply & Pricing Matrix
Aluminum hydroxide adjuvant sourcing from concentrated chemical suppliers in Germany and China feeds through formulation scheduling premiums into multi-tier pricing structures for bacterin and toxoid products. ISO 17025 laboratory accreditation costs in the United States and Denmark compress margins at regional operators while multi-site certified manufacturers capture pricing power through batch-level documentation guarantees.
Pricing Analysis
Distributor margins on autogenous vaccine contracts compress as large-scale livestock farms in Texas and Iowa consolidate procurement authority into direct veterinary laboratory partnerships. Three-tier pricing structure across premium, standard, and economy levels separates CRISPR-enabled live attenuated platforms from conventional bacterin formats and basic toxoid preparations. Pricing pressure stems from nucleic acid sequencing cost declines that shorten development cycles and intensify competitive bidding for multi-year service agreements. Mid-scale cattle operations in Wisconsin demonstrate highest price sensitivity, while Danish swine integrators prioritize turnaround speed over per-dose economics.
Supply Chain Analysis
Freight costs for temperature-sensitive biological materials elevate landed costs for Brazilian and Australian laboratories sourcing aluminum hydroxide adjuvants and specialized cell culture media from Germany and the United States. Production gravity centers on multi-site certified operators in Denmark, the Netherlands, and Iowa that anchor regional diagnostic-to-vaccine pipelines. Raw material dependencies on nucleic acid sequencing reagents, CRISPR-Cas9 modification kits, and formalin inactivation chemicals create single-source vulnerability for rapid attenuation workflows. Distribution runs through embedded veterinary laboratory networks rather than traditional pharmaceutical wholesalers, compressing channel layers and accelerating pathogen-to-vaccine turnaround.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as FDA and EMA documentation requirements force consolidation toward ISO 17025-accredited operators capable of batch-level digital traceability. Livestock procurement centralization into veterinary services departments shifts demand toward premium specifications with guaranteed pathogen surveillance components.
For Market Incumbents: Hedge against nucleic acid sequencing cost compression by embedding diagnostic partnerships that capture recurring contract value through rapid strain identification workflows. Defensive consolidation of regional laboratory networks in São Paulo and Queensland secures geographic coverage against emerging diagnostic-to-vaccine pipelines from Merck Animal Health and Zoetis. ISO 17025 multi-site certification investment remains the critical lever for retaining large-scale dairy and pork producer contracts. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Brazilian beef feedlot autogenous programs offers white-space entry before ANVISA pathway formalization accelerates competitive intensity. Underpenetrated poultry vertical integrators in Paraná present the most penetrable segment for nucleic acid sequencing-enabled service contracts. Go-to-market execution should anchor on rapid turnaround guarantees measured in weeks rather than months, displacing incumbent bacterin specialists on speed metrics. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale ISO 17025-accredited laboratories because EMA pharmacovigilance traceability mandates are pushing smaller regional operators toward exit or consortium structures. Long-term viability favors diagnostic-to-vaccine pipeline integrators with captive nucleic acid sequencing capacity and multi-year livestock farm contracts. The signal to watch is ANVISA regulatory pathway finalization for farm-specific bacterial vaccines, which would trigger accelerated capacity deployment into São Paulo veterinary networks.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Multi-Site Certification | EMA traceability mandates force capital allocation toward integrated quality management systems in European laboratories. |
| CRISPR-Cas9 Platform Integration | Gene-editing workflows compress swine respiratory vaccine development from months to weeks for Danish pork operations. |
| Diagnostic Laboratory Partnership | Embedded sequencing capabilities capture recurring contract value through rapid pathogen identification in Iowa swine networks. |
| ANVISA Pathway Development | Brazilian regulatory framework creation opens white-space for autogenous service contracts in São Paulo beef feedlots. |
| Consortium Structure Formation | Smaller German and Dutch laboratories share compliance infrastructure costs to meet EU pharmacovigilance digital traceability requirements. |
Research Methodology
Coverage spans North America, Europe, Latin America, and Asia-Pacific, with primary inputs from each region combined with secondary validation across regulatory filings and industry databases. Veterinary autogenous vaccine specialists, livestock farm veterinary services directors, diagnostic laboratory technical leads, and animal health regulatory affairs managers provided structured interviews on pathogen-to-vaccine workflows and procurement patterns. Secondary sources include FDA conditional licensing frameworks, EMA pharmacovigilance guidelines, ANVISA regulatory consultations, ISO 17025 accreditation databases, and veterinary laboratory network disclosures. Bottom-up segmentation modeling triangulates against top-down market sizing from animal production statistics and immunization protocol frequency data.
Rate-of-change decomposition separates volume expansion in cattle and swine populations from value-per-dose shifts across bacterin, toxoid, and live attenuated platforms over the projection horizon. Segmentation dimensions include product type, animal category, application function, and end-user channel structure, with regional regulatory cluster differentiation for FDA, EMA, and ANVISA jurisdictions. CAGRs derive from fitted growth curves applied to base-year veterinary service contract values, adjusted for nucleic acid sequencing cost decline trajectories and ISO 17025 accreditation penetration rates.
Caveats apply where aluminum hydroxide adjuvant supply disruptions, CRISPR-based attenuation technical limitations for specific viral families, or accelerated FDA-EMA regulatory convergence could materially shift the outlook. Forecasts embed assumptions on livestock farm consolidation velocity and diagnostic laboratory embedded partnership adoption that may revise with macroeconomic conditions or disease outbreak patterns. Stakeholders should weight assumptions against their own operating context and regional regulatory engagement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Medicine
Veterinary Medicine Market
Veterinary Medicine
Animal Drugs Market
Veterinary Medicine
Veterinary Skin Care Products Market
Veterinary Medicine
Veterinary Anesthesia Market
Veterinary Medicine
Veterinary Forceps Market
Veterinary Medicine
Global Companion Animal Pharmaceuticals Market
Veterinary Medicine
US Veterinarians Market
Veterinary Medicine
Veterinary Pain Management Market
Veterinary Medicine
South Africa Veterinary Medicine Market
Veterinary Medicine
Over-The-Counter (OTC) Veterinary Drugs Market
Veterinary Medicine
US Veterinary Diagnostics Market
Veterinary Medicine
Global Veterinary Eye Care Market
Veterinary Medicine
Monoclonal Antibodies in Veterinary Health Market
Veterinary Medicine
Veterinary Assistive Reproduction Technology Market
Veterinary Medicine
Veterinary Biologics Market
Veterinary Medicine
Veterinary Anesthesia Machines Market