
 Global Veterinary Eye Care Market | 2026-2036
Global Veterinary Eye Care Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veterinary Eye Care Market Foresight
The EU Veterinary Medicines Regulation is repositioning the cost-of-entry calculus for ophthalmic drug developers seeking European market access. Zoetis leverages its companion animal diagnostics platform to extend into integrated eye care workflows. Boehringer Ingelheim anchors its position through sustained R&D investment in equine ophthalmology portfolios. Dechra Pharmaceuticals specializes in niche formulations for exotic species, competing against broader-spectrum rivals.
Veterinary eye care encompasses the diagnosis, treatment, and surgical management of ocular diseases across non-human species, utilizing species-specific formulations with adjusted pH, osmolarity, and viscosity parameters to accommodate anatomical variations in corneal thickness and tear film composition. Ophthalmic Drops dominate current product volumes due to their accessibility in primary care settings, though Surgical Instruments command premium margins as referral caseloads expand. Companion Animals concentrate the majority of therapeutic demand, while Glaucoma Therapy represents the fastest-growing application segment driven by diagnostic advances enabling earlier detection.
The FDA Center for Veterinary Medicine, the European Medicines Agency, and Health Canada collectively shape product standards through divergent efficacy demonstration requirements and post-market surveillance protocols. These regulatory frameworks elevate compliance costs but simultaneously protect incumbent innovators with established pharmacovigilance infrastructure. Stakeholders must monitor evolving ophthalmic device classification criteria across jurisdictions to anticipate reimbursement and distribution pathway changes.
Market Dynamics
Pet insurance penetration for specialist procedures in the United States is compressing payment cycles and shifting diagnostic intensity toward earlier-stage interventions across companion animal practices.
Growth Catalysts
- FDA Center for Veterinary Medicine guidelines:Tightened efficacy documentation requirements for ophthalmic drug approvals are elevating clinical data standards and filtering marginal entrants from the pipeline.
- Diagnostic imaging convergence:Optical coherence tomography and confocal microscopy are migrating from human ophthalmology into veterinary referral centers, enabling subclinical disease detection.
- Companion animal specialty clinics:North American and Western European practices are expanding dedicated ophthalmology service lines to capture high-margin surgical caseloads.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient sourcing for veterinary ophthalmic formulations clusters in Chinese and Indian manufacturing zones, exposing formulators to geopolitical friction and customs delays.
- Species-specific formulation costs:Adjusted pH, osmolarity, and viscosity parameters for exotic species require low-batch production runs that erode economies of scale.
- Post-market surveillance divergence:FDA, EMA, and Health Canada maintain non-harmonized pharmacovigilance reporting frequencies, multiplying compliance overhead for multi-territory launches.
Strategic Opportunities
- Equine ophthalmology portfolios:Boehringer Ingelheim's sustained R&D investment signals underserved demand in performance horse populations across Kentucky, Dubai, and Ireland.
- Exotic species niche formulations:Dechra Pharmaceuticals' specialization in avian and reptile eye care reveals pricing power in low-competition therapeutic areas.
- Integrated diagnostics-to-treatment workflows:Zoetis leverages its companion animal diagnostics platform to bundle imaging, therapeutics, and surgical instruments under single-account contracts.
Industry Challenges
- Veterinary ophthalmology specialist scarcity:Residency-trained diplomates represent a bottleneck in referral network expansion, constraining surgical instrument utilization rates.
- Device classification uncertainty:Evolving ophthalmic device criteria across FDA, EMA, and Health Canada jurisdictions complicates reimbursement pathway planning and distributor qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veterinary Eye Care Market |
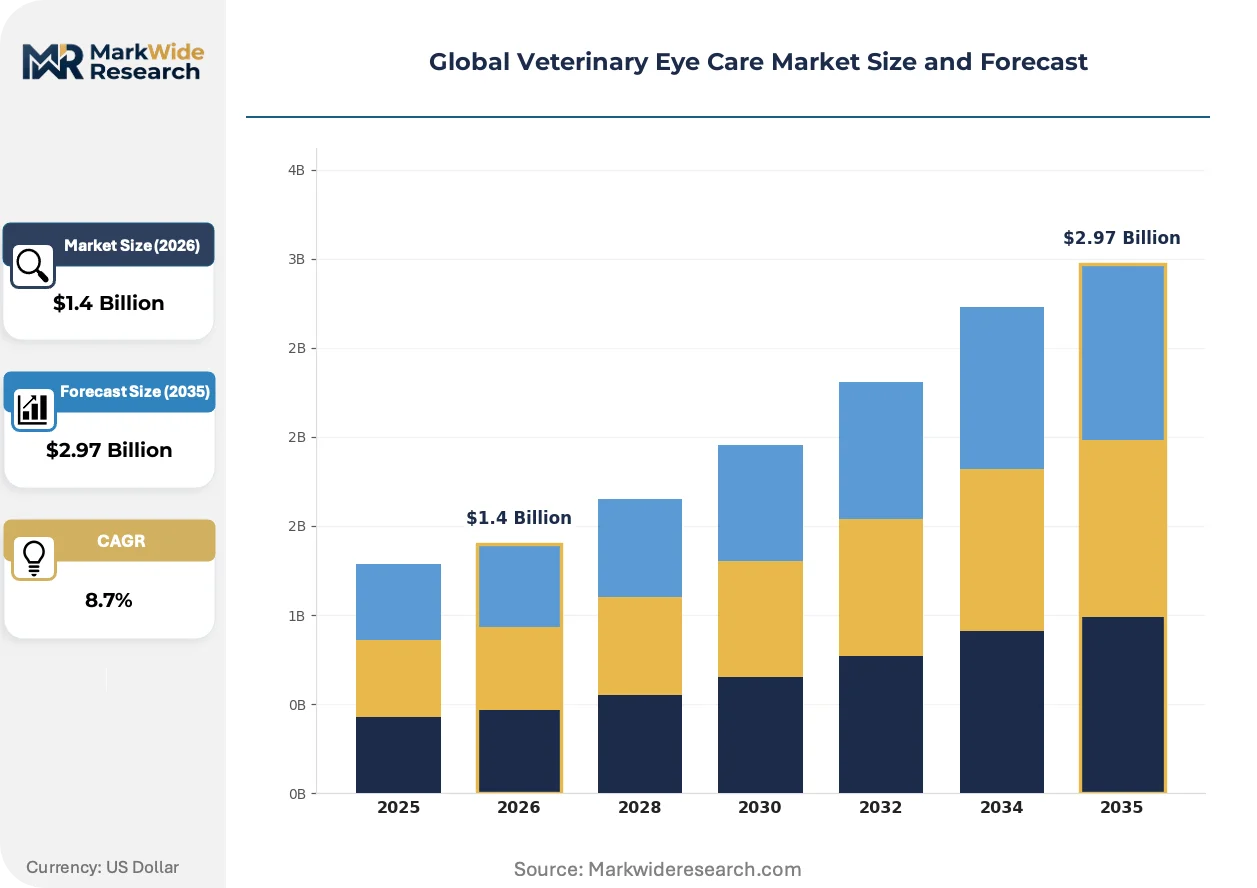
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ophthalmic Drops, Eye Ointments, Diagnostic Agents, Surgical Instruments, Contact Lenses Species: Companion Animals, Equines, Food-Producing Animals, Exotic Pets, Laboratory Animals Application: Conjunctivitis Treatment, Cataract Management, Glaucoma Therapy, Corneal Ulcer Care, Retinal Disorder Management End User: Veterinary Clinics, Specialty Hospitals, Mobile Veterinary Services, Academic & Research Institutions |
| Companies Covered | Elanco Animal Health, Boehringer Ingelheim, Zoetis, I-Med Animal Health, Ceva Santé Animale, Bausch & Lomb, Merck Animal Health, Covetrus, Dechra Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veterinary Eye Care Market Shifts & Advancements
Artificial intelligence diagnostic tools and point-of-care imaging platforms are compressing the interval between clinical presentation and definitive therapy selection in primary and referral settings alike.
Optical coherence tomography is integrating into veterinary referral workflows as a standard-of-care modality for retinal and optic nerve head assessment. Large companion animal specialty hospitals in the United States and Germany are adopting these systems at replacement cycle intervals of four to five years. The technology is integrating preoperative surgical planning with postoperative monitoring, reducing revision rates and extending instrument service contracts.
The EU Veterinary Medicines Regulation is repositioning cost-of-entry calculus for ophthalmic drug developers seeking European market access. Efficacy demonstration requirements now mandate species-specific pharmacokinetic studies that parallel human MDR standards, extending development timelines. Glaucoma therapy developers targeting France, Germany, and the Netherlands face the steepest documentation burdens.
Pet owner payment behavior is fragmenting across insurance reimbursement, wellness plan bundling, and direct out-of-pocket settlement. United States companion animal practices report rising administrative overhead from multi-payer claim adjudication. Channel conflict between direct-to-consumer telemedicine platforms and traditional referral networks is most acute in metropolitan California, Texas, and Florida markets.
Global Veterinary Eye Care Market Segmentation
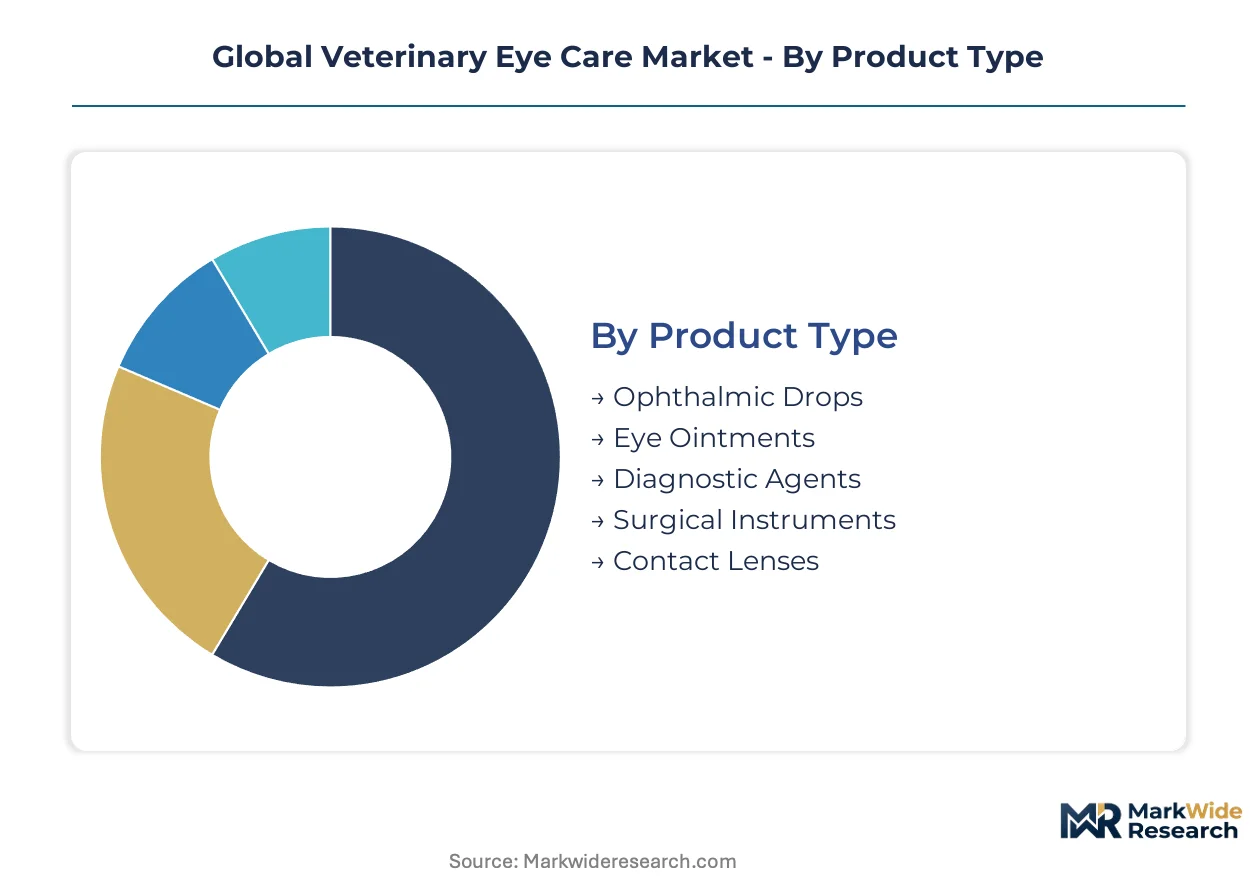
Veterinary eye care segmentation reflects divergent clinical workflows across primary, referral, and field settings. Product form factors, species anatomical variation, and end-user infrastructure capabilities each create distinct purchasing patterns and replacement cycles.
Product Type:
Replacement cycles for ophthalmic consumables compress toward 12-18 month intervals in high-throughput practices, while capital equipment extends across 4-5 year horizons.
- Ophthalmic Drops:Aqueous and viscous formulations with species-adjusted pH and osmolarity parameters dominate primary care dispensing volumes. Demand clusters in United States companion animal practices where pet insurance reimbursement accelerates prescription frequency for chronic conditions.
- Surgical Instruments:Microsurgical forceps, viscoelastic cannulas, and phacoemulsification handpieces command premium positioning in referral centers. German and United States specialty hospitals drive replacement demand as optical coherence tomography integration necessitates instrument precision upgrades.
- Eye Ointments:Semisolid petrolatum-based vehicles with prolonged corneal contact time serve postoperative and nocturnal dosing protocols in equine and exotic species.
- Diagnostic Agents:Fluorescein strips, Schirmer tear test kits, and topical anesthetics support point-of-care screening in mobile and clinic settings.
- Contact Lenses:Therapeutic bandage lenses for corneal protection occupy niche positioning in academic veterinary medical centers.
Volume placements concentrate in Ophthalmic Drops; the faster expansion belongs to Surgical Instruments.
Species:
Cost tier stratification separates high-margin exotic species formulations from volume-driven companion animal therapeutics.
- Companion Animals:Canine and feline populations concentrate therapeutic demand through insured specialist procedures and wellness plan bundling. United States metropolitan markets show diagnostic intensity shifting toward earlier-stage glaucoma and retinal interventions.
- Exotic Pets:Avian, reptile, and small mammal ophthalmology commands formulation premiums due to low-batch production requirements and veterinary specialist scarcity. Dechra Pharmaceuticals' niche positioning reveals pricing power in this underserved segment.
- Equines:Performance horse populations across Kentucky, Dubai, and Ireland generate sustained surgical instrument demand for traumatic injury management.
- Food-Producing Animals:Cattle and swine ocular therapeutics face cost constraints from agricultural economics, favoring multi-purpose antimicrobial formulations.
- Laboratory Animals:Rodent and rabbit eye care supports toxicology and pharmaceutical research protocols in academic and contract research organizations.
Revenue concentration sits with Companion Animals; Exotic Pets gain share fastest on specialist scarcity and formulation premiums.
Application:
Diagnostic imaging convergence is redrawing application boundaries as subclinical detection expands addressable caseloads.
- Glaucoma Therapy:Tonometry and optical coherence tomography advances enable pressure monitoring and optic nerve head assessment before vision loss. United States and German referral centers are expanding dedicated service lines for this indication.
- Cataract Management:Phacoemulsification surgical volumes climb as pet owner willingness-to-pay for vision restoration procedures rises in insured populations.
- Conjunctivitis Treatment:Topical antimicrobial and anti-inflammatory formulations address the most frequent presenting complaint in primary care.
- Corneal Ulcer Care:Grid keratotomy instruments and cyanoacrylate tissue adhesives serve deep ulcer management in brachycephalic breeds.
- Retinal Disorder Management:Electroretinography and genetic testing integration supports inherited disease protocols in predisposed breeds.
Procedure volumes peak in Conjunctivitis Treatment; Glaucoma Therapy climbs the fastest on diagnostic penetration.
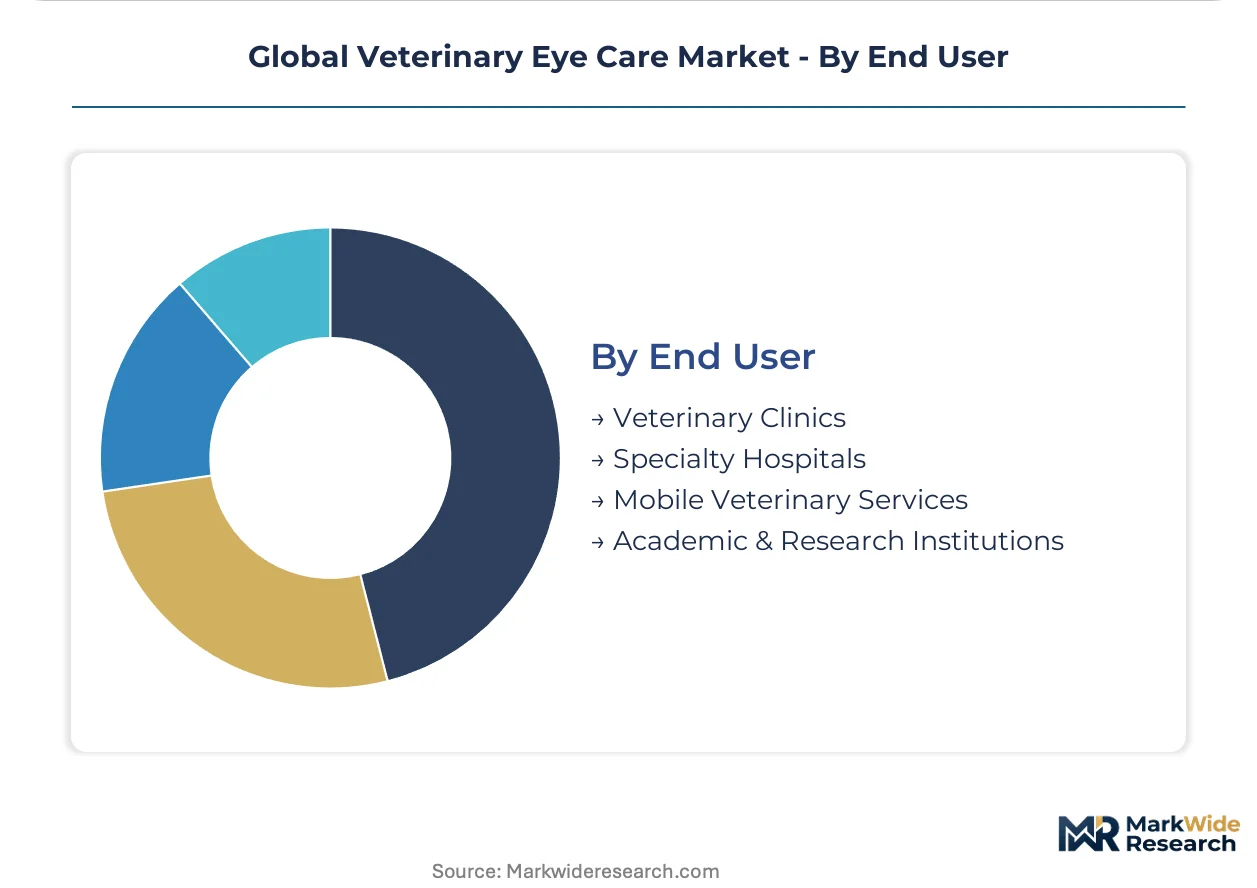
End User:
Customer type determines procurement centralization, with specialty hospitals consolidating multi-modality purchasing under integrated vendor contracts.
- Specialty Hospitals:Large companion animal referral centers in the United States and Germany bundle imaging, therapeutics, and surgical instruments under single-account agreements. Zoetis leverages diagnostics platforms to anchor these consolidated relationships.
- Veterinary Clinics:Primary care practices concentrate ophthalmic drop volumes while referring surgical cases, creating channel tension with telemedicine platforms in California, Texas, and Florida metropolitan markets.
- Mobile Veterinary Services:Field-based practitioners prioritize portable diagnostic agents and telemedicine integration for remote consultation.
- Academic & Research Institutions:Veterinary medical schools and contract research organizations drive contact lens and laboratory animal segment demand for training and protocol requirements.
Account concentration favors Specialty Hospitals; Mobile Veterinary Services expand most quickly on rural access gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pet insurance penetration for specialist procedures concentrates demand generation in the United States, while regulatory harmonization efforts in Europe and diagnostic infrastructure buildouts across Asia-Pacific reshape competitive access patterns.
United States
Companion animal specialty clinics in California, Texas, and Florida metropolitan markets are expanding dedicated ophthalmology service lines to capture high-margin surgical caseloads. The FDA Center for Veterinary Medicine guidelines tighten efficacy documentation requirements for ophthalmic drug approvals, elevating clinical data standards for new entrants. The Greater Boston and Pacific Northwest veterinary medical centers anchor adoption of optical coherence tomography systems at four-to-five-year replacement cycles.
Germany
Large companion animal referral hospitals in Bavaria and North Rhine-Westphalia bundle imaging, therapeutics, and surgical instruments under single-account vendor contracts. The EU Veterinary Medicines Regulation mandates species-specific pharmacokinetic studies that parallel human MDR standards, extending development timelines for glaucoma therapy developers. The Baden-Württemberg industrial corridor concentrates precision instrument manufacturing for microsurgical forceps and phacoemulsification handpieces.
United Kingdom
London and Southeast England veterinary practices report rising administrative overhead from multi-payer claim adjudication as pet owner payment behavior fragments across insurance reimbursement and wellness plan bundling. The Veterinary Medicines Directorate aligns with EMA post-market surveillance protocols, multiplying compliance overhead for multi-territory launches. The Midlands region hosts contract research organizations driving laboratory animal eye care demand for toxicology protocols.
France
Île-de-France referral centers face the steepest documentation burdens under EU Veterinary Medicines Regulation efficacy demonstration requirements for ophthalmic drug developers. ANSM pharmacovigilance reporting frequencies diverge from FDA and Health Canada standards, complicating reimbursement pathway planning. The Auvergne-Rhône-Alpes cluster supports equine ophthalmology surgical instrument demand for performance horse populations.
Japan
PMDA regulatory frameworks for veterinary ophthalmic devices protect incumbent innovators with established pharmacovigilance infrastructure while filtering marginal entrants. The Kanto/Tokyo metropolitan area concentrates diagnostic imaging convergence as optical coherence tomography migrates from human ophthalmology into veterinary referral centers. METI industrial policy supports point-of-care imaging platform development for primary care settings.
Global Veterinary Eye Care Market Competitive Landscape
United States producers anchor one tier; European specialists hold formulation expertise in species-specific therapeutics. The vendor base stratifies across integrated animal health conglomerates, dedicated ophthalmic device fabricators, and niche exotic species formulators. Three archetypes dominate: diagnostics-to-treatment workflow integrators, premium surgical instrument suppliers, and low-batch exotic species specialists. Competitive moves concentrate on strategic partnerships for imaging-therapeutic bundling and geographic expansion into underpenetrated metropolitan markets.
Among United States-based animal health conglomerates, Zoetis, Elanco Animal Health, and Merck Animal Health exemplify the diagnostics-to-treatment workflow integration archetype. Boehringer Ingelheim and Dechra Pharmaceuticals represent European specialists with differentiated positioning—Boehringer Ingelheim anchors equine ophthalmology portfolios while Dechra Pharmaceuticals occupies the exotic species niche formulation tier. Ceva Santé Animale and I-Med Animal Health sit within the mid-scale dedicated ophthalmic device and therapeutic supplier segment.
| Leading Market Players |
|---|
| Elanco Animal Health |
| Boehringer Ingelheim |
| Zoetis |
| I-Med Animal Health |
| Ceva Santé Animale |
| Bausch & Lomb |
| Merck Animal Health |
| Covetrus |
| Dechra Pharmaceuticals |
| Others |
Supply & Pricing Matrix
EU Veterinary Medicines Regulation species-specific pharmacokinetic mandates gate qualified supply access for ophthalmic drug developers, filtering marginal entrants and concentrating premium-tier pricing power with established pharmacovigilance infrastructure holders.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid fulfillment with premium positioning while spot inventory clears at discounted rates. Ophthalmic drops command per-unit transactional pricing in primary care settings, with differentiation resting on FDA Center for Veterinary Medicine approval tier and species-specific formulation complexity. Cost compression in generic antimicrobial formulations is intensifying because of API oversupply from Indian manufacturing zones. Food-producing animal segments exhibit acute price sensitivity; companion animal specialty hospitals show inelastic demand for surgical instrument precision grades.
Supply Chain Analysis
Direct-to-specialty-hospital channels handle consolidated procurement demand from United States and German referral centers bundling imaging, therapeutics, and instruments under single-account contracts. Active pharmaceutical ingredient sourcing for veterinary ophthalmic formulations clusters in Chinese and Indian manufacturing zones, drawing from excipient suppliers in Germany and packaging material providers in the United States. Single-source vulnerability concentrates in phacoemulsification handpiece optical components tethered to Japanese precision manufacturers. Distribution runs through veterinary distribution cooperatives and direct field sales organizations serving metropolitan California, Texas, and Florida markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over companion animal diagnostics platforms determines workflow bundling leverage and account consolidation power.
For Market Incumbents: Acquire point-of-care imaging platform capabilities to anchor specialty hospital single-account contracts against telemedicine platform disintermediation. Deepen backward integration into exotic species formulation manufacturing to capture pricing premiums from low-batch production scarcity. Consolidate equine ophthalmology surgical instrument supply relationships across Kentucky, Dubai, and Ireland performance horse clusters. For New Entrants and Emerging Players: Begin with exotic pet ophthalmology formulations where Dechra Pharmaceuticals' niche positioning reveals underserved demand and limited specialist competition. Target mobile veterinary services in rural United States access gaps where portable diagnostic agent demand outpaces established distribution coverage. Pursue telemedicine-integrated diagnostic agent bundles as the primary go-to-market angle. For Investors and Strategic Acquirers: FDA Center for Veterinary Medicine ophthalmic drug approval acceleration is the leading indicator that regulatory data package capabilities are becoming scarce acquisition targets. Five-to-ten-year viability favors vertically integrated animal health conglomerates with diagnostics-to-treatment workflow architectures. Monitor EU Veterinary Medicines Regulation implementation timelines as the critical inflection signal for European market access cost-of-entry shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Animal Diagnostics Platform Acquisition | Zoetis leverages imaging assets to bundle therapeutics and surgical instruments under consolidated contracts. |
| Exotic Species Formulation Manufacturing Scale-Up | Low-batch production capabilities capture pricing premiums in avian and reptile ophthalmology segments. |
| Optical Coherence Tomography Integration Partnership | German and United States specialty hospitals adopt systems at four-to-five-year replacement cycles. |
| Equine Ophthalmology Surgical Instrument Expansion | Performance horse populations across Kentucky, Dubai, and Ireland generate sustained traumatic injury management demand. |
| Telemedicine Platform Diagnostic Agent Bundling | Mobile veterinary services in California, Texas, and Florida metropolitan markets face acute channel tension. |
Research Methodology
Independent corroboration across veterinary ophthalmology specialist interviews, pharmaceutical regulatory affairs consultations, and specialty hospital procurement manager discussions underwrites the qualitative findings. Primary fieldwork engaged drug development executives at animal health conglomerates, formulary directors at United States pet insurance carriers, and distribution channel partners in European veterinary cooperatives. Secondary validation drew from FDA Center for Veterinary Medicine guidance documents, EMA veterinary medicines assessment reports, and Health Canada pharmacovigilance databases. Bottom-up prescription volume modeling and top-down animal health market sizing triangulate segment estimates.
Comparable-period anchoring tied projection trajectories to historical reference intervals spanning regulatory implementation phases and diagnostic technology adoption cycles. The analytical framework segments across product type, species, application, and end-user infrastructure capability throughout the forecast period. CAGRs derive from weighted average growth rates across United States, Germany, United Kingdom, France, and Japan country clusters. Modeled inputs incorporate pet insurance penetration curves, optical coherence tomography replacement cycle intervals, and EU Veterinary Medicines Regulation compliance cost escalations.
Underlying measurement precision varies by segment; ophthalmic drops and companion animal therapeutics carry tighter precision than exotic species formulations and laboratory animal applications. Forecasts reflect assumptions regarding regulatory harmonization timelines, API supply chain stability, and veterinary specialist residency training throughput. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Medicine
Veterinary Anesthesia Market
Veterinary Medicine
Global Veterinary/Animal Vaccines Market
Veterinary Medicine
Veterinary Anti-Infectives Market
Veterinary Medicine
Global Brucellosis Vaccines Market
Veterinary Medicine
Veterinary Wellness Market
Veterinary Medicine
United States Veterinary Healthcare Market
Veterinary Medicine
Veterinary Medicine Market
Veterinary Medicine
Middle East Veterinary Vaccines Market
Veterinary Medicine
Veterinary Assistive Reproduction Technology Market
Veterinary Medicine
Animal Drugs Market
Veterinary Medicine
ASEAN Rabies Veterinary Vaccines Market
Veterinary Medicine
Veterinary Biologics Market
Veterinary Medicine
US Veterinary Orthopedic Medicine Market
Veterinary Medicine
Veterinary Forceps Market
Veterinary Medicine
Veterinary Orthopedic Medicine Market
Veterinary Medicine
Veterinary Palliative Care Management Market