
 Animal Drugs Market | 2026-2036
Animal Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Drugs Market Analysis
The capital-intensity divergence between biologics innovators and generic API formulators is rotating competitive investment toward vaccine platforms and precision-delivery technologies. Zoetis Inc. leverages its vertically integrated biologics infrastructure to dominate recombinant vaccine development for livestock. Merck Animal Health anchors its position through sustained R&D spending on antiparasitic sustained-release formulations. Boehringer Ingelheim differentiates via channel control across veterinary clinic networks in North America and Europe.
Animal drugs comprise pharmacologically active compounds formulated for therapeutic, prophylactic, or growth-promoting administration to livestock, companion animals, and aquatic species, typically manufactured through fermentation, chemical synthesis, or recombinant protein expression with batch purity thresholds exceeding 98.5% for injectable grades. These products serve to control infectious disease, manage parasitic burden, and optimize feed conversion efficiency in commercial animal production. Antiparasitics command the largest revenue pool due to recurring seasonal application cycles in cattle and small ruminant operations. Vaccines represent the fastest-expanding segment as mRNA and subunit platforms displace conventional attenuated formulations. Injectable administration routes capture premium pricing relative to oral alternatives due to veterinary supervision requirements and dose-precision advantages.
The FDA Center for Veterinary Medicine enforces antimicrobial sales reporting under the Animal Drug User Fee Act, while the EMA restricts colistin and fluoroquinolone use through updated veterinary medicinal product guidelines. The USDA National Veterinary Accreditation Program further shapes market access by conditioning product distribution on certified practitioner oversight. Stakeholders must monitor evolving residue-limit harmonization between CODEX Alimentarius and national pharmacovigilance frameworks to anticipate formulation reformulation cycles and export-market eligibility shifts.
Market Dynamics
Antimicrobial stewardship mandates from the FDA Center for Veterinary Medicine and the EMA are forcing livestock producers to abandon growth-promoting antibiotic use and redirect procurement toward vaccines and precision-delivery antiparasitics.
Growth Catalysts
- mRNA vaccine platforms:Recombinant subunit and nucleic acid technologies are opening novel immunization pathways for bovine respiratory disease and avian influenza, attracting R&D capital from biologics specialists.
- Brazilian cattle herd expansion:Large-scale feedlot operations in Mato Grosso and Goiás are driving volume procurement of pour-on endectocides and clostridial vaccines for finished beef production.
- USDA National Veterinary Accreditation Program:Mandatory certified practitioner oversight for prescription veterinary products is consolidating distribution through accredited clinic networks and raising compliance-driven pharmaceutical spending.
Market Restraints
- API supply concentration:Fermentation-derived bulk actives for macrocyclic lactones concentrate in Chinese and Indian manufacturing clusters, exposing formulators to shipping volatility and customs processing delays.
- Colistin and fluoroquinolone restrictions:EMA veterinary medicinal product guidelines have eliminated these antimicrobial classes for prophylactic use in European Union member states, compressing revenue pools for legacy product lines.
- Injectable grade purity thresholds:Batch purity standards exceeding 98.5 percent for parenteral administration require capital-intensive chromatography and crystallization infrastructure that excludes mid-scale entrants.
Strategic Opportunities
- Precision-delivery wearable devices:Smart bolus and transdermal patch technologies enabling real-time therapeutic monitoring are creating white space for device-pharmaceutical convergence in North American dairy operations.
- Aquaculture expansion in Vietnam:Intensive shrimp and pangasius farming is generating unmet demand for licensed antiparasitics and bacterial vaccines in a regulatory environment still harmonizing with CODEX Alimentarius residue limits.
- US Inflation Reduction Act biomanufacturing incentives:Domestic production tax credits for active pharmaceutical ingredient reshoring are lowering facility investment hurdles for recombinant protein expression capacity.
Industry Challenges
- Recombinant protein purification expertise:Scarcity of process development specialists capable of scaling mammalian cell culture to commercial batch sizes is extending timeline-to-market for novel vaccine candidates.
- Cross-jurisdiction residue limit harmonization:Divergent maximum residue limits between CODEX Alimentarius, the FDA, and national pharmacovigilance frameworks force parallel formulation development and label expansion costs.
- Cold chain integrity for mRNA platforms:Ultra-low temperature storage requirements throughout distribution are constraining last-mile reach in rural veterinary clinic networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Drugs Market |
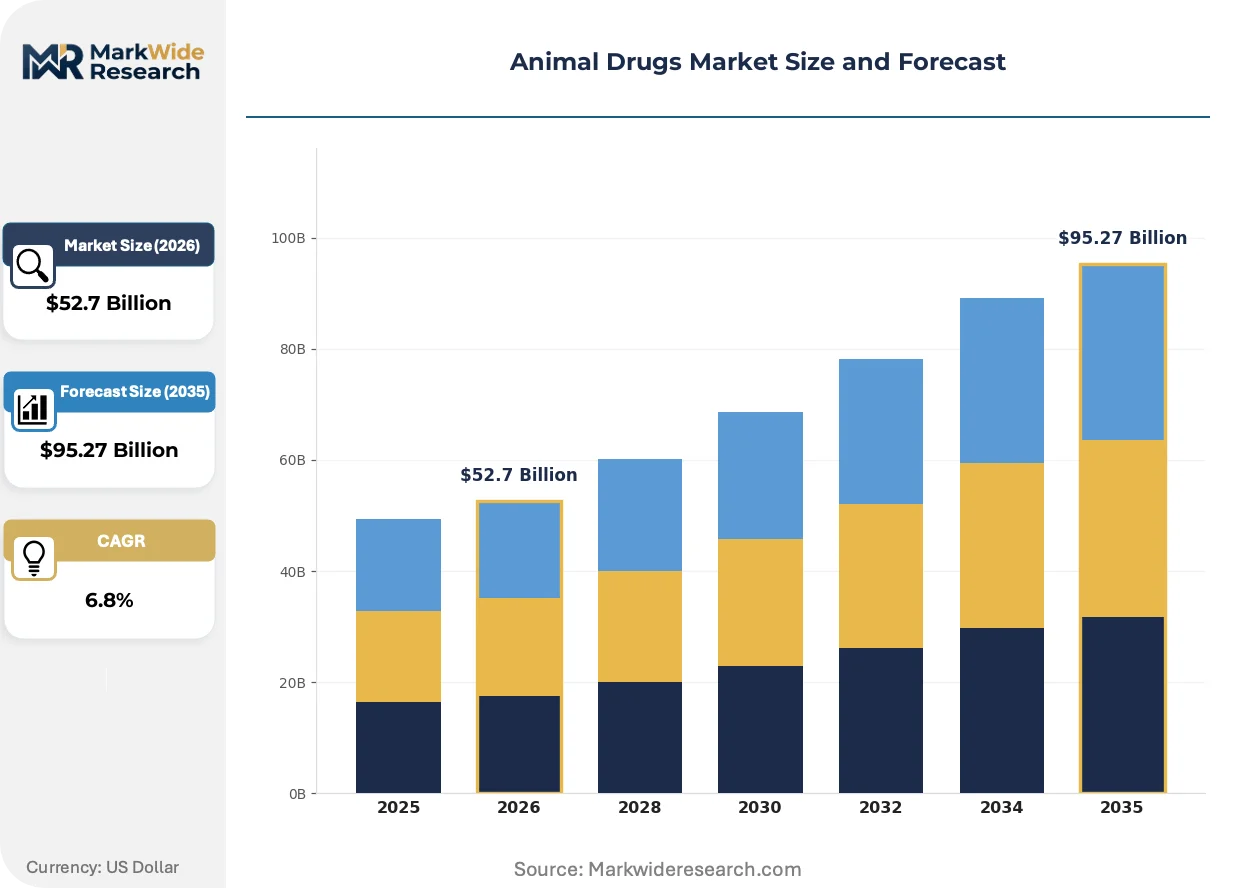
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antimicrobials, Antiparasitics, Vaccines, Hormones Application: Livestock Health, Companion Animal Care, Aquaculture, Veterinary Clinics Administration Route: Oral, Injectable, Topical, Intra-nasal Formulation Type: Powder, Liquid, Tablet, Granules |
| Companies Covered | Zoetis Inc., Merck Animal Health, Boehringer Ingelheim, Elanco Animal Health, Virbac SA, Ceva Santé Animale, Vetoquinol SA, Dechra Pharmaceuticals, Phibro Animal Health Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Drugs Market Emerging Trajectories
Biologics innovation and delivery technology convergence are redrawing competitive boundaries between pharmaceutical pure-plays and device-integrated solution providers.
Recombinant subunit vaccines utilizing viral vector and mRNA expression systems are displacing conventional attenuated and killed whole-organism formulations in commercial livestock operations. Large-scale cattle feedlots in the United States and integrated poultry producers in Brazil are accelerating adoption timelines for bovine respiratory syncytial virus and Newcastle disease platforms. This displacement is compressing manufacturing margins for legacy vaccine producers while concentrating market power among vertically integrated biologics infrastructure holders.
The EMA updated veterinary medicinal product guidelines now mandate enhanced pharmacovigilance reporting and environmental risk assessments for novel antiparasitics seeking marketing authorization. Industrial consequence includes extended regulatory review timelines and elevated clinical trial costs for ectoparasiticide innovators. European Union member state regulators are responding with conditional approval pathways that accelerate access for products demonstrating reduced environmental persistence.
Consolidated livestock operations are unbundling pharmaceutical procurement from traditional veterinary clinic dispensing models and negotiating direct supply agreements with manufacturers. This channel disintermediation is compressing distributor margins and forcing wholesaler consolidation in North American and Western European markets. The shift is most visible in United States cattle feedlots exceeding fifty thousand head capacity, where procurement teams now manage formulary decisions previously delegated to attending veterinarians.
Animal Drugs Market Segmentation
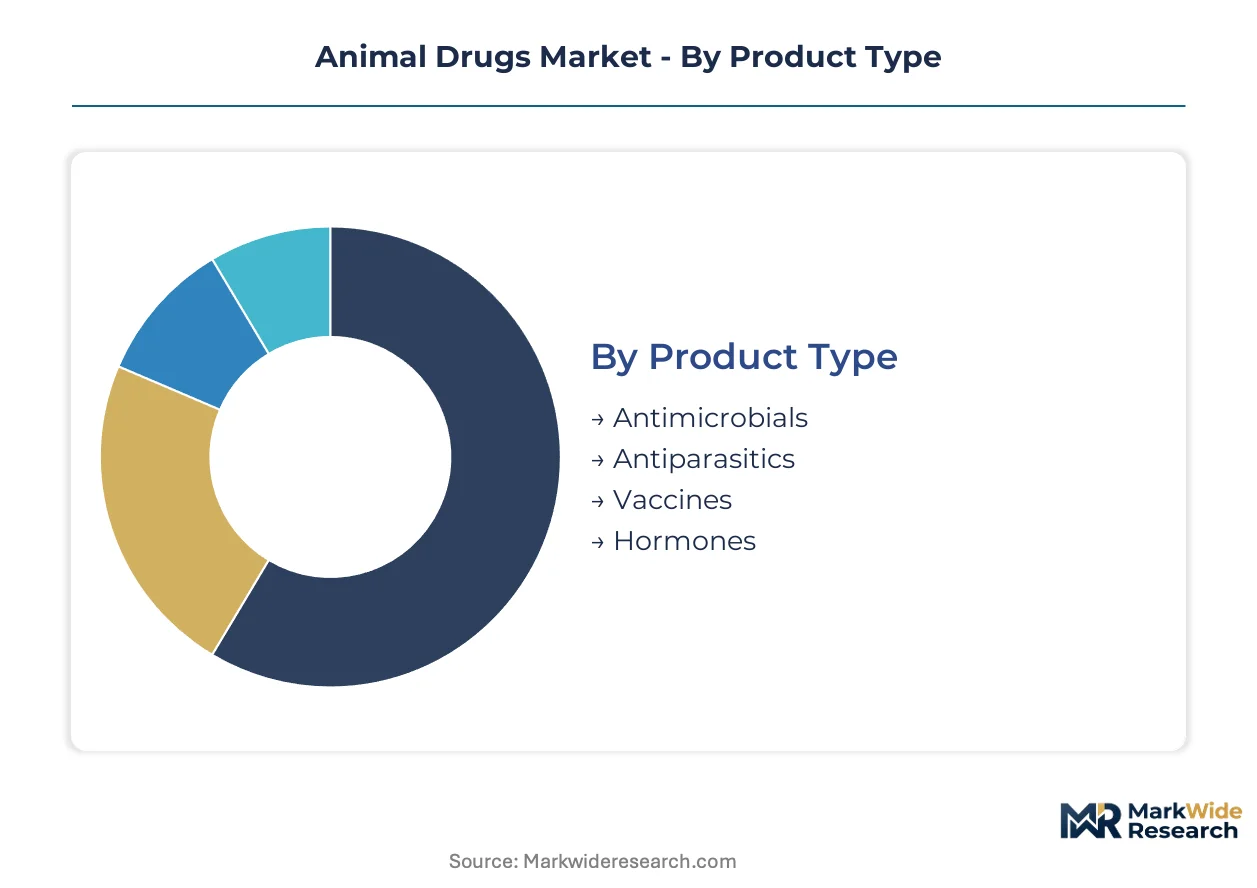
Animal drug procurement channels diverge sharply between volume livestock operations and dispersed companion animal clinics. Pharmaceutical formulators must align product specifications with distribution infrastructure, as injectable grades require cold chain integrity while oral formulations tolerate ambient logistics.
Product Type:
Channel mix varies by therapeutic class, with antiparasitics flowing through agricultural supply cooperatives and vaccines concentrating in certified veterinary networks.
- Antimicrobials:Fermentation-derived compounds including tetracyclines, penicillins, and macrolides formulated for therapeutic administration. US cattle feedlots and Brazilian feedyard operations drive volume procurement amid FDA and EMA restrictions on growth-promoting use.
- Antiparasitics:Macrocyclic lactones, benzimidazoles, and ectoparasiticides targeting helminth and arthropod burdens. Seasonal application cycles in North American cattle operations and Australian sheep stations sustain recurring revenue streams.
- Vaccines:Attenuated, killed, and recombinant subunit formulations for clostridial, respiratory, and viral diseases.
- Hormones:Growth promotants and reproductive synchrony agents regulated under national residue monitoring programs.
Antiparasitics dominate installed base. Vaccines are where expansion concentrates.
Application:
Cost tier stratification separates commodity livestock pharmaceuticals from premium companion animal therapeutics.
- Livestock Health:Mass medication protocols for disease prevention and productivity optimization in commercial production. Integrated poultry operations in Brazil and US cattle feedlots exceeding fifty thousand head drive formulation standardization.
- Companion Animal Care:Small-volume, high-margin therapeutics for canine and feline patients. Urban veterinary clinics in the United States and Western Europe command premium pricing for chronic disease management.
- Aquaculture:Licensed antiparasitics and bacterial vaccines for intensive finfish and shellfish production.
- Veterinary Clinics:Dispensing infrastructure for prescription products requiring certified practitioner oversight.
Livestock Health captures volume share. Companion Animal Care delivers margin expansion.
Administration Route:
Volume concentration favors oral delivery in feed-additive applications, while margin accrues to injectable formats requiring veterinary supervision.
- Oral:Feed additives, water-soluble powders, and bolus formulations for herd-level administration. US swine and poultry operations favor this route for antimicrobial and coccidiostat delivery.
- Injectable:Parenteral solutions and suspensions requiring batch purity exceeding 98.5 percent. Dairy operations in the United States and beef feedlots in Brazil sustain demand for long-acting formulations.
- Topical:Pour-on endectocides and transdermal applications for external parasite control.
- Intra-nasal:Mucosal vaccine delivery for respiratory disease immunization in young stock.
Oral administration leads volume throughput. Injectable formats concentrate value capture.
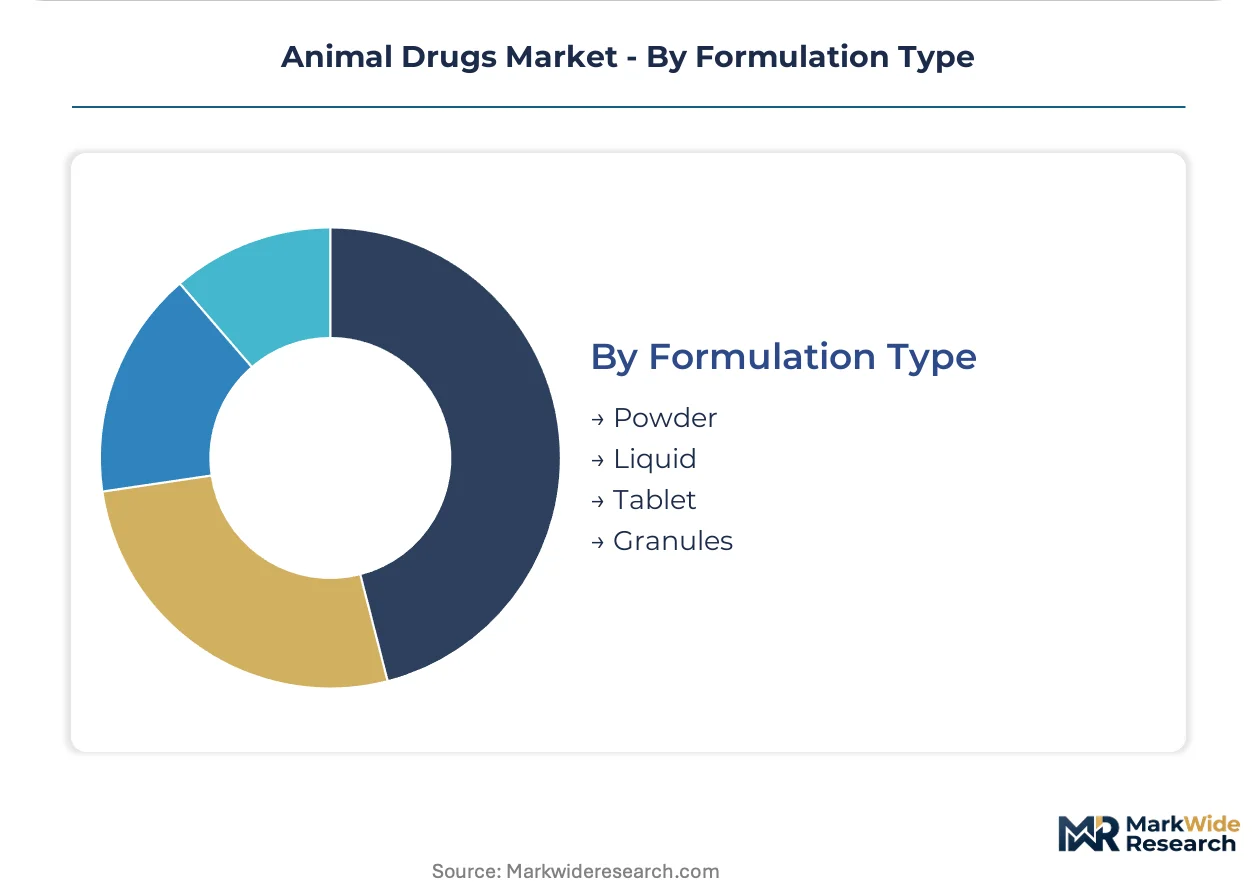
Formulation Type:
Supply concentration in powder processing infrastructure shapes competitive access for generic API formulators.
- Powder:Water-soluble and feed-premix formulations for mass medication. Chinese and Indian API clusters supply bulk actives for global compounding.
- Liquid:Injectable solutions, oral drenches, and pour-on suspensions. Sterile manufacturing requirements limit qualified supplier pools.
- Tablet:Unit-dose oral medications for companion animal precision dosing.
- Granules:Palatable coated formulations for oral administration to food-producing species.
Powder formulations anchor generic competition. Liquid formats sustain specialist margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Brazil where large-scale feedlot operations negotiate volume procurement contracts, while European producers absorb compliance premiums from antimicrobial stewardship mandates without commensurate price recovery mechanisms.
United States
Cattle feedlots exceeding fifty thousand head in Texas and Kansas drive bulk procurement of antiparasitics and respiratory vaccines. The FDA Center for Veterinary Medicine enforces antimicrobial sales reporting under the Animal Drug User Fee Act, conditioning market access on compliance infrastructure. Nebraska and Iowa host concentrated veterinary pharmaceutical distribution networks serving integrated pork and poultry operations.
Brazil
Large-scale feedyard operations in Mato Grosso and Goiás sustain volume demand for pour-on endectocides and clostridial vaccines. ANVISA harmonizes residue limit standards with CODEX Alimentarius to maintain beef export eligibility for European and Asian markets. São Paulo state anchors commercial veterinary distribution infrastructure serving the southeastern cattle corridor.
Germany
Intensive dairy operations in Lower Saxony and Bavaria sustain demand for mastitis therapeutics and reproductive hormones. The EMA restricts colistin and fluoroquinolone use through updated veterinary medicinal product guidelines, forcing procurement shifts toward vaccines and precision-delivery alternatives. Baden-Württemberg hosts specialized veterinary clinic networks consolidating pharmaceutical dispensing.
China
Pig farming consolidation in Sichuan and Henan provinces drives mass medication procurement for African swine fever prevention and respiratory disease control. The NMPA enforces batch purity thresholds exceeding 98.5 percent for injectable grades under national veterinary drug quality standards. Shandong Province concentrates fermentation-derived API manufacturing for macrocyclic lactones supplying domestic formulators.
Australia
Sheep stations in New South Wales and Victoria sustain seasonal demand for anthelmintic drenches and flystrike preventatives. The Australian Pesticides and Veterinary Medicines Authority mandates environmental risk assessments for novel ectoparasiticides seeking market authorization. Queensland hosts integrated cattle operations driving vaccine procurement for bovine ephemeral fever and clostridial diseases.
Animal Drugs Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with biologics innovators commanding premium positioning through recombinant vaccine platforms while generic API formulators compete on fermentation scale and bulk active pricing. The market structure consolidates around vertically integrated pharmaceutical conglomerates with captive biologics infrastructure, mid-scale regional formulators serving protected domestic markets, and specialized device-integrated solution providers. Strategic archetypes include biologics infrastructure holders, generic API cluster operators, and precision-delivery technology convergers. Dominant competitive moves span backward integration into recombinant protein expression capacity and geographic expansion through veterinary clinic network acquisition.
Within the biologics infrastructure tier, Zoetis Inc. and Merck Animal Health exemplify vertically integrated players with captive vaccine development capabilities, while Boehringer Ingelheim occupies a position bridging pharmaceutical formulators and channel control specialists across North American and European veterinary networks.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Merck Animal Health |
| Boehringer Ingelheim |
| Elanco Animal Health |
| Virbac SA |
| Ceva Santé Animale |
| Vetoquinol SA |
| Dechra Pharmaceuticals |
| Phibro Animal Health Corporation |
| Others |
Supply Flow & Price Mechanics
Fermentation-scale economies in Chinese and Indian API manufacturing clusters concentrate bulk active supply for macrocyclic lactones and tetracyclines, establishing price floors that generic formulators cannot undercut without sacrificing batch purity thresholds. This scale concentration compresses margins for mid-scale entrants while amplifying procurement leverage for volume livestock operations negotiating long-term offtake agreements.
Pricing Analysis
The customization-premium spread separates standard pour-on endectocides from precision-delivery formulations with real-time therapeutic monitoring capabilities. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with injectable grades commanding 15-40 percent premiums over oral alternatives due to veterinary supervision requirements. Pricing pressure stems from direct supply agreements between consolidated feedlots and manufacturers, bypassing traditional distributor markups. Commodity livestock operations in Brazil and the United States exhibit highest price sensitivity, while companion animal clinics in Western Europe absorb premium pricing for chronic disease management therapeutics.
Supply Chain Analysis
Port congestion on Shanghai-to-Rotterdam lanes and container availability constraints on trans-Pacific routes extend lead times for fermentation-derived bulk actives. Supply concentrates in Shandong Province for macrocyclic lactone APIs, Gujarat for penicillin intermediates, and Bavaria for specialized hormone formulations. Raw material dependencies include corn-derived fermentation feedstocks, chromatography resins for purification, and sterile packaging components. Single-source vulnerability concentrates in Chinese fermentation capacity for antiparasitic actives. Distribution runs through agricultural supply cooperatives for antiparasitics and certified veterinary clinic networks for prescription injectables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to Brazilian cattle herd restocking and US feedlot capacity expansion following drought-induced liquidations. Procurement normalization in North American protein production creates inventory restocking demand that lifts formulation volumes through accredited distribution channels.
For Market Incumbents: Compound channel control through veterinary clinic network acquisition in North America and Europe, locking prescription product access against generic API formulators. Prioritize backward integration into recombinant protein expression capacity to secure mRNA vaccine supply against process development specialist scarcity. Defend margin position by accelerating precision-delivery device convergence before agricultural supply cooperatives disintermediate antiparasitic distribution.
For New Entrants and Emerging Players: Cold chain logistics gaps in rural veterinary networks present white-space opportunities for last-mile distribution partnerships serving mRNA vaccine platforms. Target Vietnamese aquaculture operations with licensed antiparasitic formulations as regulatory harmonization with CODEX Alimentarius residue limits creates first-mover windows. Pursue direct supply agreements with mid-scale Brazilian feedyards as channel disintermediation weakens traditional distributor gatekeeping.
For Investors and Strategic Acquirers: Specialized precision-delivery device manufacturers with FDA 510(k) pathways and veterinary clinic integration capabilities represent priority acquisition targets. Long-term viability rests on biologics infrastructure ownership and regulatory approval velocity rather than generic API scale. Monitor EMA conditional approval pathway utilization rates as inflection indicator for environmental risk assessment burden shifts favoring reduced-persistence antiparasitic innovators.
| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Vaccine Platform Expansion | mRNA and subunit technologies displace attenuated formulations in USDA-accredited feedlot protocols. |
| Precision-Delivery Device Convergence | Smart bolus integration with pharmaceutical formulators captures dairy operation automation spending. |
| Veterinary Clinic Network Acquisition | Channel control consolidates prescription product access under FDA and EMA practitioner oversight mandates. |
| API Manufacturing Reshoring | US Inflation Reduction Act biomanufacturing incentives lower recombinant protein expression facility hurdles. |
| Environmental Risk Assessment Streamlining | EMA conditional approval pathways accelerate novel ectoparasiticide access with reduced persistence profiles. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA Center for Veterinary Medicine filings, EMA veterinary medicinal product guidelines, and USDA National Veterinary Accreditation Program standards. The research combined structured interviews with livestock procurement directors, regulatory affairs specialists at pharmaceutical formulators, veterinary clinic network administrators, and agricultural supply cooperative managers. Secondary validation drew from CODEX Alimentarius residue limit databases, ANVISA harmonization protocols, and customs trade data for fermentation-derived API flows. Bottom-up volume modeling across product type, administration route, and regional production clusters triangulated against top-down value estimates from disclosed pharmaceutical spending patterns.
Segmentation dimensions modeled include therapeutic class, species application, formulation type, and regulatory jurisdiction cluster across the projection horizon. The analytical framework derived expansion trajectories from livestock inventory cycles, antimicrobial stewardship policy implementation timelines, and biologics adoption curves in commercial feedlot operations. CAGR derivation incorporated patent expiry schedules for legacy antiparasitics, mRNA platform technology transfer rates, and precision-delivery device penetration assumptions in North American dairy operations.
Underlying assumptions cover FDA and EMA regulatory stability, Brazilian cattle herd recovery trajectories, and Chinese API export continuity, with deviation risk concentrated in residue limit harmonization failures between CODEX Alimentarius and national pharmacovigilance frameworks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Medicine
Global Veterinary Autogenous Vaccines Market
Veterinary Medicine
Global Brucellosis Vaccines Market
Veterinary Medicine
Veterinary Palliative Care Management Market
Veterinary Medicine
Veterinary Anti-Infectives Market
Veterinary Medicine
Veterinary Anesthesia Market
Veterinary Medicine
US Veterinary Orthopedic Medicine Market
Veterinary Medicine
South Africa Veterinary Medicine Market
Veterinary Medicine
Monoclonal Antibodies in Veterinary Health Market
Veterinary Medicine
US Veterinarians Market
Veterinary Medicine
Veterinary Wellness Market
Veterinary Medicine
Live Attenuated Veterinary Vaccines Market
Veterinary Medicine
Middle East Veterinary Vaccines Market
Veterinary Medicine
Veterinary Medicine Market
Veterinary Medicine
Global Newcastle Disease Vaccine Market
Veterinary Medicine
Veterinary Forceps Market
Veterinary Medicine
Over-The-Counter (OTC) Veterinary Drugs Market