
 Global Companion Animal Pharmaceuticals Market | 2026-2036
Global Companion Animal Pharmaceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Companion Animal Pharmaceuticals Market Foresight
India is narrowing its cost-competitive manufacturing gap in active pharmaceutical ingredients for veterinary use. Zoetis Inc. leverages its vertically integrated biologics network to dominate vaccine supply across North American veterinary channels. Elanco Animal Health Incorporated anchors its position through sustained R&D spending on parasiticide formulations. Boehringer Ingelheim Animal Health specializes in respiratory disease therapeutics, occupying a defensible niche in canine and feline infectious disease management.
Companion animal pharmaceuticals comprise chemically synthesized or biologically derived therapeutic agents formulated for dogs, cats, and other non-livestock species, typically dosed by weight class and administered via oral, injectable, or topical routes to prevent, treat, or manage disease conditions. These products must achieve species-specific pharmacokinetic profiles and regulatory safety thresholds distinct from human drug standards. The antiparasitics segment leads in revenue contribution due to recurring monthly dosing cycles and broad-spectrum product portfolios, while vaccines sustain the highest margin pools through cold-chain logistics barriers that limit generic competition. Nutritional supplements represent the fastest-expanding category as pet owners extend preventive health spending beyond traditional prescription boundaries.
The FDA Center for Veterinary Medicine and the EMA Committee for Medicinal Products for Veterinary Use govern market entry through distinct safety and efficacy review frameworks, with the FDA's abbreviated new animal drug application pathway accelerating generic competition in established therapeutic classes. ISO 17025 laboratory accreditation standards shape quality assurance requirements for contract manufacturing organizations serving multinational animal health companies. Stakeholders must monitor evolving antimicrobial resistance policies across major markets, as regulatory restrictions on veterinary antibiotic use threaten legacy revenue streams while creating openings for novel therapeutic modalities.
Market Dynamics
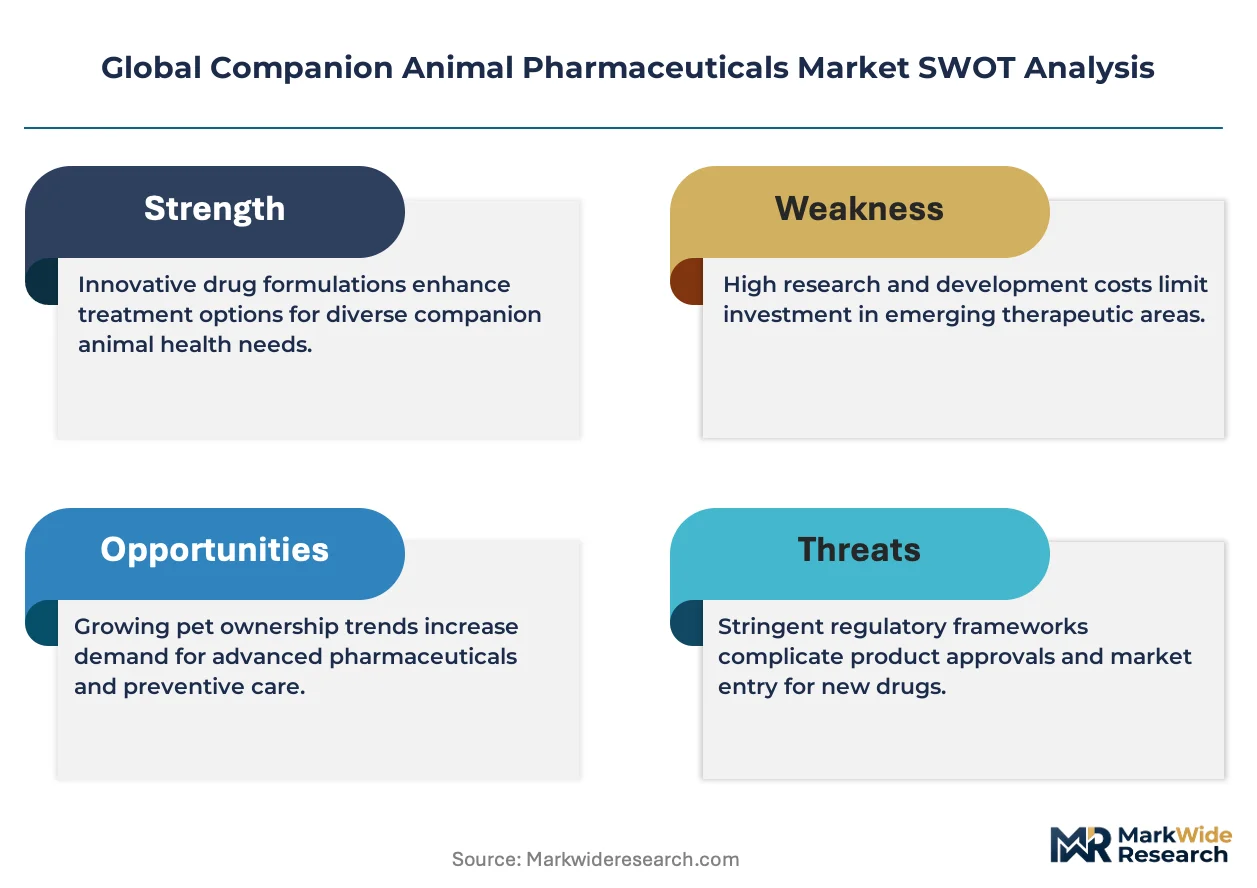
Veterinary clinics are consolidating their in-house pharmacy operations to capture recurring medication revenue, compressing traditional distribution channels while the FDA Center for Veterinary Medicine maintains rigorous approval pathways that extend competitive timelines for new molecular entities.
Growth Catalysts
- Pet insurance penetration:The United States has witnessed deepening coverage pools that expand the addressable patient base for specialty therapeutics and chronic disease management protocols.
- EMA Committee for Medicinal Products for Veterinary Use harmonization:Streamlined cross-border approval frameworks accelerate product launch velocity across European Union member states.
- Cold-chain biologics infrastructure:Advanced temperature-controlled logistics networks enable broader distribution of heat-sensitive vaccine formulations into secondary veterinary markets.
Market Restraints
- Active pharmaceutical ingredient concentration:China dominates intermediate chemical supply for veterinary manufacturing, creating geopolitical exposure and input cost volatility.
- Antimicrobial resistance policy friction:The FDA's Guidance for Industry restricts legacy antibiotic usage in companion animals, forcing portfolio restructuring without immediate revenue replacement.
- Species-specific pharmacokinetic requirements:Distinct metabolic pathways between canines and felines necessitate separate formulation development, doubling R&D expenditure per therapeutic franchise.
Strategic Opportunities
- India's contract manufacturing expansion:Cost-competitive API synthesis capabilities attract Western animal health companies seeking to diversify supply origins beyond Chinese sources.
- Nutritional supplement white space:Preventive health spending by pet owners extends beyond prescription boundaries into over-the-counter wellness categories with lighter regulatory burdens.
- ISO 17025 accreditation differentiation:Quality-certified laboratory networks command premium positioning in outsourced analytical services for multinational pharmaceutical sponsors.
Industry Challenges
- Veterinary pharmacology talent scarcity:Specialized training programs in comparative medicine produce insufficient graduates to staff expanding R&D operations and clinical trial units.
- Generic abbreviated new animal drug application competition:FDA pathway acceleration for established therapeutic classes compresses branded product lifecycle value and forces faster pipeline replenishment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Companion Animal Pharmaceuticals Market |
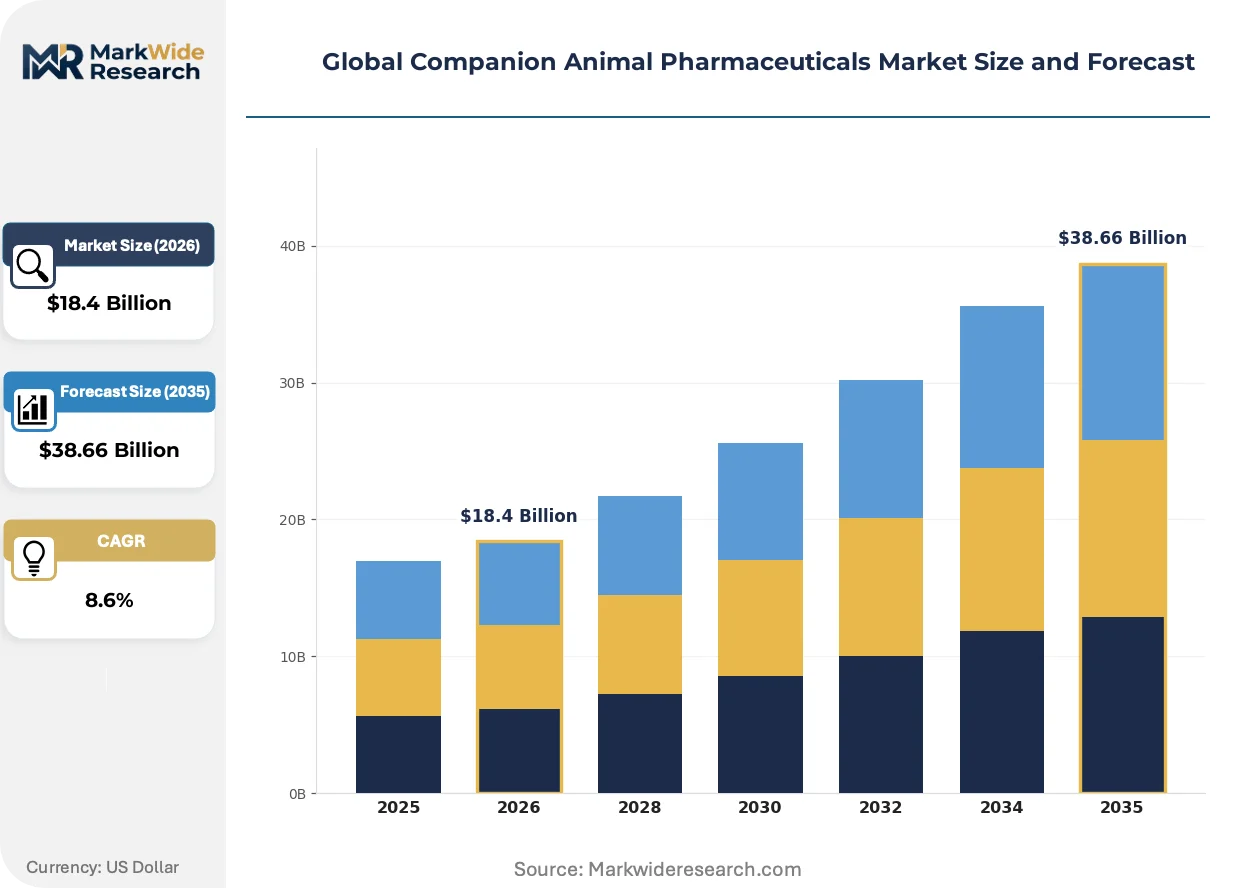
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $38.66 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antiparasitics, Antibiotics, Nutritional Supplements, Dermatologicals Therapy Area: Infectious Diseases, Endocrine Disorders, Dermatology, Musculoskeletal Conditions, Neurological Disorders End User: Veterinary Clinics, Animal Hospitals, Pet Specialty Stores, Home Care Providers Distribution Channel: Veterinary Pharmacies, Online Retailers, Wholesalers, Direct Sales |
| Companies Covered | Zoetis Inc., Elanco Animal Health Incorporated, Boehringer Ingelheim Animal Health, Merck Animal Health, Virbac, Ceva Santé Animale, Vetoquinol S.A., Dechra Pharmaceuticals Plc, Phibro Animal Health Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Companion Animal Pharmaceuticals Market Shifts & Advancements
Telemedicine platforms are virtualizing the traditional veterinary consultation model, enabling remote prescription authorization and chronic disease monitoring that reshapes how pharmaceutical products reach end patients.
Telehealth diagnostic interfaces are virtualizing preliminary clinical assessments for dermatological and behavioral conditions, allowing general practice veterinarians to triage cases before specialist referral. Small animal clinics in suburban United States markets are adopting these tools fastest, driven by staffing constraints and appointment backlogs. This virtualization compresses the traditional specialist gatekeeper role, expanding the eligible prescriber pool for advanced therapeutics previously restricted to academic referral centers.
REACH regulatory amendments governing pharmaceutical environmental discharge are forcing reformulation of topical parasiticide products across European manufacturing facilities. The industrial consequence requires biodegradability testing and aquatic toxicity screening that extends development timelines by twelve to eighteen months. Canine flea and tick prevention products face the steepest compliance burden, prompting sponsors to accelerate investment in oral systemic alternatives that bypass dermal environmental exposure pathways.
Subscription-based preventive care bundles are displacing transactional pharmacy purchasing at independent veterinary practices, locking pet owners into twelve-month medication commitments. This channel transformation concentrates purchasing volume with platform-enabled practice management software vendors rather than traditional wholesale distributors. The United Kingdom and Australia demonstrate the most advanced adoption, where corporate veterinary groups leverage scale to negotiate direct manufacturer pricing outside conventional distribution markups.
Global Companion Animal Pharmaceuticals Market Segmentation
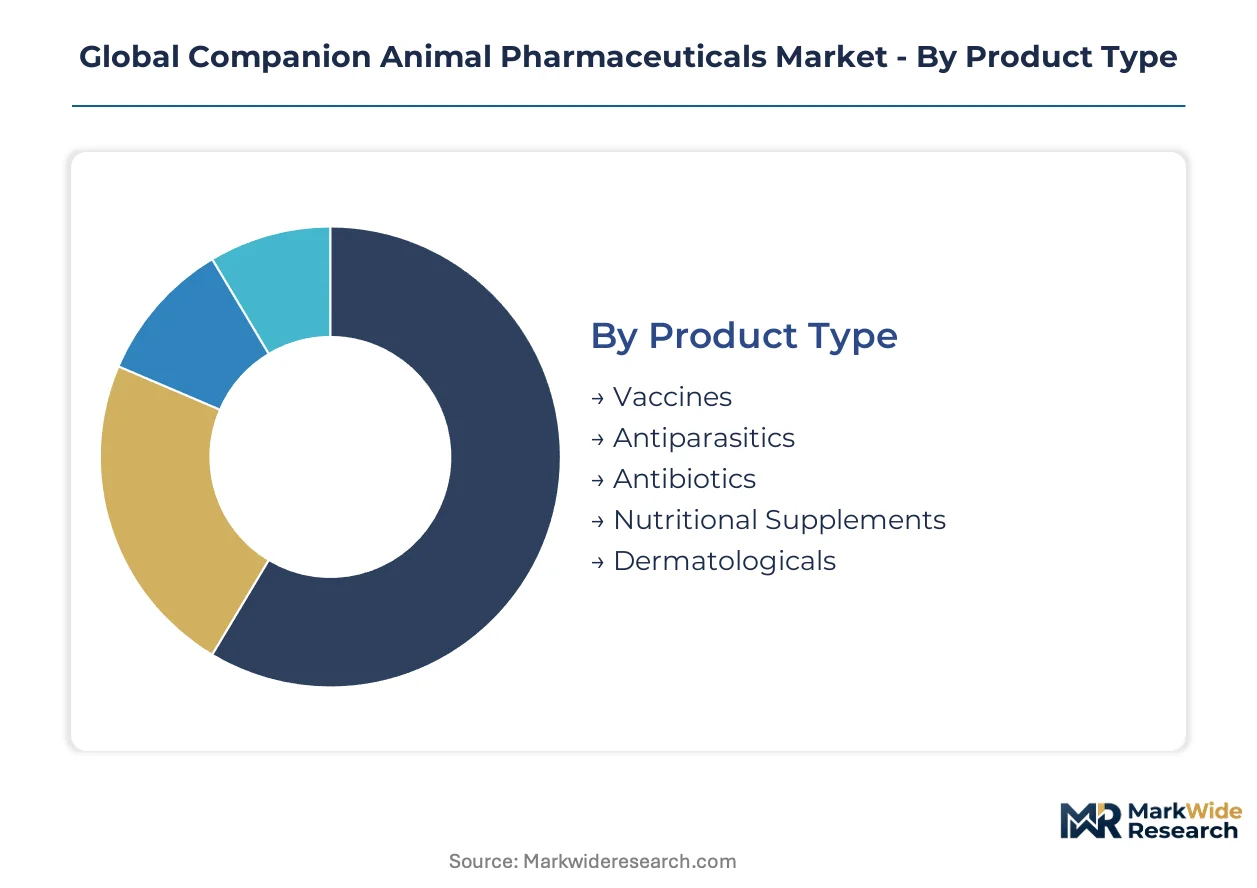
Companion animal pharmaceuticals fragment across therapeutic modality, clinical application, and procurement pathway. Each dimension carries distinct margin profiles, regulatory burdens, and customer access requirements that shape portfolio construction.
Product Type:
Cost tier differentiation separates biologic cold-chain products from commodity chemical formulations.
- Antiparasitics:Monthly-dosed formulations targeting fleas, ticks, and heartworm dominate recurring revenue streams. United States veterinary clinics capture margin through in-house dispensing of chewable and topical products, with environmental discharge regulations from ECHA driving reformulation toward oral systemic alternatives.
- Vaccines:Temperature-sensitive biologics requiring uninterrupted cold-chain logistics sustain premium positioning against generic competition. Canine core vaccines and feline respiratory combination products concentrate manufacturing with sponsors holding captive biologics infrastructure.
- Antibiotics:FDA Guidance for Industry restrictions on legacy usage compress growth trajectories in companion animal applications.
- Nutritional Supplements:Over-the-counter wellness categories with lighter regulatory burdens expand fastest as preventive spending extends beyond prescription boundaries.
- Dermatologicals:Topical formulations for allergic and infectious skin conditions serve high-visit-frequency patient cohorts.
Antiparasitics holds installed capacity. Nutritional Supplements is rotating up the share rankings.
Therapy Area:
Application focus determines clinical trial design complexity and prescriber specialization requirements.
- Infectious Diseases:Respiratory and gastrointestinal pathogens drive vaccine development priorities. Boehringer Ingelheim Animal Health concentrates R&D expenditure on canine infectious bronchitis and feline herpesvirus management protocols.
- Endocrine Disorders:Chronic insulin and thyroid supplementation protocols generate durable prescription refill patterns. Diabetic management in dogs and hyperthyroid treatment in cats sustain long-duration therapeutic relationships between veterinarians and pet owners.
- Dermatology:Atopic dermatitis and pyoderma cases generate specialty referral volume.
- Musculoskeletal Conditions:Osteoarthritis management in aging canine populations expands non-steroidal anti-inflammatory demand.
- Neurological Disorders:Seizure management and cognitive dysfunction protocols serve smaller patient pools with higher per-case pharmaceutical expenditure.
Infectious Diseases anchors the clinical trial pipeline. Dermatology is climbing the fastest as atopic condition diagnoses multiply.
End User:
Customer type dictates procurement authorization rules and inventory carrying requirements.
- Veterinary Clinics:Independent and corporate practice groups consolidate in-house pharmacy operations to capture recurring medication revenue. United Kingdom and Australian corporate groups leverage practice management platforms to negotiate direct manufacturer pricing.
- Animal Hospitals:Twenty-four-hour emergency and specialty referral centers manage complex therapeutic protocols requiring specialist prescriber credentials.
- Pet Specialty Stores:Over-the-counter nutritional supplement and preventive product distribution bypasses veterinary prescription requirements.
- Home Care Providers:Mobile veterinary services and telemedicine-enabled remote prescription authorization expand addressable geography.
Veterinary Clinics concentrate dispensing volume. Home Care Providers are gaining share fastest through platform-enabled service models.
Distribution Channel:
Supply concentration determines margin capture position between manufacturer and end patient.
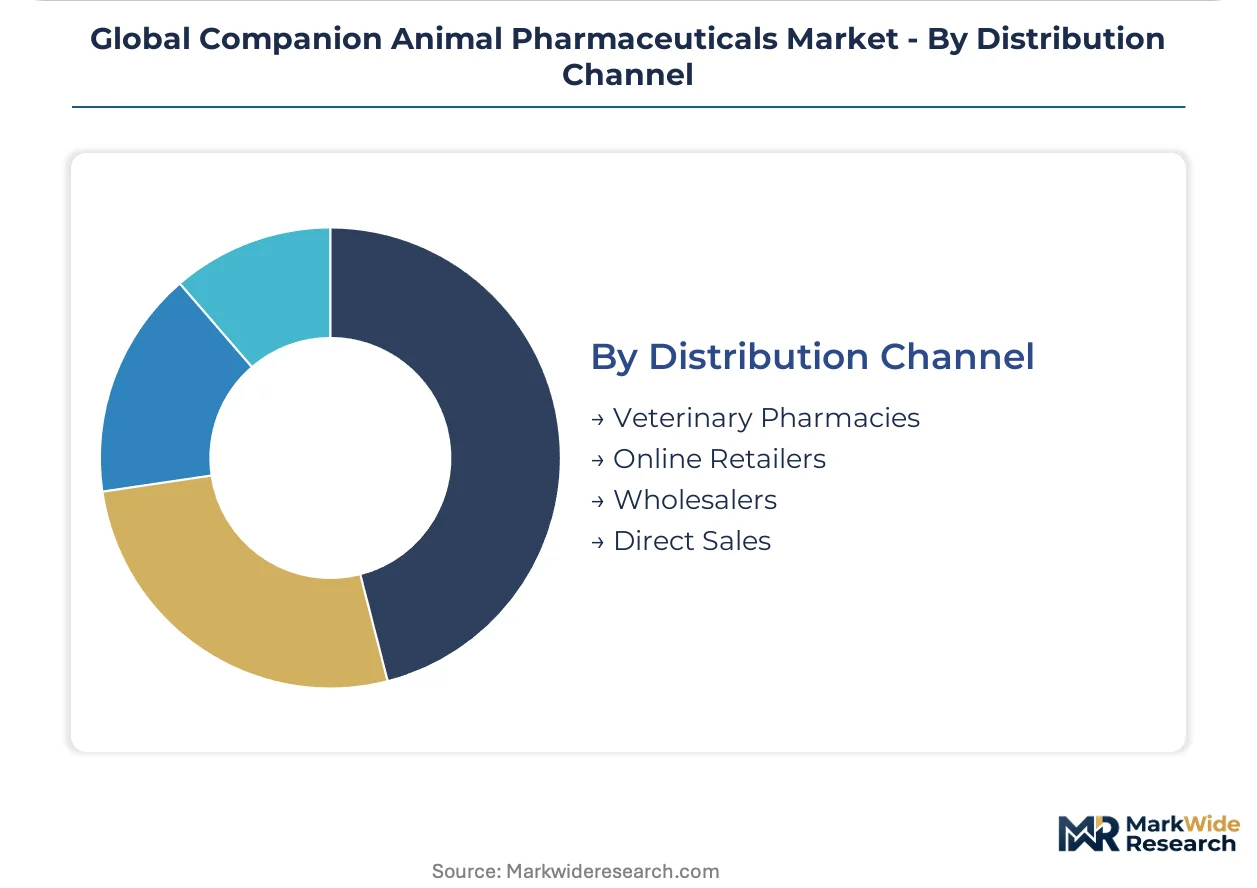
- Veterinary Pharmacies:Clinic-integrated dispensing captures markups previously allocated to wholesale intermediaries. Subscription-based preventive care bundles lock twelve-month commitments through practice management software vendors.
- Online Retailers:E-commerce platforms serving prescription verification requirements expand geographic reach beyond clinic catchment areas.
- Wholesalers:Traditional distribution infrastructure faces compression as direct manufacturer relationships proliferate.
- Direct Sales:Corporate veterinary group purchasing organizations negotiate volume pricing outside conventional markup structures.
Veterinary Pharmacies hold the dispensing infrastructure. Online Retailers are rotating up the share rankings through telemedicine integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: the United States prioritizes chronic disease management through insured specialty care, while emerging markets concentrate spend on acute infectious disease prevention and cost-optimized parasiticide protocols.
United States
Pet insurance penetration now exceeds four million covered animals, expanding the addressable pool for oncology and endocrine therapeutics. The FDA Center for Veterinary Medicine maintains abbreviated approval pathways that accelerate generic competition in mature drug classes. Corporate veterinary groups in Texas and Florida leverage practice management platforms to negotiate direct manufacturer pricing outside traditional wholesale markups.
Germany
Specialty referral centers in Munich and Berlin drive demand for advanced biologics in orthopedic and neurological applications. REACH amendments from ECHA mandate biodegradability testing for topical parasiticide formulations, extending development timelines by twelve to eighteen months. The Baden-Württemberg chemical cluster hosts contract manufacturing organizations serving Western European animal health sponsors with ISO 17025-accredited analytical capabilities.
United Kingdom
Subscription-based preventive care bundles have displaced transactional pharmacy purchasing at corporate veterinary practices, locking twelve-month medication commitments. The Veterinary Medicines Directorate enforces pharmacovigilance reporting requirements that shape post-market surveillance obligations for sponsors. Greater London corporate groups demonstrate the most advanced adoption of platform-enabled direct manufacturer negotiations.
India
Contract manufacturing expansion in Hyderabad and Ahmedabad attracts Western animal health companies seeking to diversify active pharmaceutical ingredient supply beyond Chinese sources. The Central Drugs Standard Control Organization governs veterinary drug registration through distinct safety and efficacy frameworks from human pharmaceutical standards. Gujarat's specialty chemical corridor is deepening cost-competitive synthesis capabilities for parasiticide intermediates.
Australia
Telemedicine-enabled remote prescription authorization expands addressable geography for chronic disease management in dispersed suburban and rural populations. The Therapeutic Goods Administration maintains separate veterinary medicine registration pathways that limit parallel importation from larger markets. Sydney and Melbourne corporate veterinary groups pioneer subscription preventive care models with the highest regional adoption rates.
Global Companion Animal Pharmaceuticals Market Competitive Landscape
Capability concentration sits with sponsors holding captive biologics infrastructure; scale advantage sits with diversified human health conglomerates leveraging cross-species manufacturing platforms. The market structures around three tiers: vertically integrated biologics specialists, diversified pharmaceutical divisions, and regional formulation houses serving niche therapeutic areas. Dominant competitive moves include backward integration into active pharmaceutical ingredient supply and strategic partnerships with telemedicine platform vendors to secure prescription authorization channels.
Within the biologics-specialist tier, Zoetis Inc. and Boehringer Ingelheim Animal Health occupy positions defined by cold-chain manufacturing networks and vaccine development capabilities. Elanco Animal Health Incorporated exemplifies the diversified pharmaceutical division archetype, drawing on human health R&D infrastructure to serve companion animal therapeutic needs. These three entities anchor the competitive structure through distinct capability endowments rather than overlapping strategic positioning.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Elanco Animal Health Incorporated |
| Boehringer Ingelheim Animal Health |
| Merck Animal Health |
| Virbac |
| Ceva Santé Animale |
| Vetoquinol S.A. |
| Dechra Pharmaceuticals Plc |
| Phibro Animal Health Corporation |
| Others |
Supply & Pricing Matrix
Gujarat's specialty chemical corridor anchors global parasiticide intermediate production, concentrating synthesis capacity that translates directly into margin capture for Western animal health sponsors sourcing active pharmaceutical ingredients. Contract manufacturers in Hyderabad and Ahmedabad leverage ISO 17025-accredited laboratory networks to command premium positioning in outsourced analytical services, compressing procurement timelines for multinational pharmaceutical sponsors while extending pricing power upstream.
Pricing Analysis
United States veterinary clinics capture markups 15-40% above wholesale acquisition cost through in-house dispensing of chewable and topical antiparasitic products, while European markets face pricing pressure from REACH-mandated reformulation expenses that sponsors attempt to pass through. Three-tier pricing structure across premium biologic vaccines, standard chemical parasiticides, and economy generic antibiotics separates margin pools by cold-chain complexity and regulatory exclusivity. Corporate veterinary groups in Texas and Florida negotiate direct manufacturer pricing outside traditional distribution markups, intensifying cost compression for independent practices. Price-sensitive independent veterinarians in suburban United States markets absorb margin erosion fastest, while specialty referral centers maintain least sensitivity due to insured client bases.
Supply Chain Analysis
Hyderabad-based contract manufacturers and Ahmedabad formulation houses hold expanding capacity for veterinary API synthesis, attracting Western animal health companies seeking supply diversification beyond Chinese sources. Active pharmaceutical ingredient production concentrates in India, China, and the United States, with parasiticide intermediates and vaccine adjuvants drawing from distinct geographic clusters. Raw material dependencies rest on specialty chemical precursors from Gujarat's industrial corridor, cold-chain biologics infrastructure from North American captive networks, and excipient supplies from European pharmacopeia-certified facilities. Single-source vulnerability concentrates in Chinese intermediate chemical supply, exposing sponsors to geopolitical friction and input cost volatility. Distribution runs through clinic-integrated veterinary pharmacies capturing recurring medication revenue, compressing traditional wholesale channels as subscription-based preventive care bundles lock twelve-month commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through corporate veterinary group consolidation and platform-enabled practice management software vendors, fragmenting traditional distribution intermediaries while locking purchasing volume with direct manufacturer negotiators.
For Market Incumbents: Entrench cold-chain biologics infrastructure as a defensive moat against generic abbreviated new animal drug application competition, accelerating vaccine development timelines to outpace FDA pathway erosion in chemical therapeutics. Backward integration into Indian API supply secures cost-competitive sourcing while insulating against Chinese single-source vulnerability. Channel control through telemedicine platform partnerships preserves prescription authorization access as virtual veterinary consultations expand the eligible prescriber pool. For New Entrants and Emerging Players: Australia's dispersed suburban and rural populations present underpenetrated geography for telemedicine-enabled chronic disease management, where platform-enabled service models bypass incumbent clinic infrastructure. Nutritional supplement white space offers the most penetrable segment, with lighter regulatory burdens than prescription therapeutics and preventive health spending extending beyond traditional pharmaceutical boundaries. Go-to-market through mobile veterinary services and remote prescription authorization platforms captures share fastest in geographies with veterinary staffing constraints. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue-defensibility play because subscription-based preventive care bundles lock twelve-month medication commitments and concentrate purchasing volume with platform-enabled vendors. Acquisition targets should prioritize veterinary practice management software vendors with embedded pharmacy operations and direct manufacturer pricing relationships. The signal to watch is corporate veterinary group purchasing organization consolidation velocity, as scale concentration accelerates margin compression for traditional distribution channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Supply | Captive sourcing from Gujarat and Hyderabad insulates sponsors from Chinese geopolitical exposure and input volatility. |
| Telemedicine Platform Partnership | Remote prescription authorization expands eligible prescriber pools beyond academic referral centers into general practice. |
| Cold-Chain Biologics Infrastructure Expansion | Temperature-controlled logistics networks sustain premium vaccine positioning against generic competition through distribution barriers. |
| ISO 17025 Laboratory Accreditation Investment | Quality-certified analytical capabilities command premium positioning in outsourced services for multinational pharmaceutical sponsors. |
| Subscription Preventive Care Bundle Launch | Twelve-month medication commitments lock recurring revenue and displace transactional pharmacy purchasing at independent practices. |
Research Methodology
Initial hypotheses were tested against primary input from veterinary drug development executives, regulatory affairs specialists at the FDA Center for Veterinary Medicine, corporate veterinary group procurement directors, and independent practice pharmacy managers, then refined through secondary validation. Data synthesis combined interview findings with FDA filings, EMA Committee for Medicinal Products for Veterinary Use submissions, Veterinary Medicines Directorate pharmacovigilance reports, and trade customs records. Bottom-up patient population modeling and top-down revenue triangulation anchored forecast integrity.
Demand-supply balance across the analysis window reflects companion animal demographic projections, pet insurance penetration trajectories, and veterinary clinic consolidation velocity. Segmentation dimensions modeled include therapeutic modality, clinical application focus, procurement pathway type, and regional regulatory cluster. CAGRs derived from historical prescription volume trends and sponsor R&D pipeline advancement rates, with antimicrobial resistance policy evolution and telemedicine regulatory acceptance serving as industry-specific forecast sensitivity inputs.
Practitioners should monitor FDA Guidance for Industry amendments on legacy antibiotic usage, ECHA REACH environmental discharge enforcement, and corporate veterinary group merger activity for early signals of forecast revision necessity. Quarterly review of pet insurance enrollment data, abbreviated new animal drug application filing volumes, and Indian API export customs records is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Medicine
Veterinary Biologics Market
Veterinary Medicine
Global Veterinary Autogenous Vaccines Market
Veterinary Medicine
Veterinary Dental Elevators Market
Veterinary Medicine
Veterinary Pain Management Market
Veterinary Medicine
Veterinary Orthopedic Medicine Market
Veterinary Medicine
ASEAN Rabies Veterinary Vaccines Market
Veterinary Medicine
Veterinary Anesthesia Market
Veterinary Medicine
US Veterinary Orthopedic Medicine Market
Veterinary Medicine
Animal Drugs Market
Veterinary Medicine
Veterinary Anesthesia Machines Market
Veterinary Medicine
United States Veterinary Healthcare Market
Veterinary Medicine
Veterinary Palliative Care Management Market
Veterinary Medicine
South Africa Veterinary Medicine Market
Veterinary Medicine
US Veterinary Diagnostics Market
Veterinary Medicine
Veterinary Medicine Market
Veterinary Medicine
Over-The-Counter (OTC) Veterinary Drugs Market