
 Over-The-Counter (OTC) Veterinary Drugs Market | 2026-2036
Over-The-Counter (OTC) Veterinary Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Over-The-Counter (OTC) Veterinary Drugs Market Analytics
Modular dosing formats is decoupling bulk veterinary purchasing from clinical dependency, letting livestock producers and pet owners self-select treatment tiers. Zoetis Inc. leverages its manufacturing scale across oral and topical antiparasitic lines. Merck Animal Health anchors its position through R&D intensity in transdermal delivery systems. Boehringer Ingelheim International GmbH competes on geographic dominance in European poultry and swine channels.
Over-the-counter veterinary drugs comprise non-prescription pharmaceutical preparations—antiparasitics, analgesics, antiseptics, and antibiotics—formulated in tablets, liquids, powders, or ointments for oral, topical, injectable, or transdermal administration to food-producing and companion animals. These products undergo stability testing for temperature tolerance and species-specific bioavailability to ensure therapeutic efficacy without veterinary supervision. Antiparasitics command the largest revenue pool due to recurring prophylactic use across livestock and companion segments. Oral administration routes capture expanding share as palatable chewable formulations reduce owner compliance friction. Pet owners represent the fastest-growing end-user cohort, shifting margin pools toward premium companion animal SKUs.
The FDA oversees OTC veterinary drug safety and labeling standards in the United States, while the EMA coordinates centralized assessments for European companion animal products. EPA jurisdiction intersects where antiparasitics carry environmental discharge implications, particularly for aquaculture and large livestock operations. Stakeholders must monitor evolving OTC classification thresholds that determine which formulations retain non-prescription status as antimicrobial resistance scrutiny intensifies.
Market Dynamics
The FDA's streamlined OTC approval pathways for companion animal products are compressing time-to-market cycles and redistributing margin pools toward retail-accessible formulations, fundamentally altering how veterinary pharmaceutical value chains configure.
Growth Catalysts
- Companion animal ownership expansion:Urban households in the United States and Western Europe are expanding pet populations, creating recurring demand for self-administered antiparasitic and analgesic products that bypass clinical visits.
- REACH and EMA harmonization:The European Medicines Agency's centralized assessment protocols for companion animal OTC products are reducing regulatory fragmentation across EU member states, accelerating cross-border product registration.
- Transdermal delivery maturation:Advances in transdermal absorption technology are enabling longer-acting antiparasitic formulations that improve owner compliance and extend dosing intervals for livestock and companion segments.
Market Restraints
- Active pharmaceutical ingredient concentration:Global supply of ivermectin and related antiparasitic APIs concentrates among a limited set of contract manufacturers, exposing formulators to input cost volatility and qualification delays.
- Antimicrobial resistance scrutiny:The FDA's Veterinary Feed Directive and parallel EMA guidance on responsible antibiotic use are tightening OTC classification thresholds, threatening the non-prescription status of certain legacy formulations.
- Species-specific bioavailability barriers:Pharmacokinetic variation across ruminant, monogastric, and companion animal physiologies necessitates costly reformulation cycles that fragment R&D economies of scale.
Strategic Opportunities
- Direct-to-consumer veterinary retail expansion:United States pet specialty retailers and e-commerce platforms are building dedicated OTC pharmacy sections, creating shelf-space competition previously dominated by prescription channels.
- Indian livestock producer self-selection:Dairy and poultry operations in India represent underpenetrated demand for modular antiparasitic dosing formats that reduce dependence on veterinary service infrastructure.
- EPA environmental discharge protocols:Emerging aquaculture regulations governing antiparasitic effluent are creating premium positioning opportunities for biodegradable formulations that command price premiums in certified operations.
Industry Challenges
- Veterinary pharmacovigilance capability gaps:Post-market adverse event monitoring for OTC products requires specialized toxicology expertise that mid-sized formulators struggle to staff, exposing them to regulatory enforcement risk.
- Legacy ERP integration friction:Transitioning from batch-record systems to real-time serialization for FDA track-and-trace compliance demands capital outlays that strain family-owned distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Over-The-Counter (OTC) Veterinary Drugs Market |
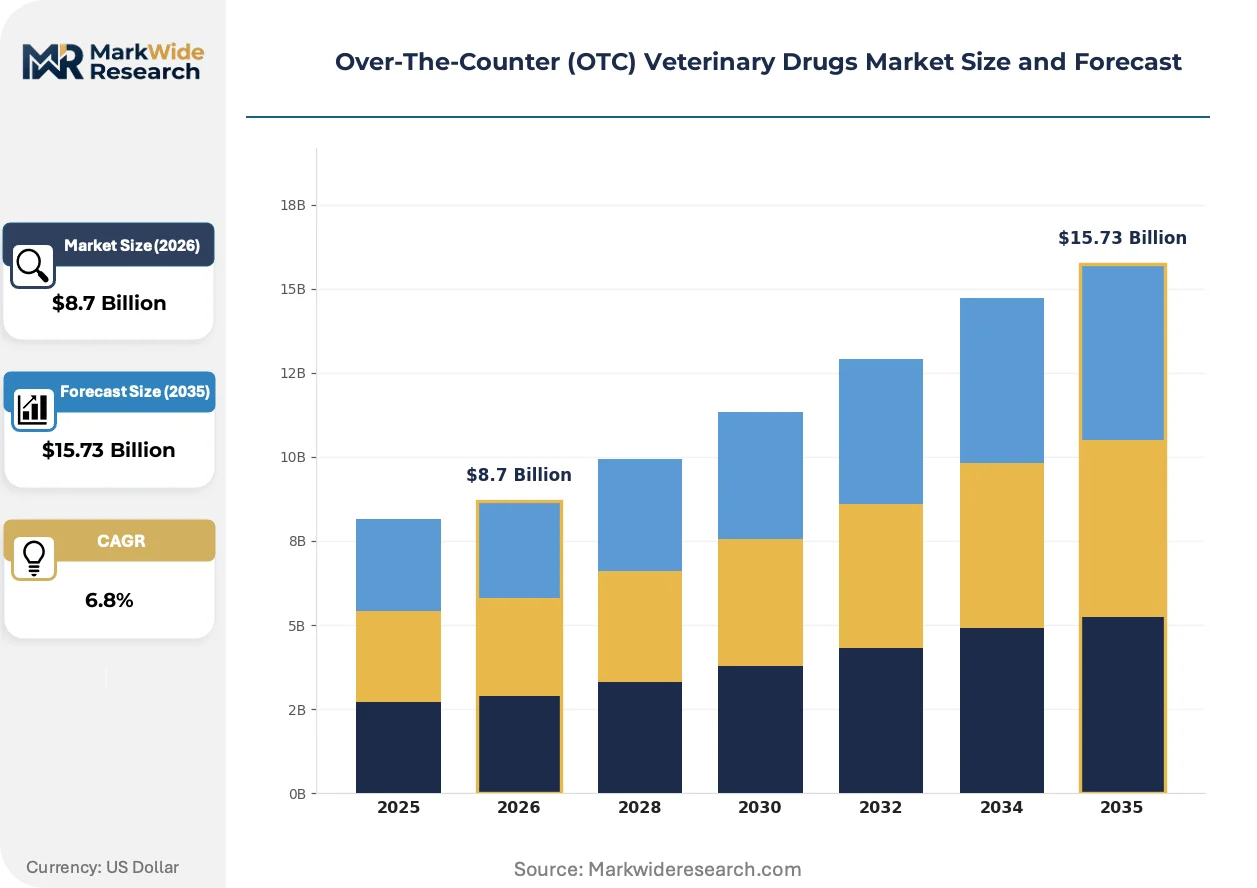
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiparasitics, Analgesics, Antiseptics, Antibiotics End User: Poultry Farmers, Pet Owners, Equestrian Centers, Livestock Producers Administration Route: Oral, Topical, Injectable, Transdermal Formulation Type: Tablets, Liquids, Powders, Ointments |
| Companies Covered | Zoetis Inc., Merck Animal Health, Boehringer Ingelheim International GmbH, Elanco Animal Health, Ceva Santé Animale, Virbac, Vetoquinol S.A., Bayer AG, Dechra Pharmaceuticals PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Over-The-Counter (OTC) Veterinary Drugs Market Evolving Landscape
Formulation science and distribution architecture are converging to separate veterinary pharmaceutical value capture from clinical gatekeeping, enabling new competitive entry points at the retail and producer levels.
Palatable chewable tablet technology is modularizing antiparasitic administration by embedding active compounds into meat-flavored matrices that eliminate pilling resistance in companion animals. Pet owners in the United States are adopting these formats at accelerating rates, displacing topical spot-on products that require skin parting and drying time. This shift is compressing the traditional veterinary dispensing margin while expanding addressable volume through supermarket and online channels.
The FDA's expanded conditional approval pathway for minor-use minor-species drugs is accelerating companion animal product pipelines by permitting efficacy data collection post-market launch. This regulatory flexibility reduces upfront clinical trial burdens for niche indications, enabling smaller formulators to reach commercialization faster. The policy most directly affects feline and exotic pet segments where historical data scarcity blocked development investment.
Subscription-based replenishment models are displacing episodic pharmacy purchases as Chewy and Amazon automate recurring deliveries of chronic-use products like heartworm preventatives. United States pet owners are consolidating purchasing decisions onto platforms that bundle diagnostics, telehealth, and pharmaceutical fulfillment. This channel consolidation pressures traditional veterinary clinics to unbundle their dispensing function or cede volume to retail-aligned formulators.
Over-The-Counter (OTC) Veterinary Drugs Market Segmentation
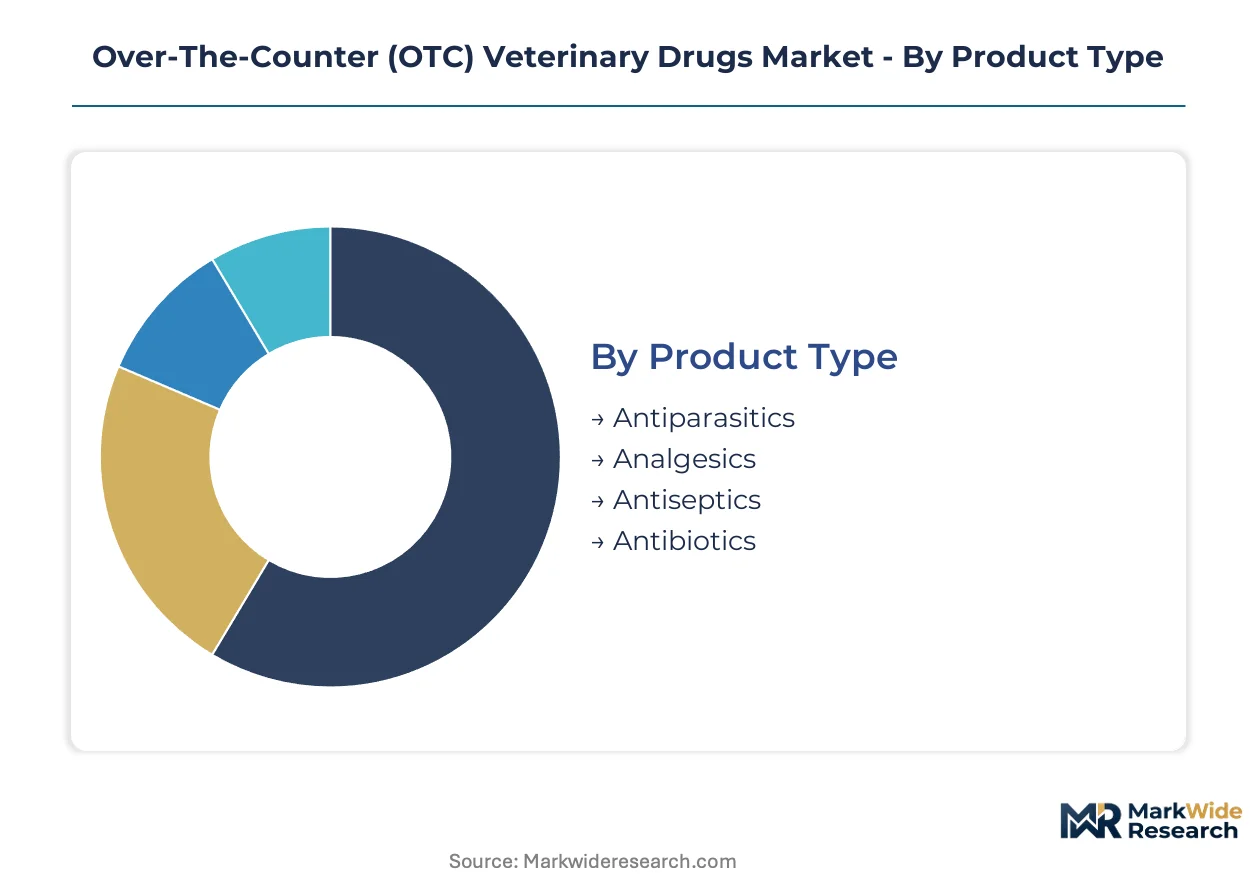
OTC veterinary drug segmentation reveals how regulatory pathways, administration convenience, and end-user sophistication fragment commercial opportunity. Each dimension carries distinct certification burdens and margin structures that determine competitive positioning.
Product Type:
FDA and EMA classification thresholds vary sharply across therapeutic categories, with environmental discharge rules from the EPA layering additional compliance costs on antiparasitic formulations.
- Antiparasitics:Ivermectin, fipronil, and selamectin formulations dominate revenue pools through recurring prophylactic dosing schedules. Companion animal owners in the United States drive volume through monthly heartworm and flea prevention protocols, though API supply concentration among Indian and Chinese contract manufacturers creates input cost volatility.
- Analgesics:NSAID and opioid-sparing formulations address post-surgical and chronic pain management without veterinary supervision. Pet owners represent the fastest-expanding demand cohort as chewable carprofen and meloxicam formats reduce pilling friction in aging dog populations.
- Antiseptics:Chlorhexidine and povidone-iodine preparations target wound irrigation and surgical site preparation.
- Antibiotics:Topical and ophthalmic formulations face tightening OTC classification thresholds as antimicrobial resistance scrutiny intensifies under FDA Veterinary Feed Directive parallels.
Leading the category by volume: Antiparasitics. Expanding most quickly: Analgesics.
End User:
Procurement sophistication and price sensitivity diverge dramatically across livestock operations versus companion animal households, reshaping packaging and distribution economics.
- Pet Owners:Urban households prioritize convenience and palatability over unit cost, accepting premium pricing for single-dose packaging and subscription replenishment. United States pet specialty retailers capture margin pools previously held by veterinary clinics through dedicated OTC pharmacy sections.
- Livestock Producers:Dairy and feedlot operations demand bulk powder and pour-on formats with veterinary feed directive compliance documentation. Modular dosing tiers let producers self-select treatment intensity based on herd health protocols without service call dependency.
- Poultry Farmers:Integrated operations require water-soluble antibiotic and coccidiostat formulations at population-scale dosing.
- Equestrian Centers:Stable managers balance performance horse welfare with regulatory show-ring medication rules.
Highest absolute spend per transaction: Livestock Producers. Steepest expansion trajectory: Pet Owners.
Administration Route:
Delivery technology maturity determines bioavailability consistency and owner compliance rates across species with divergent physiologies.
- Oral:Palatable chewable matrices embedding antiparasitic and analgesic compounds displace topical alternatives through reduced administration friction. United States pet owners accelerate adoption as meat-flavored formulations eliminate pilling resistance.
- Transdermal:Absorption-enhancing technologies enable longer-acting antiparasitic delivery with extended dosing intervals. Merck Animal Health anchors R&D investment here, though species-specific skin permeability variation necessitates costly reformulation cycles.
- Topical:Spot-on pipettes and sprays retain share in feline and exotic pet segments where oral dosing risks trauma.
- Injectable:Long-acting depot formulations concentrate in livestock prophylaxis where handling infrastructure supports parenteral administration.
Dominant by prescription conversion: Oral. Technology frontier: Transdermal.
Formulation Type:
Packaging format selection directly shapes stability testing requirements, cold chain dependency, and retail shelf-space competition.
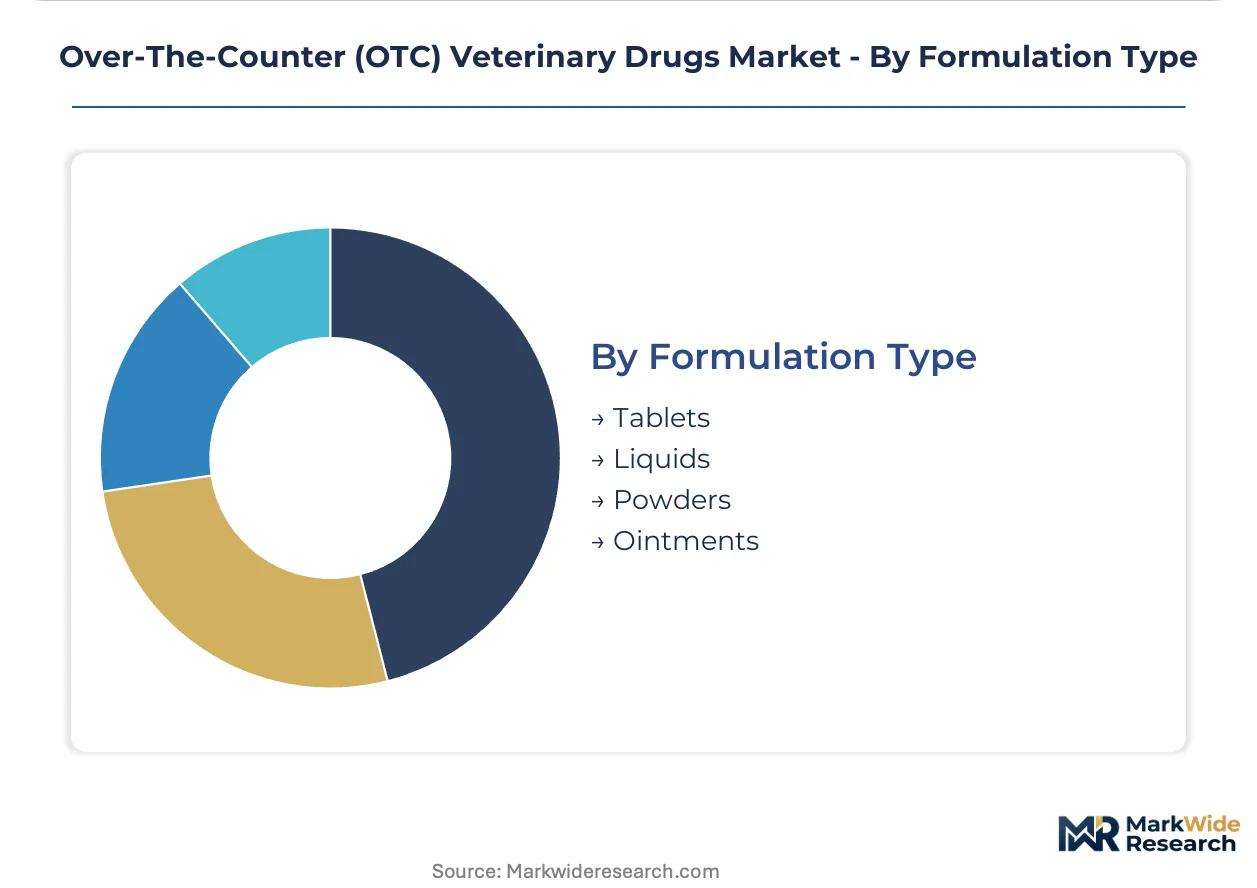
- Tablets:Film-coated and chewable solid dosages offer longest shelf stability and simplest logistics. Zoetis Inc. leverages manufacturing scale across oral antiparasitic lines with temperature-tolerant packaging for veterinary retail channels.
- Liquids:Suspensions and solutions enable precise weight-based dosing across variable livestock populations. Poultry and swine operations in the European Union favor water-medication formats compatible with automated delivery systems.
- Powders:Bulk active blending for feed incorporation serves cost-sensitive livestock producers.
- Ointments:Semi-solid preparations target topical antiseptic and ophthalmic applications.
Volume leader: Tablets. Fastest channel shift: Liquids.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of active pharmaceutical ingredients concentrates in India and China, while consumption value pools accumulate in the United States and Western Europe where pet owner spending drives premium formulation demand.
United States
Urban pet ownership expansion fuels demand for self-administered antiparasitic chewables that bypass veterinary visits. The FDA's streamlined OTC approval pathways for companion animal products compress time-to-market cycles for retail-accessible formulations. Direct-to-consumer veterinary retail channels in metropolitan clusters across California, Texas, and the Northeast Corridor capture margin pools previously held by clinical dispensing.
Germany
Livestock producers in Lower Saxony and Bavaria drive bulk procurement of modular antiparasitic dosing formats for dairy and swine operations. EMA centralized assessment protocols reduce regulatory fragmentation across EU member states, accelerating cross-border product registration. The country's pharmaceutical manufacturing base in Baden-Württemberg anchors formulation science capabilities for transdermal delivery systems.
India
Dairy cooperatives in Gujarat and Maharashtra represent underpenetrated demand for self-selection antiparasitic formats that reduce veterinary service dependency. CDSCO regulatory harmonization with international standards enables domestic formulators to supply contract manufacturing for global markets. API production clusters in Hyderabad and Ahmedabad concentrate ivermectin and related antiparasitic active supply.
Brazil
Integrated poultry and beef operations in São Paulo and Minas Gerais states drive population-scale demand for water-soluble coccidiostat formulations. ANVISA oversight of veterinary pharmaceutical safety standards shapes import substitution dynamics for domestic formulators. The country's livestock production density creates recurring prophylactic dosing schedules across commercial herds.
United Kingdom
Companion animal households in Greater London and the Southeast prioritize convenience-driven subscription replenishment for chronic-use heartworm preventatives. The Veterinary Medicines Directorate operates parallel assessment frameworks to EMA centralized procedures, creating dual registration pathways. Pet specialty retail expansion across metropolitan England displaces traditional veterinary clinic dispensing for routine antiparasitic products.
Over-The-Counter (OTC) Veterinary Drugs Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the OTC veterinary drugs sector, creating a tiered structure where manufacturing scale and R&D intensity determine positioning. The market consolidates around three strategic archetypes: multinational pharmaceutical conglomerates with animal health divisions, dedicated veterinary pure-plays, and regional formulators serving contract manufacturing niches. Dominant competitive moves include geographic expansion through distribution partnerships and portfolio diversification into palatable delivery formats.
Within the multinational conglomerate tier, Zoetis Inc. and Merck Animal Health exemplify scale-driven positioning across oral and transdermal antiparasitic lines, while Boehringer Ingelheim International GmbH anchors European poultry and swine channel presence. These entities occupy positions that leverage manufacturing infrastructure and regulatory expertise across multiple therapeutic categories and geographic markets.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Merck Animal Health |
| Boehringer Ingelheim International GmbH |
| Elanco Animal Health |
| Ceva Santé Animale |
| Virbac |
| Vetoquinol S.A. |
| Bayer AG |
| Dechra Pharmaceuticals PLC |
| Others |
Value Network & Pricing Analysis
Subscription replenishment preferences among United States pet owners are forcing formulators to absorb upfront customer acquisition costs and defer margin realization across multi-year dosing schedules, compressing working capital cycles and privileging players with balance sheet depth.
Pricing Analysis
Margin tightening in standard-tier antiparasitic tablets reflects API cost volatility from Indian and Chinese contract manufacturers. Three-tier pricing structure across premium chewables, standard tablets, and economy bulk powders separates pet specialty retail from livestock supply channels. Cost-down pressure on economy-tier livestock formulations accelerates because dairy cooperatives in India prioritize unit cost over brand loyalty. Livestock producers exhibit highest price sensitivity; urban companion animal households accept premium positioning for palatability and convenience.
Supply Chain Analysis
Direct-to-consumer e-commerce channels handle recurring replenishment demand from United States metropolitan clusters, while veterinary retail chains manage episodic purchases. API production concentrates in India and China, with formulation science capabilities anchored in Germany and the United States. Finished goods distribution draws from temperature-tolerant packaging requirements that strain cold chain infrastructure in tropical livestock regions. Single-source vulnerability in ivermectin active supply exposes formulators to qualification delays and input cost spikes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's Veterinary Feed Directive and parallel EMA antimicrobial resistance protocols erect compliance barriers that favor incumbents with established pharmacovigilance infrastructure and regulatory affairs depth.
For Market Incumbents: Hedge against subscription platform disintermediation by acquiring direct-to-consumer fulfillment capabilities or exclusive retail pharmacy partnerships. Deepen backward integration into API supply through offtake agreements with Hyderabad and Ahmedabad production clusters to offset input cost volatility. Defensive consolidation around transdermal delivery R&D protects against generic erosion in oral antiparasitic lines. For New Entrants and Emerging Players: Launch via private-label partnerships with United States pet specialty retailers seeking to displace clinic dispensing for routine heartworm preventatives. Target underpenetrated Indian dairy cooperatives with modular antiparasitic dosing formats that reduce veterinary service dependency. White-space concentration in biodegradable aquaculture formulations for EPA-certified operations offers premium positioning without direct incumbent confrontation. For Investors and Strategic Acquirers: The window for entry favors mid-sized formulators with captive API access and established EMA centralized assessment track records. Long-term viability hinges on regulatory compliance scalability across FDA and EMA jurisdictions as antimicrobial resistance scrutiny tightens OTC classification thresholds. Monitor EPA environmental discharge protocol evolution as the inflection signal for biodegradable formulation premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA streamlined OTC companion animal pathways compress time-to-market for retail-accessible formulations. |
| Backward Integration | Captive API supply from Indian contract manufacturers insulates formulators against ivermectin cost volatility. |
| Direct-to-Consumer Launch | Subscription replenishment models with Chewy and Amazon displace traditional veterinary clinic dispensing volume. |
| Product Launch | Palatable chewable antiparasitic formats embedding meat-flavored matrices eliminate pilling resistance in companion animals. |
| Geographic Expansion | EMA centralized assessment protocols reduce regulatory fragmentation across EU member states for cross-border registration. |
Research Methodology
FDA filings, EMA centralized assessment records, and CDSCO registration databases formed the secondary backbone, cross-referenced with primary interviews involving veterinary pharmaceutical regulatory affairs leads, livestock procurement managers at dairy cooperatives, and companion animal retail category buyers. Bottom-up triangulation across product-level volume estimates and top-down validation against national veterinary pharmaceutical consumption aggregates anchored market sizing integrity.
Historical trendline analysis across therapeutic category revenue pools informed projection modeling, with segmentation dimensions spanning administration route, end-user archetype, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized growth trajectories across the projection horizon. Forecast inputs incorporated FDA OTC classification threshold evolution and EMA harmonization timeline assumptions.
Antimicrobial resistance regulatory tightening, API supply concentration shocks, and companion animal ownership cyclicality are the dominant revision risks to baseline projections. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and pet owner channel migration velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Medicine
Veterinary Medicine Market
Veterinary Medicine
Global Veterinary Eye Care Market
Veterinary Medicine
Global Veterinary/Animal Vaccines Market
Veterinary Medicine
ASEAN Rabies Veterinary Vaccines Market
Veterinary Medicine
Veterinary Assistive Reproduction Technology Market
Veterinary Medicine
Veterinary Forceps Market
Veterinary Medicine
US Veterinary Orthopedic Medicine Market
Veterinary Medicine
US Veterinarians Market
Veterinary Medicine
United States Veterinary Healthcare Market
Veterinary Medicine
Veterinary Pain Management Market
Veterinary Medicine
Animal Drugs Market
Veterinary Medicine
US Veterinary Diagnostics Market
Veterinary Medicine
Monoclonal Antibodies in Veterinary Health Market
Veterinary Medicine
Veterinary Anti-Infectives Market
Veterinary Medicine
Veterinary Biologics Market
Veterinary Medicine
Middle East Veterinary Vaccines Market