
 Global Veterinary/Animal Vaccines Market | 2026-2036
Global Veterinary/Animal Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veterinary/Animal Vaccines Market Analysis
India is tilting toward domestic vaccine manufacturing capacity with expanded fill-finish lines and antigen production facilities. Zoetis Inc. leverages its transboundary disease portfolio to anchor supply relationships across Southeast Asian livestock markets. Merck Animal Health sustains competitive positioning through integrated R&D spanning vector vaccines and autogenous platforms. Boehringer Ingelheim International GmbH dominates equine and swine segments with differentiated recombinant technology pipelines.
Veterinary and animal vaccines comprise biologically active preparations containing attenuated, inactivated, or recombinant antigenic components formulated to induce protective immunity in target species, with stability profiles typically requiring cold-chain maintenance between two and eight degrees Celsius. These products serve commercial livestock operations and companion animal practices by reducing morbidity, transmission risk, and zoonotic spillover potential. Live attenuated vaccines occupy mature margin pools in bovine respiratory disease protocols, while DNA vaccines represent the fastest-growing structural category as platform flexibility accelerates development timelines for emerging pathogens. Subunit vaccines concentrate value in companion animal channels where safety premiums support pricing power above conventional formulations.
The USDA Center for Veterinary Biologics enforces potency and purity standards that shape product registration timelines and manufacturing compliance costs for suppliers targeting North American markets. EMA veterinary regulation through the Committee for Medicinal Products for Veterinary Use harmonizes batch-release criteria across EU member states, directly influencing market access for novel recombinant platforms. India's CDSCO coordinates with the Department of Animal Husbandry to align import licensing with domestic production incentives under PLI-linked schemes. Stakeholders must monitor divergence between national regulatory pathways and platform-specific approval requirements as mRNA and viral-vector technologies transition from human to veterinary applications.
Market Dynamics
The veterinary vaccines sector is reconfiguring around platform technology transitions as mRNA and viral-vector modalities migrate from human health applications into livestock and companion animal portfolios, compressing traditional development timelines and forcing legacy manufacturers to rebuild biological production infrastructure.
Growth Catalysts
- India's PLI-linked manufacturing incentives:The Department of Animal Husbandry coordinates with CDSCO to align import licensing with domestic fill-finish capacity expansion, accelerating local antigen production for cattle and buffalo immunization programs.
- Foot-and-mouth disease eradication mandates:Brazilian livestock producers are expanding vaccination coverage under federal control protocols, generating sustained demand for polyvalent formulations across the country's central-west ranching belt.
- Recombinant platform maturation:Subunit and vectored vaccines are displacing conventional inactivated products in companion animal channels where safety premiums support pricing differentiation.
Market Restraints
- Cold-chain infrastructure gaps:Last-mile temperature maintenance between two and eight degrees Celsius remains unreliable in rural India and sub-Saharan Africa, constraining market access for thermolabile live attenuated formulations.
- Regulatory divergence friction:The USDA Center for Veterinary Biologics and EMA's Committee for Medicinal Products for Veterinary Use maintain non-harmonized potency testing protocols, forcing duplicate stability studies for suppliers seeking dual market access.
- Biological raw material concentration:Bovine serum and cell culture media supply concentrates among a limited supplier base, exposing manufacturers to input cost volatility and batch-to-batch consistency risks.
Strategic Opportunities
- Thermostable formulation white space:Vaccines engineered for ambient temperature stability address cold-chain gaps in Southeast Asian backyard poultry operations and African pastoralist systems.
- Autogenous vaccine service models:Custom pathogen-specific production for aquaculture and intensive swine operations creates recurring revenue streams distinct from commodity catalog sales.
- One Health zoonotic frameworks:WHO-coordinated Rift Valley fever and Lassa fever initiatives are channeling development funding toward veterinary vaccine platforms with human health spillover potential.
Industry Challenges
- Biologics manufacturing talent scarcity:Skilled operators for aseptic fill-finish and viral propagation processes are concentrated in human pharmaceutical hubs, forcing veterinary specialists to compete for limited labor pools.
- Platform transition capex burdens:mRNA and viral-vector manufacturing requires cleanroom infrastructure and synthetic chemistry capabilities foreign to legacy attenuated vaccine plants, demanding nine-figure facility investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veterinary/Animal Vaccines Market |
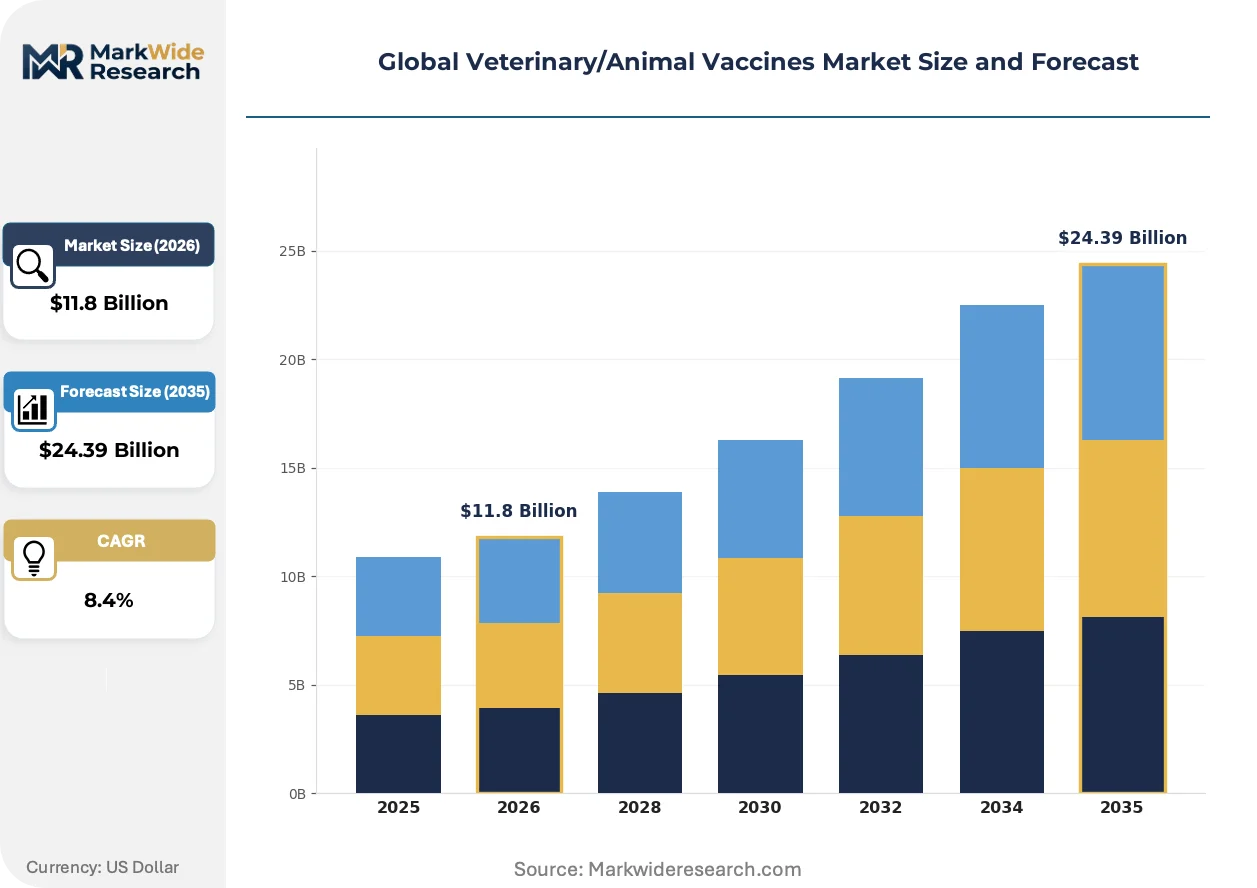
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Attenuated Vaccines, Inactivated Vaccines, Subunit Vaccines, DNA Vaccines Animal Type: Canine, Feline, Equine, Bovine Administration Route: Intramuscular, Subcutaneous, Oral, Intranasal Distribution Channel: Veterinary Clinics, Online Pharmacies, Distributors, Animal Hospitals |
| Companies Covered | Zoetis Inc., Merck Animal Health, Boehringer Ingelheim International GmbH, Elanco Animal Health, Ceva Santé Animale, Virbac, HIPRA, Phibro Animal Health Corporation, Neogen Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veterinary/Animal Vaccines Market Emerging Trajectories
Veterinary vaccine development is accelerating toward platform-flexible architectures that compress antigen design-to-dose timelines while regulatory bodies on three continents tighten cold-chain verification and potency documentation requirements.
mRNA vaccine technology is hybridizing conventional immunology with synthetic biology workflows to enable rapid response against emerging avian influenza variants and African swine fever outbreaks. Large integrated pork producers in the US Midwest and Denmark are piloting these platforms for herd-specific pathogen matching. The technology is compressing the traditional three-to-five-year development cycle into twelve-to-eighteen-month windows, forcing regulatory frameworks to adapt batch-release protocols.
The EU F-Gas Regulation and accompanying MDR veterinary annexes are mandating reduced reliance on cold-chain-dependent formulations through accelerated stability testing and alternative delivery route validation. Manufacturers targeting European market access must now submit thermostability data beyond standard label claims. This regulatory pressure is driving investment in lyophilization and adjuvant reformulation across recombinant product pipelines.
Consolidated livestock operators are unbundling vaccine procurement from traditional distributor relationships, establishing direct supply contracts with manufacturers for autogenous and custom polyvalent programs. This channel disintermediation is most visible in Brazil's integrated poultry sector and Vietnam's aquaculture conglomerates, where volume concentration enables price negotiation and technical service customization previously mediated by veterinary wholesalers.
Global Veterinary/Animal Vaccines Market Segmentation
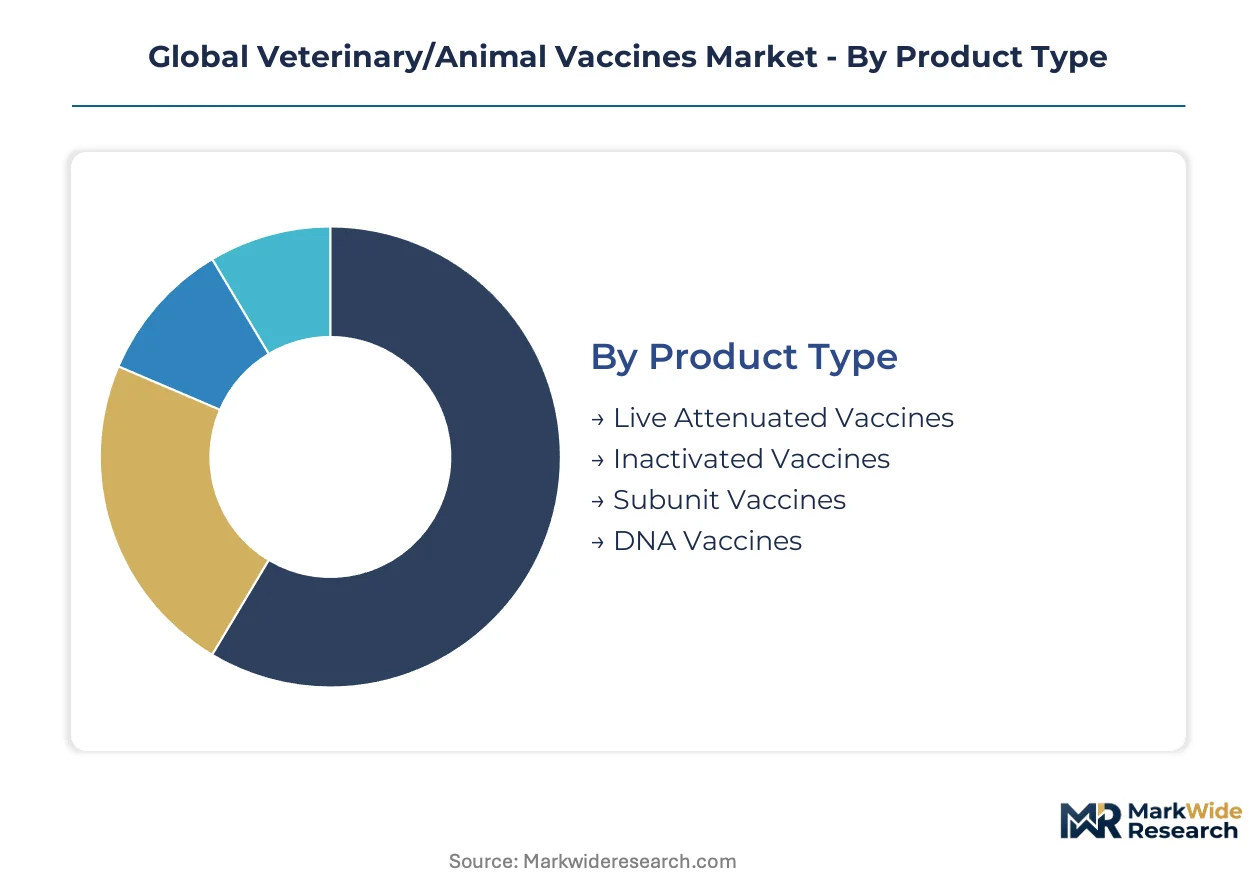
Veterinary vaccine segmentation reveals divergent margin profiles across technology platforms and species-specific demand cycles. Product type and animal category configurations determine cold-chain requirements, regulatory pathways, and pricing power in distinct end-use channels.
Product Type:
Live attenuated formulations turn inventory fastest due to thermolability constraints, while DNA platforms sit longest in development pipelines before commercial release.
- Live Attenuated Vaccines:Contain weakened pathogenic organisms that replicate limitedly in host tissue to stimulate cellular and humoral immunity. Brazilian foot-and-mouth disease programs and Indian government cattle campaigns concentrate demand, though cold-chain failures in rural distribution constrain penetration.
- DNA Vaccines:Comprise plasmid vectors encoding target antigens, enabling rapid redesign for emerging pathogens without live culture handling. Platform flexibility attracts R&D investment for African swine fever and avian influenza preparedness, with USDA and EMA frameworks adapting to accelerated approval timelines.
- Inactivated Vaccines:Rely on chemically or heat-killed whole pathogens with adjuvant enhancement for immunogenicity.
- Subunit Vaccines:Deploy purified antigenic proteins or peptides, commanding safety premiums in companion animal channels.
Live attenuated vaccines dominate installed base across livestock operations worldwide. DNA vaccines represent where expansion concentrates.
Animal Type:
Margin stratification runs deepest in companion animal segments, where pet owner willingness-to-pay exceeds production economics in food animal categories.
- Canine:Core combination protocols against distemper, parvovirus, and adenovirus sustain recurring annual revaccination cycles. Urban veterinary clinics in the United States and Western Europe drive premium subunit and recombinant uptake.
- Bovine:Respiratory disease and clostridial vaccines anchor commercial dairy and feedlot procurement at scale. India's National Animal Disease Control Program generates volume concentration for polyvalent formulations, though price sensitivity limits recombinant adoption.
- Feline:Calicivirus and herpesvirus combination products concentrate in indoor pet populations.
- Equine:Tetanus, influenza, and West Nile virus protocols serve racing and recreational stables with seasonal demand patterns.
Bovine vaccines generate largest absolute volume. Canine applications capture highest per-dose margin.
Administration Route:
Route selection determines cold-chain intensity, with parenteral methods requiring sterile handling versus oral alternatives suited to mass administration.
- Intramuscular:Delivers depot-formulated antigens into skeletal muscle for sustained immune exposure. Commercial swine and cattle operations in Denmark and the US Midwest prefer this route for modified-live respiratory vaccines.
- Oral:Enables mass administration without individual animal handling, critical for wildlife rabies baiting programs and poultry hatchery spray vaccination. Thermostable formulation requirements here exceed standard cold-chain specifications.
- Subcutaneous:Common for companion animal core vaccines in clinical settings.
- Intranasal:Targets mucosal immunity for respiratory pathogens in equine and bovine protocols.
Intramuscular delivery dominates commercial livestock protocols. Oral administration is climbing fastest for thermostable platform expansion.
Distribution Channel:
Channel control determines technical service attachment and pricing transparency, with direct manufacturer relationships displacing traditional wholesale intermediaries.
- Veterinary Clinics:Provide prescriptive authority and compliance documentation for companion animal core protocols. Brazil's integrated poultry operators and Vietnam's aquaculture conglomerates increasingly bypass this channel for autogenous vaccine procurement.
- Distributors:Maintain cold-chain logistics and credit extension for fragmented livestock producer bases. Inventory carrying costs and temperature monitoring investments concentrate this function among regional specialists.
- Animal Hospitals:Handle emergency and specialty cases with premium biologic requirements.
- Online Pharmacies:Emerge in markets with regulatory clarity on prescription verification and cold-chain shipping standards.
Distributors retain largest geographic coverage. Veterinary clinics face disintermediation pressure from direct manufacturer contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The USDA Center for Veterinary Biologics anchors North American market access through potency verification protocols that shape registration timelines for suppliers targeting the United States. Veterinary vaccine demand concentrates across five countries where livestock density, companion animal ownership, and regulatory frameworks create distinct commercial environments.
United States
Integrated pork producers in Iowa and Minnesota pilot mRNA platforms for herd-specific pathogen matching, while dairy operations in Wisconsin sustain polyvalent bovine respiratory procurement. The USDA enforces cold-chain documentation for modified-live products entering interstate commerce. Kansas-based manufacturing clusters supply attenuated formulations to feedlot operations across the Great Plains.
Brazil
Federal foot-and-mouth disease eradication protocols generate sustained demand for polyvalent formulations across Mato Grosso and Goiás ranching belts. ANVISA coordinates batch-release criteria with USDA equivalence agreements for export-oriented producers. São Paulo state's integrated poultry sector negotiates direct manufacturer contracts for autogenous programs, bypassing traditional distributor channels.
Germany
The EU F-Gas Regulation and MDR veterinary annexes mandate thermostability data beyond standard label claims for market access. Baden-Württemberg hosts recombinant platform development for equine and swine segments. Lower Saxony's dense livestock operations anchor demand for inactivated clostridial vaccines in dairy and feedlot channels.
India
The National Animal Disease Control Program drives mass immunization of cattle and buffalo herds across Uttar Pradesh and Maharashtra. CDSCO aligns import licensing with PLI-linked domestic manufacturing incentives for fill-finish capacity expansion. Hyderabad and Pune clusters concentrate antigen production facilities serving government tender programs.
China
African swine fever preparedness programs accelerate platform diversification for porcine vaccines across Sichuan and Henan provinces. The national agricultural ministry coordinates with provincial veterinary bureaus on compulsory immunization schedules. Guangdong's aquaculture conglomerates pilot autogenous services for bacterial pathogen management in intensive shrimp operations.
Global Veterinary/Animal Vaccines Market Vendor Landscape
Human-health multinationals and dedicated animal health specialists split the market along platform technology lines, with recombinant and mRNA capabilities concentrating among diversified pharmaceutical groups while regional specialists dominate conventional attenuated formulations. The competitive structure reflects tiered access to biological manufacturing infrastructure, with nine-figure facility investments creating barriers for new entrants. Two strategic archetypes prevail: integrated platforms leveraging synthetic biology workflows, and service-oriented autogenous providers capturing recurring revenue through custom pathogen matching. Dominant competitive moves include direct contracting with consolidated livestock operators and thermostable formulation development for cold-chain-constrained geographies.
Among diversified pharmaceutical groups, Zoetis Inc. and Merck Animal Health occupy positions exemplifying platform breadth across livestock and companion animal segments, while Boehringer Ingelheim International GmbH anchors the recombinant technology tier through differentiated pipelines in equine and swine applications. These entities represent the capital-intensive archetype rebuilding biological production infrastructure around mRNA and viral-vector modalities. Regional specialists including Ceva Santé Animale and Virbac sit within the service-autogenous tier, capturing value through technical customization and geographic proximity to concentrated livestock bases in Europe and Latin America.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Merck Animal Health |
| Boehringer Ingelheim International GmbH |
| Elanco Animal Health |
| Ceva Santé Animale |
| Virbac |
| HIPRA |
| Phibro Animal Health Corporation |
| Neogen Corporation |
| Others |
Supply Flow & Price Mechanics
Bovine serum and cell culture media suppliers concentrate in the United States and Europe, anchoring input costs for manufacturers while downstream margin pools accrue to recombinant platform holders and autogenous service providers with direct livestock operator relationships.
Pricing Analysis
Companion animal clinics in Western Europe command per-dose premiums three to five times above livestock procurement in India, where government tender programs compress margins for polyvalent formulations. Three-tier pricing structure across premium recombinant, standard inactivated, and economy live attenuated levels stratifies the market. Pricing pressure stems from Brazilian and Indian government bulk purchasing power in foot-and-mouth disease and brucellosis programs. Smallholder dairy producers in sub-Saharan Africa exhibit highest price sensitivity, while equine racing stables in Kentucky and Dubai absorb premium recombinant West Nile virus protocols without volume negotiation.
Supply Chain Analysis
Upstream biological raw material production clusters in the United States, Germany, and Australia, with bovine serum albumin and specialized cell lines feeding fill-finish operations across North America and Western Europe. Antigen production draws from embryonated eggs, SPF chicken flocks, and recombinant expression systems in mammalian and insect cell substrates. Single-source vulnerability concentrates in fetal bovine serum supply, where mad cow disease surveillance protocols restrict geographic sourcing. Distribution runs through regional cold-chain specialists maintaining two-to-eight-degree Celsius integrity, with direct manufacturer contracting displacing wholesale intermediaries in Brazil's integrated poultry sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The veterinary vaccines market is cycling through a platform transition recovery, with mRNA and viral-vector manufacturing investments cresting as livestock disease outbreaks accelerate procurement cycles for novel antigen delivery systems.
For Market Incumbents: Build regulatory data moats through thermostability dossiers exceeding EU F-Gas and MDR veterinary annex requirements, preempting competitor market access. Deepen backward integration into cell culture media production to neutralize bovine serum cost volatility. Anchor capacity expansion in Hyderabad and São Paulo clusters to capture Indian PLI incentives and Brazilian federal tender volumes. Defend against autogenous service disruption by embedding technical field teams within Vietnam aquaculture and US Midwest pork operations.
For New Entrants and Emerging Players: Establish a beachhead in thermostable oral formulation development for African pastoralist and Southeast Asian backyard poultry systems, bypassing cold-chain infrastructure gaps. Target aquaculture autogenous services in Guangdong and Kerala, where bacterial pathogen management lacks standardized catalog solutions. Deploy direct-to-producer digital sampling and pathogen sequencing workflows to compress custom vaccine turnaround below incumbent distributor-mediated timelines.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across mRNA and viral-vector manufacturing infrastructure, favoring diversified pharmaceutical groups with existing synthetic biology capabilities over pure-play veterinary specialists. Five-to-ten-year viability concentrates in platform-flexible developers with USDA and EMA master file submissions already progressing. Target acquisition archetype: regional autogenous specialists with established livestock operator relationships and pathogen isolate libraries in Brazil, Vietnam, or China. Monitor USDA Center for Veterinary Biologics guidance document releases on accelerated approval pathways for nucleic acid platforms as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermostable Formulation Development | EU F-Gas Regulation mandates ambient stability data, opening African and rural Asian markets previously excluded by cold-chain gaps. |
| Autogenous Vaccine Service Expansion | Direct manufacturer contracts with Vietnam aquaculture and Brazil poultry operators disintermediate traditional veterinary wholesale channels. |
| mRNA Platform Manufacturing Scale-Up | USDA batch-release protocol adaptation for nucleic acid vaccines compresses African swine fever response timelines below eighteen months. |
| Backward Integration into Cell Culture Media | In-house bovine serum albumin production neutralizes input cost volatility from limited supplier base concentration. |
| PLI-Linked Domestic Capacity Expansion | Indian CDSCO import licensing alignment with Hyderabad and Pune antigen production clusters captures government tender volumes. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of USDA Center for Veterinary Biologics guidance documents, EMA Committee for Medicinal Products for Veterinary Use regulatory filings, and Indian CDSCO PLI scheme notifications. Primary interviews engaged veterinary vaccine manufacturing executives, regulatory affairs directors, livestock procurement managers at integrated pork and poultry operations, and cold-chain logistics specialists across five countries. Secondary validation incorporated customs trade data, animal health company SEC disclosures, and national agricultural ministry immunization program reports. Bottom-up volume modeling triangulated against top-down market sizing through platform technology and species-specific demand cycles.
Forecast inputs span live attenuated, DNA, inactivated, and subunit product categories across bovine, canine, feline, equine, and poultry animal types, with administration route and distribution channel dimensions layered throughout the projection horizon. CAGRs derive from segment-level growth rate reconciliation against macro livestock population trends and regulatory approval velocity. Industry-specific inputs include foot-and-mouth disease eradication program budgets, companion animal veterinary visit frequency indices, and cold-chain infrastructure penetration rates by geography.
Sensitivities concentrate around USDA and EMA regulatory divergence on mRNA platform batch-release criteria, African swine fever outbreak velocity in China and Southeast Asia, and PLI scheme renewal timelines in India. Forecasts reflect assumptions on technology transition capex recovery periods and livestock operator consolidation trajectories. Quarterly review of national immunization program tender awards, thermostability validation study completions, and autogenous service contract announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Medicine
Global Veterinary Autogenous Vaccines Market
Veterinary Medicine
Veterinary Wellness Market
Veterinary Medicine
Veterinary Forceps Market
Veterinary Medicine
Veterinary Anesthesia Machines Market
Veterinary Medicine
Global Companion Animal Pharmaceuticals Market
Veterinary Medicine
ASEAN Rabies Veterinary Vaccines Market
Veterinary Medicine
Global Brucellosis Vaccines Market
Veterinary Medicine
Veterinary Anesthesia Market
Veterinary Medicine
Veterinary Pain Management Market
Veterinary Medicine
US Veterinary Diagnostics Market
Veterinary Medicine
Middle East Veterinary Vaccines Market
Veterinary Medicine
Veterinary Palliative Care Management Market
Veterinary Medicine
Veterinary Anti-Infectives Market
Veterinary Medicine
United States Veterinary Healthcare Market
Veterinary Medicine
Veterinary Medicine Market
Veterinary Medicine
South Africa Veterinary Medicine Market