
 Veterinary Forceps Market | 2026-2036
Veterinary Forceps Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Forceps Market Analytics
Veterinary surgical technician training capacity is rotating toward minimally invasive procedures, expanding the addressable base for precision forceps. Sklar leverages decades of instrument craftsmanship to dominate specialty catalogs. Integra LifeSciences sustains R&D intensity across regenerative surgery platforms that bundle forceps with advanced kits. B. Braun anchors European distribution through direct veterinary service networks.
Veterinary forceps are hand-held grasping instruments manufactured from stainless steel, titanium, or specialized alloys, featuring serrated jaws, ratchet locks, or atraumatic tips designed to clamp vessels, manipulate tissue, or extract foreign bodies during animal surgical and diagnostic procedures. Hemostatic forceps command the largest product share due to universal application across spay, neuter, and emergency procedures, while titanium variants capture premium margin pools from orthopedic and ophthalmic specialists. Stainless steel thumb forceps remain the volume workhorse in veterinary clinics, though alloy compositions are gaining traction in research laboratories requiring repeated sterilization cycles.
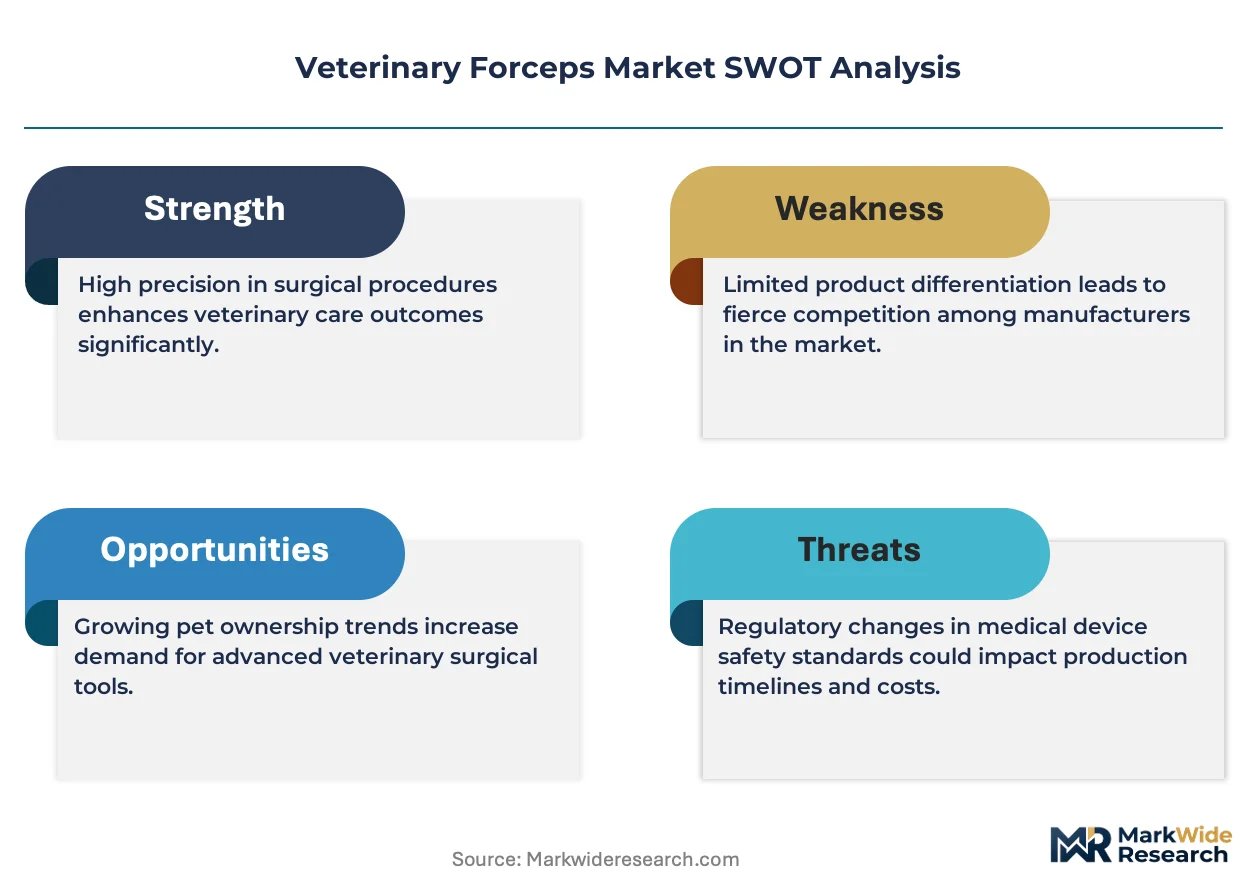
FDA 510(k) clearance requirements govern commercial entry for reusable surgical forceps in the United States, while ISO 13485 certification shapes supplier qualification across export markets. The EU Medical Device Regulation imposes stricter clinical evidence standards on Class I reusable instruments, extending compliance timelines for manufacturers serving European veterinary clinics. Stakeholders must monitor how FDA harmonization with ISO standards and EU MDR implementation will reshape competitive access and procurement qualification criteria.
Market Dynamics
Specialty veterinary surgery expansion is compressing instrument replacement cycles and elevating precision requirements across tertiary animal hospitals. This demand compression is forcing manufacturers to recalibrate alloy sourcing and sterilization durability testing protocols.
Growth Catalysts
- EU MDR implementation:Stricter clinical evidence standards for Class I reusable instruments are filtering out low-quality suppliers, creating qualification advantages for ISO 13485-certified manufacturers serving European veterinary clinics.
- Titanium alloy adoption:Orthopedic and ophthalmic veterinary specialists are specifying titanium forceps for repeated sterilization cycles, expanding premium product margins beyond traditional stainless steel volumes.
- Minimally invasive surgery training:Veterinary technician education programs are pivoting toward laparoscopic techniques, amplifying demand for precision grasping instruments with atraumatic tip designs.
Market Restraints
- Raw material cost volatility:Surgical-grade stainless steel and titanium alloy prices fluctuate with mining output constraints, squeezing margin stability for instrument fabricators.
- Supply concentration risk:German and Japanese precision metalworking clusters dominate high-grade forceps forging capacity, creating geographic vulnerability for downstream distributors.
- FDA 510(k) pathway friction:Reusable surgical instrument clearances require substantial equivalence demonstrations that extend time-to-market for novel jaw designs.
Strategic Opportunities
- Research laboratory expansion:Academic veterinary medicine programs in Australia and South Korea are building surgical training facilities that specify instrument durability beyond clinical replacement cycles.
- Telemedicine-integrated instrument kits:Remote surgical consultation platforms are bundling standardized forceps configurations to reduce on-site instrument variability.
- Indian PLI scheme alignment:Production-linked incentives for medical device manufacturing are attracting contract forging investments that could serve veterinary instrument OEMs.
Industry Challenges
- ISO 13485 auditor capacity constraints:Certification body backlogs are extending supplier qualification timelines for manufacturers seeking European market entry.
- Legacy sterilization protocol incompatibility:New alloy compositions face validation gaps against existing autoclave infrastructure at mid-sized veterinary practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Forceps Market |
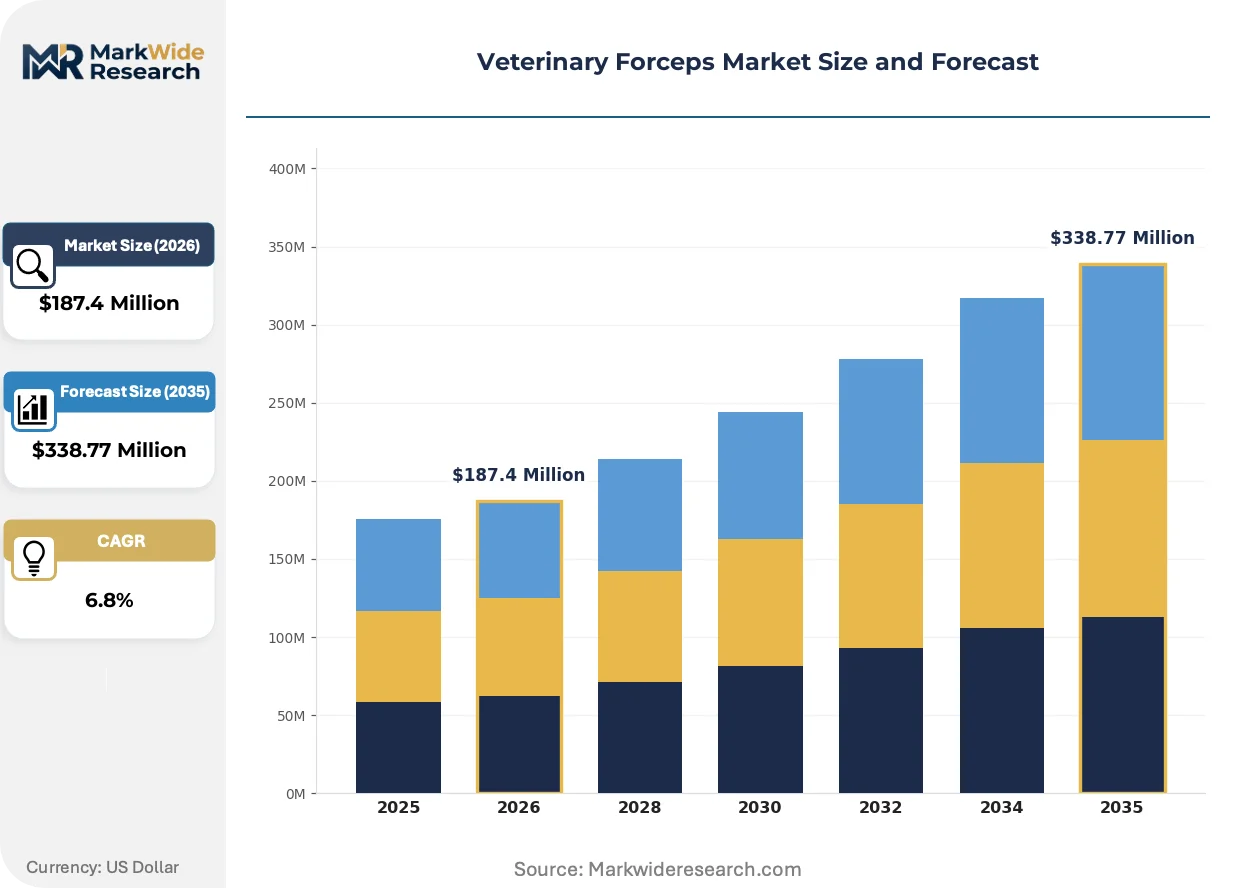
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemostatic Forceps, Thumb Forceps, Tissue Forceps, Dressing Forceps End User: Veterinary Clinics, Animal Hospitals, Research Laboratories, Zoos Material: Stainless Steel, Titanium, Plastic, Alloy Application: Surgery, Diagnostics, Animal Care, Research |
| Companies Covered | Sklar, Integra LifeSciences, B. Braun, DTR Medical, GerVetUSA, Eickemeyer, STERIS, Medtronic, Surgical Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Forceps Market Evolving Landscape
Additive manufacturing is penetrating veterinary instrument prototyping, compressing design iteration cycles from months to weeks. This acceleration is enabling rapid customization for species-specific jaw geometries.
Robotic-assisted surgical platforms are fragmenting the traditional forceps market by integrating proprietary grasping end-effectors that displace standalone instrument purchases. Large animal hospitals in the United States are piloting these systems for orthopedic procedures. The resulting hardware-software bundling is compressing addressable market scope for conventional forceps suppliers.
EU MDR clinical evidence requirements are elevating documentation burdens for Class I reusable instruments, extending compliance timelines for manufacturers serving European veterinary clinics. German distributors are consolidating supplier panels to reduce qualification overhead. Smaller forging houses without notified body relationships are exiting the veterinary segment entirely.
Group purchasing organizations at multi-site veterinary chains are consolidating instrument procurement under standardized SKU agreements. Independent clinics in Japan are losing price negotiation leverage as hospital networks centralize purchasing. This concentration is favoring manufacturers with direct service infrastructure over catalog distributors.
Veterinary Forceps Market Segmentation
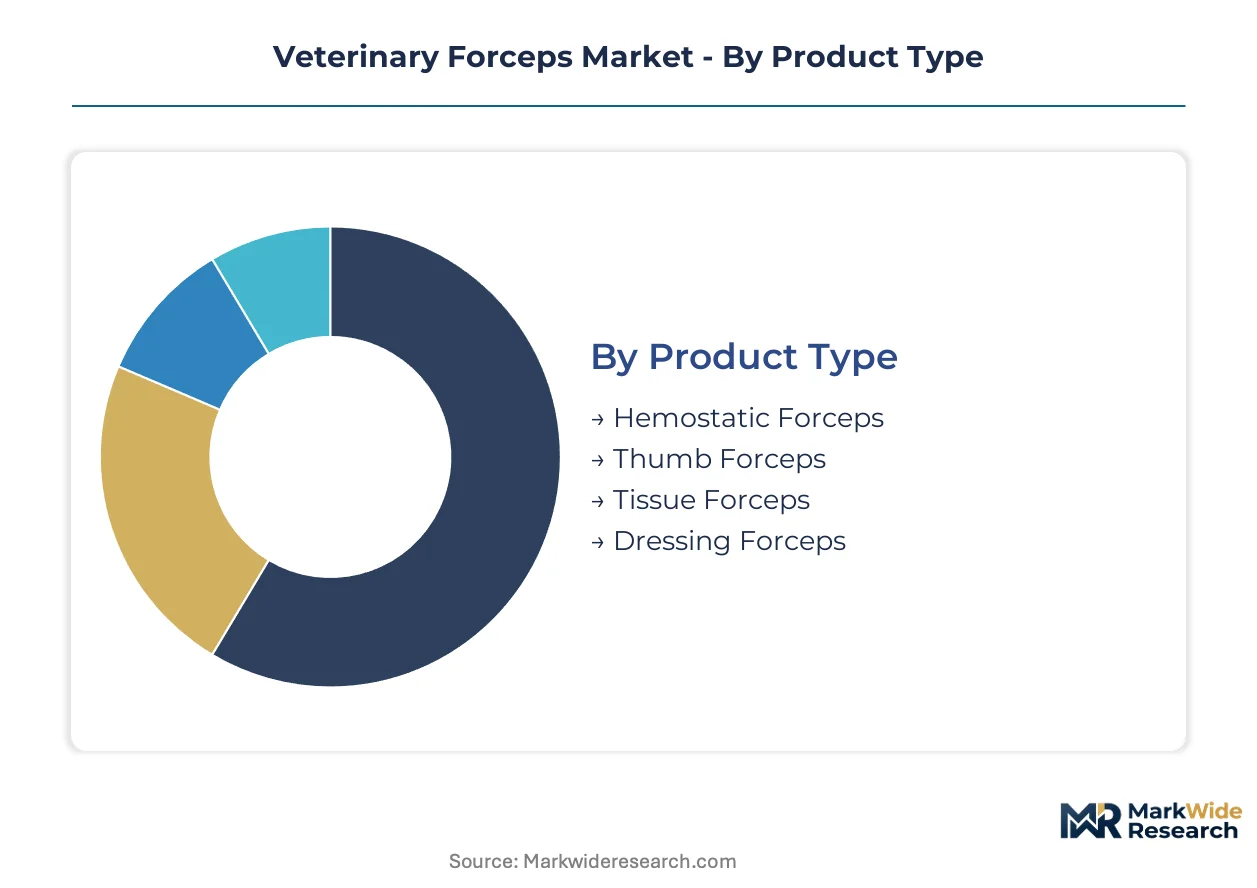
Segmentation in veterinary forceps reveals how procurement patterns diverge between high-volume sterilization environments and precision specialty settings. Understanding these splits helps manufacturers align alloy specifications, durability testing, and distribution channels with actual usage intensity across clinical and non-clinical settings.
Product Type:
Domestic production clusters in Germany and Japan supply hemostatic and thumb forceps for regional veterinary networks, while export-led demand from US specialty hospitals drives titanium tissue forceps volumes.
- Hemostatic Forceps:Ratchet-lock instruments manufactured from surgical-grade stainless steel dominate spay, neuter, and emergency procedures across high-throughput municipal clinics. Demand concentrates in United States urban animal control facilities where instrument replacement cycles compress under budget pressure.
- Thumb Forceps:Serrated-jaw grasping tools serve as the volume workhorse in general practice, with stainless steel variants capturing standard procurement contracts. Japanese distributors bundle these into standardized kits for independent clinic networks, reducing per-unit negotiation leverage.
- Tissue Forceps:Atraumatic tip designs target orthopedic and ophthalmic specialists requiring repeated sterilization durability.
- Dressing Forceps:Non-locking instruments for wound management and post-operative care in general practice settings.
Hemostatic forceps holds the largest share; momentum sits with tissue forceps as specialty surgical volumes climb.
End User:
Cost tiers separate high-capital academic medical centers from price-sensitive independent operators, with research laboratories occupying a premium durability tier above clinical replacement cycles.
- Veterinary Clinics:Independent general practices in Japan and Germany drive stainless steel thumb forceps volume through group purchasing organization contracts. These facilities prioritize instrument standardization over specialty customization, consolidating procurement under multi-SKU agreements that favor catalog distributors with direct service infrastructure.
- Animal Hospitals:Tertiary referral centers in the United States specify titanium variants for minimally invasive surgery suites and orthopedic theaters. FDA 510(k) clearance requirements govern their procurement qualification, extending vendor onboarding timelines for novel jaw geometries.
- Research Laboratories:Academic veterinary medicine programs in Australia and South Korea specify alloy compositions exceeding clinical sterilization thresholds.
- Zoos:Wildlife and exotic animal facilities require species-specific instrument geometries for non-standard anatomical applications.
Animal hospitals command premium pricing; research laboratories are expanding most quickly as academic surgical training infrastructure deepens.
Material:
Supply concentration in German and Japanese precision metalworking clusters shapes availability, with titanium and specialized alloys dependent on export forging capacity while stainless steel sources domestically across multiple markets.
- Stainless Steel:Surgical-grade compositions remain the default specification for general practice and high-volume sterilization environments, with raw material cost volatility tied to mining output constraints squeezing margin stability for fabricators serving price-sensitive clinic segments.
- Titanium:Lightweight, corrosion-resistant alloys capture premium positioning from orthopedic and ophthalmic specialists requiring repeated autoclave cycles without degradation. EU MDR implementation is filtering supplier panels toward ISO 13485-certified manufacturers capable of documenting clinical evidence for Class I reusable instruments.
- Plastic:Single-use disposable variants for field applications and emergency response settings.
- Alloy:Specialized metallurgical compositions for research environments demanding extended durability beyond standard clinical lifecycles.
Stainless steel dominates volume; titanium gains share fastest as specialty surgical training expands.
Application:
Customer type stratification shows surgery and diagnostics pulling from established hospital procurement channels, while research and animal care applications fragment across academic and institutional buyers with distinct qualification requirements.
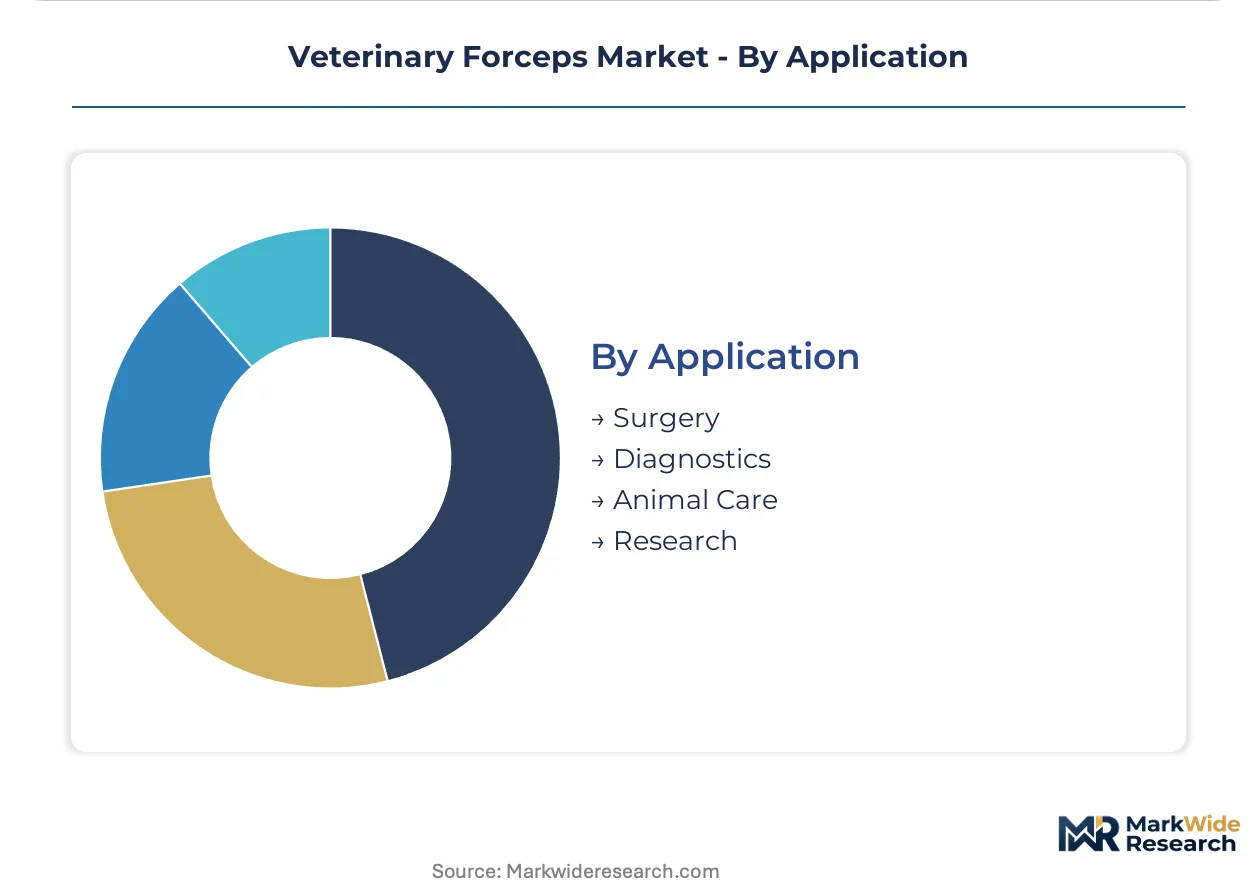
- Surgery:Spay, neuter, orthopedic, and emergency procedures drive hemostatic and tissue forceps demand across tertiary animal hospitals. Minimally invasive technique adoption is amplifying precision requirements for atraumatic tip designs as veterinary technician education pivots toward laparoscopic training.
- Diagnostics:Tissue sampling and foreign body extraction applications in general practice settings rely on thumb and dressing forceps configurations standardized for rapid sterilization turnaround.
- Animal Care:Wound management and post-operative monitoring in shelter and field environments.
- Research:Surgical training and experimental procedures in academic veterinary medicine programs requiring instrument durability beyond standard replacement cycles.
Surgery captures the largest application share; research shows the steepest expansion trajectory as laboratory infrastructure investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for veterinary forceps diverge sharply across markets. The United States prioritizes titanium precision instruments for specialty surgery suites, while Germany and Japan emphasize stainless steel durability for high-volume sterilization cycles in general practice networks.
United States
Tertiary animal hospitals in metropolitan corridors drive demand for titanium hemostatic and tissue forceps as minimally invasive surgical training expands. FDA 510(k) clearance requirements govern procurement qualification, extending vendor onboarding timelines for novel jaw geometries. Boston and Minneapolis surgical instrument clusters supply precision-forged components to domestic distributors.
Germany
EU MDR implementation is filtering supplier panels toward ISO 13485-certified manufacturers capable of documenting clinical evidence for Class I reusable instruments. The Tuttlingen precision metalworking cluster dominates high-grade forceps forging capacity, serving both domestic veterinary networks and export markets. Group purchasing organizations at multi-site chains are consolidating procurement under standardized SKU agreements.
Japan
Independent clinic networks in Tokyo and Osaka drive stainless steel thumb forceps volume through bundled kit procurement. METI industrial standards shape quality benchmarks for surgical instrument exports. The Chubu region metalworking belt supplies forged components to domestic veterinary distributors facing price pressure from hospital network centralization.
Australia
Academic veterinary medicine programs in Sydney and Melbourne are building surgical training facilities that specify instrument durability beyond clinical replacement cycles. The national therapeutic goods regulator governs medical device standards for both human and veterinary applications. Research laboratory expansion is outpacing clinical procurement growth in major metropolitan centers.
South Korea
Veterinary surgical training infrastructure in Seoul and Daegu is deepening demand for precision grasping instruments. MFDS medical device regulations align with international standards to facilitate export qualification for domestic manufacturers. Government-funded university medical centers are specifying alloy compositions exceeding standard clinical lifecycles.
Veterinary Forceps Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in veterinary forceps supply. The upper tier comprises diversified surgical instrument conglomerates with direct veterinary service networks and multi-regional distribution infrastructure. Below them, regional forging houses and catalog distributors compete on price and customization speed for independent clinic segments. Two strategic archetypes dominate: heritage craftsmanship specialists leveraging decades of instrument-making reputation, and diversified medical device platforms bundling forceps within broader surgical kits. Competitive moves concentrate on geographic expansion through distributor partnerships and portfolio diversification into titanium alloy variants.
Among heritage craftsmanship specialists, Sklar and Surgical Holdings exemplify the precision-forging archetype with established veterinary catalog presence. Integra LifeSciences and B. Braun occupy positions within the diversified medical device tier, anchoring European and North American distribution through direct service networks. STERIS and Medtronic represent the platform-bundling approach, integrating forceps within broader sterilization and surgical technology portfolios. These six entities span the competitive spectrum from specialized instrument fabrication to integrated healthcare supply.
| Leading Market Players |
|---|
| Sklar |
| Integra LifeSciences |
| B. Braun |
| DTR Medical |
| GerVetUSA |
| Eickemeyer |
| STERIS |
| Medtronic |
| Surgical Holdings |
| Others |
Value Network & Pricing Analysis
Titanium alloy substitution for surgical-grade stainless steel is redrawing procurement economics across veterinary forceps, compressing margin pools for traditional fabricators while concentrating premium pricing power with ISO 13485-certified manufacturers capable of documenting repeated sterilization durability. This material pivot simultaneously shifts supply geography toward German and Japanese precision metalworking clusters and elevates price floors for orthopedic and ophthalmic specialty instruments.
Pricing Analysis
Long-term offtake contracts dominate procurement between multi-site veterinary hospital networks and established instrument distributors, though independent clinics in Japan and Germany increasingly negotiate spot purchases through group purchasing organization frameworks. Price differentiation rests on ISO 13485 certification tier and sterilization cycle durability, with titanium variants commanding substantial premiums over stainless steel workhorses. Cost compression in the standard-grade tier is intensifying because raw material volatility in surgical-grade stainless steel squeezes fabricator margins. Municipal animal control facilities exhibit the highest price sensitivity, while tertiary referral centers in the United States show minimal elasticity for precision instruments.
Supply Chain Analysis
Inbound logistics costs from German and Japanese forging clusters to North American distributors have tightened delivery windows for titanium alloy forceps, with container availability fluctuations on Asia-Pacific trade lanes amplifying procurement uncertainty. Supply concentrates in the Tuttlingen precision metalworking belt, the Chubu region metalworking corridor, and Boston-Minneapolis surgical instrument clusters. Raw material feeds draw from surgical-grade stainless steel mills, titanium sponge processors, and specialized alloy foundries. Single-source vulnerability sits with German notified body relationships for EU MDR compliance documentation. Distribution runs through direct veterinary service networks for hospital chains and catalog distributors for independent clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Robotic-assisted surgical platforms are fragmenting instrument procurement into hardware-software bundles, creating platform-economics inflection where standalone forceps suppliers must interoperate with integrated operating room ecosystems or face displacement.
For Market Incumbents: Shield specialty market position by deepening direct service infrastructure in United States metropolitan corridors where FDA 510(k) clearance requirements extend vendor onboarding timelines for challengers. Prioritize backward integration into titanium alloy sourcing to offset raw material volatility exposure from surgical-grade stainless steel markets. The robotic platform bundling threat demands defensive certification investments that lock hospital networks into proprietary instrument geometries. For New Entrants and Emerging Players: Service-layer gaps in telemedicine-integrated instrument kit standardization offer white-space entry points where incumbents under-serve remote surgical consultation platforms. Target research laboratory expansion in Australia and South Korea, where academic veterinary medicine programs specify durability beyond clinical replacement cycles and procurement qualification emphasizes alloy documentation over brand heritage. A go-to-market angle anchored in rapid additive manufacturing prototyping for species-specific jaw geometries bypasses traditional forging capacity constraints. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision instrument specialists in the Tuttlingen cluster holding ISO 13485 certification and established notified body relationships. Long-term viability over a five-to-ten year horizon hinges on portfolio diversification into titanium variants and robotic platform interoperability. The signal to watch is consolidation velocity among German distributors filtering supplier panels under EU MDR implementation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | EU MDR implementation filters supplier panels toward documented quality management systems, extending qualification advantages. |
| Titanium Alloy Portfolio Expansion | Orthopedic and ophthalmic specialists specify repeated sterilization durability, capturing premium margin pools beyond stainless steel. |
| Direct Veterinary Service Network Buildout | Hospital network procurement centralization favors manufacturers with captive service infrastructure over catalog distributors. |
| Additive Manufacturing Capability Integration | Rapid prototyping compresses design iteration cycles from months to weeks for species-specific jaw geometries. |
| Robotic Platform Interoperability Development | Hardware-software bundling in large animal hospitals demands instrument geometries compatible with proprietary end-effector systems. |
Research Methodology
A spread of perspectives from veterinary surgical technicians, hospital purchasing committee members, biomedical engineers at tertiary animal hospitals, GPO contracts managers, and precision instrument forging specialists converged on the working assumptions shaping this analysis. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) clearance databases, ISO 13485 certification registries, EU MDR implementation guidance documents, and hospital procurement contract disclosures. Bottom-up demand modeling across end-user segments triangulated against top-down supply capacity assessments in German and Japanese metalworking clusters.
Segmentation dimensions modeled span product type, material composition, end-user facility tier, and application intensity across the projection horizon. CAGRs were derived from instrument replacement cycle compression rates, specialty surgical volume trajectories, and research laboratory infrastructure investment patterns. The quantitative framework incorporated sterilization durability testing protocols, alloy specification adoption curves, and regulatory compliance timeline differentials between notified bodies.
Underlying assumptions cover stable FDA harmonization with ISO standards, continued EU MDR implementation without regulatory rollback, and sustained mining output constraints on surgical-grade stainless steel pricing, with deviation risk concentrated in raw material cost volatility and auditor capacity bottlenecks for ISO 13485 certification. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Medicine
Veterinary Skin Care Products Market
Veterinary Medicine
Veterinary Anesthesia Market
Veterinary Medicine
United States Veterinary Healthcare Market
Veterinary Medicine
US Veterinary Orthopedic Medicine Market
Veterinary Medicine
Global Veterinary/Animal Vaccines Market
Veterinary Medicine
US Veterinarians Market
Veterinary Medicine
Global Newcastle Disease Vaccine Market
Veterinary Medicine
Veterinary Wellness Market
Veterinary Medicine
Veterinary Anesthesia Machines Market
Veterinary Medicine
Live Attenuated Veterinary Vaccines Market
Veterinary Medicine
Global Veterinary Eye Care Market
Veterinary Medicine
Global Veterinary Autogenous Vaccines Market
Veterinary Medicine
Global Brucellosis Vaccines Market
Veterinary Medicine
Veterinary Assistive Reproduction Technology Market
Veterinary Medicine
Veterinary Pain Management Market
Veterinary Medicine
Veterinary Palliative Care Management Market