
 US Veterinarians Market | 2026-2036
US Veterinarians Market Size, Share, and Industry Trends Forecast 2026-2036
US Veterinarians Market Intelligence
Veterinary specialist shortages across surgery, oncology, and diagnostic imaging is redrawing competitive boundaries in the US Veterinarians Market. Mars Veterinary Health leverages its multi-brand hospital network to sustain geographic density in suburban corridors. VCA Animal Hospitals anchors its position through specialty referral centers that capture complex cases from general practice feeders. IDEXX Laboratories dominates in-house diagnostics and laboratory services, extending its reach into clinic workflow software that binds independent practices to its ecosystem.
Veterinarians are licensed medical professionals trained to diagnose, treat, and prevent disease in animals, employing surgical instruments, pharmaceutical agents, diagnostic imaging modalities, and laboratory testing protocols to maintain animal health across companion, livestock, and exotic species. Their primary commercial purpose centers on delivering fee-for-service medical care through clinical facilities that generate revenue via examinations, procedures, product dispensing, and diagnostic referrals. General practice services still occupy the largest share of visit volume, yet specialty services capture disproportionate margin pools as complex procedures command premium pricing and repeat referral traffic. Solo practices face structural pressure from corporate consolidators, while large hospitals accumulate surgical caseloads and advanced equipment that smaller facilities cannot replicate.
The FDA Center for Veterinary Medicine governs veterinary drug approvals and compounding standards, while the DEA regulates controlled substance prescribing for animal patients; state veterinary medical boards additionally license practitioners and enforce scope-of-practice rules that vary across jurisdictions. These layered frameworks shape everything from telemedicine eligibility to pharmacy revenue streams, creating compliance costs that favor scaled operators with dedicated regulatory staff. Stakeholders must weigh whether to build specialty capacity in-house or refer cases outward, as this decision locks in margin capture or loss for the next decade of companion animal care expansion.
Market Dynamics
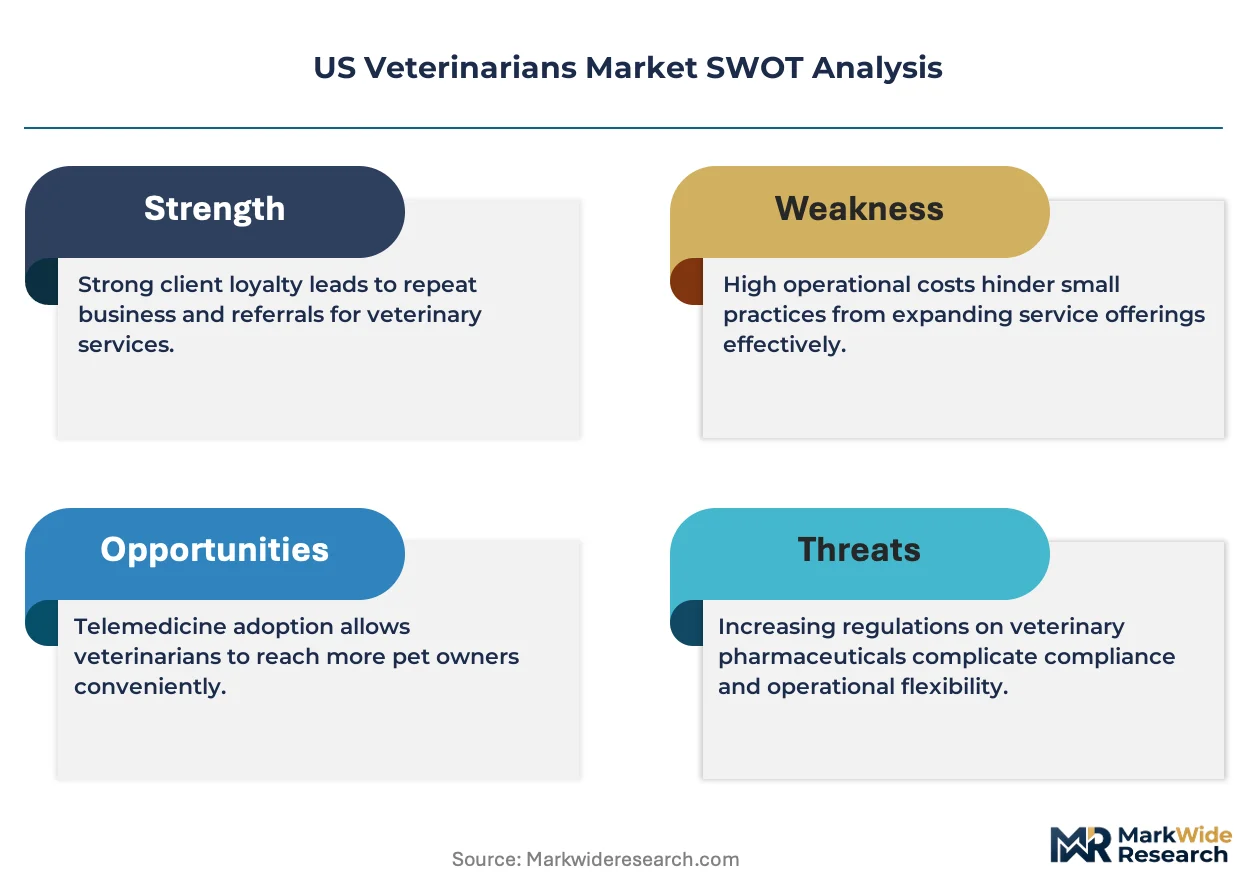
Corporate consolidators are capturing referral networks and specialty capacity faster than independent practices can replicate them, compressing margins for solo operators while concentrating surgical caseloads in multi-site hospital systems. The FDA Center for Veterinary Medicine's evolving telemedicine prescribing rules and biologics oversight are simultaneously opening new service channels and raising compliance costs that favor scaled operators with dedicated regulatory infrastructure.
Growth Catalysts
- Telemedicine prescribing expansion:FDA Center for Veterinary Medicine guidance is enabling remote consultation and prescription authority for established veterinarian-client-patient relationships, extending service reach into underserved rural counties.
- Companion animal specialty demand:Pet owners in metropolitan corridors such as Texas, Florida, and California are seeking advanced oncology, orthopedic surgery, and diagnostic imaging for aging pet populations.
- Veterinary biologics pipeline:Accelerated FDA CVM review pathways for monoclonal antibodies and gene therapies are expanding therapeutic options for chronic conditions in dogs and cats.
Market Restraints
- Veterinary specialist supply constraint:Residency-trained surgeons, oncologists, and radiologists remain concentrated in academic centers and corporate referral hospitals, limiting expansion capacity for independent practices.
- DEA controlled substance compliance:Layered federal and state reporting requirements for opioid and benzodiazepine prescribing create administrative burdens that disproportionately burden smaller clinics.
- Diagnostic equipment capex intensity:MRI, CT, and fluoroscopy systems require seven-figure capital commitments with utilization thresholds that general practices cannot sustain.
Strategic Opportunities
- Mobile specialty services:Board-certified surgeons and cardiologists operating from equipped vans are capturing caseloads from practices in secondary metros across the Southeast and Mountain West without fixed facility overhead.
- Point-of-care diagnostics convergence:Integration of AI-assisted cytology interpretation with in-house analyzers is compressing turnaround times for critical care cases.
- Veterinary technician utilization expansion:State scope-of-practice liberalization in Arizona, Colorado, and Florida is enabling credentialed technicians to perform dental extractions and anesthesia induction, extending veterinarian productivity.
Industry Challenges
- Veterinary workforce attrition:Burnout and compensation gaps are accelerating exits from clinical practice, particularly in emergency and critical care rotations.
- Legacy practice management system integration:Independent clinics operating on outdated software stacks face data migration friction when consolidating into corporate networks or adopting cloud-based referral platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Veterinarians Market |
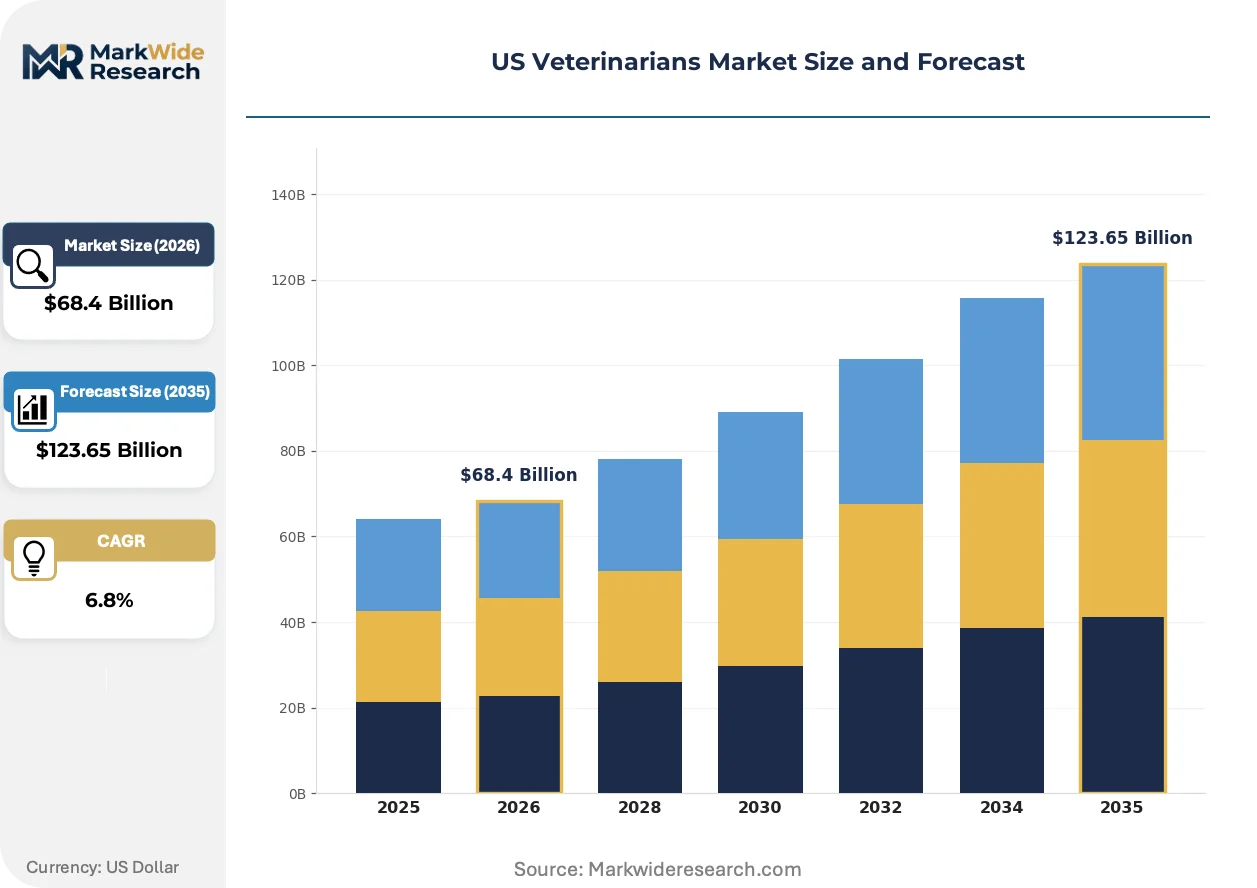
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: General Practice, Emergency Care, Specialty Services, Holistic Care Animal Type: Dogs, Cats, Birds, Exotic Animals Practice Size: Solo Practices, Small Clinics, Large Hospitals, Mobile Units End User: Pet Owners, Animal Shelters, Breeders, Research Facilities |
| Companies Covered | Mars Veterinary Health, VCA Animal Hospitals, Banfield Pet Hospital, National Veterinary Associates, BluePearl Specialty and Emergency Pet Hospital, IDEXX Laboratories, PetVet Care Centers, Heartland Veterinary Partners, Mission Veterinary Partners, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Veterinarians Market Strategic Shifts & Innovations
Artificial intelligence and remote monitoring technologies are compressing diagnostic timelines while shifting the locus of care from episodic clinic visits to continuous health surveillance. These innovations are redrawing competitive boundaries between general practices, specialty hospitals, and technology-enabled service platforms.
Artificial intelligence cytology platforms are supplanting manual microscopic review for ear and skin cytology in general practice settings. Mars Veterinary Health and VCA Animal Hospitals are deploying these systems across suburban corridor locations to reduce pathologist referral dependency. The technology is supplanting traditional send-out laboratory workflows by delivering species-specific differential diagnoses within minutes, capturing margin that previously flowed to reference laboratories.
FDA Center for Veterinary Medicine draft guidance on telemedicine prescribing is formalizing remote care protocols for chronic disease management and post-surgical follow-up. The framework establishes permissible telehealth encounters within existing veterinarian-client-patient relationships while restricting initial diagnoses to in-person examination. Small animal general practices in California and Texas are restructuring staffing models to accommodate hybrid in-person and virtual appointment schedules.
Subscription wellness plans are displacing fee-for-service billing for routine preventive care in companion animal general practice. Pet owners in metropolitan Florida and Arizona corridors are enrolling in monthly payment programs covering examinations, vaccinations, and diagnostic screening. The model concentrates patient retention within single-practice ecosystems while smoothing revenue seasonality for clinic operators.
US Veterinarians Market Segmentation
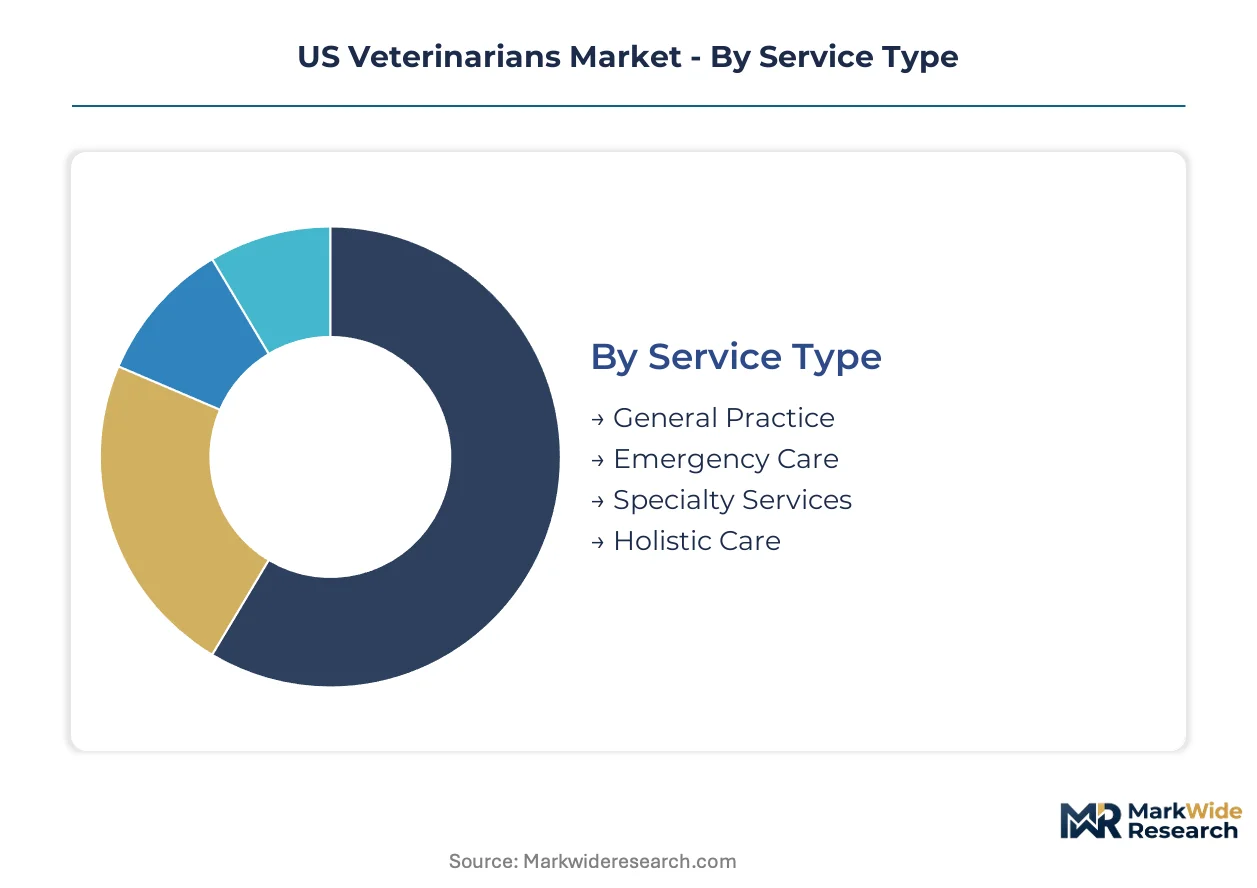
Service type and animal type segments in the US Veterinarians Market face divergent substitution pressures from telemedicine platforms, retail wellness clinics, and automated diagnostic tools. Understanding which segments absorb these competitive shocks versus which retain irreplaceable clinical value determines capital allocation and partnership strategy.
Service Type:
General practice services confront the most acute substitution threat from direct-to-consumer telehealth platforms and pharmacy retailers offering vaccine clinics, while specialty surgical and emergency interventions remain protected by regulatory scope-of-practice barriers.
- General Practice:Routine examinations, vaccinations, and minor illness management delivered through fixed-location facilities. Demand concentrates in suburban Texas and Florida corridors where household pet density supports high visit frequency, though margin pressure from corporate consolidators and retail clinic competition compresses pricing power.
- Emergency Care:After-hours critical intervention, trauma stabilization, and intensive monitoring requiring continuous staffing. Overnight caseloads in California metropolitan clusters drive revenue concentration, with specialist veterinarian shortages limiting new facility entry despite unmet demand.
- Specialty Services:Board-certified oncology, orthopedic surgery, and diagnostic imaging. Academic medical centers and corporate referral hospitals in urban corridors capture complex case referrals.
- Holistic Care:Acupuncture, herbal therapy, and alternative rehabilitation protocols. Niche demand in Colorado and Arizona markets supplements conventional treatment plans.
General practice anchors the volume base while specialty services gain share at the steepest rate.
Animal Type:
Cost tier stratification separates segments by diagnostic intensity and therapeutic spending per patient, with canine and feline populations commanding premium service pricing against lower-margin avian and exotic categories.
- Dogs:Largest patient population by expenditure, spanning preventive care through advanced oncology. Aging large-breed populations in suburban Florida and California drive orthopedic surgical demand, with pet insurance penetration expanding treatment authorization rates.
- Cats:Feline-specific medicine protocols address masked illness presentation and stress-sensitive handling. Metropolitan shelter intake programs in Texas corridor cities concentrate wellness demand.
- Birds:Avian veterinary medicine requiring specialized anesthesia and surgical equipment. Breeder and aviary operations in Florida sustain regional practice viability.
- Exotic Animals:Reptile, small mammal, and wildlife species demanding species-specific pharmacology knowledge. Zoological and private collections in California generate referral caseloads.
Dogs anchor the volume base while exotic animals climb the fastest despite smaller absolute scale.
Practice Size:
Supply concentration in metropolitan corridors favors scaled operators with capital access, while rural and secondary markets retain fragmentation.
- Solo Practices:Owner-operated single-veterinarian facilities with limited diagnostic equipment. Independent operators in rural Texas counties face equipment financing barriers and specialist referral dependency.
- Small Clinics:Multi-veterinarian practices with in-house laboratory and imaging capabilities. Suburban California locations balance personalized service with operational efficiency.
- Large Hospitals:Corporate-affiliated or independent specialty centers with surgical suites and 24-hour staffing. Urban Florida corridors concentrate advanced procedure capacity.
- Mobile Units:Equipped vehicles delivering field surgery, dentistry, and preventive care. Mountain West and Southeast secondary markets reduce fixed facility overhead.
Small clinics anchor the volume base while mobile units expand most quickly into underserved geographies.
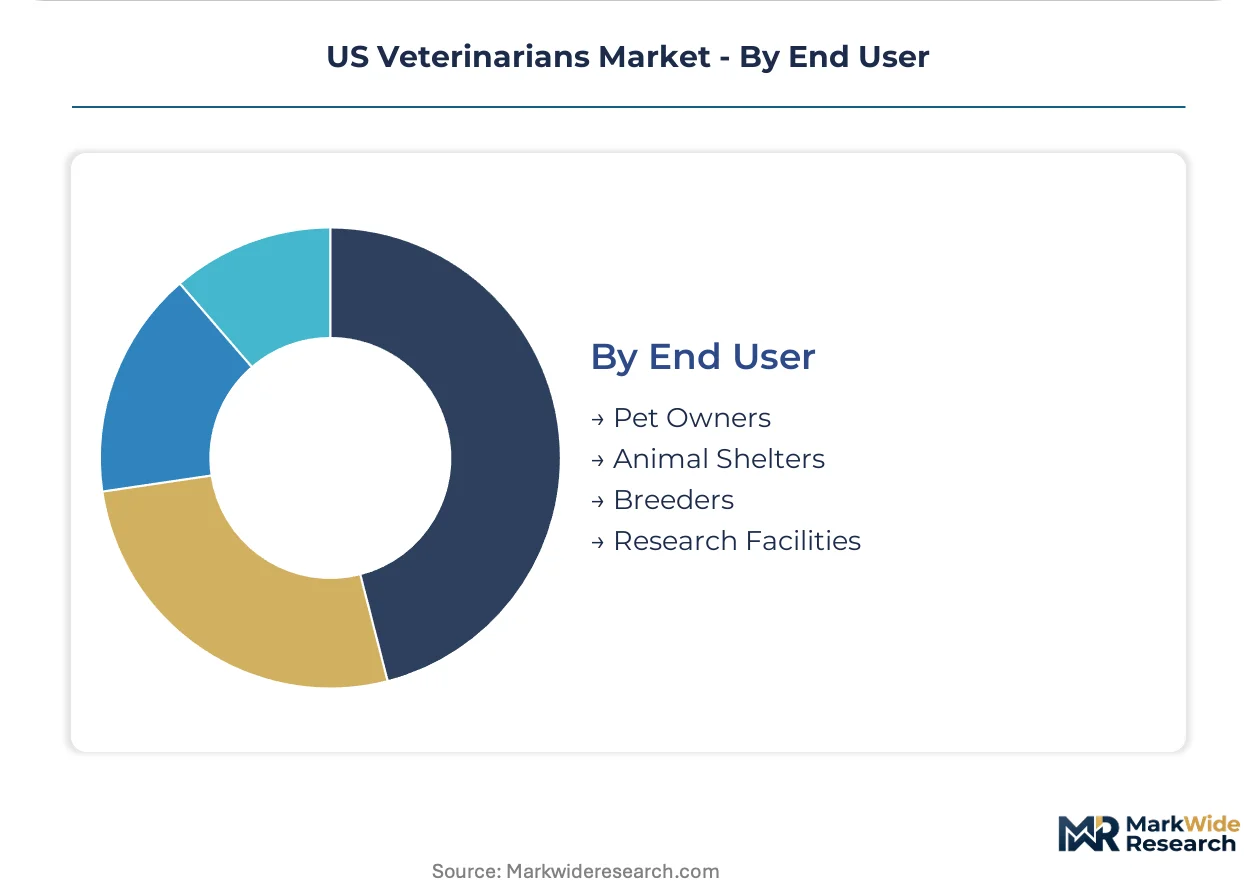
End User:
Customer type determines payment reliability, case complexity, and referral pattern stability across the revenue mix.
- Pet Owners:Individual households financing care through out-of-pocket payment or insurance reimbursement. Affluent suburban corridors in California and Florida drive discretionary spending on advanced interventions.
- Animal Shelters:Municipal and nonprofit facilities requiring high-volume sterilization and infectious disease management. Public contract pricing in Texas urban centers constrains margin.
- Breeders:Commercial and hobby breeding operations demanding reproductive services and neonatal care. AKC-registered kennel concentrations in Florida sustain regional specialty demand.
- Research Facilities:Academic and pharmaceutical institutions requiring veterinary oversight of protocol compliance. Federal funding concentration shapes geographic distribution.
Pet owners anchor the volume base while research facilities demonstrate the most stable contract pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Center for Veterinary Medicine oversight of telemedicine prescribing and biologics approval pathways shapes practice distribution across US metropolitan corridors, concentrating advanced specialty capacity where regulatory compliance infrastructure and capital access align.
California
Pet insurance penetration and aging large-breed populations drive orthopedic surgical demand in Los Angeles and San Francisco Bay Area corridors. California Veterinary Medical Board scope-of-practice rules enable veterinary technician anesthesia induction, extending specialist productivity. Corporate referral hospitals in San Diego and Sacramento capture complex oncology cases from feeder general practices.
Texas
Metropolitan shelter intake programs in Dallas-Fort Worth and Houston concentrate high-volume sterilization demand. Texas State Board of Veterinary Medical Examiners telemedicine guidance permits remote prescription renewal within established veterinarian-client-patient relationships. Independent solo practices in rural Hill Country counties face equipment financing barriers and specialist referral dependency.
Florida
AKC-registered kennel concentrations and aviary breeding operations sustain reproductive and exotic veterinary demand in Miami-Dade and Tampa Bay corridors. Florida Board of Veterinary Medicine liberalized technician scope-of-practice in 2023, enabling credentialed staff to perform dental extractions. Subscription wellness plans are displacing fee-for-service billing in Orlando suburban practices.
New York Metro
Academic medical centers in Manhattan and Long Island anchor board-certified residency training programs for surgery and diagnostic imaging. New York State Education Department veterinary licensing requirements create compliance costs favoring multi-site hospital systems over independent operators. Emergency and critical care facilities in Westchester County capture overnight trauma caseloads from Connecticut and northern New Jersey feeder markets.
Colorado
Holistic care protocols including acupuncture and rehabilitation therapy supplement conventional treatment plans in Denver-Boulder corridor practices. Colorado State Board of Veterinary Medicine enables mobile specialty services through modified facility licensing frameworks. Mountain West secondary markets reduce fixed facility overhead through equipped veterinary vans delivering field surgery.
US Veterinarians Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the US Veterinarians Market, with corporate consolidators capturing referral networks faster than independent practices can replicate capacity. Multi-brand hospital networks leverage geographic density in suburban corridors to sustain surgical caseloads, while independent specialty centers compete through board-certified expertise and academic affiliations. Three archetypes dominate: integrated corporate platforms with multi-site density, independent specialty referral hospitals with academic ties, and technology-enabled diagnostic laboratories extending into clinic workflow software. Competitive moves concentrate on specialty capacity acquisition and point-of-care diagnostics integration.
Within the integrated corporate tier, Mars Veterinary Health and VCA Animal Hospitals exemplify multi-brand consolidation strategies, while IDEXX Laboratories occupies a distinct position bridging diagnostic manufacturing with practice management software ecosystems. These three entities represent divergent paths to margin capture—horizontal hospital network expansion versus vertical integration into clinic workflow infrastructure.
| Leading Market Players |
|---|
| Mars Veterinary Health |
| VCA Animal Hospitals |
| Banfield Pet Hospital |
| National Veterinary Associates |
| BluePearl Specialty and Emergency Pet Hospital |
| IDEXX Laboratories |
| PetVet Care Centers |
| Heartland Veterinary Partners |
| Mission Veterinary Partners |
| Others |
Cost & Logistics Intelligence
FDA Center for Veterinary Medicine facility licensing requirements gate both hospital network expansion and price tier formation, with corporate operators leveraging dedicated compliance infrastructure to sustain premium positioning against independent practices facing audit cost compression.
Pricing Analysis
Long-term subscription contracts dominate companion animal preventive care, displacing fee-for-service billing in metropolitan Florida and California corridors. Three-tier pricing structure across premium specialty, standard general practice, and economy vaccine clinic levels separates board-certified surgical interventions from routine wellness exams. Cost compression in general practice is intensifying because corporate consolidators capture referral networks faster than independent operators can replicate specialty capacity. Animal shelter procurement managers demonstrate highest price sensitivity, while affluent suburban pet owners show lowest elasticity for advanced oncology and orthopedic procedures.
Supply Chain Analysis
Just-in-time inventory strategies dominate pharmaceutical and consumable procurement, though strategic stockpiling of controlled substances addresses DEA reporting compliance burdens. Domestic manufacturing anchors veterinary biologics and diagnostic reagent production, with Mexico and Ireland feeding pharmaceutical packaging and Ireland hosting European regulatory submission support. Supply chains draw from active pharmaceutical ingredient suppliers in India and China, with finished dosage form compounding resting on US-based 503B facilities. Single-source vulnerability concentrates in monoclonal antibody manufacturing for companion animal therapeutics. Distribution runs through veterinary distributor networks reaching independent practices, with direct-to-hospital logistics serving corporate multi-site systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as IDEXX Laboratories binds independent practices to its diagnostic ecosystem through workflow software integration, creating interoperability moats that reshape competitive boundaries.
For Market Incumbents: Fortify specialty referral network density in Texas and Florida suburban corridors through acquisition of board-certified surgical capacity, countering mobile specialty service entrants. Deepen backward integration into in-house veterinary biologics manufacturing to capture margin from chronic disease therapeutics. Prioritize FDA Center for Veterinary Medicine telemedicine compliance infrastructure to extend service reach into underserved rural counties without fixed facility overhead. For New Entrants and Emerging Players: State veterinary technician scope-of-practice liberalization in Arizona, Colorado, and Florida creates fast-track certification pathways for credentialed staff performing dental extractions and anesthesia induction. Target secondary metros across the Southeast and Mountain West with mobile specialty services, capturing caseloads from general practices lacking seven-figure diagnostic equipment capital. Deploy subscription wellness plan go-to-market models in Orlando and Phoenix suburban corridors, smoothing revenue seasonality against fee-for-service volatility. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across point-of-care diagnostics convergence, with AI-assisted cytology interpretation platforms requiring sustained R&D commitment. Long-term viability across the analysis window favors acquisition targets combining specialty surgical capacity with established veterinarian-client-patient relationships in high pet-density metropolitan corridors. Signal to watch: FDA Center for Veterinary Medicine draft telemedicine guidance finalization, which would unlock remote prescription renewal revenue streams and reshape practice staffing models.| Strategic Initiative | Industry Significance |
|---|---|
| Specialty Referral Network Acquisition | Board-certified surgical capacity in urban Florida corridors captures complex oncology cases from feeder general practices. |
| Point-of-Care Diagnostics Integration | AI-assisted cytology platforms reduce pathologist referral dependency while compressing turnaround times for critical care. |
| Mobile Specialty Service Deployment | Equipped veterinary vans in Mountain West secondary markets reduce fixed facility overhead while extending geographic reach. |
| Subscription Wellness Plan Rollout | Monthly payment programs in Arizona metropolitan corridors concentrate patient retention within single-practice ecosystems. |
| Veterinary Technician Scope Expansion | State-level credentialing liberalization extends veterinarian productivity through delegated anesthesia and dental procedures. |
Research Approach
Operator-level perspectives from veterinary practice owners, corporate hospital system executives, veterinary technician credentialing boards, and pharmaceutical regulatory affairs specialists anchored the qualitative base. Primary interview insights combined with secondary validation from FDA Center for Veterinary Medicine guidance documents, state veterinary medical board scope-of-practice filings, and American Veterinary Medical Association workforce surveys. Bottom-up practice-level revenue modeling triangulated against top-down market sizing from pet population demographics and household veterinary expenditure patterns.
Sensitivity analysis frameworks tested forecast robustness across alternative scenarios for specialty veterinarian supply constraints and telemedicine regulatory finalization. Segmentation dimensions modeled span service type, animal species, practice size tier, and metropolitan corridor density, with CAGRs derived from historical visit volume trends and pricing trajectory analysis. Veterinary biologics pipeline advancement and pet insurance penetration rates served as key industry-specific forecast inputs across the projection horizon.
Underlying assumptions cover stable FDA Center for Veterinary Medicine oversight timelines and continued state-level scope-of-practice liberalization, with deviation risk concentrated in veterinary workforce attrition acceleration and DEA controlled substance scheduling changes. Forecasts reflect these documented conditions, with revision becoming warranted when specialty veterinarian residency training output crosses thresholds that alleviate supply constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Medicine
Global Veterinary Autogenous Vaccines Market
Veterinary Medicine
Monoclonal Antibodies in Veterinary Health Market
Veterinary Medicine
Veterinary Assistive Reproduction Technology Market
Veterinary Medicine
ASEAN Rabies Veterinary Vaccines Market
Veterinary Medicine
Veterinary Palliative Care Management Market
Veterinary Medicine
Veterinary Dental Elevators Market
Veterinary Medicine
Veterinary Forceps Market
Veterinary Medicine
Veterinary Anti-Infectives Market
Veterinary Medicine
Global Newcastle Disease Vaccine Market
Veterinary Medicine
Global Companion Animal Pharmaceuticals Market
Veterinary Medicine
Global Veterinary Eye Care Market
Veterinary Medicine
Veterinary Biologics Market
Veterinary Medicine
Veterinary Medicine Market
Veterinary Medicine
Global Veterinary/Animal Vaccines Market
Veterinary Medicine
Global Brucellosis Vaccines Market
Veterinary Medicine
US Veterinary Diagnostics Market