
 Veterinary Assistive Reproduction Technology Market | 2026-2036
Veterinary Assistive Reproduction Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Assistive Reproduction Technology Market Analytics
The EU MDR framework is decoupling equipment certification from legacy veterinary device pathways, forcing manufacturers to rebuild compliance architectures from the ground up. Genus Plc leverages its integrated bovine genetics platform to sustain premium positioning across semen and embryo product lines. IMV Technologies anchors European supply chains through specialized biosecurity packaging and cold-chain logistics for gamete transport. STgenetics competes on sexed-semen throughput capacity, operating large-scale processing facilities that serve North American dairy cooperatives.
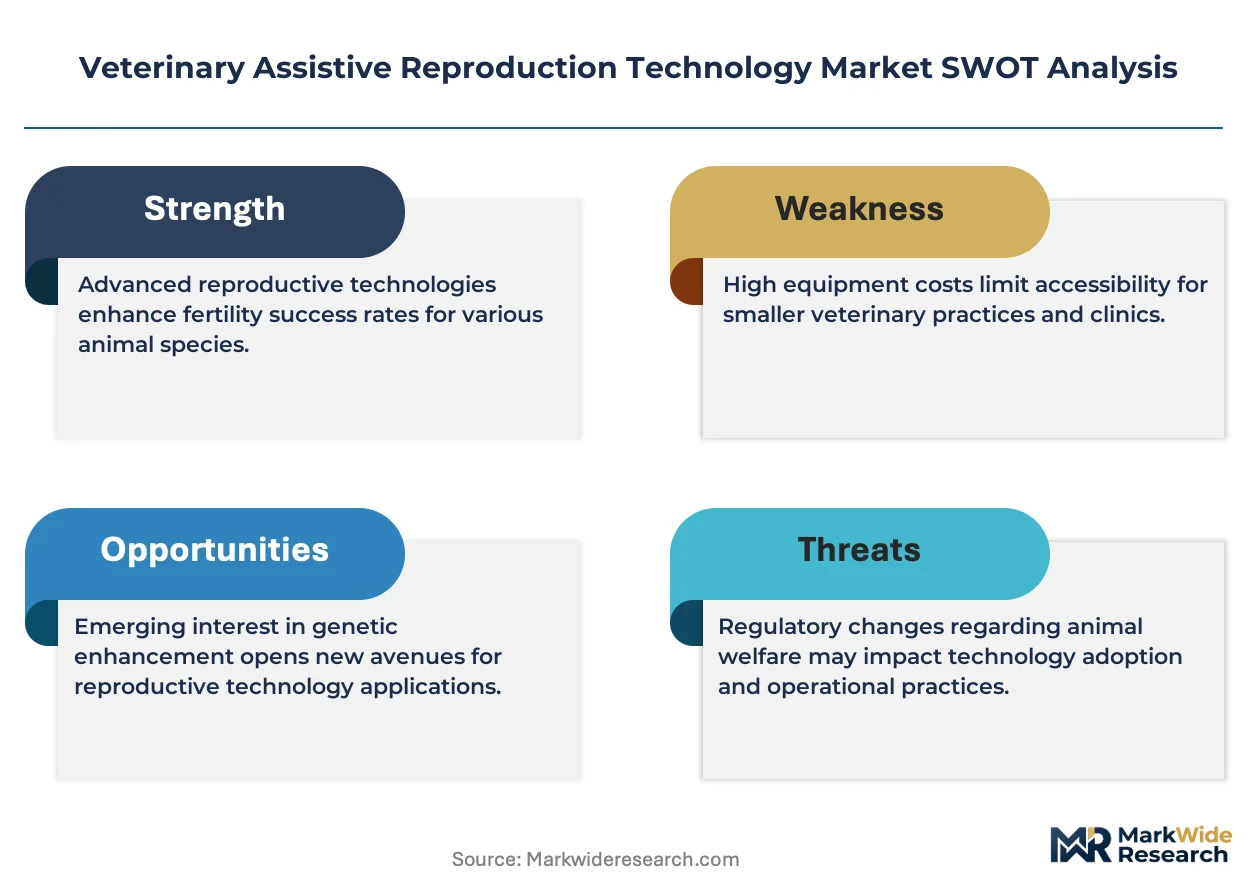
Veterinary assistive reproduction technology encompasses controlled procedures for gamete collection, processing, storage, and transfer across domestic and companion animal species, typically requiring liquid nitrogen cryopreservation at minus 196 degrees Celsius and computer-assisted semen analysis for motility grading. Its primary commercial purpose centers on accelerating genetic gain in livestock populations while preserving endangered species through managed breeding programs. Insemination technology dominates transaction volumes across the bovine segment, where dairy herd expansion drives recurring straw purchases. Embryo transfer commands premium margins within equine applications, as sport-horse breeders prioritize proven dam genetics over conventional mating timelines. Genetic enhancement applications are deepening ties between research institutions and breeding farms, creating shared infrastructure for genomic validation.
The FDA's Center for Veterinary Medicine scrutinizes device biocompatibility for intrauterine catheters and embryo recovery tubing, while ISO 9001 and ISO 13485 certifications govern quality management across production facilities. The USDA Animal and Plant Health Inspection Service enforces pathogen testing protocols for interstate and international germplasm shipments, directly shaping cold-chain packaging specifications and documentation burdens. Stakeholders must monitor convergence between human fertility device standards and veterinary regulatory expectations, as this alignment threatens to accelerate compliance costs faster than product innovation cycles.
Market Dynamics
The EU MDR framework is decoupling equipment certification from legacy veterinary device pathways, forcing manufacturers to rebuild compliance architectures from the ground up. This regulatory rupture now defines competitive viability across semen processing and embryo handling equipment categories.
Growth Catalysts
- USDA interstate germplasm protocols:The Animal and Plant Health Inspection Service mandates pathogen testing for bovine semen shipments, institutionalizing recurring demand for certified cold-chain packaging and documentation systems across North American dairy cooperatives.
- Liquid nitrogen cryopreservation at minus 196 degrees Celsius:Computer-assisted semen analysis for motility grading now integrates with automated straw filling systems, accelerating genetic gain timelines in commercial breeding farms.
- Large-scale dairy operations:Herd expansion in the United States concentrates purchasing power among integrated cooperatives, driving volume commitments for artificial insemination consumables and sexed-semen processing capacity.
Market Restraints
- Liquid nitrogen supply volatility:Cryogenic fluid costs fluctuate with industrial gas market dynamics, compressing margins for regional semen banks and smaller embryo transfer service providers.
- EU MDR compliance timeline:The European framework imposes biocompatibility testing burdens on intrauterine catheter manufacturers, extending product launch cycles by eighteen to twenty-four months.
- Conventional natural mating:Beef cattle operations in price-sensitive regions retain unassisted breeding protocols, limiting addressable market penetration for premium assisted reproduction services.
Strategic Opportunities
- Companion animal fertility services:Canine and feline embryo transfer protocols remain underdeveloped relative to livestock applications, creating whitespace for specialized veterinary clinic networks.
- FDA Center for Veterinary Medicine guidance evolution:Anticipated clarity on device biocompatibility standards for embryo recovery tubing will reduce regulatory uncertainty for domestic manufacturers.
- Genomic validation infrastructure:Shared laboratory facilities between research institutions and breeding farms enable cost-sharing models for genetic enhancement programs.
Industry Challenges
- Embryo transfer technician certification:The specialized surgical skills required for equine and bovine procedures face supply constraints, limiting service expansion in emerging dairy regions.
- ISO 13485 quality management implementation:Small equipment manufacturers struggle with documentation burdens for production facility audits, delaying market access.
- Cryogenic storage integration:Legacy semen inventory systems require costly retrofitting to interface with automated monitoring and alarm platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Assistive Reproduction Technology Market |
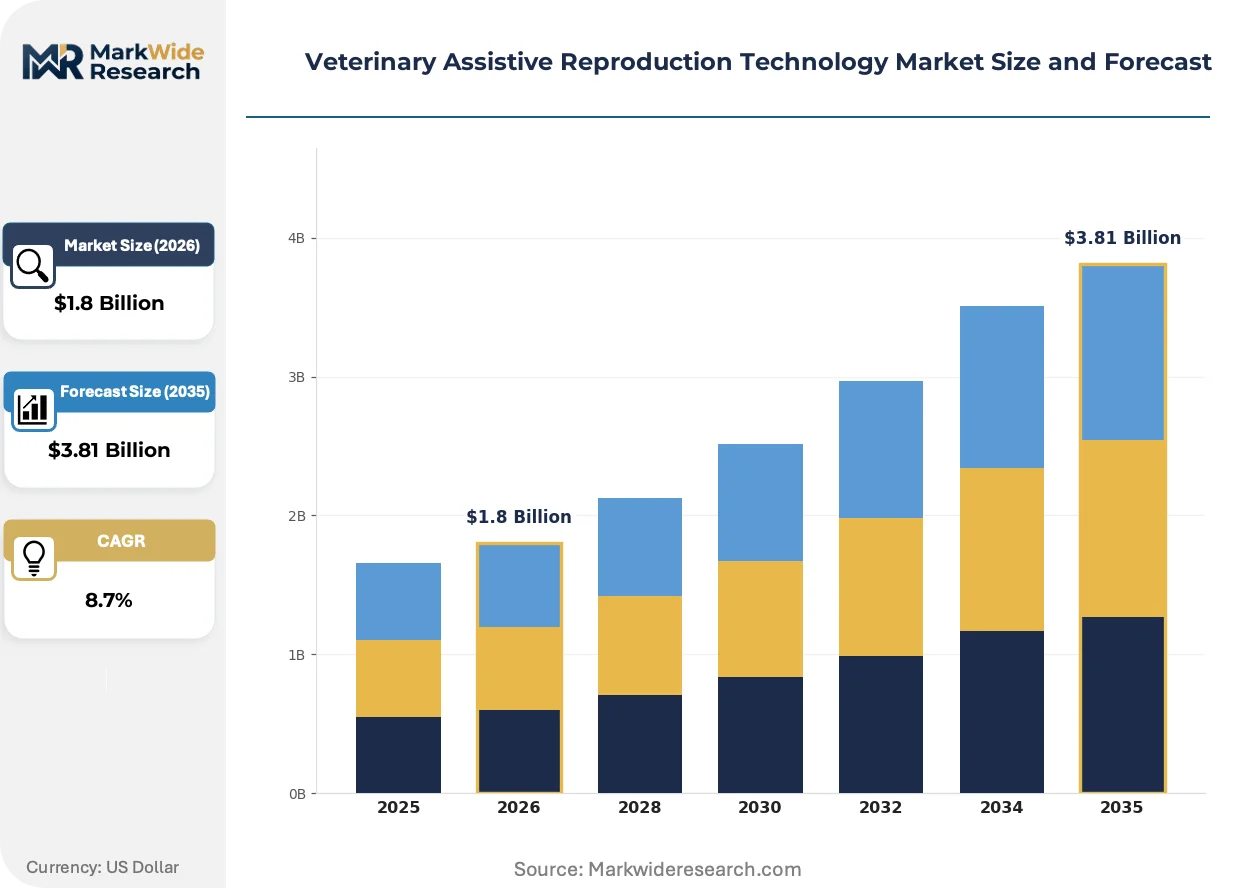
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Insemination, Embryo Transfer, Ovulation Induction, Synchronization Animal Type: Equine, Bovine, Canine, Feline Application: Breeding Programs, Genetic Enhancement, Research Studies, Clinical Treatments End User: Veterinary Clinics, Research Institutions, Breeding Farms, Zoos |
| Companies Covered | Genus Plc, IMV Technologies, URUS Group, CRV Holdings, Select Sires, SEMEX, Minitube Group, STgenetics, VikingGenetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Assistive Reproduction Technology Market Evolving Landscape
Technology convergence between human fertility standards and veterinary applications is compressing innovation cycles while elevating performance benchmarks across semen analysis and cryopreservation systems.
Sexed-semen flow cytometry is unifying genetic selection with processing throughput in large-scale bovine operations. Dairy cooperatives in the United States now specify sexed-semen purity rates above ninety percent as standard procurement terms. This capability consolidation is compressing the competitive window for conventional unsorted semen products.
REACH chemical safety registrations now govern cryoprotectant formulations used in European germplasm preservation. The ECHA substance evaluation process restricts dimethyl sulfoxide concentrations in commercial extenders, compelling reformulation of standard semen diluents. German and Dutch processing facilities are transitioning to alternative permeating cryoprotectants ahead of enforcement deadlines.
Service unbundling now separates genetic consultation from insemination execution in North American dairy procurement. Large herd operators contract directly with genomic testing laboratories, bypassing traditional veterinary intermediary channels for breeding decisions. This disintermediation concentrates in the Upper Midwest, where integrated crop-livestock operations maintain in-house technician staff.
Veterinary Assistive Reproduction Technology Market Segmentation
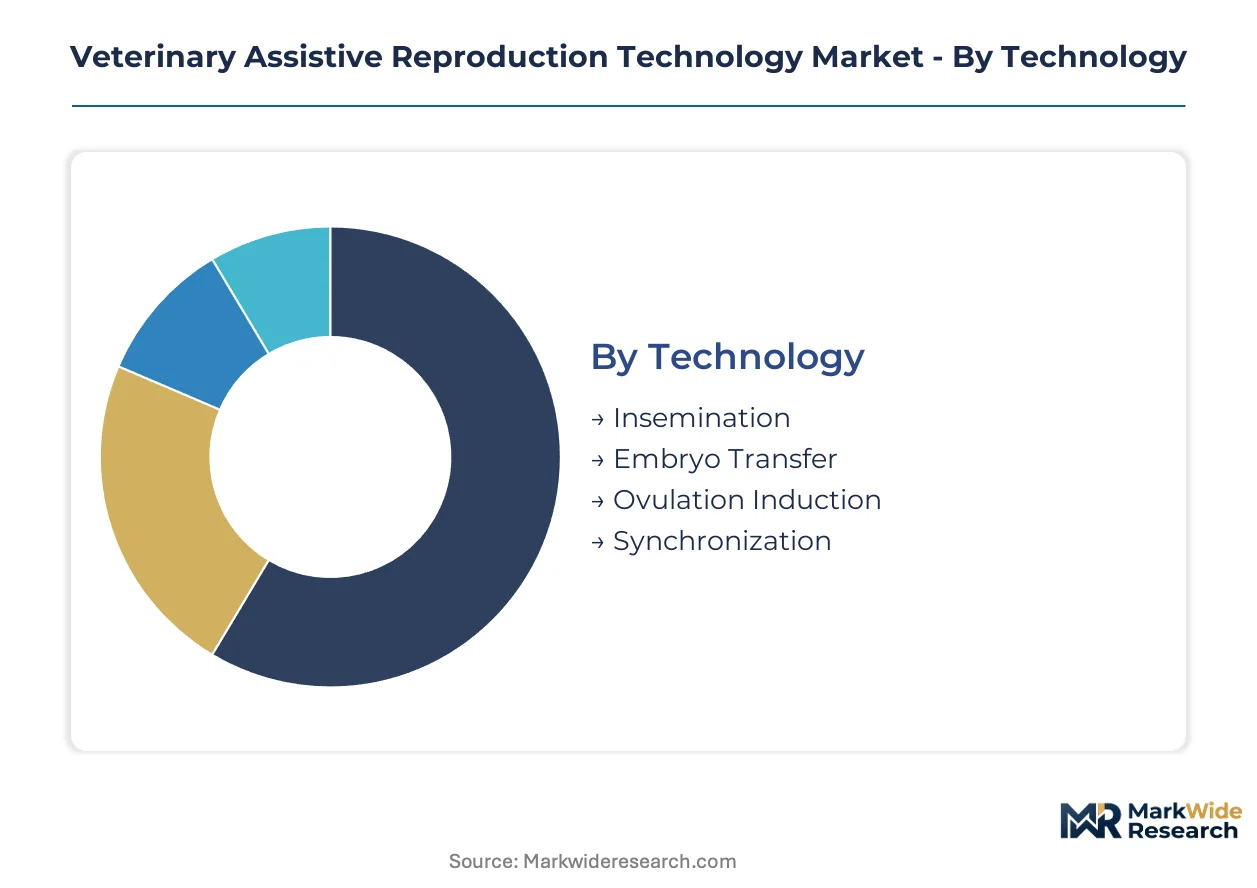
Segmentation in veterinary assistive reproduction technology reveals distinct equipment requirements, regulatory pathways, and margin structures across species and use cases. Each dimension carries implications for cold-chain logistics, technician certification, and recurring consumable demand.
Technology:
Integration depth varies sharply—insemination protocols function as standalone field procedures, while embryo transfer demands surgical infrastructure and laboratory coordination.
- Insemination:Straw-based semen delivery systems dominate commercial throughput, with liquid nitrogen cryopreservation at minus 196 degrees Celsius enabling decentralized field application. Dairy cooperatives in the United States drive recurring straw purchases through large-scale herd expansion programs.
- Embryo Transfer:Surgical recovery and transfer procedures require specialized catheters, hormonal priming protocols, and laboratory incubation capacity. Equine sport-horse breeders in Kentucky and Florida command premium margins for proven dam genetics over conventional mating timelines.
- Ovulation Induction:Hormonal synchronization protocols enable timed artificial insemination windows in commercial bovine operations.
- Synchronization:Fixed-time breeding programs reduce labor costs and technician dependency for regional dairy farms.
Insemination leads volumes today; embryo transfer is gaining share fastest.
Animal Type:
Species-specific anatomy governs catheter design, hormonal dosing, and regulatory biocompatibility testing burdens.
- Bovine:Cervical insemination dominates transaction economics, with sexed-semen flow cytometry now standard in large-scale dairy procurement. USDA interstate germplasm protocols institutionalize pathogen testing and certified cold-chain documentation for North American semen shipments.
- Equine:Sport-horse breeding concentrates demand for embryo transfer services, where surgical recovery skills face supply constraints limiting regional expansion. Kentucky and Ocala maintain the densest technician certification networks.
- Canine:Companion animal fertility services remain underdeveloped relative to livestock applications, creating whitespace for specialized veterinary clinic networks.
- Feline:Limited commercial breeding infrastructure constrains addressable market size outside research and conservation contexts.
Bovine leads volumes today; canine is expanding most quickly.
Application:
Application scope determines whether technology serves production agriculture, genetic research, or clinical intervention.
- Breeding Programs:Commercial livestock operations drive standardized insemination protocols with volume-based pricing. Dairy herd expansion in the Upper Midwest concentrates purchasing power among integrated cooperatives.
- Genetic Enhancement:Genomic validation infrastructure ties research institutions to breeding farms through shared laboratory facilities and cost-sharing models for marker-assisted selection.
- Research Studies:Academic demand shapes equipment specifications for cryopreservation and computer-assisted semen analysis.
- Clinical Treatments:Therapeutic fertility interventions in companion animals require veterinary clinic infrastructure and specialized technician training.
Breeding programs lead volumes today; genetic enhancement is climbing the fastest.
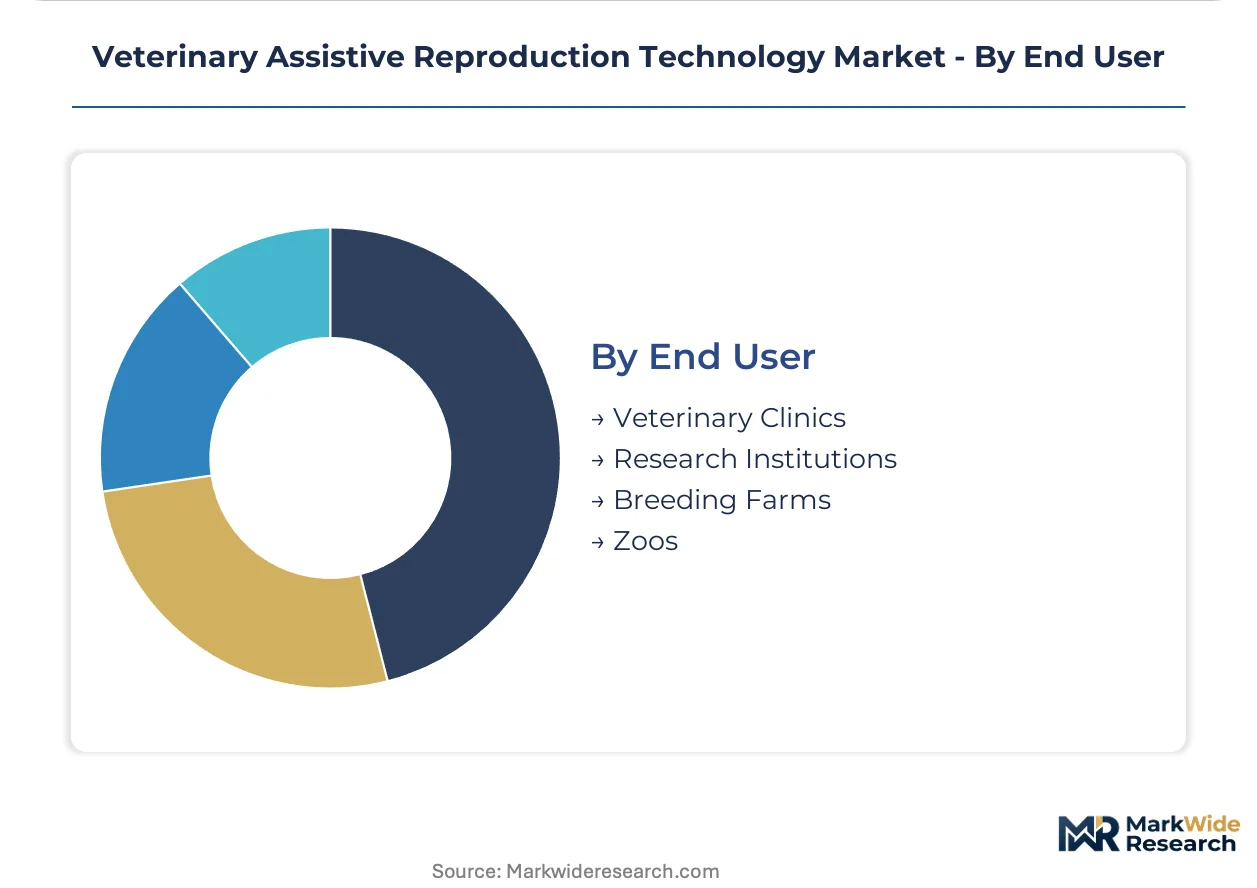
End User:
End-user category dictates procurement scale, regulatory exposure, and service bundling preferences.
- Breeding Farms:Large-scale operations maintain in-house technician staff and direct genomic testing contracts, bypassing traditional veterinary intermediaries for breeding decisions. Service unbundling concentrates in the Upper Midwest among integrated crop-livestock operations.
- Veterinary Clinics:Companion animal fertility services require capital investment in cryogenic storage and hormonal protocols, with FDA Center for Veterinary Medicine scrutiny of intrauterine catheter biocompatibility.
- Research Institutions:Shared laboratory facilities enable cost-sharing models for genetic enhancement programs and genomic validation infrastructure.
- Zoos:Conservation breeding programs for endangered species require managed reproduction protocols with specialized cryopreservation and genetic diversity tracking.
Breeding farms lead volumes today; veterinary clinics are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled embryo transfer technicians concentrate in established dairy corridors, anchoring regional service capacity and shaping equipment procurement patterns.
United States
Large-scale dairy cooperatives in Wisconsin and California drive recurring straw purchases and sexed-semen processing contracts. USDA Animal and Plant Health Inspection Service enforces interstate germplasm pathogen testing protocols. The Upper Midwest hosts the densest concentration of in-house technician staff among integrated crop-livestock operations.
Germany
Bavarian and Lower Saxon breeding farms sustain demand for automated semen analysis systems and cryogenic storage infrastructure. ECHA substance evaluation under REACH restricts dimethyl sulfoxide concentrations in commercial extenders. Dutch-German border processing facilities are transitioning to alternative permeating cryoprotectants ahead of enforcement deadlines.
France
Normandy and Brittany dairy operations maintain high artificial insemination penetration rates among Holstein herds. ANSM biocompatibility standards for intrauterine devices align with tightening EU MDR veterinary device pathways. The Massif Central cluster supports specialized equine embryo transfer services for sport-horse breeders.
Netherlands
Randstad-region breeding farms pioneer genomic validation infrastructure through shared laboratory facilities with Wageningen University research programs. Dutch national veterinary pharmaceutical regulations govern hormonal synchronization protocol approvals. Friesland maintains concentrated cold-chain logistics networks for gamete transport across Benelux dairy cooperatives.
Canada
Alberta and Ontario beef and dairy operations sustain demand for conventional and sexed-semen products. Health Canada veterinary device guidance shapes biocompatibility documentation requirements for catheter manufacturers. The Prairie Provinces host expanding technician certification programs to address regional service gaps.
Veterinary Assistive Reproduction Technology Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across semen processing, embryo handling equipment, and genetic services. The vendor base organizes around three strategic archetypes: integrated genetics platforms controlling breeding value data, specialized equipment manufacturers supplying cryopreservation and analysis systems, and cooperative semen banks serving regional dairy markets. Dominant competitive moves include backward integration into genomic testing laboratories and geographic expansion through distributor partnerships in emerging dairy regions.
Within the integrated genetics platform tier, Genus Plc and URUS Group occupy positions that exemplify consolidation around breeding value databases and global germplasm distribution networks. IMV Technologies represents the specialized equipment manufacturer archetype, anchoring European supply chains through biosecurity packaging and cold-chain logistics capabilities. These three entities collectively illustrate how competitive positioning in this market depends on controlling either genetic data assets, physical distribution infrastructure, or precision manufacturing capacity for cryogenic systems.
| Leading Market Players |
|---|
| Genus Plc |
| IMV Technologies |
| URUS Group |
| CRV Holdings |
| Select Sires |
| SEMEX |
| Minitube Group |
| STgenetics |
| VikingGenetics |
| Others |
Value Network & Pricing Analysis
Embryo transfer technician concentration in Kentucky and Florida creates labor-cost differentials that widen pricing-tier spreads between premium equine services and standard bovine insemination packages. Regional scarcity of certified surgical skills enables Ocala-based providers to command premium rates, while Upper Midwest dairy cooperatives leverage in-house technician pools to compress field-service margins.
Pricing Analysis
The bundled-vs-unbundled service split defines pricing architecture across the veterinary assistive reproduction technology market. Large dairy cooperatives now unbundle genetic consultation from insemination execution, contracting directly with genomic testing laboratories and bypassing traditional veterinary intermediaries. Three-tier pricing structure across premium, standard, and economy levels separates embryo transfer services with surgical recovery from conventional straw-based insemination and basic synchronization protocols. Price differentiation rests on certification grade and volume scale, with ISO 13485-certified equipment carrying material premiums. Pricing pressure stems from liquid nitrogen supply volatility compressing regional semen bank margins. Beef cattle operations in price-sensitive regions exhibit highest price sensitivity, while sport-horse breeders in Kentucky show lowest sensitivity due to genetics-driven value capture.
Supply Chain Analysis
Dual-sourcing requirements now mandate multi-supplier qualification for cryogenic storage equipment and semen processing consumables across North American dairy cooperatives. Geographic supply concentration centers on the United States, Germany, and the Netherlands, with Bavarian facilities dominating automated semen analysis systems and Dutch manufacturers anchoring cold-chain logistics networks. Raw material dependencies include liquid nitrogen cryogenic fluid, specialized biosecurity packaging polymers, and hormonal synchronization compounds. Supply chain risk hinges on single-source vulnerability for sexed-semen flow cytometry components. Distribution runs through cooperative semen banks and specialized veterinary equipment distributors serving regional breeding farm clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in veterinary assistive reproduction technology rests on automation-driven cost compression in semen processing and the premium-tier shift toward sexed-semen purity specifications above ninety percent.
For Market Incumbents: Anchor defensive positioning through backward integration into genomic testing laboratories and captive supply of certified cold-chain packaging. Threat from service unbundling by large dairy cooperatives demands channel control reinforcement through direct technician staffing contracts. Capacity addition in the Upper Midwest secures volume commitments from integrated crop-livestock operations. Certification investment in EU MDR compliance extends product launch cycles but creates exclusionary barriers against undercapitalized competitors. For New Entrants and Emerging Players: FDA Center for Veterinary Medicine guidance evolution in the United States opens a window for domestic manufacturers to capture share in embryo recovery tubing as regulatory uncertainty resolves. Companion animal fertility services in veterinary clinics represent the most penetrable whitespace, with canine embryo transfer protocols underdeveloped relative to livestock applications. Geographic targeting of the Prairie Provinces in Canada addresses expanding technician certification programs and regional service gaps. Go-to-market execution through specialized veterinary clinic networks with cryogenic storage infrastructure investment enables premium positioning. For Investors and Strategic Acquirers: Integrated genetics platforms controlling breeding value databases are the most active acquirer in this space, consolidating germplasm distribution networks and genomic validation infrastructure. Long-term viability favors targets with durable data assets and physical cold-chain logistics capabilities rather than pure equipment manufacturers. Acquisition target archetype: specialized biosecurity packaging and cryogenic storage firms with USDA-compliant documentation systems. Signal to watch: convergence rate between human fertility device standards and veterinary regulatory expectations as inflection indicator for compliance cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Genomic Testing | Genus Plc and URUS Group control breeding value databases that lock in dairy cooperative purchasing decisions. |
| EU MDR Compliance Certification | IMV Technologies rebuilds quality management architectures to meet biocompatibility testing burdens for intrauterine catheters. |
| Sexed-Semen Processing Capacity Expansion | STgenetics operates large-scale facilities serving North American dairy cooperatives demanding ninety-percent purity rates. |
| Companion Animal Clinic Network Development | Canine and feline embryo transfer protocols create whitespace for specialized veterinary service providers with cryogenic infrastructure. |
| REACH-Compliant Cryoprotectant Reformulation | German and Dutch processing facilities transition from dimethyl sulfoxide to alternative permeating cryoprotectants ahead of ECHA enforcement. |
Research Methodology
Coverage spans North America and Europe, with primary inputs from each region informing demand-side and supply-side assessments. The analysis combines primary interviews with breeding farm operations managers, veterinary clinic directors, embryo transfer technicians, semen processing facility quality managers, and regulatory affairs specialists at equipment manufacturers with secondary validation. Secondary sources include FDA Center for Veterinary Medicine guidance documents, USDA Animal and Plant Health Inspection Service interstate germplasm protocols, ECHA substance evaluations under REACH, ISO 13485 certification databases, and trade data on cryogenic equipment imports. Bottom-up segmentation modeling triangulates against top-down market sizing from equipment shipment records and consumable procurement patterns.
Rate-of-change decomposition separates volume growth from price-mix effects across the analysis window. The analytical framework models segmentation dimensions including technology type, animal species, application scope, and end-user category alongside regional regulatory cluster effects. CAGRs derive from fitted growth curves calibrated to historical equipment installation data and recurring consumable purchase frequencies. Industry-specific forecast inputs incorporate dairy herd expansion trajectories in the Upper Midwest and sexed-semen adoption curves in large-scale cooperatives.
Revisions become necessary when EU MDR enforcement timelines accelerate, liquid nitrogen supply disruptions persist, or USDA interstate germplasm protocols expand testing requirements. Forecasts reflect assumptions about technician certification pipeline development and genomic validation infrastructure investment sustaining genetic enhancement program growth. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Medicine
Animal Drugs Market
Veterinary Medicine
Veterinary Anesthesia Market
Veterinary Medicine
Middle East Veterinary Vaccines Market
Veterinary Medicine
Global Veterinary/Animal Vaccines Market
Veterinary Medicine
South Africa Veterinary Medicine Market
Veterinary Medicine
Over-The-Counter (OTC) Veterinary Drugs Market
Veterinary Medicine
Veterinary Pain Management Market
Veterinary Medicine
US Veterinary Diagnostics Market
Veterinary Medicine
Veterinary Anti-Infectives Market
Veterinary Medicine
Veterinary Biologics Market
Veterinary Medicine
Global Veterinary Autogenous Vaccines Market
Veterinary Medicine
Veterinary Dental Elevators Market
Veterinary Medicine
Global Companion Animal Pharmaceuticals Market
Veterinary Medicine
ASEAN Rabies Veterinary Vaccines Market
Veterinary Medicine
Global Brucellosis Vaccines Market
Veterinary Medicine
United States Veterinary Healthcare Market