
 Molded Pulp Inserts Market | 2026-2036
Molded Pulp Inserts Market Size, Share, and Industry Trends Forecast 2026-2036
Molded Pulp Inserts Market Insights
Modularization of packaging configurations around product-specific cavity designs is hardening as the dominant buyer preference across fulfillment networks. Huhtamaki leverages its thermoformed fiber expertise to anchor European pharmaceutical and food service insert contracts. Brødrene Hartmann sustains manufacturing scale across molded fiber egg and industrial packaging, extending capabilities into precision protective formats for electronics. Sonoco Products Company competes through integrated recycling and pulping operations that control raw material cost volatility.
Molded pulp inserts are formed from wet-laid or dry-laid cellulose fibers—typically recycled paper, bagasse, or bamboo pulp—pressed into custom-shaped cavities using heated molds to achieve specific caliper, density, and compression strength ratings for product protection. Their primary commercial purpose centers on replacing expanded polystyrene and plastic trays in protective packaging, cushioning, and structural support applications across transit and retail display. Protective inserts lead volume due to electronics packaging demand for anti-static, shock-absorbing cavity designs, while bagasse pulp and bamboo fiber compositions represent the fastest-growing material segment as brands pursue agricultural waste streams and rapidly renewable feedstocks to differentiate sustainability credentials. Structural inserts command premium positioning in cosmetic and pharmaceutical applications where rigidity and presentation quality determine specification.
The EPA regulates recycled fiber content claims and manufacturing effluent under Clean Water Act permits for US pulp molding facilities, while the EU Green Deal and Packaging and Packaging Waste Regulation mandate recyclability and recycled content thresholds that reshape material selection and end-of-life design for inserts sold into European markets. China's SAMR enforces GB standards for food-contact fiber packaging that constrain export-oriented producers serving dual markets. Stakeholders must monitor divergence between regional biodegradability certification requirements and emerging state-level plastic phase-out schedules to align capacity investments with compliant product portfolios.
Market Dynamics
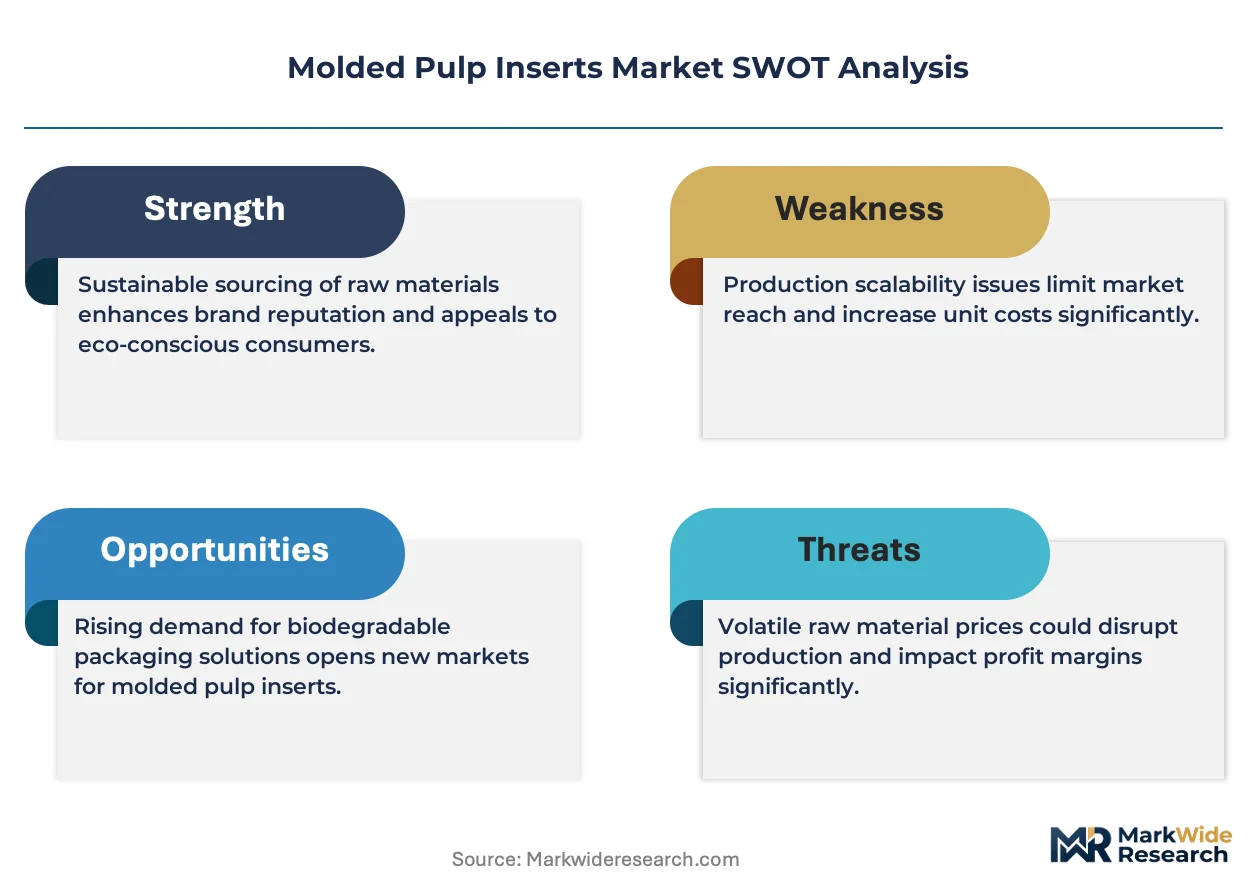
Extended producer responsibility mandates across California, Germany, and EU member states are structurally displacing expanded polystyrene with fiber-based protective formats, forcing rapid tooling investments across pulp molding networks.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Binding recyclability thresholds and recycled content floors for transport packaging are compelling electronics OEMs to specify molded pulp cavity designs over plastic trays.
- E-commerce fulfillment density:China's Shenzhen and Dongguan logistics clusters are standardizing molded pulp insert specifications across smartphone and tablet outbound shipments to reduce damage rates and plastic compliance exposure.
- Bagasse fiber processing advances:Improved refining and hot-pressing protocols for sugarcane agricultural waste are expanding caliper range and compression strength ratings to match legacy polystyrene performance.
Market Restraints
- Recycled fiber input cost volatility:OCC (old corrugated containers) pricing swings tied to Chinese import quotas and domestic collection rates compress margin predictability for independent molders lacking captive pulping.
- Tooling lead time concentration:Precision aluminum mold fabrication for complex cavity geometries concentrates with specialized toolmakers in Germany and Japan, creating 14-20 week procurement bottlenecks.
- Moisture sensitivity threshold:Unlined molded pulp exhibits dimensional instability above 85% relative humidity, constraining cold-chain pharmaceutical applications without secondary barrier films.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives for mobile device and component assembly in Noida and Sri City are creating virgin demand for protective insert specifications without incumbent plastic supplier lock-in.
- Cosmetic refill pod structural formats:Premium beauty brands are specifying rigid molded pulp trays for solid shampoo and concentrate pod retail presentation, opening unit-dose packaging applications beyond transit protection.
- California SB 54 implementation:The state's plastic pollution reduction act mandates 25% source reduction by weight, creating regulatory pull for fiber-based insert alternatives in West Coast fulfillment networks serving consumer electronics.
Industry Challenges
- Color consistency control:Batch-to-batch shade variation in recycled fiber pulp complicates brand-matched unbleached or dyed insert specifications for cosmetic and luxury goods clients.
- Hot-press energy intensity:Drying and densification cycles require sustained thermal input of 180-220°C, exposing producers to natural gas price spikes and carbon accounting pressure under EU CSRD disclosure rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molded Pulp Inserts Market |
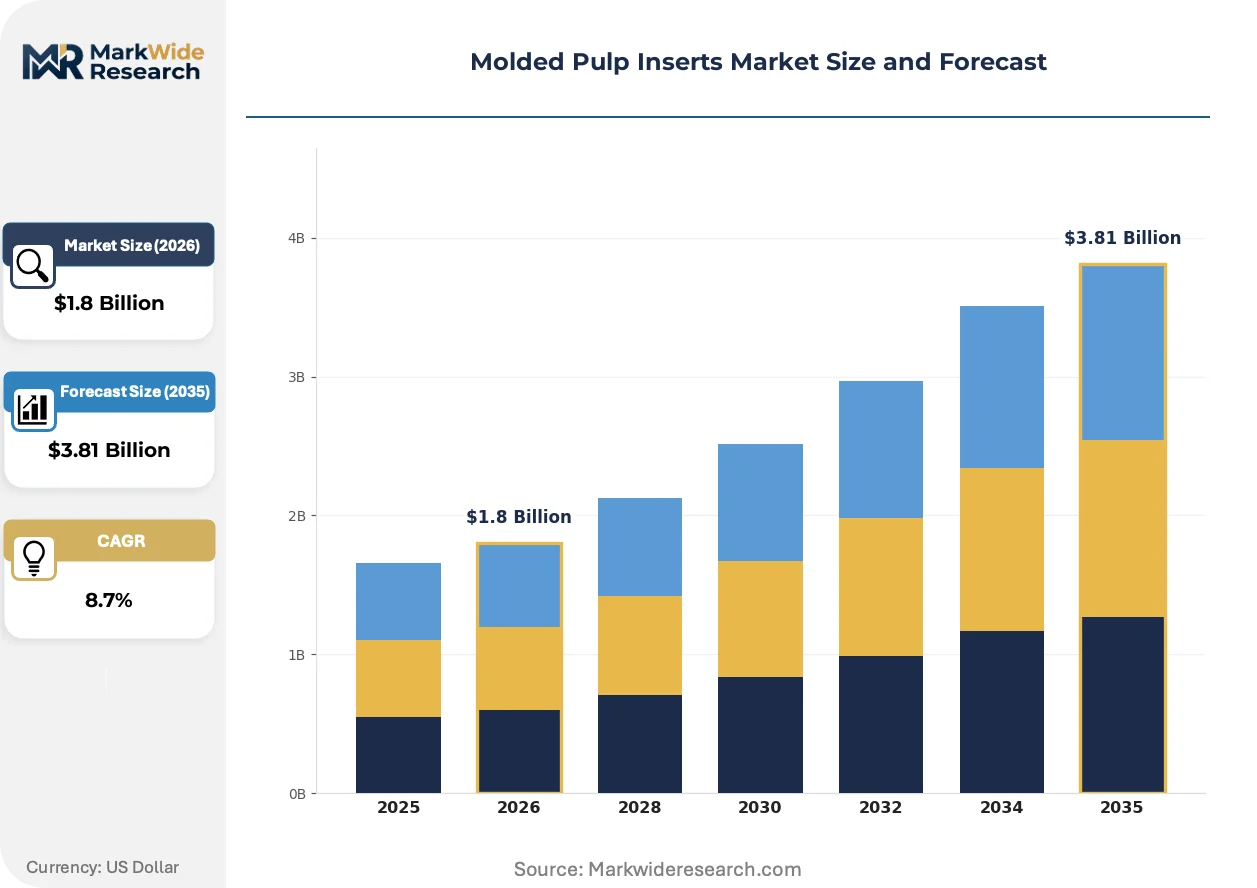
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protective Inserts, Cushioning Inserts, Structural Inserts, Decorative Inserts, Packing Inserts Material Composition: Recycled Paper, Virgin Pulp, Straw Pulp, Bamboo Fiber, Bagasse Pulp Application: Electronics Packaging, Food Service Packaging, Cosmetic Packaging, Pharmaceutical Packaging, Consumer Goods Packaging End User Industry: Electronics Manufacturers, Food & Beverage Producers, Beauty & Personal Care Brands, Pharmaceutical Companies, Household Products |
| Companies Covered | Huhtamaki, Brødrene Hartmann, Sonoco Products Company, UFP Technologies, Pactiv Evergreen, Henry Molded Products, EnviroPAK, Sabert Corporation, Pro-Pac Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molded Pulp Inserts Market Trends and Innovations
Material science advances and regulatory compliance automation are converging to expand molded pulp performance envelopes into precision-protective applications previously reserved for engineered plastics.
Dry-laid thermoformed fiber technology is rewriting protective packaging specifications for high-value electronics. Apple's supplier qualification programs for iPhone and MacBook transit inserts now accept thermoformed fiber alternatives to expanded polystyrene, compressing the performance gap between agricultural pulp and petroleum-based cushioning.
REACH restrictions on microplastics and the EU Green Deal's packaging waste targets are forcing redesign of multi-material packaging systems. Electronics OEMs serving European markets are eliminating plastic film laminates from insert surfaces, triggering investments in water-based barrier coatings for moisture and grease resistance.
Direct procurement relationships between electronics OEMs and pulp molders are displacing traditional converter intermediaries in North American and European supply chains. Amazon's Frustration-Free Packaging certification requirements now specify molded pulp formats for tier-one suppliers, visible most acutely in Seattle and Luxembourg fulfillment specification documents.
Molded Pulp Inserts Market Segmentation
Molded pulp insert specifications fragment across performance requirements, material sourcing constraints, and end-use compliance regimes. Buyers select cavity designs based on compression strength thresholds, humidity exposure limits, and regional fiber availability rather than brand preference alone.
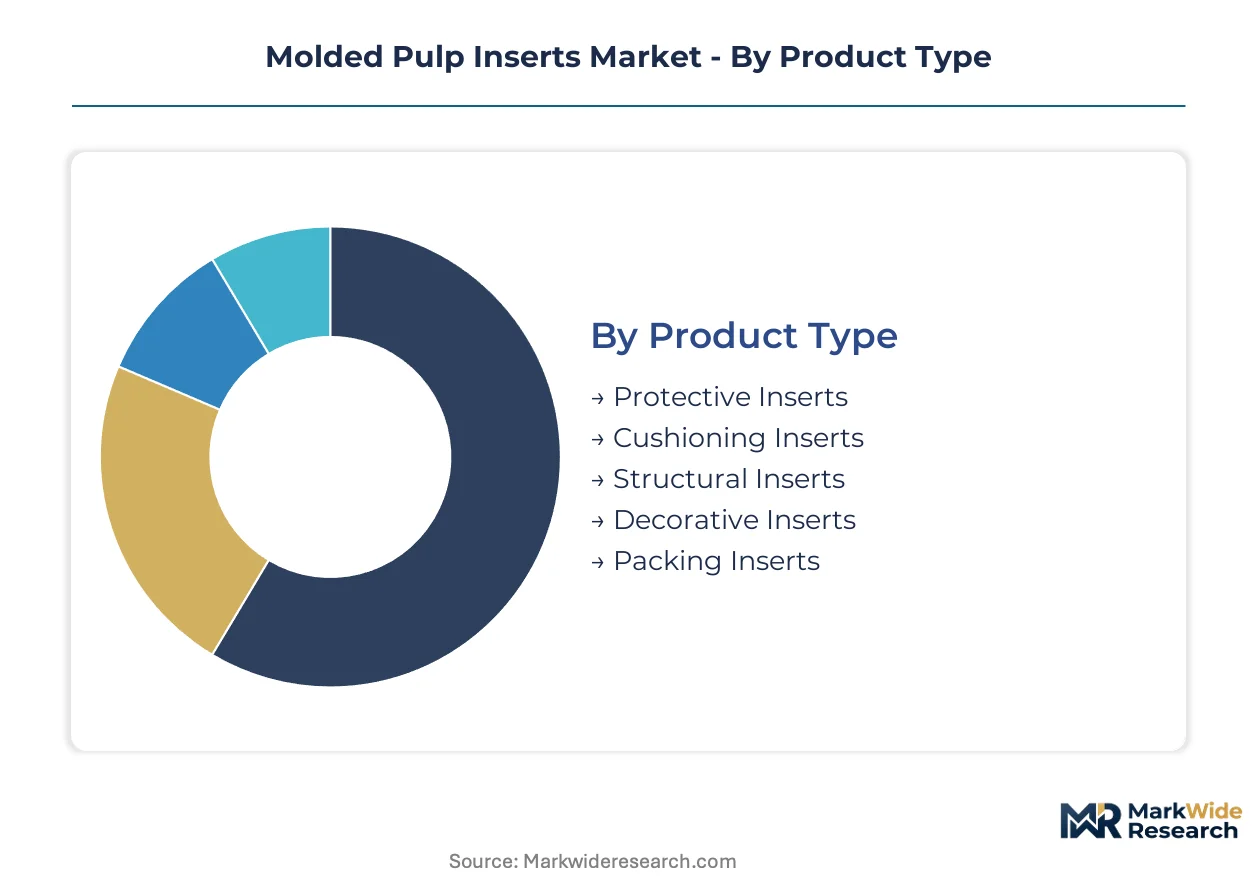
Product Type:
Tooling investments and mold fabrication lead times concentrate around insert categories serving high-volume electronics and food service contracts.
- Protective Inserts:Engineered with anti-static additives and precise cavity geometries to immobilize smartphones, tablets, and laptops during transit. Shenzhen and Dongguan fulfillment clusters standardize these specifications for outbound e-commerce shipments to reduce damage rates and plastic compliance exposure.
- Structural Inserts:High-density hot-pressed fiber formations deliver rigidity for cosmetic and pharmaceutical presentation trays. Premium beauty brands specify these for solid shampoo and concentrate pod retail display, opening unit-dose packaging applications beyond transit protection.
- Cushioning Inserts:Lower-density fiber matrices absorb shock in secondary packaging layers for fragile consumer goods.
- Decorative Inserts:Dyed or embossed surface treatments serve luxury unboxing experiences with brand-matched color specifications.
- Packing Inserts:Generic void-fill configurations prioritize cost minimization over precision fit for non-fragile shipments.
Protective inserts absorb the bulk of installed capacity; structural inserts are expanding most quickly.
Material Composition:
Raw material sourcing strategies diverge between producers with captive pulping operations and those exposed to OCC spot market volatility.
- Bagasse Pulp:Agricultural waste from sugarcane processing undergoes refined hot-pressing to achieve caliper ranges matching legacy polystyrene performance. India's PLI scheme for electronics manufacturing is driving virgin protective insert specifications without incumbent plastic supplier lock-in.
- Bamboo Fiber:Rapidly renewable feedstock with shorter harvest cycles than wood pulp supports sustainability differentiation claims. China's dual carbon goals and GB standards enforcement accelerate domestic adoption for export-oriented producers serving dual markets.
- Recycled Paper:Post-consumer OCC streams dominate volume but face price swings tied to Chinese import quotas.
- Virgin Pulp:Bleached kraft fibers serve pharmaceutical and food-contact applications requiring purity certification.
- Straw Pulp:Wheat and rice agricultural residues offer regional sourcing advantages in grain-producing provinces.
Recycled paper commands the largest share of fiber input tonnage; bagasse pulp is climbing the fastest as brands pursue agricultural waste streams.
Application:
Regulatory pressure on single-use plastics is reshaping specification priorities across end-use categories with divergent performance requirements.
- Electronics Packaging:Anti-static, shock-absorbing cavity designs dominate procurement volumes. Apple's supplier qualification programs now accept thermoformed fiber alternatives to expanded polystyrene for iPhone and MacBook transit inserts.
- Food Service Packaging:EU Packaging and Packaging Waste Regulation recyclability thresholds and China's SAMR GB standards constrain material selection for dual-market producers.
- Cosmetic Packaging:Rigid presentation quality and color consistency control determine premium brand specifications.
- Pharmaceutical Packaging:Moisture sensitivity above 85% relative humidity constrains cold-chain applications without secondary barrier films.
- Consumer Goods Packaging:Cost-driven specifications prioritize damage reduction over presentation quality for household products.
Electronics packaging channels the majority of precision mold capacity; cosmetic packaging is gaining share fastest on refill pod and solid format demand.
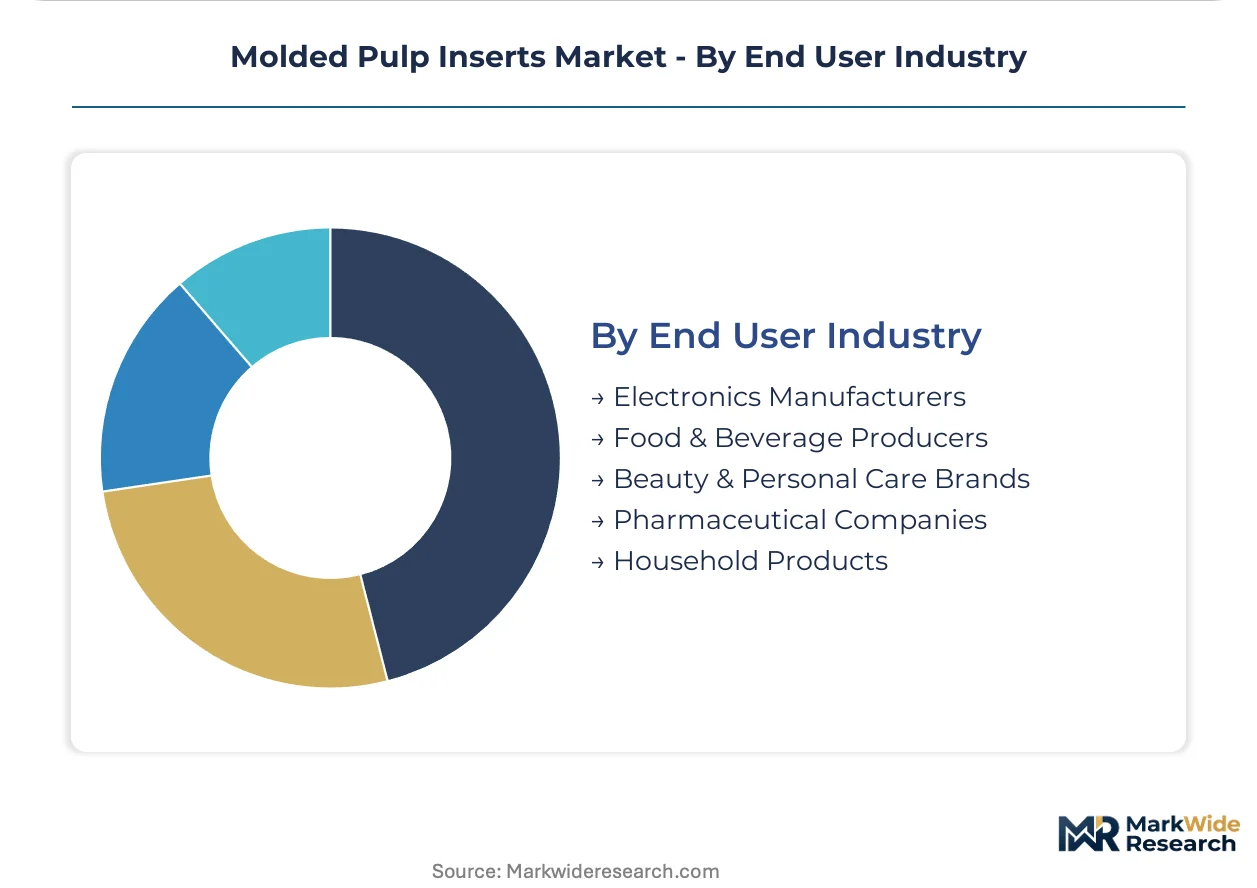
End User Industry:
Direct procurement relationships between OEMs and molders are displacing traditional converter intermediaries in North American and European supply chains.
- Electronics Manufacturers:Amazon's Frustration-Free Packaging certification requirements specify molded pulp formats for tier-one suppliers, visible in Seattle and Luxembourg fulfillment specification documents.
- Beauty & Personal Care Brands:Premium positioning demands unbleached or dyed insert specifications with batch-to-batch shade consistency control.
- Food & Beverage Producers:Huhtamaki anchors European food service insert contracts through thermoformed fiber expertise.
- Pharmaceutical Companies:EPA Clean Water Act permits and EU CSRD disclosure rules govern manufacturing effluent and carbon accounting pressure.
- Household Products:Volume-driven procurement prioritizes cost stability over performance differentiation for non-fragile goods.
Electronics manufacturers represent the dominant demand concentration; beauty and personal care brands are accelerating specifications fastest on sustainability credential requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates molded pulp insert manufacturing capacity while the United States and Germany absorb premium demand for precision protective formats. Consumption patterns diverge between Asia-Pacific electronics fulfillment networks and European regulatory-driven replacement of polystyrene cushioning.
China
Shenzhen and Dongguan logistics clusters standardize molded pulp insert specifications across smartphone and tablet outbound shipments. SAMR enforces GB standards for food-contact fiber packaging that constrain export-oriented producers serving dual markets. Yangtze River Delta pulping operations supply fiber to precision molders serving Apple supplier qualification programs.
United States
Amazon's Frustration-Free Packaging certification requirements specify molded pulp formats for tier-one suppliers in Seattle and West Coast fulfillment networks. California SB 54 mandates 25% source reduction by weight, creating regulatory pull for fiber-based alternatives. EPA Clean Water Act permits govern manufacturing effluent for domestic pulp molding facilities.
Germany
Precision aluminum mold fabrication for complex cavity geometries concentrates with specialized toolmakers creating procurement bottlenecks. EU Packaging and Packaging Waste Regulation recyclability thresholds compel electronics OEMs to specify molded pulp designs. Bavarian automotive suppliers are piloting fiber-based protective formats for component transit.
India
PLI scheme production-linked incentives for mobile device assembly in Noida and Sri City create virgin demand without incumbent plastic supplier lock-in. BIS standards for packaging materials shape specification requirements for domestic and export markets. Maharashtra and Gujarat pulping operations expand capacity to serve emerging electronics manufacturing clusters.
Japan
METI circular economy directives accelerate fiber-based packaging substitution in precision electronics supply chains. JIS standards for molded pulp products govern quality specifications for domestic and regional export markets. Kanto region toolmakers supply precision mold fabrication to regional electronics OEMs transitioning from polystyrene cushioning.
Molded Pulp Inserts Market Competitive Landscape
The competitive structure tilts toward integrated fiber processors with captive pulping operations and precision mold fabrication capabilities. Tier-one positions concentrate among European and North American players with established pharmaceutical and food service contracts, while Asian specialists capture electronics protective volumes through OEM direct procurement relationships. Two dominant competitive moves are reshaping positioning: backward integration into agricultural waste fiber sourcing to stabilize input costs, and strategic partnerships with electronics OEMs to secure multi-year insert specification contracts.
Among European-based specialists, Huhtamaki and Brødrene Hartmann exemplify the integrated processor archetype with thermoformed fiber expertise anchoring regional pharmaceutical and industrial packaging contracts. Sonoco Products Company represents the North American model of recycling and pulping operations controlling raw material cost volatility. These three players occupy positions across the premium specification tier where precision cavity designs and compliance documentation determine procurement decisions.
| Leading Market Players |
|---|
| Huhtamaki |
| Brødrene Hartmann |
| Sonoco Products Company |
| UFP Technologies |
| Pactiv Evergreen |
| Henry Molded Products |
| EnviroPAK |
| Sabert Corporation |
| Pro-Pac Packaging |
| Others |
Pricing and Supply Chain Analysis
Precision-to-commodity cavity design divergence splits the market into specification-tiers where anti-static, complex-geometry protective formats for electronics OEMs command substantial premiums over generic void-fill configurations, and this bifurcation maps directly onto supply chain geography with premium mold fabrication concentrating in Germany and Japan while commodity pulping feeds from Yangtze River Delta recycled fiber operations.
Pricing Analysis
Margin tightening in precision protective tiers reflects 14-20 week aluminum mold procurement bottlenecks from specialized German and Japanese toolmakers. Three-tier pricing structure across premium, standard, and economy levels differentiates by cavity complexity and anti-static certification. Cost compression accelerates in commodity cushioning as OCC spot volatility from Chinese import quota fluctuations squeezes independent molders lacking captive pulping. Electronics OEMs show lowest price sensitivity; household goods distributors exhibit highest.
Supply Chain Analysis
Recycled fiber supply rests on Yangtze River Delta pulping operations, German precision toolmakers, and Indian bagasse processing expansion. Raw material dependencies center on OCC streams, sugarcane agricultural waste, and bamboo pulp from southern Chinese provinces. Single-source vulnerability concentrates in precision aluminum mold fabrication for complex cavity geometries. Distribution runs through direct procurement relationships between electronics OEMs and molders displacing traditional converter intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dry-laid thermoformed fiber technology is displacing expanded polystyrene cushioning in high-value electronics transit protection, creating a multi-year specification transition window for positioning across the value chain.
For Market Incumbents: Acquire captive pulping operations to stabilize OCC input cost exposure against Chinese import quota volatility. Secure multi-year insert specification contracts with electronics OEMs through Apple's supplier qualification programs and Amazon's Frustration-Free Packaging certification pathways. Invest in water-based barrier coating R&D to eliminate plastic film laminates for EU Green Deal compliance.
For New Entrants and Emerging Players: Enter via India's PLI scheme electronics manufacturing clusters in Noida and Sri City where virgin protective insert demand lacks incumbent plastic supplier lock-in. Target cosmetic refill pod structural formats for premium beauty brands specifying rigid molded pulp trays. Pursue direct procurement relationships with West Coast fulfillment networks serving California SB 54 mandates.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated fiber processors possessing precision mold fabrication capabilities given EU Packaging and Packaging Waste Regulation recyclability threshold enforcement. Long-term viability favors backward integration into agricultural waste fiber sourcing. Watch bagasse pulp processing yield improvements as the inflection signal for agricultural waste stream competitiveness against recycled paper.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Waste Fiber Sourcing | Bagasse pulp processing in Maharashtra and Gujarat stabilizes input costs against OCC spot volatility. |
| Precision Mold Fabrication Capacity Expansion | German and Japanese toolmaker partnerships compress 14-20 week procurement bottlenecks for complex cavity geometries. |
| Water-Based Barrier Coating R&D Investment | Eliminates plastic film laminates to meet EU Green Deal packaging waste targets for electronics OEMs. |
| Direct Procurement Relationship Development | Amazon's Frustration-Free Packaging certification requirements specify molded pulp formats for tier-one suppliers. |
| Anti-Static Additive Formulation Partnership | Electronics packaging specifications for smartphones and tablets require shock-absorbing cavity designs with static control. |
Research Methodology
Trade databases, regulatory filings, and industry association reports formed the secondary backbone, cross-referenced with primary interviews involving pulp molding plant managers, electronics OEM procurement leads, packaging distribution channel partners, and sustainability compliance directors. Bottom-up capacity assessments across Yangtze River Delta and Indian pulping operations were triangulated with top-down demand modeling from e-commerce fulfillment cluster specifications.
Historical trendline analysis of molded pulp insert adoption rates across electronics transit applications informed projection frameworks over the analysis window. Segmentation dimensions modeled include product type, material composition, application category, and end-user industry vertical. CAGRs were derived from elasticity-adjusted volume trajectories incorporating bagasse fiber processing yield improvements and regulatory compliance automation investments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under OCC price spike scenarios and precision mold fabrication capacity constraints. Projections reflect assumptions around EU Packaging and Packaging Waste Regulation enforcement timelines and Chinese dual carbon goal implementation pacing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fiber-Based Packaging
North America Molded Pulp Packaging Market
Fiber-Based Packaging
Fiber Bale Packaging Film Market
Fiber-Based Packaging
Europe Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
Molded Fiber Containers Market
Fiber-Based Packaging
Global Molded Fiber Bowls Market
Fiber-Based Packaging
Fibreglass Trays Market
Fiber-Based Packaging
Bio-Based PSA for Paper and Fiber-Based Flexible Packaging Market
Fiber-Based Packaging
Composite Cardboard Tubes Market
Fiber-Based Packaging
Fiber Based Packaging Market
Fiber-Based Packaging
North America Molded Fiber Packaging Market
Fiber-Based Packaging
Wheat Straw Packaging Market
Fiber-Based Packaging
Molded Fiber Trays Market
Fiber-Based Packaging
Jumbo Kraft Tubes Market
Fiber-Based Packaging
Crystalline Polyethylene Terephthalate Market
Fiber-Based Packaging
Global Molded Pulp Packaging Market
Fiber-Based Packaging
Fiber Bale Packaging Market