
 Molded Fiber Pulp Edge Protectors Market | 2026-2036
Molded Fiber Pulp Edge Protectors Market Size, Share, and Industry Trends Forecast 2026-2036
Molded Fiber Pulp Edge Protectors Market Foresight
European pulp processing capacity is shifting toward molded fiber specialization as cartonboard producers diversify beyond commodity grades. Smurfit Kappa Group leverages its integrated recycling network to secure consistent furnish for edge protector lines. Henry Molded Products anchors its position through dedicated thermoforming equipment calibrated for thick-wall fiber structures. Huhtamaki competes by extending its food-service fiber expertise into industrial protective formats.
Molded fiber pulp edge protectors are engineered from slurried cellulose fibers, typically 80-120 gsm density, formed under vacuum pressure and heat-cured into rigid L-shaped, U-shaped, or V-shaped profiles that absorb corner-impact energy during palletized transport. Corner protectors dominate volume due to universal compatibility with strapped pallet loads across furniture and electronics end users, while recycled paper material leads on cost but specialty fiber commands margin in moisture-resistant applications. V-wedge formats are gaining traction among automotive suppliers seeking nested stacking efficiency for irregular component geometries.
EPA guidelines on recyclable packaging content and EU REACH restrictions on chemical binders are reshaping formulation standards for fiber-based protective products. The EU Green Deal's packaging waste directives and FDA food-contact material rules for incidental fiber exposure collectively push manufacturers toward certified virgin and post-consumer fiber streams. Stakeholders must monitor evolving extended producer responsibility schemes and binder chemistry thresholds to maintain market access across regulated jurisdictions.
Market Dynamics
The molded fiber pulp edge protectors market pivots on the collision between EU single-use plastic bans and automotive suppliers' zero-waste logistics mandates, forcing rapid substitution of polyethylene corner guards across European supply chains.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases eliminate plastic foam alternatives in temperature-controlled transit, pushing pharmaceutical distributors toward fiber-based thermal protection systems.
- Automotive lightweighting:German OEMs specify molded fiber edge protectors for battery module shipments to reduce tare weight in electric vehicle component logistics.
- Recycled fiber furnish:Integrated paper mills divert OCC streams into molded fiber specialty grades, securing cost-competitive raw material for thick-wall protector production.
Market Restraints
- Natural gas price volatility:Heat-curing of molded fiber slurries depends on thermal energy; European gas benchmark fluctuations compress processor margins during winter demand peaks.
- Tooling lead times:Custom thermoform molds for V-wedge geometries require 14-18 week fabrication cycles, constraining rapid response to automotive program launches.
- Moisture sensitivity:Uncoated recycled fiber protectors fail humidity stress tests above 85% relative humidity, limiting adoption in tropical port-to-port container movements.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for electronics manufacturing attract molded fiber packaging investments to serve smartphone export corridors from Tamil Nadu and Karnataka.
- Coating chemistry convergence:Barrier technologies from food-service fiber applications migrate to industrial protectors, enabling water resistance without petrochemical laminates.
- Direct mill-to-fulfillment channels:E-commerce platforms bypass distributor networks for standardized L-profile protectors, capturing margin previously allocated to packaging wholesalers.
Industry Challenges
- Pulp rheology expertise:Formulating slurries for 80-120 gsm density targets requires specialized wet-end chemistry knowledge scarce outside legacy paperboard engineering teams.
- REACH compliance timelines:ECHA substance evaluation cycles for novel bio-based binders extend 18-24 months, delaying product launches for moisture-resistant grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molded Fiber Pulp Edge Protectors Market |
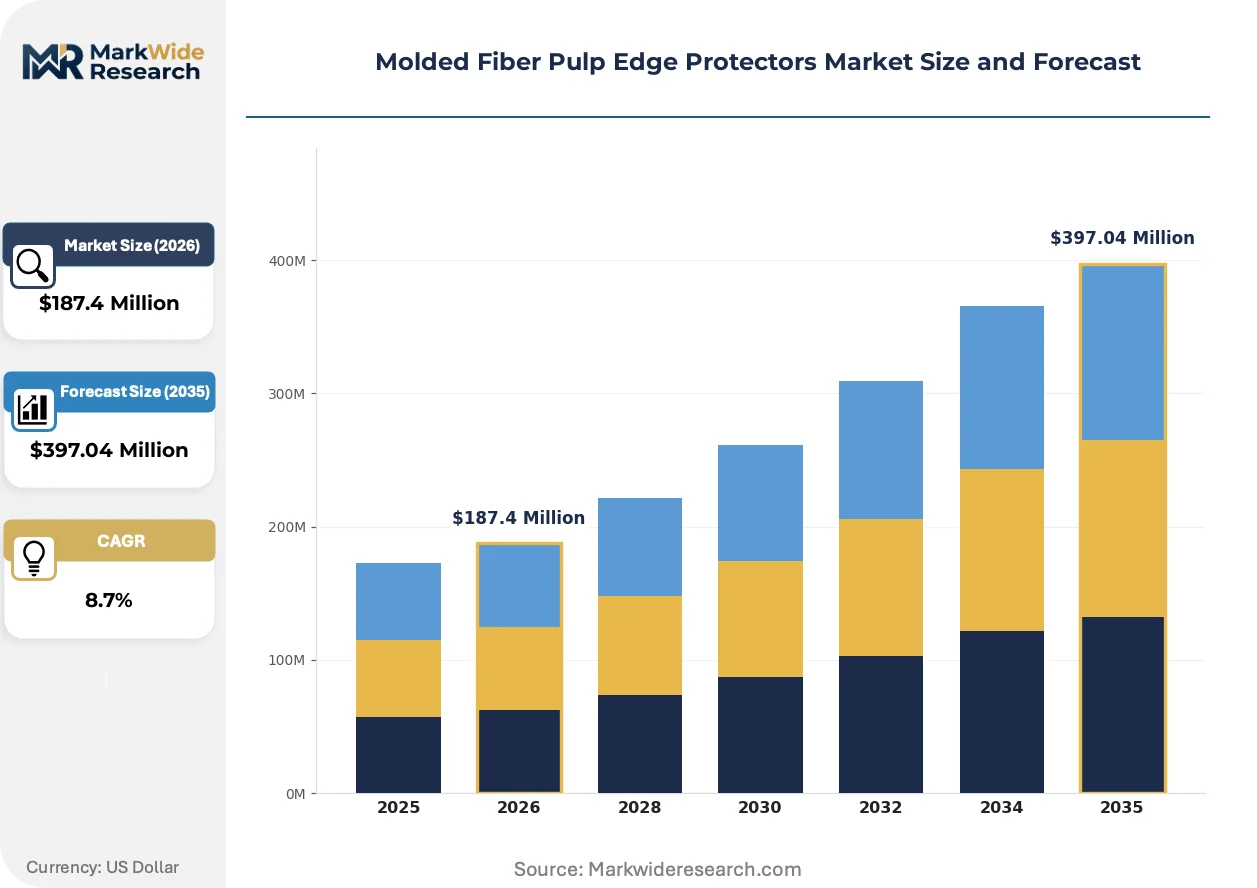
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corner Protectors, Edge Guard, V-Wedge, U-Wedge End User: Furniture Manufacturers, Electronics Packaging, Automotive Suppliers, Construction Application: Shipping, Storage, Transit, Handling Material: Recycled Paper, Virgin Fiber, Specialty Fiber, Others |
| Companies Covered | Smurfit Kappa Group, Henry Molded Products, Huhtamaki, FiberCel, CSL Packaging, International Paper Company, DS Smith, Great Northern Fiber Interior Packaging, WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molded Fiber Pulp Edge Protectors Market Shifts & Advancements
Active R&D programs across European and North American fiber processors center on eliminating performance gaps between molded pulp and plastic alternatives while compressing unit production costs through automation.
Precision vacuum-forming with real-time grammage control is electrifying quality consistency in thick-wall protector manufacturing. Automotive tier-one suppliers in Germany's Baden-Württemberg region adopt these systems for zero-defect battery packaging programs. The technology is electrifying competitive positioning by enabling fiber processors to match polyethylene dimensional tolerances at equivalent cycle speeds.
EPA guidelines on recyclable packaging content are tightening disclosure requirements for federal procurement contracts. US-based electronics distributors now mandate third-party certification of post-consumer fiber percentages in edge protector specifications. The regulation most affects corner protector volumes in government-funded infrastructure equipment shipments, where contractors substitute certified fiber products to maintain bid eligibility.
Consolidated buying by multinational furniture retailers compresses supplier rosters to single-source molded fiber contracts spanning multiple continents. Procurement teams at Swedish and Dutch retail headquarters now specify unified protector geometries across Asian and European distribution centers. This concentration is most visible in flat-pack furniture logistics, where standardized L-profiles reduce SKU complexity and enable volume pricing leverage against regional fiber processors.
Molded Fiber Pulp Edge Protectors Market Segmentation
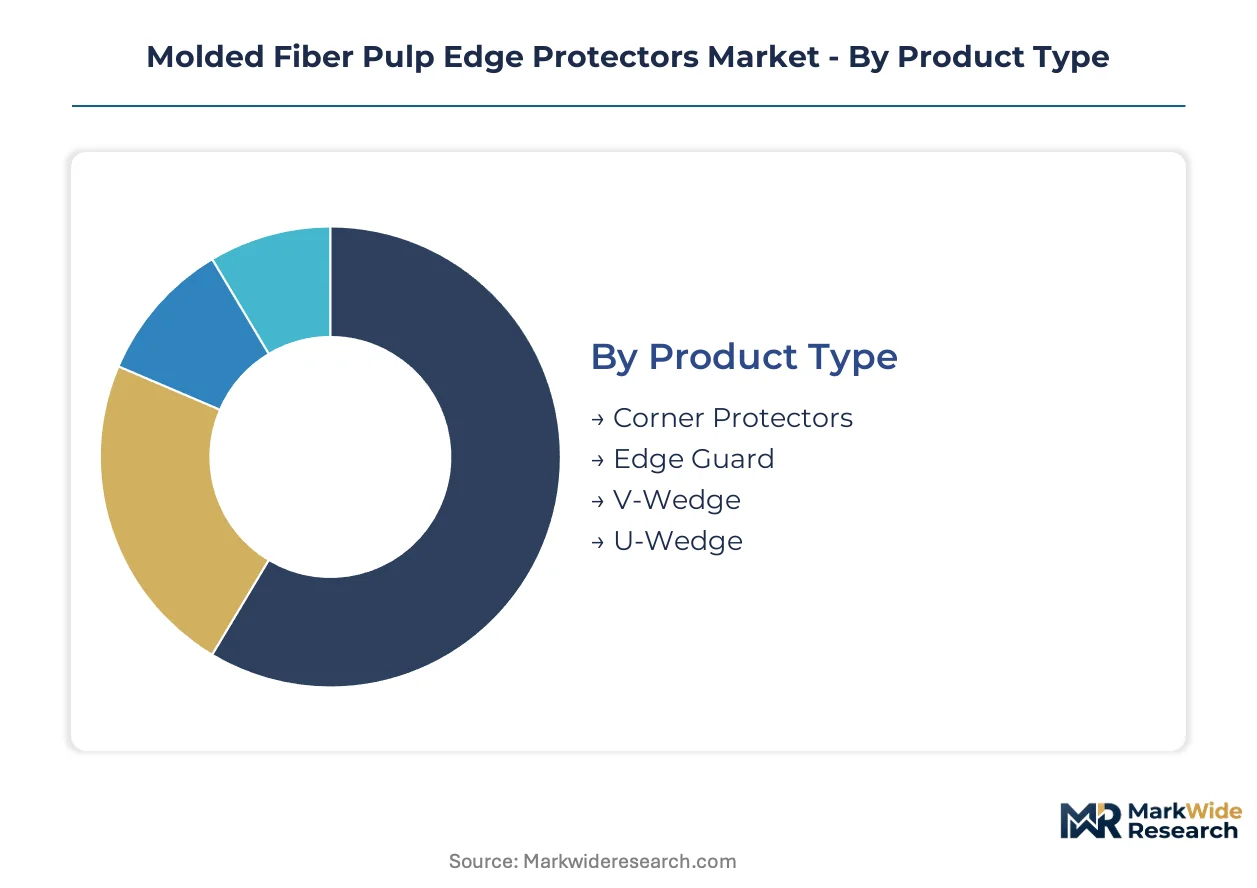
Molded fiber pulp edge protector specifications diverge sharply by load geometry, end-use durability requirements, and furnish chemistry. Procurement teams select formats based on pallet strapping patterns, humidity exposure, and regulatory certification tiers rather than unit cost alone.
Product Type:
Format engineering determines impact absorption geometry and nesting density in returnable logistics loops.
- Corner Protectors:L-shaped profiles formed at 80-120 gsm density absorb concentrated corner-impact energy during strapped pallet transit. Furniture flat-pack distributors in Germany and electronics fulfillment centers in the Netherlands specify these for universal compatibility with automated stretch-wrapping lines. Demand concentrates where palletized unit loads face repeated forklift handling.
- V-Wedge:Nested triangular profiles enable stacking efficiency for irregular automotive component geometries. German battery module suppliers specify V-wedges to secure cylindrical cell arrays during plant-to-plant movements. The format gains traction where dimensional tolerance rivals polyethylene alternatives.
- Edge Guard:Continuous linear profiles protect elongated furniture edges and panel products. Swedish retailers specify uniform edge guards across Asian and European distribution centers to reduce SKU complexity.
- U-Wedge:Channel-form protectors cradle sensitive electronics edges during air-freight movements. Tamil Nadu smartphone exporters adopt U-wedges for shock isolation in temperature-variable cargo holds.
Corner protectors lead on scale; V-wedge leads on momentum.
End User:
Customer procurement maturity separates specification-driven automotive programs from price-sensitive furniture volume buying.
- Automotive Suppliers:German OEMs mandate zero-defect fiber packaging for electric vehicle battery shipments. Baden-Württemberg tier-one suppliers require real-time grammage control and REACH-compliant binder chemistry. Programs specify moisture-resistant grades despite 15-20% cost premiums over recycled alternatives.
- Electronics Packaging:US distributors face EPA recyclable content disclosure requirements for federal procurement contracts. Third-party certification of post-consumer fiber percentages now gates bid eligibility. Smartphone export corridors from Karnataka drive volume through PLI-linked manufacturing investments.
- Furniture Manufacturers:Consolidated multinational retailers compress supplier rosters to single-source contracts spanning continents. Flat-pack logistics favor standardized L-profiles with volume pricing leverage against regional processors.
- Construction:Building material distributors specify heavy-duty edge protection for gypsum board and engineered panel shipments. Humidity sensitivity limits adoption in tropical port-to-port movements.
Automotive suppliers lead on specification intensity; electronics packaging leads on regulatory-driven substitution.
Application:
Use-phase exposure severity dictates barrier coating requirements and fiber density targets.
- Shipping:Ocean container movements expose protectors to 85%+ relative humidity stress. Uncoated recycled fiber fails accelerated aging tests, pushing pharmaceutical distributors toward specialty fiber with bio-based moisture barriers.
- Transit:Multi-modal movements with repeated handling cycles demand corner-impact resilience. German automotive logistics specify fiber protectors over polyethylene for lightweighting in electric vehicle component supply chains.
- Storage:Warehouse stacking loads emphasize compressive strength over moisture resistance. Integrated paper mills divert OCC streams into storage-grade protectors at cost-competitive furnish rates.
- Handling:Short-cycle forklift movements prioritize low unit cost. Recycled paper material dominates where exposure duration remains under 72 hours.
Shipping leads on performance requirements; transit leads on plastic substitution velocity.
Material:
Furnish chemistry separates commodity volume plays from certified specialty margins.
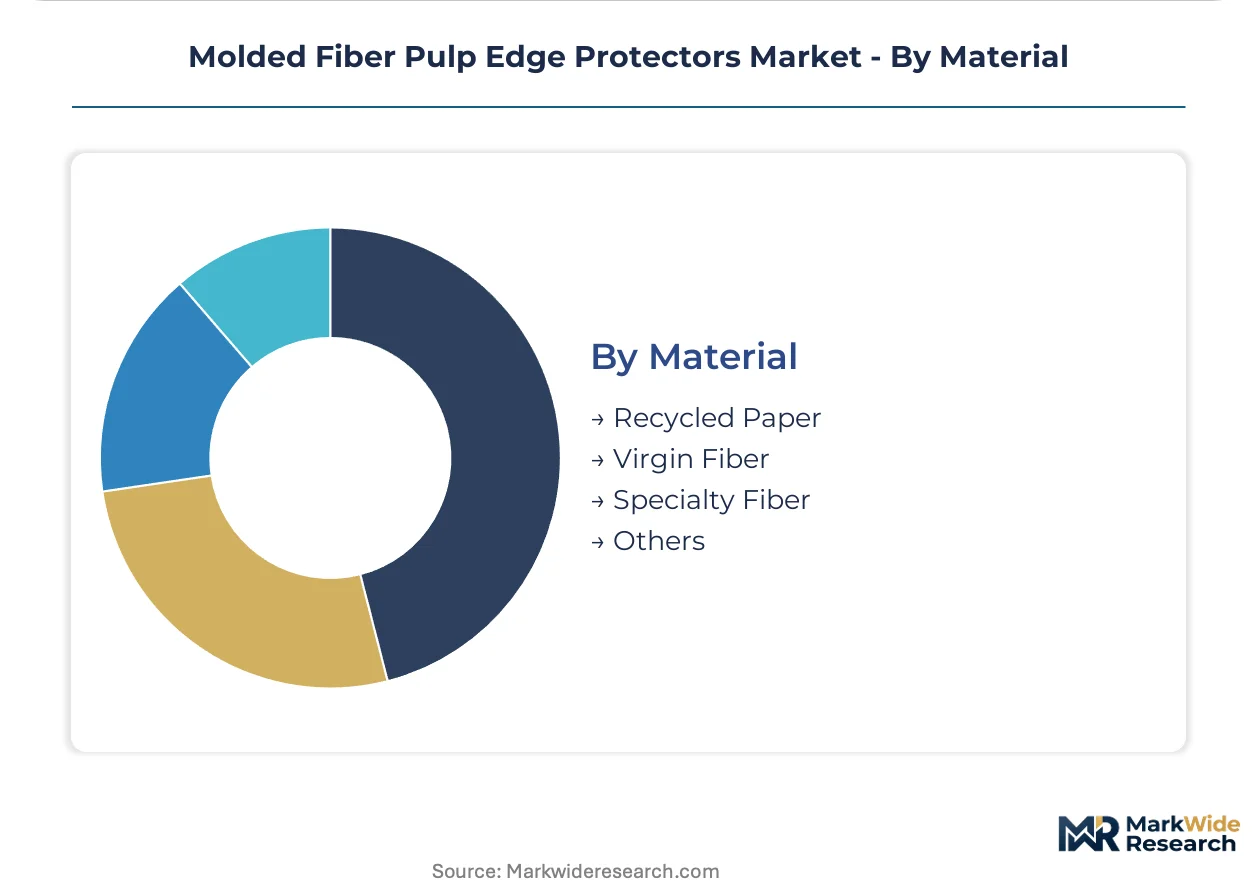
- Recycled Paper:OCC-derived slurries cost 30-40% below virgin alternatives. European integrated mills divert cartonboard waste streams into molded fiber specialization. Humidity sensitivity above 85% relative humidity constrains adoption in tropical logistics.
- Specialty Fiber:Chemically treated pulps achieve moisture resistance without petrochemical laminates. Food-service barrier technologies migrate to industrial protectors under ECHA evaluation timelines. REACH compliance cycles extend 18-24 months for novel bio-based binders.
- Virgin Fiber:Certified sustainable plantation sources serve FDA food-contact incidental exposure rules. Premium pricing captures margin in pharmaceutical and premium electronics segments.
- Others:Agricultural residue fibers and hybrid cellulose-mineral composites test at pilot scale. Smurfit Kappa Group evaluates straw-based furnish for carbon footprint reduction in edge protector lines.
Recycled paper leads on volume; specialty fiber leads on margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions where EU REACH compliance costs and energy tariffs create arbitrage opportunities for fiber processors. German automotive demand pulls capacity eastward while Asian electronics corridors capture investment through production-linked incentives.
Germany
Baden-Württemberg automotive tier-one suppliers specify zero-defect molded fiber packaging for electric vehicle battery modules. The EU F-Gas Regulation eliminates fluorinated foam alternatives in temperature-controlled transit. Stuttgart industrial corridor processors deploy precision vacuum-forming with real-time grammage control for thick-wall protector manufacturing.
United States
Electronics distributors face EPA recyclable content disclosure requirements for federal procurement contracts. Third-party certification of post-consumer fiber percentages now gates bid eligibility in government-funded infrastructure shipments. Southeast paperboard mills divert OCC streams into molded fiber specialization to serve furniture flat-pack logistics.
India
Tamil Nadu and Karnataka smartphone export corridors drive volume through PLI scheme-linked manufacturing investments. Central government production-linked incentives attract molded fiber packaging investments to serve electronics manufacturing clusters. Bangalore-Tamil Nadu industrial belt processors configure thermoforming lines for U-wedge geometries in air-freight electronics movements.
Netherlands
Rotterdam port logistics and EU Green Deal packaging waste directives accelerate polyethylene substitution in palletized transit. ECHA substance evaluation cycles for bio-based binders extend compliance timelines for moisture-resistant grades. Dutch furniture retail headquarters consolidate supplier rosters to single-source fiber contracts spanning Asian and European distribution centers.
China
Yangtze River Delta integrated paper mills diversify cartonboard capacity into molded fiber specialization for export packaging. Dual carbon goals and MEE environmental enforcement tighten furnish sourcing standards for industrial protective products. Shanghai-Suzhou industrial cluster processors test agricultural residue fibers for carbon footprint reduction in edge protector lines.
Molded Fiber Pulp Edge Protectors Market Competitive Landscape
European producers anchor the integrated recycling tier; North American specialists hold position through captive paperboard supply. Market structure consolidates around three to five vertically integrated paper groups with dedicated molded fiber divisions, supplemented by regional thermoforming specialists serving automotive program launches. Strategic archetypes separate integrated recyclers, thick-wall thermoforming specialists, and food-service fiber diversifiers. Competitive moves concentrate on backward integration into OCC furnish streams and geographic expansion through distributor network capture.
Among European integrated paper groups, Smurfit Kappa Group exemplifies the recycler-anchored archetype through its furnish security model. Henry Molded Products occupies a position within the thick-wall thermoforming specialist tier. Huhtamaki represents food-service fiber expertise migration into industrial protective formats.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| Henry Molded Products |
| Huhtamaki |
| FiberCel |
| CSL Packaging |
| International Paper Company |
| DS Smith |
| Great Northern Fiber Interior Packaging |
| WestRock Company |
| Others |
Supply & Pricing Matrix
Backward integration into OCC furnish streams anchors competitive positioning for European integrated mills while compressing pricing power among non-integrated thermoforming specialists. German automotive procurement teams leverage captive paperboard supply to extract volume discounts on REACH-compliant specialty fiber grades, leaving regional processors exposed to natural gas cost volatility during winter curing cycles.
Pricing Analysis
Distributor margins in European palletized logistics channels absorb 12-18 percentage points before protectors reach furniture flat-pack retailers. Three-tier pricing structure across premium, standard, and economy levels separates moisture-resistant specialty fiber from uncoated recycled grades, with certification premiums widening as ECHA evaluation timelines extend. Cost compression in standard-tier recycled paper runs through natural gas benchmark fluctuations, while automotive suppliers show least price sensitivity due to zero-defect program requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from German battery module suppliers, bypassing packaging wholesalers entirely. Production concentrates in Germany, the United States, and India, with furnish sourcing anchored in integrated cartonboard waste streams. Mold slurry formulation draws from wet-end chemistry expertise concentrated in legacy paperboard engineering teams. Single-source vulnerability sits with 14-18 week thermoform tooling fabrication cycles for V-wedge geometries. Distribution runs through e-commerce platforms capturing margin from standardized L-profile volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The molded fiber pulp edge protectors market reads as a late-cycle quality story as automotive suppliers shift procurement specifications toward zero-defect moisture-resistant grades with REACH-compliant binder chemistry.
For Market Incumbents: Anticipate margin compression from natural gas price volatility by securing long-term thermal energy contracts or electrifying heat-curing lines. Consolidate regional thermoforming specialists to capture automotive program launch volumes before 14-18 week tooling cycles lock in competitor relationships. Prioritize ECHA pre-submission for novel bio-based binders to compress 18-24 month compliance timelines. For New Entrants and Emerging Players: Enter via Tamil Nadu and Karnataka smartphone export corridors where PLI scheme investments create demand pull without entrenched supplier relationships. Target U-wedge geometries for air-freight electronics movements where dimensional tolerance requirements remain less stringent than automotive battery specifications. Lead with coating chemistry convergence from food-service fiber applications to differentiate on moisture resistance without petrochemical laminates. For Investors and Strategic Acquirers: Roll-up economics work for thick-wall thermoforming specialists because automotive program launches require dedicated equipment calibration that regional players cannot replicate without capital intensity. Target mid-cap processors with captive OCC furnish streams and existing REACH certification portfolios. Watch ECHA substance evaluation cycle acceleration as the inflection signal for specialty fiber margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into OCC Furnish | Integrated mills divert cartonboard waste streams to secure cost-competitive raw material for thick-wall protector production. |
| Electrification of Heat-Curing Lines | Precision vacuum-forming with real-time grammage control enables fiber processors to match polyethylene dimensional tolerances. |
| ECHA Pre-Submission for Bio-Based Binders | Early engagement with REACH compliance timelines compresses 18-24 month evaluation cycles for moisture-resistant grades. |
| Direct Mill-to-Fulfillment Channel Capture | E-commerce platforms bypass distributor networks to capture margin previously allocated to packaging wholesalers. |
| Coating Chemistry Migration from Food-Service | Barrier technologies from food-service fiber applications enable water resistance without petrochemical laminates. |
Research Methodology
Multiple input streams — primary interviews with procurement directors at automotive tier-one suppliers, packaging engineers at electronics distributors, and plant managers at integrated paper mills, alongside secondary validation through EU REACH substance databases, EPA recyclable content guidelines, and customs trade flows for molded fiber protective products — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation applied across product type, end user, application, and material furnish chemistry dimensions over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by regional regulatory substitution velocity and automotive program launch cadence. Forecast inputs incorporated natural gas price sensitivity bands and ECHA evaluation cycle timelines for novel bio-based binders.
The model holds under stable EU Green Deal implementation trajectories and sustained automotive lightweighting mandates; deviation in F-Gas Regulation enforcement intensity or REACH compliance acceleration would shift specialty fiber adoption curves. Periodic stress-testing of base assumptions against pulp rheology expertise scarcity and tooling lead time constraints is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Bubble Wrap Packaging Market
Protective Packaging
Secondary Containment Trays Market
Protective Packaging
Asia-Pacific Protective Packaging Market
Protective Packaging
Foam Edge Protectors Market
Protective Packaging
Thermal Insulated Mailers Market
Protective Packaging
Insulated Shippers Market
Protective Packaging
Anti-Static Foam Packaging Market
Protective Packaging
Global Air Cushion Packaging Market
Protective Packaging
Grease Resistant Packaging Market
Protective Packaging
Foam Packaging Inserts Market
Protective Packaging
Global Packaging Inserts and Cushions Market
Protective Packaging
North America Insulated Packaging Market
Protective Packaging
South Africa Protective Packaging Market
Protective Packaging
Padded Dividers Market
Protective Packaging
Inflatable Packaging Market
Protective Packaging
Insulated Styrofoam Shipping Boxes Market