
 Anti-Static Foam Packaging Market | 2026-2036
Anti-Static Foam Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Static Foam Packaging Market Analysis
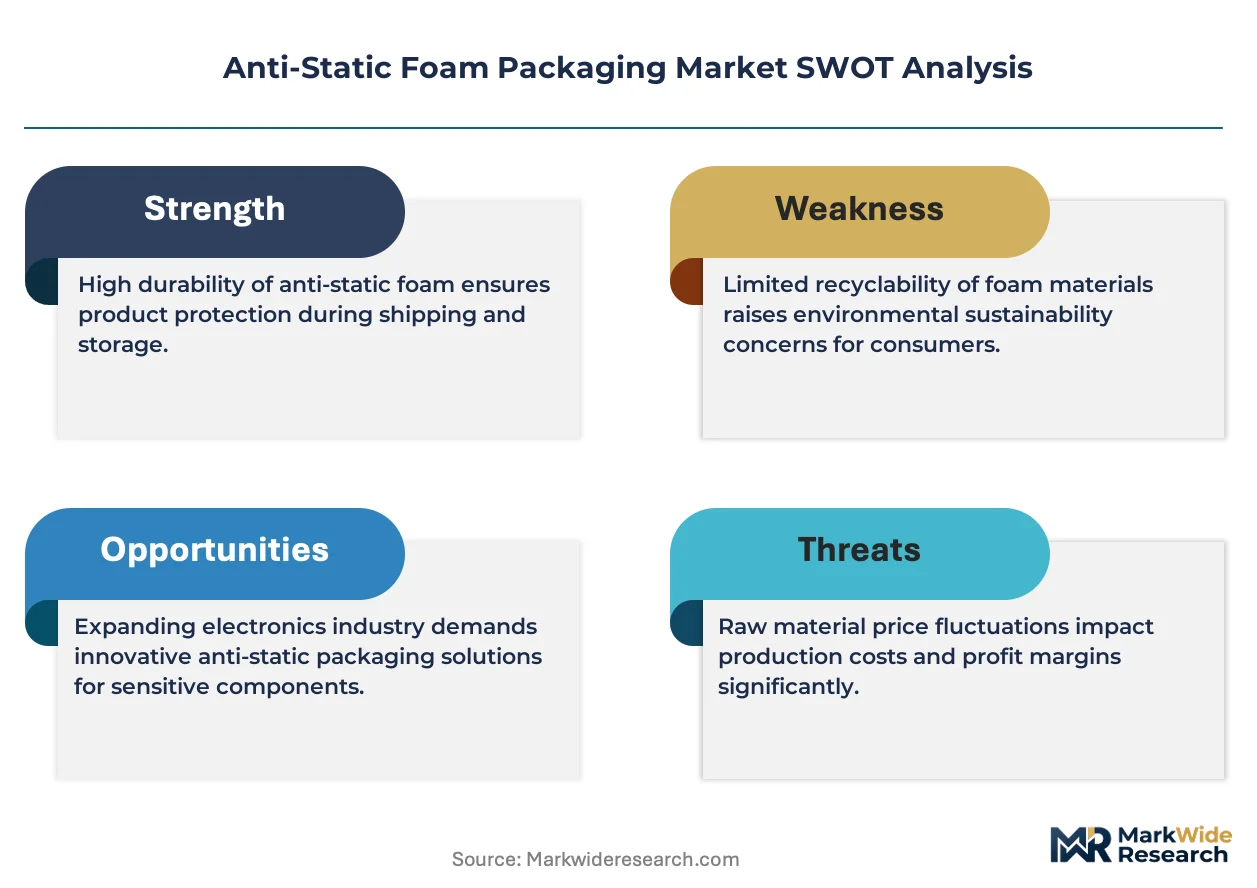
Contract electronics manufacturers are unwinding their historical reliance on generic cushioning suppliers as chip packaging sensitivity thresholds tighten. Sealed Air Corporation leverages its IntelliLoft foam platform to sustain premium positioning in semiconductor tray applications. Pregis LLC anchors North American medical device foam kitting through cleanroom-certified converting operations. Storopack Hans Reichenecker GmbH competes on European automotive just-in-time foam insert programs with localized molding cells.
Anti-static foam packaging denotes cellular polymer structures impregnated with surfactant or carbon-based conductive additives, typically exhibiting surface resistivity between 10^3 and 10^11 ohms per square to dissipate electrostatic discharge without generating triboelectric charge. These materials protect integrated circuits, printed circuit assemblies, and precision electromechanical components from field-induced damage during transit, storage, and handling operations. Polyethylene foam dominates volume shipments for cost-sensitive consumer electronics cushioning, while conductive foam commands margin pools in aerospace parts packaging where MIL-PRF-81705 compliance is mandatory. Custom shapes represent the fastest-growing form category as OEMs specify cavity-matched inserts for robotic pick-and-place compatibility.
FDA device packaging regulations, EPA chemical substance reporting under TSCA Section 8(a), and ISO 9001 quality management standards collectively shape material qualification timelines and converter certification requirements in this market. The EU REACH restriction on per- and polyfluoroalkyl substances is forcing reformulation of traditional antistatic masterbatches ahead of enforcement deadlines. Stakeholders must monitor how semiconductor fabrication node shrinkage below three nanometers alters ESD sensitivity classifications and corresponding foam resistivity specifications.
Market Dynamics
Semiconductor fabrication node shrinkage below three nanometers is tightening ESD sensitivity thresholds and forcing foam resistivity specifications into narrower bands, compressing converter margins while elevating technical qualification barriers.
Growth Catalysts
- REACH PFAS restrictions:EU ECHA enforcement deadlines are accelerating converter migration toward carbon-black and surfactant-based antistatic chemistries, creating first-mover advantages for qualified suppliers.
- Robotic pick-and-place compatibility:Korean memory chip fabs are specifying cavity-matched foam inserts with dimensional tolerances under 0.5mm to enable automated handling.
- Wafer-level packaging expansion:Advanced packaging architectures for AI accelerators are multiplying touchpoints requiring ESD protection per shipped unit.
Market Restraints
- Petrochemical feedstock volatility:Ethylene and propylene price swings directly compress polyethylene foam converter margins with limited pass-through mechanisms.
- Carbon black supply concentration:Conductive additive production clusters in China create single-source dependencies for MIL-PRF-81705 grade foam.
- Reformulation lag:PFAS-free masterbatch development cycles extend 18-24 months, delaying REACH compliance certification.
Strategic Opportunities
- Indian electronics manufacturing:PLI scheme subsidies for semiconductor assembly and testing are creating greenfield demand for cleanroom-certified foam kitting.
- Biodegradable antistatic foams:Starch-polymer blends meeting surface resistivity specifications open medical device disposal compliance pathways.
- Closed-loop takeback programs:OEMs in German automotive are mandating foam insert recycling to satisfy CSRD circularity reporting.
Industry Challenges
- Cleanroom certification timelines:ISO 14644 Class 7 validation for foam converting operations extends 12-16 months, gating medical device supplier qualification.
- Resistivity testing standardization:Inconsistent ANSI/ESD STM11.12 versus IEC 61340-5-1 measurement protocols create cross-border shipment disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Static Foam Packaging Market |
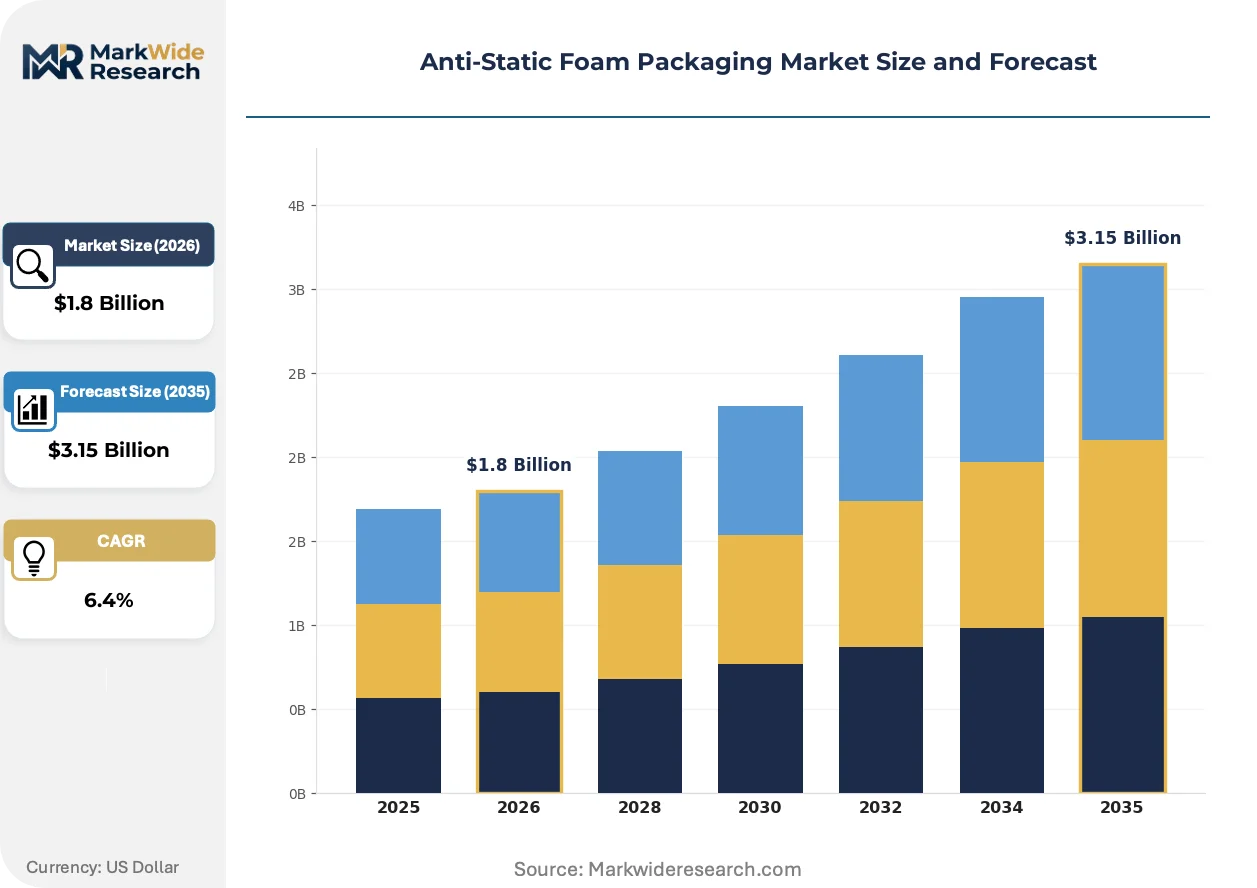
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane Foam, Polyethylene Foam, ESD Foam, Conductive Foam Application: Electronics, Automotive Components, Medical Devices, Aerospace Parts Form: Blocks, Sheets, Custom Shapes, Roll Stock End User: Manufacturers, Retailers, Distributors, OEMs |
| Companies Covered | Sealed Air Corporation, Pregis LLC, Storopack Hans Reichenecker GmbH, UFP Technologies, Inc., GWP Group Limited, BASF SE, DS Smith Plc, Kaneka Corporation, Conductive Containers, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Static Foam Packaging Market Emerging Trajectories
Material science advances and regulatory chemistry bans are converging to reshape antistatic foam formulation roadmaps, with conductivity mechanisms and end-of-life properties now co-equal design priorities.
Carbon nanotube-doped polyethylene foam is displacing traditional surfactant-impregnated grades in aerospace component packaging. Defense contractors adopting MIL-PRF-81705 Revision E are specifying CNT-enhanced materials for humidity-independent resistivity performance. This displacement is compressing demand for carbon-black loaded foams in premium segments while elevating raw material costs.
ECHA REACH restrictions on per- and polyfluoroalkyl substances are forcing masterbatch reformulations ahead of 2025 enforcement windows. European converters are qualifying glycerol ester and quaternary ammonium salt alternatives with 10^6-10^9 ohm surface resistivity targets. Medical device foam kitters in Germany and France face compressed qualification timelines to maintain MDR technical documentation compliance.
Contract electronics manufacturers are consolidating supplier panels around vertically integrated foam converters with in-house molding and cleanroom slitting capabilities. Foxconn and Pegatron procurement teams are awarding multi-year agreements to qualified partners, displacing fragmented regional cushioning suppliers. This concentration is most visible in South Korean memory chip fabrication zones where Samsung and SK Hynix logistics teams enforce single-source foam strategies.
Anti-Static Foam Packaging Market Segmentation
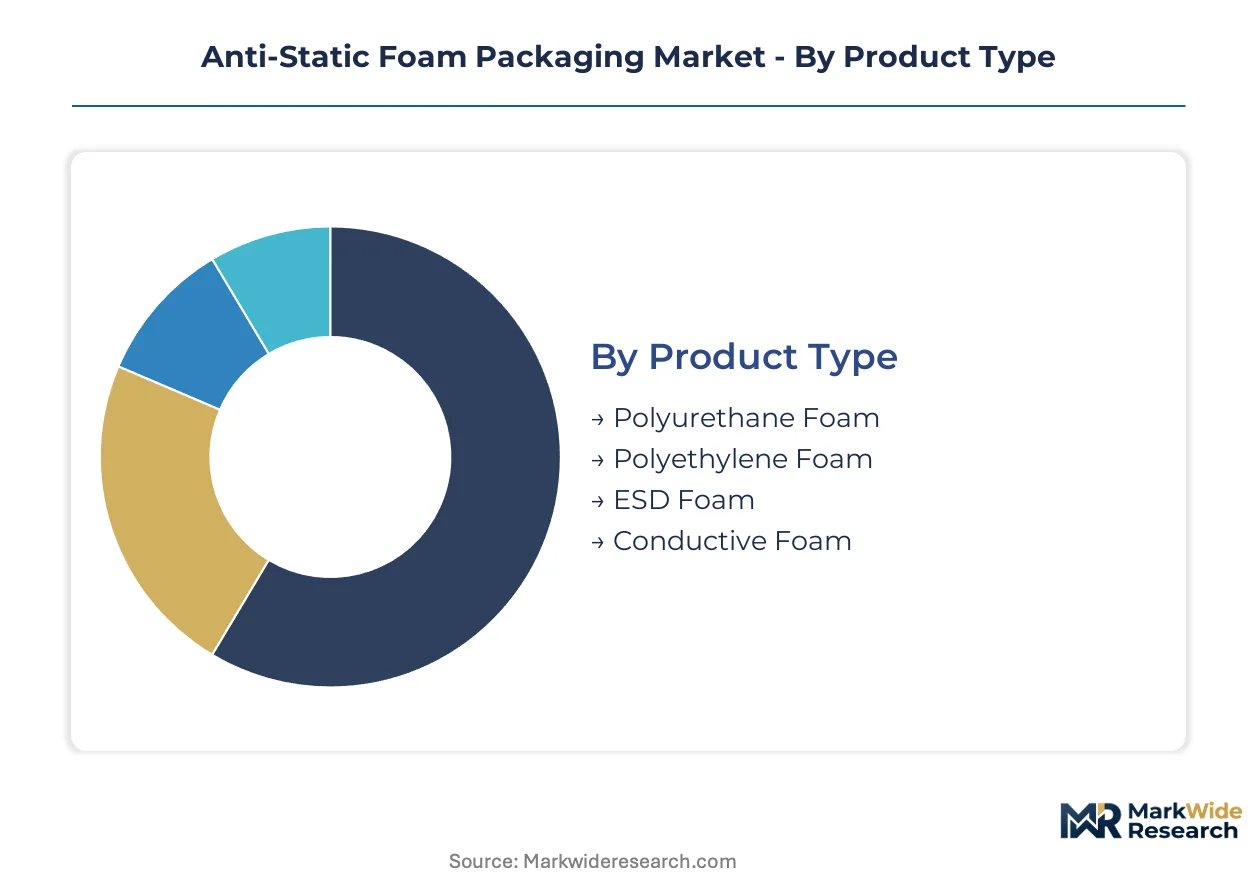
Segmentation in anti-static foam packaging separates commodity polyethylene cushioning from precision-engineered conductive grades where MIL-PRF-81705 compliance commands substantial premiums. Each dimension—material chemistry, end-use sensitivity, form factor, and buyer type—creates distinct margin architectures and qualification barriers that shape converter strategy.
Product Type:
Margin pools concentrate in conductive and ESD-specific formulations where aerospace and semiconductor certifications limit supplier entry, while commodity polyethylene competes on resin pass-through economics.
- Polyethylene Foam:Low-density closed-cell structure dominates consumer electronics cushioning for smartphones, tablets, and peripheral accessories. Samsung and Foxconn procurement teams specify this grade for cost-sensitive tray applications across Vietnamese and Indian assembly plants.
- Conductive Foam:Carbon-black or carbon nanotube loaded polymers deliver humidity-independent surface resistivity for MIL-PRF-81705 Revision E compliance. Defense contractors and aerospace tier-1 suppliers in the US and France mandate this grade for satellite component and avionics module packaging where field failure costs exceed material expense by orders of magnitude.
- ESD Foam:Surfactant-impregnated open-cell polyurethane achieves 10^6-10^9 ohm resistivity for controlled discharge in cleanroom environments. South Korean memory chip fabs specify cavity-matched ESD inserts with sub-0.5mm dimensional tolerances for robotic handling compatibility.
- Polyurethane Foam:Higher compression set resistance suits reusable dunnage and returnable packaging loops in German automotive just-in-time supply chains.
The dominant share belongs to Polyethylene Foam, while Conductive Foam is closing the gap fastest as aerospace procurement specifications tighten.
Application:
Application segmentation tracks directly to regulatory burden and sensitivity classification, with medical and aerospace segments carrying multi-year qualification timelines that protect incumbent positions.
- Electronics:Contract manufacturers for memory chips, AI accelerators, and mobile devices drive volume demand. Wafer-level packaging architectures multiply ESD touchpoints per shipped unit, expanding foam insert counts from single trays to multi-cavity kits.
- Aerospace Parts:AS9100 and MIL-PRF-81705 compliance requirements restrict supplier panels to converters with dedicated aerospace cleanrooms and lot traceability systems. Boeing and Airbus tier-2 logistics teams in the US and France source exclusively from qualified foam molders.
- Medical Devices:FDA 21 CFR Part 820 and EU MDR technical documentation requirements extend foam kitting qualification to 18-24 months. German and Swiss device manufacturers specify cleanroom-converted foam with ISO 14644 Class 7 certification.
- Automotive Components:Sensor modules and ECU packaging for electric powertrains require antistatic protection through assembly plant logistics loops. European OEMs mandate CSRD-aligned recycling takeback for foam inserts.
Electronics commands the largest volume position, though Aerospace Parts exhibits the steepest expansion trajectory as satellite constellation deployments accelerate.
Form:
Form factor selection determines converter capital intensity, with custom molding cells requiring six-figure tooling investments that fragment supply for precision applications.
- Custom Shapes:Cavity-matched inserts engineered for robotic pick-and-place compatibility represent the most technically demanding segment. Korean memory fabs specify these for automated wafer handling with dimensional tolerances under 0.5mm.
- Sheets:Flat stock for die-cutting and laminating serves high-volume electronics cushioning where converters compete on slitting speed and thickness consistency.
- Blocks:Bun stock for fabrication into specialized shapes supports low-volume aerospace and medical prototyping where tooling amortization is prohibitive.
- Roll Stock:Continuous foam for automated packaging lines in consumer electronics fulfillment centers, particularly in US and Chinese e-commerce logistics hubs.
Sheets retain the broadest installed base, yet Custom Shapes is gaining share fastest as OEM automation requirements proliferate.
End User:
End user type segments procurement behavior, with OEM direct specifications increasingly displacing distributor influence in semiconductor and aerospace supply chains.
- OEMs:Samsung, SK Hynix, and Apple logistics teams enforce single-source foam strategies with multi-year agreements, consolidating supply around vertically integrated converters with in-house molding and cleanroom capabilities.
- Manufacturers:Contract electronics manufacturers including Foxconn and Pegatron manage foam procurement through centralized commodity desks for standard cushioning grades.
- Distributors:Independent distributors serve fragmented regional demand for standard sheet and block formats, particularly in Southeast Asian electronics assembly corridors.
- Retailers:Limited direct procurement, primarily for aftermarket electronics accessories packaging where antistatic specifications are minimal.
OEMs control specification authority for premium grades, while Manufacturers capture volume leadership in standard polyethylene applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese foam converters export precision-molded ESD inserts to South Korean memory fabrication zones, while German automotive suppliers ship PFAS-free masterbatch formulations to French medical device kitters under REACH compliance timelines.
United States
Defense contractors and aerospace tier-1 suppliers drive MIL-PRF-81705 grade foam demand for satellite component packaging. FDA 21 CFR Part 820 and EPA TSCA Section 8(a) reporting shape medical device foam qualification. Boeing logistics teams in Seattle and Airbus suppliers in Mobile, Alabama source exclusively from AS9100-certified converters with dedicated cleanrooms.
Germany
Automotive OEMs mandate CSRD-aligned circularity reporting for foam insert recycling through just-in-time supply chains. ECHA REACH PFAS restrictions force glycerol ester and quaternary ammonium salt masterbatch reformulations ahead of enforcement windows. Stuttgart and Munich industrial corridors host vertically integrated converters serving Bosch and Siemens ECU packaging programs.
South Korea
Samsung and SK Hynix logistics teams enforce single-source foam strategies with cavity-matched inserts for robotic wafer handling. MFDS medical device regulations extend qualification timelines for cleanroom-certified kitting. Pyeongtaek and Icheon memory fabrication zones concentrate demand for sub-0.5mm dimensional tolerance foam molding.
China
Carbon black additive production clusters create single-source dependencies for conductive foam grades serving export markets. MIIT industrial standards and dual carbon goals pressure converters toward lower-emission manufacturing. Suzhou and Shenzhen electronics assembly corridors supply Foxconn and Pegatron with high-volume polyethylene cushioning for smartphone tray applications.
India
PLI scheme subsidies for semiconductor assembly and testing generate greenfield demand for cleanroom-certified foam kitting infrastructure. BIS quality standards and CDSCO medical device regulations shape import substitution strategies. Gujarat and Karnataka electronics manufacturing clusters attract first-mover converters qualifying under accelerated procurement timelines.
Anti-Static Foam Packaging Market Vendor Landscape
Player mix skews toward vertically integrated material-science conglomerates and specialized regional converters. Market structure concentrates around three tiers: multinational foam specialists with cleanroom molding networks, petrochemical-backed resin compounders, and independent fabricators serving fragmented regional demand. Strategic moves center on PFAS-free masterbatch qualification racing and robotic-handling cavity-matching capabilities.
Within the multinational specialist tier, Sealed Air Corporation and Pregis LLC occupy positions anchored by in-house molding and cleanroom slitting infrastructure. Storopack Hans Reichenecker GmbH exemplifies the European automotive-focused archetype with localized just-in-time molding cells. These three entities represent the dominant competitive anchors against which regional fabricators qualify for OEM panel inclusion.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Pregis LLC |
| Storopack Hans Reichenecker GmbH |
| UFP Technologies, Inc. |
| GWP Group Limited |
| BASF SE |
| DS Smith Plc |
| Kaneka Corporation |
| Conductive Containers, Inc. |
| Others |
Supply Flow & Price Mechanics
Multi-year capacity reservation agreements with Korean memory fabs lock in both conductive foam supply access and price visibility through the analysis window, insulating qualified converters from ethylene spot volatility while freezing out speculative entrants.
Pricing Analysis
Current-generation carbon nanotube-doped polyethylene foam commands substantial premiums over prior-generation carbon-black loaded grades, while next-generation PFAS-free surfactant formulations face compressed qualification timelines that delay price discovery. Three-tier pricing structure across MIL-PRF-81705 certified aerospace grades, cleanroom-converted medical device kitting, and commodity consumer electronics cushioning reflects certification burden and volume scale differentiation. Pricing pressure stems from REACH compliance-driven masterbatch reformulation costs that converters struggle to pass through to cost-sensitive contract manufacturers. Consumer electronics procurement teams at Foxconn and Pegatron exhibit highest price sensitivity, while defense contractors absorbing satellite component packaging costs show least elasticity.
Supply Chain Analysis
Inventory buffers for carbon black conductive additives have compressed to eight-week coverage as Chinese production clusters face export license scrutiny, extending lead times for MIL-PRF-81705 grade foam molders in the United States and France. Raw material sourcing draws from Saudi ethylene crackers, Chinese carbon black manufacturing zones, and German glycerol ester surfactant compounders. Single-source vulnerability concentrates in carbon nanotube feedstock where qualified suppliers number fewer than five globally. Distribution runs through vertically integrated converter networks with captive molding and cleanroom slitting capabilities, displacing fragmented regional fabricators from OEM panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across certification tiers, regional regulatory clusters, and automation-readiness levels creates multiple niche entry points as semiconductor packaging sensitivity thresholds proliferate specification complexity.
For Market Incumbents: Compound cleanroom certification advantages by accelerating PFAS-free masterbatch qualification ahead of ECHA enforcement windows, while adding captive carbon nanotube compounding capacity to hedge against conductive additive supply concentration. Threat from vertically integrated Korean foam converters with robotic-handling cavity-matching capabilities demands preemptive capacity expansion in Pyeongtaek-adjacent molding cells. For New Entrants and Emerging Players: Anchor in Indian PLI-subsidized semiconductor assembly corridors where cleanroom-certified foam kitting infrastructure remains underdeveloped and BIS quality standards create qualification barriers favoring first-mover investment. Medical device foam kitting for CDSCO-regulated manufacturers represents the most penetrable segment given compressed domestic supply. Go-to-market through joint qualification programs with Gujarat-based electronics manufacturing cluster developers accelerates OEM panel inclusion. For Investors and Strategic Acquirers: Specialized European automotive foam converters with CSRD-aligned circularity capabilities and localized just-in-time molding cells offer acquisition exposure to regulatory-driven supplier consolidation. Long-term viability hinges on REACH chemistry compliance and robotic-handling dimensional precision as dual moats. Signal to monitor: Samsung and SK Hynix procurement team announcements on single-source foam strategy expansion or dual-sourcing pilot programs.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Masterbatch Qualification | ECHA REACH compliance deadlines force chemistry reformulation racing among European converters. |
| Robotic Handling Cavity Matching | Korean memory fabs specify sub-0.5mm tolerance inserts for automated wafer processing. |
| Cleanroom Certification Investment | ISO 14644 Class 7 validation gates medical device supplier qualification for 18-24 months. |
| Carbon Nanotube Compounding Capacity | Humidity-independent resistivity performance displaces carbon-black grades in aerospace procurement. |
| Closed-Loop Takeback Programs | German automotive OEMs mandate CSRD-aligned foam insert recycling for circularity reporting. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, with foam converting plant managers, semiconductor logistics procurement leads, medical device packaging engineers, and aerospace tier-1 supplier quality directors providing operational validation. Secondary sources included customs trade data for ethylene and propylene derivatives, ECHA REACH substance restriction timelines, SEC 10-K filings from multinational packaging conglomerates, and ISO certification registry databases. Bottom-up shipment estimates from individual converter facilities were triangulated against top-down petrochemical feedstock consumption models.
Across the analysis window, the forecast framework models volume and value trajectories through segmentation by material chemistry tier, end-use sensitivity classification, form factor capital intensity, and buyer procurement archetype. CAGRs were derived from regression analysis against semiconductor fabrication capacity expansion schedules and wafer-level packaging adoption curves. Industry-specific inputs incorporated carbon black price elasticity coefficients and cleanroom certification lag distributions.
Decision-makers should treat outputs as directional under assumptions of sustained semiconductor node shrinkage and REACH enforcement adherence; material deviation in PFAS substitution timelines or carbon nanotube supply availability would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Padded Dividers Market
Protective Packaging
Latin America Protective Packaging Market
Protective Packaging
Paper Cushion Systems Market
Protective Packaging
Padded Mailers Market
Protective Packaging
Thermal Insulated Bubble Wrap Market
Protective Packaging
Middle East and Africa Protective Packaging Market
Protective Packaging
Global Air Cushion Packaging Market
Protective Packaging
Grease Resistant Packaging Market
Protective Packaging
Insulated Packaging Market
Protective Packaging
Foam Mesh Sleeves Market
Protective Packaging
Europe Protective Packaging Market
Protective Packaging
Foam Protective Packaging Market
Protective Packaging
South Africa Protective Packaging Market
Protective Packaging
Insulated Styrofoam Shipping Boxes Market
Protective Packaging
Void Fill Pillows Market
Protective Packaging
Bubble Wrap Packaging Market