
 North America Insulated Packaging Market | 2026-2036
North America Insulated Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Insulated Packaging Market Intelligence
Asset-light leasing models for temperature-controlled fleet infrastructure are reshaping competitive entry barriers in insulated packaging. Sealed Air Corporation leverages its film and foam technology portfolio to sustain R&D intensity across multi-layer barrier systems. Sonoco Products Company anchors its position through geographic dominance in molded fiber and temperature-assurance solutions across the US Southeast and Midwest.
Insulated packaging comprises engineered thermal barriers—typically incorporating expanded polystyrene, polyurethane foam, or reflective aluminum foil layers with R-values ranging from 3.5 to 7.0 per inch—designed to maintain specified temperature ranges for 24–96 hours in passive distribution environments. Its primary commercial purpose centers on protecting temperature-sensitive payloads during last-mile and mid-haul logistics where mechanical refrigeration is unavailable or cost-prohibitive. Foam containers dominate pharmaceutical transport applications where payload integrity demands rigid dimensional stability and extended thermal duration. Thermal wraps represent the fastest-expanding product category as food delivery platforms prioritize lightweight, collapsible formats that reduce reverse logistics costs.
The US FDA enforces strict cold-chain documentation requirements for pharmaceutical distribution under current Good Distribution Practice guidelines, directly elevating demand for validated insulated packaging with integrated temperature monitoring. EPA regulations on expanded polystyrene recycling and state-level extended producer responsibility laws in California and New York constrain material choices while accelerating molded pulp and curbside-recyclable alternatives. Health Canada and PMRA maintain parallel cold-chain standards that Canadian cross-border suppliers must satisfy. Stakeholders should monitor evolving state recycling mandates and biopharma serialization requirements as these will determine which material platforms and validation protocols capture preferential procurement positions.
Market Dynamics
Extended producer responsibility frameworks are forcing material platform transitions across the North America insulated packaging value chain, compressing design cycles and elevating compliance costs for converters serving pharmaceutical and food delivery end-uses.
Growth Catalysts
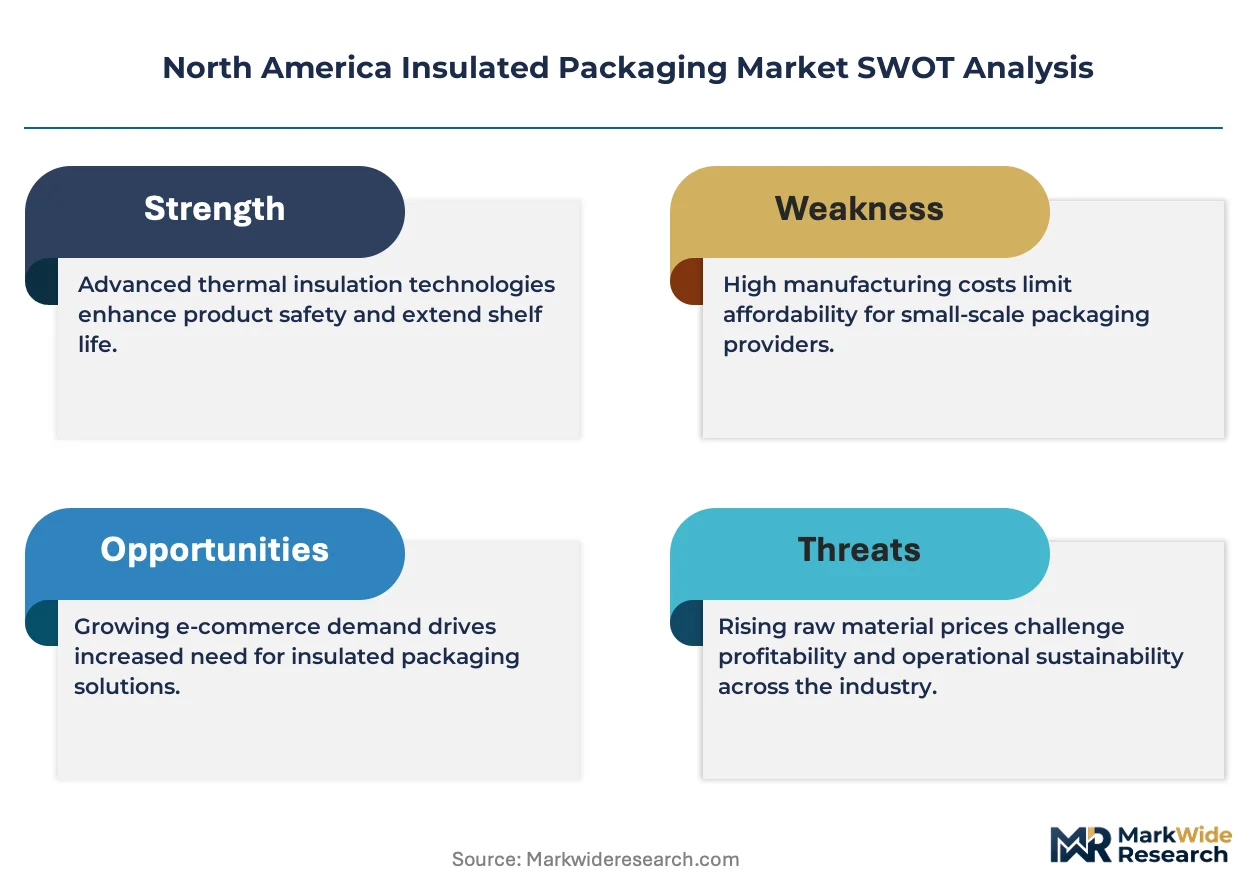
- Biopharma cold-chain expansion:Cell and gene therapy logistics require validated thermal duration beyond 72 hours, pulling multi-layer barrier systems into oncology distribution networks from Boston to San Diego.
- California SB 54 mandates:The state's plastic pollution reduction law accelerates curbside-recyclable molded pulp adoption, creating procurement preference for fiber-based alternatives in meal-kit fulfillment.
- Last-mile food delivery density:Urban cluster concentration in the US Northeast corridor generates route-specific thermal wrap demand that collapses reverse logistics costs for platform operators.
Market Restraints
- Polystyrene feedstock volatility:Benzene price swings compress converter margins on expanded polystyrene foam containers, the dominant pharmaceutical payload format.
- Canadian cross-border compliance:Health Canada and PMRA cold-chain documentation requirements impose dual validation burdens on US suppliers serving Toronto and Vancouver biotech clusters.
- Mechanical refrigeration substitution:Active temperature-controlled fleet expansion in the US Southeast threatens passive insulated packaging demand for mid-haul pharmaceutical routes.
Strategic Opportunities
- Mexico pharmaceutical manufacturing:Nearshoring of biologics fill-finish operations to Baja California and Querétaro creates demand for validated cold-chain packaging at the US-Mexico border.
- Refrigerated e-grocery penetration:Temperature-assurance solutions for frozen protein home delivery remain underdeveloped in Canadian metropolitan markets outside Toronto.
- US EPA recycling infrastructure grants:Federal funding for expanded polystyrene densification equipment creates co-investment pathways for converter networks in the Midwest.
Industry Challenges
- Thermal validation engineering scarcity:Qualified ISTA 7E protocol technicians are concentrated in legacy pharmaceutical packaging hubs, constraining regional converter expansion.
- Multi-material separation complexity:Laminated foil-foam-film constructions complicate mechanical recycling streams, requiring redesign for California and New York extended producer responsibility compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Insulated Packaging Market |
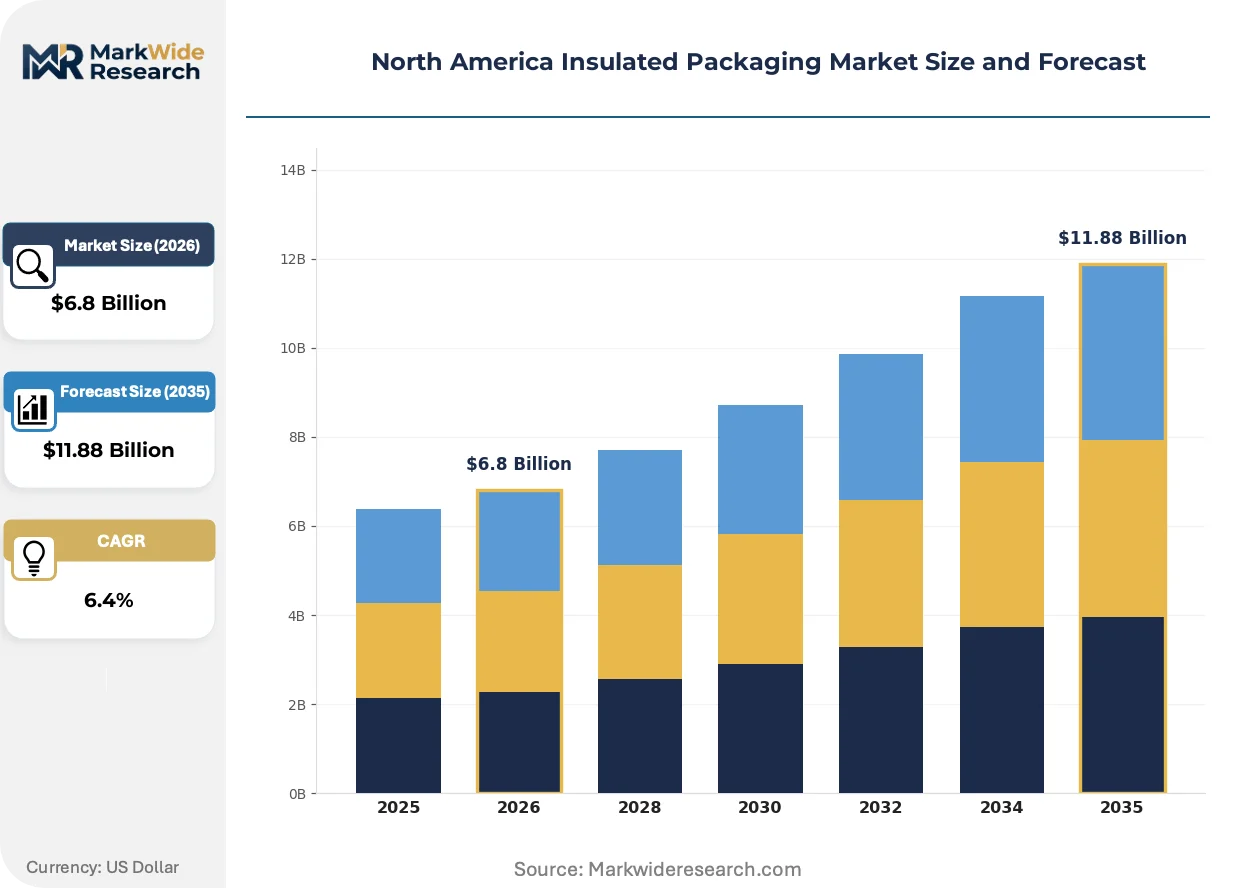
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Containers, Thermal Wraps, Refrigerated Boxes, Insulated Bags, Gel Packs Application: Food Delivery, Pharmaceutical Transport, Electronics Shipping, Chemical Storage, Floral Preservation End User: Catering Services, Biotech Firms, Electronic Manufacturers, Chemical Suppliers, Florists Packaging Material: Expanded Polystyrene, Polyurethane Foam, Aluminum Foil, Bubble Wrap, Molded Pulp |
| Companies Covered | Sealed Air Corporation, Sonoco Products Company, Packaging Corporation of America, Cold Chain Technologies, Temperpack Technologies Inc., Smurfit Kappa Group, Insulated Products Corp., Graphic Packaging International, Inc., Huhtamaki Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Insulated Packaging Market Strategic Shifts & Innovations
Material science convergence and regulatory stringency are compressing product lifecycles across the North America insulated packaging market, favoring platforms that reconcile thermal performance with end-of-life recoverability.
Phase-change material formulations are migrating from hydrated salt solutions to bio-based paraffin and fatty acid ester blends. Biopharma 3PL providers in the US Northeast are piloting these materials for cell therapy shipments requiring tighter temperature bands. The shift is migrating from niche oncology applications toward standard infectious vaccine distribution, displacing conventional gel packs in validated cold-chain protocols.
The US EPA's National Recycling Strategy and state-level extended producer responsibility laws in California, New York, and Maine are constraining expanded polystyrene deployment. Converter networks must now certify curbside recyclability or organized collection pathways for thermal wraps and molded containers. Food delivery platforms operating across these jurisdictions are accelerating fiber-based format adoption to preempt compliance penalties.
Asset-light temperature-controlled fleet leasing is restructuring procurement relationships between insulated packaging suppliers and logistics operators. Pharmaceutical distributors in the US Midwest are unbundling packaging procurement from transportation contracts, creating direct supplier relationships with thermal solution providers. This disintermediation is most visible in Chicago and Detroit, where 3PL consolidation has concentrated buying power among fewer fleet operators seeking modular, route-agnostic thermal systems.
North America Insulated Packaging Market Segmentation
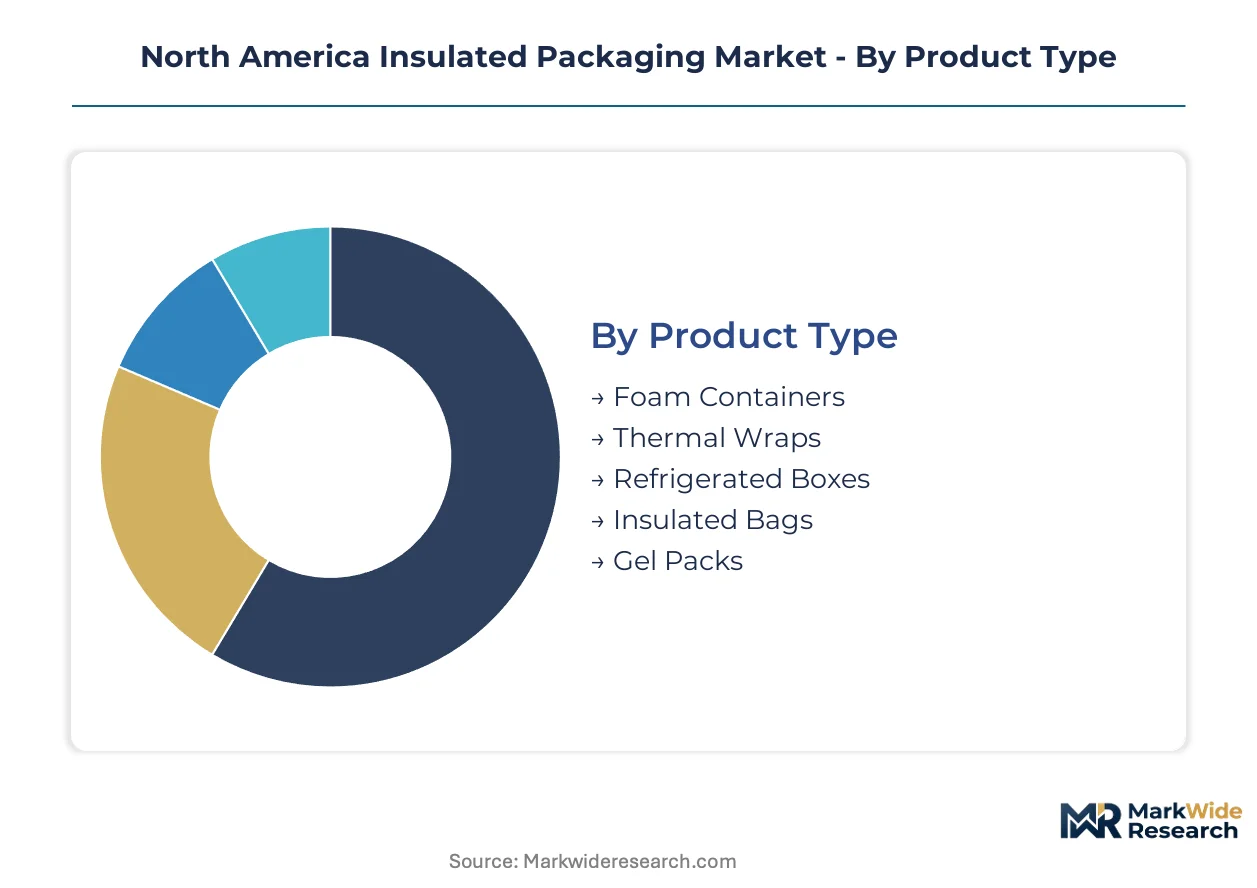
Segmentation in insulated packaging reveals divergent service intensity requirements across temperature-sensitive supply chains. Pharmaceutical transport demands rigorous thermal validation protocols and extended after-sales documentation, while food delivery platforms prioritize rapid replenishment cycles with minimal technical support overhead.
Product Type:
After-sales service intensity varies dramatically across product formats, with pharmaceutical-grade foam containers requiring ISTA protocol recertification and field engineering support that collapsible thermal wraps simply do not demand.
- Foam Containers:Rigid expanded polystyrene or polyurethane constructions with R-values of 5.0-7.0 per inch provide dimensional stability for 72-96 hour thermal duration. Demand concentrates in the US Northeast corridor from Boston to Philadelphia, where biotech firms expanding cell therapy logistics pull multi-layer barrier systems into oncology distribution networks.
- Thermal Wraps:Lightweight, collapsible aluminum foil-bubble laminate formats reduce reverse logistics costs through compact return volume. Food delivery platforms in urban Northeast clusters generate route-specific demand as operators prioritize payload flexibility over extended duration.
- Refrigerated Boxes:Active-mechanical or passive-phase-change hybrid systems for frozen protein distribution.
- Insulated Bags:Flexible quilted formats for short-duration meal-kit and grocery delivery applications.
- Gel Packs:Hydrated salt or bio-based paraffin phase-change media for supplemental thermal mass.
By volume, foam containers lead. By growth pace, thermal wraps are expanding most quickly.
Application:
Cost tier stratification separates premium-validated pharmaceutical segments from commodity food delivery procurement, with electronics and chemical applications occupying intermediate positions on both specification and service intensity.
- Pharmaceutical Transport:FDA-enforced cold-chain documentation under current Good Distribution Practice guidelines elevates demand for validated packaging with integrated temperature monitoring. The US Northeast and San Diego biotech corridors drive adoption as cell and gene therapy logistics require thermal duration beyond 72 hours.
- Food Delivery:Last-mile platform density in urban Northeast clusters generates collapsible format demand that prioritizes reverse logistics economics over extended thermal performance. California SB 54 mandates accelerate curbside-recyclable molded pulp adoption in meal-kit fulfillment.
- Electronics Shipping:Temperature-sensitive semiconductor and battery components requiring moderate thermal protection.
- Chemical Storage:Industrial reagents and specialty coatings with narrow temperature stability windows.
- Floral Preservation:Seasonal peak demand for temperature-controlled cut flower distribution.
Pharmaceutical transport commands premium pricing tiers. Food delivery is climbing the fastest on volume expansion.
End User:
Customer type determines procurement centralization, with biotech firms consolidating buying power through 3PL relationships while catering services and florists fragment across regional distributor networks.
- Biotech Firms:Centralized procurement of validated cold-chain packaging through dedicated quality assurance departments with direct supplier relationships. FDA serialization requirements and Health Canada cross-border documentation impose dual validation burdens on packaging selections.
- Catering Services:Decentralized purchasing through foodservice distributors with limited technical specification involvement.
- Electronic Manufacturers:Semiconductor and battery producers with moderate thermal protection requirements.
- Chemical Suppliers:Industrial distributors serving temperature-sensitive reagent markets.
- Florists:Seasonal, price-sensitive procurement through wholesale floral supply channels.
Biotech firms concentrate specification authority. Catering services represent the broadest addressable base.
Packaging Material:
Supply concentration in polystyrene feedstock chains creates margin volatility that converters must navigate through material platform diversification toward fiber-based alternatives.
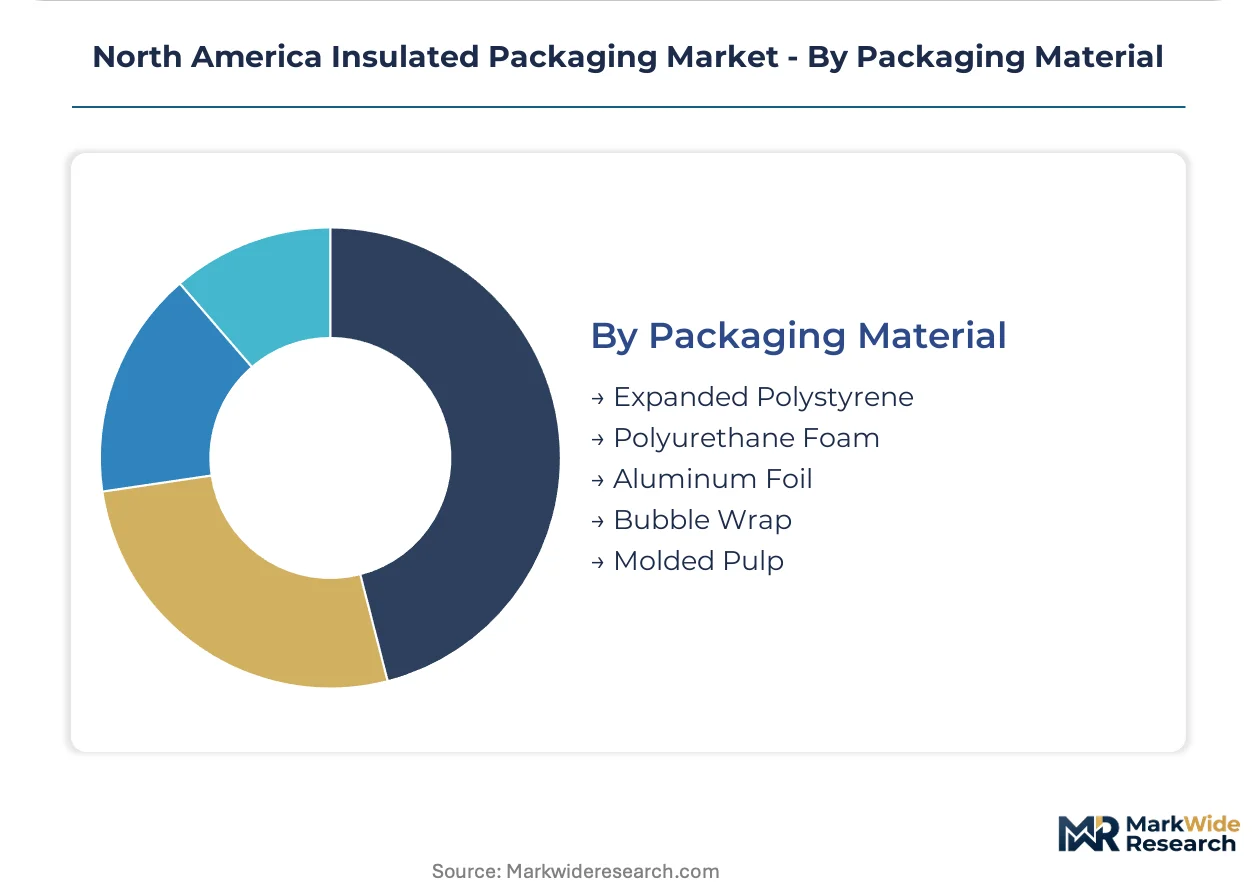
- Expanded Polystyrene:Dominant pharmaceutical payload format with established molding infrastructure and lowest unit cost for high-volume production. Benzene price swings compress converter margins, while EPA recycling infrastructure constraints and California extended producer responsibility laws accelerate displacement.
- Molded Pulp:Curbside-recyclable fiber formats gaining procurement preference as food delivery platforms preempt California, New York, and Maine compliance penalties. US EPA recycling infrastructure grants for densification equipment create co-investment pathways in the Midwest.
- Polyurethane Foam:Higher R-value alternative for extended-duration pharmaceutical applications.
- Aluminum Foil:Reflective barrier layers in multi-laminate thermal wrap constructions.
- Bubble Wrap:Air-entrapment insulation for lightweight, collapsible formats.
Expanded polystyrene retains volume leadership. Molded pulp is gaining share fastest on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biotech procurement departments and food delivery platform operators concentrate buying power across distinct North American corridors, with pharmaceutical validation requirements and state recycling mandates reshaping supplier relationships in each jurisdiction.
United States
The FDA enforces current Good Distribution Practice documentation for pharmaceutical cold chains, while California SB 54 and New York extended producer responsibility laws accelerate molded pulp adoption. The Boston-to-Philadelphia corridor anchors cell therapy logistics demand, pulling multi-layer barrier systems into oncology distribution networks.
Canada
Health Canada and PMRA maintain parallel cold-chain standards that US suppliers must satisfy for Toronto and Vancouver biotech clusters. Cross-border compliance imposes dual validation burdens on packaging selections serving Canadian metropolitan markets outside Toronto where refrigerated e-grocery penetration remains underdeveloped.
Mexico
Nearshoring of biologics fill-finish operations to Baja California and Querétaro creates validated cold-chain packaging demand at the US-Mexico border. Federal environmental regulations and state-level industrial incentives shape material platform choices for converters establishing cross-border supply relationships.
North America Insulated Packaging Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered procurement relationships. The market structure consolidates around three strategic archetypes: diversified packaging conglomerates with film and foam technology portfolios, molded fiber specialists with geographic density in the US Southeast and Midwest, and temperature-assurance pure-plays serving pharmaceutical validation requirements. Competitive moves center on portfolio diversification toward curbside-recyclable formats and strategic partnerships with asset-light temperature-controlled fleet operators.
Among diversified packaging conglomerates, Sealed Air Corporation and Sonoco Products Company exemplify contrasting geographic and technology positioning. Sealed Air represents the multi-layer barrier systems archetype with sustained R&D intensity across film and foam portfolios. Sonoco anchors molded fiber and temperature-assurance solutions across the US Southeast and Midwest. Cold Chain Technologies occupies the pharmaceutical pure-play position, sitting within the validated cold-chain segment where FDA documentation requirements and ISTA protocol certification create specialized competitive moats.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Sonoco Products Company |
| Packaging Corporation of America |
| Cold Chain Technologies |
| Temperpack Technologies Inc. |
| Smurfit Kappa Group |
| Insulated Products Corp. |
| Graphic Packaging International, Inc. |
| Huhtamaki Group |
| Others |
Cost & Logistics Intelligence
Benzene feedstock concentration in the US Gulf Coast petrochemical corridor anchors margin volatility for expanded polystyrene converters, pushing downstream value capture toward pharmaceutical-grade validation services and away from commodity foam production.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and food-delivery packaging tiers. FDA-validated cold-chain formats with ISTA 7E protocol documentation command premium positioning against unvalidated thermal wraps. Cost compression in commodity foam containers intensifies because benzene price swings erode converter margins. Food delivery platforms exhibit highest price sensitivity, while biotech procurement departments prioritize thermal validation reliability over unit cost.
Supply Chain Analysis
Upstream benzene and styrene monomer production concentrates in the US Gulf Coast, with Canadian chemical complexes and Mexican petrochemical facilities providing secondary supply nodes. Converter networks draw from expanded polystyrene resin, polyurethane foam precursors, and aluminum foil laminate stocks. Single-source vulnerability runs through Gulf Coast benzene crackers exposed to hurricane disruption. Distribution feeds through pharmaceutical 3PL consolidators in the US Northeast corridor and foodservice distributors serving urban delivery clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell and gene therapy logistics disruption is accelerating validated packaging demand faster than converter capacity expansion, creating a high-growth window where regulatory compliance investments compound competitive separation.
For Market Incumbents: Build validation protocol moats through ISTA 7E certification density in the Boston-Philadelphia corridor. Secure captive supply of bio-based phase-change materials to preempt gel pack displacement. Anchor capacity expansion in Midwest converter networks accessing EPA recycling infrastructure grants. Threatened position: commodity foam producers facing California SB 54 compliance penalties. For New Entrants and Emerging Players: Canadian metropolitan markets outside Toronto present underpenetrated refrigerated e-grocery territory with limited incumbent validation infrastructure. Mexico's Baja California and Querétaro biologics nearshoring clusters offer white-space demand for cross-border cold-chain packaging. Pursue direct relationships with asset-light temperature-controlled fleet operators disintermediating traditional 3PL procurement channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed pharmaceutical packaging pure-plays holding FDA documentation capabilities but limited fiber-based format portfolios. Long-term viability centers on material platform diversification toward curbside-recyclable alternatives. Signal to monitor: California and New York extended producer responsibility enforcement timelines as inflection indicators for molded pulp adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Curbside-Recyclable Material Transition | California SB 54 compliance preempts penalty exposure for meal-kit fulfillment operators. |
| Phase-Change Material Formulation Shift | Bio-based paraffin blends displace hydrated salt solutions in cell therapy distribution. |
| Validation Protocol Certification Investment | ISTA 7E technician scarcity creates regional moats around Boston and Philadelphia hubs. |
| Asset-Light Fleet Partnership Structuring | Direct supplier relationships with Chicago and Detroit 3PL consolidators bypass distributor margins. |
| Cross-Border Compliance Infrastructure | Health Canada and PMRA dual validation capabilities capture Toronto and Vancouver biotech procurement. |
Research Approach
A spread of perspectives from pharmaceutical quality assurance directors, cold-chain logistics engineers, food delivery platform procurement leads, and molded fiber converter plant managers converged on the working assumptions. Primary interviews combined with secondary validation against FDA guidance documents, EPA National Recycling Strategy filings, California SB 54 regulatory texts, and Health Canada cold-chain standards. Customs data on expanded polystyrene resin imports and pharmaceutical 3PL contract disclosures provided volume anchors. Bottom-up product format demand modeling triangulated against top-down regional biotech cluster expansion projections.
Demand-supply balance dynamics shaped the analytical framework across the analysis window, with segmentation dimensions spanning product type, application, end user, and packaging material grade. Treatment temperature band, thermal duration requirement, and regional regulatory cluster density provided pharmaceutical-specific modeling inputs. CAGRs derived from historical volume trajectories adjusted for regulatory inflection points and material substitution elasticities.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Gulf Coast petrochemical producers or rapid phase-change material patent licensing would shift outcomes. Cross-checking against EPA recycling infrastructure grant disbursement rates and biotech 3PL contract renewal frequencies is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Anti-Corrosive Packaging Market
Protective Packaging
Static Shielding Bags Market
Protective Packaging
Corrugated Bubble Wrap Market
Protective Packaging
Foam Packaging Inserts Market
Protective Packaging
Grease Resistant Packaging Market
Protective Packaging
Packaging and Protective Packaging Market
Protective Packaging
Adhesive Bubble Wrap Market
Protective Packaging
Middle East and Africa Protective Packaging Market
Protective Packaging
Padded Mailers Market
Protective Packaging
Foam Protective Packaging Market
Protective Packaging
Bubble Wrap Packaging Market
Protective Packaging
Global Packaging Inserts and Cushions Market
Protective Packaging
North America Protective Packaging Market
Protective Packaging
Protective Wrapping Paper Market
Protective Packaging
Insulated Shipping Boxes Market
Protective Packaging
Thermal Insulated Mailers Market