
 Europe Molded Fiber Pulp Packaging Market | 2026-2036
Europe Molded Fiber Pulp Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Molded Fiber Pulp Packaging Market Foresight
Advanced pulp refining and precision thermoforming is reconfiguring how protective packaging achieves dimensional accuracy at scale. Huhtamaki leverages its pan-European thermoforming infrastructure to supply food-grade fiber trays with consistent wall thickness. Stora Enso anchors the upstream supply chain through its integrated Nordic pulp and board operations. Brødrene Hartmann specializes in molded fiber egg packaging and extends this expertise into industrial protective applications.
Europe molded fiber pulp packaging consists of cellulose fiber slurries formed under heat and pressure into rigid, dimensionally stable structures, typically achieving densities between 0.15 and 0.35 g/cm³ depending on application requirements. Compression molding remains the dominant production method for thick-walled industrial dunnage, while vacuum forming serves thin-gauge food service trays where surface detail and stackability matter. The food service end user segment leads volume consumption across the region, whereas consumer electronics applications command premium positioning due to anti-static and precision-fit specifications. Trays represent the most mature product category, with containers showing the fastest structural growth as brands eliminate plastic windows and secondary wrapping.
EMA, EFSA, and the EU Single-Use Plastics Directive collectively shape product compliance pathways, with EFSA migration limits governing direct food contact and national transpositions of the Directive setting phase-out timelines. REACH chemical restrictions further constrain additive packages used for grease resistance and moisture barriers. Stakeholders must monitor how the EU Packaging and Packaging Waste Regulation recalibrates extended producer responsibility fees and recycled content mandates for fiber-based alternatives.
Market Dynamics
The EU Single-Use Plastics Directive operates as the dominant structural force, compelling food service operators and industrial packagers to eliminate plastic cutlery, plates, and protective dunnage in favor of cellulose-based alternatives. This regulatory compression is reconfiguring supply chain specifications across Germany's automotive corridor and France's food service networks.
Growth Catalysts
- EU Single-Use Plastics Directive:The phased ban on plastic food containers and cutlery forces quick-service restaurants and institutional caterers to specify molded fiber trays and clamshells, locking in structural demand through 2035.
- Germany's industrial packaging corridor:Automotive and electronics manufacturers in Baden-Württemberg and Bavaria now mandate fiber-based protective dunnage for component shipments, creating concentrated volume pull.
- Advanced thermoforming:Precision heat-and-pressure forming achieves wall thickness consistency below 0.5mm variation, enabling molded fiber to meet electronics anti-static packaging specifications previously reserved for expanded polystyrene.
Market Restraints
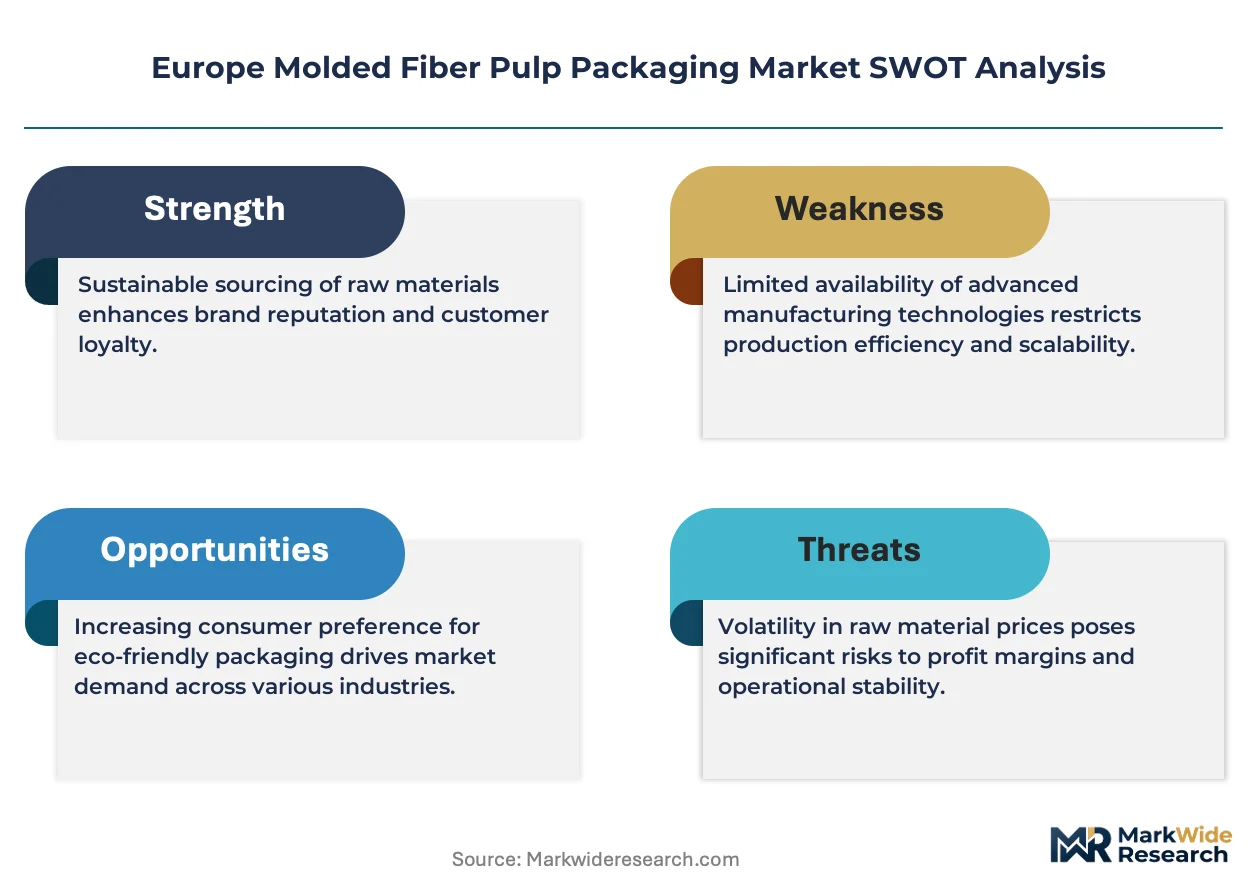
- Nordic pulp supply concentration:Stora Enso and a limited set of integrated Nordic operators control high-grade cellulose feedstock, creating input cost volatility when energy prices spike.
- REACH chemical restrictions:Additive packages for grease resistance and moisture barriers face constrained approval pathways, limiting performance parity with plastic laminates in wet-food applications.
- Expanded polystyrene residual demand:Cold-chain pharmaceutical and premium electronics segments continue specifying EPS for thermal insulation and precision fit, delaying full displacement.
Strategic Opportunities
- Eastern European manufacturing expansion:Poland and Romania offer lower energy and labor costs for compression molding operations, enabling margin recovery against Western European production.
- Consumer electronics premium tier:Anti-static and precision-fit specifications for smartphones and laptops command 40-60% price premiums over standard food service trays.
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility fee recalibration and recycled content mandates for fiber-based alternatives will structurally favor molded pulp over plastic competitors.
Industry Challenges
- Pulp refining technician scarcity:The specialized skill set for controlling fiber slurry consistency and drainage rates remains concentrated among aging workforces in Nordic mill towns.
- EFSA migration testing timelines:Direct food contact certification requires 12-18 month evaluation cycles for novel barrier coatings, delaying product launches.
- Legacy plastics integration:Food service operators with capital sunk in automated plastic tray sealing lines face friction retooling for fiber-based material flow characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Molded Fiber Pulp Packaging Market |
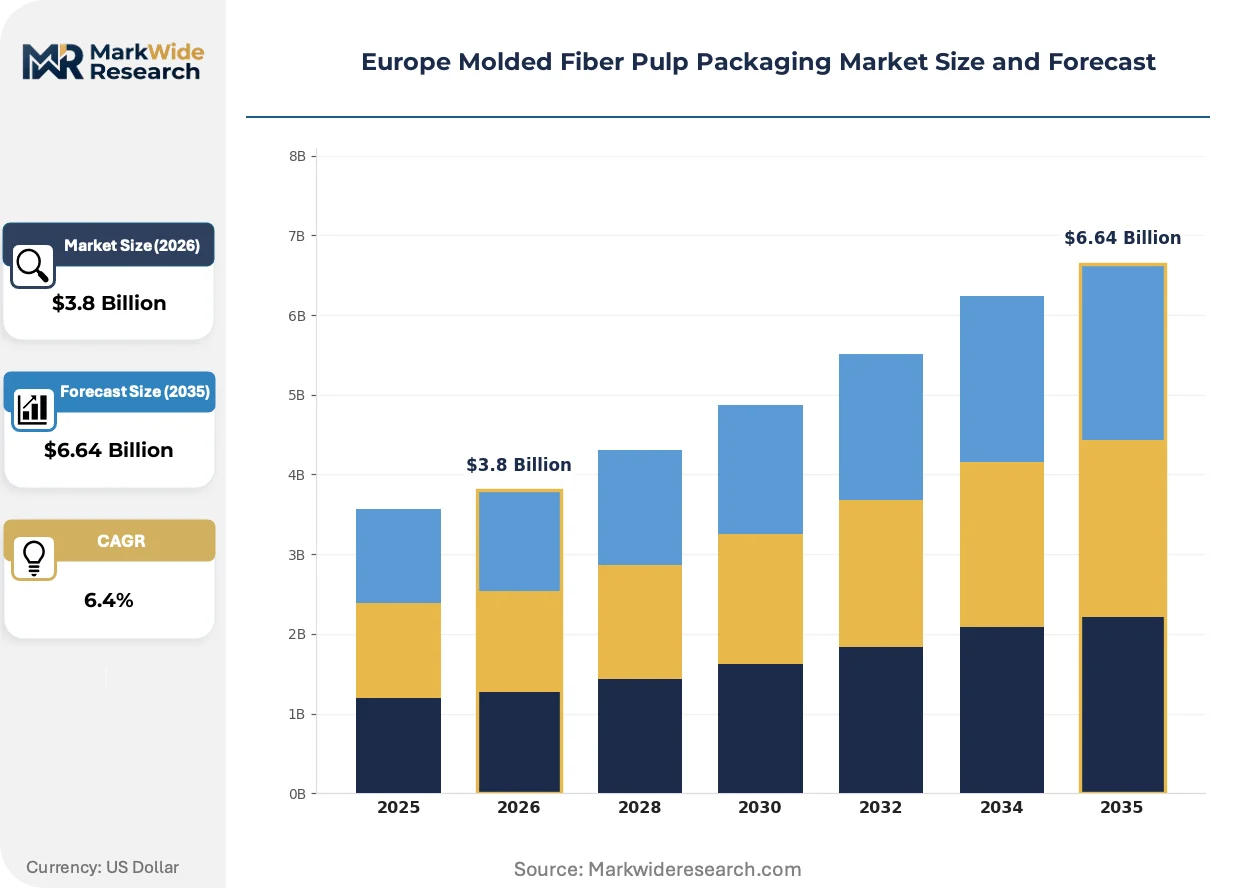
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trays, Containers, Holders, Lids End User: Food Service, Consumer Electronics, Healthcare, Cosmetics Thickness: Thin, Medium, Thick, Extra Thick Technology: Injection Molding, Compression Molding, Vacuum Forming, Others |
| Companies Covered | Huhtamaki, Omni-Pac Group, PAPACKS Sales GmbH, Brødrene Hartmann, Stora Enso, Pulp-Tec Limited, KIEFEL GmbH, James Cropper PLC, buhl-paperform GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Molded Fiber Pulp Packaging Market Shifts & Advancements
Active reshaping in this market centers on the convergence of precision manufacturing with regulatory-driven material substitution. Technology developers, pulp processors, and end-use specifiers are co-evolving solutions that compress the performance gap between fiber and plastic.
Thermoformed fiber barrier technology is hybridizing conventional cellulose structures with spray-applied bio-based coatings to achieve grease resistance without fluorochemical additives. Quick-service chains in France and the Netherlands are piloting these hybrid trays for hot, oily foods at 50,000-unit weekly volumes. The technology is compressing the timeline for full plastic displacement in categories previously deemed technically unreachable for fiber.
REACH enforcement through ECHA is tightening scrutiny on per- and polyfluoroalkyl substances used in legacy grease-resistant treatments, forcing reformulation across the supply base. Industrial consequence includes accelerated R&D spending on polysaccharide and protein-based barrier alternatives. Food contact applications face the most acute compliance pressure, with German operators leading the shift to certified-PFAS-free specifications.
Direct mill-to-converter relationships are displacing traditional merchant pulp distribution in molded fiber supply chains. Large food service buyers in the UK and Germany now contract directly with Nordic pulp producers for slurry consistency guarantees, bypassing intermediate traders. This pattern concentrates most visibly in the egg packaging and industrial dunnage segments, where volume predictability rewards supply chain compression.
Europe Molded Fiber Pulp Packaging Market Segmentation
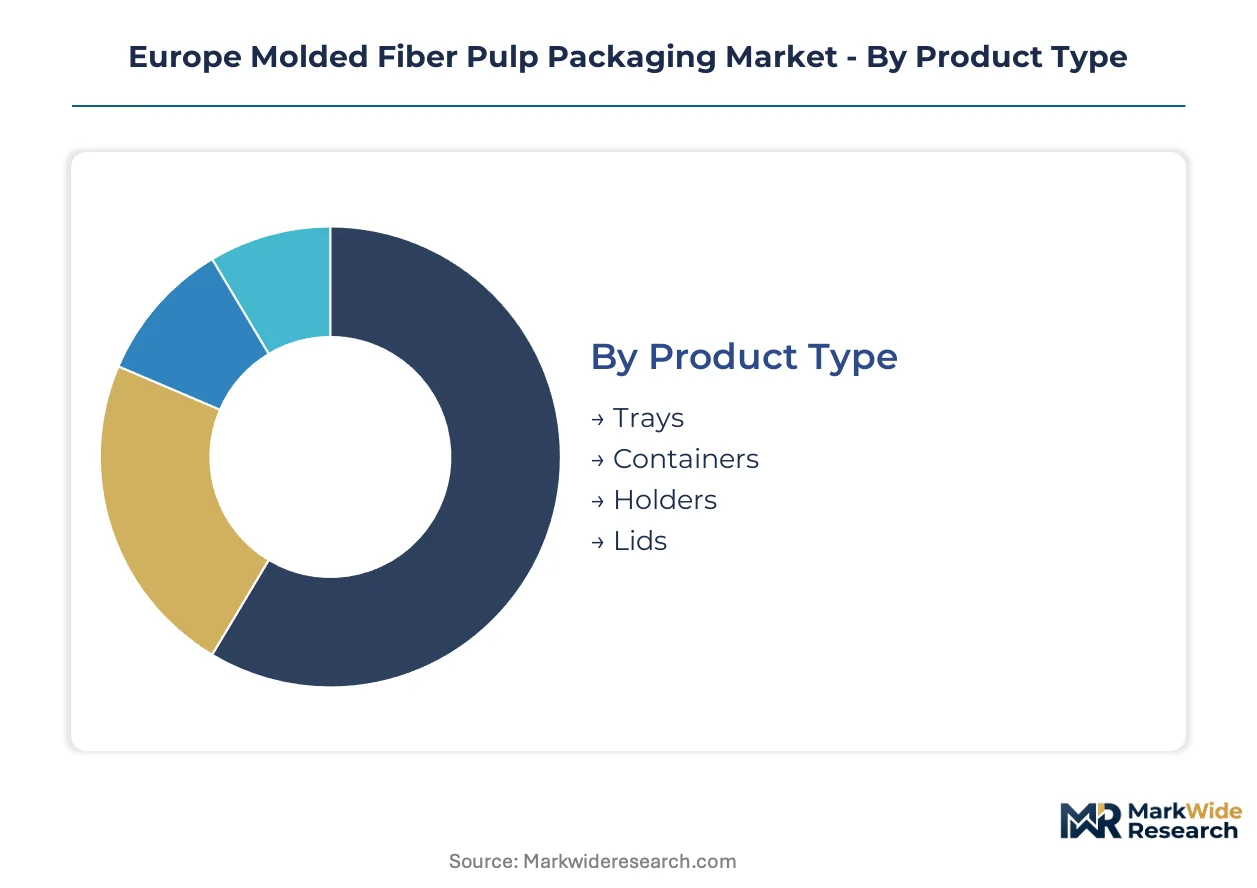
Segmentation in Europe molded fiber pulp packaging reveals how production cycle times and specification intensity vary dramatically across end-use requirements. Food service trays turn over in weeks while industrial dunnage contracts lock in for years, creating fundamentally different margin and capacity planning profiles across the value chain.
Product Type:
Cycle times compress from months for industrial dunnage to days for commodity food trays, with mold complexity and wall thickness driving the differential.
- Trays:Flat or shallow-formed structures with ribbed reinforcement patterns, typically 2-5mm wall thickness. Demand concentrates in German quick-service restaurant chains and institutional caterers replacing plastic under EU Single-Use Plastics Directive mandates. EFSA food contact certification timelines of 12-18 months constrain new supplier entry despite volume pull.
- Containers:Deep-drawn rectangular or round vessels with integrated stacking features. French retail brands and Netherlands-based meal-kit operators specify these for wet and oily foods, driving fastest adoption of bio-based barrier coatings as PFAS restrictions tighten under REACH enforcement.
- Holders:Precision-molded cavities for bottle, cup, or component retention. Beverage multipacks and automotive part shipments in Baden-Württemberg use these for transit protection.
- Lids:Flat or domed closures with snap-fit or friction-seal interfaces. Coffee cup lids and food container covers face the steepest price competition from plastic alternatives.
Trays anchor the volume base while containers gain share at the steepest rate as brands eliminate plastic windows and secondary wrapping.
End User:
Margin structures diverge sharply between price-sensitive food service and specification-intensive electronics, with healthcare occupying a premium compliance tier.
- Food Service:Quick-service restaurants, institutional caterers, and meal-kit providers specifying molded fiber for cutlery, plates, and takeaway containers. German and French operators lead volume procurement, with EFSA migration limits governing direct food contact specifications.
- Consumer Electronics:Smartphone, laptop, and component manufacturers requiring anti-static properties and dimensional tolerances below 0.5mm. Bavarian electronics clusters command 40-60% price premiums over food-grade equivalents for precision-fit protective dunnage.
- Healthcare:Pharmaceutical and medical device packaging with sterilization compatibility and cleanroom handling requirements. Limited penetration due to validation protocols and cold-chain insulation gaps versus expanded polystyrene.
- Cosmetics:Premium beauty brands specifying molded fiber for primary and secondary packaging with high surface finish requirements. Niche positioning constrained by fiber's textural limitations versus rigid plastic.
Food service commands absolute volume while consumer electronics delivers the highest margin per kilogram of pulp processed.
Thickness:
Production throughput and energy intensity scale inversely with wall thickness, compressing economics at the thin-gauge end.
- Thin:Sub-2mm walls for lightweight food service lids and shallow trays. Vacuum forming dominates; Netherlands and UK converters achieve highest line speeds here.
- Medium:2-4mm walls balancing structural integrity with material efficiency. Standard for clamshells and meal containers across French retail networks.
- Thick:4-8mm walls for industrial dunnage and egg packaging. Compression molding in Poland and Romania targets this segment for margin recovery.
- Extra Thick:Above 8mm for heavy-duty protective applications and precision-engineered component cradles. German automotive suppliers specify these for powertrain part shipments.
Medium thickness holds the production center of gravity while thin-gauge applications expand most quickly as barrier coatings close the performance gap.
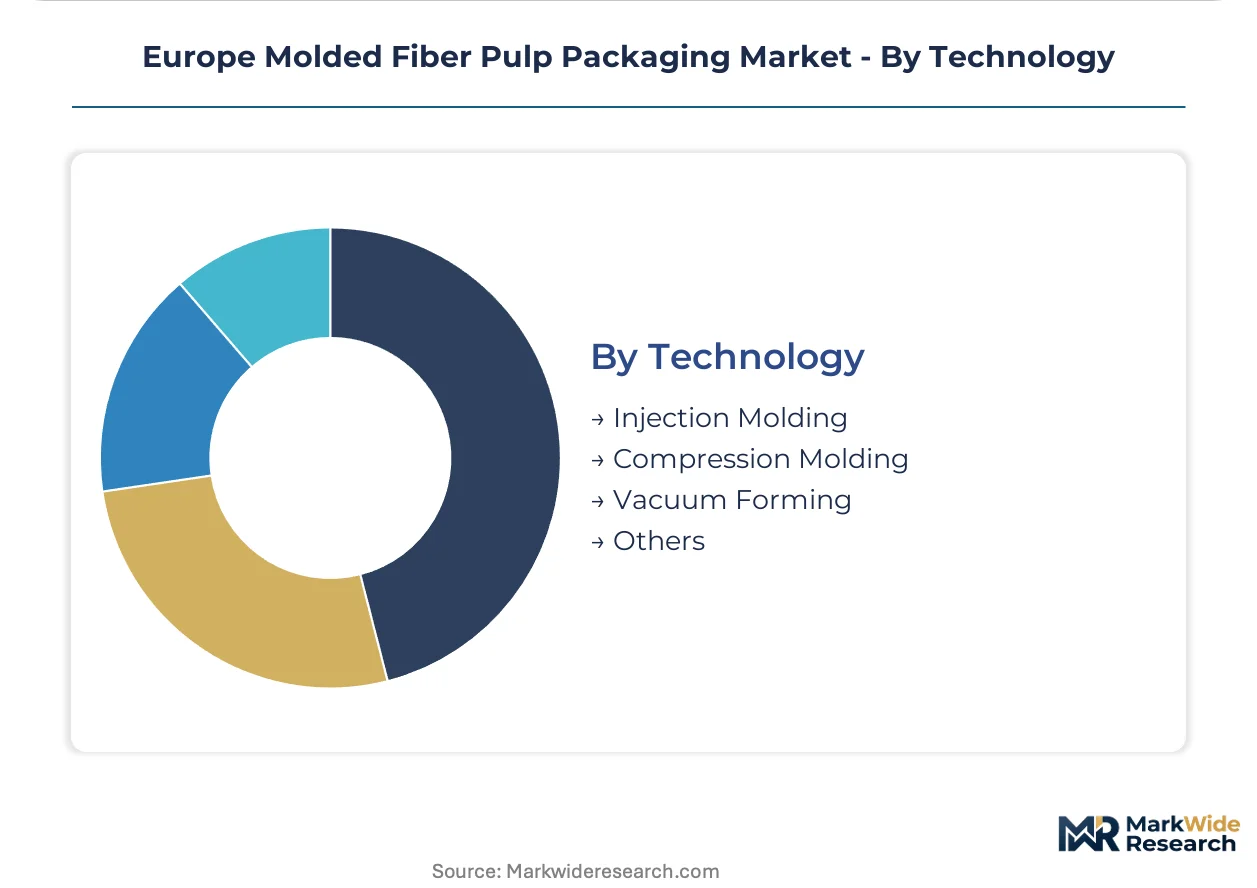
Technology:
Capital deployment and labor skill requirements stratify sharply across forming methods, with thermoforming infrastructure commanding the highest entry barriers.
- Compression Molding:Heat and pressure forming of thick-walled industrial parts using matched metal molds. Dominates German automotive dunnage and Brødrene Hartmann's egg packaging operations with highest capital intensity but lowest per-unit energy at scale.
- Vacuum Forming:Suction-drawn fiber slurry against single-sided molds for thin-gauge trays and lids. Huhtamaki's pan-European network leverages this for food service consistency below 0.5mm wall variation.
- Injection Molding:Pulp slurry injection into closed molds for complex geometries with undercuts. Limited deployment due to drainage challenges and slower cycle times.
- Others:Emerging processes including 3D-printed mold tooling and hybrid thermoforming-compression sequences. Pilot scale only, concentrated in Nordic research clusters.
Compression molding retains the installed base while vacuum forming climbs the fastest as food service volume accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish pulp producers supply fiber slurry to German automotive manufacturers and French food service networks through integrated Nordic-to-Central European logistics corridors. This trade flow anchors regional supply chain configuration.
Germany
Automotive manufacturers in Baden-Württemberg and Bavaria mandate fiber-based protective dunnage for powertrain component shipments. EFSA migration limits govern direct food contact specifications for quick-service restaurant chains. Berlin-Brandenburg hosts pilot programs for PFAS-free barrier coatings in institutional catering.
France
Retail brands and meal-kit operators in Île-de-France specify deep-drawn containers for wet and oily foods. REACH enforcement through ECHA tightens scrutiny on per- and polyfluoroalkyl substances in legacy grease-resistant treatments. Auvergne-Rhône-Alpes converters pilot bio-based barrier coatings at commercial volumes.
United Kingdom
Large food service buyers contract directly with Nordic pulp producers for slurry consistency guarantees, bypassing traditional merchant distribution. The UK Packaging Waste Regulations recalibrate extended producer responsibility fees. London-Southeast logistics hubs coordinate cross-channel supply to Netherlands and Belgium.
Netherlands
Vacuum forming converters achieve highest line speeds for thin-gauge food service lids and shallow trays. The EU Single-Use Plastics Directive phase-out timelines accelerate plastic-to-fiber transitions in quick-service chains. Rotterdam port infrastructure supports pulp import consolidation from Nordic mill operations.
Poland
Compression molding operations target thick-walled industrial segments for margin recovery against Western European production costs. Lower energy and labor costs attract capacity expansion from German automotive suppliers. Warsaw-Łódź manufacturing corridors specialize in egg packaging and heavy-duty protective applications.
Europe Molded Fiber Pulp Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidation concentrates around integrated pulp-to-converter operations and precision thermoforming networks. Three archetypes dominate: Nordic pulp-integrated multinationals, pan-European thermoforming specialists, and regional compression molding fabricators. Capacity expansion and direct mill-to-brand supply chain compression represent the dominant competitive moves.
Among Nordic pulp-integrated operators, Stora Enso anchors upstream supply chain positioning through its integrated board and fiber operations. Huhtamaki occupies the pan-European thermoforming specialist tier with food-grade tray consistency capabilities. Brødrene Hartmann exemplifies the precision-molded industrial protection archetype, extending egg packaging expertise into automotive dunnage applications.
| Leading Market Players |
|---|
| Huhtamaki |
| Omni-Pac Group |
| PAPACKS Sales GmbH |
| Brødrene Hartmann |
| Stora Enso |
| Pulp-Tec Limited |
| KIEFEL GmbH |
| James Cropper PLC |
| buhl-paperform GmbH |
| Others |
Supply & Pricing Matrix
Undercapacity in Poland's compression molding corridor is compressing supplier pricing power while accelerating German automotive buyers toward long-term offtake contracts. This utilization squeeze feeds back into Nordic pulp producers' contract structures, tightening slurry consistency guarantees and locking in volume commitments.
Pricing Analysis
Current-gen vacuum forming equipment commands 25-35% price premiums over legacy compression molding lines, while next-gen thermoforming infrastructure with sub-0.5mm wall tolerance sits at a further elevation. The dominant structure runs contract-based long-term offtake between Nordic pulp mills and German automotive suppliers, with spot-market thin-gauge food trays absorbing residual volatility. Price differentiation centers on EFSA certification tier and volume scale, with uncertified converters facing 15-20% discounts. Pricing pressure stems from REACH-compliant barrier coating R&D costs passing through to food service buyers. Quick-service restaurant chains show highest price sensitivity, while Bavarian electronics clusters accept premiums for anti-static specifications.
Supply Chain Analysis
Nordic pulp feedstock from Finland and Sweden anchors upstream supply, with Polish and Romanian compression molding operations drawing from this concentrated base. The chain rests on high-grade cellulose slurry, precision-machined aluminum molds, and bio-based barrier coating formulations. Single-source vulnerability concentrates in Stora Enso's integrated Nordic operations, where energy price spikes transmit directly to input costs. Distribution runs through direct mill-to-converter relationships displacing traditional merchant pulp traders, with large UK and German buyers contracting slurry consistency guarantees upstream.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is cycling through a regulatory-driven recovery, with the EU Single-Use Plastics Directive phase-out timelines creating predictable demand floors across food service and industrial segments.
For Market Incumbents: Pre-empt capacity constraints in Eastern European manufacturing corridors by securing Polish and Romanian compression molding assets before cost arbitrage narrows. Lock in direct pulp supply agreements with Nordic producers to defend margin position against feedstock volatility, while accelerating PFAS-free barrier coating certification to meet tightening ECHA enforcement timelines. For New Entrants and Emerging Players: Romania's underpenetrated industrial dunnage segment offers white-space access with lower capital barriers than saturated German automotive corridors. Target consumer electronics precision-fit specifications in Bavaria and Baden-Württemberg, where 40-60% price premiums reward technical capability over scale. Lead with anti-static material science partnerships rather than commodity tray competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across vacuum forming food service equipment as standardized thermoforming platforms achieve scale economics. Five-to-ten year viability favors integrated pulp-to-converter operations with captive Nordic feedstock access. Monitor EFSA migration testing backlog durations as the inflection signal—shortening timelines indicate regulatory maturation enabling faster product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Pulp Supply | Captive cellulose feedstock locks in slurry consistency guarantees for German automotive contracts. |
| PFAS-Free Barrier Coating Certification | EFSA-compliant grease resistance opens wet-food applications previously blocked by REACH restrictions. |
| Eastern European Capacity Expansion | Polish and Romanian manufacturing corridors recover margin against Western European labor and energy costs. |
| Precision Thermoforming Infrastructure Deployment | Sub-0.5mm wall tolerance equipment penetrates Bavarian electronics anti-static specifications. |
| Direct Mill-to-Brand Supply Chain Compression | Bypassing merchant pulp traders secures volume predictability for UK and German institutional caterers. |
Research Methodology
A standing panel of pulp refining technicians, thermoforming equipment operators, EFSA regulatory affairs specialists, and automotive packaging procurement managers provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from ECHA substance restriction databases, EU Packaging and Packaging Waste Regulation draft texts, and Nordic mill energy disclosure filings. Bottom-up capacity assessments at Polish and Romanian manufacturing facilities triangulated against top-down demand modeling from German automotive shipment data.
Scenario-bracketing framed the analytical approach, with regulatory enforcement intensity and pulp feedstock cost volatility bounding optimistic and conservative cases across the projection horizon. Segmentation dimensions modeled include product type, end-user industry, wall thickness tier, and forming technology, with additional stratification by EFSA certification status. CAGRs derived from installed capacity expansion schedules and substitution elasticity estimates for plastic-to-fiber transitions. Industry-specific inputs incorporated REACH chemical restriction timelines and EU Single-Use Plastics Directive national transposition schedules.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Asian packaging conglomerates or accelerated next-gen barrier coating breakthroughs would shift outcomes beyond modeled ranges. Cross-checking against EFSA direct food contact approval databases and Nordic pulp futures pricing benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fiber-Based Packaging
Global Molded Pulp Packaging Market
Fiber-Based Packaging
Molded Pulp Inserts Market
Fiber-Based Packaging
Jumbo Kraft Tubes Market
Fiber-Based Packaging
Composite Cardboard Tubes Market
Fiber-Based Packaging
Molded Fiber Trays Market
Fiber-Based Packaging
Fiber Bale Packaging Market
Fiber-Based Packaging
Molded Fiber Packaging Market
Fiber-Based Packaging
Europe Transfer Molded Pulp Packaging Market
Fiber-Based Packaging
North America Molded Pulp Packaging Market
Fiber-Based Packaging
Fibreglass Trays Market
Fiber-Based Packaging
Fiber Based Packaging Market
Fiber-Based Packaging
North America Molded Fiber Packaging Market
Fiber-Based Packaging
Bio-Based PSA for Paper and Fiber-Based Flexible Packaging Market
Fiber-Based Packaging
Molded Pulp Basket Market
Fiber-Based Packaging
Corrugated Fiberboard Market
Fiber-Based Packaging
USA and Canada Molded Fiber Pulp Packaging Market